
 Radiotherapy Induced Oral Mucositis Treatment Market | 2026-2036
Radiotherapy Induced Oral Mucositis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Radiotherapy Induced Oral Mucositis Treatment Market Analytics
Modular mucositis care kits are hardening as the default procurement format across outpatient radiation centers, bundling oral rinses with bioelectronic devices and nutritional supplements into single-patient protocols. Pfizer leverages its institutional pharmacy relationships to sustain formulary placement for systemic agents in academic medical centers. Amgen anchors its position through R&D intensity in biologic supportive care, while Galera Therapeutics differentiates via superoxide dismutase mimetics targeted at severe-grade mucositis prevention.
Radiotherapy induced oral mucositis comprises inflammatory and ulcerative lesions of the oral mucosa resulting from ionizing radiation damage to epithelial stem cells, typically graded by WHO or RTOG scales from erythema to confluent ulceration requiring opioid analgesia. Its primary purpose is to reduce treatment interruptions, maintain nutritional intake, and preserve quality of life during curative or palliative radiation regimens. Topical agents occupy the largest revenue pool due to immediate symptom relief and low barrier to prescribing, while photobiomodulation technology represents the fastest-growing segment as clinical evidence accumulates for its anti-inflammatory and tissue-repair mechanisms. Mucositis care kits concentrate margin capture by consolidating otherwise fragmented purchasing decisions into bundled reimbursement codes.
FDA oncology supportive care guidance shapes trial endpoints and labeling claims for new mucositis therapies, while EMA's qualification of novel drug development tools influences European adoption timelines for preventive agents. ISO standards for medical device biocompatibility govern bioelectronic device materials in contact with compromised oral tissue. Stakeholders must monitor whether CMS reimbursement policy shifts toward bundled episode payments for radiation toxicity management, as this would restructure competitive advantage toward integrated therapy platforms over standalone pharmaceutical offerings.
Market Dynamics
Prophylactic protocol standardization at proton therapy centers is compressing procurement cycles and forcing vendors to bundle hardware, pharmaceuticals, and monitoring services into unified care pathways rather than standalone product sales.
Growth Catalysts
- CMS bundled payment pilots:Medicare reimbursement experiments for radiation toxicity management are incentivizing oncology centers to adopt integrated mucositis prevention kits, consolidating previously fragmented purchasing decisions.
- Photobiomodulation clinical validation:Accumulating peer-reviewed evidence for low-level laser therapy's anti-inflammatory mechanisms is expanding formulary inclusion at academic medical centers and community radiation clinics.
- Proton therapy infrastructure expansion:New treatment facilities in Houston, Jacksonville, and emerging hubs are creating concentrated demand clusters for severe-grade mucositis prophylaxis.
Market Restraints
- FDA efficacy threshold escalation:Tightened oncology supportive care guidance demands larger trial populations and harder endpoints, extending development timelines and capital requirements for new entrants.
- Single-source biologic dependency:Superoxide dismutase mimetic production concentrates in specialized fermentation facilities, creating supply vulnerability for novel preventive agents.
- Reimbursement code fragmentation:Separate billing pathways for devices, drugs, and nutritional supplements complicate bundled protocol adoption in fee-for-service environments.
Strategic Opportunities
- Home-based care extension:Remote patient monitoring platforms enable post-discharge mucositis management, capturing value currently lost to acute intervention readmissions.
- EMA novel drug development tool qualification:Accelerated European adoption pathways for preventive agents with qualified biomarker endpoints create first-mover positioning.
- Artificial intelligence symptom prediction:Machine learning integration with electronic health records enables personalized prophylaxis dosing, differentiating platform offerings from commodity rinses.
Industry Challenges
- Specialized radiation oncology nursing shortage:Protocol administration requires trained staff for bioelectronic device operation and patient education, constraining rollout velocity at expanding centers.
- Legacy electronic medical record integration:Mucositis grading data capture across WHO and RTOG scales demands custom interface development with dominant hospital information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radiotherapy Induced Oral Mucositis Treatment Market |
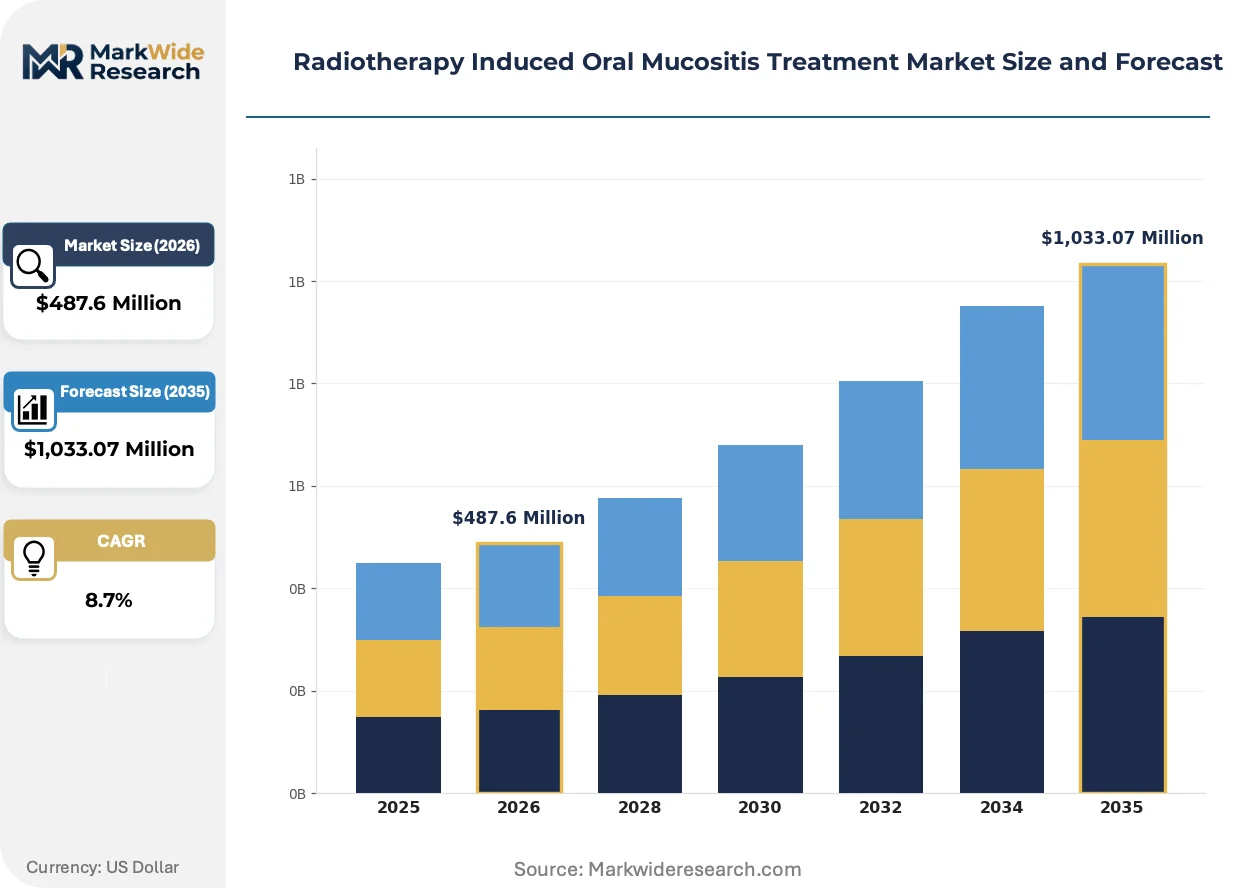
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Agents, Systemic Agents, Oral Rinses, Mucositis Care Kits Technology: Laser Therapy, Cryotherapy, Bioelectronic Devices, Photobiomodulation Care Setting: Outpatient Clinics, Inpatient Facilities, Home Care, Research Institutions Treatment Approach: Preventive Care, Symptomatic Management, Nutritional Support, Integrated Therapy |
| Companies Covered | Galera Therapeutics, Pfizer, Amgen, EpicentRx, Shanxi Zhendong Pharmacy, Solasia Pharma, Biocon, Merck, Innovation Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radiotherapy Induced Oral Mucositis Treatment Market Evolving Landscape
Digital health integration and biomarker-guided personalization are displacing empirical symptom management, with technology vendors racing to embed predictive analytics into routine radiation workflows before protocol standardization locks in incumbent positions.
Photobiomodulation devices utilizing specific wavelength combinations for mitochondrial stimulation are automating tissue repair monitoring through embedded sensors that adjust treatment parameters in real time. Outpatient radiation centers in the United States are adopting these systems at accelerating pace as capital equipment budgets recover post-pandemic. This automation is compressing the specialist technician time required per patient session, enabling higher throughput without proportional staffing increases.
EMA qualification pathways for novel drug development tools are reshaping trial design requirements for mucositis prevention agents across European oncology networks. Manufacturers must now demonstrate biomarker validity alongside clinical efficacy to secure accelerated assessment status. Biologic supportive care developers are responding by front-loading investment in translational science partnerships before Phase II initiation.
Episode-based contracting is consolidating purchasing authority at integrated delivery networks, displacing individual clinician preference as the primary selection mechanism for mucositis products. Procurement committees now evaluate total cost of unplanned treatment interruptions rather than unit price per rinse or device. This shift is most visible at proton therapy hubs where bundled radiation toxicity management contracts cover 90-day post-treatment windows.
Radiotherapy Induced Oral Mucositis Treatment Market Segmentation
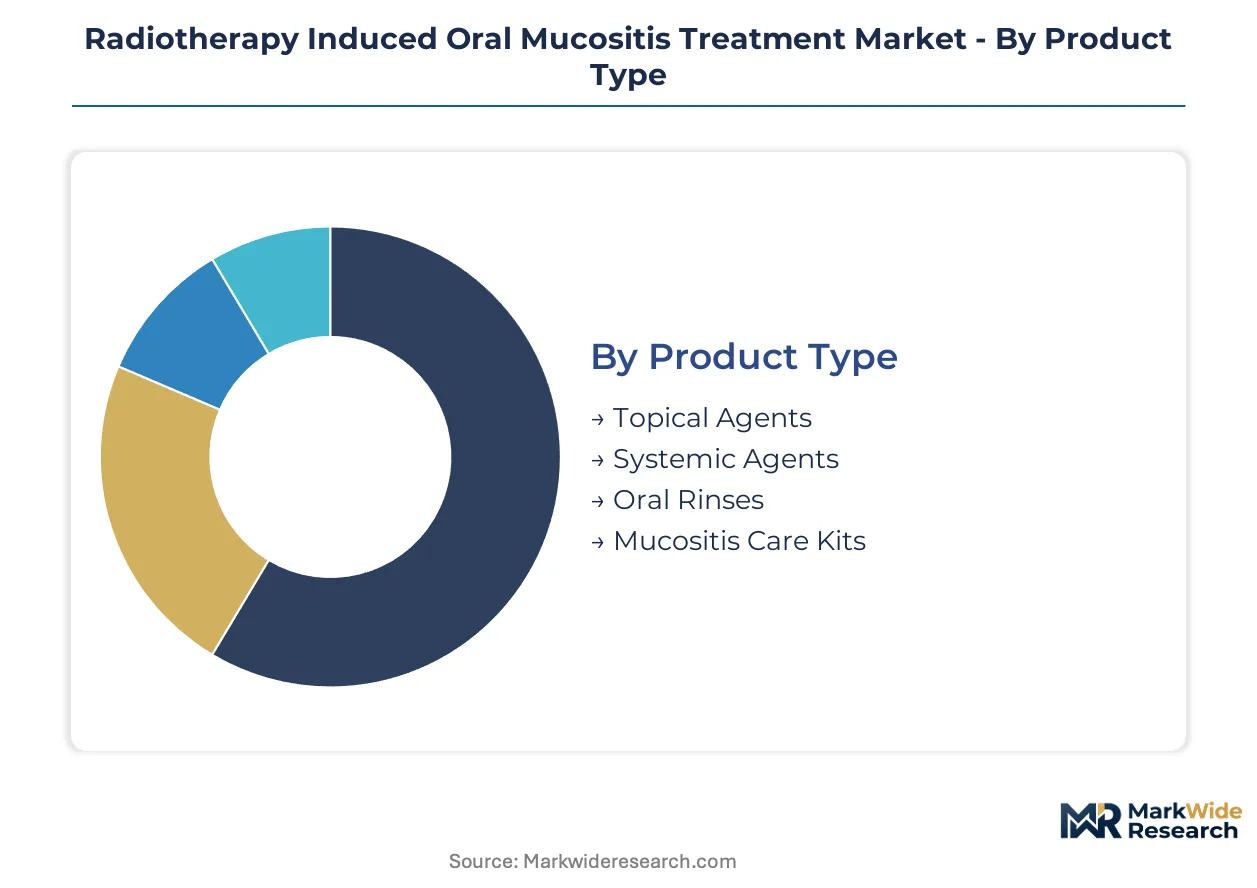
Segmentation in this market determines procurement pathways and reimbursement eligibility. Product bundling decisions, technology adoption curves, and care delivery economics all vary sharply across these dimensions.
Product Type:
Standardization dominates at the commodity end while customization concentrates in bundled protocols and biologic formulations.
- Topical Agents:Immediate-symptom formulations including anesthetic gels and barrier pastes. Demand clusters at community radiation clinics in the United States where prescribing barriers remain lowest and formulary access is broadest.
- Systemic Agents:Palifermin and recombinant growth factors delivered intravenously. Academic medical centers in Houston and Jacksonville concentrate procurement for severe-grade prophylaxis tied to proton therapy protocols.
- Oral Rinses:Chlorhexidine and benzydamine solutions for routine mucosal hygiene.
- Mucositis Care Kits:Bundled single-patient protocols combining rinses, devices, and supplements.
Most installed capacity flows through Topical Agents. Expansion is steepest in Mucositis Care Kits.
Technology:
Capital intensity separates hardware-dependent modalities from consumable-based interventions, reshaping sales cycle length and customer lifetime value.
- Laser Therapy:Low-level laser devices for mitochondrial stimulation and anti-inflammatory effect. Outpatient radiation centers in the United States are automating tissue repair monitoring through embedded sensors that adjust treatment parameters in real time.
- Photobiomodulation:Specific wavelength combinations for epithelial regeneration. Academic medical centers are expanding formulary inclusion fastest as peer-reviewed evidence accumulates for its tissue-repair mechanisms.
- Cryotherapy:Cooling protocols to reduce blood flow and mucosal damage during infusion.
- Bioelectronic Devices:Electrical stimulation systems for pain modulation and healing acceleration.
Equipment sales concentrate in Laser Therapy. Photobiomodulation is climbing the fastest as capital budgets recover post-pandemic.
Care Setting:
Reimbursement structure and staffing density determine which settings can absorb protocol complexity and device training requirements.
- Outpatient Clinics:Freestanding radiation centers handling curative and palliative regimens. These facilities in the United States are adopting automated photobiomodulation systems at accelerating pace as throughput pressures mount.
- Inpatient Facilities:Hospital-based oncology units managing severe-grade mucositis with opioid analgesia requirements. Demand concentrates where bundled episode payments cover 90-day post-treatment windows.
- Home Care:Post-discharge management through remote patient monitoring platforms.
- Research Institutions:Clinical trial sites evaluating novel preventive agents and biomarker-guided protocols.
Patient volume flows through Outpatient Clinics. Home Care is gaining share fastest as remote monitoring platforms mature.
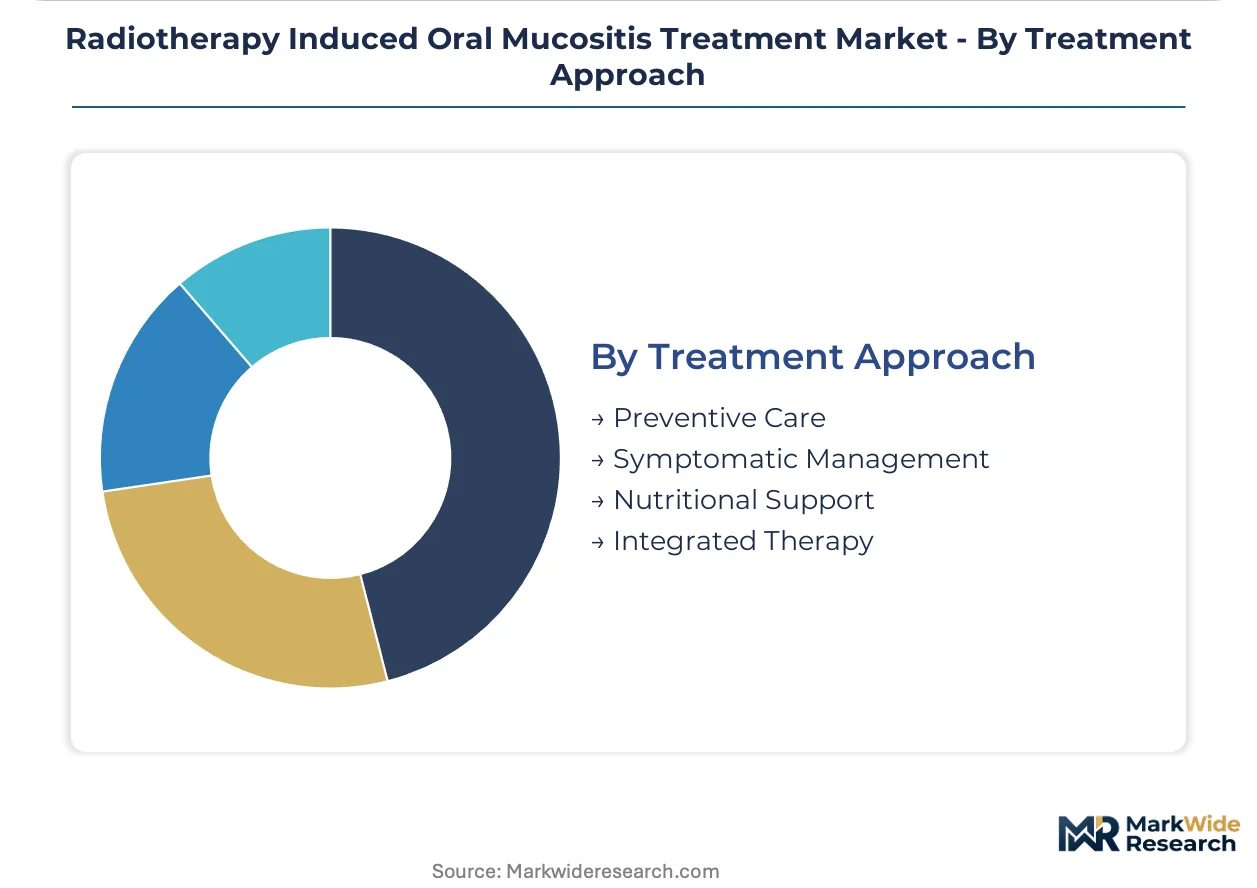
Treatment Approach:
Margin structure and evidence requirements diverge sharply between prophylactic positioning and reactive symptom management.
- Preventive Care:Prophylactic protocols initiated before radiation cycles. Proton therapy centers in Houston and Jacksonville are standardizing these bundles ahead of treatment, compressing procurement cycles.
- Integrated Therapy:Coordinated hardware, pharmaceutical, and nutritional interventions. Academic medical centers concentrate demand where CMS bundled payment pilots incentivize consolidated purchasing decisions.
- Symptomatic Management:Reactive treatment of established mucositis grades per WHO or RTOG scales.
- Nutritional Support:Specialized supplements maintaining caloric intake during ulcerative phases.
Protocol adoption concentrates in Preventive Care. Integrated Therapy is expanding most quickly as episode-based contracting consolidates purchasing authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Prophylactic mucositis management originated in academic radiation oncology departments across the United States before spreading to proton therapy centers in Germany and Japan. Protocol standardization now drives procurement patterns in concentrated treatment hubs worldwide.
United States
FDA oncology supportive care guidance shapes trial endpoints for new preventive agents entering the market. Medicare bundled payment pilots for radiation toxicity management incentivize integrated care kit adoption at major proton therapy centers. Houston and Jacksonville treatment hubs concentrate demand for severe-grade prophylaxis protocols.
Germany
EMA qualification pathways for novel drug development tools accelerate European assessment timelines for biomarker-guided therapies. ISO standards for medical device biocompatibility govern bioelectronic materials in contact with compromised oral tissue. Academic medical centers in Bavaria and North Rhine-Westphalia lead formulary inclusion for photobiomodulation systems.
Japan
PMDA regulatory frameworks for supportive cancer care products establish efficacy thresholds for mucositis prevention agents. METI industrial policy supports domestic manufacturing of laser therapy devices for radiation oncology applications. Tokyo and Osaka metropolitan treatment networks standardize preventive protocols ahead of curative radiation cycles.
United Kingdom
NICE technology appraisals determine reimbursement eligibility for systemic mucositis agents within the National Health Service. MHRA post-Brexit regulatory autonomy enables faster approval pathways for innovative supportive care products. London and Manchester academic radiation centers concentrate procurement for integrated therapy platforms.
China
NMPA streamlined review pathways for oncology supportive care products compress development timelines for domestic preventive agents. Dual carbon policy goals incentivize energy-efficient photobiomodulation device manufacturing. Beijing and Shanghai proton therapy facilities expand prophylactic protocol adoption as capital equipment budgets grow.
Radiotherapy Induced Oral Mucositis Treatment Market Competitive Landscape
The competitive structure tilts toward biologic specialists with institutional pharmacy relationships. Market concentration remains moderate, with established pharmaceutical conglomerates and targeted biotechnology developers sharing procurement influence. Two strategic archetypes dominate: diversified oncology supportive care platforms leveraging formulary placement, and precision biologic developers concentrating on severe-grade prevention mechanisms. Competitive moves center on R&D partnerships for biomarker validation and bundled care kit integration with radiation center procurement committees.
Among US-based biopharmaceutical developers, Galera Therapeutics, Pfizer, and Amgen occupy distinct positioning archetypes. Galera Therapeutics exemplifies the targeted biotechnology model focused on superoxide dismutase mimetics for severe-grade mucositis prevention. Pfizer represents the diversified pharmaceutical platform leveraging institutional pharmacy networks for formulary maintenance. Amgen anchors the biologic supportive care specialist tier through sustained R&D intensity in growth factor therapies. Shanxi Zhendong Pharmacy and Solasia Pharma represent regional players with geographic concentration in Asian radiation oncology markets.
| Leading Market Players |
|---|
| Galera Therapeutics |
| Pfizer |
| Amgen |
| EpicentRx |
| Shanxi Zhendong Pharmacy |
| Solasia Pharma |
| Biocon |
| Merck |
| Innovation Pharmaceuticals |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up photobiomodulation device manufacturers anchor supply consolidation across outpatient radiation networks, compressing procurement timelines while enforcing three-tier pricing discipline across premium laser systems, mid-range LED arrays, and economy-grade consumer units.
Pricing Analysis
Subscription-based bundled care kits dominate procurement at proton therapy centers, separating premium biologic-inclusive protocols from standard pharmaceutical bundles and economy rinse-only tiers. Price differentiation hinges on FDA clearance tier and institutional formulary placement. Cost compression in the economy segment intensifies as GPO contracts consolidate purchasing volume. Academic medical centers show lowest price sensitivity due to bundled episode payments, while community clinics face acute budget constraints.
Supply Chain Analysis
Domestic-content mandates in China's dual carbon policy and India's PLI scheme are reshaping sourcing for laser diode components and fermentation-derived biologics. Manufacturing concentrates in China, Germany, and the United States for photobiomodulation hardware, while superoxide dismutase mimetic production draws from specialized facilities in Japan and Switzerland. Single-source vulnerability pervades rare-earth phosphors for wavelength-specific LEDs. Distribution runs through institutional pharmacy networks at academic medical centers and GPO channels for community radiation clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in radiotherapy-induced oral mucositis treatment rests on automation-driven throughput gains at proton therapy hubs and premium-tier protocol adoption for severe-grade prophylaxis.
For Market Incumbents: Extend formulary lock-in through embedded photobiomodulation sensor integration that automates tissue repair monitoring, raising switching costs for radiation centers. Deepen backward integration into superoxide dismutase mimetic fermentation capacity to neutralize single-source supply vulnerability from specialized biologic manufacturers. For New Entrants and Emerging Players: Capture home-based care extension through remote patient monitoring platforms that manage post-discharge mucositis, a segment currently underserved by acute-focused incumbents. Penetrate community radiation clinics in the United States with simplified, non-bundled oral rinse protocols that bypass complex procurement committee requirements. For Investors and Strategic Acquirers: Valuations sit cheapest among precision biologic developers with qualified biomarker endpoints but unproven commercial infrastructure. Long-term viability favors platforms combining hardware automation with pharmaceutical content over standalone device or drug plays. Watch FDA oncology supportive care guidance revisions as the critical inflection signal for development timeline risk.| Strategic Initiative | Industry Significance |
|---|---|
| Bundled Episode Contracting | CMS pilots at Houston and Jacksonville proton centers consolidate purchasing authority away from individual clinicians. |
| EMA Novel Drug Development Tool Qualification | Accelerated European assessment timelines reward front-loaded translational science investment before Phase II initiation. |
| Photobiomodulation Sensor Automation | Embedded real-time tissue monitoring compresses specialist technician time and enables higher patient throughput. |
| Home Care Remote Monitoring Platform | Post-discharge mucositis management captures value currently lost to acute intervention readmissions at inpatient facilities. |
| Superoxide Dismutase Mimetic Manufacturing Scale-Up | Fermentation capacity expansion mitigates supply concentration risk for severe-grade prophylaxis agents. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining structured discussions with radiation oncology department heads, hospital formulary directors, GPO contract managers, and biomedical device procurement leads with secondary validation against FDA 510(k) filings, CMS reimbursement code databases, ClinicalTrials.gov mucositis protocol registries, and EMA qualification pathway documentation. Bottom-up installed base modeling and top-down market sizing triangulated volume estimates.
Comparable-period anchoring tied projection assumptions to historical proton therapy center expansion patterns and photobiomodulation device adoption curves across the analysis window. Segmentation modeling spanned product type, technology modality, care setting, and treatment approach dimensions. CAGRs derived from patient volume forecasts at major radiation hubs and protocol penetration rates for bundled care kits. Industry-specific inputs included WHO/RTOG grading scale standardization timelines and CMS bundled payment pilot expansion scope.
Regulatory guidance revision, reimbursement policy discontinuation, and photobiomodulation clinical evidence accumulation are the dominant revision risks to projection assumptions. Forecasts reflect documented assumptions about proton therapy infrastructure buildout velocity and formulary inclusion timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Purpura Treatment Market
Medical Treatment
Global Radiodermatitis Treatment Market
Medical Treatment
Prion Disease Treatment Market
Medical Treatment
Laser Therapy Market
Medical Treatment
Mast Cell Tumors Treatment Market
Medical Treatment
Meningococcal Meningitis Treatment Market
Medical Treatment
Onchocerciasis Treatment Market
Medical Treatment
Global Sex Reassignment Surgery Market
Medical Treatment
CINV Treatment Market
Medical Treatment
Anti-Rickettsial Treatment Market
Medical Treatment
Necrotizing Skin Infections Treatment Market
Medical Treatment
Global Autoimmune Treatment Market
Medical Treatment
Familial Hypercholesterolemia Treatment Market
Medical Treatment
Burns Treatment Market
Medical Treatment
Scoliosis Management Market
Medical Treatment
Lysosomal Disease Treatment Market