
 Peripheral Nerve Injuries Market | 2026-2036
Peripheral Nerve Injuries Market Size, Share, and Industry Trends Forecast 2026-2036
Peripheral Nerve Injuries Market Intelligence
Biologics-grade nerve conduit specifications are unwinding older synthetic-only treatment paradigms in peripheral nerve repair. Axogen Corporation dominates allograft-based reconstruction platforms with proprietary Avance nerve graft processing. Medtronic leverages its neurostimulation heritage to extend into peripheral electrical stimulation protocols. Polyganics specializes in synthetic absorbable nerve guides that compete on cost against biologic alternatives.
Peripheral nerve injuries encompass damage to motor, sensory, and autonomic nerves outside the central nervous system, typically requiring tension-free repair across gaps exceeding five millimeters using autografts, allografts, or engineered conduits. The primary commercial purpose centers on restoring functional innervation to prevent permanent denervation atrophy and neuropathic pain syndromes. Nerve conduits and grafts together anchor the product portfolio, with bioengineered solutions commanding premium positioning against conventional suturing. Hospital end users concentrate the highest procedure volumes, while regenerative medicine applications represent the fastest-expanding application segment as cell therapy adjuncts mature.
FDA 510(k) and PMA pathways govern device commercialization in the United States, while EMA medical device regulation and MDR compliance shape European market access requirements. Japan's PMDA enforces stringent clinical evidence standards for novel nerve repair biologics that delay entry but validate premium reimbursement. Stakeholders must monitor evolving regenerative medicine advanced therapy designations across these regulators to anticipate competitive windows and prioritize development investments.
Market Dynamics
Hospital procurement committees now prioritize bioengineered nerve conduits over synthetic alternatives, compressing legacy product margins while elevating regenerative medicine platforms to standard-of-care status in tertiary referral networks.
Growth Catalysts
- EMA MDR compliance deadlines:European medical device regulation upgrades are accelerating hospital transitions from Class II to Class III nerve repair devices, forcing infrastructure investment that favors advanced biologics suppliers.
- Cell therapy adjunct maturation:Schwann cell and induced pluripotent stem cell integration with nerve conduits is expanding addressable gap lengths beyond the five-millimeter autograft ceiling.
- Japan's tertiary cluster concentration:Keio University Hospital and Osaka University Medical Hospital anchor national referral pathways that concentrate high-complexity nerve reconstruction volumes and validate premium reimbursement.
Market Restraints
- Allograft tissue supply concentration:Axogen Corporation's proprietary Avance processing network controls domestic cadaveric nerve tissue availability, creating single-source dependency for processed human nerve allografts.
- PMDA clinical evidence requirements:Japan's pharmaceutical and medical devices agency mandates extended follow-up periods for novel biologics that extend commercialization timelines.
- Autograft morbidity persistence:Donor-site neuroma and sensory deficit risks sustain surgeon preference for nerve harvesting despite conduit availability, limiting category conversion.
Strategic Opportunities
- Germany's rehabilitation integration:Bundled payment pilots for post-surgical neuromuscular re-education create channel openings for peripheral electrical stimulation device combinations.
- Absorbable synthetic cost positioning:Polyganics' polyglycolic acid nerve guides compete at thirty to fifty percent below allograft pricing, penetrating cost-constrained community hospital settings.
- FDA regenerative medicine advanced therapy designation:Expedited review pathways for cell-laden conduits compress development timelines and unlock priority voucher monetization.
Industry Challenges
- Microsurgical fellowship pipeline contraction:Declining enrollment in peripheral nerve reconstruction subspecialty training limits qualified surgeon availability for complex gap repairs.
- Biologics cold chain integrity:Temperature excursion during transport degrades processed allograft viability, requiring redundant logistics infrastructure that elevates operational overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Peripheral Nerve Injuries Market |
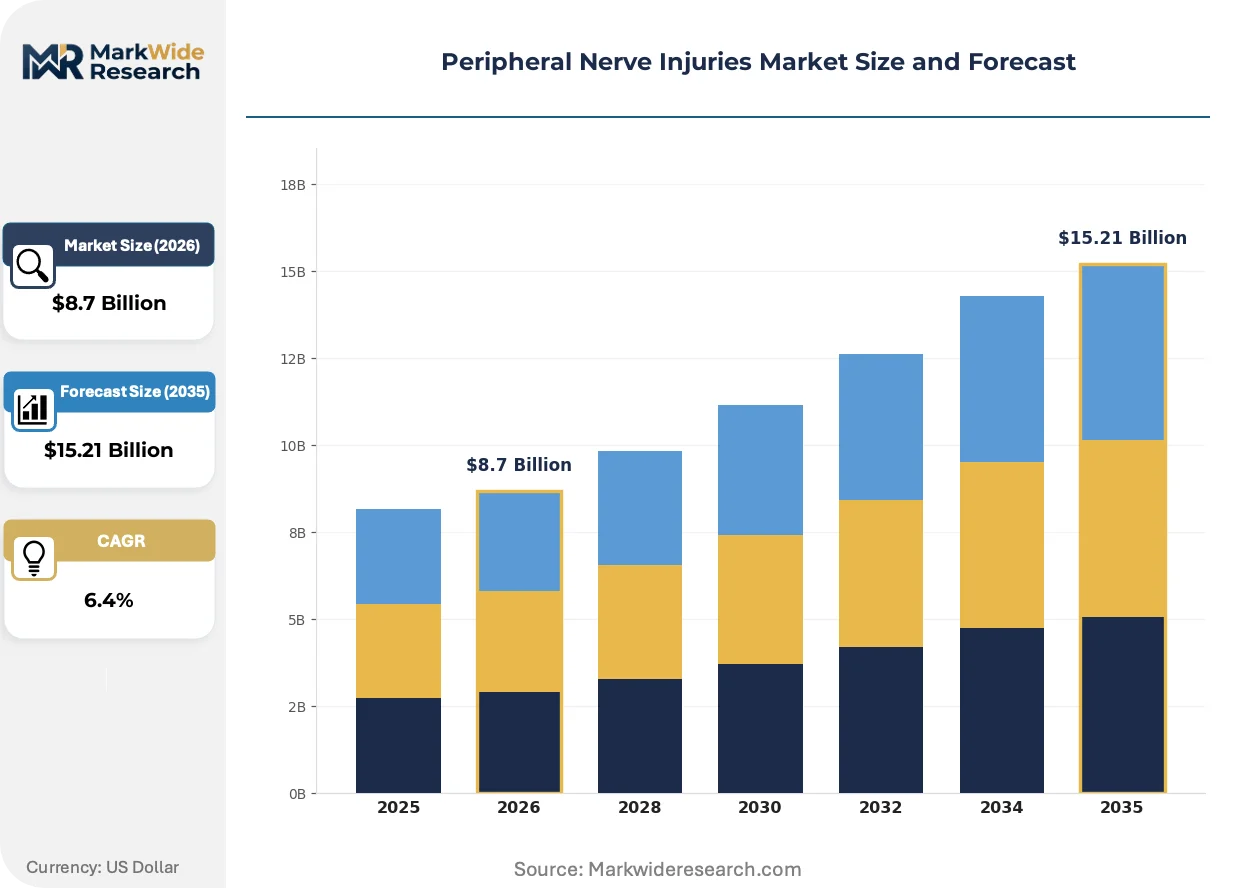
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sutures, Grafts, Nerve Conduits, Electrical Stimulation Devices Application: Trauma, Surgical Repair, Neuroprosthetics, Regenerative Medicine End User: Hospitals, Outpatient Clinics, Rehabilitation Centers, Academic Institutions Technology: Bioengineered Solutions, Microneurography, 3D Bioprinting, Nerve Growth Factor |
| Companies Covered | Toyobo, Polyganics, Axogen Corporation, Medtronic, Baxter International, Stryker Corporation, Orthocell Limited, Astellas Pharma, Integra LifeSciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Peripheral Nerve Injuries Market Strategic Shifts & Innovations
Biomaterial science convergence with electrical stimulation protocols is redefining functional recovery endpoints, shifting competitive advantage from structural repair metrics to measurable motor and sensory restoration benchmarks.
Decellularized extracellular matrix scaffolds derived from porcine small intestinal submucosa are displacing synthetic collagen tubes in gap repairs exceeding fifteen millimeters. Academic medical centers in the United States and Germany have adopted these platforms as first-line alternatives to autografts. The displacement is compressing synthetic conduit addressable market share while elevating reimbursement requirements for bioactive claims.
Japan's PMDA has tightened post-market surveillance obligations for novel nerve repair biologics, mandating five-year patient-reported outcome submissions that extend regulatory commitment periods. This industrial consequence favors established manufacturers with dedicated pharmacovigilance infrastructure over emerging entrants. High-complexity reconstruction segments in Osaka and Tokyo metropolitan areas are responding by consolidating procurement around suppliers with proven compliance histories.
Hospital value analysis committees have assumed primary vendor selection authority from individual surgeons, compressing traditional physician-preference-item autonomy. Integrated delivery networks in the United States are replacing decentralized purchasing with standardized formularies that favor contract-tiered pricing. This behavioral shift is most visible in California and Texas health systems where procurement centralization has accelerated within the past eighteen months.
Peripheral Nerve Injuries Market Segmentation
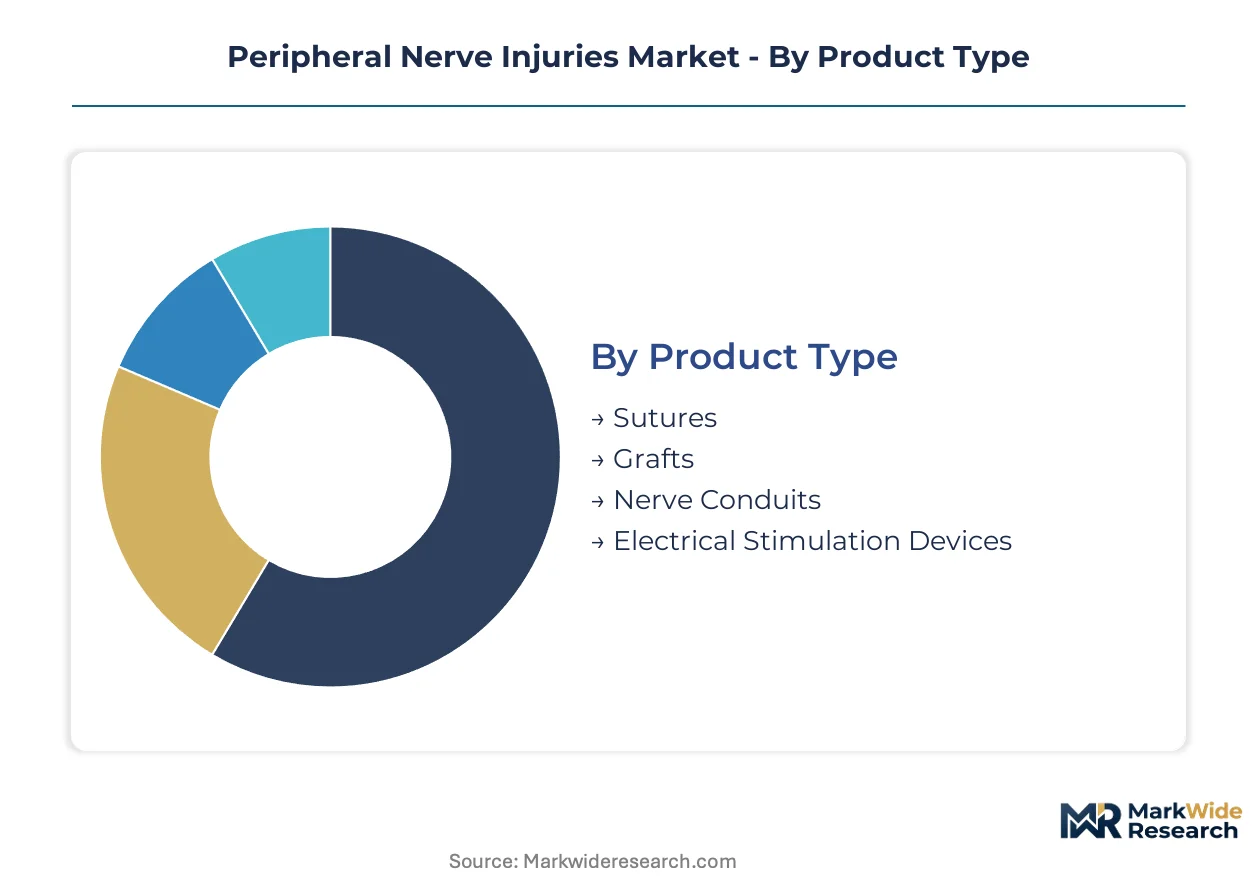
Peripheral nerve repair requires precise matching of product specifications to gap length, anatomical location, and functional recovery targets. Segmentation reveals how regulatory pathways and procurement priorities are reshaping competitive positioning across device categories.
Product Type:
FDA 510(k) clearance timelines vary dramatically across material classifications, with absorbable synthetics moving faster than biologics requiring donor tissue oversight.
- Nerve Conduits:Hollow tubular scaffolds bridge transection gaps without tension, with bioabsorbable polymers and decellularized matrices commanding premium hospital formulary placement. Demand concentrates in United States tertiary centers where bundled payments reward reduced revision rates.
- Grafts:Autografts harvested from sensory nerves remain the clinical benchmark for gaps exceeding 30 millimeters, though donor-site morbidity drives allograft substitution in Germany and Japan where processed cadaveric tissue networks are mature.
- Sutures:Microsurgical epineurial and perineurial repair filaments anchor small-diameter nerve coaptation in digital and facial reconstruction.
- Electrical Stimulation Devices:Portable and implantable systems accelerate axonal regeneration through targeted depolarization protocols.
Established volume favors Sutures; emerging adoption favors Nerve Conduits.
Application:
Reimbursement coding density determines commercial prioritization, with trauma reconstruction offering established DRG pathways versus regenerative medicine requiring emerging technology carve-outs.
- Regenerative Medicine:Cell-seeded conduits and gene therapy adjuncts target previously irreparable nerve defects, with Schwann cell delivery systems advancing through FDA regenerative medicine advanced therapy designation. Academic medical centers in Osaka and Texas anchor early adoption cohorts.
- Surgical Repair:Iatrogenic injury reconstruction during oncologic and orthopedic procedures generates predictable case volumes with defined procurement contracts.
- Trauma:Emergency department referrals for laceration and avulsion injuries drive acute intervention volumes with compressed decision windows.
- Neuroprosthetics:Brain-computer interface and targeted muscle reinnervation applications restore volitional control in amputee populations.
Reimbursement stability favors Surgical Repair; steepest expansion trajectory favors Regenerative Medicine.
End User:
Capital equipment requirements and case complexity thresholds fragment purchasing authority across institutional settings.
- Hospitals:Integrated delivery networks centralize procurement for high-volume reconstruction services, with value analysis committees displacing individual surgeon preference in California and Texas health systems.
- Rehabilitation Centers:Post-surgical neuromuscular re-education programs in Germany's bundled payment pilots create channel openings for electrical stimulation device combinations.
- Outpatient Clinics:Ambulatory surgical centers handle limited gap repairs under local anesthesia with compressed supply chain requirements.
- Academic Institutions:Research hospitals anchor clinical trial enrollment and first-line adoption of novel biologics requiring extended follow-up protocols.
Procurement scale favors Hospitals; patient access expansion favors Rehabilitation Centers.
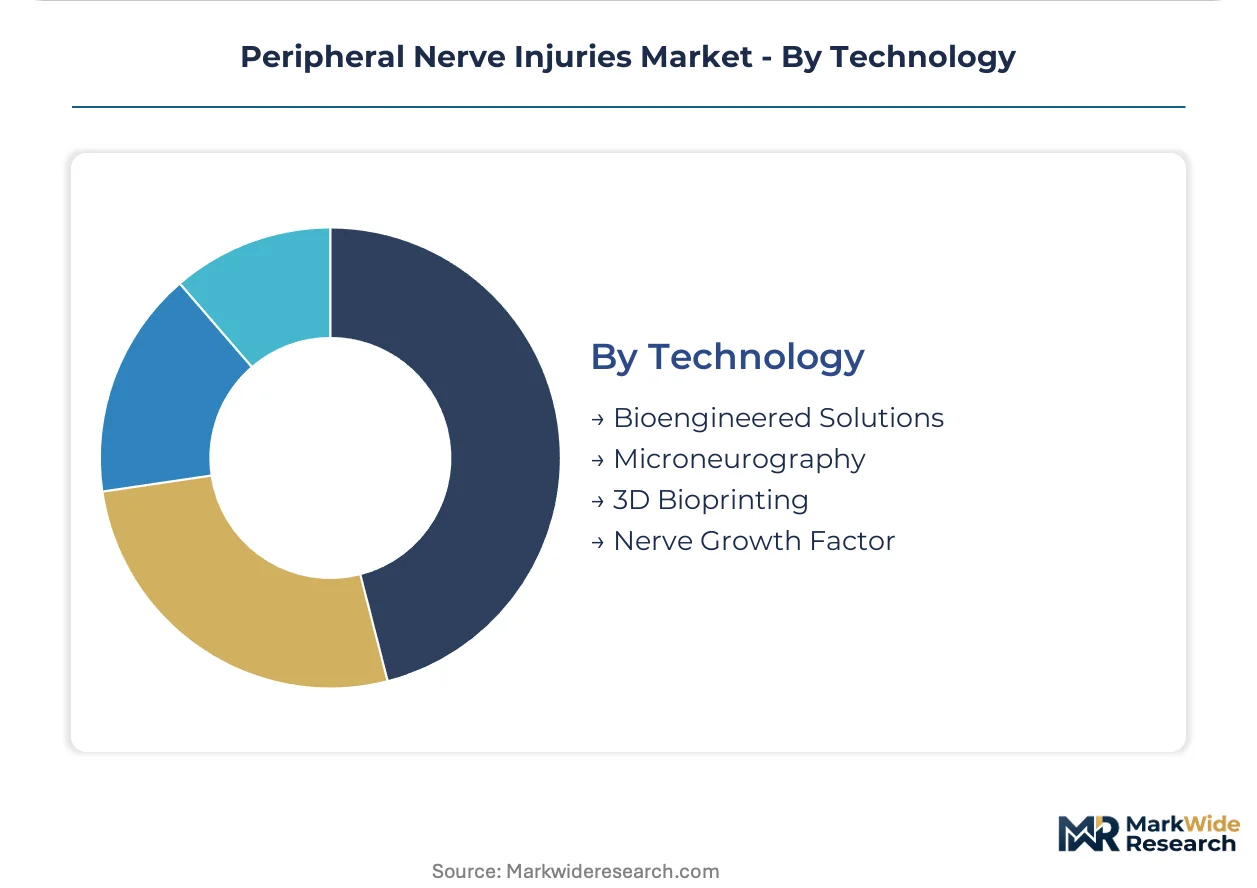
Technology:
Intellectual property density and manufacturing complexity separate defendable platform positions from commodity competition.
- Bioengineered Solutions:Decellularized extracellular matrix scaffolds derived from porcine small intestinal submucosa displace synthetic collagen tubes in gap repairs exceeding fifteen millimeters, with EMA MDR Class III designation validating premium positioning.
- 3D Bioprinting:Patient-specific conduit geometries with integrated guidance channels address brachial plexus and complex anatomical reconstructions.
- Microneurography:Intraoperative nerve action potential recording guides graft length decisions and predicts functional recovery.
- Nerve Growth Factor:Recombinant protein delivery systems accelerate axonal sprouting rates in combination with conduit implantation.
Clinical validation favors Bioengineered Solutions; manufacturing flexibility favors 3D Bioprinting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports processed cadaveric nerve allografts to tertiary centers across Western Europe, anchoring a trade corridor that supplies biologics to France, Italy, and the Netherlands.
United States
Integrated delivery networks in California and Texas centralize procurement through value analysis committees, displacing individual surgeon preference. FDA 510(k) and PMA pathways govern device commercialization with regenerative medicine advanced therapy designations compressing timelines for cell-laden conduits. Academic medical centers in Boston and Houston anchor clinical trial enrollment for novel biologics.
Germany
Bundled payment pilots for post-surgical neuromuscular re-education create channel openings for peripheral electrical stimulation device combinations. EMA MDR Class III designation validates premium positioning for decellularized extracellular matrix scaffolds. The Rhine-Ruhr metropolitan region concentrates hospital procurement authority for high-complexity nerve reconstruction volumes.
Japan
Keio University Hospital and Osaka University Medical Hospital anchor national referral pathways that concentrate high-complexity nerve reconstruction volumes. PMDA mandates extended follow-up periods for novel biologics that extend commercialization timelines but validate premium reimbursement. The Kanto and Kansai regions dominate tertiary care clustering for peripheral nerve repair.
United Kingdom
NHS England specialized commissioning frameworks concentrate high-cost nerve repair procedures within designated trauma centers. MHRA post-Brexit regulatory autonomy maintains alignment with EMA MDR standards while streamlining domestic innovation pathways. The Oxford-Cambridge-London golden triangle anchors academic research translation for bioengineered conduit technologies.
France
ANSM oversight of advanced therapy medicinal products creates a parallel regulatory track for cell-seeded nerve conduits alongside standard medical device pathways. University hospital clusters in Paris and Lyon coordinate national referral networks for brachial plexus reconstruction. The Île-de-France region concentrates both procurement authority and research infrastructure for regenerative medicine applications.
Peripheral Nerve Injuries Market Key Industry Players
Listed leaders compete with private specialists across platform maturity, with publicly traded entities dominating allograft processing and synthetic conduit manufacturing while venture-backed firms pioneer cell therapy adjuncts. The market structure tilts toward consolidation in processed biologics, where tissue supply networks create defendable positions, while synthetic absorbable segments sustain price-competitive fragmentation. Three archetypes dominate: allograft processors with proprietary tissue networks, diversified medtech conglomerates leveraging neurostimulation heritage, and absorbable polymer specialists competing on cost. M&A activity concentrates on cell therapy platform acquisitions and regional distribution rights consolidation.
Within the allograft processing tier, Axogen Corporation exemplifies vertical control over cadaveric tissue supply chains. Among diversified conglomerates, Medtronic and Stryker Corporation occupy positions bridging neurostimulation and surgical reconstruction portfolios. Polyganics represents the cost-optimized synthetic specialist archetype, competing at price points thirty to fifty percent below biologic alternatives.
| Leading Market Players |
|---|
| Toyobo |
| Polyganics |
| Axogen Corporation |
| Medtronic |
| Baxter International |
| Stryker Corporation |
| Orthocell Limited |
| Astellas Pharma |
| Integra LifeSciences |
| Others |
Cost & Logistics Intelligence
Capacity utilization at decellularized matrix processing facilities in the United States and Germany anchors price floors for bioengineered nerve conduits, while underutilized synthetic polymer lines in the Netherlands compress margins on absorbable alternatives. Scale economies in allograft tissue networks concentrate pricing power among processors with proprietary cadaveric supply agreements, forcing smaller synthetic specialists toward cost-competitive positioning in community hospital segments.
Pricing Analysis
Next-generation cell-laden conduits command substantial premiums over current-generation decellularized scaffolds, which in turn price above prior-generation synthetic collagen tubes. Three-tier pricing structure across premium, standard, and economy levels reflects FDA pathway complexity, with PMA-track biologics carrying certification premiums against 510(k) synthetics. Cost compression in absorbable polymer segments intensifies because Polyganics and comparable specialists compete on unit economics for hospital formulary inclusion. Community hospitals exhibit highest price sensitivity, while academic tertiary centers prioritize clinical outcomes over acquisition cost.
Supply Chain Analysis
The United States and Germany anchor processed cadaveric allograft production, while the Netherlands and Japan concentrate synthetic absorbable manufacturing. Decellularized extracellular matrix scaffolds draw from porcine small intestinal submucosa sourced through agricultural processing networks, with Schwann cell therapy adjuncts resting on bioreactor capacity at academic medical centers. Single-source vulnerability characterizes allograft tissue supply, where Axogen's proprietary Avance processing network controls domestic cadaveric nerve availability. Distribution runs through integrated delivery network procurement committees in California and Texas health systems, with direct hospital contracting displacing distributor intermediaries in high-volume reconstruction segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Microsurgical fellowship enrollment contraction has created acute surgeon scarcity for complex gap repairs, elevating the value of platforms that reduce operative complexity or enable non-specialist intervention. This capability gap rewards automation investments and procedural simplification across the product portfolio.
For Market Incumbents: Compound tissue supply network advantages by securing exclusive cadaveric procurement agreements with additional academic medical center organ procurement organizations, while simultaneously investing in cold chain redundancy to mitigate temperature excursion risks that degrade allograft viability. Defend against synthetic price erosion by embedding bioactive claims into hospital value analysis committee presentations that justify premium positioning through reduced revision rates. Vertical integration into Schwann cell bioreactor capacity represents the critical lever for next-generation conduit differentiation. For New Entrants and Emerging Players: Post-surgical neuromuscular re-education service layers remain underdeveloped by incumbent device manufacturers, creating channel openings for peripheral electrical stimulation bundling in Germany's rehabilitation centers. Target ambulatory surgical centers in United States metropolitan corridors where limited gap repairs under local anesthesia favor cost-optimized synthetic guides over biologic alternatives. A direct-to-clinic distribution model bypassing integrated delivery network procurement committees offers the most penetrable go-to-market angle for price-competitive entrants. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among allograft processors with proprietary tissue networks that lock in hospital customers through supply security guarantees rather than transactional device sales. Long-term viability across the analysis window favors platforms with regulatory moats in cell therapy adjuncts, where FDA regenerative medicine advanced therapy designation compresses competitive entry timelines. Acquisition targets should display demonstrated pharmacovigilance infrastructure capable of satisfying Japan PMDA five-year post-market surveillance obligations. The signal to watch is bundled payment pilot expansion in Germany and Texas, which would validate combined device-rehabilitation platform economics.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Regenerative Medicine Advanced Therapy Designation | Expedited review compresses development timelines for cell-laden conduits entering United States academic medical centers. |
| Hospital System Partnership | Integrated delivery network formulary placement in California and Texas secures predictable volume through procurement centralization. |
| CE Marking Pathway | EMA MDR Class III designation validates premium positioning for decellularized scaffolds in German tertiary referral networks. |
| Reimbursement Strategy | Japan PMDA clinical evidence requirements extend timelines but validate premium pricing in Keio and Osaka University Hospital clusters. |
| Software Companion Development | Intraoperative nerve action potential recording integration guides graft decisions and predicts functional recovery endpoints. |
Research Approach
Initial hypotheses were tested against primary input from peripheral nerve surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers, and refined through secondary validation against FDA 510(k) and PMA filings, EMA MDR submission databases, Japan PMDA approval records, and hospital procurement contract repositories. Bottom-up procedure volume estimates were triangulated with top-down market size calculations derived from allograft processor revenue disclosures and synthetic conduit manufacturer trade data.
Variance decomposition across product type, application, end user, and technology dimensions structured the analytical framework, with growth trajectories derived from gap-length trend extrapolation and cell therapy adjunct maturation curves. Modeled inputs included Schwann cell bioreactor capacity expansion, microsurgical fellowship graduation rates, and bundled payment pilot geographic spread throughout the projection horizon.
Forecasts assume regulatory continuity in FDA, EMA, and PMDA pathways; material policy shifts such as accelerated approval withdrawal or MDR class reclassification would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Nasopharyngeal Carcinoma Treatment Market
Medical Treatment
Gaucher Disease Treatment Market
Medical Treatment
Tetanus Treatment Market
Medical Treatment
Tinea Pedis Treatment Market
Medical Treatment
Allergy Treatment Market
Medical Treatment
Spinal Cord Compression Market
Medical Treatment
Alagille Syndrome Treatment Market
Medical Treatment
Achalasia Treatment Market
Medical Treatment
Mast Cell Tumors Treatment Market
Medical Treatment
Global Medication Management Market
Medical Treatment
Kidney Stones Management Market
Medical Treatment
Liver Fluke Treatment Market
Medical Treatment
Liver Transplantation Market
Medical Treatment
Europe Platelet Rich Plasma (PRP) Market
Medical Treatment
Lysosomal Storage Disease Treatment Market
Medical Treatment
Hypothermia Management Market