
 Ventral Hernia Treatment Market | 2026-2036
Ventral Hernia Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Ventral Hernia Treatment Market Analytics
Aftermarket service revenue from mesh surveillance and revision consultation is reconfiguring how manufacturers capture lifetime patient value. Medtronic plc leverages its integrated surgical ecosystem to sustain recurring revenue across the repair-to-revision continuum. Becton, Dickinson and Company anchors its position through broad distribution control in acute care settings. W. L. Gore & Associates, Inc. differentiates via specialized ePTFE material science that commands premium positioning in complex hernia repair.
Ventral hernia treatment encompasses surgical intervention for abdominal wall defects using synthetic or biologic mesh reinforcement, typically involving polypropylene, polyester, or expanded polytetrafluoroethylene implants designed to restore fascial integrity and prevent recurrence. The primary purpose is to reduce hernia recurrence rates while minimizing surgical site complications and patient recovery duration. Laparoscopic mesh procedures occupy the dominant volume position due to established reimbursement and surgeon training infrastructure, while robotic surgery represents the fastest-expanding procedural category as capital equipment availability broadens. Biologic mesh commands the highest margin pool within material segmentation, driven by its adoption in contaminated surgical fields where synthetic alternatives carry elevated infection risk.
FDA 510(k) premarket notification requirements and EU MDR technical documentation standards govern mesh biocompatibility, mechanical performance, and post-market surveillance obligations across the two largest addressable markets. Japan's PMDA and METI frameworks impose additional clinical data requirements that shape product registration timelines and market entry sequencing for foreign manufacturers. Stakeholders must monitor evolving regulatory divergence between FDA real-world evidence pathways and EU MDR notified body capacity constraints when prioritizing commercialization investments and portfolio rationalization decisions.
Market Dynamics
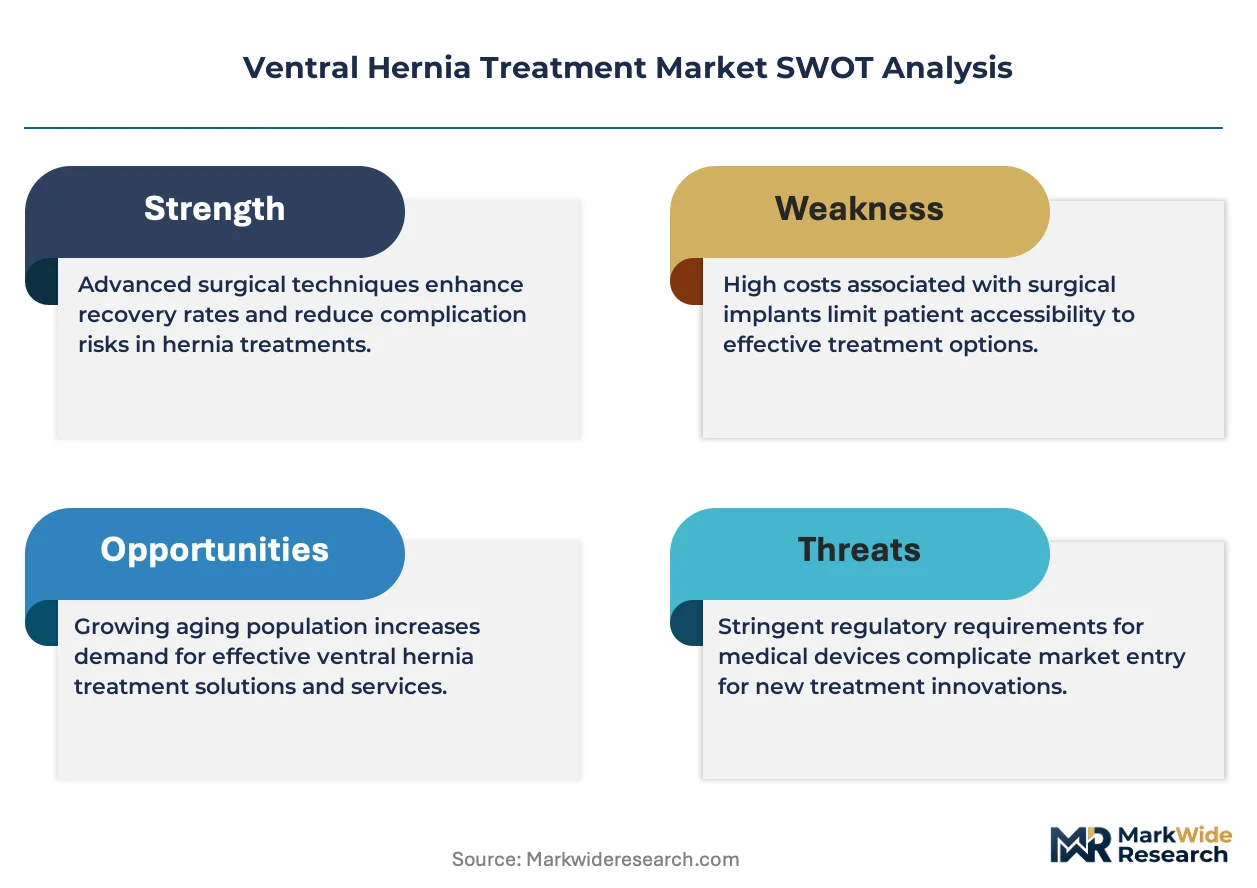
Mesh material science and procedural technique selection are bifurcating the competitive landscape between premium biologic platforms and commoditized synthetic alternatives, with reimbursement parity driving volume toward laparoscopic synthetic repair while complex cases sustain biologic premium pools.
Growth Catalysts
- FDA 510(k) Real-World Evidence Pathways:Accelerated clearance timelines for mesh iterations with established predicate devices compress regulatory friction for manufacturers with robust post-market surveillance infrastructure.
- Robotic Surgical System Deployment:Capital equipment expansion in United States hospital systems is creating trained surgeon cohorts capable of complex ventral hernia repair with reduced conversion rates.
- Biologic Mesh Adoption in Contaminated Fields:General surgery departments increasingly specify porcine or bovine-derived implants where synthetic infection risk elevates revision probability.
Market Restraints
- Polypropylene Raw Material Concentration:Petrochemical feedstock volatility and limited domestic resin production in key manufacturing geographies compress margin stability for synthetic mesh producers.
- EU MDR Notified Body Capacity Constraints:Extended technical documentation review timelines for legacy mesh products delay recertification and create supply discontinuity risk in European markets.
- Non-Mesh Suture Repair Resurgence:Component separation techniques without prosthetic reinforcement gain traction in select academic medical centers, threatening volume in specific defect classifications.
Strategic Opportunities
- Japan PMDA Clinical Data Requirements:Foreign manufacturers with prospective Japanese registry data capture first-mover positioning as domestic surgeons transition toward biologic alternatives.
- Mesh Surveillance and Revision Consultation Services:Post-implant monitoring programs create recurring revenue attachment to initial device placement, extending manufacturer patient lifetime value capture.
- Hybrid Fixation Technology Convergence:Integration of absorbable tacker systems with permanent mesh substrates reduces chronic pain incidence while maintaining recurrence prevention efficacy.
Industry Challenges
- Robotic Surgery Training Pipeline Bottlenecks:Proctored case volume requirements and simulator access constraints limit qualified surgeon supply expansion despite capital equipment availability.
- EU MDR Post-Market Clinical Follow-Up Burden:Systematic literature review obligations and periodic safety update report generation consume regulatory affairs bandwidth for diversified mesh portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ventral Hernia Treatment Market |
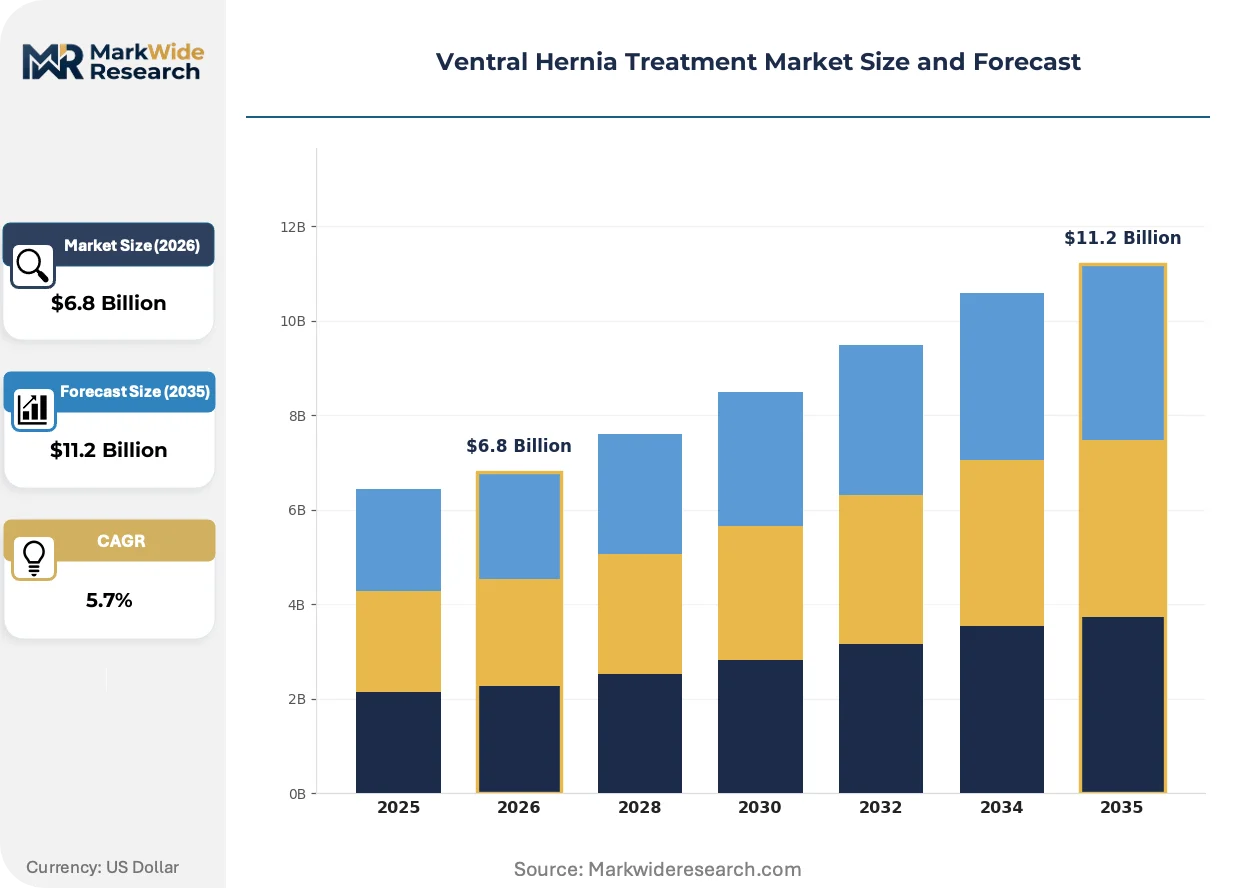
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laparoscopic Mesh, Open Repair, Robotic Surgery, Tissue Repair End User: Hospitals, Ambulatory Surgical Centers, Clinics, Rehabilitation Facilities Procedure Type: Elective Surgery, Emergency Surgery, Minimally Invasive Surgery, Robotic-Assisted Surgery Material: Polypropylene, Polyester, ePTFE, Biologic Mesh |
| Companies Covered | Medtronic plc, Becton, Dickinson and Company, Ethicon Inc., B. Braun SE, W. L. Gore & Associates, Inc., Integra LifeSciences Corporation, Cook Medical Inc., TELA Bio, Inc., Baxter International, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ventral Hernia Treatment Market Evolving Landscape
Procedural technique standardization and material biocompatibility advancement are compressing the gap between synthetic durability and biologic integration performance, reshaping surgeon preference formation and procurement evaluation criteria.
Resorbable synthetic mesh formulations incorporating delayed-absorption polymers are collapsing the historical trade-off between permanent mechanical support and long-term foreign body response. Academic medical centers in Germany and the United States are piloting these platforms in clean-contaminated cases previously reserved for biologics. The structural consequence is a compression of biologic mesh addressable market into severely contaminated or infected fields where synthetic resorption kinetics remain inadequate.
EU MDR technical documentation standards for Class III implantable devices are elevating clinical evidence requirements for mesh biocompatibility and mechanical performance characterization. Manufacturers face expanded post-market surveillance obligations including systematic literature review and periodic safety update reporting. Synthetic mesh portfolios with legacy predicate clearance pathways face the most pronounced compliance burden as notified bodies apply contemporary evidentiary standards to established products.
Hospital procurement committees are consolidating ventral hernia mesh purchasing through value-analysis frameworks that weight recurrence rate data against episode-of-care cost. United States integrated delivery networks are displacing individual surgeon preference with standardized formularies tiered by defect complexity and contamination risk. This behavioral shift concentrates volume with manufacturers capable of portfolio breadth spanning synthetic permanent, synthetic resorbable, and biologic platforms.
Ventral Hernia Treatment Market Segmentation
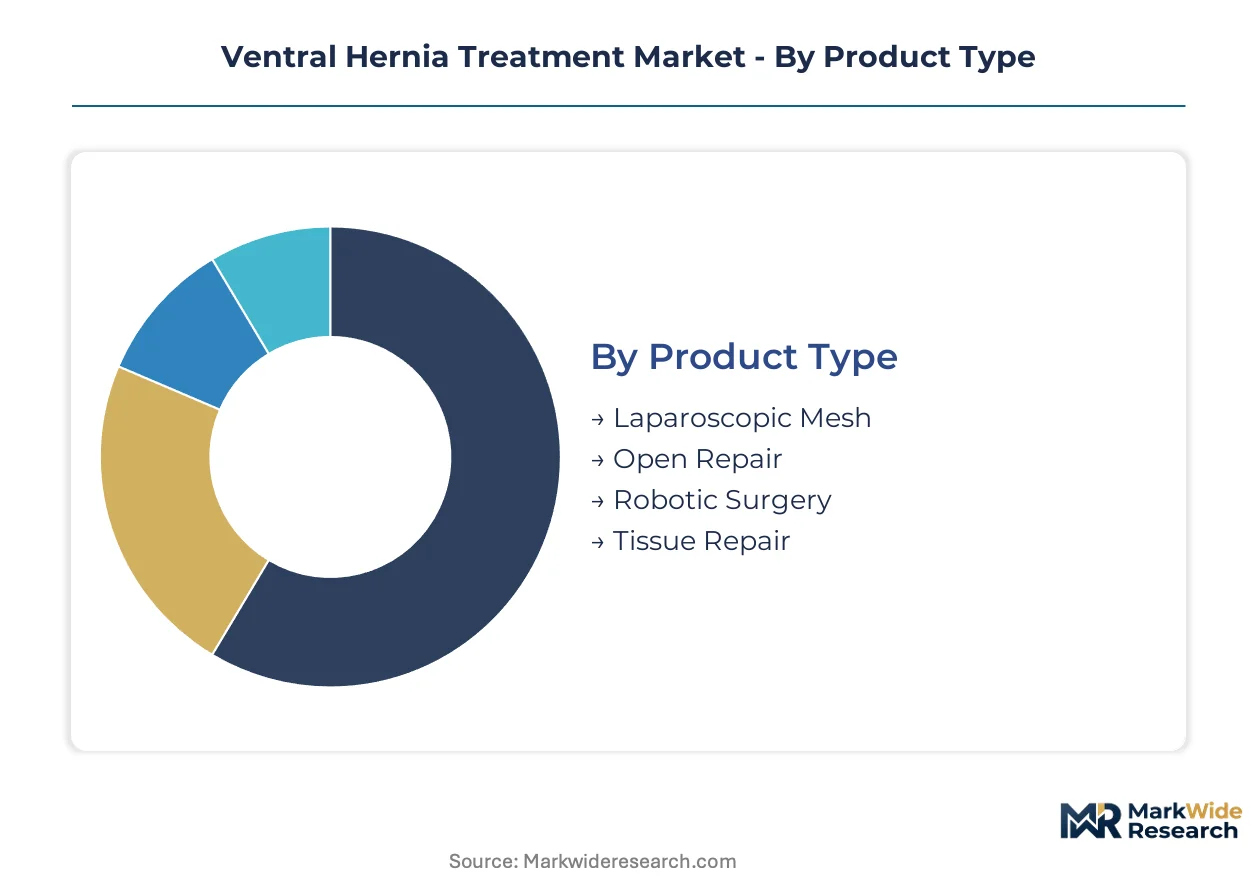
Mesh material selection and procedural technique determine recurrence outcomes, infection risk profiles, and reimbursement pathways across the ventral hernia treatment landscape. Manufacturers align portfolio breadth against hospital procurement standardization and surgeon training infrastructure.
Product Type:
Mature laparoscopic platforms dominate procedural volume while robotic systems represent the emerging expansion frontier.
- Laparoscopic Mesh:Polypropylene or polyester implants deployed through trocar access with intraperitoneal or extraperitoneal positioning. United States general surgery departments concentrate demand here due to established CPT reimbursement codes and fellowship-trained surgeon supply.
- Robotic Surgery:da Vinci or comparable platforms enabling sutured fascial closure with mesh reinforcement in complex defects. United States hospital systems with capital equipment availability drive fastest expansion as proctored training pipelines mature.
- Open Repair:Traditional laparotomy with mesh overlay or sublay techniques for giant hernias or hostile abdomen cases.
- Tissue Repair:Component separation without prosthetic mesh in contaminated fields or patient preference scenarios.
Laparoscopic Mesh retains volume leadership; Robotic Surgery holds the steepest expansion curve.
End User:
Facility reimbursement tiers and episode-of-care accountability reshape patient routing and device procurement concentration.
- Hospitals:Academic medical centers and community hospitals with 24-hour emergency general surgery coverage manage complex ventral hernia cases requiring mesh revision capability. Germany's DRG-based hospital funding concentrates high-acuity procedures in certified visceral surgery departments.
- Ambulatory Surgical Centers:Freestanding facilities capturing elective umbilical and small incisional hernias with same-day discharge protocols. United States commercial payor contracts favor ASC site-of-service differentials for straightforward laparoscopic repairs.
- Clinics:Outpatient settings handling diagnosis, preoperative optimization, and postoperative surveillance.
- Rehabilitation Facilities:Post-acute centers managing wound care and functional recovery after complex repairs.
Hospitals anchor the highest-acuity volume; Ambulatory Surgical Centers are climbing the fastest as site-of-service shifts accelerate.
Procedure Type:
Clinical urgency and technical approach stratify resource intensity, mesh selection, and outcome risk profiles.
- Elective Surgery:Scheduled repairs with optimized patient comorbidities and prehabilitation protocols. Japan's aging surgical population concentrates demand here as PMDA-approved biologic meshes gain traction in clean-contaminated preoperative planning.
- Emergency Surgery:Incarcerated or strangulated hernias requiring immediate intervention with elevated infection risk. Contaminated operative fields in these cases sustain premium biologic mesh positioning against synthetic alternatives.
- Minimally Invasive Surgery:Laparoscopic or robotic approaches with reduced wound complications versus open techniques.
- Robotic-Assisted Surgery:Computer-enhanced precision for complex abdominal wall reconstruction with intracorporeal suturing.
Elective Surgery commands the volume base; Emergency Surgery maintains the highest per-procedure margin contribution.
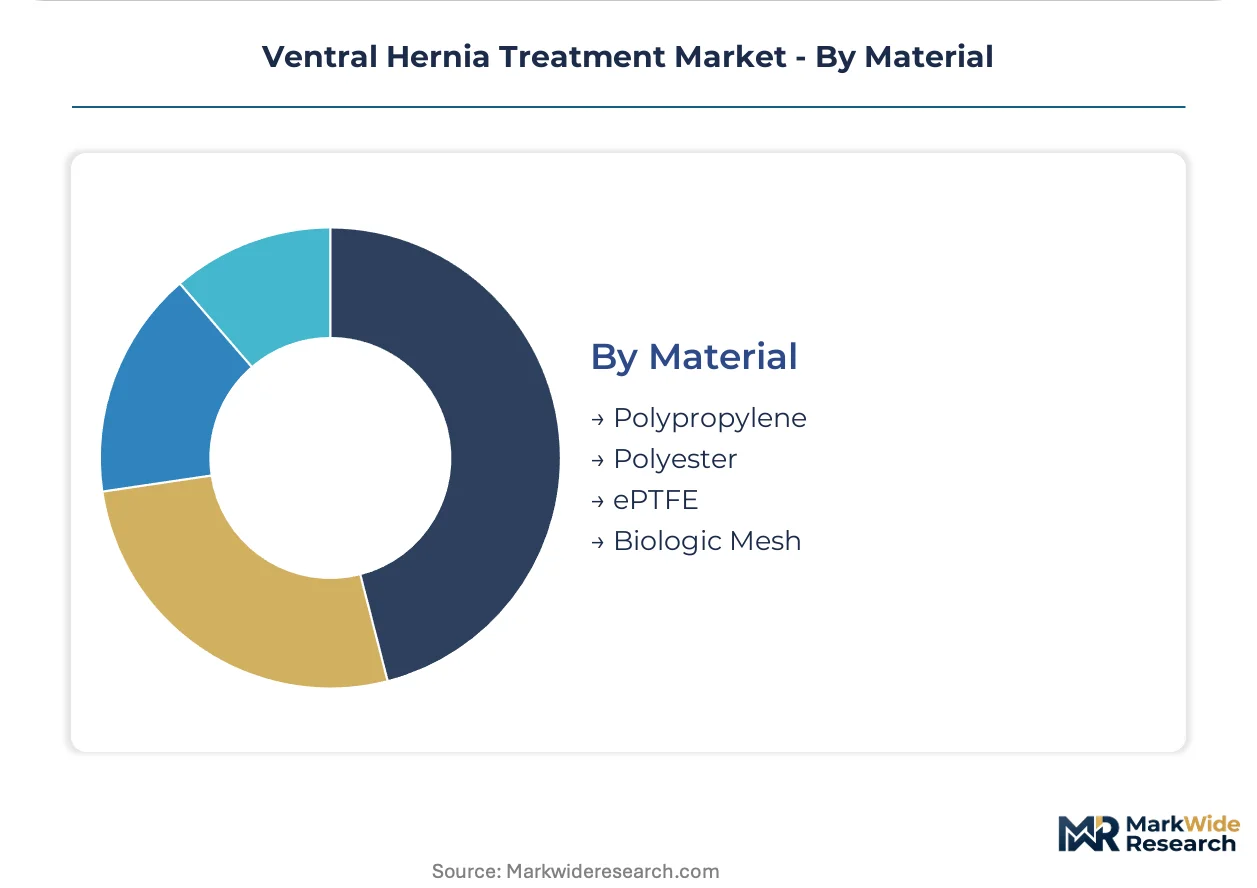
Material:
Biocompatibility profiles and mechanical durability trade-offs segment pricing power and clinical indication boundaries.
- Biologic Mesh:Porcine dermal or bovine pericardial matrices providing scaffold for host tissue integration with complete resorption. United States academic centers specify these in contaminated or infected fields where synthetic permanent implants carry unacceptably elevated explantation risk.
- Polypropylene:Lightweight macroporous monofilament synthetic with decades of clinical surveillance data and lowest unit cost. Volume procurement contracts in German hospital networks standardize on polypropylene for clean elective cases.
- Polyester:Multifilament synthetic with distinct handling characteristics and alternative pore architecture.
- ePTFE:Expanded polytetrafluoroethylene with microporous structure reducing visceral adhesion formation.
Polypropylene sustains volume leadership; Biologic Mesh commands the steepest margin expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mesh manufacturing clusters concentrate in the United States, Germany, and Japan, with each geography shaping distinct regulatory pathways and surgeon training infrastructure that determine commercialization sequencing.
United States
Academic medical centers in Boston and Houston drive biologic mesh adoption for contaminated field repairs. FDA 510(k) real-world evidence pathways accelerate predicate-based clearances for established manufacturers. The Cleveland Clinic and Mayo Clinic anchor prospective registry generation that shapes surgeon preference formation.
Germany
DRG-based hospital funding concentrates complex ventral hernia volume in certified visceral surgery departments across Bavaria and North Rhine-Westphalia. EU MDR notified body capacity constraints delay legacy product recertification, creating supply discontinuity risk. Berlin's Charité hospital network pilots resorbable synthetic platforms in clean-contaminated cases.
Japan
Aging surgical populations and PMDA clinical data requirements concentrate demand in elective biologic mesh procedures. METI frameworks impose additional post-market surveillance obligations that extend registration timelines. Osaka's Kansai region anchors surgeon training infrastructure for robotic-assisted ventral hernia repair.
United Kingdom
NHS England's value-based procurement frameworks standardize mesh formularies across integrated care systems in London and the Midlands. MHRA post-Brexit regulatory divergence from EU MDR creates parallel compliance pathways. Manchester's academic surgical centers generate real-world evidence supporting hybrid fixation technology adoption.
France
ANSM vigilance reporting requirements and HAS health technology assessment shape reimbursement for premium mesh platforms in Paris and Lyon hospital networks. The country's surgical society guidelines increasingly specify biologic alternatives in contaminated fields. Toulouse's aerospace-adjacent manufacturing base supplies specialized polymer feedstocks for synthetic mesh production.
Ventral Hernia Treatment Market Competitive Landscape
Integrated surgical ecosystems and specialized material science platforms split the market between diversified conglomerates and focused technology developers. Tiered competitive positioning emerges from portfolio breadth spanning synthetic permanent, synthetic resorbable, and biologic mesh alternatives. Three archetypes dominate: diversified medtech conglomerates with distribution scale, specialized biomaterial developers with proprietary polymer science, and robotic surgical system vendors capturing procedural pull-through. Manufacturers defend position through M&A targeting complementary fixation technologies and strategic partnerships with academic medical centers for clinical evidence generation.
Within the diversified conglomerate tier, Medtronic plc and Becton, Dickinson and Company anchor global distribution infrastructure across acute care settings. W. L. Gore & Associates, Inc. exemplifies the specialized material science archetype, occupying premium positioning through proprietary ePTFE platforms. These three entities represent distinct competitive vectors—scale-driven procurement consolidation, acute care channel control, and complex case premium capture—that collectively define market structure.
| Leading Market Players |
|---|
| Medtronic plc |
| Becton, Dickinson and Company |
| Ethicon Inc. |
| B. Braun SE |
| W. L. Gore & Associates, Inc. |
| Integra LifeSciences Corporation |
| Cook Medical Inc. |
| TELA Bio, Inc. |
| Baxter International, Inc. |
| Others |
Value Network & Pricing Analysis
Undercapacity in EU MDR notified body review capacity is compressing recertification timelines for legacy mesh portfolios, forcing manufacturers to prioritize premium biologic platforms where pricing power remains intact while synthetic producers absorb margin pressure from delayed market access.
Pricing Analysis
FDA 510(k) predicate pathways dictate the pricing tier structure across the ventral hernia treatment landscape. Three-tier pricing stratifies across biologic premium, synthetic permanent standard, and synthetic lightweight economy levels, with contamination risk and defect complexity as the primary differentiation drivers. Cost compression in polypropylene segments is intensifying because of petrochemical feedstock volatility and hospital procurement consolidation into value-analysis frameworks. Ambulatory surgical centers exhibit the highest price sensitivity due to fixed reimbursement rates, while academic medical centers prioritize recurrence outcome data over unit cost.
Supply Chain Analysis
Export-control restrictions on advanced polymer manufacturing equipment limit capacity expansion in certain jurisdictions, constraining supply elasticity for specialized mesh substrates. Manufacturing concentrates in the United States, Germany, and Japan, with each geography anchoring distinct regulatory cluster production. Raw material flows draw from petroleum-derived polypropylene resin, porcine and bovine tissue processing facilities, and fluoropolymer feedstocks for ePTFE platforms. Single-source vulnerability in biologic tissue processing creates supply continuity exposure during animal health events. Distribution runs through hospital procurement committees and group purchasing organizations that consolidate volume across integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating in United States integrated delivery networks and German DRG-funded hospital systems, fragmenting individual surgeon preference and forcing manufacturers to defend position through portfolio breadth rather than product-specific loyalty.
For Market Incumbents: Entrench market position by securing GPO contracts that span synthetic permanent, synthetic resorbable, and biologic mesh tiers, while investing in robotic surgery training infrastructure to capture procedural pull-through revenue. Non-mesh suture repair resurgence in academic centers threatens volume in select defect classifications, requiring clinical evidence generation that demonstrates recurrence rate superiority. Backward integration into biologic tissue processing secures supply continuity against animal health disruptions. For New Entrants and Emerging Players: Build out presence in Japan's elective biologic mesh segment where PMDA clinical data requirements create first-mover barriers for established competitors. Mesh surveillance and revision consultation services represent the most penetrable white-space opportunity, enabling recurring revenue attachment to initial device placement. Target hospital value-analysis committees with bundled pricing that combines mesh, fixation devices, and post-implant monitoring protocols. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among manufacturers with integrated surgical ecosystems spanning capital equipment, consumables, and training services. Long-term viability over the coming decade hinges on regulatory affairs bandwidth capable of navigating divergent FDA real-world evidence and EU MDR post-market surveillance obligations. Acquisition targets should demonstrate prospective registry data generation in Japan or hybrid fixation technology portfolios. The signal to watch is EU MDR notified body capacity expansion timelines, which would release pent-up supply and reshape competitive dynamics.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Mayo Clinic and Cleveland Clinic registry data shapes surgeon preference formation across academic centers. |
| FDA 510(k) Real-World Evidence Pathway | Established predicate clearances compress regulatory friction for mesh iteration launches. |
| Biologic Mesh Manufacturing Scale-Up | Porcine tissue processing capacity expansion addresses supply constraints in contaminated field applications. |
| Robotic Surgery Training Program | Proctored case pipelines at Houston and Boston centers expand qualified surgeon supply. |
| EU MDR Recertification Strategy | Notified body engagement prioritizes biologic platforms with highest margin preservation potential. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR technical documentation, hospital procurement databases, and GPO contract disclosures. Primary interviews engaged general surgeons, hospital purchasing committee members, biomedical engineers, regulatory affairs directors at mesh manufacturers, and GPO contracts managers. Secondary validation drew from CMS Medicare reimbursement data, DRG tariff schedules, and PMDA approval records. Bottom-up procedure volume estimates and top-down manufacturer revenue triangulation anchored market sizing.
Forecast inputs include procedural technique adoption curves, mesh material substitution patterns, capital equipment deployment timelines, and regulatory pathway evolution across the projection horizon. Segmentation modeling incorporates product type, end user facility tier, procedure urgency, and material biocompatibility class alongside regional regulatory cluster dynamics. CAGRs derive from trend extrapolation against historical procedure growth and reimbursement rate stability. Japan's aging surgical population and United States ASC site-of-service shifts represent key demand-side inputs.
Stress conditions across EU MDR notified body capacity, polypropylene resin price volatility, and robotic surgery training pipeline bottlenecks were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions about regulatory divergence stability and hospital procurement consolidation velocity. Material shifts in FDA real-world evidence pathway scope or EU MDR post-market clinical follow-up burden would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Refsum Disease Treatment Market
Medical Treatment
US Hyperbaric Oxygen Therapy (HBOT) Market
Medical Treatment
Pompe Disease Treatment Market
Medical Treatment
Monkeypox Treatment Market
Medical Treatment
Liver Transplantation Market
Medical Treatment
Tennis Elbow Treatment Market
Medical Treatment
Bloch-Sulzberger Treatment Market
Medical Treatment
Laser Therapy Market
Medical Treatment
Liver Fluke Treatment Market
Medical Treatment
Asthma Treatment Market
Medical Treatment
Cephalic Disorders Treatment Market
Medical Treatment
Myotonic Dystrophy Treatment Market
Medical Treatment
Facial Spasm Treatment Market
Medical Treatment
Acupuncture Treatment Market
Medical Treatment
Basal Cell Carcinoma Treatment Market
Medical Treatment
Lysosomal Storage Disease Treatment Market