
 Recycled Steel Market | 2026-2036
Recycled Steel Market Size, Share, and Industry Trends Forecast 2026-2036
Recycled Steel Market Outlook
Automotive sector procurement is realigning toward low-emission flat-rolled grades as OEMs face Scope 3 disclosure rules. Nucor Corporation leverages electric arc furnace scale to anchor North American supply contracts for vehicle-grade sheet. ArcelorMittal competes through integrated recycling-to-automotive pathways across European mill networks. Tata Steel dominates Indian flat-rolled recycling with captive scrap sourcing tied to domestic automotive programs.
Recycled steel comprises ferrous scrap reprocessed through electric arc furnace or basic oxygen furnace routes, typically yielding products with total metallic content above 90 percent and controlled residual copper levels below 0.40 percent for deep-drawing applications. Its primary purpose centers on reducing primary iron ore dependency while cutting carbon dioxide intensity per ton of finished steel. Hot rolled and cold rolled sheet categories lead value generation, with reinforcing bars representing the highest-volume but lower-margin structural segment. Stainless steel recycling commands premium positioning due to nickel and chromium recovery economics, while low carbon grades attract automotive qualification programs.
The US EPA enforces scrap handling and air emission standards at electric arc furnace facilities, while the EU Green Deal and REACH frameworks impose carbon border adjustments that favor verified low-emission recycled content. China's MEE enforces dual carbon compliance thresholds that reshape scrap import quality requirements and domestic collection infrastructure. Stakeholders must monitor evolving carbon accounting methodologies and scrap quality certification schemes to secure premium contract tiers.
Market Dynamics
Carbon border adjustments are compressing cost structures for secondary steel producers while fragmenting procurement qualifications across automotive and construction value chains.
Growth Catalysts
- EU Green Deal carbon border adjustments:Verified low-emission recycled content secures premium contract tiers from automotive OEMs facing Scope 3 disclosure mandates.
- Electric arc furnace technology:Scrap-to-steel processing cuts carbon dioxide intensity per ton versus basic oxygen furnace routes, attracting ESG-linked financing.
- India's western industrial corridor:PLI scheme incentives accelerate secondary steel capacity additions targeting domestic automotive programs.
Market Restraints
- Scrap quality volatility:Residual copper contamination above 0.40 percent disqualifies deep-drawing grades for automotive sheet applications.
- China's MIIT dual carbon enforcement:Tightening scrap-to-steel ratios at electric arc furnace operators constrain feedstock flexibility.
- Primary iron ore price cycles:Volatile seaborne ore costs compress recycled steel margin spreads during downcycles.
Strategic Opportunities
- India's construction sector:Underpenetrated reinforcing bar demand in tier-two cities creates volume expansion potential for secondary producers.
- Stainless steel recycling:Nickel and chromium recovery economics command premium positioning in medical and food-processing equipment.
- EU REACH framework:Extended producer responsibility mandates create closed-loop collection infrastructure partnerships.
Industry Challenges
- Scrap sorting automation:Sensor-based separation systems require capital deployment that mid-scale operators struggle to fund.
- Automotive qualification timelines:OEM material certification cycles stretch 18-24 months, delaying volume ramp for new recycled grade entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recycled Steel Market |
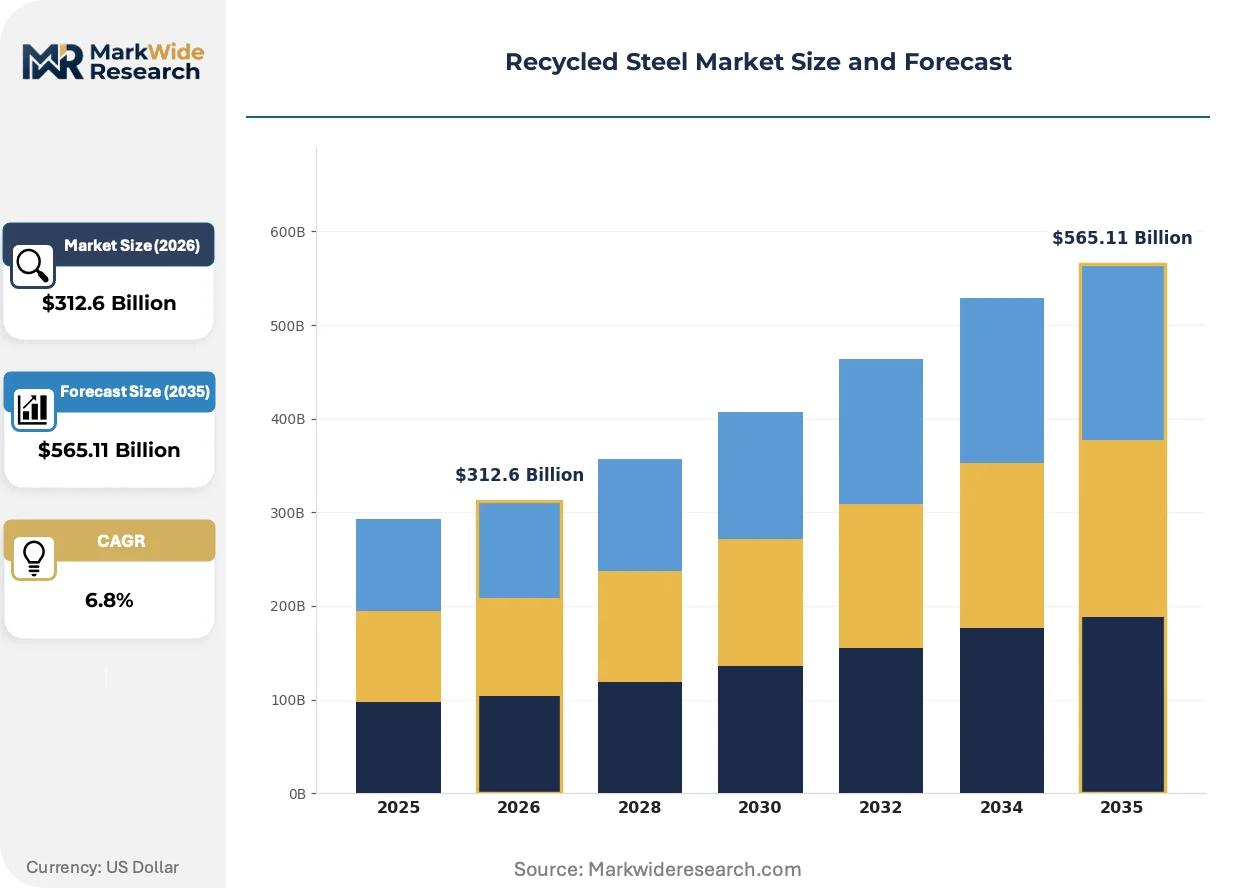
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $565.11 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
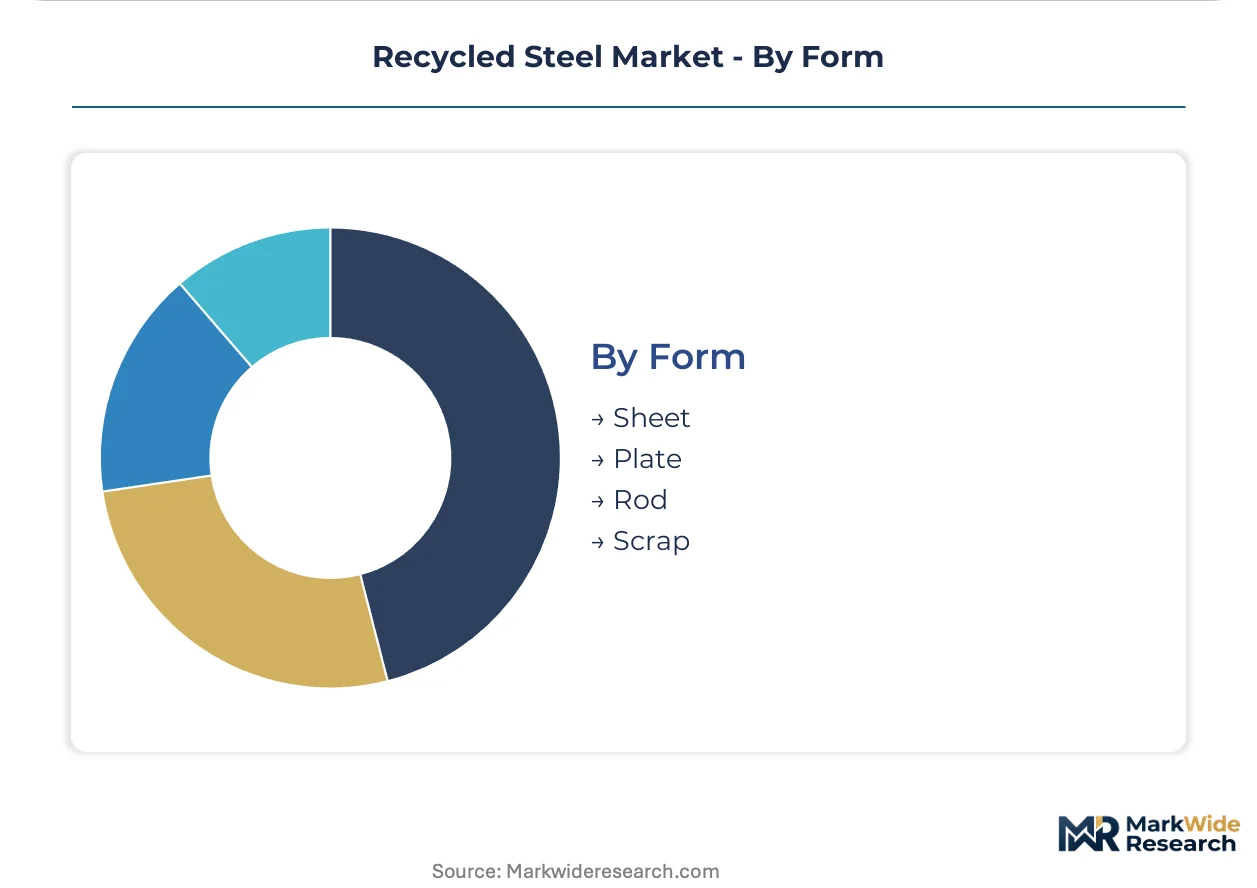
| Segmentation | Product Type: Hot Rolled, Cold Rolled, Reinforcing Bars, Stainless Steel End User: Construction, Automotive, Shipbuilding, Manufacturing Grade: Structural, High Strength, Alloy, Low Carbon Form: Sheet, Plate, Rod, Scrap |
| Companies Covered | ArcelorMittal, Nucor Corporation, Steel Dynamics, Tata Steel, Schnitzer Steel Industries, European Metal Recycling Limited, Sims Metal Management, DOWA Holdings, Aurubis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recycled Steel Market Strategic Shifts
Digital traceability systems and automated scrap characterization are compressing quality assurance timelines while enabling mass-customization of recycled steel grades.
Artificial intelligence-driven scrap composition analysis is decentralizing quality control from centralized labs to furnace-floor sensors. Automotive OEMs are piloting real-time chemistry verification to compress incoming inspection cycles. This capability is decentralizing supplier qualification from incumbent mill networks to regional scrap processors.
China's MEE dual carbon compliance thresholds are reshaping scrap import quality requirements and domestic collection infrastructure. Electric arc furnace operators must document carbon intensity per heat to maintain operating licenses. Secondary producers in Shandong and Hebei provinces are retrofitting emissions monitoring systems to meet tightened verification protocols.
Automotive procurement teams are consolidating supplier lists around certified low-carbon flat-rolled grades with embedded carbon accounting. Tier-one stamping plants are replacing spot-market purchases with multi-year offtake agreements tied to verified Scope 3 reductions. This pattern concentrates most visibly in Germany's automotive supply chain, where KBA vehicle certification now references steel carbon intensity.
Recycled Steel Market Segmentation
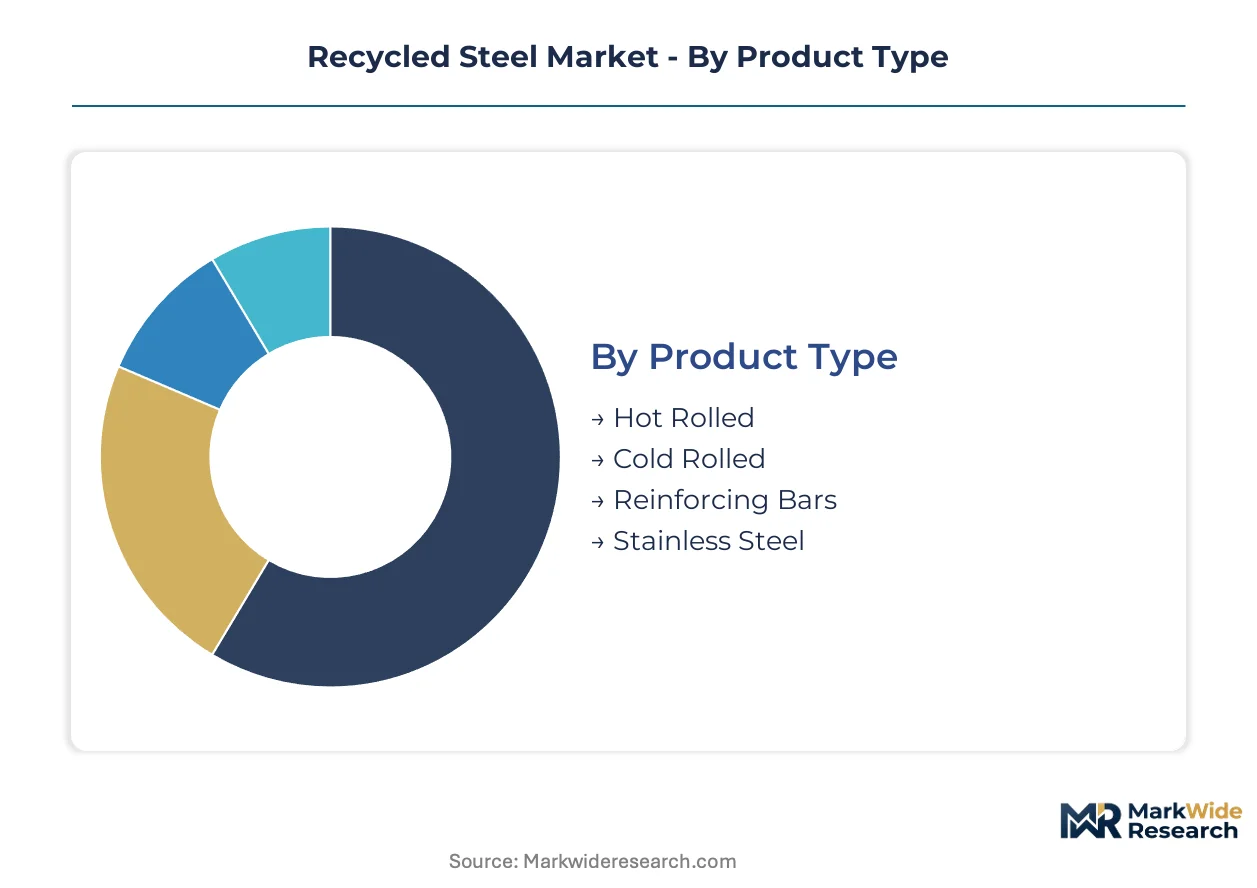
Recycled steel segmentation reflects divergent technical specifications across end-use qualification thresholds. Product form and metallurgical grade determine furnace routing, carbon intensity accounting, and contract pricing tiers.
Product Type:
Customization intensity spans from commodity reinforcing bars to precision-tolerance cold rolled sheet.
- Hot Rolled:Produced directly from electric arc furnace or basic oxygen furnace routes without subsequent cold reduction. Automotive chassis and structural frame demand concentrates in Germany's Ruhr Valley and India's Maharashtra corridor, where OEMs enforce sub-0.30 percent residual copper specifications for weldability certification.
- Cold Rolled:Annealed and temper-rolled to tight dimensional tolerances below 0.5 millimeter thickness variation. Body-in-white panel procurement from European automotive networks requires embedded carbon accounting under EU Green Deal verification protocols, compressing supplier qualification timelines to 18-month cycles.
- Reinforcing Bars:High-volume structural concrete reinforcement with lower residual element constraints.
- Stainless Steel:Nickel and chromium recovery from end-of-life equipment commands premium positioning in medical and food-processing applications.
Most installed capacity flows through Hot Rolled. Expansion is steepest in Cold Rolled.
End User:
Cost tier stratification separates spot-market construction procurement from multi-year automotive offtake agreements.
- Construction:Reinforcing bar and structural section demand concentrates in India's tier-two urban corridors, where PLI scheme incentives accelerate secondary steel capacity additions. Project developers prioritize landed cost over carbon certification, fragmenting supplier relationships across regional scrap processors.
- Automotive:OEM material certification cycles stretch 18-24 months for flat-rolled grades. Scope 3 disclosure mandates under EU Green Deal frameworks are consolidating procurement around verified low-emission suppliers with furnace-level emissions monitoring.
- Shipbuilding:Plate thickness requirements above 50 millimeters favor basic oxygen furnace routes with scrap supplementation.
- Manufacturing:General industrial fabrication spans multiple product forms with variable quality specifications.
Construction absorbs the highest tonnage volumes. Automotive commands the steepest price premiums per ton.
Grade:
Metallurgical sophistication determines scrap blend flexibility and residual element control thresholds.
- Structural:Standard carbon-manganese compositions for general fabrication with tolerant residual specifications.
- High Strength:Microalloyed with niobium or vanadium for weight reduction in automotive and construction applications.
- Alloy:Engineered chromium, molybdenum, or nickel additions for wear resistance and elevated temperature service.
- Low Carbon:Sub-0.10 percent carbon content enables deep-drawing deformation for automotive body panels. Residual copper contamination above 0.40 percent disqualifies sheet for tier-one stamping plants, forcing segregated scrap collection infrastructure.
Structural grade dominates current melt shop output. Low Carbon is gaining share fastest under automotive decarbonization programs.
Form:
Supply chain configuration separates furnace-feed scrap from finished mill products with divergent logistics economics.
- Sheet:Cold rolled and coated flat products for automotive and appliance manufacturing.
- Plate:Heavy-gauge material for shipbuilding, pressure vessels, and heavy equipment frames.
- Rod:Wire-drawing feedstock for fasteners, welding electrodes, and concrete reinforcement mesh.
- Scrap:Unprocessed ferrous feedstock graded by density, metallic content, and residual contamination. China's MEE dual carbon enforcement is tightening scrap-to-steel ratio documentation at electric arc furnace operators, reshaping import quality requirements and domestic collection infrastructure.
Sheet and Plate concentrate finished product value. Scrap form is expanding most quickly as furnace capacity multiplies in India and Southeast Asia.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Ruhr Valley automotive stamping corridor concentrates demand for verified low-carbon flat-rolled grades. Electric arc furnace operators across four continents are retrofitting emissions monitoring systems to capture carbon border adjustment premiums. Scrap collection infrastructure is expanding fastest in industrial corridors tied to government production-linked incentive schemes.
United States
Nucor Corporation anchors North American supply contracts for vehicle-grade sheet from electric arc furnace complexes in the Carolinas. EPA air emission standards at EAF facilities enforce continuous stack monitoring and reporting thresholds. Detroit-area automotive stamping plants are replacing spot-market purchases with multi-year offtake agreements tied to Scope 3 disclosure mandates.
Germany
KBA vehicle certification now references steel carbon intensity, compressing supplier qualification timelines for body-in-white panel procurement. EU Green Deal carbon border adjustments favor verified low-emission recycled content from Ruhr Valley mill networks. Flat-rolled recycling pathways across European integrated networks are consolidating procurement around furnace-level emissions monitoring.
China
MIIT dual carbon goals are tightening scrap-to-steel ratios at electric arc furnace operators in Shandong and Hebei provinces. MEE compliance thresholds reshape scrap import quality requirements and domestic collection infrastructure. EAF operators must document carbon intensity per heat to maintain operating licenses under tightened verification protocols.
India
PLI scheme incentives accelerate secondary steel capacity additions targeting domestic automotive programs in Maharashtra and Gujarat. BIS standards enforcement is upgrading quality certification for reinforcing bar and structural section output. Western industrial corridor project developers in tier-two urban corridors prioritize landed cost over carbon certification, fragmenting supplier relationships.
Japan
METI circular economy directives are expanding end-of-life vehicle dismantling infrastructure for high-grade scrap recovery. JIS standards for residual copper content in deep-drawing grades enforce sub-0.40 percent thresholds for automotive qualification. Kansai region stainless steel recyclers command premium positioning in medical and food-processing equipment through nickel and chromium recovery economics.
Recycled Steel Market Competitive Environment
Capacity expansion dominates the current landscape as electric arc furnace operators retrofit emissions monitoring systems to capture carbon border adjustment premiums. The vendor base stratifies across three tiers: integrated steelmakers with captive scrap sourcing, independent EAF specialists with regional mill networks, and pure-play scrap processors feeding external furnace operators. Two competitive vectors are reshaping positioning: backward integration into scrap collection infrastructure, and multi-year offtake agreements with automotive OEMs tied to verified Scope 3 reductions.
Among North American EAF specialists, Nucor Corporation and Steel Dynamics occupy positions anchored by scale advantages in flat-rolled vehicle-grade supply. ArcelorMittal represents the integrated recycling-to-automotive pathway archetype across European mill networks. Tata Steel exemplifies captive scrap sourcing tied to domestic automotive programs in emerging secondary steel markets. Schnitzer Steel Industries sits within the pure-play scrap processor tier, feeding external furnace operators without downstream mill ownership. These archetypes illustrate how carbon accounting verification capabilities are becoming the primary sorting mechanism for premium contract tier access.
| Leading Market Players |
|---|
| ArcelorMittal |
| Nucor Corporation |
| Steel Dynamics |
| Tata Steel |
| Schnitzer Steel Industries |
| European Metal Recycling Limited |
| Sims Metal Management |
| DOWA Holdings |
| Aurubis |
| Others |
Value Chain & Pricing Dynamics
Automotive OEM procurement consolidation around verified low-carbon flat-rolled grades is compressing supplier margins while rewarding furnace-level emissions documentation with premium contract tiers. This buyer-side pressure forces electric arc furnace operators to absorb sensor-based quality control costs or surrender volume to integrated competitors with captive scrap infrastructure.
Pricing Analysis
Scrap cost pass-through dominates contract pricing, with seaborne ore volatility and residual copper contamination penalties acting as dual margin levers. Pricing stratifies across premium, standard, and economy tiers based on embedded carbon certification under EU Green Deal protocols and automotive qualification status. Cost compression in standard grades is intensifying as Chinese MIIT dual carbon enforcement tightens scrap-to-steel ratios. Construction procurement teams in India's tier-two corridors exhibit highest price sensitivity, while German automotive stamping plants accept material premiums for KBA-referenced carbon intensity verification.
Supply Chain Analysis
Skilled furnace operator availability constrains capacity expansion in India's Maharashtra-Gujarat corridor and Germany's Ruhr Valley mill networks. Supply concentrates in China, the United States, and India, with feedstock draws from post-consumer demolition scrap and end-of-life vehicle dismantling. Single-source vulnerability sits with concentrated nickel and chromium recovery streams for stainless steel grades. Distribution runs through mill-direct offtake agreements for automotive sheet and spot-market intermediaries for reinforcing bar.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The recycled steel market compounds steadily as carbon border adjustments permanently restructure procurement qualification thresholds across automotive and construction value chains.
For Market Incumbents: Deepen backward integration into segregated scrap collection infrastructure to control residual copper contamination below 0.40 percent thresholds for automotive deep-drawing grades. Invest in furnace-floor sensor networks to compress quality assurance timelines and defend contract tiers against emerging EAF specialists with digital traceability capabilities. For New Entrants and Emerging Players: Digital-channel scrap sourcing platforms offer the lowest-friction entry path into fragmented regional collection markets. Target India's western industrial corridor reinforcing bar demand, where PLI scheme incentives lower capital barriers and BIS standards enforcement remains uneven. Pursue construction sector procurement relationships before attempting automotive qualification cycles. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale EAF operators in Southeast Asia possessing furnace capacity but lacking emissions monitoring certification. Five-to-ten year viability hinges on carbon accounting infrastructure deployment rather than raw scale. Watch for MIIT dual carbon compliance threshold tightening as the signal for distressed asset availability in China's Shandong and Hebei provinces.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Scrap Collection | Captive feedstock secures residual copper control for automotive sheet qualification under EU Green Deal protocols. |
| Furnace-Level Emissions Monitoring Deployment | Real-time carbon intensity documentation unlocks premium contract tiers from Scope 3-disclosure-mandated OEMs. |
| Automotive Qualification Program Investment | Eighteen-to-twenty-four month certification cycles create durable switching costs against unqualified competitors. |
| Regional EAF Capacity Expansion | PLI scheme incentives in India's western corridor accelerate secondary steel output for domestic construction demand. |
| Stainless Steel Recovery Infrastructure | Nickel and chromium recovery economics command medical and food-processing equipment premiums through METI circular economy channels. |
Study Parameters
Direct dialogue with electric arc furnace operators, automotive Tier 1 procurement directors, scrap processing facility managers, and regulatory compliance officers at MIIT and MEE grounded qualitative assessment. Secondary validation drew from EPA air emission filings, EU Green Deal carbon border adjustment documentation, BIS standards publications, and customs trade data for ferrous scrap flows. Bottom-up capacity modeling and top-down demand segmentation were triangulated against furnace-level production estimates.
Bottom-up volume builds aggregated individual EAF facility output across product form and grade specifications, while top-down demand splits traced automotive, construction, and manufacturing end-use consumption. Segmentation dimensions spanned product type, metallurgical grade, and regional regulatory cluster throughout the forecast period. CAGR derivation rested on scrap-to-steel ratio enforcement trajectories and electric arc furnace technology diffusion curves.
The model assumes a particular technology adoption path; alternative pathways for AI-driven scrap composition analysis would alter the outlook for decentralized quality control economics. Forecasts reflect assumptions regarding MIIT dual carbon compliance timelines and EU Green Deal carbon border adjustment implementation. Material deviation in automotive OEM procurement consolidation patterns or primary iron ore price cycle amplitude warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Nickel Nano Powder Market
Metals & Minerals
Cobalt Carbonate Market
Metals & Minerals
Dead Sea Mineral Market
Metals & Minerals
Flake Graphite Market
Metals & Minerals
Precious Metals E-Waste Recovery Market
Metals & Minerals
Gold Recycling Market
Metals & Minerals
Global Magnesium Market
Metals & Minerals
Ilmenite Market
Metals & Minerals
Global Lithium Market
Metals & Minerals
Cobalt Nitrate Market
Metals & Minerals
Global Base Metal Mining Market
Metals & Minerals
Testing Inspection and Certification TIC for the Metals and Minerals Market
Metals & Minerals
Recycled Scrap Metal Market
Metals & Minerals
Pre-Painted Galvanised Iron (PPGI) Market
Metals & Minerals
20MnCr5 Steel Market
Metals & Minerals
Prefab Iron Market