

Copper Chromium Black Market Size, Share, and Industry Trends Forecast 2026-2036
Copper Chromium Black Market Insights
Buyer concentration across the copper chromium black value chain is broadening as aerospace manufacturers consolidate pigment procurement under fewer tier-one suppliers while specialty coatings formulators fragment into niche regional buyers. The Shepherd Color Company leverages its Cincinnati-based manufacturing footprint to sustain supply continuity for North American heat-resistant coating customers. Vibrantz Technologies anchors its position through integrated colorant R&D laboratories in the United States and Europe. Heubach competes by controlling legacy pigment distribution networks that reach smaller metal plating firms across Western Europe.
Copper chromium black denotes a mixed-metal oxide pigment with a spinel crystal structure, typically synthesized through high-temperature calcination of copper and chromium precursors at temperatures exceeding 800°C, yielding a jet-black powder with exceptional thermal stability and infrared reflectance properties valued in solar-absorptive and camouflage coatings. The copper-chromium alloy segment dominates volume flows into aerospace component finishing, where thermal barrier specifications are most stringent. Surface coating applications represent the fastest-expanding demand pool as architectural ceramic producers in Asia adopt infrared-reflective dark pigments for energy-efficient building materials.
EPA oversight of hexavalent chromium emissions shapes permissible manufacturing processes for U.S.-based pigment producers, while REACH registration requirements in Europe mandate full toxicity dossiers for copper chromium black imports. China's SAMR enforces GB standards on heavy metal migration limits in ceramics and toys, directly conditioning export eligibility for domestic pigment manufacturers. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation costs and qualify alternative supply sources before compliance deadlines tighten.
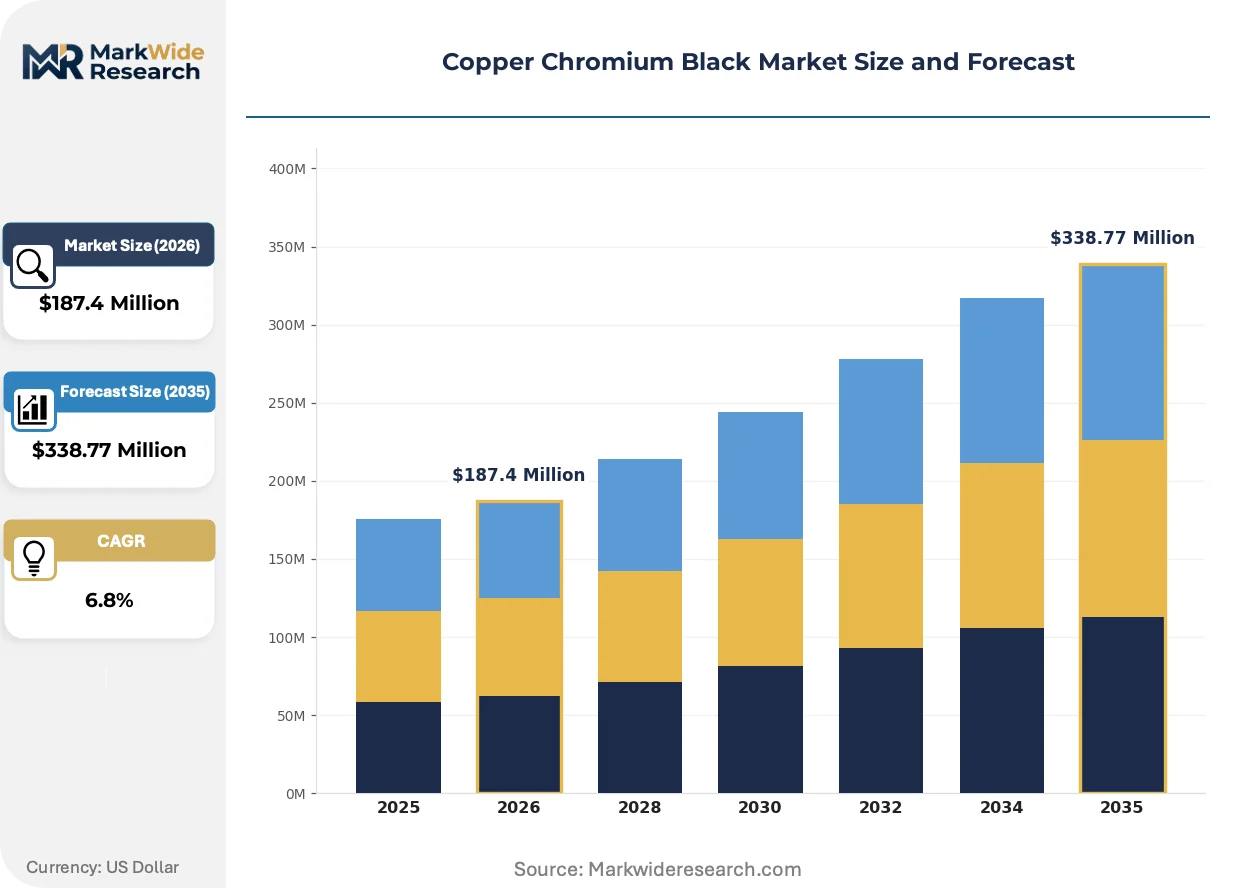
Market Dynamics
REACH registration dossiers and EPA hexavalent chromium emission limits are forcing simultaneous reformulation of legacy pigment grades and qualification of alternative supply sources before compliance deadlines tighten.
Growth Catalysts
- Aerospace thermal barrier specifications:Heat-resistant coating requirements for engine components and exhaust systems are pulling copper chromium black into high-temperature formulations.
- China's dual carbon goals:Energy-efficient building mandates are accelerating infrared-reflective dark pigment adoption in architectural ceramics.
- GB standards enforcement:SAMR heavy metal migration limits are conditioning export eligibility and driving quality upgrades among domestic Chinese producers.
Market Restraints
- Calcination energy costs:Natural gas and electricity price volatility directly impacts production economics for spinel-structure pigments requiring 800°C+ processing temperatures.
- Chromite ore concentration:South African and Turkish supply dominance creates raw material vulnerability for chromium precursor sourcing.
- Complex oxide synthesis limitations:Particle size distribution control remains technically constrained for sub-micron grades demanded by thin-film coatings.
Strategic Opportunities
- India ceramics sector:Underpenetrated architectural tile producers present white space for infrared-reflective pigment specification.
- Photovoltaic thermal management:Solar absorber coatings for concentrated solar power systems represent an emerging application vector.
- EU Green Deal industrial decarbonization:Carbon border adjustment mechanisms create competitive openings for low-carbon pigment process technologies.
Industry Challenges
- High-temperature process engineering talent:Specialized calcination furnace operation and control expertise is scarce across pigment manufacturing regions.
- REACH dossier completion timelines:Extended toxicity study requirements are compressing product registration windows for new market entrants.
- Legacy coating system compatibility:Reformulated copper chromium grades require extensive recertification with established resin and binder systems.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Copper Chromium Black Market Trends and Innovations
Solid-state synthesis methods and regulatory compliance automation are compressing development cycles while reshaping how pigment producers validate and commercialize new grades.
Low-temperature sol-gel precursor preparation is decentralizing production geography by enabling smaller-scale, distributed manufacturing nodes that bypass traditional high-capital calcination infrastructure. Regional coatings formulators in Southeast Asia are piloting these methods to reduce import dependency. The technology is decentralizing supply chain risk away from concentrated high-volume production centers.
EPA's evolving hexavalent chromium emission standards are mandating closed-loop scrubbing systems and real-time stack monitoring for U.S.-based calcination facilities. Capital expenditure requirements for compliance are favoring established producers with integrated environmental controls. Surface coating applications serving Department of Defense specifications are experiencing the most intensive compliance verification.
Specification-driven procurement is consolidating buyer power as aerospace OEMs reduce approved supplier lists and demand comprehensive material certification packages. Tier-one coatings suppliers are absorbing compliance documentation burdens previously borne by pigment producers. This concentration is most visible in North American and Western European defense and commercial aviation supply chains.
Copper Chromium Black Market Segmentation
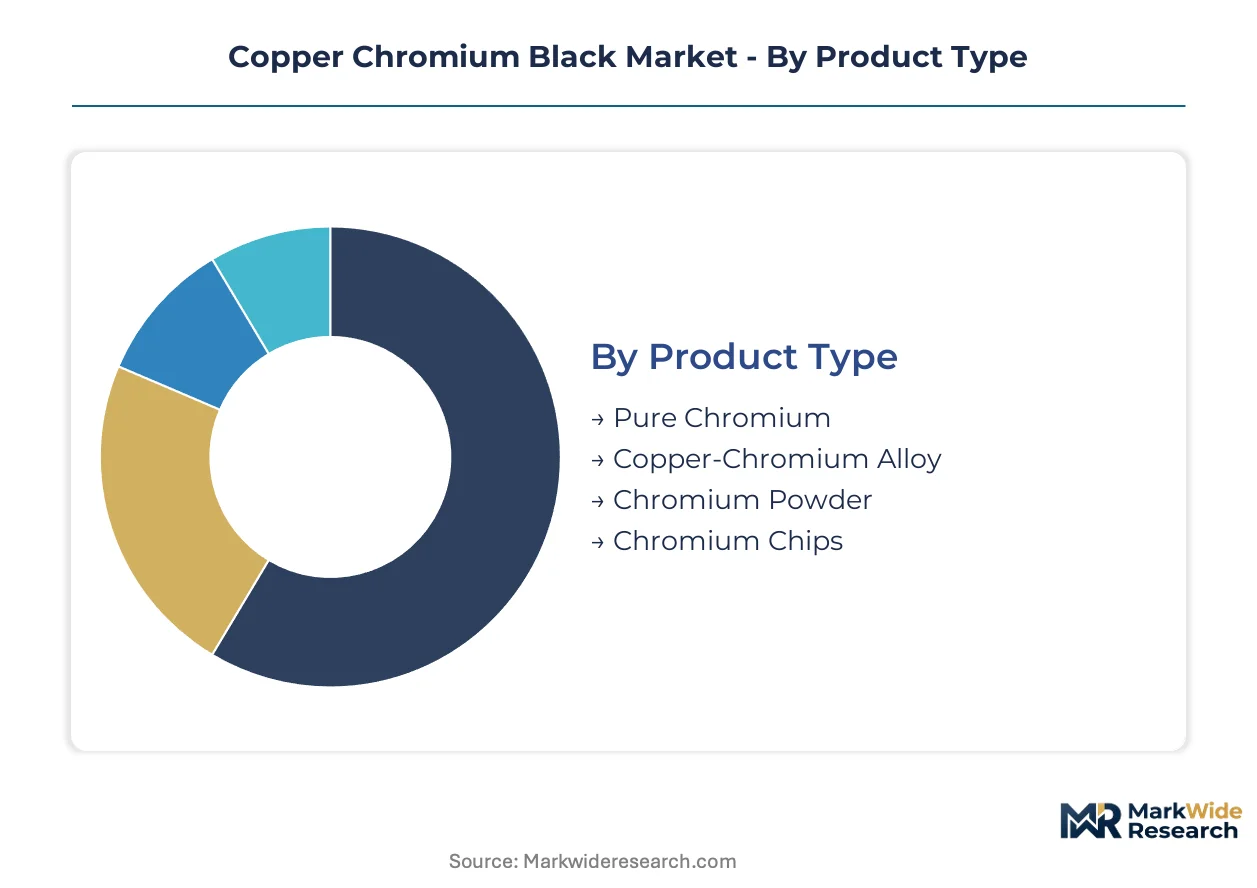
Segmentation in the copper chromium black market reveals how thermal performance requirements and regulatory compliance reshape procurement patterns across pigment grades. Buyers select formulations based on calcination temperature thresholds, heavy metal migration limits, and infrared reflectance specifications rather than color properties alone.
Product Type:
Standardization dominates commodity grades while specialty spinel structures demand precise calcination parameter control.
- Copper-Chromium Alloy:Mixed-metal oxide spinel synthesized at 800°C-plus temperatures delivers jet-black powder with exceptional thermal stability. Aerospace manufacturers in the United States specify this grade for engine component thermal barrier coatings where exhaust system temperatures exceed 650°C.
- Pure Chromium:Single-metal oxide pigment with narrower infrared absorption spectrum and lower thermal expansion coefficient. Demand concentrates in German automotive underhood coatings where SAMR-compliant export documentation is mandatory for Chinese-sourced formulations.
- Chromium Powder:Finely divided metallic precursor requiring controlled oxidation state management during calcination.
- Chromium Chips:Coarse granular feedstock for masterbatch compounding in high-volume ceramic glaze production.
Most installed capacity flows through Copper-Chromium Alloy. Expansion is steepest in Pure Chromium.
Application:
Volume concentration sits with mature coating systems while emerging specifications pull technical resources toward unproven thermal management formulations.
- Surface Coating:Architectural ceramic producers across China adopt infrared-reflective dark pigments for energy-efficient building materials under dual carbon mandates. GB standard compliance on heavy metal migration limits conditions specification eligibility for export-oriented manufacturers.
- Aerospace Components:Heat-resistant formulations for turbine blades and exhaust nozzles require sub-micron particle size distribution control. Tier-one coatings suppliers absorb REACH dossier completion burdens previously borne by pigment producers in Western European supply chains.
- Electrical Conductors:EMI shielding applications in telecommunications infrastructure.
- Chemical Manufacturing:Catalytic substrate coloring for high-temperature process equipment.
Surface Coating commands the greatest production volume. Aerospace Components are gaining share fastest.
End User Industry:
Procurement sophistication varies sharply between consolidated OEMs and fragmented metal finishers.
- Aerospace Manufacturers:Consolidated approved supplier lists demand comprehensive material certification packages including EPA hexavalent chromium emission documentation. Cincinnati-based pigment producers leverage integrated environmental controls to sustain North American supply continuity.
- Metal Plating Firms:Legacy distribution networks across Western Europe serve smaller finishers with reformulated compliant grades. Extended toxicity study requirements compress registration windows for new market entrants seeking qualification.
- Electronics Fabricators:Printed circuit board and connector manufacturers specifying conductive coatings.
- Chemical Processors:Reactor vessel and heat exchanger producers requiring corrosion-resistant pigmentation.
Aerospace Manufacturers absorb the highest technical qualification costs. Metal Plating Firms show the steepest reformulation demand curve.
Distribution Channel:
Relationship intensity determines channel selection between specification-driven OEM procurement and spot-market commodity purchasing.
- Direct Sales:Long-term supply agreements with integrated colorant R&D laboratories enable real-time formulation adjustment. Vibrantz Technologies anchors position through United States and European technical service presence.
- Industrial Suppliers:Regional coatings formulators in Southeast Asia pilot sol-gel precursor methods to reduce import dependency. Shepherd Color Company sustains supply continuity through Cincinnati manufacturing footprint.
- Online Trading Platforms:Spot-market procurement for standardized grades with established technical data sheets.
- Authorized Dealers:Local technical representation for compliance documentation and application support.
Direct Sales channels carry the highest margin structures. Industrial Suppliers are expanding coverage most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands substantially greater installed calcination capacity than the United States, yet American aerospace OEMs impose more stringent supplier qualification protocols that filter export eligibility. Regulatory divergence between SAMR heavy metal standards and EPA hexavalent chromium limits forces producers to maintain parallel formulation portfolios.
United States
Aerospace thermal barrier coatings for turbine engines and exhaust systems absorb the highest-specification copper chromium black grades. EPA stack monitoring mandates and closed-loop scrubbing requirements favor established producers with integrated environmental infrastructure. Cincinnati-based manufacturing clusters sustain supply continuity for defense and commercial aviation coatings formulators serving Boeing and Lockheed Martin supply chains.
Germany
Automotive underhood coatings specify pure chromium variants with lower thermal expansion coefficients for engine bay applications. REACH registration dossiers and ECHA toxicity study requirements compress product registration windows for new market entrants. Western German pigment distribution networks reach smaller metal plating firms across the Ruhr industrial region with reformulated compliant grades.
China
Architectural ceramic producers in Guangdong and Fujian provinces scale infrared-reflective dark pigment adoption under dual carbon mandates for energy-efficient building materials. SAMR GB standards enforcement on heavy metal migration limits conditions export eligibility and drives quality upgrades among domestic producers. Jiangxi and Hunan province manufacturing bases expand calcination capacity to serve local ceramics and coatings sectors.
Japan
Electronics fabricators specifying conductive coatings for printed circuit boards and telecommunications infrastructure drive precision-grade demand. METI industrial standards and JIS certification requirements shape procurement specifications for EMI shielding applications. Kansai region chemical processors concentrate catalytic substrate coloring demand for high-temperature process equipment.
South Korea
Solar absorber coatings for concentrated solar power systems emerge as an experimental application vector for thermal management formulations. MFDS chemical substance registration and KOSHA industrial safety protocols govern pigment import and handling procedures. Seoul Capital Area coatings formulators pilot specification-driven procurement consolidation mirroring North American aerospace patterns.
Copper Chromium Black Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across calcination-based pigment manufacturing. Market structure tilts toward consolidation as aerospace OEMs reduce approved supplier lists and tier-one coatings suppliers absorb compliance documentation burdens. Three archetypes dominate: integrated colorant laboratories with transatlantic technical service presence, legacy pigment distributors controlling Western European reach, and regional Chinese producers scaling capacity under domestic dual carbon procurement. Competitive moves concentrate on strategic partnerships for REACH dossier completion and geographic expansion into underpenetrated Indian ceramics markets.
Within the Cincinnati-based manufacturing tier, The Shepherd Color Company exemplifies supply continuity positioning for North American heat-resistant coating customers. Among integrated laboratory operators, Vibrantz Technologies occupies a position through United States and European technical service infrastructure. Heubach sits within the legacy distribution archetype, anchoring Western European market access for smaller metal plating firms requiring compliant grade reformulation.
| Leading Market Players |
|---|
| The Shepherd Color Company |
| Vibrantz Technologies |
| Heubach |
| Asahi Kasei Kogyo |
| Zhonglong Materials |
| Hunan Jufa Pigment |
| Fulln Glaze |
| Jolychem(Shanghai) Company |
| Jiangxi Dingrui New Materials |
| Others |
Pricing and Supply Chain Analysis
China's dual carbon goals gate both qualified supply and premium-tier pricing access, as SAMR GB standards enforcement conditions export eligibility and drives quality upgrades that stratify pigment grades across compliance tiers. Aerospace OEMs in the United States pay substantial premiums for REACH-compliant documentation packages while architectural ceramic producers in Asia source standardized infrared-reflective grades at compressed margins.
Pricing Analysis
Capacity additions in Jiangxi and Hunan provinces are reshaping price floors for commodity-grade copper chromium black, compressing margins for standardized infrared-reflective formulations. Three-tier pricing structure across premium aerospace certification grades, standard ceramic-compliant tiers, and economy masterbatch feedstock segments reflects calcination temperature thresholds and heavy metal migration documentation depth. Pricing pressure stems from natural gas and electricity price volatility impacting 800°C-plus spinel synthesis economics. Metal plating firms across Western Europe exhibit the highest price sensitivity due to fragmented procurement scale, while consolidated aerospace manufacturers absorb premium-tier costs for thermal barrier specifications.
Supply Chain Analysis
China's domestic content mandates under dual carbon procurement policies are reshaping sourcing patterns, favoring Jiangxi and Hunan province manufacturing bases over import-dependent Southeast Asian formulators. Chromite ore draws from South African and Turkish concentrate suppliers, while copper precursor supply rests on Chilean and Peruvian mining output. Single-source vulnerability concentrates in chromium feedstock given South African supply dominance. Distribution runs through tier-one coatings suppliers absorbing REACH dossier completion burdens for Western European defense and commercial aviation supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where REACH registration deadlines and EPA hexavalent chromium emission standards simultaneously compress product registration windows and consolidate procurement under qualified suppliers.
For Market Incumbents: Deepen backward integration into chromite ore precursor supply to mitigate South African concentration risk. Expand Cincinnati-based calcination capacity to capture aerospace thermal barrier specification demand as Boeing and Lockheed Martin supply chains reduce approved supplier lists. Invest in closed-loop scrubbing infrastructure ahead of EPA stack monitoring mandate tightening. For New Entrants and Emerging Players: The price-point gap between premium aerospace certification grades and economy ceramic feedstock tiers creates entry space for mid-tier producers. Target Indian architectural tile producers with infrared-reflective pigment specifications underpenetrated by established Chinese exporters. Pursue sol-gel precursor technology licensing to bypass high-capital calcination infrastructure requirements. For Investors and Strategic Acquirers: Roll-up economics work for regional Chinese pigment producers because SAMR enforcement is consolidating export-eligible manufacturing capacity under compliant operators. Five-to-ten year viability hinges on dual carbon building mandate persistence and aerospace thermal management specification expansion. Watch EPA hexavalent chromium emission standard evolution as inflection indicator for North American supply chain restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chromite Precursor Supply | Mitigates South African ore concentration vulnerability for chromium feedstock security. |
| REACH Dossier Completion Partnership | Accelerates market access for new grades under ECHA toxicity study timelines. |
| Sol-Gel Technology Licensing | Enables distributed manufacturing nodes bypassing 800°C calcination capital requirements. |
| Indian Ceramics Market Entry | Captures underpenetrated architectural tile specification demand outside Chinese supply dominance. |
| Closed-Loop Scrubbing Infrastructure Deployment | Satisfies EPA hexavalent chromium emission mandates for defense coating supply continuity. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with calcination plant managers, aerospace coatings procurement leads, ceramic glaze formulators, and REACH regulatory consultants with secondary validation through customs trade data, SEC pigment producer filings, SAMR GB standard publications, and ECHA registration dossiers. Bottom-up capacity assessments across Jiangxi, Hunan, and Cincinnati manufacturing clusters triangulated against top-down demand modeling from aerospace OEM thermal barrier specifications.
Segment-weighting across product type, application, end user industry, and distribution channel dimensions shaped volume and value outputs across the projection horizon. Aerospace thermal barrier coating content per engine platform, ceramic glaze adoption rates under China's dual carbon mandates, and SAMR export eligibility qualification timelines fed industry-specific forecast inputs. CAGRs derived from regression analysis against calcination capacity expansion schedules and regulatory compliance deadline clustering.
Caveats apply where EPA hexavalent chromium emission standard evolution or REACH dossier completion timeline extensions could materially shift the outlook. Chromite ore supply disruption, natural gas price volatility impacting spinel synthesis economics, and aerospace OEM supplier list consolidation pace represent specific revision triggers. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.