
 Metallurgical Coal Market | 2026-2036
Metallurgical Coal Market Size, Share, and Industry Trends Forecast 2026-2036
Metallurgical Coal Market Intelligence
Australia's metallurgical coal belt is narrowing the cost gap with Mongolian supply corridors. BHP Group leverages integrated rail-port infrastructure across Queensland to sustain export volumes into Asian steel mills. Glencore plc anchors its trading position through long-term offtake agreements with Pacific Rim buyers. Anglo American plc competes on premium hard coking coal grades from its Moranbah-Grosvenor complex.
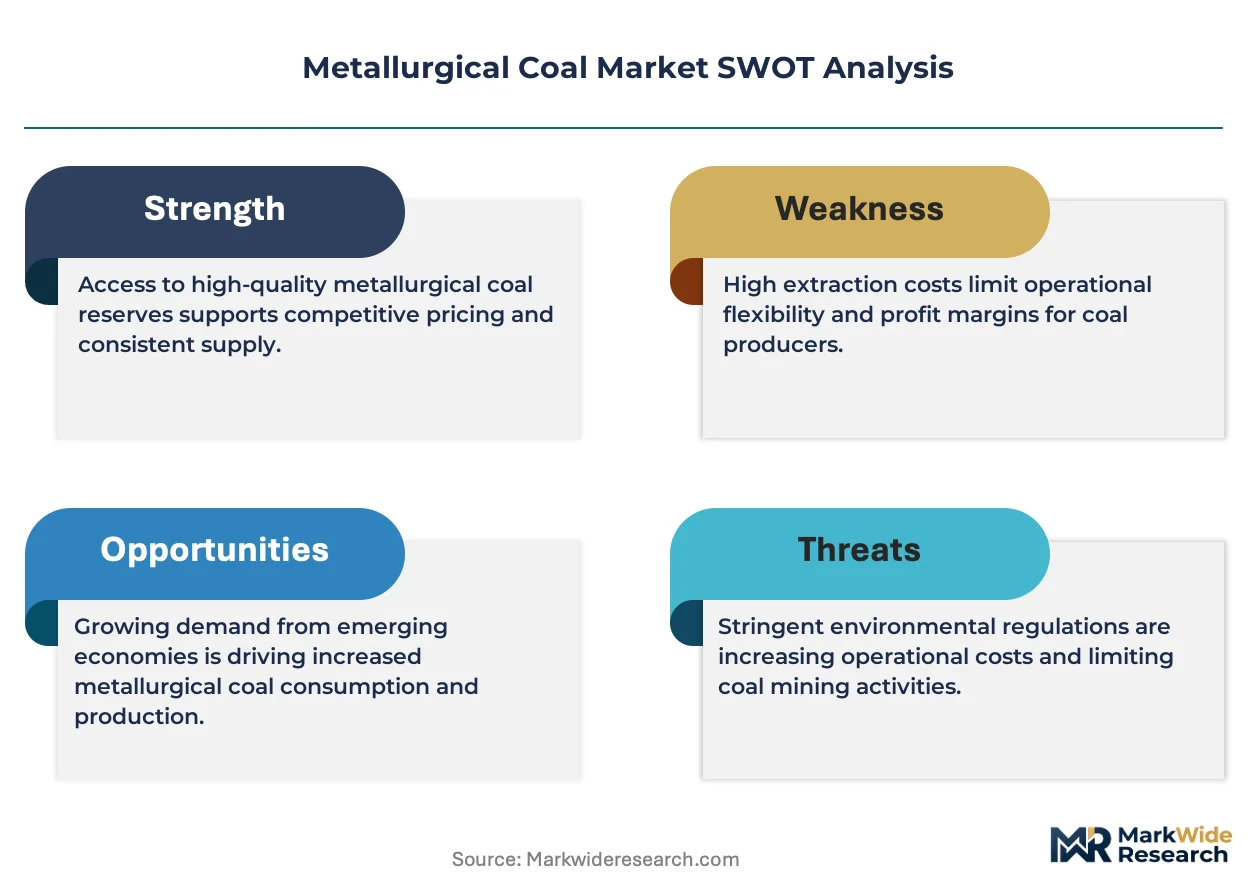
Metallurgical coal is a high-carbon bituminous coal graded by coking properties, volatile matter content, and plastic layer thickness, with premium grades requiring less than 10.5% ash and strong coke strength after reaction to support blast furnace ironmaking. Hard coking coal commands the strongest margin pool due to irreplaceable performance in large blast furnaces, while pulverized coal for PCI injection grows fastest as mills chase coke rate reduction. Steel mills dominate end-user procurement through direct sales channels, though commodity exchanges gain traction for price risk management.
MEE emissions standards in China and Australia's EPA mining oversight constrain permitted sulfur and ash levels, reshaping quality premiums at loading ports. ISO coal classification standards and the EU Carbon Border Adjustment Mechanism create divergent compliance burdens for export-bound producers. Stakeholders must track how carbon border adjustments redirect trade flows before long-term supply contracts reset.
Market Dynamics
China's MEE emissions standards are forcing steel mills to abandon medium-ash coking coal, compressing the addressable supply base and amplifying quality premiums at loading ports across Queensland and Mongolia.
Growth Catalysts
- Blast furnace expansion:Steel mills in India and Southeast Asia are adding capacity to supply infrastructure projects, pulling additional hard coking coal volumes through Pacific Rim supply corridors.
- MEE standards compliance:China's Ministry of Ecology and Environment mandates sub-10.5% ash content, redirecting procurement toward Australian and Mongolian premium grades.
- PCI injection growth:Pulverized coal injection rates are climbing as mills reduce coke consumption, expanding demand for high-volatile semi-soft coking coal varieties.
Market Restraints
- Supply corridor concentration:Australian rail-port infrastructure bottlenecks and Mongolian border crossing delays create single-point vulnerability for Asian mill procurement.
- Input cost volatility:Diesel and ammonium nitrate prices swing with crude oil markets, destabilizing open-cut mining economics in Queensland's Bowen Basin.
- Direct reduced iron substitution:Electric arc furnace routes and hydrogen-based DRI threaten long-term blast furnace feedstock demand in European steelmaking.
Strategic Opportunities
- Underpenetrated Indian procurement:Domestic steel mills lack long-term offtake discipline, creating entry points for traders offering price-hedged supply contracts.
- EU Carbon Border Adjustment Mechanism:The phased implementation creates premium tiers for verified low-emission coking coal, rewarding producers with methane capture certification.
- Semi-soft grade arbitrage:Blending technology advances allow wider use of semi-soft coking coal in coke ovens, opening Mongolian and Russian reserve bases previously excluded from premium markets.
Industry Challenges
- Geologist and mining engineer scarcity:Australia's resources sector competes with renewable energy projects for technical talent, delaying greenfield project timelines.
- ISO certification complexity:Divergent coal classification standards between ISO, ASTM, and Chinese GB protocols create contract disputes over quality specifications.
- Port queue management:Cyclone disruptions and vessel bunching at Hay Point and Gladstone force demurrage costs onto producers with limited storage buffer.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metallurgical Coal Market |
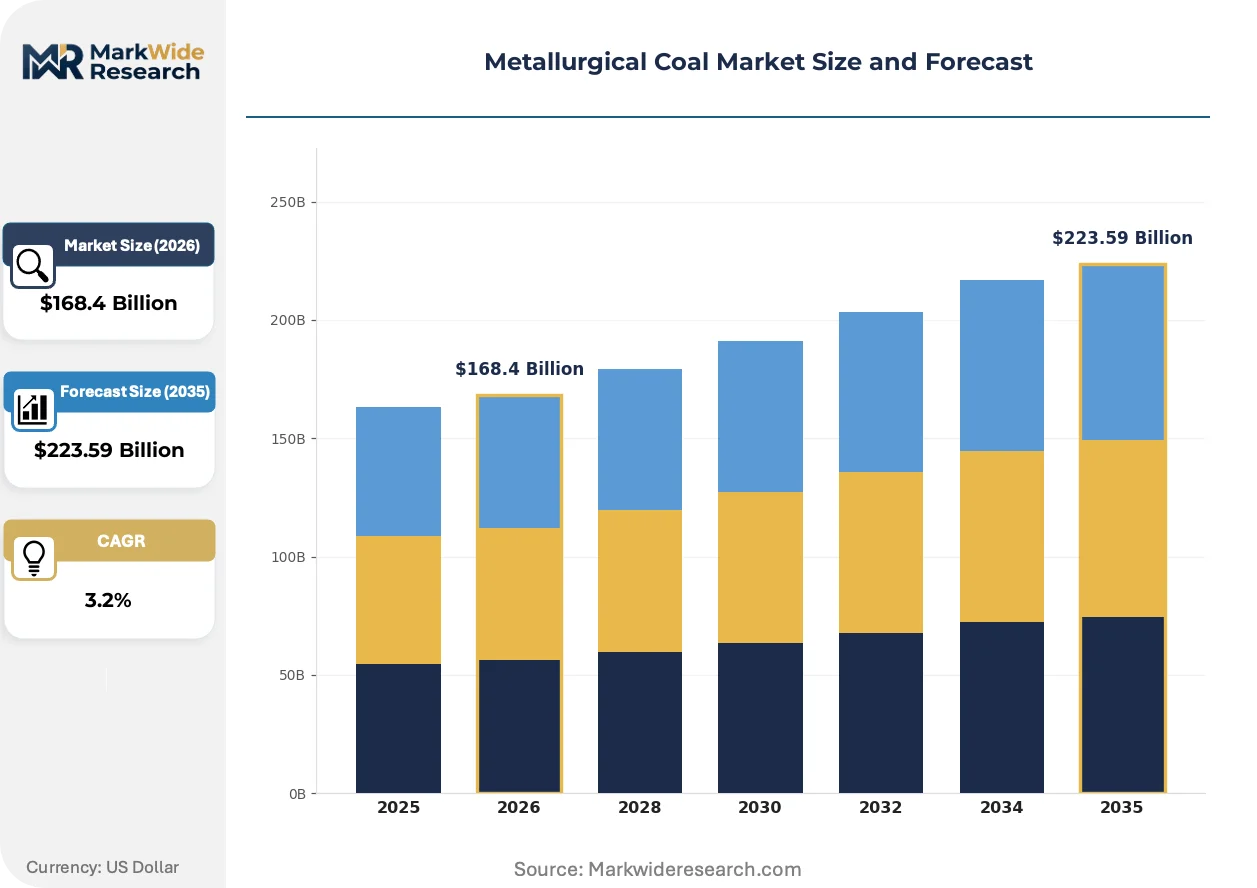
| Market Size in 2026 | $168.4 Billion |
| Market Size in 2035 | $223.59 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Premium Coking Coal, Semi-soft Coking Coal, Hard Coking Coal, Pulverized Coal Application: Blast Furnace Steelmaking, Direct Reduction, PCI Injection, Foundry Use, Power Generation End User: Steel Mills, Ironworks, Foundries, Power Plants, Energy Producers Distribution Channel: Direct Sales, Brokers, Commodity Exchanges, Exporters, Importers |
| Companies Covered | Teck Resources Limited, Arch Resources, BHP Group, Whitehaven Coal, China Shenhua Energy, Anglo American plc, Peabody Energy, Rio Tinto, Glencore plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metallurgical Coal Market Strategic Shifts & Innovations
Automation and emissions tracking are compressing the information lag between mine face and steel mill procurement desk, enabling real-time quality adjustments that reshape contract structures.
Sensor-based coal analyzers installed at mine mouths and port loadouts are digitizing quality assurance workflows. BHP and Anglo American operations in Queensland now transmit ash, sulfur, and coke strength data directly to mill laboratories before vessel departure. This compression of information asymmetry is enabling index-linked pricing clauses that reset monthly rather than quarterly.
China's dual carbon goals and MEE enforcement are tightening the allowable sulfur window for imported coking coal. Mills in Hebei and Jiangsu provinces now reject cargoes exceeding 0.6% sulfur, forcing traders to blend down high-sulfur Mongolian parcels. The policy is accelerating investment in coal washing capacity at Gants Mod border facilities.
Japanese steel mills through Nippon Steel and JFE Holdings are consolidating procurement desks and extending contract durations to secure volume certainty. Spot market participation has thinned as buyers prioritize supplier relationships over price optimization, reversing the liquidity growth seen in the previous decade. This behavioral shift is most pronounced in premium hard coking coal categories where replacement sourcing carries furnace risk.
Metallurgical Coal Market Segmentation
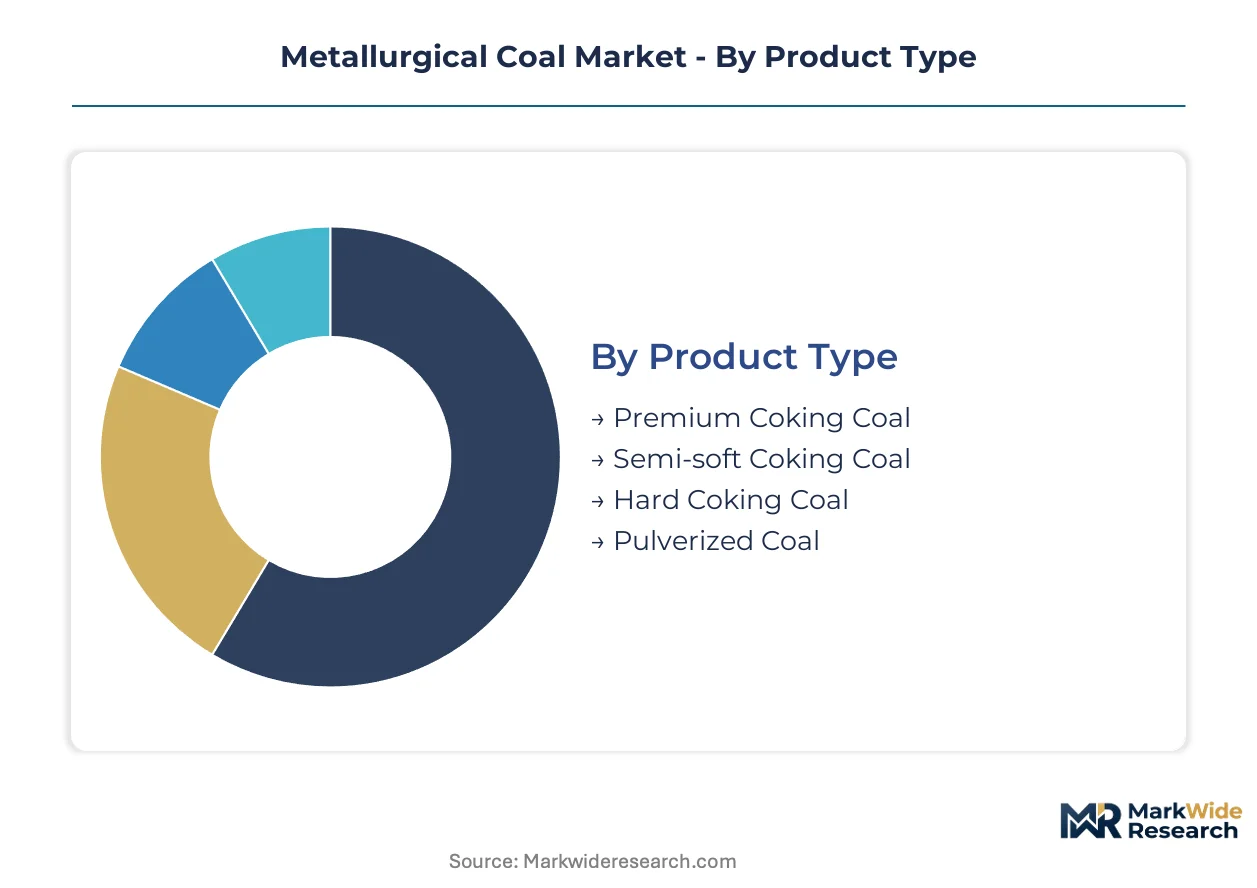
Metallurgical coal grades command divergent price premiums based on coking properties and blast furnace compatibility. Procurement channels and end-user specifications fragment demand across distinct quality tiers and supply corridors.
Product Type:
Cost tier stratification separates premium grades from blending feedstocks in procurement decisions across Asian steel mills.
- Hard Coking Coal:High-rank bituminous coal with strong coke strength after reaction and low volatile matter below 22%. Demand concentrates in Hebei and Jiangsu province mills under China's MEE emissions standards mandating sub-10.5% ash content.
- Premium Coking Coal:Ultra-low ash metallurgical coal with superior plastic layer thickness above 25mm. Japanese mills through Nippon Steel and JFE Holdings anchor procurement through multi-year offtake agreements to secure furnace consistency.
- Semi-soft Coking Coal:Intermediate volatile coal blended with hard coking varieties to reduce coke oven costs.
- Pulverized Coal:Finely ground injection-grade coal displacing coke in blast furnace tuyeres.
Hard coking coal commands the established base. The steepest expansion runs through pulverized coal injection grades.
Application:
Volume distribution tracks blast furnace route dominance against emerging direct reduction alternatives in steelmaking economics.
- Blast Furnace Steelmaking:Primary ironmaking route consuming 70-80% of metallurgical coal through coke oven batteries and PCI injection systems. Indian mills at Tata Steel and JSW Steel expand capacity along the eastern corridor from Jamshedpur to Odisha.
- PCI Injection:Pulverized coal blown through tuyeres to replace coke as reducing agent and heat source. Southeast Asian mills in Vietnam and Indonesia adopt high injection rates to lower production costs.
- Direct Reduction:Shaft furnace and rotary kiln processes using non-coking coal or natural gas.
- Foundry Use:Small-scale cupola furnace operations for cast iron production.
- Power Generation:Opportunistic combustion of off-specification metallurgical coal.
Blast furnace steelmaking retains volume leadership. Direct reduction applications are climbing the fastest as hydrogen-based routes gain engineering traction.
End User:
Customer type concentration determines contract duration and price index linkage in procurement negotiations.
- Steel Mills:Integrated producers operating coke ovens and blast furnaces as core assets. Australian and Mongolian supply corridors serve mills across China, India, Japan, and South Korea through dedicated port infrastructure.
- Ironworks:Merchant pig iron producers supplying foundries and mini-mills.
- Foundries:Small-volume consumers of foundry coke for cast metal production.
- Power Plants:Occasional buyers of metallurgical coal rejected by steel specifications.
- Energy Producers:Industrial heat and steam generators accepting high-ash varieties.
Steel mills anchor procurement volume. Ironworks represent the fastest-growing customer segment as merchant pig iron trade expands.
Distribution Channel:
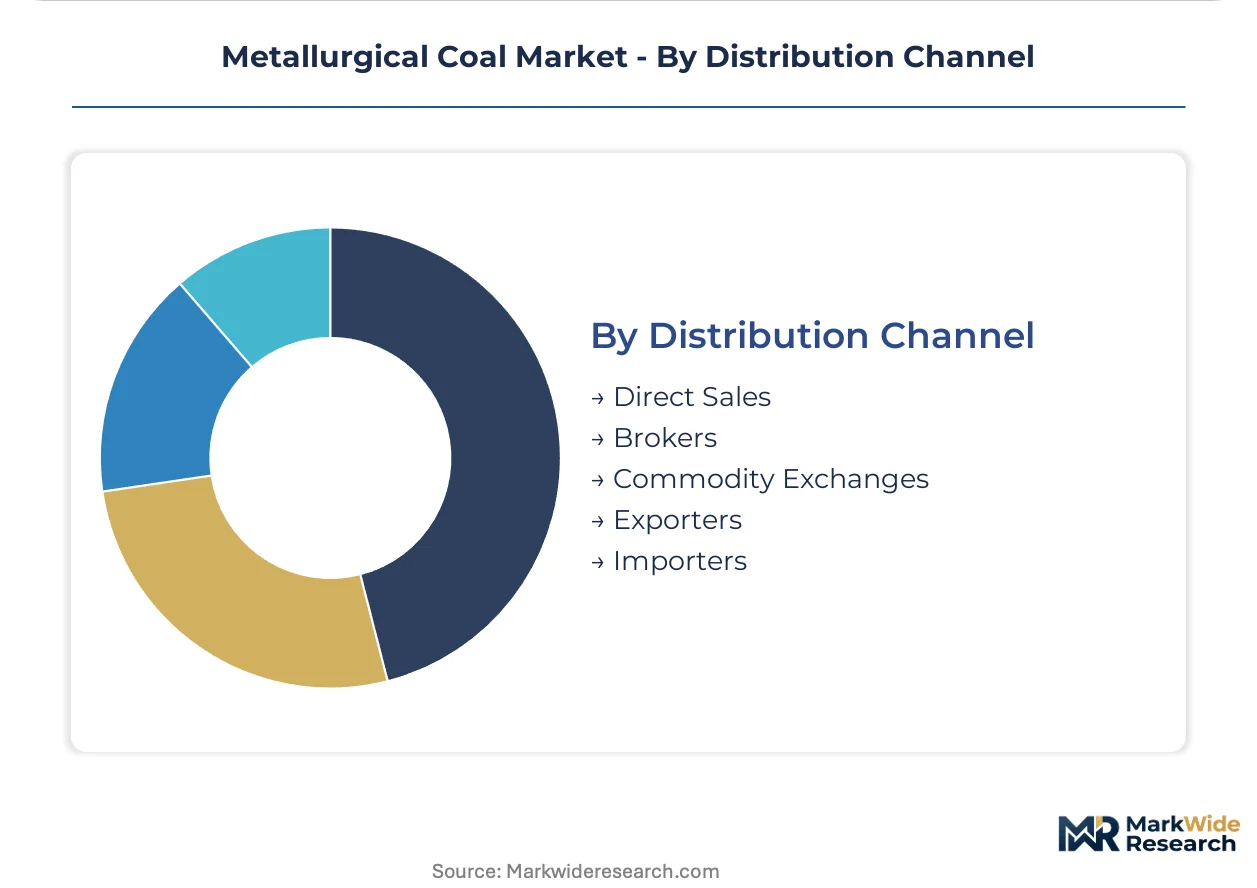
Supply concentration shapes channel selection between direct relationships and intermediated trading structures.
- Direct Sales:Long-term contracts linking Australian producers to Japanese and Korean mills with quarterly price resets. BHP Group and Anglo American leverage Queensland rail-port integration to sustain direct relationships.
- Brokers:Intermediaries aggregating Mongolian and Russian parcels for Chinese mill blending operations.
- Commodity Exchanges:Singapore Exchange and Dalian Commodity Exchange contracts for price risk management.
- Exporters:National coal boards and trading houses managing cross-border logistics.
- Importers:Mill-affiliated procurement desks and independent trading companies.
Direct sales channels retain contract value concentration. Commodity exchanges gain share fastest as price volatility drives hedging demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australian rail-port corridors and Mongolian border crossings channel the bulk of seaborne hard coking coal into Asian blast furnaces. Queensland's Bowen Basin and Mongolia's South Gobi province anchor export capacity serving mills from Jiangsu to Jamshedpur.
China
Hebei and Jiangsu province mills under MEE emissions standards mandate sub-10.5% ash content in imported coking coal. The dual carbon goals framework redirects procurement toward Australian premium grades. Tangshan steel clusters now reject cargoes exceeding 0.6% sulfur, forcing blend-down operations at Gants Mod border facilities.
India
Tata Steel and JSW Steel expand blast furnace capacity along the eastern corridor from Jamshedpur to Odisha. The domestic steel sector lacks long-term offtake discipline, creating entry points for price-hedged supply contracts. Paradip and Visakhapatnam ports handle rising metallurgical coal volumes from Australian and Russian origins.
Japan
Nippon Steel and JFE Holdings consolidate procurement desks and extend contract durations to secure volume certainty. METI oversight shapes energy security frameworks for coking coal stockpiling. Kashima and Nagoya steelworks anchor premium hard coking coal demand through multi-year offtake agreements with Queensland producers.
Australia
BHP Group and Anglo American leverage integrated rail-port infrastructure across Queensland to sustain export volumes. EPA mining oversight constrains permitted sulfur and ash levels, reshaping quality premiums at Hay Point and Gladstone loadouts. Bowen Basin open-cut operations face diesel and ammonium nitrate cost volatility tied to crude oil markets.
South Korea
POSCO and Hyundai Steel anchor metallurgical coal demand through dedicated procurement desks in Seoul. The country's steelmakers prioritize supplier relationships over spot market participation to manage furnace risk. Gwangyang and Pohang steelworks receive Australian and North American coking coal through Busan and Gwangyang port terminals.
Metallurgical Coal Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in mining and logistics. The metallurgical coal sector concentrates around diversified mining conglomerates with captive rail-port infrastructure and long-term offtake relationships. Two archetypes dominate: integrated resource majors controlling end-to-end supply chains, and pure-play coal operators trading on grade specificity. Competitive moves center on capacity expansion in premium hard coking coal deposits and strategic partnerships with Asian mill procurement desks.
Within the integrated major tier, BHP Group and Anglo American plc exemplify operators with captive Queensland infrastructure. Glencore plc occupies a distinct position as a trading-heavy conglomerate anchoring market liquidity through long-term offtake structures. These three entities represent the dominant competitive anchors shaping contract terms and quality premiums across Pacific Rim supply corridors.
| Leading Market Players |
|---|
| Teck Resources Limited |
| Arch Resources |
| BHP Group |
| Whitehaven Coal |
| China Shenhua Energy |
| Anglo American plc |
| Peabody Energy |
| Rio Tinto |
| Glencore plc |
| Others |
Cost & Logistics Intelligence
Rail-port infrastructure bottlenecks in Queensland determine both the premium spreads between Australian and Mongolian hard coking coal and the geographic shape of Asian mill procurement corridors. Diesel and ammonium nitrate cost volatility tied to crude oil markets compresses open-cut mining margins while amplifying price tier differentiation at loading ports.
Pricing Analysis
China's MEE emissions standards dictate the pricing tier structure across Pacific Rim supply corridors, with sub-10.5% ash mandates creating steep premiums for Australian premium grades against high-sulfur Mongolian parcels requiring blend-down. Three-tier pricing structure across premium hard coking, standard semi-soft, and economy PCI injection grades separates furnace-consistent supply from blending feedstock. Cost compression in the semi-soft tier intensifies because Japanese mills through Nippon Steel and JFE Holdings prioritize supplier relationships over price optimization. Merchant pig iron producers in India exhibit the highest price sensitivity, while integrated Japanese steelworks show the least.
Supply Chain Analysis
Australian EPA mining oversight and China's dual carbon goals function as de facto export-control regimes limiting high-ash, high-sulfur coal flows into premium corridors. Supply concentrates in Australia, Mongolia, and Russia, with Queensland's Bowen Basin and South Gobi province anchoring export capacity. Mining economics rest on diesel fuel, ammonium nitrate explosives, and specialized haul truck fleets. Single-source vulnerability runs through Hay Point and Gladstone port queues where cyclone disruptions force demurrage costs onto producers. Distribution runs through long-term offtake agreements linking BHP Group and Anglo American directly to Japanese and Korean mill procurement desks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity runs through underpenetrated Indian procurement where domestic steel mills lack long-term offtake discipline, creating niches for traders offering price-hedged supply contracts.
For Market Incumbents: Entrench position by deepening backward integration into Queensland rail-port infrastructure and securing multi-year offtake extensions with Japanese mills through JFE Holdings and Nippon Steel. Hydrogen-based direct reduced iron substitution in European steelmaking threatens long-term blast furnace feedstock demand, requiring incumbents to anchor volume certainty through contract duration extensions with Pacific Rim buyers. For New Entrants and Emerging Players: Eastern Indian blast furnace expansion from Jamshedpur to Odisha offers the most penetrable geography, where Tata Steel and JSW Steel capacity additions outpace domestic supply discipline. Target price-hedged supply contracts as the primary go-to-market angle, leveraging Singapore Exchange and Dalian Commodity Exchange instruments to differentiate from incumbent direct sales structures. Semi-soft coking coal arbitrage through Mongolian reserve bases previously excluded from premium markets provides secondary entry. For Investors and Strategic Acquirers: The market sits at a quality-premium expansion phase that favors integrated resource majors with captive infrastructure over pure-play traders. Long-term viability across the five-to-ten year window hinges on carbon border adjustment compliance, with EU Carbon Border Adjustment Mechanism phased implementation rewarding methane capture certification. Watch steel mill consolidation in Hebei province as the inflection indicator for contract structure durability.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Premium Hard Coking Coal | BHP Group and Anglo American leverage Queensland deposits to serve Hebei province mills under MEE ash mandates. |
| Backward Integration into Rail-Port Infrastructure | Captive logistics through Hay Point and Gladstone loadouts insulates export volumes from vessel bunching and demurrage. |
| Long-term Offtake Agreement Extension | Japanese mills through Nippon Steel prioritize volume certainty over spot optimization, reversing previous decade liquidity growth. |
| Coal Washing Investment at Border Facilities | Gants Mod processing capacity enables blend-down of high-sulfur Mongolian parcels for Jiangsu province acceptance. |
| Methane Capture Certification Program | EU Carbon Border Adjustment Mechanism compliance creates premium tiers for verified low-emission coking coal supply. |
Research Approach
A standing panel of mine operations managers, steel mill procurement directors, commodity trading desk heads, and logistics coordinators provided ongoing calibration throughout the study period. Primary interviews with these stakeholders combined with secondary validation from Australian Bureau of Agricultural and Resource Economics trade data, China customs import records, Japan Iron and Steel Federation production statistics, and SEC filings from listed mining conglomerates. Bottom-up volume modeling across Queensland and Mongolian export corridors triangulated against top-down steel production forecasts.
Scenario bracketing anchored the analytical framework across the projection horizon, with demand elasticity tested against blast furnace route persistence and hydrogen-based DRI substitution trajectories. Segmentation dimensions modeled included coal grade tier, steelmaking application, end-user integration level, and regional procurement corridor. CAGRs derived from production capacity announcements, port throughput data, and mill expansion timelines. Industry-specific inputs incorporated MEE enforcement intensity and EU Carbon Border Adjustment Mechanism implementation pace.
The forecast holds incumbent behavior within observed patterns; aggressive moves by pure-play traders or state-backed Mongolian coal boards would shift outcomes. Material shifts in Chinese dual carbon policy enforcement or Australian EPA mining oversight stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Metal Forging Market
Metals
High Purity Aluminium Market
Metals
Industrial Silver Market
Metals
Aluminum Ingots Market
Metals
Rubidium Market
Metals
Monel Alloy Market
Metals
Aluminum Sheet Market
Metals
Rare Earth Metals Market
Metals
Platinum Compounds Market
Metals
Global Brass Rods Market
Metals
Bearing Steel Market
Metals
Aluminum Flat Products Market
Metals
Copper and Copper Alloy Scrap and Recycling Market
Metals
Electrolytic Iron Market
Metals
Battery Metals Market
Metals
Global Mercury Market