
 Aluminium Conductors Market | 2026-2036
Aluminium Conductors Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminium Conductors Market Analysis
Skilled welders and metallurgists with alloy-tuning expertise is reorganizing output capacity across the Aluminium Conductors Market as foundries struggle to staff precision casting lines. Prysmian SpA leverages vertical integration from raw aluminium to finished cable to secure supply continuity for European grid tenders. Nexans SA anchors its position through R&D intensity in thermal-resistant conductor alloys. Southwire Company LLC dominates North American utility procurement through manufacturing scale and channel control.
Aluminium conductors are stranded or solid metal wires composed of aluminium or aluminium-alloy cores, typically heat-treated to achieve conductivity ratings of 61% IACS while maintaining tensile strength above 160 MPa for long-span overhead installations. Their primary purpose is to transmit electrical power across transmission and distribution networks at lower cost and weight than equivalent copper alternatives. ACSR conductors occupy the largest volume share due to decades of utility specification lock-in and proven reliability across extreme climate zones. AAAC alloys represent the fastest-expanding product category as grid operators seek higher ampacity without tower reinforcement. Underground cable applications command premium margin pools where corrosion-resistant sheathing and specialized jointing techniques create technical barriers.
FERC interconnection standards and IEEE overhead conductor specifications shape product certification requirements for US utility procurement, while IEC 61089 governs international dimensional and mechanical benchmarks for alloy-stranded designs. China's GB standards and MEE environmental compliance protocols are tightening smelter emissions thresholds, indirectly constraining raw metal supply elasticity for conductor manufacturers. India's CEA technical standards and BIS certification mandates are accelerating domestic testing infrastructure buildout as state utilities expand rural electrification. Stakeholders must monitor how carbon-border adjustment mechanisms and evolving alloy purity standards reshape sourcing economics and foundry location decisions.
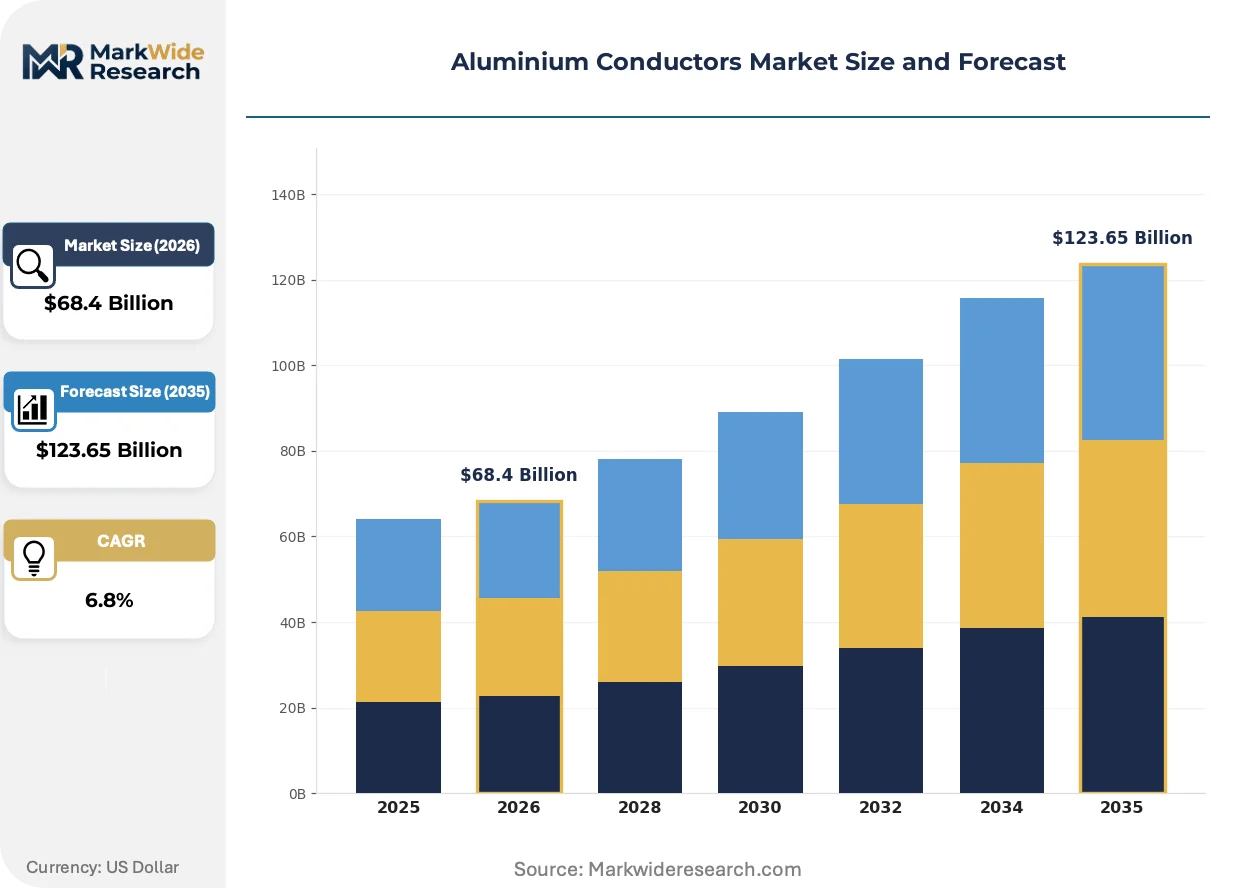
Market Dynamics
Grid modernization mandates across utilities are forcing wholesale replacement cycles for legacy transmission infrastructure, concentrating procurement power in regional transmission operators and state-backed power authorities.
Growth Catalysts
- Renewable interconnection queues:Wind and solar farm developers in Texas, California, and Iowa are driving demand for high-capacity AAAC conductors to connect remote generation sites to load centers.
- GB standards compliance:China's MEE environmental protocols are accelerating smelter consolidation, channeling raw metal supply toward certified conductor manufacturers serving State Grid tenders.
- FERC Order 2023:The Federal Energy Regulatory Commission's interconnection reforms are compressing project timelines, pulling forward conductor procurement for queued renewable projects.
Market Restraints
- Alumina refining concentration:Australian bauxite and Guinean ore feedstock dependencies create input cost volatility that squeezes margin pools for stranded conductor foundries.
- Copper-aluminium price ratio compression:When LME copper premiums narrow against aluminium ingot, utilities delay substitution decisions and extend legacy copper asset lives.
- IEC 61089 testing bottlenecks:Limited accredited laboratories in emerging markets extend certification timelines, freezing regional suppliers out of tender participation.
Strategic Opportunities
- Rural electrification corridors:India's CEA-mandated village connectivity programs are opening volume contracts for corrosion-resistant ACSR designs in Bihar and Uttar Pradesh.
- Subsea cable sheathing:North Sea offshore wind interconnectors are creating premium demand for specialized aluminium alloys with enhanced seawater resistance.
- Carbon-border adjustment positioning:EU CBAM implementation is incentivizing European smelter restarts, enabling regional conductor manufacturers to claim embedded emissions advantages.
Industry Challenges
- Precision casting expertise scarcity:Foundries in the US Midwest and Germany's Ruhr region cannot staff alloy-tuning metallurgists for thermal-resistant conductor production.
- Jointing technique certification:Underground cable installers face extended retraining timelines for compression sleeve standards required by IEEE 837.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminium Conductors Market |
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ACSR, AAC, AAAC, EC Rod Application: Transmission Lines, Distribution Networks, Overhead Power Lines, Underground Cables End User: Utilities, Industrial, Residential, Commercial Installation Type: Onshore, Offshore, Indoor, Outdoor |
| Companies Covered | Prysmian SpA, Nexans SA, Southwire Company LLC, Sumitomo Electric Industries Ltd., Apar Industries Ltd., LS Cable & System Ltd., Alcoa Corp., Hindalco Industries Ltd., Henan Tong-Da Cable Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminium Conductors Market Emerging Trajectories
Conductor technology is splitting into divergent performance tiers as grid operators segment procurement between cost-optimized legacy designs and premium thermal-resistant alloys for congested corridors.
High-temperature low-sag (HTLS) composite core technology is bifurcating the overhead conductor market. These hybrid designs incorporate carbon-fiber or glass-fiber cores wrapped in aluminium-zirconium alloy strands, doubling ampacity without tower reinforcement. European transmission system operators in Germany and Spain are specifying HTLS for constrained rights-of-way, while US regional transmission organizations in PJM and ERCOT are piloting reconductoring projects. The technology is bifurcating procurement patterns into separate tender streams for conventional ACSR replacement versus capacity-upgrade projects.
REACH substance restrictions and EU F-Gas Regulation phase-down schedules are reshaping conductor manufacturing chemistry. European cable producers must reformulate lubricants and cross-linking agents used in extrusion processes, eliminating perfluorinated compounds from sheathing compounds. German and French foundries are qualifying bio-based alternatives for conductor annealing atmospheres. The regulatory pressure is compressing formulation patent cycles and accelerating supplier qualification timelines for compound vendors.
Utility procurement departments are consolidating vendor panels and unbundling installation services from material supply. Major power authorities in Brazil and Saudi Arabia are moving toward framework agreements with conductor manufacturers, then separately contracting specialized stringing crews. This disintermediation is fragmenting the value chain and pressuring integrated suppliers to defend margin pools through captive installation capabilities or pure-play manufacturing scale. The shift is most visible in Middle Eastern grid expansion programs where EPC contractors now source conductors directly rather through distribution intermediaries.
Aluminium Conductors Market Segmentation
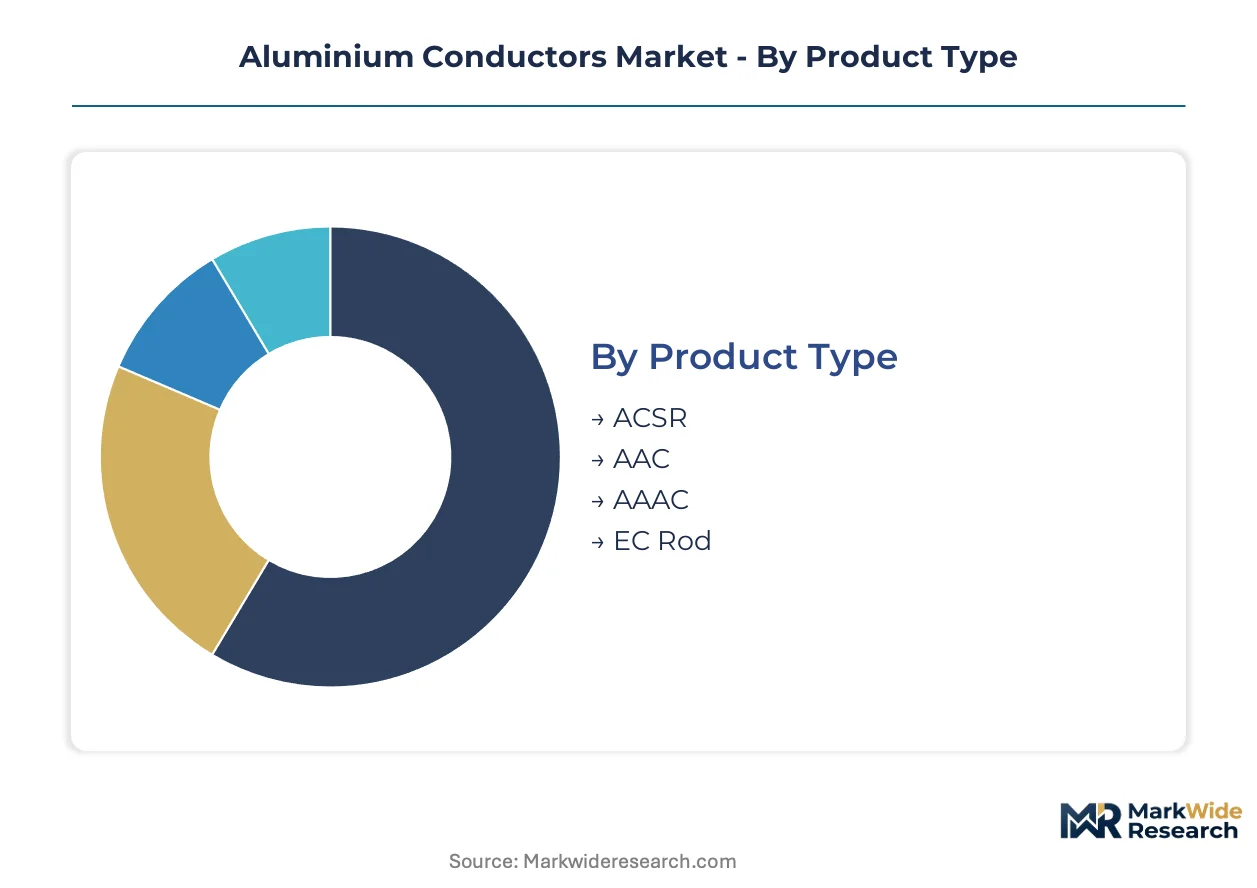
Product differentiation in aluminium conductors hinges on alloy composition and stranding architecture, with procurement patterns diverging sharply between cost-driven utilities and performance-seeking grid operators managing congested transmission corridors.
Product Type:
Margin pools concentrate in thermal-resistant alloys where foundry-level metallurgical expertise creates supply scarcity and pricing power.
- ACSR:Aluminium conductor steel-reinforced designs embed galvanized steel cores within stranded aluminium outer layers, delivering tensile strength above 160 MPa for long-span installations. Indian state utilities in Bihar and Uttar Pradesh are locking in multi-year ACSR framework agreements under CEA-mandated rural electrification programs. ACSR holds installed capacity. AAAC is rotating up the share rankings.
- AAAC:All-aluminium alloy conductors employ heat-treated aluminium-magnesium-silicon alloys achieving conductivity ratings near 61% IACS with reduced weight versus steel-cored alternatives. Texas and California renewable interconnection queues are pulling forward AAAC procurement for remote wind and solar farm tie-ins to load centers.
- AAC:All-aluminium conductors serve lower-tension distribution networks where mechanical loading requirements permit lighter unalloyed constructions.
- EC Rod:Electrical conductivity grade rod supplies downstream cable extrusion and wire drawing operations for specialized industrial applications.
Procurement volume tilts toward ACSR in emerging markets while alloy-intensive segments command premium positioning in reconductoring tenders.
Application:
Underground cable deployments capture the widest margin spreads due to corrosion-resistant sheathing requirements and specialized jointing technique barriers.
- Transmission Lines:High-voltage backbone corridors spanning 132 kV to 800 kV ratings require conductors engineered for minimal sag under thermal loading and ice accretion. German and Spanish transmission system operators are specifying HTLS composite core designs for constrained rights-of-way where tower reinforcement is economically prohibitive.
- Underground Cables:Insulated aluminium conductors with cross-linked polyethylene sheathing penetrate urban density zones and subsea interconnectors. North Sea offshore wind projects are sourcing specialized aluminium alloys with enhanced seawater resistance for inter-array and export cable applications.
- Distribution Networks:Medium-voltage feeders and lateral taps prioritize cost-optimized ACSR and AAC constructions for radial supply topologies.
- Overhead Power Lines:Traditional open-wire constructions persist in rural and semi-urban territories with lower aesthetic and reliability constraints.
Overhead installations retain volume dominance. Underground configurations are climbing the fastest as urban densification accelerates.
End User:
Utility procurement departments are consolidating vendor panels and unbundling installation services, compressing margins for integrated suppliers while rewarding pure-play manufacturing scale.
- Utilities:Regional transmission operators and state-backed power authorities concentrate procurement power through framework agreements spanning multiple project cycles. Saudi Arabia and Brazil are separating conductor supply from specialized stringing crew contracts, fragmenting value chain capture.
- Industrial:Mining, smelting, and petrochemical facilities source medium-voltage feeders and plant distribution infrastructure with customized ampacity specifications.
- Commercial:Data center and logistics park developers are procuring dedicated substation tie-ins with redundancy requirements.
- Residential:Low-voltage service drops and neighborhood distribution laterals represent high-volume, specification-commoditized demand.
Utility tenders anchor revenue stability. Industrial accounts are expanding most quickly as captive generation and direct grid access proliferate.
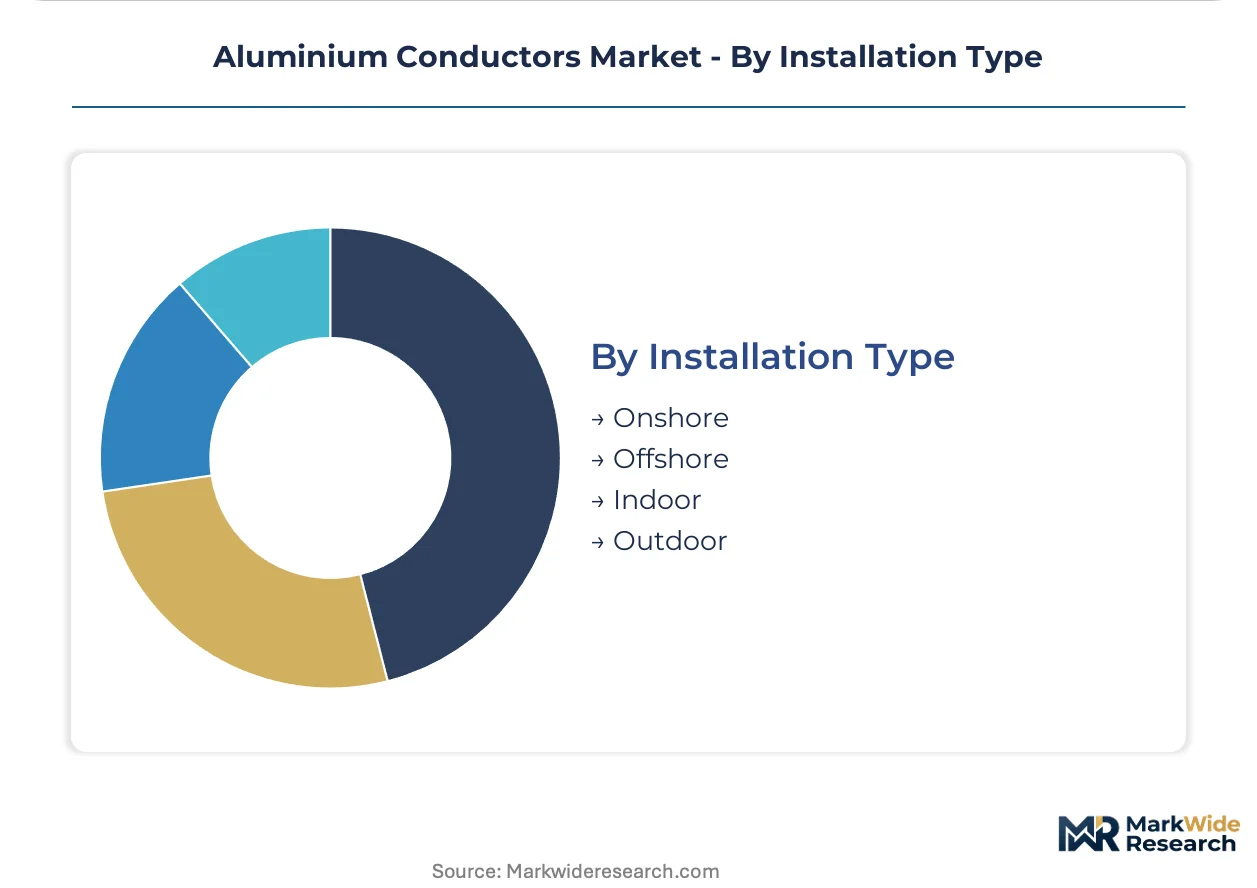
Installation Type:
Offshore deployments command the steepest technical barriers and qualification timelines, insulating qualified suppliers from price-based competition.
- Onshore:Terrestrial transmission and distribution corridors across plains, hills, and desert terrain constitute the baseline demand pool. US Midwest utilities are managing precision casting expertise scarcity for thermal-resistant conductor production.
- Offshore:Submarine cable installations and platform interconnections require alloy formulations resisting chloride-induced corrosion and fatigue cycling. European offshore wind buildouts are concentrating demand in specialized foundries with marine certification.
- Outdoor:Exposed overhead lines dominate utility infrastructure with weathering and galloping resistance specifications.
- Indoor:Switchgear busbars and substation rigid conductors serve confined electrical facility environments.
Outdoor overhead systems retain installed base dominance. Offshore applications are rotating up the share rankings as maritime renewable capacity expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FERC interconnection standards anchor US procurement patterns while China's MEE environmental protocols and India's CEA technical mandates reshape supply-side concentration across East Asian and South Asian manufacturing clusters.
China
State Grid tenders concentrate demand for AAAC conductors serving renewable interconnection queues in Xinjiang and Inner Mongolia. MEE environmental compliance protocols are accelerating smelter consolidation, channeling raw metal supply toward certified conductor manufacturers. Yangtze River Delta foundries in Jiangsu and Zhejiang provinces are scaling thermal-resistant alloy production for domestic grid modernization.
United States
ERCOT and PJM regional transmission organizations are piloting HTLS reconductoring projects across constrained Texas and Mid-Atlantic corridors. FERC Order 2023 compresses project timelines, pulling forward conductor procurement for queued renewable developments. Georgia and South Carolina manufacturing clusters are struggling with precision casting expertise scarcity for thermal-resistant conductor lines.
India
CEA-mandated rural electrification programs in Bihar and Uttar Pradesh are locking in multi-year ACSR framework agreements for village connectivity. BIS certification mandates are accelerating domestic testing infrastructure buildout as state utilities expand distribution networks. Gujarat and Maharashtra industrial corridors are concentrating foundry capacity for cost-optimized stranded conductor production.
Germany
Transmission system operators are specifying HTLS composite core designs for constrained rights-of-way where tower reinforcement is economically prohibitive. EU F-Gas Regulation phase-down schedules are forcing reformulation of lubricants and cross-linking agents in conductor extrusion processes. Ruhr region foundries cannot staff alloy-tuning metallurgists for thermal-resistant production lines.
Brazil
Major power authorities are moving toward framework agreements with conductor manufacturers, then separately contracting specialized stringing crews. National grid expansion programs are fragmenting value chain capture as EPC contractors source conductors directly rather than through distribution intermediaries. São Paulo and Minas Gerais industrial zones are anchoring South American manufacturing capacity.
Aluminium Conductors Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the aluminium conductors market, with consolidated European cable specialists competing against fragmented Asian metal processors and integrated North American wire producers. The vendor base separates into three strategic archetypes: vertically integrated energy infrastructure conglomerates controlling raw metal through finished cable, pure-play conductor specialists leveraging metallurgical R&D intensity, and regional wire producers competing on manufacturing scale and channel control. Dominant competitive moves include backward integration into smelter and alloy supply and geographic expansion through state-backed grid tender participation.
Among Italy-based cable specialists, Prysmian SpA exemplifies the vertically integrated archetype with captive aluminium supply chains serving European transmission tenders. French conglomerate Nexans SA occupies a position within the R&D-intensive tier, anchoring thermal-resistant alloy development for reconductoring applications. Southwire Company LLC represents North American scale-driven competition, sitting within the manufacturing volume tier that dominates utility procurement through channel density across US regional markets.
| Leading Market Players |
|---|
| Prysmian SpA |
| Nexans SA |
| Southwire Company LLC |
| Sumitomo Electric Industries Ltd. |
| Apar Industries Ltd. |
| LS Cable & System Ltd. |
| Alcoa Corp. |
| Hindalco Industries Ltd. |
| Henan Tong-Da Cable Co. Ltd. |
| Others |
Supply Flow & Price Mechanics
IEC 61089 certification requirements gate both supplier qualification timelines and price differentiation between accredited and non-accredited conductor manufacturers, compressing margin pools for foundries unable to secure laboratory access while allowing certified producers to command sustained premiums in tender participation.
Pricing Analysis
European HTLS composite core conductors trade at substantial premiums over standard ACSR equivalents in Texas and California procurement queues. Three-tier pricing structure across thermal-resistant alloys, standard ACSR, and economy-grade AAC separates foundries by metallurgical capability and testing infrastructure access. Pricing pressure stems from alumina refining concentration in Australian and Guinean feedstock channels. State utilities in India exhibit highest price sensitivity, while German transmission system operators prioritize ampacity performance over unit cost.
Supply Chain Analysis
Strategic stockpiling of aluminium ingot dominates procurement behavior among European cable producers anticipating CBAM-related supply disruptions. Raw metal supply concentrates in China's Yangtze River Delta, India's Gujarat corridor, and Germany's Ruhr industrial zone. Foundry operations draw from bauxite processed through Australian and Guinean alumina refineries. Single-source vulnerability runs through concentrated smelter certification under China's MEE protocols. Distribution runs through direct EPC contractor relationships in Saudi Arabia and Brazil, bypassing traditional intermediary channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Grid modernization programs are transforming aluminium conductor procurement into a platform-economics structure where interoperability between HTLS technology standards and legacy ACSR infrastructure determines competitive positioning across transmission system operators.
For Market Incumbents: Fortify captive alloy supply through backward integration into certified smelter partnerships, insulating margin pools from MEE-driven raw metal channeling in China. Deepen installation service capabilities to defend against unbundling trends separating conductor supply from specialized stringing contracts in Middle Eastern and Latin American tenders.
For New Entrants and Emerging Players: Differentiate on marine-certified alloy formulations for North Sea offshore wind interconnectors, where technical barriers insulate qualified suppliers from price-based competition. Target corrosion-resistant sheathing segments in subsea cable applications as the most penetrable white-space opportunity. Pursue qualification partnerships with European transmission system operators piloting HTLS reconductoring projects.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across thermal-resistant alloy production lines as precision casting expertise scarcity forces wage premiums for metallurgists. Five-to-ten year viability favors foundries with demonstrated IEC 61089 laboratory relationships and captive raw metal arrangements. Watch for smelter consolidation announcements under China's environmental protocols as inflection indicators for regional supply elasticity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Smelter Supply | Secures raw metal channeling priority under China's MEE environmental protocols. |
| HTLS Composite Core Technology Licensing | Enables capacity-upgrade reconductoring tenders in Germany and Spain. |
| Marine Alloy Certification Investment | Unlocks North Sea offshore wind interconnector procurement pools. |
| Installation Capability Captive Buildout | Defends against unbundling of stringing services in Saudi and Brazilian tenders. |
| IEC 61089 Laboratory Partnership | Accelerates certification timelines for emerging market supplier qualification. |
Methodological Framework
A spread of perspectives from utility procurement officers, foundry operations managers, EPC contractor project directors, and transmission system operator planning engineers converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against FERC interconnection databases, IEC standards documentation, State Grid tender disclosures, and customs trade flows for aluminium ingot and stranded conductor categories. Bottom-up volume builds triangulated against top-down smelter capacity assessments.
Segmentation dimensions modeled span product architecture, voltage application tier, installation environment, and end-user procurement structure across the projection horizon. CAGRs derived from regression analysis of historical tender volumes against announced grid modernization program commitments. Industry-specific forecast inputs incorporated renewable interconnection queue depths in ERCOT and PJM territories, plus CEA-mandated rural electrification contract schedules.
The analysis sits within stated boundaries; outcomes outside sustained state-backed infrastructure investment levels or accelerated HTLS technology adoption curves would require recalibration. Forecasts reflect documented assumptions regarding smelter certification trajectories and alloy purity standard evolution. Revision becomes warranted when carbon-border adjustment mechanism implementation crosses implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Beryllium Copper Billet Market
Metals
Global Aluminum Market
Metals
Metal Forging Parts Market
Metals
Europe Aluminium Wire Rod Market
Metals
United States Aluminum Extrusion Market
Metals
Saudi Arabia Aluminum Market
Metals
Tin Chloride Market
Metals
Rare Earth Metals Market
Metals
Ferrosilicon Magnesium Market
Metals
Aluminum Flat-Rolled Products Market
Metals
Aluminum Fluoride Market
Metals
Global Brass Rods Market
Metals
Beryllium Market
Metals
High-End Copper Foil Market
Metals
Carbotanium Market
Metals
Global Metal and Metal Manufactured Products Market