
 Beryllium Copper Plate Market | 2026-2036
Beryllium Copper Plate Market Size, Share, and Industry Trends Forecast 2026-2036
Beryllium Copper Plate Market Insights
Buyer concentration among aerospace tier-one suppliers is pivoting toward long-term alloy supply agreements with certified producers. Materion leverages captive beryllium extraction to sustain upstream cost control across defense and semiconductor customer bases. NGK Metals anchors Japanese electronics demand through precision-rolled strip capacity in Nagoya. IBC Advanced Alloys differentiates via North American toll processing for oilfield and aviation clients requiring lot-traceable material.
Beryllium copper plate is a precipitation-hardenable copper alloy containing 0.2% to 2.0% beryllium by weight, typically supplied in solution-annealed or age-hardened tempers with tensile strengths exceeding 1,200 MPa after heat treatment; manufacturers produce it through vacuum induction melting, hot rolling, and controlled thermal processing to achieve the fatigue resistance and electrical conductivity required for high-reliability connectors and springs. Electrical connectors command the largest application share due to 5G infrastructure buildouts and electric vehicle charging hardware, while oilfield equipment represents the fastest-growing segment as directional drilling tools require non-sparking, high-strength alloys in sour gas environments. Precipitation hardened grades capture the dominant product type position because end users prioritize strength-to-conductivity ratios over standard alloy economics in safety-critical installations.
OSHA enforces strict permissible exposure limits for beryllium in workplace air, compelling fabricators to invest in ventilated machining centers and worker monitoring programs. REACH registration requirements in Europe restrict uncertified alloy imports, while China's GB standards govern beryllium content labeling for industrial resale. Stakeholders must monitor regulatory divergence between jurisdictions to avoid supply chain disqualification as certification regimes tighten.
Market Dynamics
Precipitation-hardened beryllium copper plate procurement is tightening around certified supply chains as REACH compliance and OSHA exposure protocols force fabricators toward lot-traceable, single-source alloy agreements with documented thermal processing histories.
Growth Catalysts
- 5G Infrastructure Buildouts:Base station antenna connectors and high-frequency signal relays require the fatigue resistance and electrical conductivity that precipitation-hardened grades deliver.
- REACH Registration Requirements:ECHA mandates for beryllium content documentation and safe-use communication are consolidating demand toward certified European producers with established compliance infrastructure.
- Directional Drilling Tool Demand:Sour gas exploration in the Permian Basin and North Sea is accelerating non-sparking alloy consumption for downhole components in hydrogen sulfide environments.
Market Restraints
- Beryllium Ore Supply Concentration:Over 60% of mined beryllium originates from sporadically operating bertrandite deposits in Utah and sporadic spot-market spodumene byproduct recovery, creating raw material availability risk.
- Substitution by Copper-Nickel-Tin Spinodal Alloys:C72900 and related spinodal systems offer comparable strength without beryllium toxicity concerns, capturing connector applications where electrical conductivity requirements moderate.
- OSHA Permissible Exposure Limit Compliance Costs:The 0.2 microgram per cubic meter workplace air standard necessitates ventilated machining centers, respiratory protection programs, and medical surveillance that elevate fabrication overhead.
Strategic Opportunities
- Underpenetrated Indian Electronics Fabrication:PLI scheme incentives for semiconductor and telecom equipment manufacturing are creating first-mover advantage for certified alloy suppliers establishing toll processing partnerships in Gujarat and Karnataka.
- EV Charging Hardware Thermal Management:High-current contactors and busbar connectors in 800-volt architectures favor beryllium copper's conductivity-strength combination over pure copper or aluminum alternatives.
- Dual Carbon Goals in China:MIIT energy efficiency mandates for industrial equipment are accelerating lightweight, high-reliability alloy substitution in precision motion control and robotics end-use sectors.
Industry Challenges
- Heat Treatment Technician Scarcity:Controlled aging protocols for achieving specified mechanical properties require specialized metallurgical expertise that vocational programs have not scaled to match demand.
- Lot Traceability System Integration:Aerospace and defense customers mandate blockchain or equivalent digital chain-of-custody documentation that legacy ERP systems cannot accommodate without substantial middleware investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beryllium Copper Plate Market |
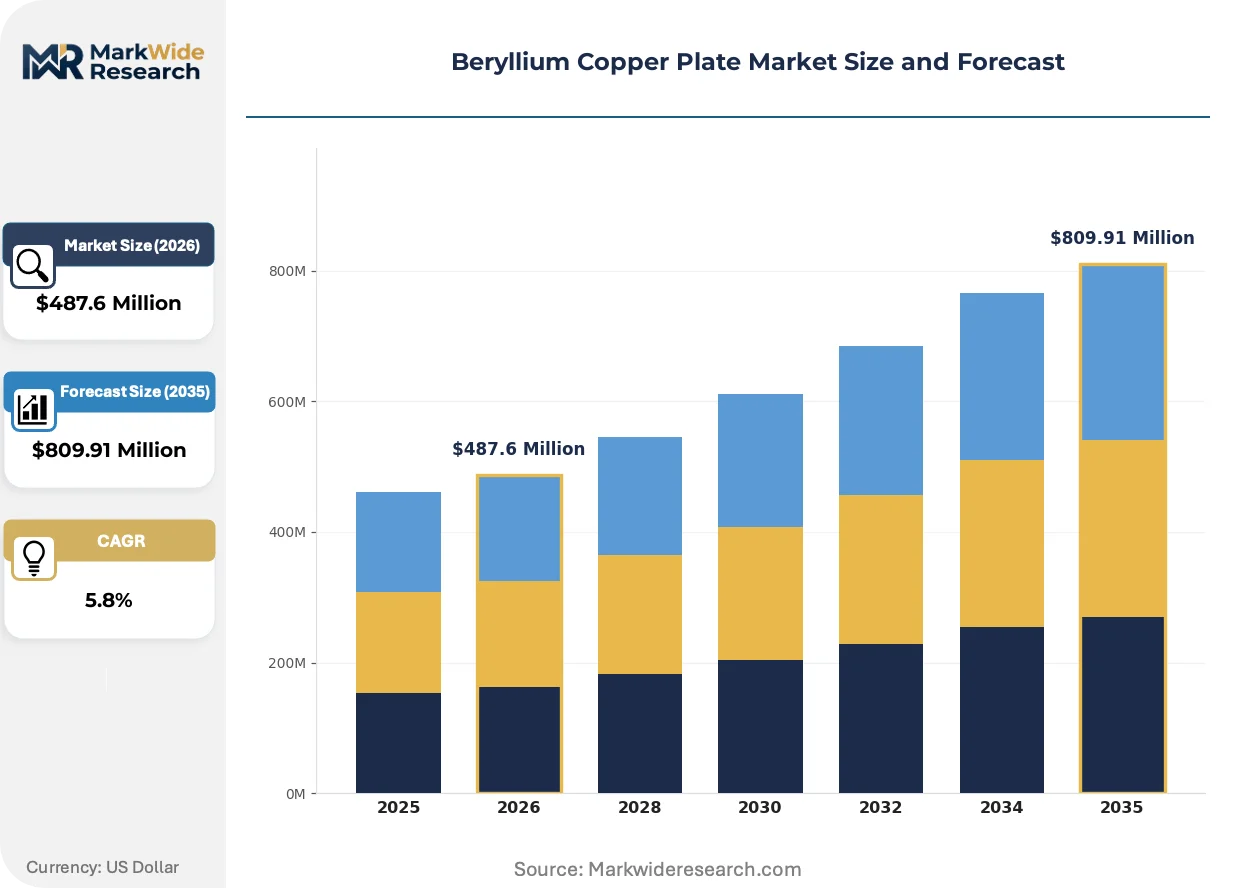
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $809.91 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Alloy, High Conductivity, Precipitation Hardened, Free Machining Application: Electrical Connectors, Springs & Clips, Aerospace Components, Oilfield Equipment End User Industry: Electronics Manufacturers, Aviation & Defense, Energy Sector, Precision Tooling Form: Sheets, Plates, Foils, Strips |
| Companies Covered | Materion, NGK Metals, IBC Advanced Alloys, Belmont Metals, AMPCO METAL, Aviva Metals, Wieland-Werke, Mitsubishi Shindoh, Shanghai Metal Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beryllium Copper Plate Market Trends and Innovations
Thermal processing automation and digital compliance infrastructure are compressing lead times while tightening material certification standards across defense, semiconductor, and energy end-use sectors.
Continuous in-line age-hardening furnaces with real-time hardness monitoring are automating temper consistency that previously required batch oven sampling and laboratory verification. Aerospace fastener manufacturers in Germany and the United States are adopting these systems to eliminate lot rejection risk. The technology is automating quality assurance labor out of high-volume strip production while enabling just-in-time delivery contracts that batch processing cannot support.
OSHA's 2023 expanded beryllium standard for general industry is mandating engineering controls and medical surveillance that small machine shops cannot sustain without consolidation or toll processing arrangements. Fabricators serving oilfield and aviation customers are outsourcing precision grinding and EDM operations to certified toll processors with established ventilation infrastructure. The regulation is most severely affecting job-shop manufacturers in Texas and Oklahoma, many of which are exiting the alloy to avoid liability exposure.
Long-term alloy supply agreements with embedded price collars are displacing spot market purchasing among tier-one aerospace suppliers. Materion and NGK Metals are capturing five-to-seven-year contracts with minimum volume commitments that lock in capacity and insulate against beryllium price volatility. This procurement consolidation is most visible in the Pacific Northwest and Nagoya precision electronics clusters, where connector manufacturers are sacrificing flexibility for supply security and audit-ready documentation.
Beryllium Copper Plate Market Segmentation
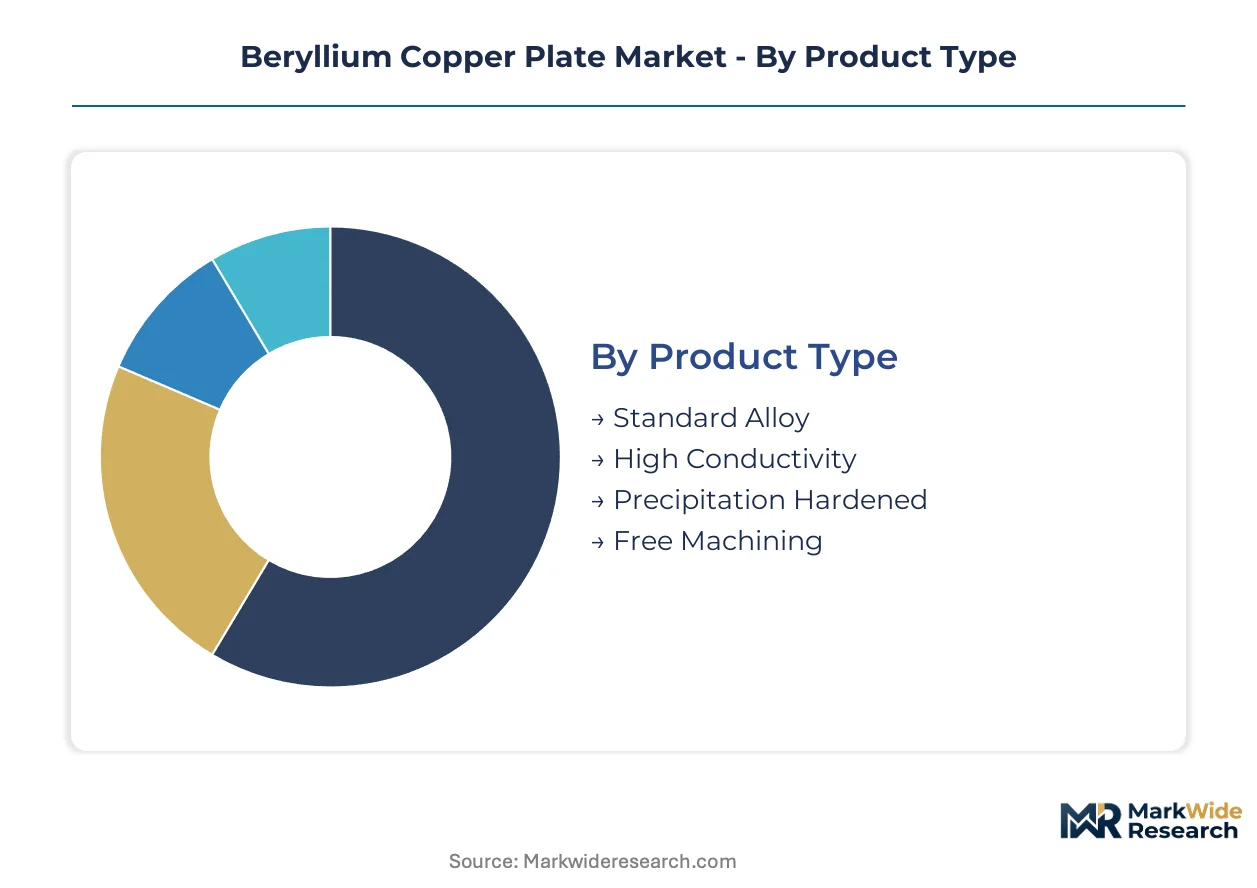
Segmentation in beryllium copper plate markets tracks capital allocation across metallurgical complexity tiers and regulatory exposure levels. Procurement patterns diverge sharply between commodity-grade fabricators and certified suppliers serving aerospace and semiconductor end-use sectors.
Product Type:
Capital intensity escalates with thermal processing sophistication, from as-cast standard alloys to precision-aged precipitation-hardened grades requiring vacuum furnace infrastructure.
- Precipitation Hardened:Age-hardenable alloys achieving tensile strengths exceeding 1,200 MPa through controlled thermal cycles. Demand concentrates in aerospace fastener and 5G base station connector applications where fatigue resistance justifies premium pricing and lot-traceability documentation.
- High Conductivity:Lower-beryllium formulations optimized for electrical performance in high-current EV charging hardware. Japanese electronics clusters in Nagoya and German automotive suppliers prioritize this grade for 800-volt busbar connectors requiring conductivity-strength balance.
- Standard Alloy:General-purpose grades serving industrial tooling and non-critical electrical applications with minimal heat treatment requirements.
- Free Machining:Lead-enhanced variants for high-speed screw machine production of small precision components where chip control outweighs conductivity requirements.
Most installed capacity flows through Precipitation Hardened grades. Expansion is steepest in High Conductivity alloys.
Application:
Application segmentation reflects divergent certification burdens, from mass-produced electronics components to safety-critical aerospace and energy installations.
- Electrical Connectors:Dominant volume segment spanning telecommunications infrastructure, automotive charging systems, and industrial controls. 5G antenna interconnects and EV high-voltage contactors in China and Germany drive specification tightening toward precipitation-hardened grades with documented thermal histories.
- Oilfield Equipment:Non-sparing directional drilling tools for sour gas environments in the Permian Basin and North Sea. Hydrogen sulfide corrosion resistance and spark-free operation mandate specialized alloy selection with full material certification chains.
- Aerospace Components:Fasteners, landing gear bushings, and actuator components requiring FAA-compliant lot traceability and statistical process control documentation.
- Springs & Clips:High-cycle fatigue applications in precision instrumentation and semiconductor test equipment where stress relaxation resistance determines service life.
Electrical Connectors absorb the majority of rolling mill output. Oilfield Equipment is climbing the fastest as unconventional drilling deepens.
End User Industry:
End-user segmentation maps procurement sophistication, from commodity electronics fabricators to defense contractors requiring embedded compliance infrastructure.
- Electronics Manufacturers:Connector and relay producers in precision electronics clusters across China, Germany, and the United States. REACH registration requirements and OSHA exposure protocols are consolidating procurement toward certified suppliers with established ventilation and worker monitoring programs.
- Aviation & Defense:Tier-one aerospace suppliers and defense contractors mandating blockchain-enabled chain-of-custody documentation. Five-to-seven-year alloy supply agreements with embedded price collars are displacing spot market purchasing.
- Energy Sector:Oilfield service companies and downhole tool manufacturers requiring sour-gas-rated alloys with full metallurgical certification for directional drilling operations.
- Precision Tooling:Mold and die manufacturers, welding electrodes, and plastic injection tooling where wear resistance and thermal conductivity balance determine alloy selection.
Electronics Manufacturers command the largest share of mill-direct volume. Aviation & Defense is gaining share fastest through long-term contract consolidation.
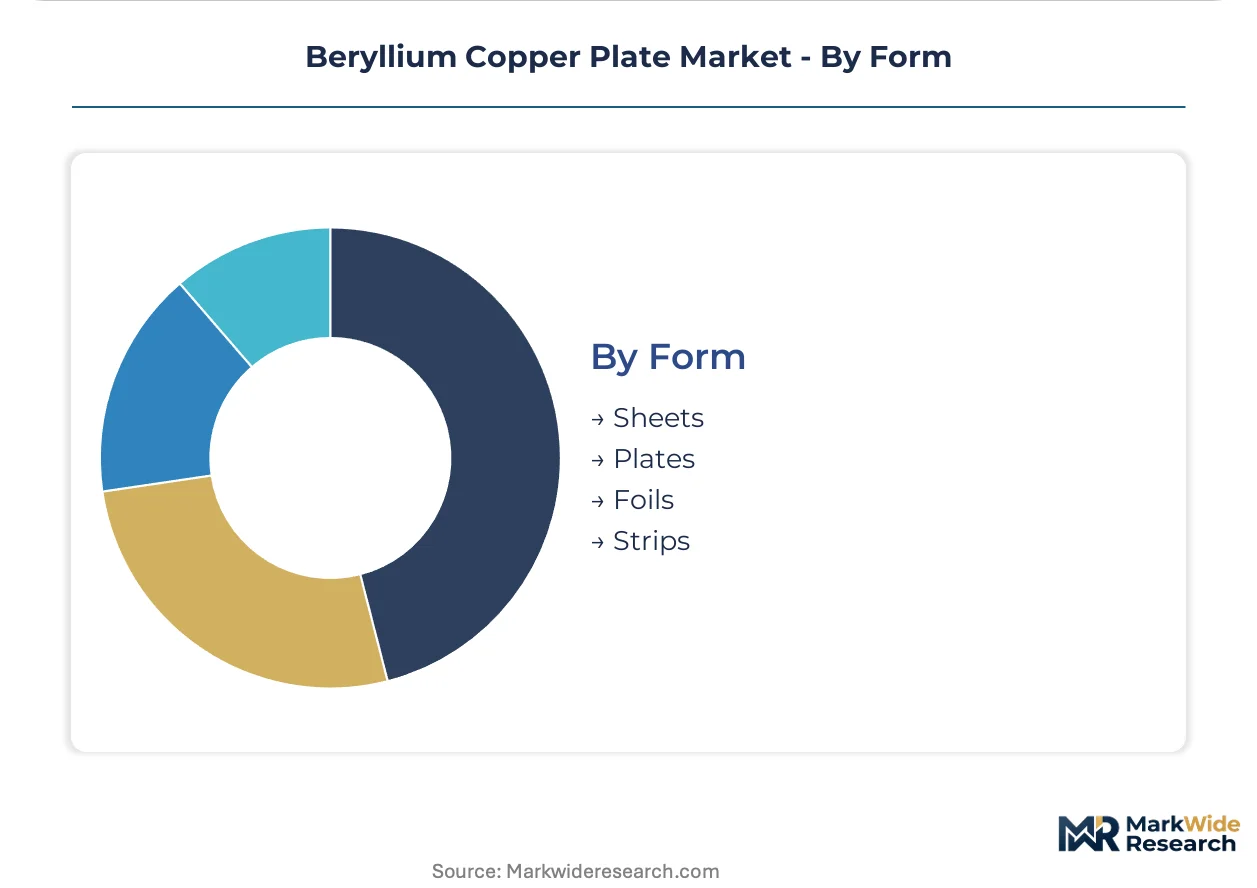
Form:
Form factor segmentation tracks downstream processing economics, from thin-gauge precision strip to heavy plate requiring specialized heat treatment equipment.
- Strips:Precision-rolled narrow gauges for progressive die stamping of miniature connectors and springs. Continuous in-line age-hardening furnaces with real-time hardness monitoring are automating temper consistency for high-volume Japanese and German electronics producers.
- Plates:Thick-section material for aerospace structural components and oilfield downhole tools requiring solution annealing and controlled aging to achieve through-thickness property uniformity.
- Sheets:Intermediate gauges for fabricated electrical buswork and industrial tooling where flatness and surface finish specifications vary by end-use.
- Foils:Ultra-thin gauges for specialized electromagnetic shielding and miniature spring applications in medical and semiconductor test equipment.
Strip production dominates rolling mill utilization. Plate demand is expanding most quickly on aerospace and energy sector procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States procurement concentrates on aerospace certification chains while Chinese demand clusters around precision electronics fabrication, revealing divergent regulatory compliance burdens across major consumption centers.
United States
Aerospace tier-one suppliers in the Pacific Northwest and Texas are locking in five-to-seven-year alloy supply agreements with embedded price collars. OSHA's expanded 2023 beryllium standard mandates engineering controls and medical surveillance that small fabricators cannot sustain. Precision machining clusters around Houston and Seattle are consolidating toward certified toll processors with established ventilation infrastructure.
Germany
Automotive suppliers in Baden-Württemberg prioritize high-conductivity grades for 800-volt EV charging hardware requiring conductivity-strength balance. REACH registration requirements through ECHA restrict uncertified alloy imports and consolidate demand toward domestic producers with compliance infrastructure. The Stuttgart precision electronics corridor is automating connector production through continuous in-line age-hardening furnaces.
China
MIIT energy efficiency mandates for industrial equipment accelerate lightweight alloy substitution in precision motion control applications. GB standards govern beryllium content labeling for industrial resale, creating documentation requirements for domestic distribution. Yangtze River Delta fabrication clusters in Suzhou and Shanghai are scaling precipitation-hardened grade capacity for 5G base station connectors.
Japan
Electronics manufacturers in the Nagoya precision strip corridor demand lot-traceable material with documented thermal processing histories. METI industrial policy supports domestic alloy production for semiconductor test equipment and high-frequency signal relays. Chubu region rolling mills are capturing long-term supply agreements from connector producers sacrificing flexibility for certification security.
India
PLI scheme incentives for semiconductor and telecom equipment manufacturing create first-mover positioning for certified alloy suppliers. The country's national industrial regulator enforces workplace safety protocols that elevate fabrication overhead for non-compliant operators. Gujarat and Karnataka electronics fabrication zones are attracting toll processing partnerships from established Asian producers.
Beryllium Copper Plate Market Competitive Landscape
North American producers anchor the premium-tier certification vector; Japanese and European specialists hold precision-rolled strip capacity for high-volume electronics contracts. Market structure consolidates around three strategic archetypes: captive beryllium extractors with upstream cost control, precision-rolled strip specialists serving narrow-gauge demand, and toll processors offering lot-traceable thermal processing for safety-critical applications. Competitive positioning hardens through long-term supply agreements with minimum volume commitments and backward integration into beryllium extraction assets.
Among North American integrated producers, Materion exemplifies the captive-extraction archetype through in-house bertrandite sourcing, while IBC Advanced Alloys occupies the toll-processing tier serving oilfield and aviation clients requiring documented thermal histories. NGK Metals anchors Japanese electronics demand through Nagoya-based precision capacity. These three represent the dominant competitive configurations: upstream-integrated defense suppliers, regional toll processors with compliance infrastructure, and precision-strip specialists serving high-volume connector manufacturers.
| Leading Market Players |
|---|
| Materion |
| NGK Metals |
| IBC Advanced Alloys |
| Belmont Metals |
| AMPCO METAL |
| Aviva Metals |
| Wieland-Werke |
| Mitsubishi Shindoh |
| Shanghai Metal Corporation |
| Others |
Pricing and Supply Chain Analysis
Five-to-seven-year alloy supply agreements with embedded price collars among tier-one aerospace suppliers are forcing supply chains toward certified toll processors with documented thermal histories, compressing spot market liquidity and elevating premiums for lot-traceable material.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for standard-grade precipitation-hardened alloys. Three-tier pricing structure across premium certified, standard industrial, and economy-grade levels separates aerospace fastener producers from oilfield tool fabricators and commodity electronics stampers. Price differentiation hinges on certification documentation depth and volume scale, with premium tiers commanding substantial markups for blockchain-enabled chain-of-custody. Pricing pressure stems from copper-nickel-tin spinodal substitution in moderate-conductivity connector applications. Electronics manufacturers in Nagoya and Suzhou exhibit highest price sensitivity, while aviation and defense contractors prioritize supply security over unit economics.
Supply Chain Analysis
Beryllium ore supply rests on sporadically operating bertrandite deposits in Utah and spot-market spodumene byproduct recovery, creating raw material availability risk that propagates through downstream alloy production. Geographic supply concentration spans the United States, Japan, and Germany for precision-rolled strip capacity, with China expanding precipitation-hardened grade output for domestic 5G infrastructure. Raw material dependencies include mined beryllium concentrates, copper cathodes, and controlled-atmosphere furnace infrastructure. Single-source vulnerability characterizes upstream extraction, where over sixty percent of mined supply originates from domestic U.S. deposits. Distribution runs through mill-direct contracts for high-volume electronics and toll processing arrangements for safety-critical aerospace and oilfield applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
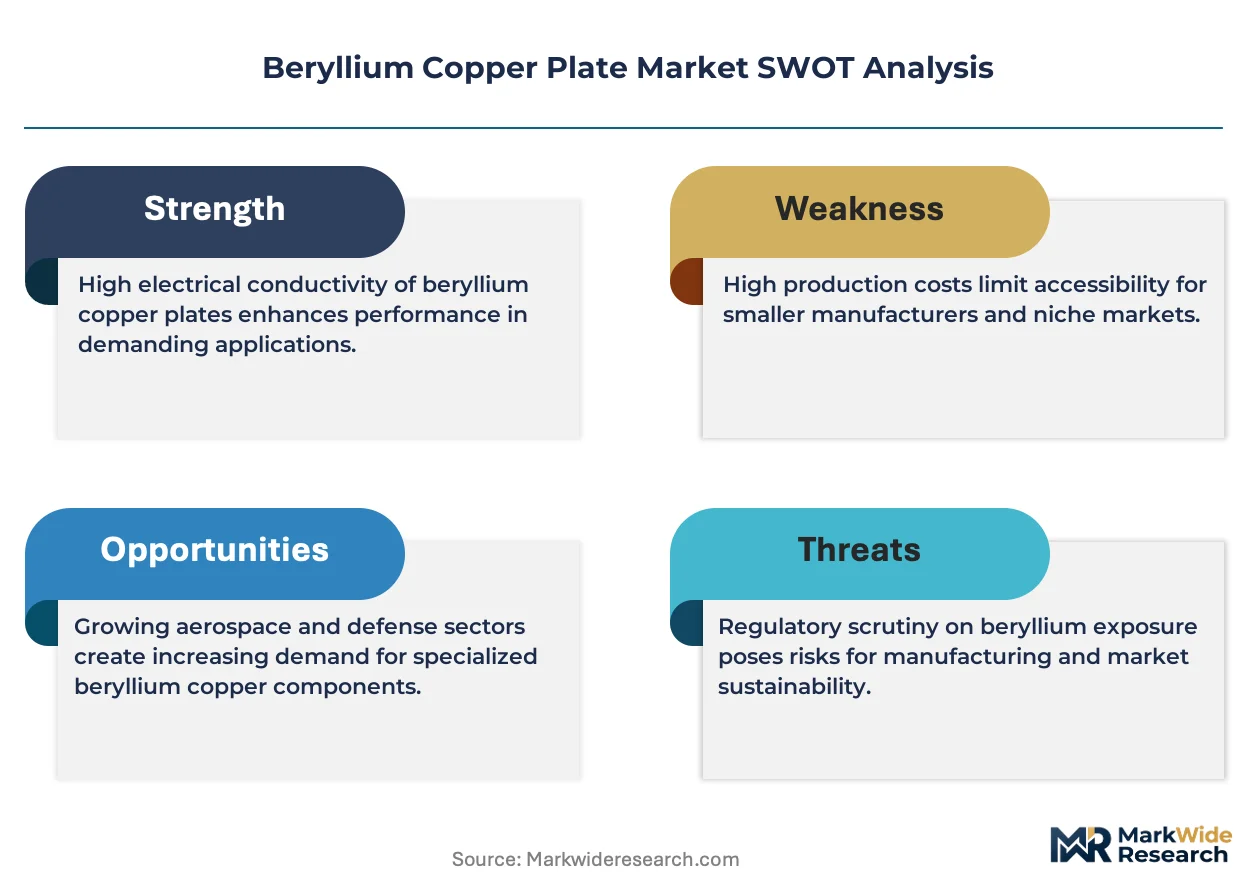
The beryllium copper plate market represents a late-cycle quality story as procurement consolidation around REACH-compliant, OSHA-certified supply chains elevates specification premiums and disqualifies commodity-grade competitors.
For Market Incumbents: Acquire vacuum induction melting and continuous in-line age-hardening furnace assets to automate temper consistency and eliminate lot rejection risk. Consolidate toll processing partnerships in Texas and Oklahoma as OSHA's expanded beryllium standard forces small fabricators toward exit. Copper-nickel-tin spinodal alloys threaten connector market share where conductivity requirements moderate. Backward integration into captive beryllium extraction insulates against raw material volatility and secures upstream cost control.
For New Entrants and Emerging Players: The price-point gap between premium certified and economy-grade material creates entry space for mid-tier producers offering documented thermal histories without full aerospace certification overhead. Target India's Gujarat and Karnataka electronics fabrication zones where PLI scheme incentives attract first-mover toll processing partnerships. The most penetrable segment lies in high-conductivity grades for 800-volt EV charging hardware, where conductivity-strength balance requirements favor beryllium copper over pure copper alternatives. Go-to-market positioning should emphasize rapid lot traceability system deployment to meet emerging blockchain documentation mandates.
For Investors and Strategic Acquirers: Asymmetric upside sits with precision-rolled strip specialists serving Nagoya and Stuttgart connector clusters, where long-term supply agreements lock in capacity and insulate against beryllium price volatility. Five-to-ten-year viability framing favors producers with embedded compliance infrastructure and established ventilation programs that small competitors cannot replicate. Acquisition target archetype: regional toll processors with FAA-compliant thermal processing documentation and established oilfield customer relationships. The signal to watch is heat treatment technician scarcity, which could constrain output expansion and sustain pricing power for automated producers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Beryllium Extraction | Captive bertrandite sourcing secures upstream cost control against sporadic spot-market availability. |
| Continuous In-Line Age-Hardening Furnace Deployment | Real-time hardness monitoring automates temper consistency for just-in-time aerospace delivery contracts. |
| Long-Term Alloy Supply Agreement with Price Collars | Five-to-seven-year contracts with minimum volume commitments lock in capacity and insulate against volatility. |
| Blockchain-Enabled Lot Traceability System | Digital chain-of-custody documentation satisfies FAA and defense customer mandates for material certification. |
| Toll Processing Partnership in India | PLI scheme incentives in Gujarat and Karnataka create first-mover positioning for certified alloy suppliers. |
Research Methodology
Bottom-up electrical connector and aerospace component modeling reconciled against top-down beryllium extraction and rolling mill capacity tracking forms the analytical core. Primary interviews with plant managers at precision strip producers, procurement leads at tier-one aerospace suppliers, oilfield service company metallurgists, and heat treatment technicians inform demand-side validation. Secondary sources include SEC filings from integrated producers, OSHA enforcement data on beryllium exposure compliance, ECHA REACH registration databases, and customs trade records for beryllium copper alloy imports. Triangulation between end-use consumption estimates and supply-side production capacities validates volume and value outputs.
Historical trendline analysis of precipitation-hardened grade consumption patterns across the projection horizon informs growth trajectory assumptions. Segmentation modeling spans product type, application, end-user industry, and form factor dimensions, with additional granularity for certification tier and thermal processing sophistication. CAGRs derive from regression analysis of segment-level demand drivers against supply constraints. Industry-specific forecast inputs include 5G base station deployment schedules, EV charging infrastructure buildout rates, and directional drilling activity in sour gas formations.
Caveats apply where regulatory divergence between OSHA, ECHA, and China's GB standards could materially shift the outlook for cross-border alloy trade. Forecasts reflect assumptions regarding beryllium ore supply continuity, substitution dynamics from spinodal alloys, and automation adoption rates for thermal processing. A small set of named triggers warrants ongoing watch: heat treatment technician scarcity, blockchain documentation mandate expansion, and upstream extraction asset consolidation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Tungsten Metal Powder Market
Metals
Metal Injection Molding (Mim) Powders Market
Metals
Arc Ferrite Magnet Market
Metals
Nickel Sulfate Market
Metals
Smelting Chemicals Market
Metals
Brazil Aluminum Market
Metals
Finished Steel Products Market
Metals
Metal Coil Lamination Market
Metals
China Neodymium Iron Boron Magnet Market
Metals
Global Tin Market
Metals
Aluminium Collars Market
Metals
High Purity Lead Market
Metals
Europe Metal Service Centers Market
Metals
Lanthanum Market
Metals
North America and Europe Metal Powder Market
Metals
Potassium Platinochloride Market