
 Powder Coating Booth Market | 2026-2036
Powder Coating Booth Market Size, Share, and Industry Trends Forecast 2026-2036
Powder Coating Booth Market Analytics
Chinese equipment fabricators is hardening as domestic producers scale automated booth assembly lines for export markets. Nordson Corporation leverages its precision spray control portfolio to anchor premium positions in North American and European coating facilities. Gema Switzerland GmbH sustains technology leadership through electrostatic application innovations, while WAGNER competes aggressively on modular system configurability for mid-sized metal fabrication shops.
A powder coating booth constitutes an enclosed or semi-enclosed chamber engineered to contain overspray during electrostatic powder application, typically integrating recovery cyclones, cartridge filtration modules, and controlled airflow systems maintaining 0.3 to 0.5 m/s cross-draft velocities. These structures serve the essential industrial purpose of capturing reclaimable powder particulate while ensuring operator safety and finish uniformity across batch or continuous production modes. Automated booths command the dominant share of value as automotive painting lines demand synchronized conveyor integration and real-time powder recovery rates exceeding 95 percent. Batch booths retain stronghold positions in custom metal fabrication and job shop environments where part variety precludes dedicated conveyor systems, while modular booths represent the fastest-growing configuration as manufacturers seek scalable capacity additions without full line replacement.
EPA National Emission Standards for Hazardous Air Pollutants and OSHA ventilation requirements govern booth exhaust and worker exposure thresholds in the United States, compelling capital investment in upgraded filtration and containment architectures. China's MEE enforces parallel emission controls through GB standards on industrial coating processes, creating comparable compliance-driven replacement cycles across East Asian manufacturing bases. Stakeholders must evaluate whether to prioritize captive recovery technology development or partner with specialized filtration suppliers as regulatory stringency tightens across multiple jurisdictions.
Market Dynamics
Automotive OEM consolidation of painting operations into centralized mega-facilities is compressing equipment procurement cycles while elevating performance specifications for powder recovery efficiency and cross-draft uniformity.
Growth Catalysts
- EPA National Emission Standards for Hazardous Air Pollutants:US coating facilities face mandatory booth exhaust upgrades, accelerating capital deployment toward enclosed recovery systems with filtration rates exceeding 99 percent.
- China's industrial manufacturing corridors:Coating line retrofits in Guangdong and Jiangsu provinces concentrate demand for automated booth configurations with integrated conveyor synchronization.
- Electrostatic spray precision technology:Real-time powder application control enables automotive tier-one suppliers to achieve transfer efficiency above 95 percent, reducing material waste and rework costs.
Market Restraints
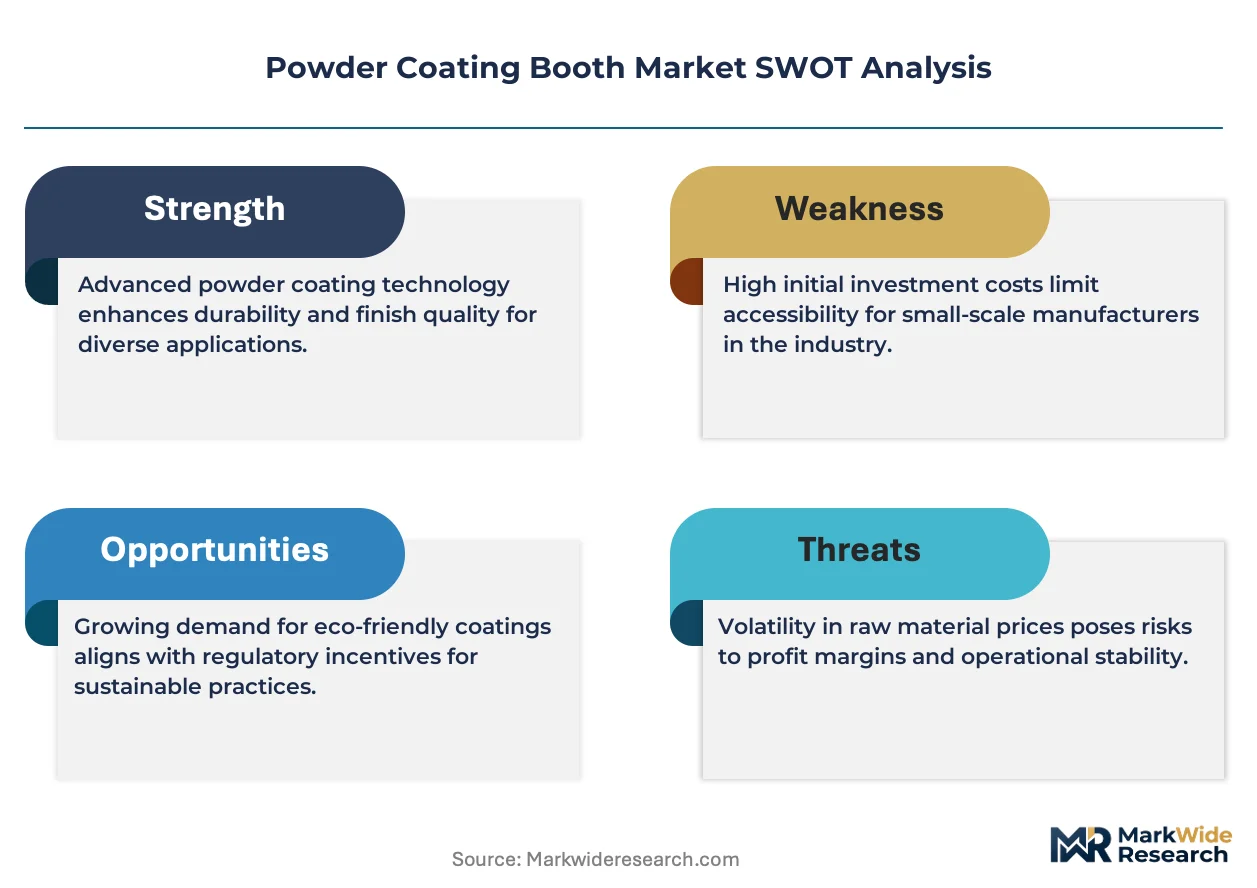
- Steel and aluminum input volatility:Booth frame fabrication depends on commodity metal pricing that fluctuates with energy costs, compressing margins for equipment fabricators on fixed-price contracts.
- Cartridge filtration supply concentration:Specialized filter media production clusters in Germany and Japan, creating vulnerability for North American booth operators seeking qualified replacement components.
- Liquid coating substitution threat:Advanced waterborne paint systems with reduced VOC profiles compete for automotive exterior applications where color-matching flexibility outweighs powder durability advantages.
Strategic Opportunities
- India's PLI scheme for automotive manufacturing:Greenfield coating facilities in Pune and Chennai offer first-mover positioning for modular booth suppliers capable of rapid deployment.
- Convergence of IoT sensors and predictive maintenance platforms:Smart booth systems that monitor airflow velocity and filter saturation enable service-contract revenue streams beyond equipment sale.
- EU Green Deal industrial decarbonization incentives:Member state subsidies for energy-efficient manufacturing equipment favor powder coating adoption over thermal-cure liquid alternatives in metal fabrication.
Industry Challenges
- Electrostatic application specialist shortage:Booth commissioning and optimization requires technicians trained in high-voltage safety and powder fluidization dynamics, creating bottlenecks for rapid facility ramp-up.
- Legacy solvent-booth infrastructure retrofit complexity:Existing paint shops face structural constraints on airflow ducting and floor loading that complicate powder system integration without complete building modification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Powder Coating Booth Market |
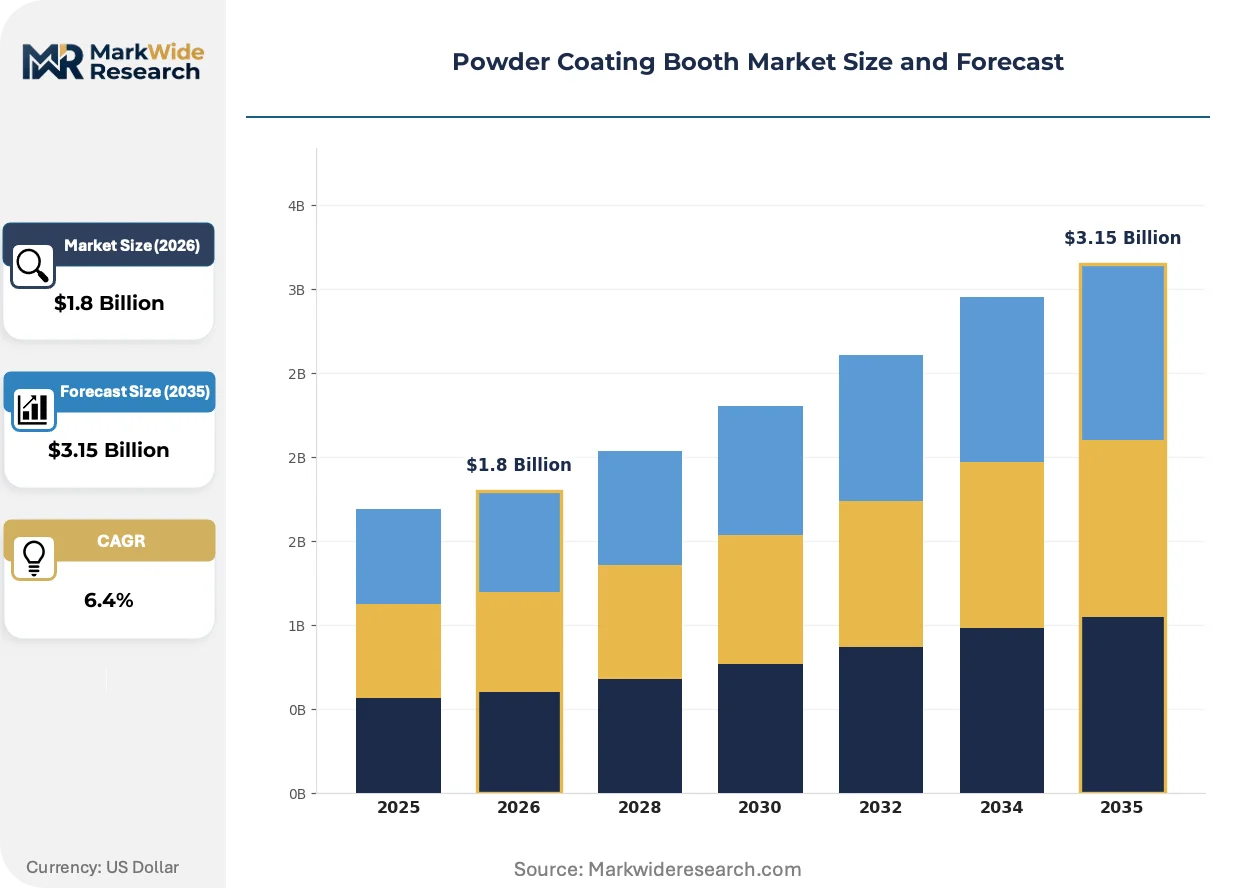
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Booths, Automated Booths, Modular Booths, Downdraft Booths End User: Aerospace, Automotive OEMs, Consumer Goods, Metal Fabrication Application: Industrial Coating, Decorative Coating, Functional Coating, Automotive Painting Technology: Electrostatic Coating, Manual Coating, High-Volume Low-Pressure, Others |
| Companies Covered | Nordson Corporation, Gema Switzerland GmbH, WAGNER, Hangzhou Color Powder Coating Equipment, Mitsuba Systems Pvt. Ltd., Dürr, Eastwood Company, Oven Empire Manufacturing, Rippert GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Powder Coating Booth Market Evolving Landscape
Equipment architecture is fragmenting into interchangeable subsystems as manufacturers seek operational flexibility without full line replacement, while regulatory pressure on emissions intensifies filtration performance requirements.
Modular booth construction is modularizing powder coating infrastructure into standardized floor sections, filtration pods, and recovery cyclones that permit capacity scaling in 2-meter increments. Tier-two automotive suppliers and custom metal fabricators adopt these configurations to defer capital commitment until order volumes justify expansion. This approach compresses lead times from 16 weeks to 6 weeks and enables relocation of production assets between facilities.
REACH restrictions on per- and polyfluoroalkyl substances are compelling European coating operations to eliminate fluoropolymer-based powder formulations previously prized for chemical resistance. Industrial finishers in Germany and Italy face reformulation costs and application parameter recalibration for automotive underhood components and agricultural machinery. Booth suppliers respond with enhanced temperature control systems accommodating wider powder cure windows.
Consolidated procurement by multi-site coating service providers is displacing decentralized equipment purchasing as national job shop chains centralize technical specifications and vendor qualification. Large metal fabrication groups in the United States negotiate enterprise frameworks with single-source booth suppliers, extracting volume pricing and standardized training protocols. This concentration pressures regional equipment distributors to develop aftermarket service capabilities or exit the market.
Powder Coating Booth Market Segmentation
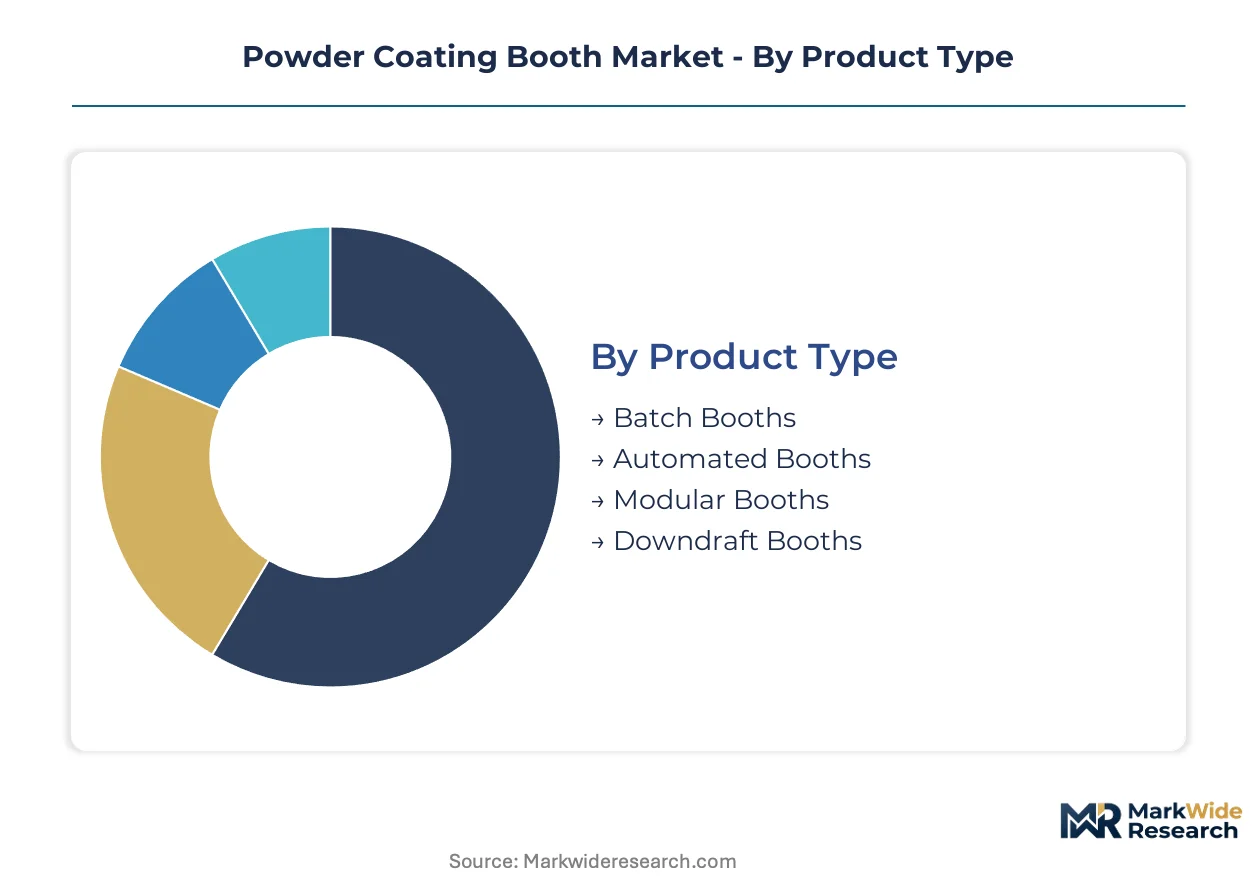
Powder coating booth procurement patterns diverge sharply across operational scales and regulatory exposure. Segmentation reveals how capital deployment priorities shift between compliance-driven replacement and capacity expansion scenarios.
Product Type:
Equipment upgrade cycles accelerate where recovery efficiency mandates tighten, reshaping replacement priorities across facility vintages.
- Automated Booths:These systems integrate conveyor synchronization and real-time powder recovery exceeding 95 percent. Automotive OEMs in Germany and the United States concentrate demand as centralized mega-facilities consolidate painting operations into single-site configurations.
- Modular Booths:Standardized floor sections and filtration pods enable capacity scaling in 2-meter increments. Custom metal fabricators in Guangdong province adopt these configurations to defer capital commitment until order volumes justify expansion.
- Batch Booths:Job shop environments with high part variety rely on these configurations where dedicated conveyor systems prove economically unviable.
- Downdraft Booths:Vertical airflow designs serve specialized applications requiring superior contamination control during critical coating phases.
Volume placements concentrate in Automated Booths; the faster expansion belongs to Modular Booths.
End User:
Customer concentration patterns reflect divergent performance specifications and procurement sophistication across industrial sectors.
- Automotive OEMs:Tier-one suppliers demand synchronized conveyor integration and cross-draft uniformity within 0.3 to 0.5 m/s tolerances. EPA National Emission Standards for Hazardous Air Pollutants compel these operators toward enclosed recovery systems with filtration rates exceeding 99 percent.
- Metal Fabrication:Job shops and custom fabricators prioritize configurability over throughput, driving adoption of modular systems with rapid redeployment capability.
- Aerospace:Precision finish requirements and stringent quality documentation favor batch configurations with dedicated environmental controls.
- Consumer Goods:Appliance and furniture manufacturers balance coating durability against color-matching flexibility in mid-volume production environments.
Procurement volume clusters with Automotive OEMs; Metal Fabrication demonstrates the steepest expansion trajectory as distributed manufacturing reshoring accelerates.
Application:
Functional requirements separate commodity protection from premium finish specifications across end-use categories.
- Automotive Painting:Exterior and underhood components demand transfer efficiency above 95 percent to minimize material waste and rework costs in high-volume production.
- Industrial Coating:Agricultural machinery and construction equipment prioritize chemical resistance and weathering durability over aesthetic precision.
- Functional Coating:Electrical insulation and corrosion barriers serve specialized industrial requirements with performance specifications distinct from decorative applications.
- Decorative Coating:Consumer-facing products balance color consistency against production economics in shorter run lengths.
Revenue concentration sits with Automotive Painting; Functional Coating is climbing the fastest as electrification infrastructure expands.
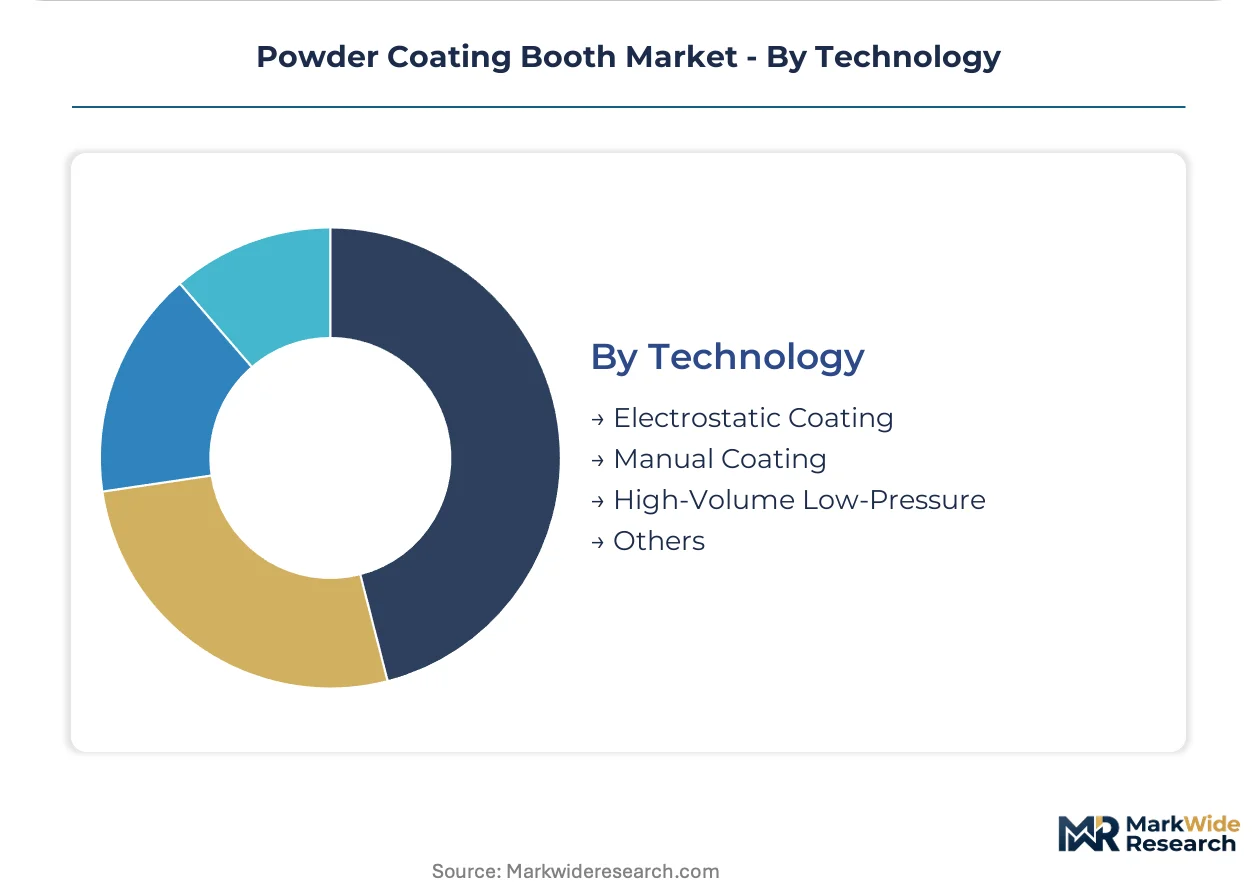
Technology:
Application method selection hinges on part geometry complexity, volume scale, and operator skill availability.
- Electrostatic Coating:Charged particle attraction delivers superior wrap-around coverage on complex geometries. Real-time powder application control enables automotive tier-one suppliers to achieve transfer efficiency above 95 percent.
- High-Volume Low-Pressure:Reduced overspray characteristics serve finishing operations where material conservation competes with capital investment constraints.
- Manual Coating:Job shops with extreme part variety retain these methods where automated system reprogramming costs exceed labor expenditure.
- Others:Emerging application technologies including tribo-charging variants address specialized powder formulations and substrate combinations.
Deployment volume favors Electrostatic Coating; High-Volume Low-Pressure is gaining share fastest among mid-sized metal fabrication operations seeking efficiency without full automation investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Steel fabrication clusters in Guangdong and Jiangsu provinces anchor powder coating booth manufacturing capacity, while regulatory divergence across major economies reshapes equipment specifications and procurement timelines.
United States
Automotive OEM consolidation into centralized mega-facilities drives demand for enclosed recovery systems with 99 percent filtration rates. EPA National Emission Standards for Hazardous Air Pollutants mandate booth exhaust upgrades, compelling capital deployment toward compliance architectures. Michigan and Ohio industrial corridors concentrate coating line retrofits as tier-one suppliers synchronize conveyor integration.
Germany
REACH restrictions on per- and polyfluoroalkyl substances force reformulation of fluoropolymer-based powders for automotive underhood components. EU Green Deal industrial decarbonization incentives favor powder coating over thermal-cure liquid alternatives. Bavaria and Baden-Württemberg manufacturing bases lead adoption of modular booth configurations for scalable capacity.
China
Domestic equipment fabricators scale automated booth assembly lines for export markets as coating line retrofits accelerate in Pearl River Delta manufacturing corridors. MEE enforces GB standards on industrial coating processes through parallel emission controls. Guangdong and Jiangsu provinces concentrate demand for conveyor-synchronized automated configurations.
India
PLI scheme incentives for automotive manufacturing attract greenfield coating facilities in Pune and Chennai industrial zones. Modular booth suppliers target rapid deployment capabilities for first-mover positioning. Maharashtra and Tamil Nadu manufacturing clusters drive procurement of scalable systems without full line replacement.
Japan
Precision finish requirements in aerospace and electronics sustain demand for batch configurations with dedicated environmental controls. METI industrial efficiency standards elevate filtration performance specifications. Chubu and Kansai manufacturing regions concentrate adoption of electrostatic application technologies for complex geometries.
Powder Coating Booth Market Competitive Landscape
Global majors compete with regional champions across technology tiers and geographic proximity to end-user clusters. The vendor base stratifies between precision application specialists, modular system integrators, and commodity frame fabricators. Three archetypes dominate: integrated spray-control technology providers, scalable configuration specialists, and regional job-shop equipment suppliers. Competitive moves concentrate on strategic partnerships for filtration technology access and geographic expansion through distributor network development.
Among Switzerland-based precision specialists, Gema Switzerland GmbH exemplifies electrostatic application leadership, while Nordson Corporation anchors North American and European premium positioning through spray control portfolio breadth. WAGNER occupies the modular configurability tier for mid-sized metal fabrication. Chinese fabricators including Hangzhou Color Powder Coating Equipment represent regional scale players scaling automated assembly for export market penetration.
| Leading Market Players |
|---|
| Nordson Corporation |
| Gema Switzerland GmbH |
| WAGNER |
| Hangzhou Color Powder Coating Equipment |
| Mitsuba Systems Pvt. Ltd. |
| Dürr |
| Eastwood Company |
| Oven Empire Manufacturing |
| Rippert GmbH & Co. KG |
| Others |
Value Network & Pricing Analysis
Modular booth construction techniques spreading from Guangdong fabricators are simultaneously compressing production costs and redistributing supply leverage toward standardized component suppliers. This production-method transition forces traditional integrated manufacturers to unbundle service offerings or absorb margin erosion.
Pricing Analysis
Extended warranty and commissioning service bundles separate premium booth suppliers from commodity frame fabricators competing on equipment-only transactions. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by filtration certification grade and conveyor synchronization capability. Cost compression in standard-tier configurations is intensifying because Chinese producers are scaling automated assembly for export markets. Job shops and custom metal fabricators exhibit highest price sensitivity, while automotive OEMs prioritize performance specifications over unit cost.
Supply Chain Analysis
Container freight rate volatility between Chinese manufacturing clusters and North American industrial corridors directly impacts landed costs for booth frame assemblies and filtration modules. Supply concentrates in China, Germany, and the United States for structural steel fabrication, cartridge filtration media, and electrostatic spray control systems. Production draws from specialized steel alloys, precision-machined aluminum extrusions, and high-voltage transformer components. Single-source vulnerability persists for German and Japanese cartridge filter suppliers. Distribution runs through regional equipment distributors with aftermarket service capabilities or direct OEM procurement for mega-facility deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into filtration media production and captive recovery technology development defines the current vertical-integration race, as regulatory stringency tightens across multiple jurisdictions.
For Market Incumbents: Extend service-contract revenue streams beyond equipment sale through IoT-enabled predictive maintenance platforms monitoring airflow velocity and filter saturation. Deepen backward integration into specialized filtration media to defend against supply concentration in Germany and Japan. Secure enterprise framework agreements with multi-site coating service providers centralizing technical specifications. For New Entrants and Emerging Players: EPA National Emission Standards for Hazardous Air Pollutants in the United States opens a window for modular booth suppliers offering rapid deployment capabilities for compliance-driven retrofits. Target India's PLI scheme automotive manufacturing corridors in Pune and Chennai for greenfield facility first-mover positioning. Pursue partnership strategies with specialized filtration suppliers rather than captive technology development. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by industrial automation conglomerates seeking spray control technology portfolios. Five-to-ten year viability favors suppliers with demonstrated conveyor synchronization capabilities and established automotive OEM relationships. Monitor electrostatic application specialist shortage severity as inflection indicator for service-contract pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Filtration Media | Captive supply of cartridge components insulates margin pressure from German and Japanese supplier concentration. |
| Modular System Configurability Expansion | Scalable 2-meter incremental capacity additions attract Guangdong metal fabricators deferring full line replacement. |
| Predictive Maintenance Platform Deployment | IoT sensor integration enables recurring revenue streams from automotive tier-one supplier installations. |
| Enterprise Framework Agreement Negotiation | Volume pricing extraction from consolidated multi-site coating service providers pressures regional distributors. |
| Regulatory Compliance Certification Investment | EPA and MEE filtration rate validation secures access to automotive OEM mega-facility procurement cycles. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs alongside structured interviews with plant engineers, OEM procurement teams, aftermarket service heads, and coating line operators. Primary fieldwork encompassed technical discussions with electrostatic application specialists and facility maintenance directors at tier-one automotive suppliers. Secondary sources included EPA enforcement databases, China's MEE GB standard publications, SEC 10-K disclosures from listed equipment manufacturers, and customs import records for booth frame assemblies. Bottom-up facility-level capacity assessments triangulated against top-down industry production estimates.
Segment-level granularity modeled product type distinctions across automated, modular, batch, and downdraft configurations alongside end-user categories spanning automotive OEMs, metal fabrication, aerospace, and consumer goods. Technology dimensions incorporated electrostatic coating, high-volume low-pressure, and manual application methods. CAGRs derived from regression analysis against industrial capital expenditure cycles and regulatory compliance deadlines. Forecast inputs incorporated automotive production platform standardization timelines and coating line retrofit acceleration patterns in Pearl River Delta manufacturing corridors.
The model assumes a particular technology adoption path; alternative pathways for tribo-charging application variants would alter the outlook for electrostatic spray control market share distribution. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and commodity metal price stabilization. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Solvent Borne Coatings Market
Coatings
Global Polyurea Coating Market
Coatings
Epoxy Powder Coatings Market
Coatings
Solar Reflective Film Market
Coatings
Mexico Industrial Wood Coatings Market
Coatings
Global Fusion Bonded Epoxy Coatings Market
Coatings
Acrylic Coating Market
Coatings
Asia-Pacific Flat Glass Coating Market
Coatings
Mexico Protective Coatings Market
Coatings
Intumescent Fire Retardant Coating Market
Coatings
FEVE Fluoropolymer Coatings Market
Coatings
South Korea Marine Coatings Market
Coatings
Global Mirror Coatings Market
Coatings
Middle-East and Africa Coil Coatings Market
Coatings
Europe Protective Coatings Market
Coatings
Automotive Refinish Coatings Market