
 Europe Metal Precision Turned Product Manufacturing Market | 2026-2036
Europe Metal Precision Turned Product Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Metal Precision Turned Product Manufacturing Market Insights
The Europe Metal Precision Turned Product Manufacturing Market is rebalancing between aerospace-grade titanium fasteners and commodity carbon-steel bushings used in general machinery. DMG Mori leverages its control over advanced CNC turning centers to dominate high-mix, low-volume aerospace contracts. Hardy's Precision Engineering anchors its position in the UK through specialized Swiss machining for medical and defense applications. INDUSTRUM GROU competes across Central Europe by sustaining long-term supply relationships with German automotive Tier-1 suppliers.
Metal precision turned products are cylindrical components produced through subtractive machining processes that achieve tight dimensional tolerances, typically within ±0.005 mm, serving as critical joining, spacing, or load-bearing elements in assembled systems. CNC turning generates the majority of European volume, though Swiss machining commands premium pricing for medical and aerospace applications where concentricity below 0.002 mm is mandatory. Aluminum and titanium material segments are expanding fastest as automotive lightweighting and aircraft build rates rise, while brass retains mature, stable demand in plumbing and electrical fittings. The technology split reveals margin pools concentrated in Swiss machining and multi-axis CNC turning, with manual turning relegated to prototype and repair work.
REACH and the EU Green Deal are tightening material provenance requirements, compelling manufacturers to document carbon intensity across steel and aluminum supply chains. ECHA chemical restrictions and CE marking under the Machinery Directive shape product standards for exported components. The EU F-Gas Regulation indirectly affects cooling systems in machining facilities, raising operational compliance costs. Stakeholders must monitor how the EU AI Act and proposed digital product passports reshape traceability obligations for precision components entering regulated end-use sectors.
Market Dynamics
REACH compliance and the EU Green Deal are forcing European precision turned product manufacturers to requalify entire steel and aluminum supply chains for carbon intensity documentation, compressing margins while creating certification-based competitive tiers.
Growth Catalysts
- Automotive electrification:German and Italian OEMs are expanding machined aluminum fastener programs for battery enclosures and electric motor housings, pulling volume from traditional internal combustion engine component lines.
- REACH material provenance mandates:ECHA chemical restrictions on hexavalent chromium coatings are accelerating adoption of zinc-nickel and trivalent chrome alternatives across aerospace and medical device supply chains.
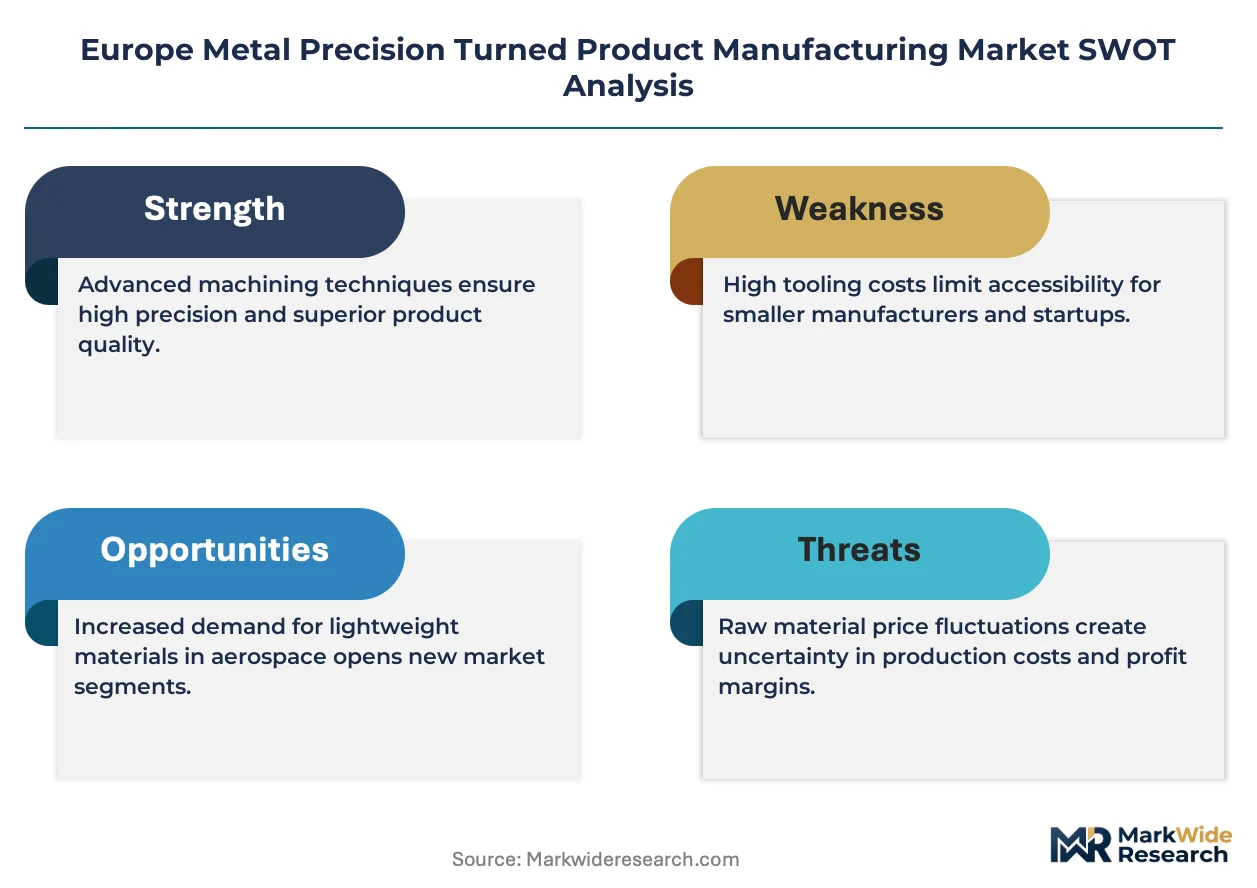
- Swiss machining technology:Concentricity capabilities below 0.002 mm are unlocking premium medical implant contracts from Swiss and German orthopedic device manufacturers.
Market Restraints
- Scrap aluminum price volatility:LME aluminum fluctuations above 15% quarterly swings are compressing hedging margins for high-volume commodity bushing producers serving general machinery.
- CNC turning capacity concentration:Poland and the Czech Republic now host 40% of new European machine tool installations, creating geographic dependency risk for just-in-time automotive supply chains.
- Titanium substitution ceiling:Inconel 718 retains dominant share in jet engine hot sections above 650°C, limiting titanium fastener penetration in next-generation narrowbody programs.
Strategic Opportunities
- Romania and Bulgaria manufacturing zones:Untapped Swiss machining expertise in Cluj-Napoca and Sofia is attracting German medical device OEMs seeking CE-marked component sources outside established Western European cost bases.
- Digital product passport alignment:The EU AI Act traceability requirements are creating first-mover advantage for manufacturers with blockchain-enabled batch documentation systems.
- Hybrid CNC-Swiss cell configurations:Multi-axis turning centers with live tooling are converging with traditional Swiss sliding-headstock platforms, enabling single-setup production of complex medical instrument shafts.
Industry Challenges
- CNC programming talent scarcity:CAM software proficiency for 5-axis simultaneous turning-milling operations is concentrating among Polish and German technical institutes, leaving Southern European facilities dependent on contractor support.
- MDR recertification timelines:Medical device component suppliers face 18-24 month validation cycles for updated biocompatibility documentation under the EU Medical Device Regulation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Metal Precision Turned Product Manufacturing Market |
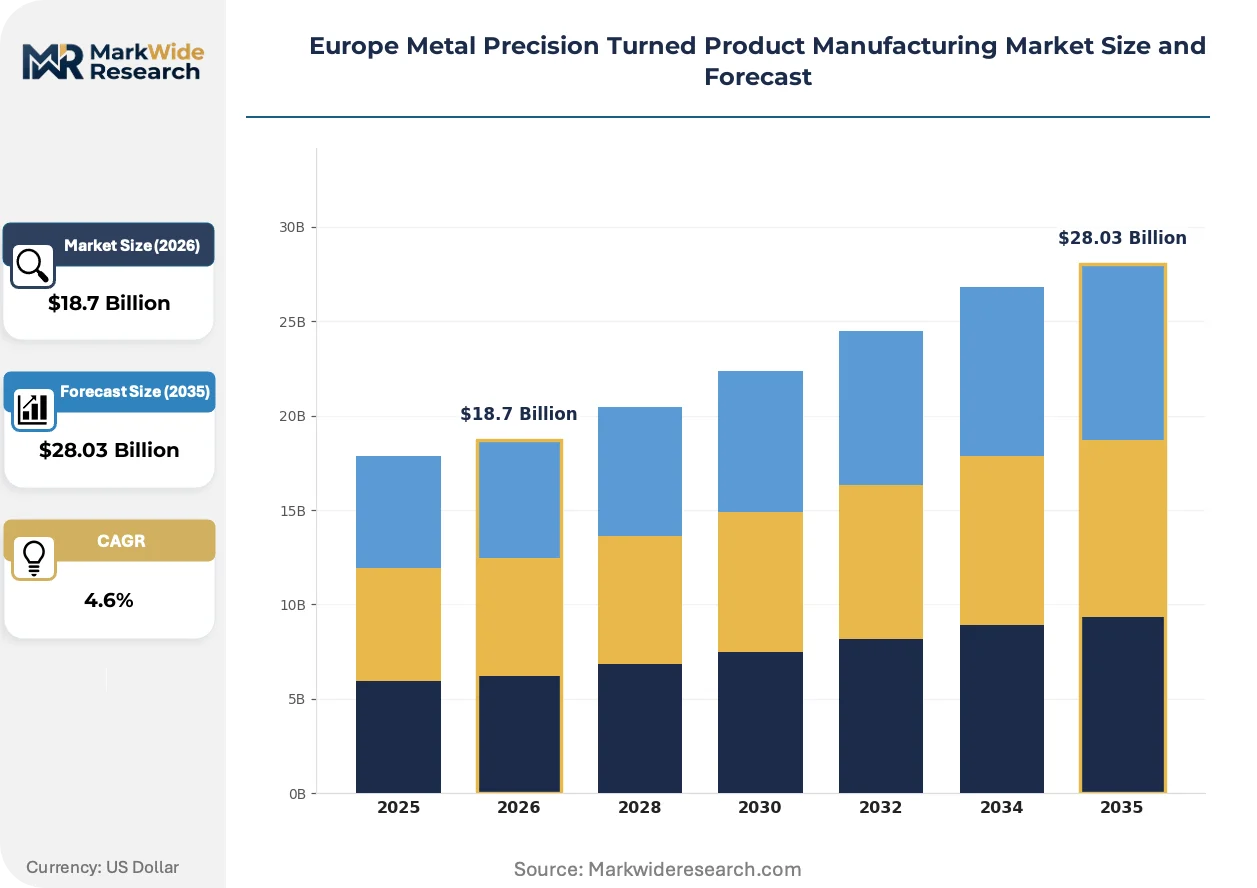
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Screws, Bolts, Fasteners, Bushings End User: Aerospace, Automotive, Electronics, Machinery Material: Aluminum, Steel, Brass, Titanium Technology: CNC Turning, Swiss Machining, 3D Printing, Manual Turning |
| Companies Covered | Bulmac Engineering Ltd, INDUSTRUM GROU, VASCHUK LTD, ELIRI SA, DANI 151 LTD, UAB Kiruna, Hardy's Precision Engineering, Sargasas UA, DMG Mori, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Metal Precision Turned Product Manufacturing Market Trends and Innovations
European precision turned product manufacturing is bifurcating between automated high-mix cells for aerospace and medical applications and commodity carbon-steel volume production under severe energy cost pressure.
Multi-axis CNC turning centers with integrated robotic part handling are decentralizing production economics for complex aerospace fasteners. Tier-1 suppliers in Toulouse and Hamburg are adopting these cells for lot sizes below 500 units, compressing traditional batch-and-queue lead times from six weeks to 72 hours. This capability is decentralizing sourcing decisions from centralized commodity purchasing to program-specific engineering teams.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants in machining facility cooling systems, raising capital requirements for coolant temperature control upgrades. German and Austrian precision shops are retrofitting magnetic bearing chillers and closed-loop heat recovery systems to maintain ±0.5°C thermal stability for tight-tolerance titanium work. Aerospace fastener manufacturers in Baden-Württemberg report 12-15% operational cost increases from compliance-driven equipment replacement cycles.
Consolidation among German automotive Tier-1 suppliers is compressing supplier qualification cycles and unbundling after-sales technical support from component pricing. Procurement teams at Stuttgart and Munich headquarters now mandate digital twin compatibility for all new turned product qualifications, favoring suppliers with native CAD/CAM data exchange capabilities. This behavioral shift is most visible in powertrain electrification programs where aluminum bushing designs iterate monthly rather than annually.
Europe Metal Precision Turned Product Manufacturing Market Segmentation
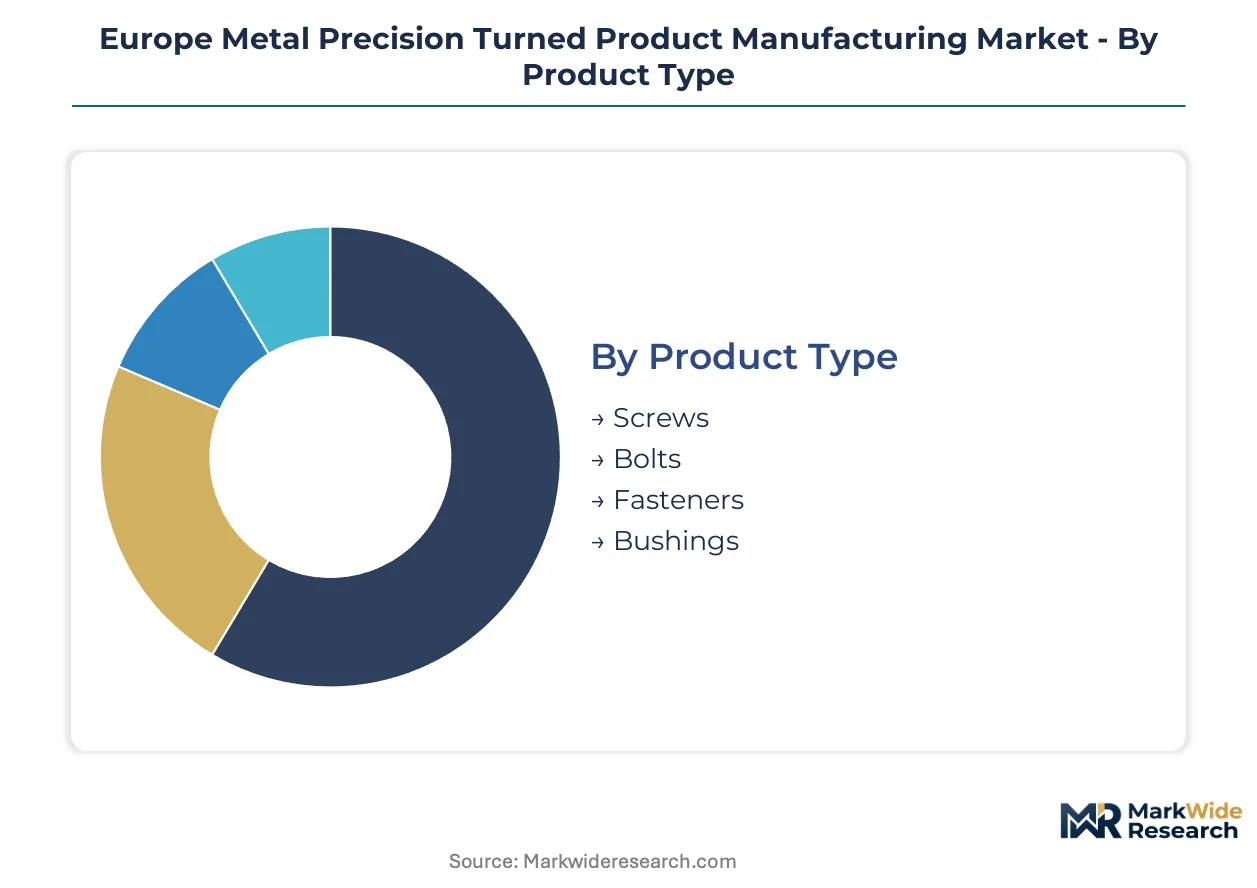
Segmentation in European precision turned products reveals how capital deployment, regulatory exposure, and end-use criticality split manufacturing economics. Each dimension—product geometry, customer industry, material grade, and production technology—carries distinct margin profiles and compliance burdens that reshape competitive positioning across the continent.
Product Type:
Capital intensity escalates with geometric complexity and tolerance stringency, separating commodity hardware from aerospace-grade threaded components.
- Screws:Thread-rolling and precision grinding equipment for aerospace socket-head cap screws demands seven-figure capital outlays per production line. German automotive electrification programs are pulling high-tensile aluminum screw volumes away from traditional carbon-steel chassis applications.
- Bolts:Heavy hex structural bolts for wind turbine tower assemblies require 1,000-ton forging presses followed by CNC finishing, creating barriers to entry for smaller Central European shops. Norwegian and Scottish offshore wind installations are absorbing increasing shares of corrosion-resistant super-duplex stainless bolt output.
- Fasteners:Self-locking aerospace fasteners with integrated prevailing torque features command premium pricing through proprietary thread-forming patents held by established French and Italian suppliers.
- Bushings:Cylindrical spacers for general machinery represent the most price-competitive segment, with Polish producers leveraging volume scale to serve German agricultural equipment OEMs.
Bushings absorb the bulk of installed capacity; screws are expanding most quickly.
End User:
Customer concentration and qualification cycles segment the market into long-cycle certified supply chains versus spot-market commodity demand.
- Aerospace:Nadcap accreditation and OEM-specific process approvals lock suppliers into decade-long relationships with Airbus and Safran. Titanium fastener demand from Toulouse and Hamburg final assembly lines is climbing with narrowbody production rates.
- Automotive:Battery enclosure machining programs at Stuttgart and Munich headquarters now specify aluminum bushing geometries that iterate monthly, compressing supplier engineering response times.
- Electronics:Miniature brass connectors for telecommunications infrastructure face pricing pressure from Asian competition, limiting European producer participation.
- Machinery:General industrial equipment manufacturers in Northern Italy and Baden-Württemberg source carbon-steel spacers through distributor networks with minimal technical qualification.
Automotive pulls the greatest absolute volume; aerospace delivers the steepest expansion trajectory in value terms.
Material:
Raw material cost volatility and carbon-intensity documentation requirements are re-tiering supplier economics across the European supply base.
- Aluminum:6xxx and 7xxx series alloys for electric vehicle battery trays require solution heat treatment and artificial aging, adding process steps that favor integrated producers. REACH-mandated carbon footprint declarations are favoring smelters with verified renewable energy sourcing in Iceland and Norway.
- Titanium:Ti-6Al-4V bar stock for medical implants and airframe fasteners carries material costs tenfold above carbon steel, concentrating demand among Swiss and German orthopedic device manufacturers with concentricity requirements below 0.002 mm.
- Steel:Low-carbon steel grades compliant with EU Green Deal benchmarks are gaining share in automotive applications, displacing conventional grades without verified emissions documentation.
- Brass:Lead-free brass variants for plumbing fittings face stable but mature demand from building renovation programs across France and Benelux markets.
Steel dominates installed machine hours; aluminum is climbing fastest amid electrification programs.
Technology:
Equipment sophistication and labor skill requirements stratify production economics from commodity volume to precision premium.
- CNC Turning:Multi-axis turning centers with live tooling represent the largest installed base, with Polish and Czech facilities hosting 40% of new European machine tool investments. These platforms handle complex aerospace fastener geometries in lot sizes below 500 units.
- Swiss Machining:Sliding-headstock lathes with guide bushings achieve the concentricity and surface finish required for medical implant shafts and miniature aerospace components. Cluj-Napoca and Sofia are emerging as lower-cost locations for CE-marked Swiss machining outside Western European wage structures.
- 3D Printing:Directed energy deposition for titanium aerospace brackets is displacing some forged-and-machined geometries, though turned features remain necessary for threaded interfaces and precision bores.
- Manual Turning:Prototype and repair work persists in job shops across Northern Italy and the UK, though volumes are negligible in commercial production.
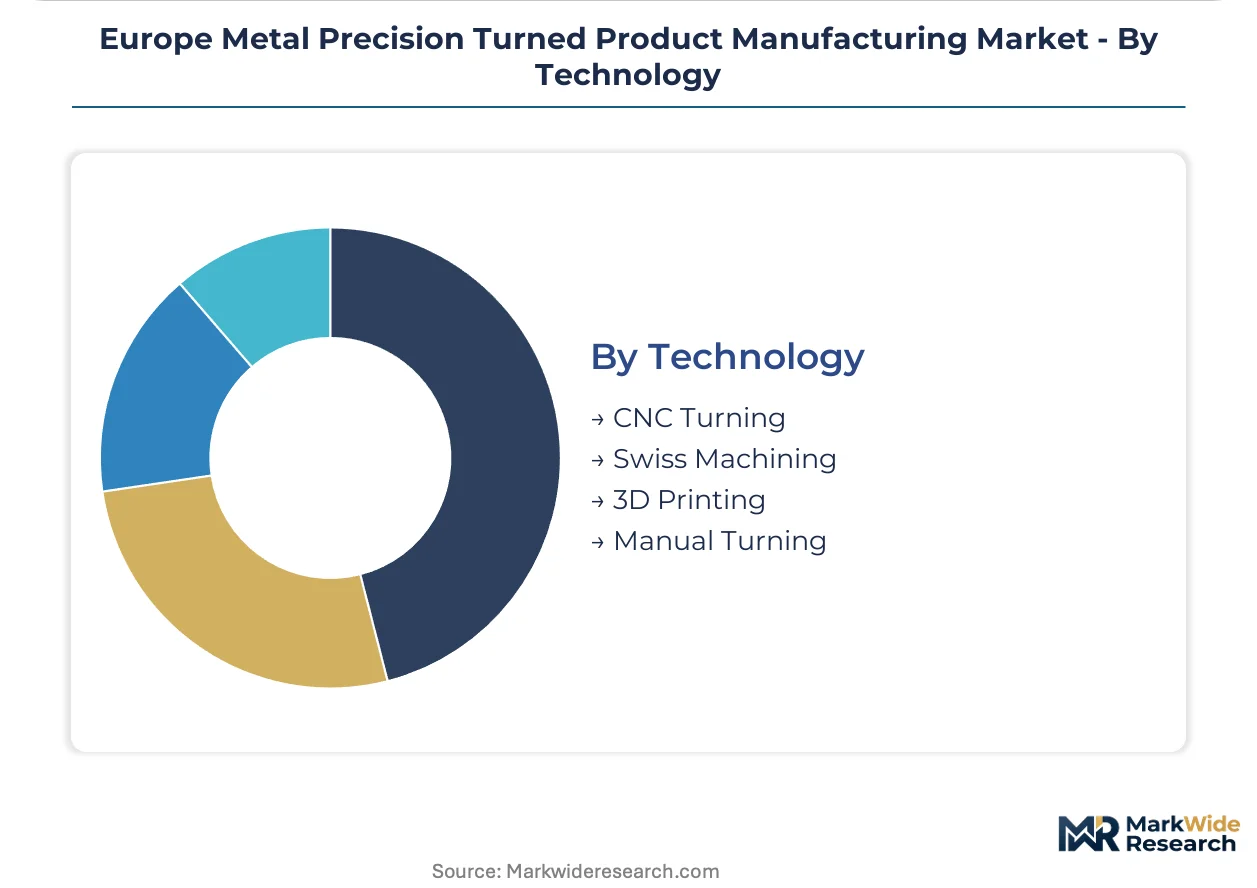
CNC Turning commands the majority of spindle hours; Swiss Machining is gaining share fastest in value-added medical and aerospace contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Baden-Württemberg's precision engineering corridor anchors European metal turned product manufacturing, with Stuttgart and surrounding industrial zones hosting dense concentrations of automotive and aerospace tier-1 suppliers.
Germany
Automotive electrification programs at Stuttgart and Munich headquarters are pulling aluminum fastener volumes toward battery enclosure applications. REACH compliance mandates from ECHA are forcing requalification of steel supply chains for carbon intensity documentation. DMG Mori's advanced CNC turning center installations in Bielefeld and Pfronten dominate high-mix aerospace contract manufacturing.
Poland
Cost-competitive CNC turning capacity is concentrating around Wrocław and Katowice, serving German automotive just-in-time supply chains. The EU Green Deal's low-carbon steel benchmarks are compelling foundry upgrades in Silesian manufacturing zones. Swiss machining expertise is emerging in Kraków's technical university corridor, attracting medical device OEMs from Switzerland.
United Kingdom
Defense and medical device demand anchors precision turned product output across the Midlands and Southern England. The EU AI Act's traceability requirements are reshaping export documentation for components bound for continental European aerospace programs. Hardy's Precision Engineering exemplifies specialized Swiss machining capability for orthopedic implant contracts.
Italy
Electrification-driven aluminum machining programs are expanding at Turin and Milan-area automotive suppliers. CE marking under the Machinery Directive shapes product standards for precision components exported to German machinery OEMs. Northern Italian job shops in Emilia-Romagna retain manual turning capacity for prototype and repair work.
Czech Republic
Central European CNC turning investments are clustering around Brno and Ostrava, capturing automotive supplier migration from Western European cost bases. The F-Gas Regulation is driving coolant system retrofits in precision shops, raising operational compliance costs. INDUSTRUM GROU maintains long-term supply relationships with German automotive tier-1 suppliers from its regional base.
Europe Metal Precision Turned Product Manufacturing Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology sophistication and certification tiers, with Swiss machining specialists commanding pricing multiples over standard CNC turning houses. The vendor base stratifies between aerospace-accredited Nadcap suppliers, automotive-qualified volume producers, and medical device CE-marked specialists. Three archetypes dominate: integrated multi-axis CNC houses with robotic cells, Swiss machining specialists for medical concentricity requirements, and commodity carbon-steel volume producers serving agricultural machinery. Competitive moves concentrate on hybrid CNC-Swiss cell configurations and blockchain-enabled batch documentation for digital product passport alignment.
Among UK-based precision engineering specialists, Hardy's Precision Engineering occupies a position within the medical-defense Swiss machining tier. German-Japanese capital equipment dominance is represented by DMG Mori, which anchors the high-mix aerospace contract segment through control over advanced turning center technology. INDUSTRUM GROU exemplifies the Central European automotive supplier archetype, sustaining long-term tier-1 relationships across German electrification programs.
| Leading Market Players |
|---|
| Bulmac Engineering Ltd |
| INDUSTRUM GROU |
| VASCHUK LTD |
| ELIRI SA |
| DANI 151 LTD |
| UAB Kiruna |
| Hardy's Precision Engineering |
| Sargasas UA |
| DMG Mori |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal carbon-intensity benchmarks gate qualified supply access and premium-tier pricing power across European precision turned product manufacturing, forcing buyers to pay certification premiums for documented low-carbon steel grades while excluding non-compliant suppliers from automotive electrification contracts.
Pricing Analysis
Outcome-based pricing anchored to defect-free production runs dominates Swiss machining contracts for medical implants, where concentricity guarantees below 0.002 mm command multiples over standard CNC turning. Three-tier pricing structure across Nadcap-accredited aerospace, automotive-qualified volume, and CE-marked medical tiers reflects certification investment recovery. Cost compression in commodity carbon-steel bushings intensifies because Polish volume producers leverage scale economies. German automotive OEMs exhibit lowest price sensitivity for aluminum fastener programs with monthly design iterations, while general machinery distributors remain highly sensitive.
Supply Chain Analysis
Scrap aluminum return flows and titanium bar stock remelting programs in Baden-Württemberg precision shops reduce virgin material costs by 8-12% for qualified suppliers. Raw material sourcing draws from Icelandic renewable-energy aluminum smelters, Ukrainian titanium sponge processors, and Silesian low-carbon steel foundries. Single-source vulnerability concentrates in Ti-6Al-4V bar stock from a limited German-Swiss supplier base. Distribution runs through German automotive Tier-1 headquarters procurement teams for qualified supply, with spot-market distributor networks serving machinery aftermarket demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European precision turned product manufacturing sits in a technology-transition phase where hybrid CNC-Swiss cell configurations displace legacy batch-and-queue production economics.
For Market Incumbents: Hedge against titanium substitution ceilings in jet engine hot sections by deepening backward integration into heat-treatment and surface-coating capabilities. Secure Nadcap accreditation renewal ahead of Airbus narrowbody production ramp. Capacity addition in Romania and Bulgaria manufacturing zones captures medical device OEM migration from Western European cost bases.
For New Entrants and Emerging Players: Blockchain-enabled batch documentation systems offer a technology-first wedge into digital product passport compliance for EU AI Act traceability mandates. Target Cluj-Napoca and Sofia Swiss machining white space with CE-marked component qualifications for German orthopedic device supply chains. Pursue direct engineering relationships with Stuttgart battery enclosure program teams rather than distributor channels.
For Investors and Strategic Acquirers: German automotive Tier-1 unbundling of after-sales technical support from component pricing is the leading indicator that integrated CAD/CAM data exchange capabilities will command acquisition premiums. Five-to-ten-year viability favors Swiss machining specialists with medical device MDR recertification progress over commodity carbon-steel volume houses. Monitor ECHA chemical restriction expansion timelines for coating substitution inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid CNC-Swiss Cell Deployment | Enables single-setup production of complex medical instrument shafts for German orthopedic OEMs. |
| Blockchain Batch Documentation | Aligns supplier systems with EU AI Act traceability requirements for digital product passports. |
| Backward Integration into Heat Treatment | Captures margin pools from solution aging of 7xxx series aluminum for EV battery trays. |
| CE Marking Pathway Investment | Unlocks medical device contracts from Swiss and German orthopedic manufacturers with MDR compliance. |
| Geographic Manufacturing Footprint Expansion | Positions capacity in Romanian and Bulgarian zones to serve German Tier-1 automotive migration. |
Research Methodology
Trade association filings from VDMA, CEEMET, and Make UK formed the secondary backbone, supplemented by ECHA regulatory databases and EU customs records for aluminum and titanium bar stock flows. Primary interviews with CNC programming directors at Polish technical institutes, procurement leads at Stuttgart automotive headquarters, and regulatory affairs managers at French aerospace Tier-1 suppliers validated capacity and pricing assumptions. Bottom-up machine tool installation counts across Wrocław, Brno, and Katowice production zones were triangulated against top-down end-use demand estimates from automotive electrification programs and narrowbody build rates.
Historical trendline analysis of Swiss machining premium spreads over standard CNC turning informed margin trajectory modeling across the projection horizon. Segmentation dimensions included product geometry complexity, end-use criticality tier, material grade carbon-intensity documentation level, and production technology sophistication. CAGRs were derived from regression analysis of automotive electrification content-per-vehicle trends and medical device implant procedure growth patterns, cross-referenced against machine tool investment cycles in Central European manufacturing zones.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ECHA chemical restriction acceleration or LME aluminum volatility spikes beyond historical bands. Practitioners should monitor German automotive Tier-1 supplier consolidation announcements and MDR recertification backlog durations for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Metals
Dysprosium Market
Specialty Metals
Global Metal Bellows Market
Specialty Metals
Case Hardening Steel Market
Specialty Metals
North America Metal Turned Precision Product Manufacturing Market
Specialty Metals
Global Special Steel Market
Specialty Metals
Precision Stainless Steel Market
Specialty Metals
Specialty Metallic Pigments Market
Specialty Metals
Metal Halide Market
Specialty Metals
Precious Metal Plating Market