
 Clutch Spring Wires Market | 2026-2036
Clutch Spring Wires Market Size, Share, and Industry Trends Forecast 2026-2036
Clutch Spring Wires Market Outlook
Modular spring-and-hub assemblies is consolidating buyer preference across transmission platforms, reducing standalone wire procurement volumes while raising specification thresholds. NHK Spring Co. Ltd. leverages captive heat-treatment capacity to anchor premium supply contracts with Japanese automakers. Suzuki Garphyttan Group sustains European OEM relationships through specialized oil-tempered wire grades. KIS Wire Ltd. competes on cost-adjusted delivery schedules to Tier-1 clutch manufacturers in South Korea.
Clutch spring wires are high-carbon steel or alloy wire forms, typically 1.5–6.0 mm in diameter, cold-coiled and stress-relieved to deliver precise load-deflection characteristics for friction engagement systems. The finished wire must maintain tensile strength above 1800 MPa after forming to survive millions of compression cycles in manual and dual-clutch transmissions. Outer spring configurations dominate current volume owing to their deployment in every multi-plate clutch stack, while stainless steel grades capture expanding share in corrosion-sensitive aerospace auxiliary systems. The raw material stage concentrates margin pressure from volatile alloy surcharges, whereas finished goods prototyping commands premium pricing due to rapid tooling iteration requirements.
Japan's METI sets JIS G 3521 benchmarks for mechanical spring wire, while China's SAMR enforces GB/T 4357 dimensional tolerances that determine market access for imported coil stock. REACH compliance in Europe restricts certain surface coating chemistries, redirecting investment toward physical vapor deposition finishes. Stakeholders must monitor evolving powertrain electrification timelines, as clutch content per vehicle becomes the decisive variable in long-term wire demand planning.
Market Dynamics
Powertrain electrification timelines are compressing clutch spring wire demand planning horizons, forcing suppliers to hedge between internal combustion continuity and hybrid transmission architectures. Material efficiency mandates from Japan's METI and China's SAMR are accelerating cross-section optimization investments ahead of volume certainty.
Growth Catalysts
- High-tensile wire specifications:Automotive OEMs in Asia-Pacific are expanding procurement of advanced spring configurations for dual-clutch transmissions. Load-deflection precision requirements now exceed 1800 MPa tensile thresholds.
- GB/T 4357 dimensional compliance:China's SAMR enforcement of tighter tolerances is filtering import competition and elevating domestic supplier technical capabilities. Market access now hinges on certified coil stock conformity.
- Modular assembly adoption:Transmission platforms are consolidating around integrated spring-and-hub designs. Specification thresholds rise even as standalone wire procurement volumes compress.
Market Restraints
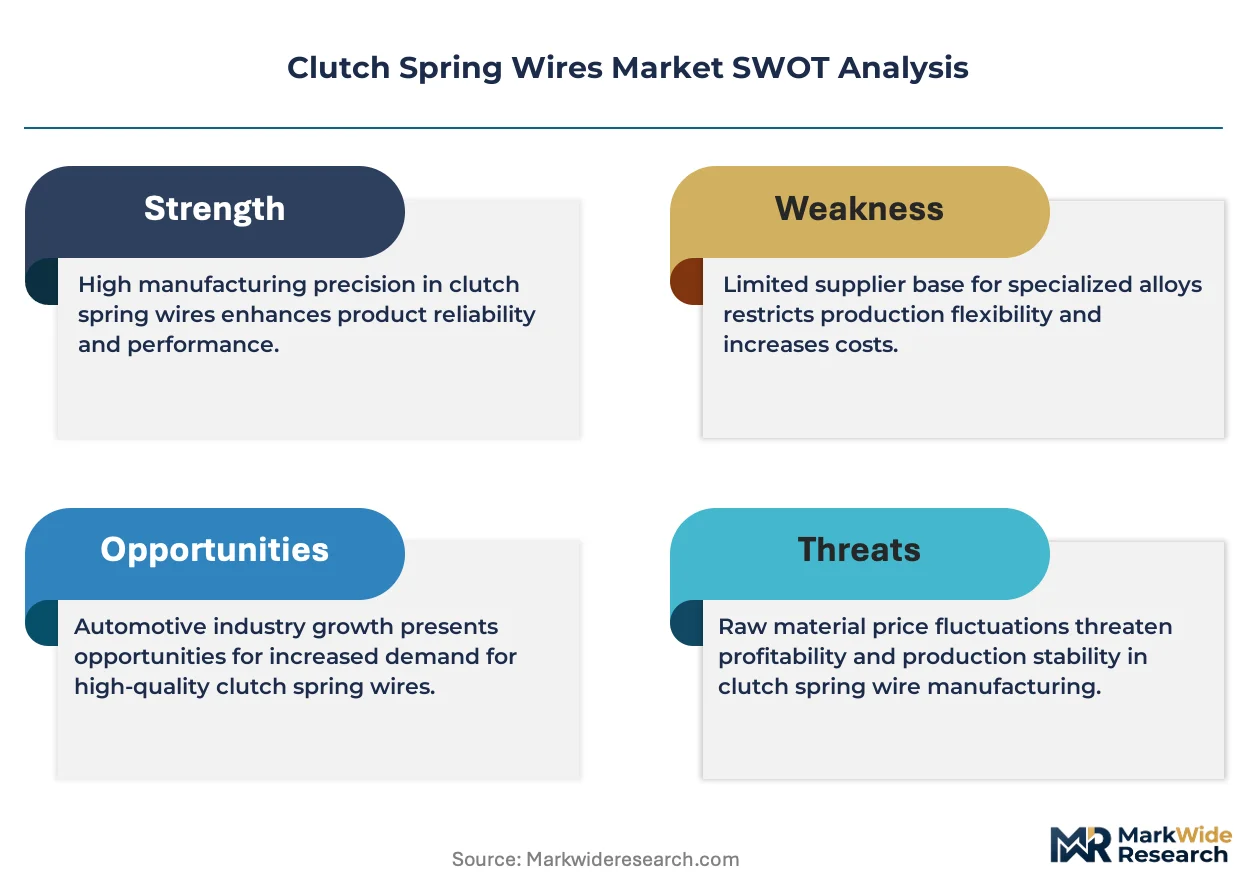
- Alloy surcharge volatility:Raw material stage margins face persistent pressure from nickel and chromium price swings. Finished goods prototyping premiums cannot fully offset input cost instability.
- Supplier concentration risk:Heat-treatment capacity clusters in Japan and Germany create geographic chokepoints. Captive thermal processing assets determine contract access for premium grades.
- Electrification substitution threat:Battery-electric powertrains eliminate multi-plate clutch stacks entirely. Long-term wire demand per vehicle becomes the decisive demand variable.
Strategic Opportunities
- Aerospace auxiliary systems:Stainless steel grades are capturing expanding share in corrosion-sensitive aviation applications. These specifications command 40-60% premiums over automotive grades.
- Physical vapor deposition finishes:REACH restrictions on traditional surface coatings are redirecting investment toward PVD technologies. European OEMs now specify coating chemistry compliance as a procurement gate.
- South Korean clutch manufacturing:Cost-adjusted delivery schedules to Tier-1 suppliers near Seoul and Busan represent underpenetrated volume potential. Regional logistics optimization can displace incumbent supply relationships.
Industry Challenges
- Heat-treatment skill scarcity:Precision tempering of high-carbon alloys requires specialized metallurgical expertise. Workforce gaps constrain capacity expansion at mid-tier suppliers.
- Rapid tooling iteration cycles:OEM prototyping demands compress development timelines to 8-12 weeks. Capital equipment utilization suffers from frequent die changeovers.
- JIS G 3521 certification timelines:Japanese OEM qualification protocols extend 18-24 months for new wire grades. Compliance documentation burdens delay market entry for qualified suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clutch Spring Wires Market |
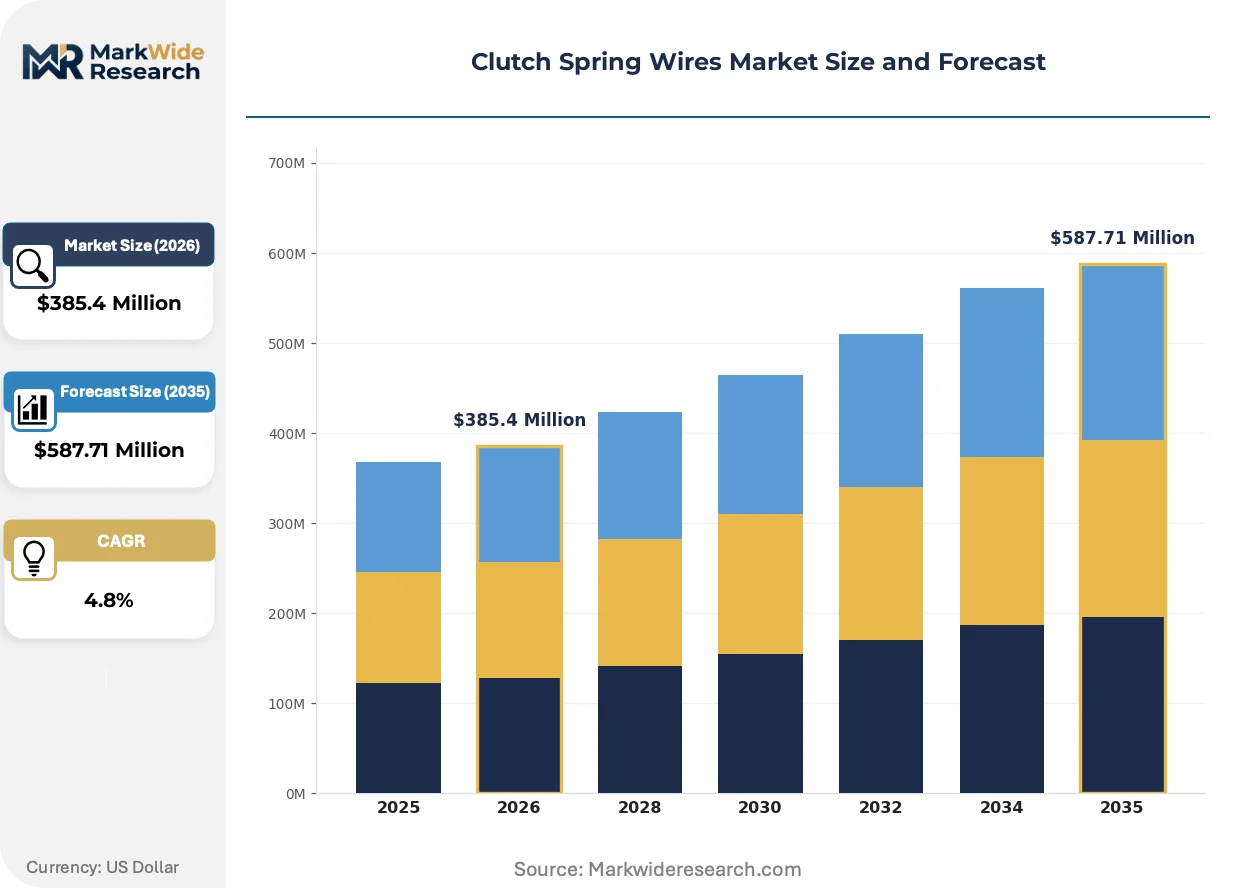
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $587.71 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Outer Spring, Inner Spring, Torsion Spring, Compression Spring Material: Steel, Brass, Stainless Steel, Alloy End User: Automotive, Aerospace, Industrial Equipment, Consumer Electronics Manufacturing Stage: Raw Material, Semi-Finished, Finished Goods, Prototyping |
| Companies Covered | NHK Spring Co. Ltd., Suzuki Garphyttan Group, KIS Wire Ltd., Sumitomo Electric Industries, JFE Steel Corporation, ArcelorMittal, Thyssenkrupp AG, POSCO, Nippon Steel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clutch Spring Wires Market Strategic Shifts
Wire forming technologies and surface treatment methods are converging to meet load precision requirements while eliminating environmentally restricted chemistries. Process innovation now determines competitive position as much as material specification.
Multi-stage stress-relief ovens with programmable thermal profiles are absorbing variability in cold-coiled wire mechanical properties. Japanese transmission suppliers are adopting these systems at replacement cycle points. The technology is absorbing quality assurance labor costs while compressing rejection rates for outer spring configurations.
REACH restrictions on hexavalent chromium surface coatings are redirecting European supplier investment toward physical vapor deposition and plasma electrolytic oxidation finishes. ECHA enforcement timelines are accelerating qualification of alternative chemistries ahead of sunset dates. Aerospace auxiliary system suppliers in Germany and France are most affected, with PVD specifications now written into procurement tenders.
Consolidated spring-and-hub procurement contracts are displacing standalone wire purchasing across manual and dual-clutch transmission platforms. Tier-1 clutch assemblers near Shanghai and Stuttgart are bundling component sourcing to reduce supplier management overhead. This pattern is most visible in China's eastern manufacturing corridor, where Ningbo-based assemblers now specify modular assembly deliverables rather than raw coil stock.
Clutch Spring Wires Market Segmentation
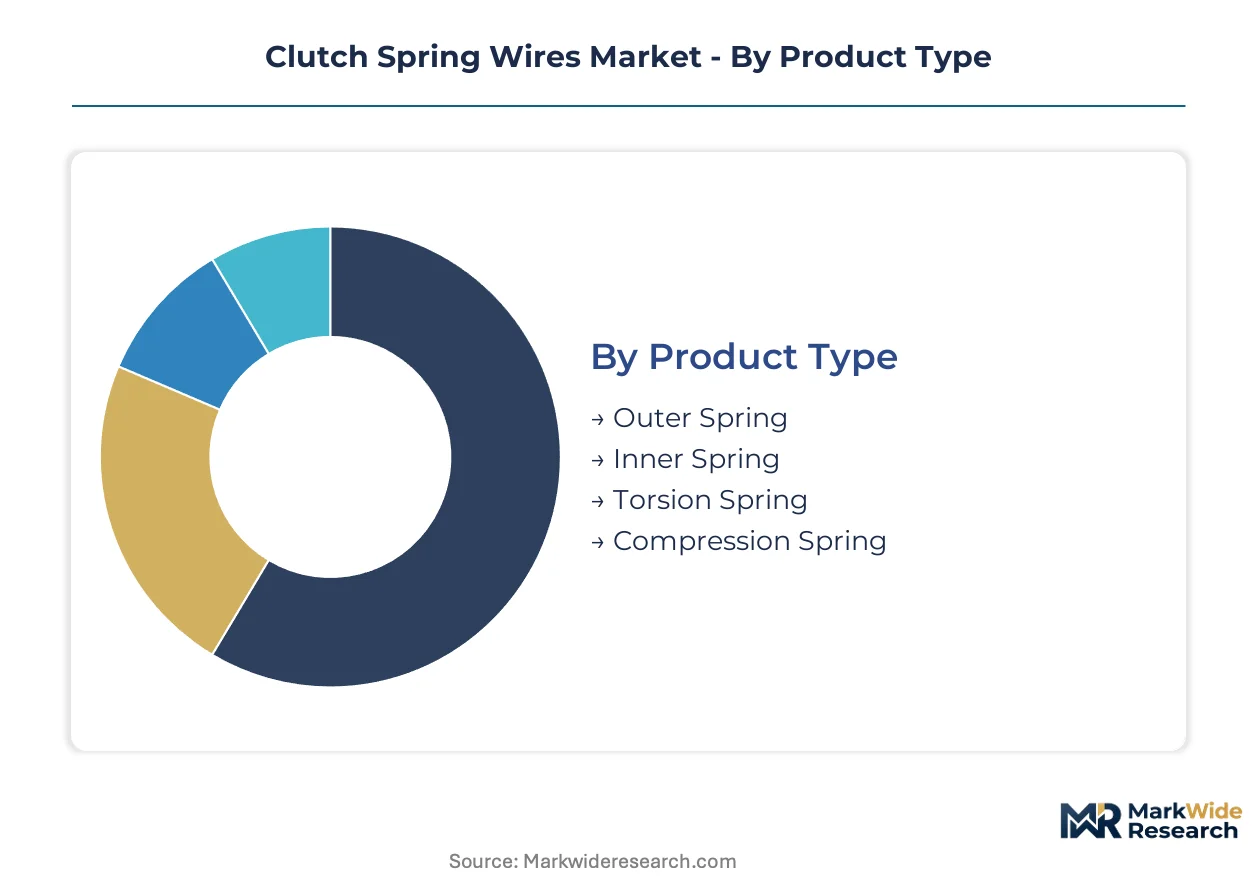
Segmentation in clutch spring wires reveals how specification thresholds diverge across powertrain architectures and corrosion environments. Procurement patterns split between high-volume automotive contracts and premium aerospace auxiliary systems, with material grades and manufacturing stages determining margin capture.
Product Type:
Outer spring configurations command the volume base across manual and dual-clutch transmissions, while inner spring and torsion variants serve specialized engagement geometries.
- Outer Spring:These wire forms encircle the clutch pack perimeter, typically 3.0–6.0 mm in diameter, delivering the primary clamp load for friction engagement. Demand concentrates at transmission assemblers near Stuttgart and Shanghai, where NHK Spring and domestic Chinese suppliers compete on JIS G 3521 and GB/T 4357 compliance respectively. Load-deflection precision above 1800 MPa tensile strength separates qualified suppliers from commodity coil stock vendors.
- Inner Spring:Smaller-diameter configurations, generally 1.5–3.5 mm, nest within the clutch hub to manage release bearing travel and pedal feel. Adoption is accelerating in compact dual-clutch modules where space constraints favor nested spring geometries over conventional outer-spring dominance.
- Torsion Spring:These deliver rotational resistance for clutch damper hubs, absorbing driveline torque spikes before transmission input. European OEMs specify torsion springs for longitudinally mounted performance transmissions.
- Compression Spring:Generic cylindrical forms serve auxiliary clutch actuation mechanisms and pedal return functions. Specifications here tolerate wider dimensional tolerances than primary engagement springs.
Mature deployment sits with outer spring configurations across established manual transmission platforms. Newer deployment is concentrated in inner spring geometries for downsized dual-clutch architectures.
Material:
Material selection trades tensile performance against corrosion resistance, with alloy surcharges and REACH coating restrictions redirecting procurement toward stainless alternatives.
- Steel:High-carbon grades per JIS G 3521 and GB/T 4357 dominate automotive volume, with oil-tempered wire from Suzuki Garphyttan Group anchoring European OEM relationships. Nickel and chromium price volatility compresses raw material stage margins regardless of finished goods prototyping premiums.
- Stainless Steel:Austenitic and precipitation-hardening grades capture aerospace auxiliary systems where salt spray resistance exceeds 1000 hours. German and French aviation suppliers now specify PVD finishes after ECHA restrictions on hexavalent chromium coatings.
- Alloy:Silicon-chrome and vanadium-modified steels push tensile thresholds toward 2000 MPa for racing and heavy-duty commercial clutch applications. Heat-treatment capacity constraints in Japan and Germany limit qualified supply.
- Brass:Limited to low-load electrical contact springs within clutch position sensors, where conductivity outweighs mechanical strength requirements.
Steel grades anchor mass-market automotive procurement. Stainless steel grades are expanding most quickly in corrosion-sensitive aviation and marine auxiliary systems.
End User:
End-use concentration determines specification stringency, with automotive OEMs driving standardization while aerospace and industrial buyers tolerate longer qualification cycles.
- Automotive:Manual and dual-clutch transmission assemblers in China's eastern manufacturing corridor—clustering near Shanghai and Ningbo—represent the demand core. METI-enforced material efficiency standards and SAMR dimensional compliance filter import competition.
- Aerospace:Auxiliary power unit and flight control system suppliers specify stainless grades with 40–60% pricing premiums over automotive equivalents. REACH-driven coating chemistry shifts affect German and French procurement most directly.
- Industrial Equipment:Forklift and agricultural machinery clutches tolerate wider load-deflection tolerances than automotive grades, with replacement part demand cycling independently of OEM production schedules.
- Consumer Electronics:Miniature compression springs for haptic feedback mechanisms represent negligible volume but extreme precision requirements at sub-millimeter wire diameters.
Automotive platforms concentrate mature wire demand across established transmission architectures. Aerospace auxiliary systems are gaining share fastest as electrification compresses clutch content per passenger vehicle.
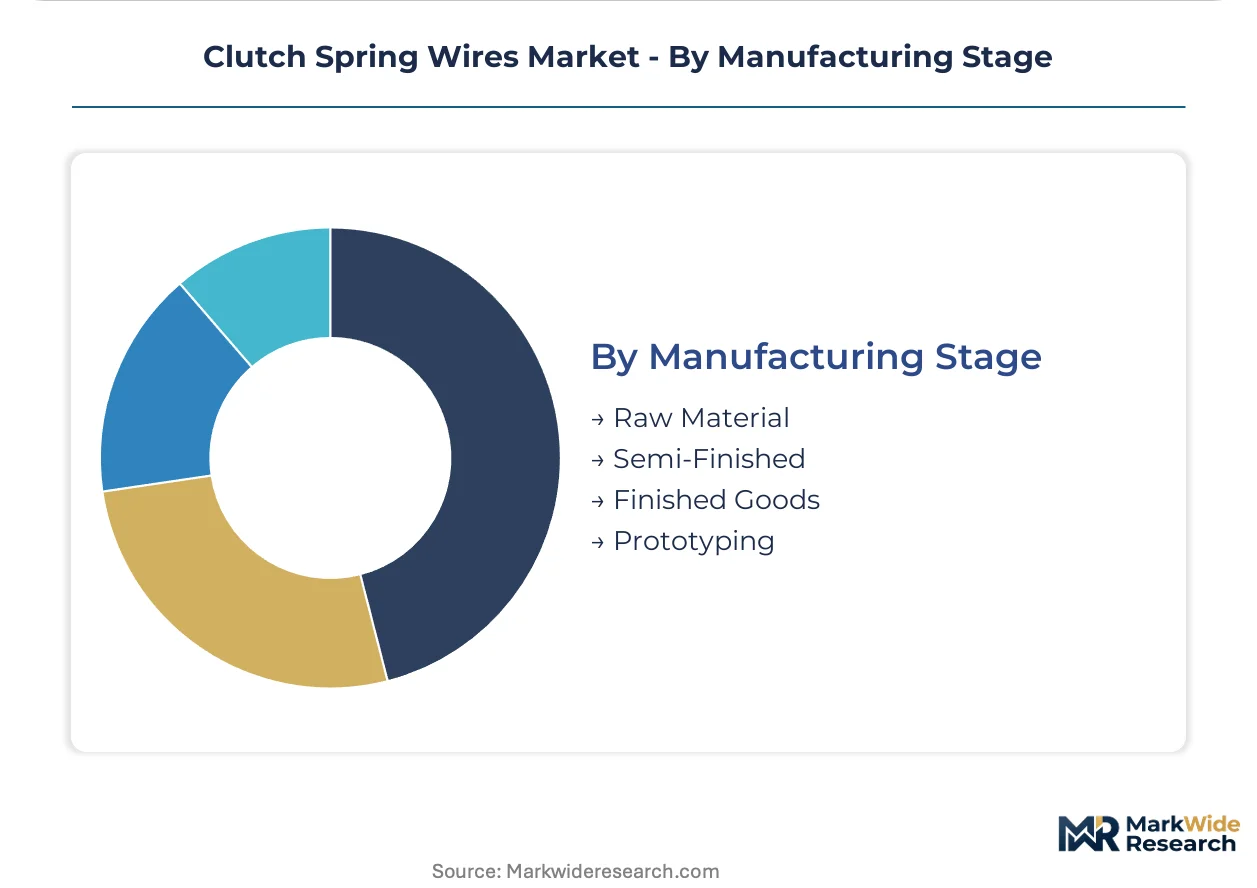
Manufacturing Stage:
Stage of manufacture determines margin capture, with raw material suppliers absorbing alloy surcharge volatility while prototyping commands premium pricing for rapid tooling iteration.
- Raw Material:Rod and coil stock producers face persistent margin pressure from nickel and chromium price swings. Captive heat-treatment capacity at tier-integrated suppliers such as NHK Spring insulates against this volatility.
- Semi-Finished:Stress-relieved and shot-peaned wire ready for final coiling offers intermediate value capture. South Korean suppliers near Seoul and Busan compete on cost-adjusted delivery schedules to displace incumbent relationships.
- Finished Goods:Cold-coiled and preset springs delivered to clutch assembly plants command specification premiums, with JIS G 3521 certification timelines extending 18–24 months for new grades.
- Prototyping:Rapid tooling iteration for new transmission platforms compresses development cycles to 8–12 weeks, with die changeover frequency degrading capital equipment utilization.
Finished goods procurement dominates established transmission programs. Prototyping services are climbing the fastest as powertrain electrification timelines force compressed development horizons.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan and Germany concentrate production of heat-treated coil stock, while China absorbs the largest share of finished clutch assembly demand. This geographic split shapes procurement patterns and regulatory compliance burdens across the value chain.
China
Transmission assemblers near Shanghai and Ningbo drive demand for GB/T 4357 compliant wire grades. SAMR dimensional tolerance enforcement filters import competition and elevates domestic supplier technical capabilities. The eastern manufacturing corridor clusters clutch assembly plants within 200 kilometers of port infrastructure, compressing logistics costs for coil stock delivery.
Japan
METI-enforced material efficiency standards accelerate cross-section optimization investments at wire producers. JIS G 3521 certification timelines extend 18–24 months for new grades, creating qualification barriers for foreign suppliers. Heat-treatment capacity concentrates in the Chubu region around Nagoya, anchoring premium supply relationships with domestic automakers.
Germany
European OEMs specify REACH-compliant surface coatings for clutch spring wire, redirecting supplier investment toward PVD finishes. ECHA restrictions on hexavalent chromium chemistries affect procurement tenders from Stuttgart-based transmission assemblers. The Baden-Württemberg industrial corridor hosts specialized oil-tempered wire production for performance vehicle applications.
South Korea
Tier-1 clutch manufacturers near Seoul and Busan compete on cost-adjusted delivery schedules to displace incumbent Japanese supply relationships. MFDS oversight of industrial materials standards shapes import documentation requirements. The Busan-Ulsan manufacturing belt concentrates automotive component production within integrated supplier parks.
United States
EPA industrial emissions standards affect heat-treatment facility permitting for wire producers in the Midwest automotive belt. NHTSA fuel economy regulations indirectly influence clutch content per vehicle in manual transmission platforms. Michigan and Ohio-based transmission plants source semi-finished wire from domestic rod mills with captive thermal processing assets.
Clutch Spring Wires Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the clutch spring wire value chain. The market structure tiers between integrated steel producers with captive wire drawing capacity and independent coil stock specialists serving niche specification requirements. Two dominant strategic archetypes emerge: metallurgical innovators optimizing alloy compositions for tensile performance, and logistics-integrated suppliers compressing delivery cycles through regional warehouse networks. Capacity expansion and certification pre-qualification represent the primary competitive moves as electrification compresses demand planning horizons.
Among Japanese suppliers, NHK Spring Co. Ltd. and Suzuki Garphyttan Group exemplify divergent positioning archetypes. NHK Spring occupies a position within the integrated component systems tier, while Suzuki Garphyttan represents the specialized wire grade segment. South Korea's KIS Wire Ltd. anchors the cost-optimized logistics tier serving regional clutch assemblers. These three entities collectively illustrate how geographic concentration, captive heat-treatment assets, and certification depth determine contract access across premium and volume market segments.
| Leading Market Players |
|---|
| NHK Spring Co. Ltd. |
| Suzuki Garphyttan Group |
| KIS Wire Ltd. |
| Sumitomo Electric Industries |
| JFE Steel Corporation |
| ArcelorMittal |
| Thyssenkrupp AG |
| POSCO |
| Nippon Steel Corporation |
| Others |
Value Chain & Pricing Dynamics
Captive heat-treatment capacity at tier-integrated suppliers anchors both supply security and premium pricing power in clutch spring wire procurement. Japanese and German producers with in-house thermal processing assets command 15-20% pricing premiums over coil stock vendors exposed to volatile nickel and chromium alloy surcharges.
Pricing Analysis
Margin tightening in raw material supply reflects persistent nickel and chromium price volatility that coil stock producers cannot pass through fully. Contract-based long-term offtake agreements dominate automotive procurement, with JIS G 3521 and GB/T 4357 certification tiers separating premium-qualified suppliers from commodity vendors. Price differentiation hinges on heat-treatment certification depth and geographic delivery reliability, with South Korean clutch assemblers showing highest price sensitivity and aerospace auxiliary buyers least sensitive.
Supply Chain Analysis
High-carbon steel rod supply rests on integrated steel producers in Japan, Germany, and China with captive wire drawing capacity. Critical inputs include nickel-alloyed spring steel grades, oil-tempering quench oils, and REACH-compliant surface coating chemistries. Single-source vulnerability concentrates in heat-treatment furnace capacity around Nagoya and Stuttgart. Distribution runs through regional coil stock warehouses serving transmission assembly clusters near Shanghai, Stuttgart, and Seoul.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clutch spring wire procurement functions as a cost-of-compliance market where Japan's METI material efficiency standards and China's SAMR dimensional tolerances erect 18-24 month qualification barriers that protect incumbent positions.
For Market Incumbents: Acquire distressed heat-treatment assets in South Korea to preempt regional competitors from building captive thermal processing capacity. Deepen backward integration into specialty alloy rod supply to insulate margins from nickel surcharge volatility. Electrification substitution threats demand accelerated diversification into aerospace stainless grades.
For New Entrants and Emerging Players: Enter via modular spring-and-hub assembly contracts rather than standalone coil stock supply to bypass JIS G 3521 certification timelines. Target South Korean Tier-1 clutch manufacturers near Busan with cost-adjusted delivery schedules displacing Japanese incumbents. Lead with physical vapor deposition coating capabilities to capture REACH-driven specification shifts in European procurement.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified steel conglomerates seeking transmission component exposure. Long-term viability hinges on powertrain electrification timelines compressing clutch content per vehicle. Watch dual-clutch transmission platform longevity at German and Chinese OEMs as the critical demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Treatment Capacity Expansion | Captive thermal processing assets in Chubu region anchor premium supply contracts with Japanese automakers. |
| Backward Integration into Rod Supply | In-house production of high-carbon steel coil stock insulates margins from nickel and chromium surcharge volatility. |
| Physical Vapor Deposition Certification | REACH-compliant PVD finishes open procurement tenders from Stuttgart-based transmission assemblers. |
| Regional Logistics Hub Establishment | Warehouse networks near Shanghai and Ningbo compress delivery cycles for eastern manufacturing corridor clutch plants. |
| Aerospace Grade Qualification | Stainless steel grades with salt spray resistance above 1000 hours capture 40-60% pricing premiums over automotive specifications. |
Study Parameters
Trade association filings, customs import records, and SEC 10-K disclosures formed the secondary backbone for market sizing and competitive positioning assessment. Primary interviews with Tier-1 clutch procurement managers, heat-treatment plant engineers, and transmission platform directors combined with secondary validation through JIS G 3521 certification databases and SAMR compliance registries. Bottom-up coil stock volume estimates triangulated against top-down transmission production forecasts.
Historical trendline analysis of wire diameter specifications and tensile strength thresholds informed projection modeling across the analysis window. Segmentation dimensions included spring configuration type, material grade tier, manufacturing stage, and end-use industry cluster. CAGRs derived from powertrain electrification scenario weighting against dual-clutch transmission platform longevity assumptions. Forecast inputs incorporated METI material efficiency standard enforcement timelines and ECHA coating chemistry restriction sunset dates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated battery-electric vehicle adoption or extended internal combustion platform longevity. Assumptions reflect documented powertrain transition roadmaps from major OEMs and regulatory agency filing patterns. Electrification substitution rates, alloy surcharge volatility, and heat-treatment capacity expansion decisions warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Aluminum Powders Pastes and Flakes Market
Metals
Global Chromium Market
Metals
Gold Smelting Market
Metals
Aluminum Sheet Market
Metals
Cold Drawn Wire Market
Metals
Metallic Rope Cords Market
Metals
Steel Sheet for Home Appliances Market
Metals
Ferrosilicon Magnesium Market
Metals
Stainless Steel Round Bar Market
Metals
Aluminum Welding Market
Metals
Merchant Bar Quality (MBQ) Steel Market
Metals
Galvanized Steel Coil Market
Metals
Global Copper Market
Metals
Electrodeposited Copper Foil Market
Metals
Global Galvanized Steel Wire Market
Metals
Zinc Ingots Market