
 Heat-Treated Steel Plates Market | 2026-2036
Heat-Treated Steel Plates Market Size, Share, and Industry Trends Forecast 2026-2036
Heat-Treated Steel Plates Market Intelligence
High-strength aluminum-lithium alloys in aircraft fuselage applications is broadening the performance benchmark that heat-treated steel plates must meet in adjacent heavy industries. ArcelorMittal leverages integrated blast furnace-to-heat-treatment routes across European sites to sustain margin capture on quenched and tempered grades. POSCO anchors Asia-Pacific supply security through captive steelmaking and dedicated heat-treatment lines in Pohang. SSAB competes on premium wear-resistant and armor plate outputs from its Oxelösund and Mobile operations.
Heat-treated steel plates are carbon or alloy steel flats subjected to controlled thermal cycles—quenching, tempering, or annealing—to achieve specified hardness, tensile strength, and toughness values, typically ranging from 500 MPa to over 1,100 MPa yield strength depending on grade and end-use. These plates serve critical load-bearing, wear-resistant, and safety-critical functions across infrastructure, energy, transportation, and defense equipment. Quenched and tempered plates command the dominant value share due to their superior strength-to-weight ratios in structural components and machinery. Alloy steel plates represent the fastest-expanding category as nickel, chromium, and molybdenum additions enable performance in extreme temperature and corrosive environments. Annealed plates remain a mature, volume-driven segment where margin pools are thinner and procurement logic centers on consistent mechanical properties for downstream forming.
China's SAMR enforces GB standards on steel plate mechanical properties and chemical composition, while the EU F-Gas Regulation and CBAM framework reshape cost structures for imported heat-treated material into European fabrication yards. The US NHTSA and FAA both maintain material qualification protocols that effectively gate market access for non-domestic plate suppliers in automotive and aerospace applications. Buyers and producers must monitor how carbon accounting rules and regional content thresholds evolve before committing to long-term capacity or sourcing configurations.
Market Dynamics
The EU Carbon Border Adjustment Mechanism is restructuring import economics for Asian heat-treated plate producers while offshore wind turbine foundations drive specification upgrades toward higher-strength quenched and tempered grades.
Growth Catalysts
- Offshore wind foundation specifications:Monopile and jacket designs now require yield strengths above 690 MPa, pulling quenched and tempered plate volumes into North Sea and East Asian fabrication yards.
- Defense manufacturing expansion:Armor plate procurement for vehicle hulls and naval vessels is accelerating in Germany, India, and China as military modernization programs advance.
- CBAM implementation:The EU's carbon border levy on embedded emissions is creating competitive openings for low-carbon European producers against conventional import sources.
Market Restraints
- Alloy input cost volatility:Nickel and molybdenum price swings compress margins on high-performance grades where these elements constitute 3-8% of material cost.
- Supply concentration in integrated producers:Captive blast furnace and heat-treatment capacity at ArcelorMittal, POSCO, and Nippon Steel limits merchant market availability for independent fabricators.
- High-strength aluminum-lithium substitution:Aircraft fuselage applications above 500 MPa equivalent are migrating to lighter alloys, capping steel plate penetration in aerospace.
Strategic Opportunities
- India's renewable energy buildout:Solar tracker and wind tower fabrication is concentrating in Gujarat and Tamil Nadu, creating localized demand for structural grades.
- Hydrogen infrastructure deployment:Pressure vessel and pipeline specifications for hydrogen transport require new testing protocols that favor qualified domestic suppliers.
- Digital heat-treatment optimization:Machine learning control of quench rate and tempering curves is reducing energy intensity and mechanical property variance.
Industry Challenges
- Metallurgical technician scarcity:Qualified furnace operators and quality engineers with quench-and-temper expertise are retiring faster than training pipelines replenish.
- Extended certification timelines:NHTSA and FAA material qualification protocols for automotive and aerospace applications stretch 18-36 months, freezing supplier switches.
- Legacy ERP integration with carbon accounting:Mill information systems require overhaul to track embedded emissions for CBAM compliance and customer Scope 3 reporting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heat-Treated Steel Plates Market |
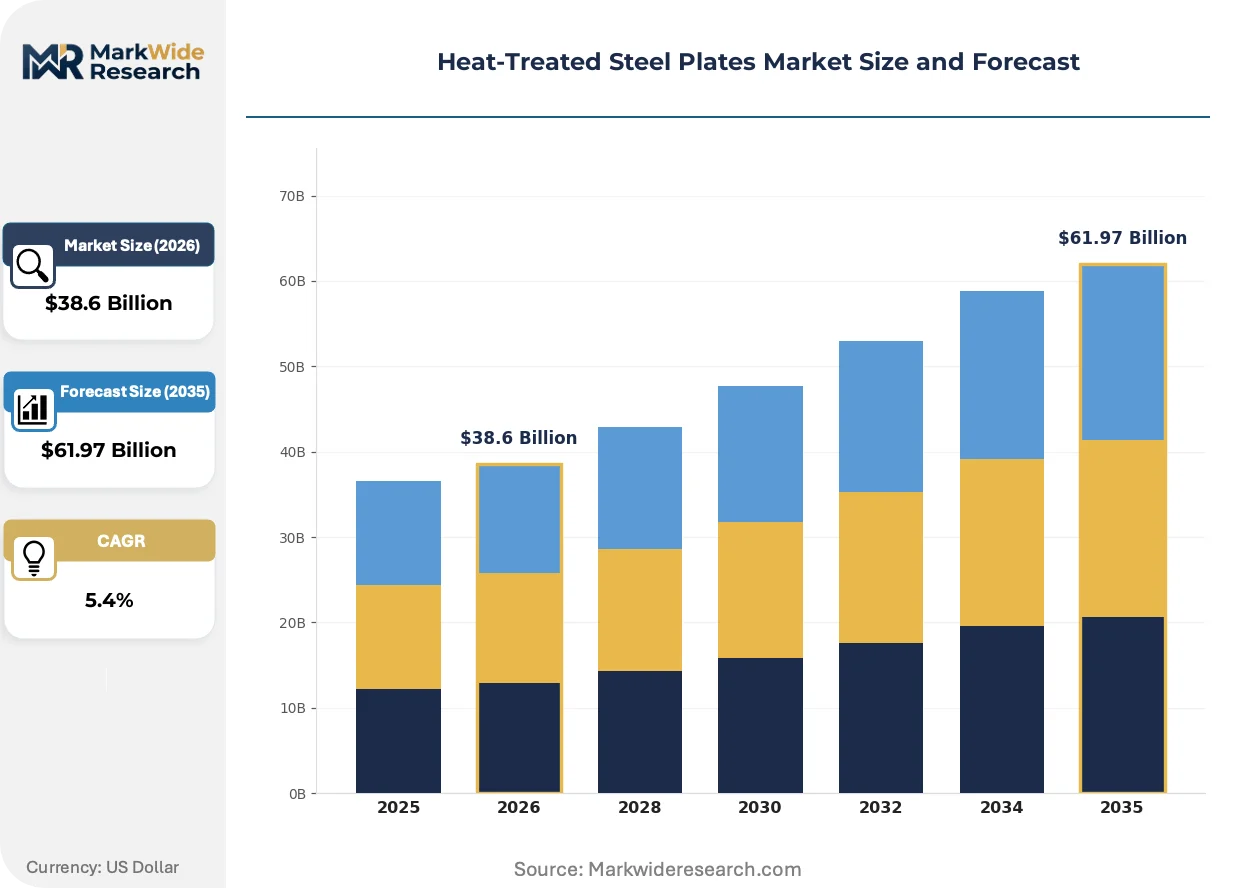
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $61.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Quenched Plates, Tempered Plates, Annealed Plates, Alloy Steel Plates End User: Aerospace, Construction, Energy, Automotive Application: Structural Components, Machinery, Tooling, Automotive Parts Supply Chain: Direct Sales, Distributors, Online Retail, Others |
| Companies Covered | POSCO, SSAB, ArcelorMittal, Tata Steel, Thyssenkrupp, China Baowu Steel Group, JFE Holdings, Voestalpine, Nippon Steel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heat-Treated Steel Plates Market Strategic Shifts & Innovations
Process digitization and regulatory carbon accounting are converging to redefine how heat-treated plates are specified, traced, and priced across heavy fabrication value chains.
Direct quenching technology is electrifying energy recovery in plate mills. Continuous cooling from rolling heat eliminates reheating cycles, cutting natural gas consumption by 30-40% in modern lines. Offshore wind fabricators in Denmark and Germany are prioritizing these low-carbon routes for foundation monopiles to meet project-level emissions targets.
REACH and the EU F-Gas Regulation are tightening process chemical controls. Quench oil formulations face substitution pressure from polymer and water-based alternatives with lower volatile organic compound profiles. Heat-treatment shops in Poland and Italy are retrofitting closed-loop systems to maintain access to German automotive and machinery OEM supply bases.
Buyers are consolidating supplier panels around certified low-carbon product categories. Energy majors and wind developers now mandate mill-specific emissions data for plate purchases above 50 tonnes. This specification shift favors integrated producers with blast furnace gas capture and electric arc furnace flexibility in Sweden, Spain, and South Korea.
Heat-Treated Steel Plates Market Segmentation
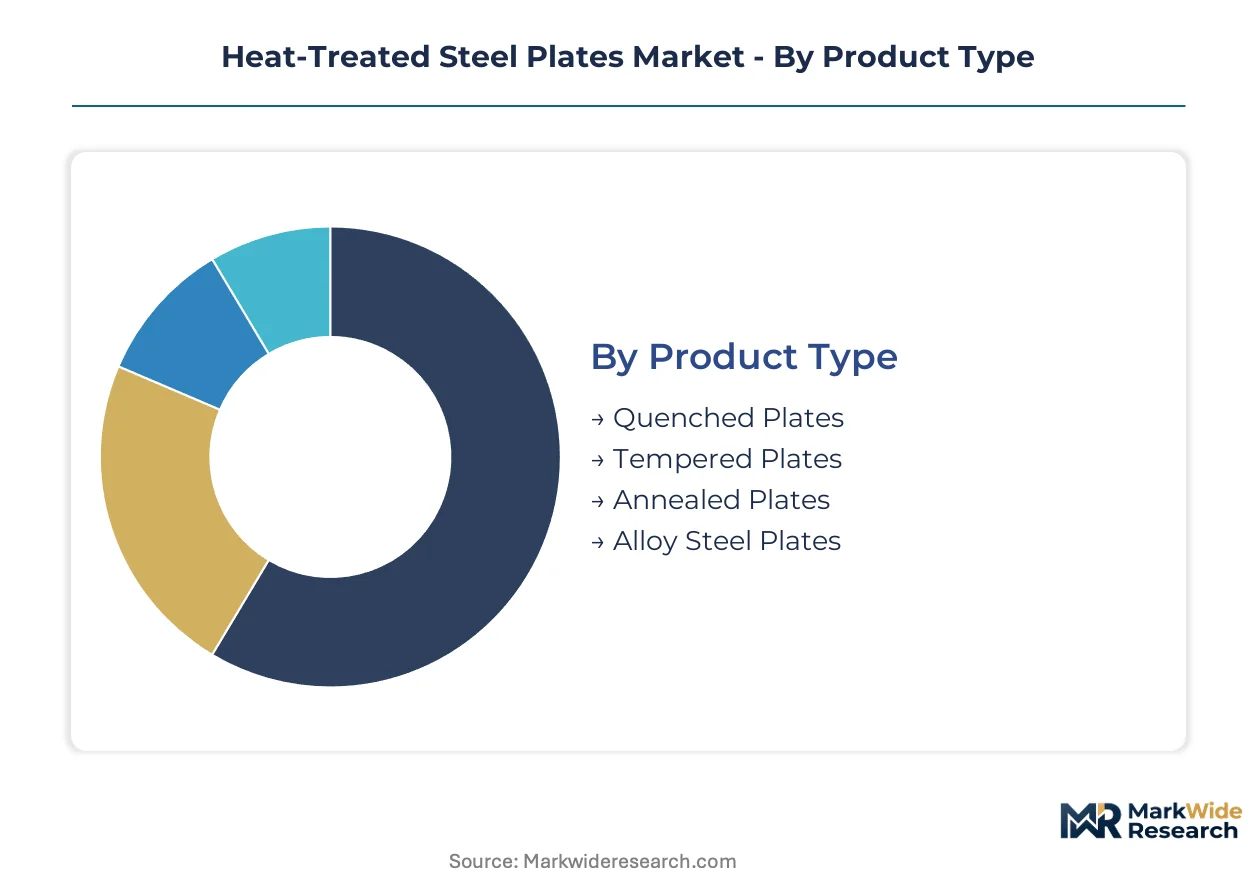
Heat-treated steel plates serve divergent performance requirements across load-bearing infrastructure, precision machinery, and safety-critical applications. Segmentation reveals how supply-side capabilities align with end-use specifications and procurement channels.
Product Type:
Integrated producers with captive blast furnace and heat-treatment lines dominate capacity allocation across these metallurgical categories.
- Quenched Plates:Rapid cooling from austenitizing temperature produces martensitic microstructures with yield strengths exceeding 690 MPa. Offshore wind monopile fabricators in Denmark and Germany specify these grades for North Sea foundation structures facing cyclic wave loading.
- Alloy Steel Plates:Nickel, chromium, and molybdenum additions enable performance in cryogenic and corrosive environments. Demand is concentrating in hydrogen pressure vessel manufacturing as Germany and South Korea deploy transmission infrastructure.
- Tempered Plates:Reheating quenched material to sub-critical temperatures improves toughness while retaining strength. Used in construction machinery booms and crane components where impact resistance matters.
- Annealed Plates:Slow furnace cooling produces soft, ductile microstructures optimized for subsequent forming operations. Volume-driven procurement from automotive stamping operations in Michigan and Bavaria.
Quenched plates absorb the bulk of installed capacity; alloy steel plates are expanding most quickly.
End User:
Customer sophistication and certification requirements create distinct margin tiers across these verticals.
- Energy:Wind tower and solar tracker manufacturers in Gujarat and Tamil Nadu drive structural grade procurement. NHTSA and FAA protocols do not apply here, shortening supplier qualification cycles compared to transportation applications.
- Construction:Infrastructure and commercial building projects specify quenched and tempered grades for high-rise columns and bridge girders. China's SAMR enforces GB standards on mechanical properties for domestic projects.
- Aerospace:Fuselage and landing gear applications face aluminum-lithium substitution above 500 MPa equivalent. Steel plate penetration here is capped by weight-driven material selection.
- Automotive:Armor plate procurement for military vehicle hulls is accelerating in Germany and India as defense modernization programs advance. Extended NHTSA qualification timelines freeze supplier switches for 18-36 months.
Energy sector procurement dominates current volume; automotive armor applications are climbing the fastest.
Application:
Functional requirements determine whether buyers prioritize strength-to-weight ratio, wear resistance, or forming compatibility.
- Structural Components:Load-bearing frameworks in infrastructure and heavy equipment demand consistent through-thickness properties. Direct quenching technology from rolling heat is gaining preference for carbon intensity reduction.
- Automotive Parts:Suspension components and chassis reinforcements require controlled mechanical property bands. REACH and EU F-Gas Regulation are tightening process chemical controls on quench oil formulations used in these applications.
- Machinery:Earthmoving and material handling equipment uses tempered grades for impact resistance. Procurement concentrates around OEM fabrication yards in Ohio and Baden-Württemberg.
- Tooling:Dies and molds require precise hardness profiles and dimensional stability. Annealed plates predominate here for subsequent machining and heat treatment.
Structural components claim the largest share of plate consumption; automotive parts are gaining share fastest.
Supply Chain:
Channel selection reflects order size, technical service requirements, and geographic proximity to heat-treatment capacity.
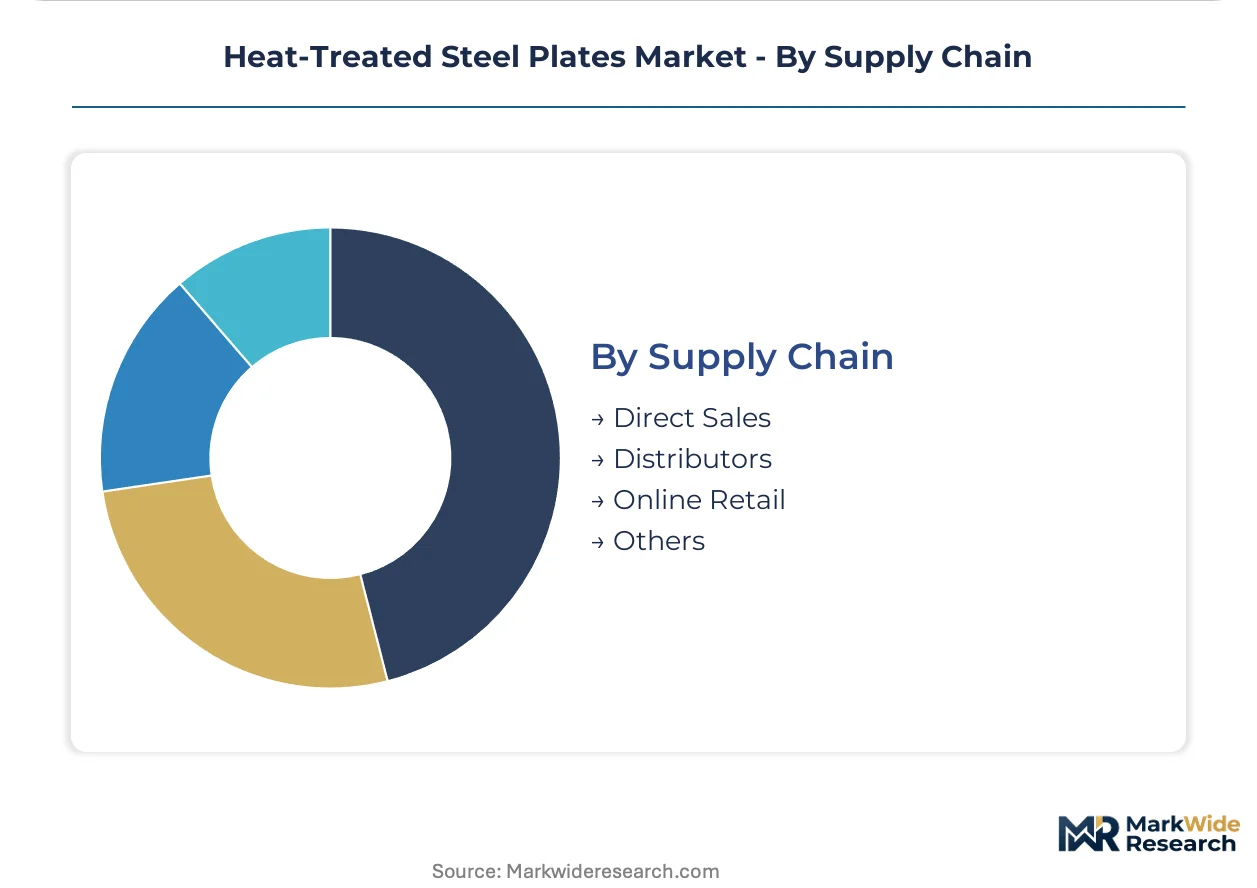
- Direct Sales:Mill-direct procurement serves wind developers and defense contractors purchasing above 50 tonnes. Energy majors now mandate mill-specific emissions data for CBAM compliance and Scope 3 reporting.
- Distributors:Stocking intermediaries provide just-in-time availability for job shops and smaller fabricators. Networks concentrate near Pohang, Mobile, and Oxelösund production sites.
- Online Retail:Digital platforms handle standard grades in small lot sizes for maintenance and repair operations. Limited penetration in quenched and tempered categories requiring technical consultation.
- Others:Consortium purchasing and long-term supply agreements serve specialized project procurement outside standard commercial channels.
Direct sales channels handle the majority of high-performance tonnage; distributor networks are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China, India, and Germany concentrate demand as renewable energy buildouts and defense manufacturing reshape procurement patterns. Offshore wind foundations and hydrogen infrastructure are pulling high-strength grades into fabrication yards across these markets.
China
SAMR enforces GB standards on mechanical properties and chemical composition for domestic projects. Dual carbon goals are accelerating direct quenching technology adoption in Yangtze River Delta mills to cut natural gas consumption. Pohang-based POSCO competes through captive steelmaking and dedicated heat-treatment lines serving Asian fabrication demand.
Germany
Offshore wind monopile fabricators in the North Sea specify quenched grades above 690 MPa yield strength. The EU CBAM framework and F-Gas Regulation are restructuring import economics for heat-treated material into European yards. Baden-Württemberg hosts machinery OEM procurement concentrating around tempered grades for construction equipment.
India
Solar tracker and wind tower fabrication is concentrating in Gujarat and Tamil Nadu, creating localized structural grade demand. The PLI scheme supports domestic steel capacity expansion for renewable energy components. Maharashtra defense contractors are accelerating armor plate procurement for vehicle hull modernization programs.
United States
NHTSA and FAA material qualification protocols gate market access for automotive and aerospace plate suppliers. Michigan automotive stamping operations drive volume procurement of annealed plates for downstream forming. Ohio fabrication yards concentrate earthmoving equipment demand for tempered grades with impact resistance specifications.
South Korea
Hydrogen pressure vessel manufacturing is expanding as Germany and South Korea deploy transmission infrastructure requiring new testing protocols. MFDS and METI standards influence regional specification alignment. Busan-Ulsan industrial corridors anchor domestic heat-treatment capacity serving energy sector procurement.
Heat-Treated Steel Plates Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated producers commanding premium quenched and tempered volumes while merchant mills serve standard annealed grades. The vendor base organizes around three strategic archetypes: captive blast furnace-to-heat-treatment operators, alloy steel specialists with corrosion-resistant capabilities, and regional distributors managing inventory for job shop networks. M&A activity concentrates on securing captive ore-to-plate routes, while capacity expansion targets direct quenching technology for carbon intensity reduction.
Within the integrated producer tier, POSCO, ArcelorMittal, and SSAB exemplify divergent geographic and metallurgical positioning. POSCO anchors Asia-Pacific supply security through Pohang-based operations. ArcelorMittal sustains margin capture on high-strength grades across European sites. SSAB occupies a position in premium wear-resistant and armor plate outputs from Oxelösund and Mobile operations.
| Leading Market Players |
|---|
| POSCO |
| SSAB |
| ArcelorMittal |
| Tata Steel |
| Thyssenkrupp |
| China Baowu Steel Group |
| JFE Holdings |
| Voestalpine |
| Nippon Steel Corporation |
| Others |
Cost & Logistics Intelligence
Direct quenching technology electrifies energy recovery in plate mills while simultaneously concentrating production economics among integrated blast furnace operators and compressing margin pools for merchant reheat-treatment facilities. The EU CBAM framework and F-Gas Regulation compound this shift by embedding carbon accounting into procurement specifications, forcing price differentiation between low-carbon European routes and conventional import sources.
Pricing Analysis
High-volume annealed grades trade on thin commodity margins while quenched and tempered specialty plates capture premium spreads. Pricing stratifies across certified low-carbon, standard performance, and merchant-market tiers based on embedded emissions data and NHTSA qualification status. Cost compression in standard structural grades intensifies as Chinese mill capacity floods regional markets. Wind developers purchasing above 50 tonnes exhibit lowest price sensitivity due to project-level emissions mandates; job shops sourcing through distributors show highest sensitivity to lot-size premiums.
Supply Chain Analysis
NHTSA and FAA material qualification protocols gate market access for non-domestic plate suppliers in automotive and aerospace applications, concentrating certified supply among incumbent integrated producers. Production gravity centers on China, South Korea, and Germany where captive steelmaking meets dedicated heat-treatment lines. Nickel, chromium, and molybdenum alloying elements draw from concentrated mining jurisdictions, exposing margin volatility to commodity swings. Single-source vulnerability runs through blast furnace-dependent routes lacking electric arc furnace flexibility. Distribution runs through mill-direct channels for energy and defense contractors above volume thresholds, with stocking intermediaries serving fragmented fabrication networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The heat-treated steel plates sector sits at a metallurgical inflection where direct quenching technology displaces conventional reheat-treatment cycles, rewarding capital-intensive integrated producers while marginalizing standalone heat-treatment shops.
For Market Incumbents: To counter high-strength aluminum-lithium substitution in adjacent aerospace applications, deepen captive ore-to-plate integration through Pohang or Oxelösund asset control and accelerate NHTSA qualification pipeline investments to freeze out merchant competitors. Carbon capture retrofits at European blast furnaces defend margin position against CBAM-exposed import competition. For New Entrants and Emerging Players: Specialized distributors with closed-loop quench oil handling capabilities offer the fastest channel to German automotive OEM supply bases restricted by REACH compliance requirements. Target India's Gujarat and Tamil Nadu solar tracker fabrication clusters where localized structural grade demand outruns domestic heat-treatment capacity. Pursue hydrogen pressure vessel certification partnerships with Busan-Ulsan industrial corridor fabricators as a qualification springboard. For Investors and Strategic Acquirers: Exit pathways concentrate in mid-cap alloy steel specialists with corrosion-resistant capabilities and captive molybdenum-chromium sourcing relationships. Long-term viability hinges on electric arc furnace feedstock flexibility and direct quenching technology deployment. Watch for inflection where CBAM carbon border levy rates materially restructure import competitiveness against European integrated producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Ore Supply | Secures nickel and molybdenum alloying element access against price volatility in critical raw material inputs. |
| Direct Quenching Technology Deployment | Reduces natural gas consumption by 30-40% in Yangtze River Delta and North Sea fabrication yard supply routes. |
| NHTSA Material Qualification Investment | Freezes automotive armor plate supplier switches for 18-36 months through extended certification timeline barriers. |
| Hydrogen Pressure Vessel Certification Partnership | Opens German and South Korea transmission infrastructure procurement to qualified domestic heat-treatment suppliers. |
| Carbon Capture Retrofit at Blast Furnace Assets | Defends European margin position against CBAM-exposed Asian import competition in offshore wind foundation grades. |
Research Approach
Independent corroboration across furnace operator interviews, wind developer procurement leads, and defense contractor quality engineers underwrites the qualitative findings on specification evolution and supplier switching dynamics. Secondary validation draws from SAMR GB standard filings, EU ETS transaction registries, and NHTSA material qualification databases. Bottom-up segmentation modeling triangulates against top-down capacity assessments from integrated producer disclosures.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. The analytical framework models product type, end user vertical, application function, and supply chain channel dimensions alongside regional regulatory cluster variations. CAGRs derive from installed capacity utilization trajectories and specification upgrade elasticities in offshore wind and hydrogen infrastructure end uses.
Caveats apply where EU CBAM levy rate adjustments or nickel-molybdenum commodity spikes could materially shift the outlook for import competitiveness and alloy grade margin pools. Forecasts reflect assumptions on certification timeline stability and direct quenching technology adoption curves. A model refresh is warranted upon material change in embedded emissions accounting protocols or hydrogen infrastructure deployment acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Copper and Copper Alloy Market
Metals
Global Oxygen-Free Copper Market
Metals
Metal Casting Market
Metals
US and Mexico Stainless Steel Market
Metals
Colloidal Metal Particles Market
Metals
Brazing Strips Market
Metals
Huntite Market
Metals
Niobium Oxide Market
Metals
India Metal Fabrication Market
Metals
Europe Aluminum Extrusion Market
Metals
Aluminium Rolled Products Market
Metals
North America and Europe Metal Powder Market
Metals
Recycled Metal Market
Metals
Global Tantalum Market
Metals
Global Aluminium Wire Rod Market
Metals
GCC Aluminium Cans Market