
 Galvanized Steel Tubes Market | 2026-2036
Galvanized Steel Tubes Market Size, Share, and Industry Trends Forecast 2026-2036
Galvanized Steel Tubes Market Analysis
Welding technician availability is rotating toward constraint in several producing regions, limiting throughput expansion at mills running continuous galvanizing lines. Tata Steel leverages its integrated steelmaking capacity to sustain captive supply of hot-rolled coil feedstock for tube production. Jindal Pipes anchors its position through deep distribution across India's northern and western construction corridors. Youfa Steel Pipe Group dominates export flows into Southeast Asian infrastructure projects.
Galvanized steel tubes are carbon steel hollow sections coated with a zinc layer through hot-dip or electro-galvanizing processes, typically achieving 40–600 g/m² zinc mass to resist atmospheric corrosion in structural and fluid conveyance applications. Round tubes command the largest volume share due to universal compatibility with piping, fencing, and mechanical frameworks, while square and rectangular profiles capture premium positioning in architectural exposed-steel applications where aesthetic uniformity and load-bearing geometry matter. Medium and heavy thickness grades concentrate margin pools, as oil and gas transmission standards and high-rise structural codes require thicker wall sections that command higher per-ton pricing.
The US market faces ASTM A53 and A500 compliance requirements administered by ASTM International, while India's BIS enforces IS 1239 and IS 1161 standards for structural and plumbing tube quality. China's SAMR oversees GB/T 3091 and GB/T 13793 certifications that govern welded galvanized tubes for low-pressure fluid service and general structures. Stakeholders must monitor evolving zinc coating specifications and carbon intensity disclosures, as procurement policies across construction and automotive end users harden around traceable environmental credentials.
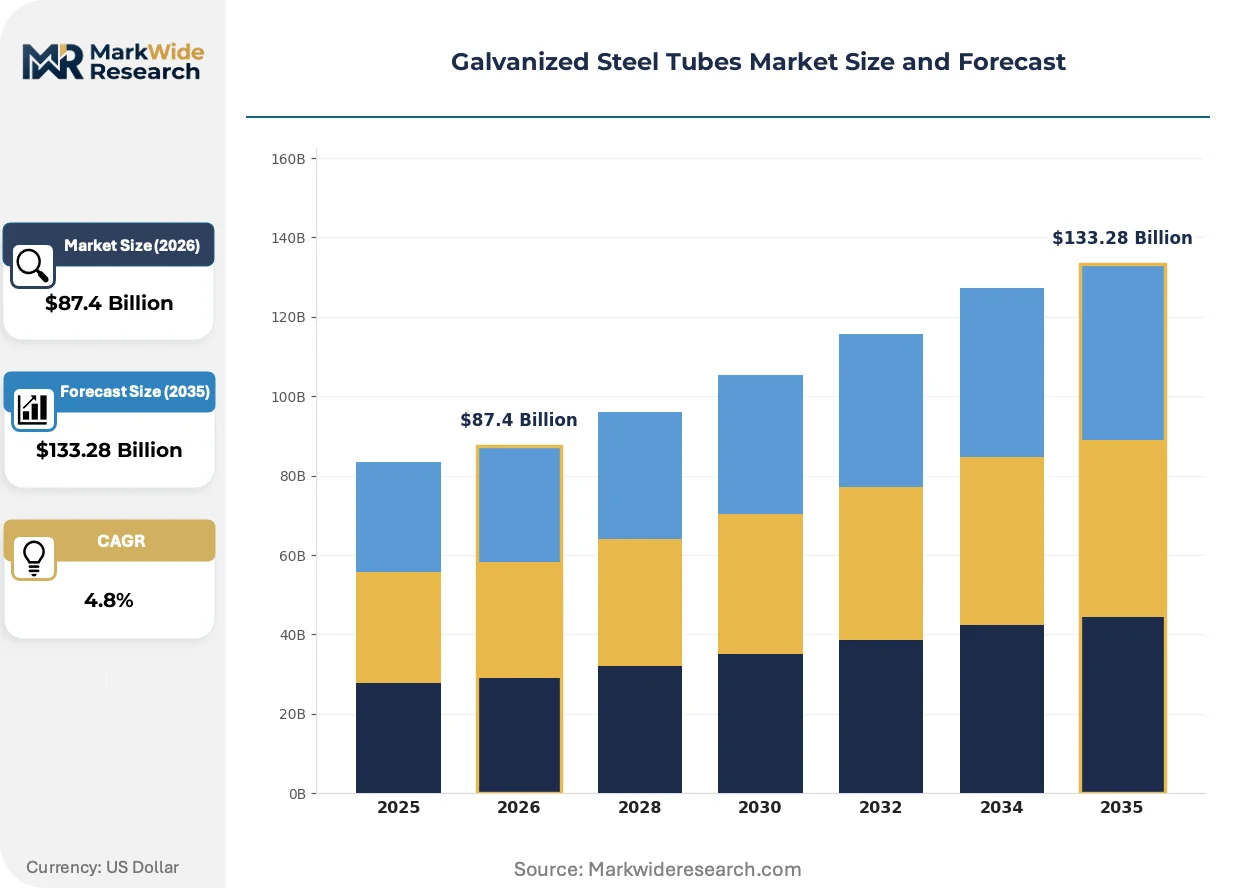
Market Dynamics
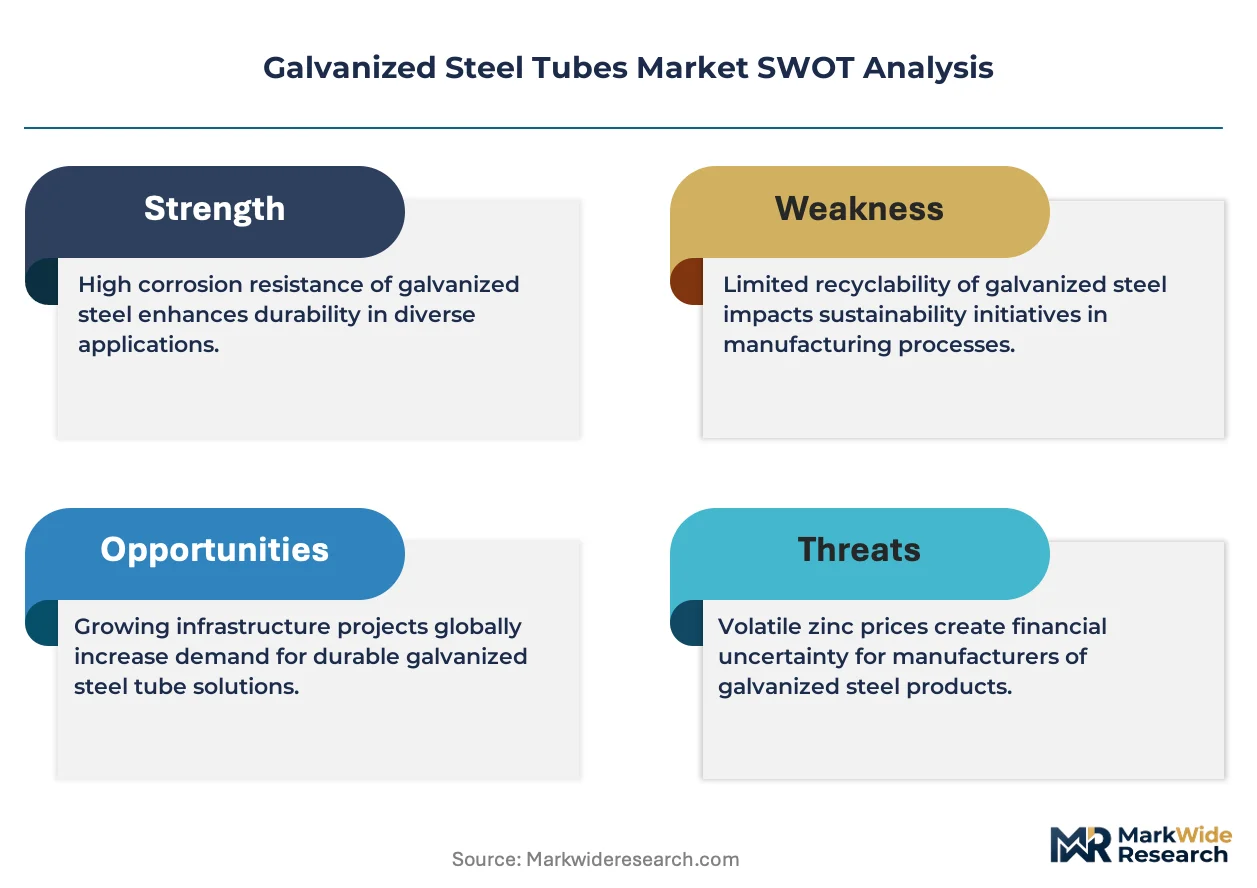
Welding technician scarcity across producing regions is tightening throughput at continuous galvanizing lines, forcing mills to prioritize higher-margin tube grades while deferring capacity expansion. This labor constraint intersects with tightening zinc coating specifications under India's BIS and China's SAMR regimes, compressing margins for non-compliant producers.
Growth Catalysts
- India's PLI scheme for specialty steel:Production-linked incentives for coated steel products are accelerating domestic galvanizing capacity additions and reducing import dependence for construction-grade tubes.
- Urban housing densification:High-rise residential programs across South and Southeast Asia are specifying rectangular hollow sections for structural frames, displacing traditional angle and channel configurations.
- IS 1239 compliance mandates:India's BIS enforcement of medium and heavy-grade structural tube standards is filtering substandard imports and consolidating procurement toward certified domestic mills.
Market Restraints
- Zing price volatility:London Metal Exchange zinc contract fluctuations transmit directly to coating cost structures, compressing margins for electro-galvanized tube producers locked into annual supply contracts.
- Concentrated HRC supply:Captive hot-rolled coil availability favors integrated steelmakers, leaving independent tube mills exposed to feedstock allocation decisions from Tata Steel and JSW Steel in India.
- Aluminum-laminated substitution:Composite piping systems with aluminum barrier layers are capturing premium plumbing applications where corrosion resistance requirements exceed galvanized tube performance envelopes.
Strategic Opportunities
- Vietnam infrastructure pipeline:Power transmission and industrial zone development under the National Master Plan are creating import demand for heavy-wall structural tubes that domestic Vietnamese capacity cannot satisfy.
- Pre-galvanized coil integration:Tube mills adopting in-line annealing and zinc pot controls can bypass standalone galvanizing steps, reducing energy intensity and coating thickness variability.
- EcoVadis and CDP procurement filters:European engineering contractors are embedding carbon disclosure scores into tender evaluation, creating first-mover advantage for mills with verified Scope 1-2 emissions data.
Industry Challenges
- Welding technician pipeline collapse:Vocational training throughput for gas metal arc and submerged arc welding has not kept pace with mill expansion, extending commissioning timelines for new continuous lines by 6-12 months.
- Multi-standard certification burden:Export-oriented producers must maintain parallel compliance with ASTM A53, EN 10255, and GB/T 3091 test protocols, multiplying laboratory accreditation costs and audit frequency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Galvanized Steel Tubes Market |
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $133.28 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Square Tubes, Round Tubes, Rectangular Tubes, Oval Tubes End User: Construction, Automotive, Electrical, Furniture Thickness: Thin, Medium, Heavy, Extra Heavy Application: Structural, Manufacturing, Agriculture, Hussing |
| Companies Covered | APL Apollo, Jindal Pipes, Tata Steel, Goodluck India, SWASTIK PIPE, Nezone Group, Zenith Birla (India), Bhushan Power & Steel, Youfa Steel Pipe Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Galvanized Steel Tubes Market Emerging Trajectories
Galvanizing process control and coating specification are diverging toward two distinct performance tiers, separating commodity construction tubes from engineered structural applications. This technical stratification is reshaping capital allocation and R&D priorities across the supply base.
High-build zinc-aluminum-magnesium alloy coatings are bifurcating the corrosion-protection segment, offering 3-5x atmospheric durability versus conventional zinc layers. Offshore wind foundation contractors and coastal infrastructure developers are specifying ZAM-coated tubes for 50-year design life requirements. The technology is compressing demand for thick pure-zinc coatings above 300 g/m² in marine-exposure applications.
China's SAMR enforcement of GB/T 3091-2015 amendments is tightening weld seam integrity testing for low-pressure fluid service tubes. Mill operators must deploy ultrasonic and eddy-current inspection systems to maintain certification, raising capital intensity for tier-2 producers. The coastal export corridor from Tianjin to Shanghai is experiencing the fastest compliance-driven equipment replacement cycle.
Engineering-procurement-construction firms are consolidating tube sourcing through framework agreements with tier-1 mills, displacing spot-market purchasing for project-specific lots. This concentration is compressing distributor margins and forcing regional stockists to specialize in value-added cutting, threading, and fabrication services. The shift is most visible in India's western construction corridor, where Reliance Industries and Adani Group projects are driving single-source contracting models.
Galvanized Steel Tubes Market Segmentation
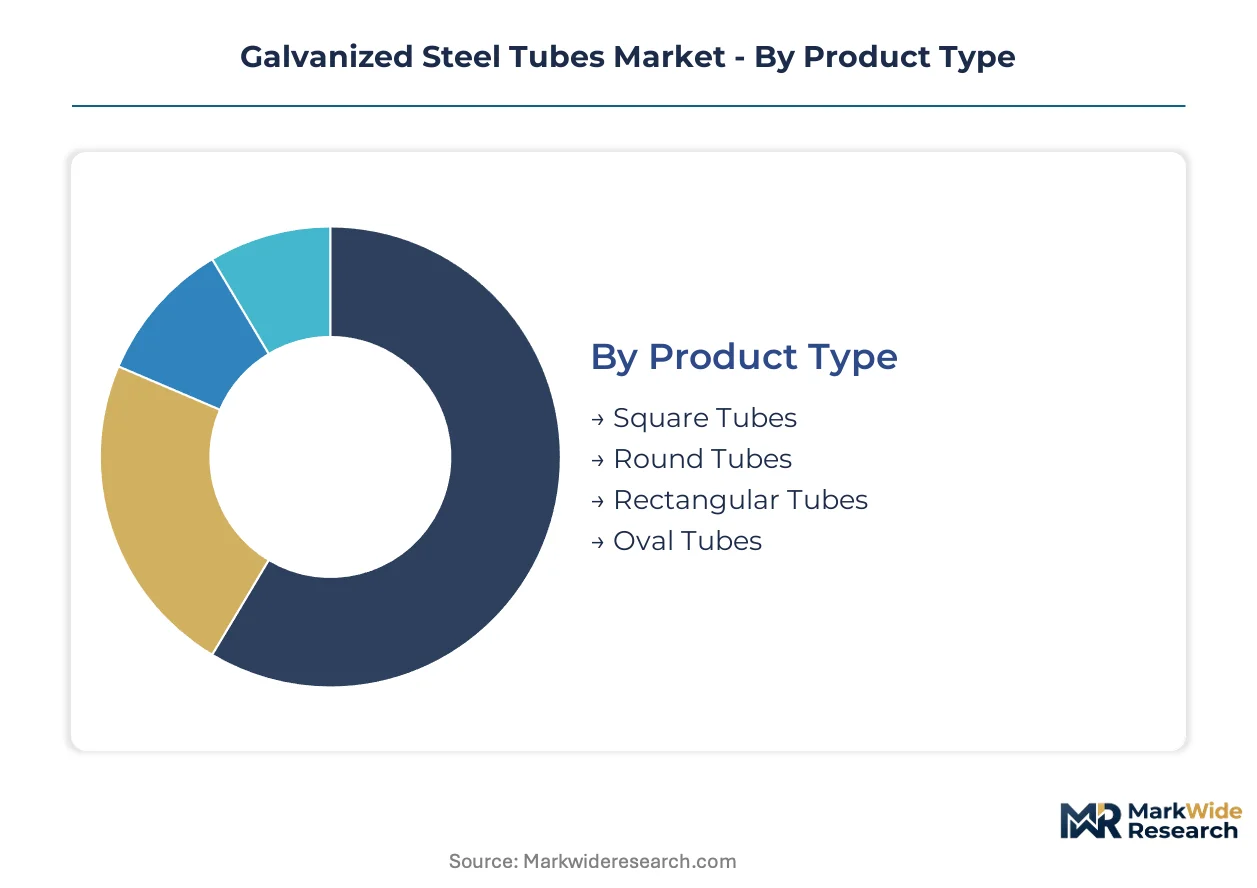
Product geometry, end-use corrosion exposure, and wall thickness specifications create distinct margin pools across the galvanized steel tubes supply base. Mills optimize continuous galvanizing line configurations around specific dimensional and coating combinations rather than serving all segments equally.
Product Type:
Margin concentration follows architectural visibility and mechanical compatibility, with premium positioning available where aesthetic finish and load-bearing geometry intersect.
- Round Tubes:Circular hollow sections with uniform stress distribution dominate fluid conveyance, fencing, and mechanical framework applications. Demand concentrates in India's western construction corridor where Reliance Industries and Adani Group infrastructure projects specify IS 1239-compliant medium-grade round sections for plumbing and structural bracing.
- Square Tubes:Equal-sided profiles enable efficient welding joints and flat surface mounting in exposed steel frameworks. High-rise residential programs across South and Southeast Asia are specifying square hollow sections for curtain wall supports, displacing traditional angle configurations in urban densification projects.
- Rectangular Tubes:Asymmetric profiles optimize bending resistance in directional load applications.
- Oval Tubes:Elliptical cross-sections serve decorative railing and specialized furniture applications.
The dominant share belongs to Round Tubes, while Square Tubes is closing the gap fastest.
End User:
Application-specific coating durability requirements and certification burdens separate price-realization tiers across customer categories.
- Construction:Structural framing, scaffolding, and infrastructure applications specify zinc coatings from 40–600 g/m² depending on atmospheric exposure. India's BIS enforcement of IS 1161 standards for structural quality is filtering substandard imports and consolidating procurement toward certified domestic mills.
- Automotive:Chassis components and exhaust systems require precision dimensional tolerance and weld seam integrity. China's SAMR oversight of GB/T 3091 compliance is tightening ultrasonic inspection requirements for automotive-grade tube suppliers.
- Electrical:Conduit and cable protection systems prioritize uniform interior surface finish.
- Furniture:Decorative and structural seating frameworks emphasize aesthetic coating appearance.
Construction commands the volume lead, though Automotive is expanding most quickly on electrification platform demand.
Thickness:
Wall section depth directly determines per-ton pricing and capital equipment requirements at tube mills.
- Medium:Wall thicknesses balancing structural adequacy with material efficiency capture the largest revenue pool. Oil and gas transmission standards and mid-rise structural codes in India and China specify medium grades that command premium pricing over thin-walled commodity tubes.
- Heavy:Thick-walled sections for high-rise structural codes and pressure service concentrate margin pools. Vietnam's National Master Plan infrastructure pipeline is creating import demand for heavy-wall structural tubes that domestic Vietnamese capacity cannot satisfy.
- Thin:Lightweight sections for non-structural applications compete on coating consistency.
- Extra Heavy:Specialized industrial and offshore applications require dedicated rolling mill capacity.
Medium thickness holds the revenue center, while Heavy is gaining share fastest on infrastructure specification upgrades.
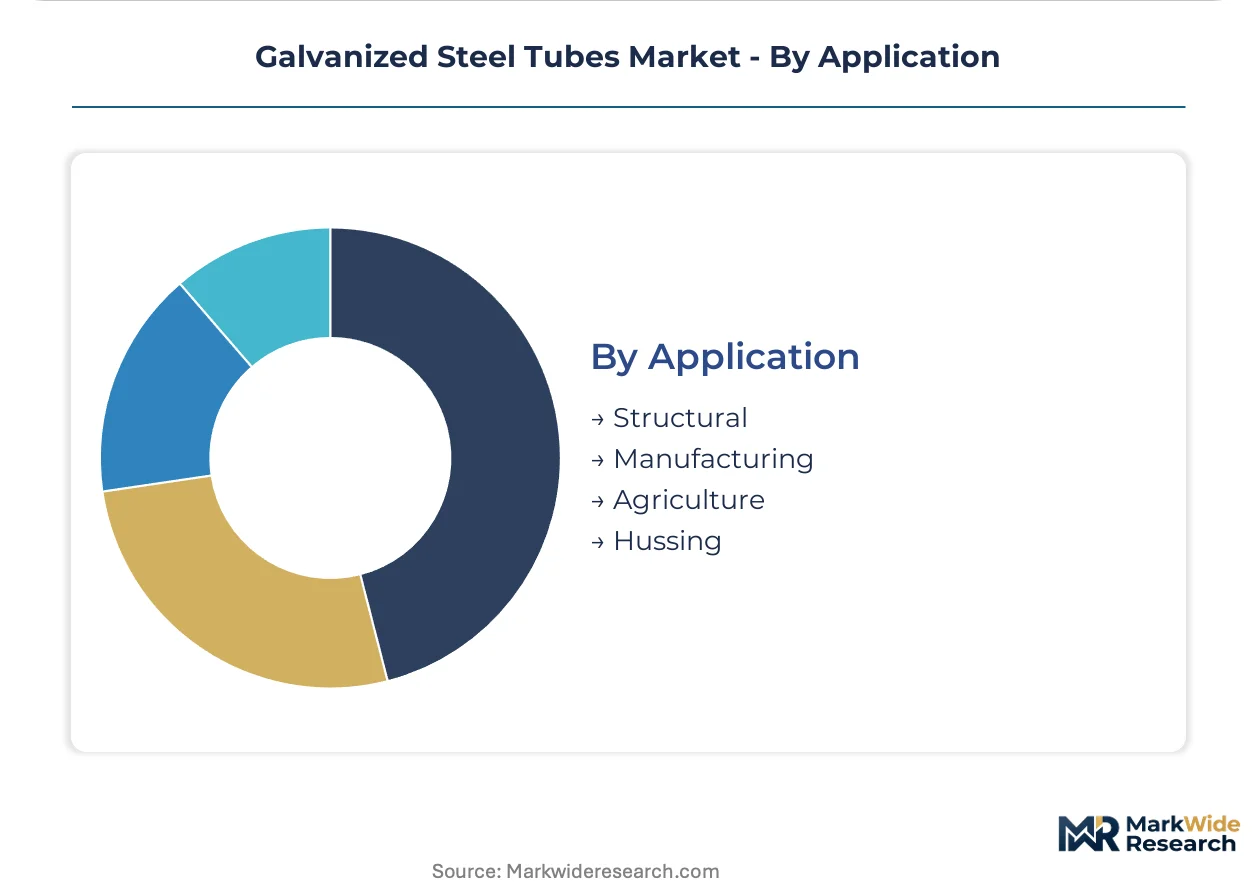
Application:
Performance certification requirements and design life specifications segment the addressable market by technical complexity.
- Structural:Load-bearing frameworks for buildings, bridges, and industrial facilities require compliance with national building codes. Offshore wind foundation contractors are specifying ZAM-coated tubes for 50-year design life requirements, compressing demand for thick pure-zinc coatings in marine-exposure applications.
- Manufacturing:Industrial equipment frames and material handling systems prioritize dimensional repeatability.
- Agriculture:Greenhouse frames and irrigation systems balance corrosion resistance with cost sensitivity.
- Housing:Residential plumbing and fencing applications drive volume through standardized specifications.
Structural application dominates value capture, with Manufacturing showing the steepest expansion trajectory on industrial automation investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across major economies. India's infrastructure-led demand favors heavy-wall structural grades, while US procurement emphasizes ASTM-certified fluid service tubes. China's coastal export mills supply Southeast Asian construction with cost-optimized round sections.
United States
Transmission pipeline replacement and data center construction are absorbing medium-grade round tubes. ASTM International administers A53 and A500 compliance requirements that filter import eligibility. Houston-Gulf Coast petrochemical clusters specify heavy-wall galvanized conduit for process piping systems.
India
Urban housing densification and highway expansion are concentrating demand for IS 1239-compliant structural sections. BIS certification mandates for medium and heavy-grade tubes are filtering substandard imports. Jamshedpur-Ranchi steel belt anchors domestic galvanizing capacity expansion.
China
Coastal infrastructure and renewable energy projects are specifying GB/T 3091-certified welded tubes. SAMR enforcement of weld seam integrity testing is raising capital intensity for tier-2 producers. Tianjin-Shanghai export corridor dominates Southeast Asian supply flows.
Germany
Offshore wind foundation contractors are specifying ZAM-coated tubes for 50-year marine exposure design life. REACH and EU Green Deal disclosure requirements are hardening procurement filters around carbon intensity. Ruhr industrial belt maintains specialized rolling capacity for precision automotive-grade sections.
Vietnam
Power transmission and industrial zone development under the National Master Plan are creating import demand for heavy-wall structural tubes. Domestic galvanizing capacity cannot satisfy specification-grade requirements. Northern port clusters around Haiphong are receiving Chinese and Indian mill shipments.
Galvanized Steel Tubes Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive hot-rolled coil supply separating the two groups. Tata Steel and JSW Steel leverage backward integration into steelmaking to control feedstock costs and allocation priority. Independent tube mills compete through coating specialization and regional distribution density. Capacity expansion and certification stacking represent the dominant competitive vectors, as mills add parallel ASTM, EN, and GB test protocols to capture export tenders.
Among Indian integrated producers, Tata Steel exemplifies the captive-feedstock archetype, while Jindal Pipes anchors the distribution-intensive specialist tier. Youfa Steel Pipe Group occupies the export-scale position, supplying Southeast Asian infrastructure projects from Chinese coastal mills. These three represent distinct competitive postures: upstream control, downstream reach, and cross-border volume.
| Leading Market Players |
|---|
| APL Apollo |
| Jindal Pipes |
| Tata Steel |
| Goodluck India |
| SWASTIK PIPE |
| Nezone Group |
| Zenith Birla (India) |
| Bhushan Power & Steel |
| Youfa Steel Pipe Group |
| Others |
Supply Flow & Price Mechanics
Continuous galvanizing line scale economies in India and China concentrate cost leadership among integrated steelmakers, compressing price floors for independent tube mills while elevating margin capture for Tata Steel and JSW Steel through captive hot-rolled coil supply. This scale concentration reinforces two-tier pricing stratification: project-based offtake contracts from EPC firms anchor volume, while spot-market transactions expose non-integrated producers to zinc price volatility and feedstock allocation risk.
Pricing Analysis
Long-term offtake agreements dominate procurement for Indian infrastructure projects, with Reliance Industries and Adani Group locking in annual volume commitments at fixed zinc-adjusted pricing. Price differentiation separates IS 1239-certified structural grades from commodity plumbing tubes, with BIS compliance premiums widening as enforcement tightens. Cost compression in electro-galvanized segments is intensifying because LME zinc contract volatility transmits directly to coating costs, leaving spot-market buyers most price-sensitive while framework-contracted EPCs maintain cost predictability.
Supply Chain Analysis
Strait of Malacca transit underwrites raw material flows for Southeast Asian tube consumption, with zinc concentrate shipments from Australia and Indonesia feeding Chinese and Indian galvanizing capacity. Hot-rolled coil supply concentrates in India, China, and Japan, with captive production favoring integrated mills. Single-source vulnerability rests on concentrated HRC allocation decisions from Tata Steel and JSW Steel. Distribution runs through regional stockists specializing in value-added cutting and threading services, particularly in India's western construction corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's PLI scheme for specialty steel and tightening BIS certification mandates are accelerating capacity consolidation, creating a high-growth disruption window where compliance-ready producers capture disproportionate share from import-dependent competitors.
For Market Incumbents: Consolidate coating specialization advantages by deepening pre-galvanized coil integration to bypass standalone galvanizing steps, reducing energy intensity and thickness variability. Defend against ZAM-coated tube substitution in marine-exposure applications by accelerating R&D into zinc-aluminum-magnesium alloy capabilities. Prioritize certification stacking across ASTM, EN, and GB protocols to lock in export tender eligibility.
For New Entrants and Emerging Players: Anchor in Vietnam's heavy-wall structural tube import gap, where domestic galvanizing capacity cannot satisfy National Master Plan infrastructure specifications. Target IS 1161-compliant medium-grade segments in India's northern construction corridors, where distributor fragmentation creates white-space for certified regional mills. Pursue EPC framework agreement positioning through demonstrated weld seam integrity and rapid lot-size flexibility.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among tier-1 mills with locked EPC framework agreements and captive HRC supply, suggesting long-term viability over a multi-year horizon favors backward-integrated producers. Acquisition targets should screen for BIS/ASTM dual-certification readiness and continuous line commissioning timelines within operational windows. Monitor welding technician training pipeline throughput as an inflection indicator for capacity expansion feasibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Pre-Galvanized Coil Integration | In-line annealing and zinc pot controls reduce energy intensity for Tata Steel and JSW Steel. |
| ZAM Coating Capability Buildout | Zinc-aluminum-magnesium alloys capture offshore wind foundation specifications from European EPCs. |
| Multi-Standard Certification Stacking | Parallel ASTM, EN, and GB protocols unlock Southeast Asian infrastructure tender eligibility. |
| Welding Technician Training Pipeline | Vocational program investment shortens continuous line commissioning timelines by 6-12 months. |
| EcoVadis Carbon Disclosure Verification | Verified Scope 1-2 emissions data satisfies European engineering contractor procurement filters. |
Methodological Framework
A spread of perspectives from continuous line operators, EPC procurement managers, welding technician training directors, and zinc coating R&D leads converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation through BIS certification records, SAMR enforcement bulletins, customs trade data, and SEC filings from listed steelmakers. Bottom-up segment sizing triangulated against top-down macroeconomic drivers across the analysis window.
Segmentation dimensions modeled include product geometry, wall thickness grade, end-use corrosion exposure, and coating specification tier throughout the forecast period. CAGRs were derived from elasticity-adjusted demand projections and capacity utilization trajectories. Industry-specific forecast inputs incorporated PLI scheme disbursement schedules and BIS enforcement intensity timelines.
Decision-makers should treat outputs as directional under base assumptions of sustained Indian infrastructure investment and stable zinc concentrate supply; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as welding technician pipeline constraints and aluminum-laminated substitution threats evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Clad Pipe Market
Pipes and Tubes
UAE PVC Pipes Market
Pipes and Tubes
Hot Dip Galvanized Steel Pipe Market
Pipes and Tubes
Acid Resistant Pipe Market
Pipes and Tubes
Copper Tube Market
Pipes and Tubes
Global Titanium Tube Market
Pipes and Tubes
Chlorinated Polyvinyl Chloride (Cpvc) Pipes Market
Pipes and Tubes
Europe Pipe Market
Pipes and Tubes
Multibore Tubes Market
Pipes and Tubes
Galvanized Iron Pipes Market
Pipes and Tubes
Thermoplastic Pipe Market
Pipes and Tubes
GRP Pipe Market
Pipes and Tubes
Aluminium Tubes for OPC Drum Market
Pipes and Tubes
Pipe Market
Pipes and Tubes
Weld Overlay Process Clad Pipes Market
Pipes and Tubes
Global Tracer Wires Market