
 Electrolytic Iron Market | 2026-2036
Electrolytic Iron Market Size, Share, and Industry Trends Forecast 2026-2036
Electrolytic Iron Market Intelligence
The capital-intensity divergence between integrated smelter-operators and merchant powder producers is bifurcating competitive dynamics in electrolytic iron. Hoganas AB leverages its captive reduction facilities to sustain cost discipline across high-purity powder grades. JFE Steel Corporation anchors its position through integrated steelmaking synergies that feed specialized magnetic sheet output. TOHO ZINC competes on electrowinning expertise refined across non-ferrous metal extraction, extending technical credibility into battery-grade iron precursors.
Electrolytic iron denotes refined metallic iron produced through electrodeposition from aqueous ferrous salt solutions, typically achieving purity exceeding 99.9% with controlled carbon, sulfur, and phosphorus residuals below 50 ppm; this material serves as feedstock for soft magnetic components, pharmaceutical-grade iron compounds, and premium powder metallurgy parts where impurity tolerance approaches zero. Powders command the deepest margin pools owing to atomization complexity and batch certification overhead, while pellets retain volume leadership in legacy induction-melting workflows. Ultra-high purity grades represent the fastest-expanding slice as solid-state battery researchers and medical device sterilization equipment makers tighten material specifications.
FDA pharmaceutical-grade material standards and EPA hazardous waste rules from electrodeposition sludge govern US market access, while REACH registration and RoHS substance restrictions shape European product qualification pathways. Japan's METI circular-economy guidelines for critical minerals are beginning to influence electrolytic iron recycling mandates and scrap-input ratios. Stakeholders must monitor how battery supply chain due-diligence rules migrate from cobalt and lithium into upstream iron precursor classifications.
Market Dynamics
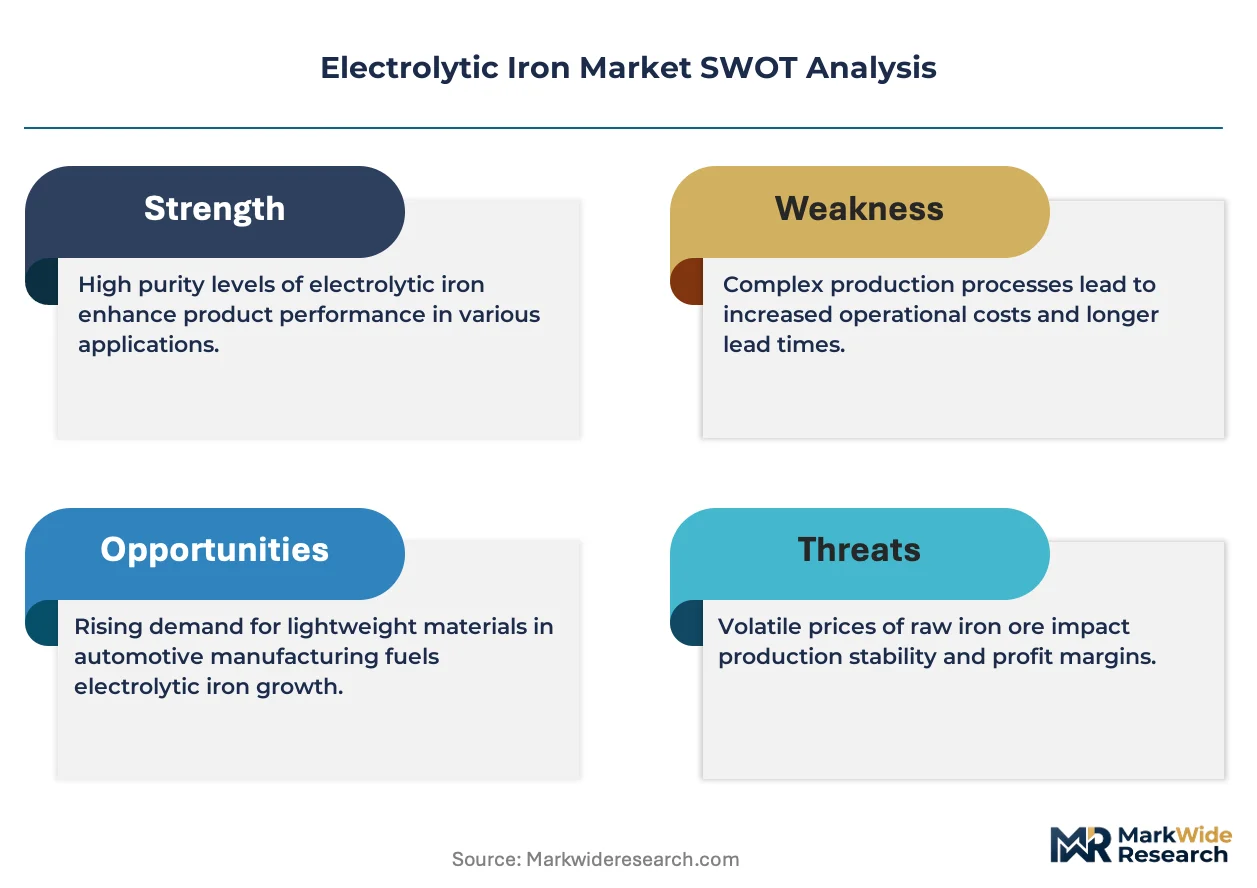
Powder metallurgy specifications in automotive drivetrains are forcing electrolytic iron producers to recalibrate purity thresholds and batch certification protocols. The divergence between legacy induction-melting demand and emerging solid-state battery precursor requirements is splitting technical roadmaps across the supplier base.
Growth Catalysts
- Automotive lightweighting mandates:OEM specifications for densified powder-forged gears and sprockets are pulling ultra-high-purity iron feedstock into transmission and driveline component supply chains.
- REACH substance restrictions:European chemical registration requirements are disqualifying lower-grade ferrous inputs from medical device and pharmaceutical compound manufacturing, redirecting procurement toward certified electrodeposition sources.
- Solid-state battery R&D pipelines:Lithium-metal anode development programs are specifying battery-grade iron precursors with sub-10 ppm metallic impurities, opening specification-driven demand from energy storage developers.
Market Restraints
- Electrowinning energy intensity:Ferric chloride reduction requires sustained high-amperage direct current, exposing production economics to regional electricity tariff volatility and grid carbon intensity penalties.
- Feedstock ore concentration:High-grade magnetite availability concentrates in Western Australia and northern Sweden, concentrating supply risk for electrodeposition operators without captive mine access.
- Sponge iron substitution:Direct-reduced iron from Midrex shaft furnaces is capturing share in induction-melting applications where 99.5% purity suffices, compressing addressable volume for standard-grade electrolytic pellets.
Strategic Opportunities
- India pharmaceutical excipient demand:CDSCO track-and-trace mandates for active pharmaceutical ingredients are elevating documentation requirements that favor qualified electrolytic iron sulfate suppliers over commodity ferrous salts.
- Japan circular-economy mineral guidelines:METI recycling mandates for critical metals are creating preferential procurement pathways for electrodeposition operators demonstrating scrap-input ratios above threshold levels.
- Additive manufacturing feedstock:Plasma atomization of electrolytic iron into spherical powder for binder jet and laser powder bed fusion is opening margin pools in aerospace and medical implant prototyping workflows.
Industry Challenges
- Electrochemist talent scarcity:Ferrous electrowinning expertise concentrates among aging specialists in non-ferrous zinc and copper operations, constraining workforce transfer into dedicated iron electrodeposition facilities.
- Batch certification timelines:Pharmaceutical-grade material qualification requires 18-24 month stability studies under ICH guidelines, freezing working capital and delaying revenue recognition for new production campaigns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrolytic Iron Market |
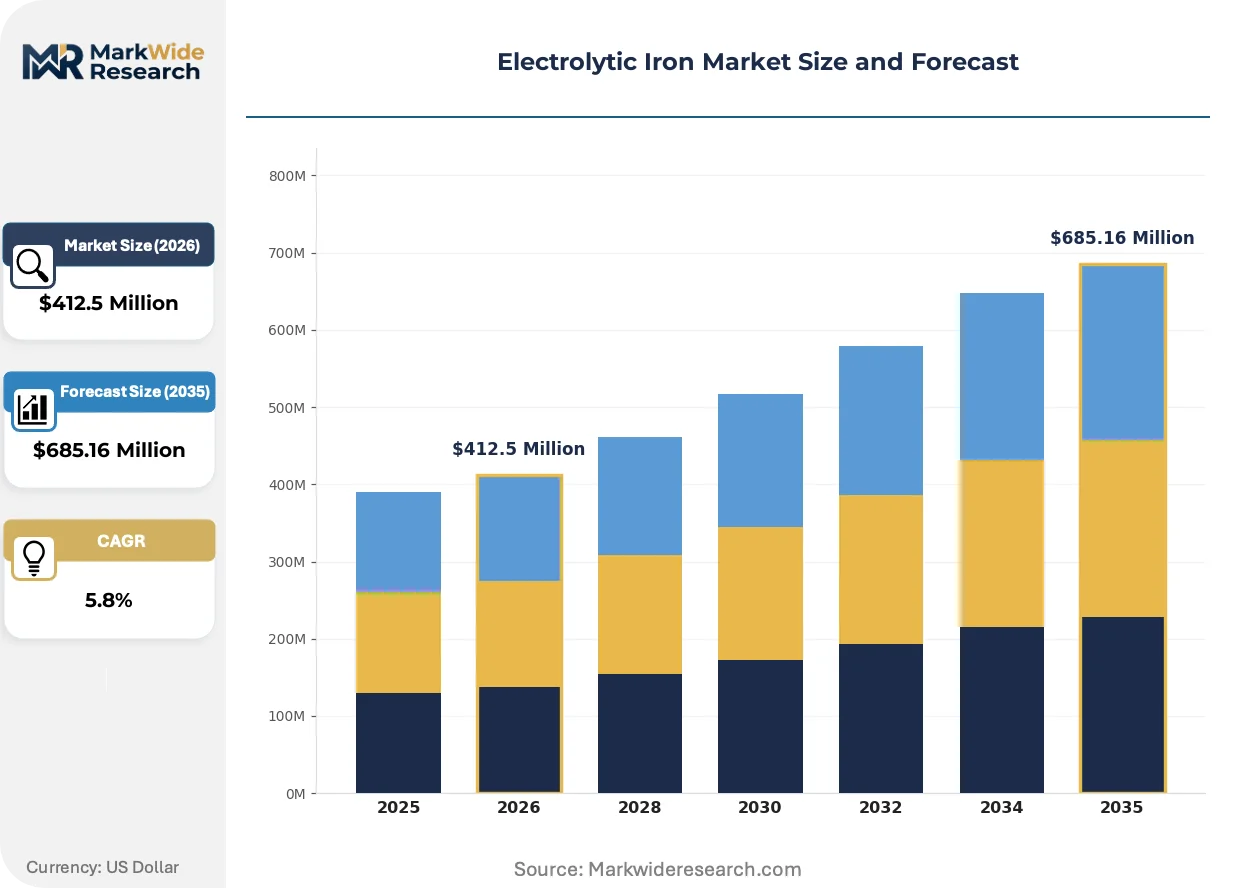
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $685.16 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pellets, Powders, Sheets, Bars Application: Electronics, Automotive, Aerospace, Renewable Energy End User: Manufacturers, Research Institutions, Construction, Medical Purity Level: Low, Medium, High, Ultra-High |
| Companies Covered | Hoganas AB, JFE Steel Corporation, TOHO ZINC, Blyth Metals Ltd., Dr. Fritsch, Industrial Metal Powders Pvt. Ltd., Porwal Metallurgicals, Allied Metals, Rio Tinto, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrolytic Iron Market Strategic Shifts & Innovations
Electrolytic iron production is bifurcating between commodity-scale electrodeposition for legacy industrial applications and precision-controlled electrowinning for specification-critical end uses. Technical differentiation is concentrating in impurity detection thresholds and atomization morphology control.
Membrane electrode assembly electrowinning is decomposing the traditional tank-house configuration by enabling continuous ferrous ion extraction without batch sludge handling. Solid-state battery researchers at Korean and Japanese materials institutes are piloting this configuration for battery-grade precursor production. The technology is decomposing capital intensity barriers that previously constrained entry into sub-50 ppm purity segments.
EU F-Gas Regulation phase-down schedules are pressuring electrodeposition operators to retrofit sulfur hexafluoride-based switchgear in rectifier substations. Industrial gas suppliers are accelerating fluoronitrile alternative qualification programs across German and Polish electrowinning corridors. Magnetic sheet manufacturers in the Czech Republic and Slovakia are auditing supplier carbon footprints to preempt scope-three disclosure requirements under CSRD.
Specification-driven buyers are consolidating vendor panels around dual-source qualified suppliers capable of spanning pharmaceutical, magnetic, and powder metallurgy grades simultaneously. Tier-one automotive powder forgers are requiring lot-level ICP-MS trace element certificates with 28-day delivery guarantees, displacing spot-market purchasing for critical drivetrain components. This consolidation is most visible in German and Japanese supply chains where OEM quality agreements mandate single-source accountability for magnetic core material lots.
Electrolytic Iron Market Segmentation
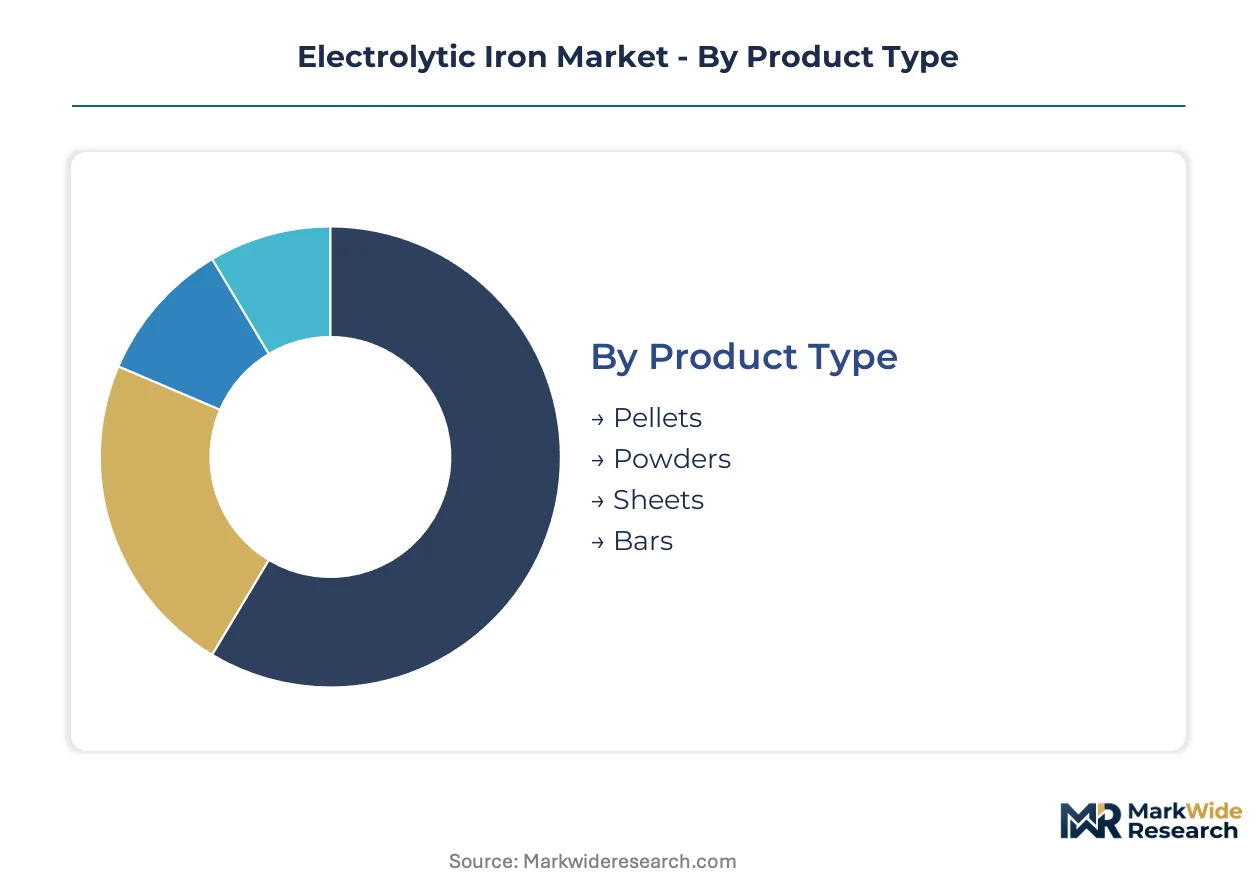
Electrolytic iron procurement splits sharply between legacy industrial formats and specification-critical grades where impurity thresholds determine supplier qualification. Understanding these divides reveals where certification investments and capacity commitments concentrate across the value chain.
Product Type:
Powders command the deepest margin pools owing to atomization complexity and batch certification overhead, while pellets retain volume leadership in legacy induction-melting workflows.
- Pellets:Spherical or irregular agglomerates produced through electrodeposition and subsequent reduction, typically sized 1-10 mm for direct feeding into induction furnaces. Steel foundries in Germany and Japan consume the majority for specialty castings where 99.5% purity suffices, though direct-reduced iron from Midrex furnaces is compressing this segment's addressable volume.
- Powders:Atomized particulates achieving controlled particle size distributions from 10-150 microns, requiring inert gas atomization and magnetic separation to meet powder metallurgy specifications. Automotive powder forgers in Stuttgart and Nagoya specify ultra-high-purity grades for densified gear production under OEM lightweighting mandates.
- Sheets:Rolled electrodeposited material for magnetic core laminations, produced in thicknesses from 0.1-0.5 mm with controlled crystallographic texture.
- Bars:Cast or extruded ingots serving laboratory and research applications requiring machinable feedstock for prototype magnetic components.
Pellets hold installed capacity. Powders is rotating up the share rankings.
Application:
Volume concentrates in established electromagnetic applications, while specification-driven demand from emerging energy storage formats is climbing fastest.
- Electronics:Soft magnetic cores for transformers, inductors, and electromagnetic shielding requiring precisely controlled coercivity and permeability. Japanese magnetic sheet manufacturers in the Tokyo-Yokohama corridor specify sub-50 ppm sulfur residuals to prevent core losses at high switching frequencies.
- Automotive:Powder-forged transmission components, variable valve timing systems, and electric drivetrain magnetic assemblies. German OEM quality agreements now mandate single-source accountability for critical drivetrain material lots, consolidating procurement around dual-qualified suppliers.
- Aerospace:Specialized magnetic components for flight control systems and sensor housings where weight minimization intersects with extreme reliability requirements.
- Renewable Energy:Generator cores and grid-scale inverter magnetic components, with emerging demand from solid-state battery precursor programs specifying battery-grade iron with sub-10 ppm metallic impurities.
Electronics maintains the largest installed base. Renewable Energy is climbing the fastest.
End User:
Procurement sophistication diverges sharply between specification-driven manufacturers and research buyers prioritizing flexibility over scale.
- Manufacturers:Tier-one automotive suppliers and magnetic component fabricators requiring lot-level ICP-MS trace element certificates with 28-day delivery guarantees. These buyers are consolidating vendor panels around suppliers capable of spanning pharmaceutical, magnetic, and powder metallurgy grades simultaneously.
- Research Institutions:National laboratories and university materials science departments purchasing small-batch material for solid-state battery and additive manufacturing R&D. Korean and Japanese materials institutes are piloting membrane electrode assembly electrowinning configurations for battery-grade precursor production.
- Construction:Limited specialty applications in electromagnetic shielding for data centers and high-performance architectural components.
- Medical:Pharmaceutical-grade iron compounds for parenteral nutrition and MRI contrast agent precursors, requiring 18-24 month stability studies under ICH guidelines that freeze working capital for new production campaigns.
Manufacturers dominate committed offtake. Research Institutions are expanding most quickly.
Purity Level:
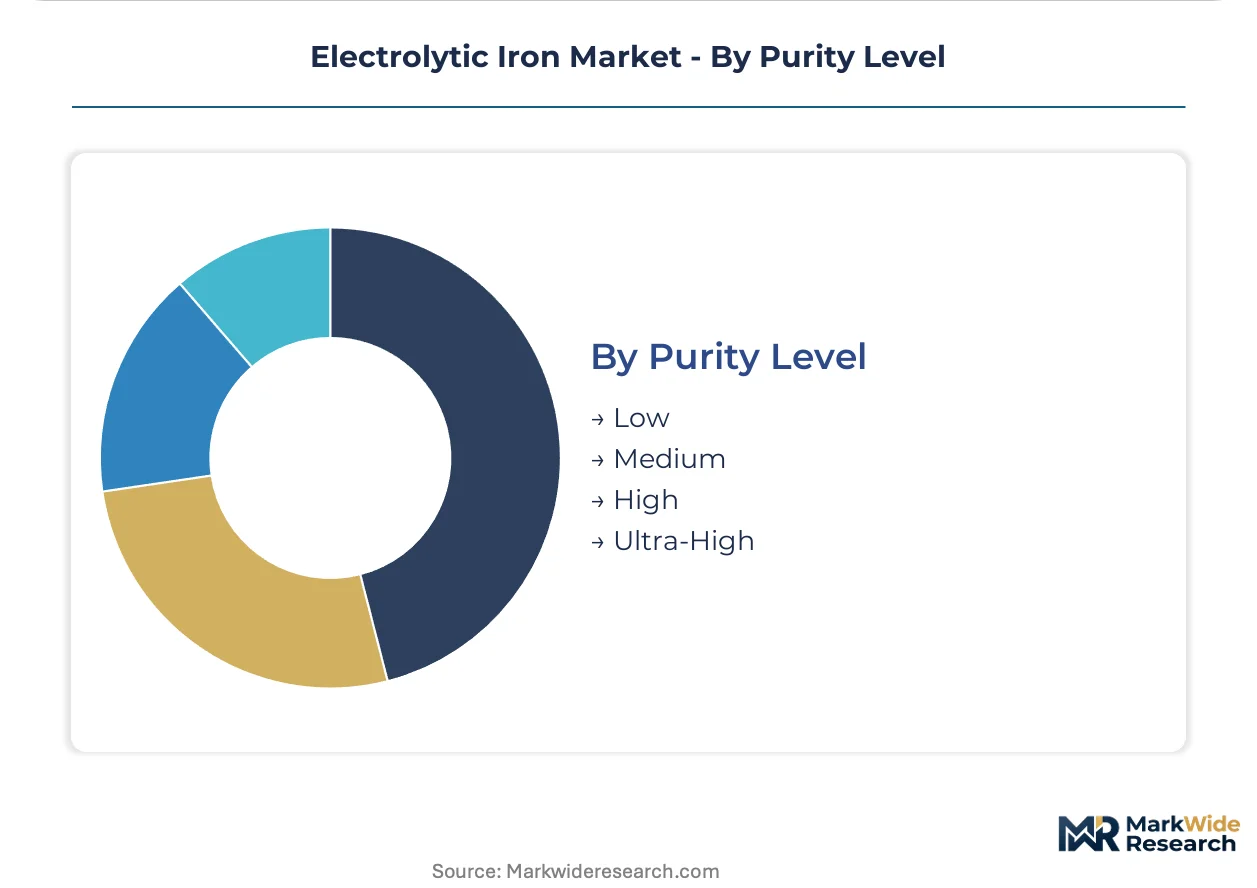
Grade stratification determines supplier qualification barriers and pricing tiers, with ultra-high specifications opening the steepest expansion trajectory.
- Ultra-High:Purity exceeding 99.95% with carbon, sulfur, and phosphorus residuals below 10 ppm, produced through precision-controlled electrowinning with membrane separation. Solid-state battery researchers and medical device sterilization equipment makers are tightening material specifications fastest in this tier.
- High:99.9-99.95% purity serving pharmaceutical excipient and premium powder metallurgy applications where REACH substance restrictions are disqualifying lower-grade ferrous inputs.
- Medium:99.5-99.9% purity for standard magnetic components and industrial chemical synthesis where cost sensitivity permits slightly elevated impurity tolerance.
- Low:99.0-99.5% purity facing displacement by direct-reduced iron in induction-melting applications where sponge iron substitution is capturing share.
High purity grades hold established capacity. Ultra-High is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows reveal pronounced asymmetries in electrolytic iron trade. China maintains substantial net export positions in standard-grade pellets, while Germany and Japan remain structural importers of ultra-high-purity powders for automotive and magnetic applications.
Germany
Automotive powder forgers in Stuttgart and Munich drive substantial ultra-high-purity iron procurement for densified gear production. REACH substance restrictions enforced by ECHA disqualify lower-grade ferrous inputs from medical device manufacturing, redirecting procurement toward certified electrodeposition sources. The Ruhr industrial corridor hosts specialized magnetic sheet fabricators auditing supplier carbon footprints to preempt CSRD scope-three disclosure requirements.
China
Domestic powder metallurgy expansion for electric vehicle drivetrain components absorbs growing volumes of domestically produced electrolytic iron. NMPA pharmaceutical-grade material standards govern market access for iron sulfate excipient suppliers serving domestic drug manufacturers. The Yangtze River Delta concentration of electrodeposition operators faces tightening MEE environmental inspections on electrodeposition sludge handling protocols.
Japan
Magnetic component manufacturers in the Tokyo-Yokohama corridor specify sub-50 ppm sulfur residuals for high-frequency transformer cores. METI circular-economy guidelines for critical minerals are creating preferential procurement pathways for operators demonstrating scrap-input ratios above threshold levels. Nagoya-based automotive suppliers now mandate single-source accountability for critical drivetrain material lots under revised OEM quality agreements.
United States
FDA pharmaceutical-grade material standards and EPA hazardous waste rules from electrodeposition sludge govern market access for domestic producers. Midwestern steel foundries consume standard-grade pellets for specialty castings where 99.5% purity suffices, though Midrex sponge iron substitution compresses this segment. Research institutions in the Boston corridor are piloting membrane electrode assembly electrowinning for solid-state battery precursor production.
India
CDSCO track-and-trace mandates for active pharmaceutical ingredients elevate documentation requirements favoring qualified electrolytic iron sulfate suppliers over commodity ferrous salts. Maharashtra-based pharmaceutical compounders are expanding dedicated electrodeposition capacity to serve parenteral nutrition and MRI contrast agent precursor demand. Gujarat industrial zones host emerging powder metallurgy operations supplying automotive component manufacturers in Pune and Chennai.
Electrolytic Iron Market Key Industry Players
Concentration sits with integrated steelmakers and specialized powder metallurgy houses that command captive reduction facilities and atomization expertise. The competitive terrain splits between commodity-scale electrodeposition operators serving legacy induction-melting demand and precision-controlled electrowinning specialists targeting specification-critical end uses. Three archetypes dominate: integrated smelter-operators leveraging steelmaking synergies, merchant powder producers with inert gas atomization capabilities, and non-ferrous metal extractors extending electrowinning expertise into ferrous applications. Capacity expansion and portfolio diversification toward battery-grade precursors represent the dominant competitive moves across the supplier base.
Within the integrated steelmaker tier, JFE Steel Corporation exemplifies players anchoring positions through steelmaking synergies feeding specialized magnetic output. Among European powder specialists, Hoganas AB occupies a position representing captive reduction facility advantages sustaining cost discipline across high-purity grades. On the non-ferrous extraction vector, TOHO ZINC sits within specialists extending electrowinning credibility refined across zinc operations into battery-grade iron precursor segments.
| Leading Market Players |
|---|
| Hoganas AB |
| JFE Steel Corporation |
| TOHO ZINC |
| Blyth Metals Ltd. |
| Dr. Fritsch |
| Industrial Metal Powders Pvt. Ltd. |
| Porwal Metallurgicals |
| Allied Metals |
| Rio Tinto |
| Others |
Cost & Logistics Intelligence
REACH registration and RoHS substance restrictions gate both supplier qualification and price differentiation simultaneously, compressing margins for uncertified operators while amplifying premiums for electrodeposition sources with documented impurity traceability. Pharmaceutical-grade batch certification under ICH guidelines freezes working capital for 18-24 months, embedding documentation costs into quoted prices that commodity ferrous salt suppliers cannot match.
Pricing Analysis
Configured-to-order pricing for ultra-high-purity grades with sub-10 ppm metallic impurities commands spreads of 40-60% above standard pellet quotations, reflecting atomization complexity and ICP-MS certification overhead. Pricing stratifies across premium, standard, and economy tiers where powder metallurgy specifications for automotive drivetrain components anchor the premium band. Cost compression in standard-grade pellets is intensifying because Midrex sponge iron substitution captures share in induction-melting applications. Tier-one automotive powder forgers exhibit lowest price sensitivity due to OEM quality agreement mandates, while steel foundries in legacy casting workflows retain highest sensitivity.
Supply Chain Analysis
China, Germany, and Japan concentrate electrolytic iron production, with Chinese operators dominating standard-grade pellet export volumes and German-Japanese specialists controlling ultra-high-purity powder output. Electrodeposition feedstock draws from high-grade magnetite concentrates in Western Australia and northern Sweden, with ferric chloride and sulfuric acid inputs sourced from regional chemical suppliers. Single-source vulnerability concentrates in electrowinning rectifier equipment and inert gas atomization systems. Distribution runs through qualified vendor panels with lot-level traceability requirements, displacing spot-market purchasing for specification-critical grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electrolytic iron market sits in early-cycle recovery as automotive lightweighting mandates restock powder metallurgy supply chains after destocking phases. Solid-state battery precursor development programs provide secondary cyclical lift through specification-driven procurement.
For Market Incumbents: Fortify backward integration into captive high-grade magnetite feedstock to offset ore concentration risk in Western Australia and northern Sweden. Deepen certification investments for FDA pharmaceutical-grade and REACH-registered tiers to defend against emerging electrodeposition specialists in India and China. Prioritize electrowinning workforce development programs to address aging specialist scarcity constraining capacity expansion. For New Entrants and Emerging Players: Service-layer gaps in 28-day delivery guarantees for lot-level ICP-MS certificates present white-space opportunities against established German and Japanese suppliers. Target Indian pharmaceutical excipient demand where CDSCO track-and-trace mandates favor qualified electrolytic iron sulfate suppliers over commodity alternatives. Pursue membrane electrode assembly electrowinning technology licensing to bypass capital intensity barriers in sub-50 ppm purity segments. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across battery-grade precursor production as membrane electrode assembly configurations reduce tank-house infrastructure requirements. Long-term viability favors precision-controlled electrowinning specialists with demonstrated scrap-input ratios above METI threshold levels. Acquisition target archetypes include non-ferrous zinc extractors with transferable electrowinning expertise and Indian pharmaceutical compounders expanding electrodeposition capacity. Monitor solid-state battery researcher procurement specifications as inflection indicator for sub-10 ppm metallic impurity demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Electrode Assembly Adoption | Reduces capital barriers for battery-grade precursor production in Korean and Japanese institutes. |
| Backward Integration into Magnetite Feedstock | Secures ore supply against Western Australia and northern Sweden concentration risk. |
| Pharmaceutical-Grade Certification Investment | Opens CDSCO and FDA-governed excipient markets with 18-24 month stability study requirements. |
| Scrap-Input Ratio Demonstration | Qualifies for METI circular-economy preferential procurement pathways in Japanese supply chains. |
| Inert Gas Atomization Capacity Expansion | Captures additive manufacturing feedstock demand for spherical powder in aerospace prototyping. |
Research Approach
Cross-validation between primary interviews with electrodeposition plant managers, powder metallurgy procurement leads at Tier 1 automotive suppliers, pharmaceutical regulatory affairs directors, and magnetic component fabrication engineers anchors the qualitative findings. Secondary validation draws from SEC filings of integrated steelmakers, ECHA REACH registration databases, FDA pharmaceutical-grade material guidance documents, and METI circular-economy policy circulars. Bottom-up capacity assessments triangulate against top-down demand modeling across powder, pellet, sheet, and bar product categories.
Sensitivity analysis around electricity tariff volatility, high-grade magnetite ore availability, and electrowinning technology substitution informs the analytical framework across the projection horizon. Segmentation dimensions modeled include purity level tiers, product format specifications, end-use application requirements, and regional regulatory cluster variations. CAGRs derive from installed capacity utilization rates, OEM quality agreement procurement volumes, and researcher pilot program scale-up trajectories. Forecast inputs incorporate solid-state battery precursor specification evolution and pharmaceutical excipient documentation requirement changes.
Forecasts assume regulatory continuity in REACH, FDA pharmaceutical-grade standards, and METI circular-economy guidelines; material policy shifts would require re-modeling. Specific risk factors include ECHA substance restriction expansion, EPA electrodeposition sludge handling rule changes, and NMPA pharmaceutical-grade material standard adoption. Recalibration cycles align with material shifts in automotive OEM lightweighting mandate enforcement and solid-state battery commercialization timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Tin Chloride Market
Metals
Galvanized Steel Market
Metals
Shipbuilding Steel Plate Market
Metals
Rhodium Market
Metals
Global Stretch Spring Wire Market
Metals
Beryllium Copper for Industrial Equipment Market
Metals
Palladium Market
Metals
Copper Clad Aluminum Wire Market
Metals
GCC Metal Forging Market
Metals
Middle-East and Africa Metal Finishing Market
Metals
Welding Materials Market
Metals
Expanded Metal Foils Market
Metals
Beryllium Copper for Telecommunication Market
Metals
Ore Metals Market
Metals
Qatar Metalworking Market
Metals
Aluminium Forging Market