
 Steel Rebar Market | 2026-2036
Steel Rebar Market Size, Share, and Industry Trends Forecast 2026-2036
Steel Rebar Market Analysis
ISO 6935 certification is rotating the competitive set toward mills with integrated melt shops and continuous casting capability. ArcelorMittal leverages its European R&D network to sustain premium deformed rebar output for seismic zones. Nucor Corporation anchors North American supply through electric arc furnace flexibility and scrap-based circularity. China Baowu Steel Group dominates domestic volume via captive iron ore and coke operations.
Steel rebar denotes ribbed steel bars, typically carbon-manganese grades with yield strengths of 400–600 MPa, produced through hot rolling or continuous casting to bond mechanically with concrete. Its primary purpose is to absorb tensile, shear, and thermal stresses within reinforced concrete structures. Deformed rebar commands the largest volume share due to universal building code acceptance, while epoxy coated rebar captures margin pools in marine and chemical exposure applications. Hot rolled output leads manufacturing process volumes, though continuous casting lines are displacing older ingot routes for yield efficiency.
ASTM A615, BIS IS 1786, and China's GB/T 1499 govern mechanical properties, bend testing, and chemical limits that determine market access for export-oriented mills. EPA enforcement on electric arc furnace emissions and India's CEA building codes for seismic zones are redirecting capital toward cleaner melt technologies and higher-grade alloy formulations. Stakeholders must monitor divergence between regional certification cycles and carbon border adjustment mechanisms to avoid stranded capacity in non-compliant product lines.
Market Dynamics
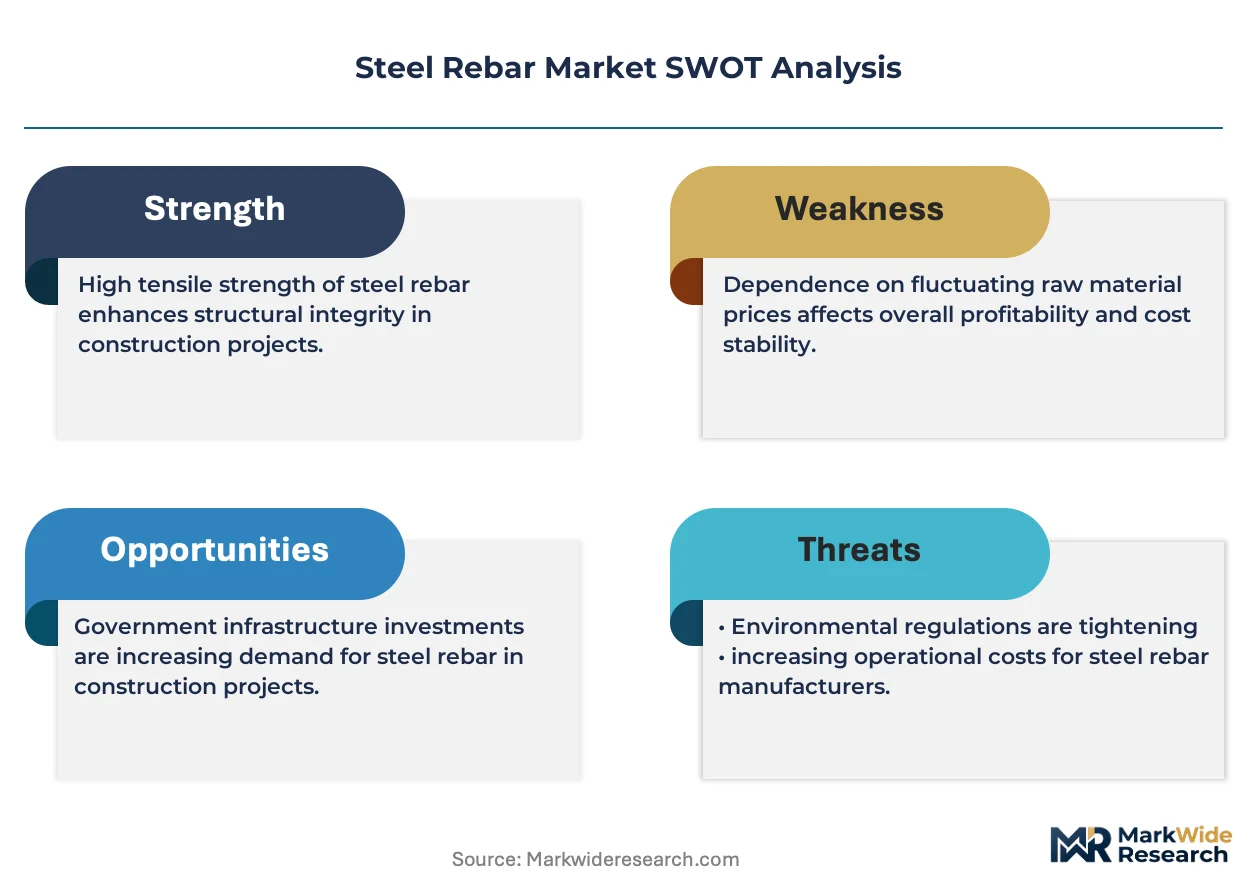
ISO 6935 certification mandates are compressing the supplier base toward mills with integrated melt shops, forcing capacity rationalization among second-tier producers lacking continuous casting infrastructure.
Growth Catalysts
- Infrastructure resilience mandates:India's CEA seismic codes and coastal protection programs in Gujarat and Maharashtra are accelerating procurement of high-tensile rebar grades for critical structures.
- GB/T 1499 revision:China's updated national standard tightens chemical composition limits and bend testing protocols, filtering import access toward quality-compliant exporters.
- Continuous casting yield efficiency:Hot rolling lines with inline quenching are capturing volume from ingot-based routes, reducing unit energy consumption and scrap generation.
Market Restraints
- Scrap price volatility:Electric arc furnace operators face margin compression when ferrous scrap inventories tighten in North American and European collection networks.
- Import certification friction:India's BIS mandatory certification scheme creates 6-12 month approval timelines for overseas mills without local testing infrastructure.
- Fiber-reinforced polymer substitution:Corrosion-resistant composite bars are displacing epoxy-coated rebar in marine piling and chemical containment applications.
Strategic Opportunities
- Southeast Asia megaproject pipelines:Indonesia's Nusantara capital relocation and Vietnam's North-South expressway corridor are concentrating demand for 500 MPa+ deformed grades.
- Carbon border adjustment positioning:EU CBAM implementation creates premium pricing windows for mills with verified Scope 1-2 emissions data and renewable energy certificates.
- Epoxy coating service integration:Coastal infrastructure programs in saline environments are expanding specification of fusion-bonded epoxy coatings for 60-year design life requirements.
Industry Challenges
- Metallurgical talent scarcity:Continuous casting process engineering expertise concentrates among aging workforces in established steel regions, constraining greenfield project staffing.
- Dual certification complexity:Mills seeking simultaneous ASTM A615 and BIS IS 1786 approval face divergent bend-test protocols and retest rules that extend qualification timelines.
- Legacy EAF emissions retrofitting:EPA enforcement on particulate and NOx limits is forcing capital allocation toward baghouse upgrades and secondary emissions capture systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steel Rebar Market |
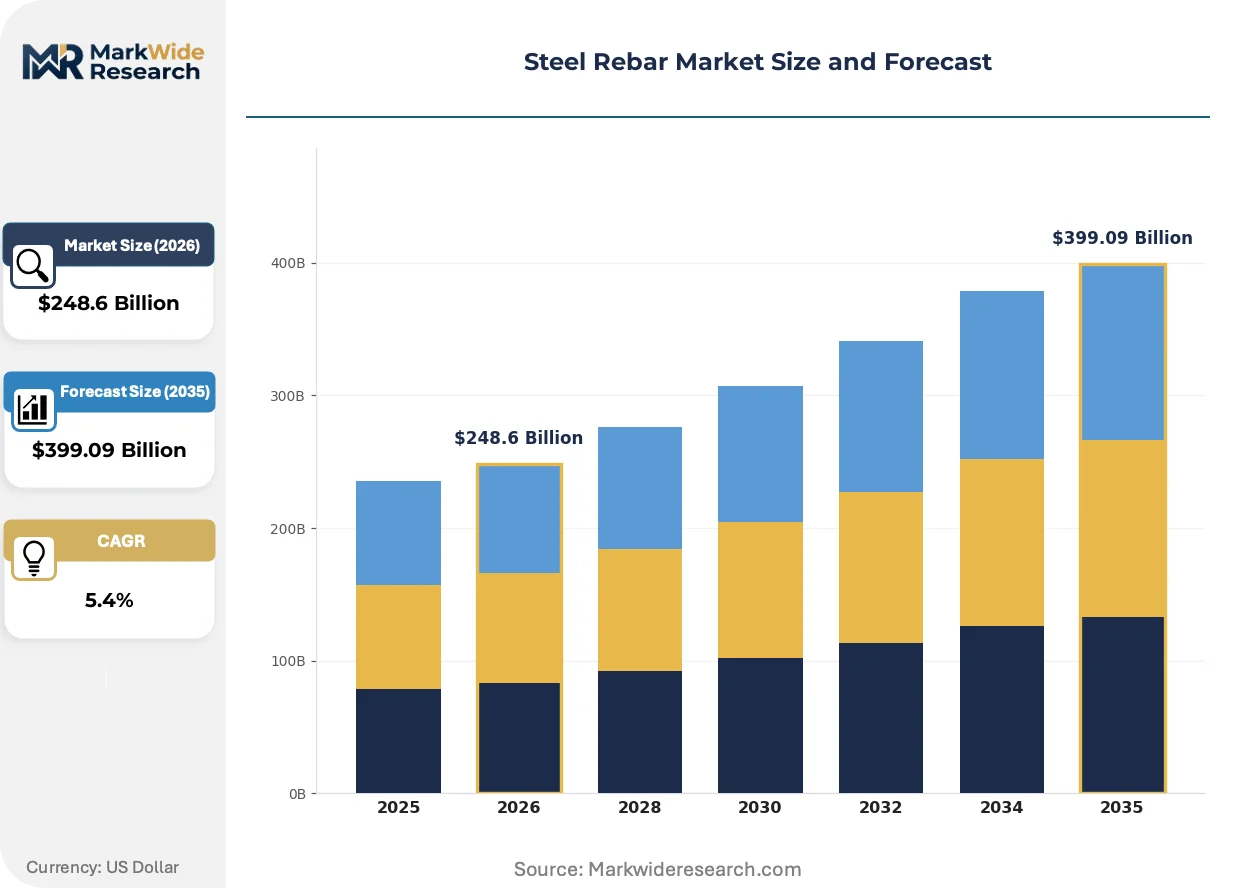
| Market Size in 2026 | $248.6 Billion |
| Market Size in 2035 | $399.09 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Deformed Rebar, Mild Steel Rebar, Epoxy Coated Rebar, Stainless Steel Rebar End User: Construction, Infrastructure, Residential, Commercial Manufacturing Process: Hot Rolled, Cold Rolled, Welded, Continuous Casting Distribution Channel: Wholesale, Retail, Online, Direct Sales |
| Companies Covered | Gerdau S.A., TATA Steel, ArcelorMittal, NLMK Group, JSW Steel, Nippon Steel Corporation, China Baowu Steel Group, Commercial Metals Company, Nucor Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steel Rebar Market Emerging Trajectories
Microalloying chemistry advances and inline thermomechanical processing are redefining grade economics, enabling higher yield strengths without costly vanadium additions while compressing heat-treatment cycles.
Quenched and self-tempered (QST) processing is supplanting traditional microalloyed routes for 500 MPa rebar production. Southeast Asian infrastructure developers are specifying QST grades for seismic-resistant designs, lured by weldability improvements and reduced alloy costs. The technology is enabling tier-two mills to bridge the quality gap without vertical integration into ferroalloy supply.
India's BIS has expanded mandatory certification to cover all imported rebar consignments, eliminating the prior exemption for project-specific approvals. The measure redirects procurement toward domestic mills with established testing laboratory relationships. Export-oriented producers in the Middle East and Southeast Asia are establishing in-country sample preparation facilities to compress approval cycles.
Engineering-procurement-construction firms are consolidating supplier panels to three approved mills per project, replacing the prior five-to-seven vendor rosters. This concentration transfers inventory risk to mills while securing volume commitments and technical collaboration on grade development. The pattern is most pronounced in India's western states, where Gujarat-based EPCs are negotiating multi-year offtake agreements tied to coastal infrastructure timelines.
Steel Rebar Market Segmentation
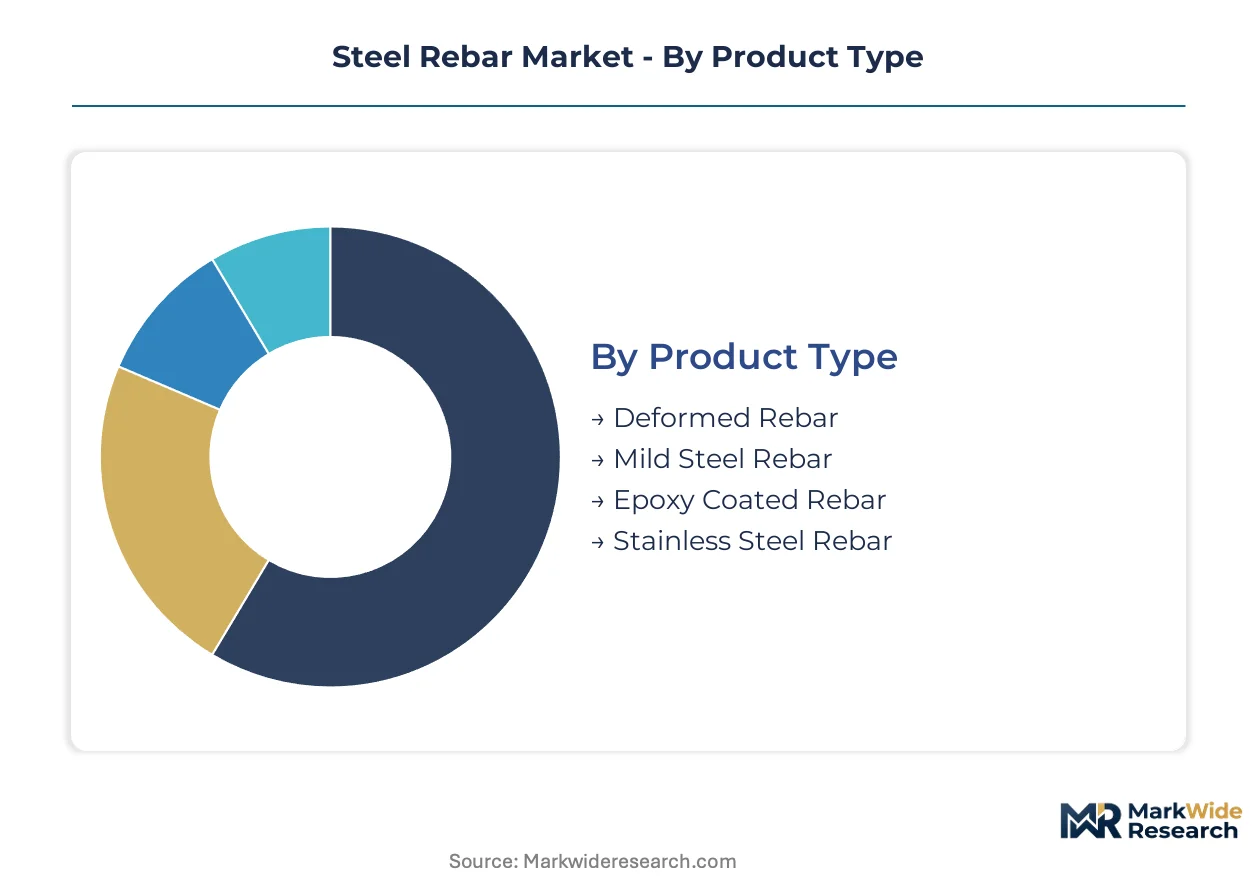
Rebar procurement channels diverge sharply by project scale and certification requirements. Large infrastructure developers negotiate direct mill contracts for certified grades, while fragmented residential builders rely on distributor networks for standard inventory.
Product Type:
Deformed and epoxy-coated grades flow through specification-driven channels requiring mill certificates, while mild steel and stainless variants reach end-users via stocked distributor inventories with shorter lead times.
- Deformed Rebar:Ribbed surface geometry ensures mechanical bonding with concrete through hot-rolled carbon-manganese processing. India's western states—Gujarat and Maharashtra—are concentrating procurement for coastal infrastructure resilience programs requiring seismic-grade certification.
- Epoxy Coated Rebar:Fusion-bonded epoxy barrier provides 60-year corrosion protection in marine and chemical exposure environments. Vietnam's North-South expressway corridor and Indonesia's Nusantara capital relocation are specifying coated grades for saline soil conditions.
- Mild Steel Rebar:Lower yield strength grades serve non-structural applications and temporary works where code compliance permits reduced specifications.
- Stainless Steel Rebar:Chromium-nickel alloy compositions address extreme chloride exposure in bridge decks and coastal nuclear facilities where lifecycle cost justifies premium material.
Deformed rebar dominates installed base. Epoxy coated rebar is where expansion concentrates.
End User:
Cost tier separation distinguishes specification-grade procurement for infrastructure megaprojects from price-sensitive residential sourcing through wholesale channels.
- Construction:General building contractors source standard grades through distributor relationships with 30-60 day inventory cycles. India's CEA seismic codes are filtering procurement toward mills with BIS IS 1786 certification and established testing laboratory partnerships.
- Infrastructure:State-owned project authorities mandate high-tensile grades with full traceability documentation. Southeast Asian megaprojects—Indonesia's capital relocation, Vietnam's expressway network—are accelerating 500 MPa+ deformed rebar procurement.
- Residential:Individual builders and small developers purchase through retail hardware networks with limited technical specification involvement.
- Commercial:Corporate facility developers balance code-minimum compliance with green building certification requirements affecting material selection.
Infrastructure commands premium pricing tiers. Residential volume is climbing the fastest.
Manufacturing Process:
Volume concentration favors continuous casting and hot-rolled output for structural grades, while specialized applications retain cold-rolled and welded process routes.
- Hot Rolled:Conventional rebar production through roughing and finishing mills delivers 400-600 MPa yield strengths with oxide scale surface finish. China's GB/T 1499 standard revision is tightening chemical composition limits and bend testing protocols for hot-rolled export grades.
- Continuous Casting:Inline quenching and thermomechanical processing achieve yield efficiency improvements and reduced unit energy consumption. QST processing is supplanting microalloyed routes for 500 MPa production in Southeast Asian seismic-resistant designs.
- Cold Rolled:Room-temperature reduction produces tighter dimensional tolerances for precision anchoring applications in precast concrete systems.
- Welded:Fabricated mesh and cage products serve reinforcement prefabrication for accelerated construction schedules in high-labor-cost markets.
Hot rolled output retains volume leadership. Continuous casting lines are gaining share fastest.
Distribution Channel:
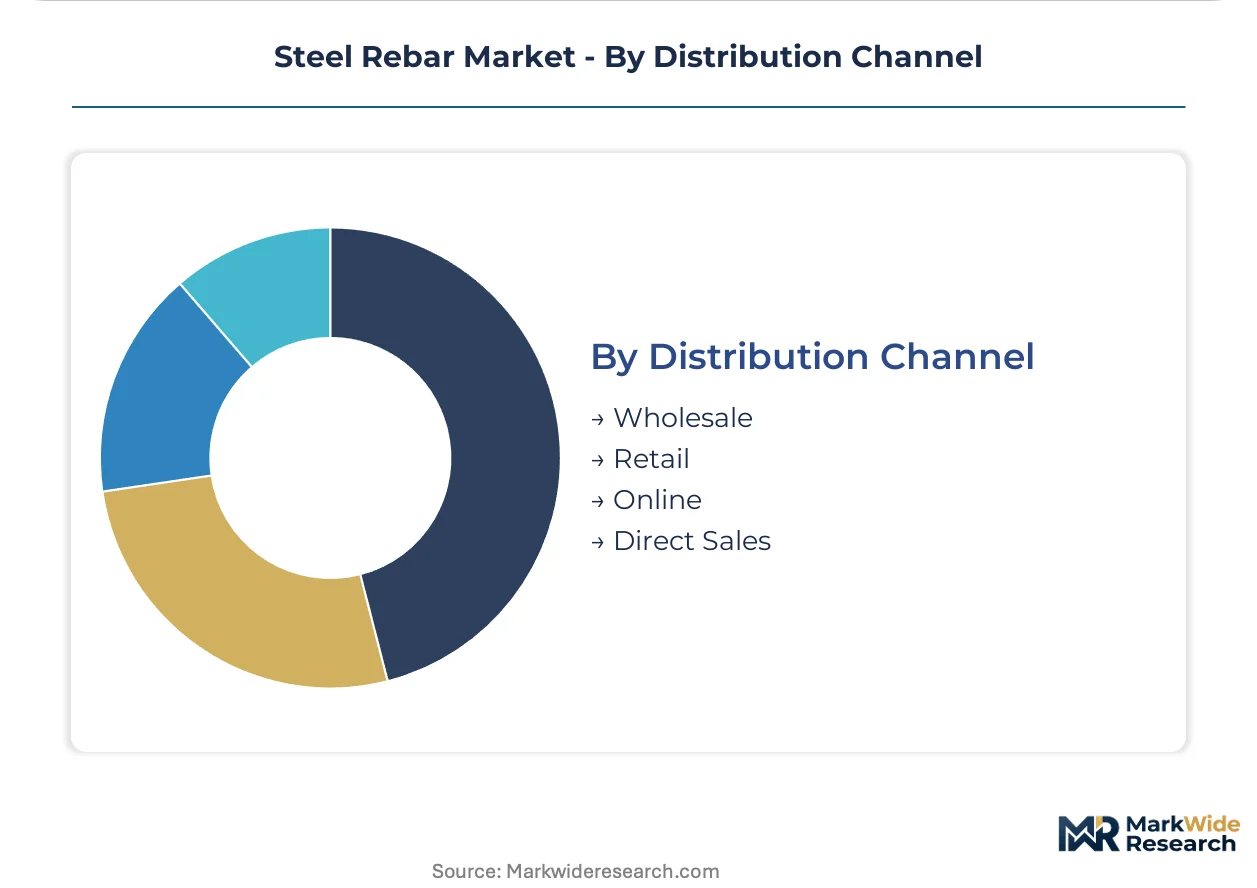
Customer type and order scale determine channel selection, with direct sales capturing project-tied volumes and wholesale serving fragmented demand.
- Direct Sales:Engineering-procurement-construction firms consolidate supplier panels to three approved mills per project, replacing five-to-seven vendor rosters. Gujarat-based EPCs are negotiating multi-year offtake agreements tied to coastal infrastructure timelines.
- Wholesale:Regional distributors maintain inventory positions for standard grades serving mid-sized contractors without mill-direct qualification.
- Retail:Hardware outlets and construction supply yards serve small-scale builders with immediate availability and limited batch sizes.
- Online:Digital platforms emerge for price discovery and standard grade procurement among contractors with established specification familiarity.
Direct sales anchor project-grade volume. Wholesale channels handle residual standard-grade demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's CEA seismic codes and China's GB/T 1499 standard revision are redirecting procurement toward certified mills with integrated melt shop capability. Infrastructure megaprojects across Southeast Asia are compressing supplier qualification timelines.
China
GB/T 1499 standard revision tightens chemical composition limits and bend testing protocols for hot-rolled export grades. MEE enforcement on electric arc furnace emissions is forcing capital allocation toward baghouse upgrades. Jiangsu and Shandong provinces concentrate capacity for high-tensile rebar serving domestic infrastructure.
India
Gujarat and Maharashtra are prioritizing coastal infrastructure resilience with CEA-mandated seismic-grade certification. BIS mandatory certification for all imported rebar consignments eliminates prior project-specific exemptions. Mumbai-based EPCs negotiate multi-year offtake agreements tied to port modernization timelines.
United States
EPA enforcement on particulate and NOx limits redirects investment toward secondary emissions capture systems. Nucor Corporation anchors North American supply through electric arc furnace flexibility. Texas and Georgia mill clusters capture infrastructure stimulus procurement for bridge and highway reinforcement.
Vietnam
North-South expressway corridor specifications demand 500 MPa+ deformed grades with full traceability documentation. QST processing adoption accelerates among domestic mills seeking seismic-resistant design approval. Ho Chi Minh City construction authorities consolidate supplier panels to three approved mills per project phase.
Indonesia
Nusantara capital relocation drives procurement of epoxy-coated rebar for saline soil conditions. BIS certification friction creates 6-12 month approval timelines for mills without local testing infrastructure. Java-based fabricators establish in-country sample preparation facilities to compress qualification cycles.
Steel Rebar Market Vendor Landscape
Player mix skews toward integrated steel producers with captive iron ore and coke operations. The supplier base compresses toward mills with continuous casting infrastructure and ISO 6935 certification. Three archetypes dominate: scale-driven integrated producers, scrap-based circularity specialists, and regional quality-compliant exporters. Competitive moves concentrate on capacity rationalization among second-tier producers and carbon border adjustment positioning for EU market access.
Among Brazilian and Indian integrated producers, Gerdau S.A., TATA Steel, and JSW Steel occupy positions defined by backward integration into ferroalloy supply and coastal mill proximity to infrastructure demand clusters. These entities exemplify the quality-compliant exporter archetype navigating dual certification complexity between ASTM A615 and BIS IS 1786 protocols. Their geographic positioning anchors supply relationships with EPC firms consolidating vendor rosters in Gujarat and Maharashtra.
| Leading Market Players |
|---|
| Gerdau S.A. |
| TATA Steel |
| ArcelorMittal |
| NLMK Group |
| JSW Steel |
| Nippon Steel Corporation |
| China Baowu Steel Group |
| Commercial Metals Company |
| Nucor Corporation |
| Others |
Supply Flow & Price Mechanics
Mill-scale economies in electric arc furnace and integrated melt shop operations compress unit fixed costs while concentrating procurement leverage among EPC firms consolidating vendor panels. China's GB/T 1499 standard revision and India's BIS certification mandates are filtering supply toward quality-compliant producers, elevating price floors for non-certified imports and reshaping competitive positioning across Southeast Asian infrastructure corridors.
Pricing Analysis
Certification level (ISO 6935/BIS IS 1786/GB/T 1499 compliance) creates the primary spread between premium project-grade and standard distributor inventory. Three-tier pricing structure across certified seismic-grade, standard deformed, and economy mild steel levels reflects divergent testing and traceability documentation requirements. Pricing pressure stems from scrap cost volatility tightening electric arc furnace margins in North American and European collection networks. Residential builders purchasing through wholesale channels exhibit highest price sensitivity, while infrastructure authorities mandate certified grades with limited substitution tolerance.
Supply Chain Analysis
Container availability fluctuations on Asia-Europe and transpacific trade lanes are extending inbound logistics cycles for mills without regional stocking partnerships. Production gravity centers on China, India, and Vietnam, with Jiangsu, Gujarat, and Ho Chi Minh City mill clusters anchoring regional supply. Raw material flows draw from Australian iron ore, Mongolian coking coal, and North American ferrous scrap networks. Single-source vulnerability concentrates in seaborne iron ore dependency for non-integrated producers. Distribution runs through direct mill contracts for infrastructure volumes and wholesale distributor networks for fragmented residential demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous casting process engineering expertise concentrates among aging workforces in established steel regions, constraining greenfield project staffing and compressing the supplier base toward incumbent mills with proven operational track records.
For Market Incumbents: Fortify quality-certification portfolios by securing dual ASTM A615 and BIS IS 1786 approvals ahead of India's expanding mandatory certification scope. Deepen backward integration into ferroalloy supply to offset vanadium cost volatility threatening microalloyed grade margins. Prioritize QST processing line investments to bridge the quality gap for tier-two competitors lacking thermomechanical capability. For New Entrants and Emerging Players: BIS certification fast-track through in-country sample preparation facilities unlocks procurement access to India's western state infrastructure programs. White-space concentration exists in epoxy coating service integration for Vietnam's North-South expressway and Indonesia's Nusantara capital relocation. Target coastal infrastructure resilience specifications in Gujarat and Maharashtra through technical collaboration with EPC firms consolidating supplier panels. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated producers with multi-year offtake agreements tied to megaproject timelines. Long-term viability favors mills with verified Scope 1-2 emissions data positioning for EU carbon border adjustment mechanisms. Acquisition focus should center on regional quality-compliant exporters navigating dual certification complexity. Monitor QST processing adoption rates as inflection indicator for seismic-grade market access.| Strategic Initiative | Industry Significance |
|---|---|
| QST Processing Line Investment | Enables 500 MPa grade production without costly vanadium additions for seismic designs. |
| Dual Certification Achievement | Unlocks access to India's BIS-mandated procurement and US infrastructure stimulus programs. |
| Backward Integration into Ferroalloys | Reduces input cost volatility for microalloyed grades serving high-tensile specifications. |
| In-Country Testing Laboratory Partnership | Compresses 6-12 month BIS approval timelines for export-oriented Middle Eastern mills. |
| Carbon Border Adjustment Positioning | Secures premium EU market access through verified emissions data and renewable energy certificates. |
Methodological Framework
A standing panel of electric arc furnace operators, continuous casting process engineers, EPC procurement directors, and BIS certification auditors provided ongoing calibration throughout the study period. Primary fieldwork combined structured interviews with mill technical directors and distributor inventory managers, validated against secondary sources including China's GB/T standard filings, India's BIS certification registries, SEC 10-K disclosures from listed producers, and customs trade data for ferrous scrap and rebar shipments. Bottom-up volume builds from mill capacity utilization and top-down demand estimates from infrastructure project pipelines were cross-referenced for convergence.
Consistency checks against World Steel Association production statistics and regional construction spending indices validated analytical outputs across the projection horizon. The modeling framework segmented volume and value by product type (deformed, epoxy coated, mild steel, stainless), end user (construction, infrastructure, residential, commercial), manufacturing process (hot rolled, continuous casting, cold rolled, welded), and distribution channel (direct sales, wholesale, retail, online). CAGRs were derived from regression analysis of historical shipment data against infrastructure investment cycles and regulatory compliance timelines, with QST processing adoption rates and BIS certification expansion schedules as key industry-specific inputs.
Decision-makers should treat outputs as directional under assumptions of continued BIS certification expansion, sustained Southeast Asian megaproject funding, and stable scrap collection network economics; material deviation in any assumption would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Ready-Mix Concrete Market
Building & Construction Materials
Fiberglass Light Poles Market
Building & Construction Materials
Europe Gypsum Board Market
Building & Construction Materials
Hydraulic Binder Market
Building & Construction Materials
Plastic Fencing Market
Building & Construction Materials
Wood Panel Market
Building & Construction Materials
Artificial Bowling Surface Market
Building & Construction Materials
Italy Ceramic Tiles Market
Building & Construction Materials
Asphalt Modifiers Market
Building & Construction Materials
Granite Flooring Market
Building & Construction Materials
Plastic Roofing Tiles Market
Building & Construction Materials
Railing Market
Building & Construction Materials
Asia-Pacific Cross-Laminated Timber Market
Building & Construction Materials
Canada Facade Market
Building & Construction Materials
Central & South America Iron Casting Market
Building & Construction Materials
Residential and Commercial Smart Glass Market