
 Railing Market | 2026-2036
Railing Market Size, Share, and Industry Trends Forecast 2026-2036
Railing Market Outlook
Market Context
A shift from single-source steel procurement to multi-source aluminum and composite sourcing is repositioning supply chain economics across the railing industry. Trex Company leverages its captive composite extrusion capacity to anchor pricing power in residential deck railings. Q-railing competes through European distribution density and stainless steel specialization. The AZEK Company extends its polymer decking footprint into coordinated railing systems, dominating the bundled outdoor-living segment.
Technical Definition and Segment Structure
Railing denotes a barrier system comprising posts, handrails, infill panels, and mounting hardware, engineered to resist specified lateral loads typically measured in pounds per linear foot while providing fall protection at elevated walking surfaces. Metal railings incorporate aluminum alloys with powder-coated finishes or 316-grade stainless steel for coastal corrosion resistance, whereas glass infill systems employ laminated or tempered panels to preserve sightlines in commercial atriums and waterfront properties. Metal railings occupy the largest installed base due to code familiarity and contractor acceptance, while glass segments command premium positioning in hospitality and high-rise residential towers where aesthetic transparency drives specification. Vinyl railings sustain volume leadership in suburban residential replacement cycles, though wood faces erosion from maintenance-cost sensitivity among homeowners.
Regulatory Framework and Outlook
The International Code Council publishes the International Building Code, which governs guardrail height, spacing, and load requirements across US jurisdictions, while the European Committee for Standardization maintains EN 1090 for structural steel and aluminum fabrication compliance. OSHA mandates specific fall-protection thresholds for industrial and commercial installations, creating a dual compliance layer that shapes product design and liability exposure. Stakeholders must monitor evolving amendments to national building codes and energy-efficiency standards that increasingly influence material selection for exterior building envelope components.
Market Dynamics
The International Building Code's 2024 load-bearing amendments are forcing wholesale redesigns of guardrail anchoring systems across US residential and commercial construction, compressing certification timelines and elevating engineering costs for manufacturers.
Growth Catalysts
- Suburban Retrofit Cycles:Aging deck infrastructure across US exurban counties is triggering replacement demand for low-maintenance vinyl and composite railings.
- OSHA Fall-Protection Thresholds:Stricter workplace safety mandates for industrial mezzanines and elevated platforms are expanding specification volume for steel guardrail systems.
- Glass Infill Aesthetics:Hospitality developers in coastal Florida and California are specifying laminated glass panels to preserve sightlines in high-rise balconies.
Market Restraints
- Aluminum Price Volatility:LME aluminum futures swings are compressing margins for extrusion-dependent railing fabricators.
- Coastal Corrosion Costs:316-grade stainless steel sourcing concentrates in European and Asian mills, exposing US fabricators to tariff and freight risk.
- Wood Substitution Decline:Pressure-treated lumber maintenance costs are accelerating homeowner migration to synthetic alternatives, eroding traditional carpentry contractor relationships.
Strategic Opportunities
- German Urban Renewal:EN 1090-compliant structural steel fabrication capacity is undersupplied relative to Berlin and Munich high-rise pipeline.
- Integrated Outdoor Living:Bundled deck-railing-lighting systems are capturing premium positioning in US sunbelt residential markets.
- Modular Industrial Guardrails:Bolt-free, tool-free installation systems are penetrating warehouse and logistics verticals seeking rapid reconfiguration.
Industry Challenges
- Code Certification Lag:Multi-jurisdictional IBC amendment cycles delay product launches by 8-14 months.
- Skilled Installer Scarcity:Glass panel alignment and structural anchoring require specialized glazing and rigging expertise that contracting pools lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Railing Market |
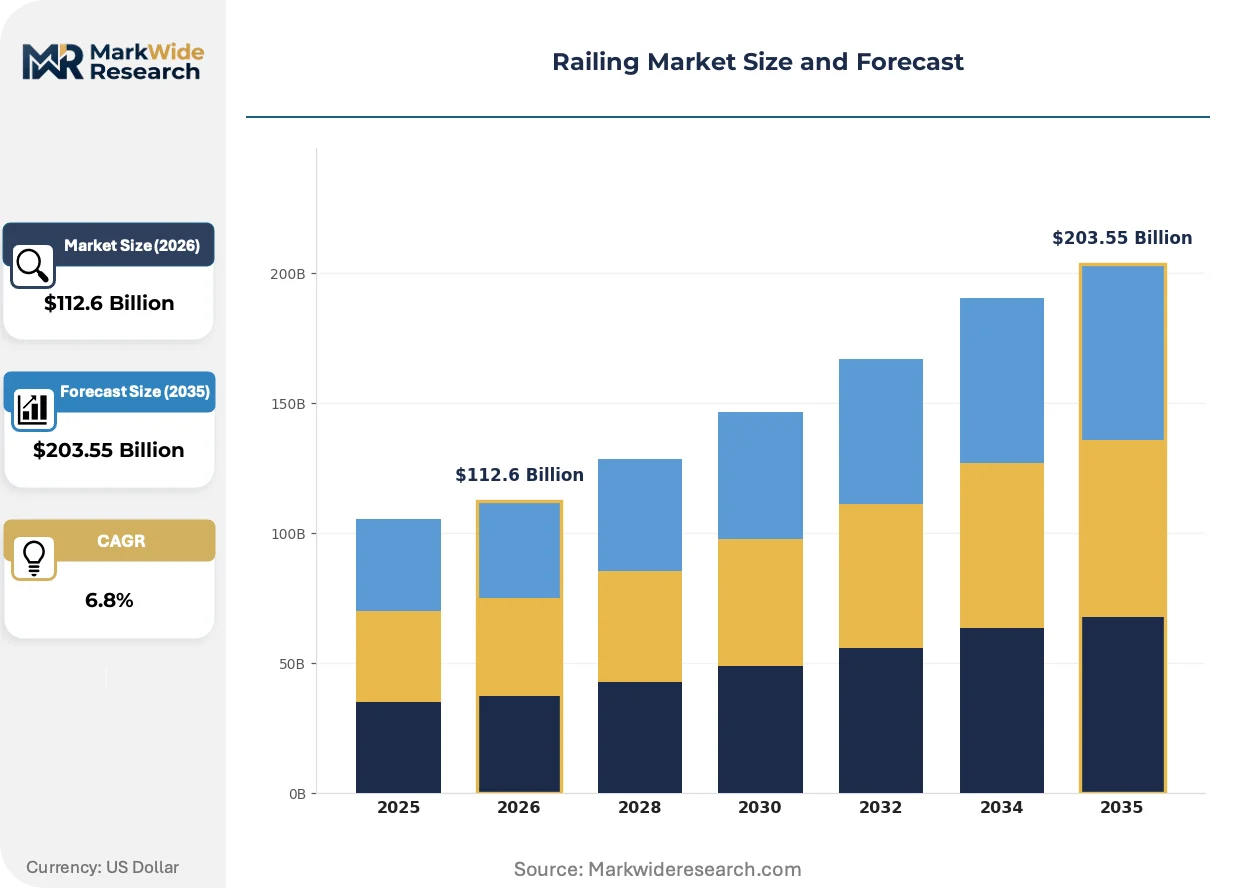
| Market Size in 2026 | $112.6 Billion |
| Market Size in 2035 | $203.55 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wood, Metal, Vinyl, Glass Installation Type: Balcony, Staircase, Deck, Pool End User: Residential, Commercial, Institutional, Industrial Design Style: Modern, Traditional, Rustic, Contemporary |
| Companies Covered | Fortress Railing Systems, Q-railing, Trex Company, Feeney Incorporated, Century Aluminum Railing, The AZEK Company, The Wagner Companies, Deckorators, C.R. Laurence (CRL), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Railing Market Strategic Shifts
Material science advances and regulatory tightening are converging to redefine performance benchmarks and procurement patterns across residential, commercial, and industrial railing segments.
Pultruded fiberglass-reinforced polymer (FRP) railing systems are electrifying corrosion-resistant infrastructure specifications. Water treatment facilities and coastal boardwalk authorities in Florida and the Gulf Coast are specifying FRP for salt-air durability. The technology is electrifying competitive positioning by enabling 50-year service life warranties that aluminum and steel cannot match.
REACH chemical restriction expansions are reshaping powder-coat formulation requirements across European supply chains. Manufacturers serving Germany and France must now certify zero heavy-metal content in architectural finishes. The regulation is compressing supplier pools and elevating compliance costs for mid-tier fabricators without in-house coating capacity.
Direct-to-contractor digital specification platforms are fragmenting traditional two-step distribution. Builders and remodelers in Texas and Arizona are bypassing lumberyard intermediaries to configure custom railing systems online. The channel shift is most visible in suburban residential replacement cycles where speed and visual configuration tools drive selection.
Railing Market Segmentation
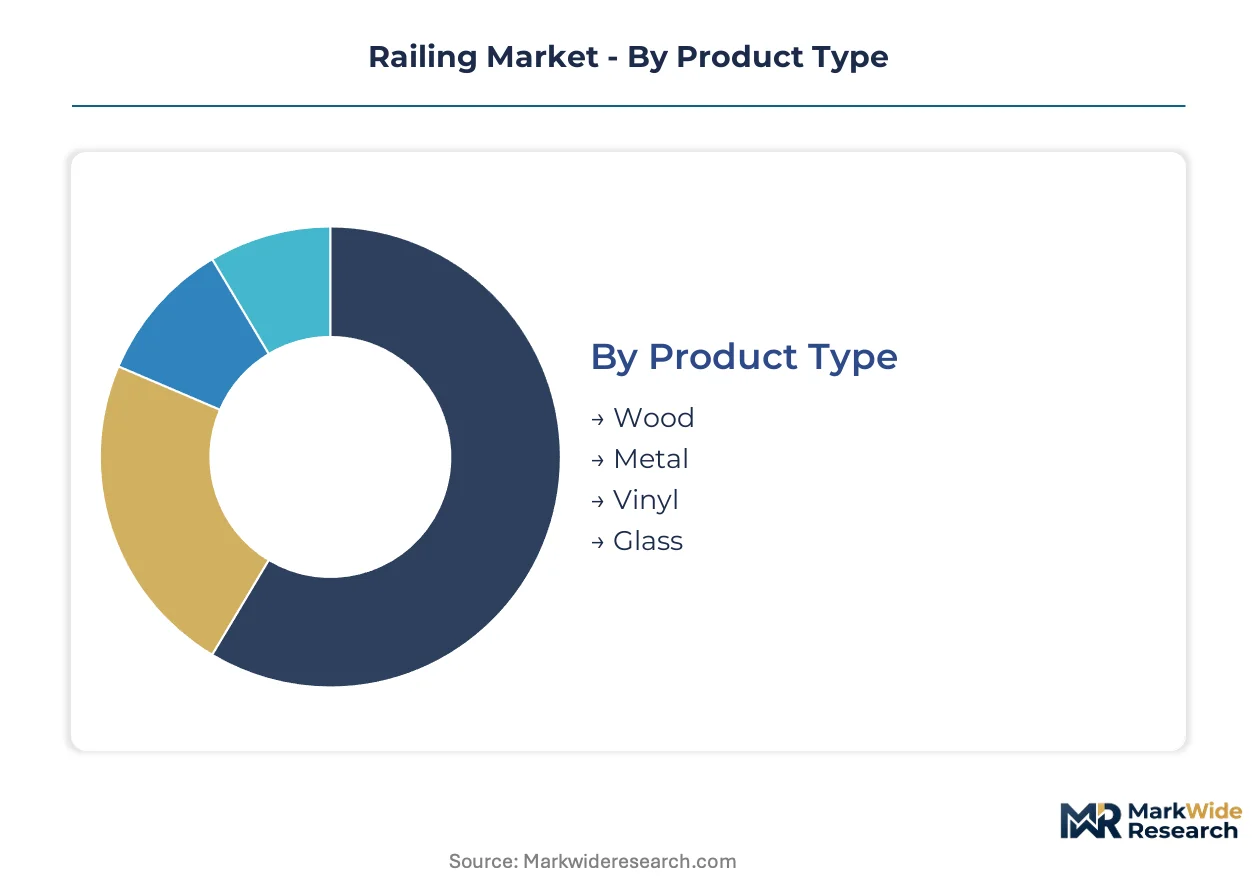
Segmentation in the railing industry reveals how certification requirements, material specifications, and installation contexts fragment procurement patterns. Manufacturers must align product portfolios with distinct code compliance pathways rather than pursuing universal platform strategies.
Product Type:
Metal railings carry EN 1090 structural steel certification burdens in Europe and IBC load-testing requirements in the United States, while glass systems demand laminated safety glass documentation and coastal wind-load engineering. Wood faces reduced regulatory scrutiny but carries warranty liability exposure from rot and insect damage.
- Metal:Aluminum alloys with powder-coated finishes and 316-grade stainless steel dominate commercial and coastal specifications. Demand concentrates in German urban renewal projects and Florida waterfront developments where corrosion resistance commands premium positioning. IBC load-bearing amendments are forcing redesigns of anchoring systems and compressing certification timelines.
- Vinyl:Polyvinyl chloride formulations with UV stabilizers and impact modifiers serve suburban residential replacement cycles. Demand clusters in US exurban counties where low-maintenance requirements drive homeowner migration from pressure-treated lumber. REACH chemical restrictions are elevating formulation compliance costs for European suppliers.
- Wood:Pressure-treated lumber and cedar species face accelerating substitution from synthetic alternatives. Maintenance-cost sensitivity among homeowners erodes traditional carpentry contractor relationships in North American residential markets.
- Glass:Laminated and tempered panels preserve sightlines in hospitality and high-rise residential towers. Coastal Florida and California developers specify these systems for balcony applications where aesthetic transparency drives specification.
Metal sits at the top of the volume ranking, with glass climbing the fastest.
Installation Type:
Cost tier differentiation separates high-engineering commercial applications from standardized residential replacements. Deck and pool installations command premium hardware specifications for moisture and chemical exposure, while staircase systems face the most stringent code enforcement.
- Deck:Elevated residential platforms require guardrail systems resisting lateral loads measured in pounds per linear foot. US sunbelt markets drive bundled deck-railing-lighting configurations as outdoor living spaces expand.
- Staircase:Vertical circulation barriers face the tightest IBC height and spacing requirements. Commercial and institutional specifications concentrate engineering resources on handrail continuity and graspability standards.
- Balcony:High-rise residential and hospitality applications prioritize fall protection with minimal visual obstruction. Laminated glass infill penetrates this segment fastest where sightline preservation justifies cost premiums.
- Pool:Chlorine and saltwater exposure demand corrosion-resistant materials and specialized anchoring hardware. Florida and Gulf Coast municipalities specify pultruded FRP systems for boardwalk and pool enclosure durability.
Deck captures the largest installed base, with pool applications gaining share fastest on coastal infrastructure investment.
End User:
Customer type determines procurement channel and specification authority. Residential buyers prioritize visual configuration tools and speed, while industrial purchasers emphasize OSHA compliance documentation and rapid installation protocols.
- Residential:Single-family and multifamily property owners drive vinyl and composite volume through retrofit cycles. Direct-to-contractor digital platforms fragment traditional lumberyard distribution in Texas and Arizona markets.
- Commercial:Hospitality developers and office landlords specify glass and stainless steel for aesthetic positioning. EN 1090 compliance requirements in Germany and IBC amendments in the United States elevate engineering costs.
- Institutional:Schools, hospitals, and government facilities prioritize durability and maintenance cost predictability. Procurement runs through formal specification processes with extended approval timelines.
- Industrial:Warehouse and logistics operators seek bolt-free, tool-free guardrail systems for rapid reconfiguration. OSHA fall-protection mandates for mezzanines and elevated platforms expand specification volume.
Residential holds the volume lead, with industrial expanding most quickly on warehouse construction.
Design Style:
Maturity curves separate established traditional specifications from emerging contemporary preferences. Modern and contemporary styles command material premiums while traditional and rustic segments compete on installation efficiency.
- Traditional:Ornamental metalwork and classical proportions dominate historic district renovations and conservative suburban developments. Specification relies on contractor familiarity rather than engineering differentiation.
- Modern:Clean lines and minimal visual mass drive aluminum and glass combinations. Urban residential towers in Berlin, Munich, and coastal US cities specify these systems for architectural coherence.
- Contemporary:Mixed material palettes and asymmetric compositions serve custom residential and boutique hospitality. Visual configuration tools enable homeowner participation in design decisions.
- Rustic:Reclaimed wood and wrought-iron aesthetics target vacation properties and rural estates. Limited volume concentrates in mountain and lake region construction.
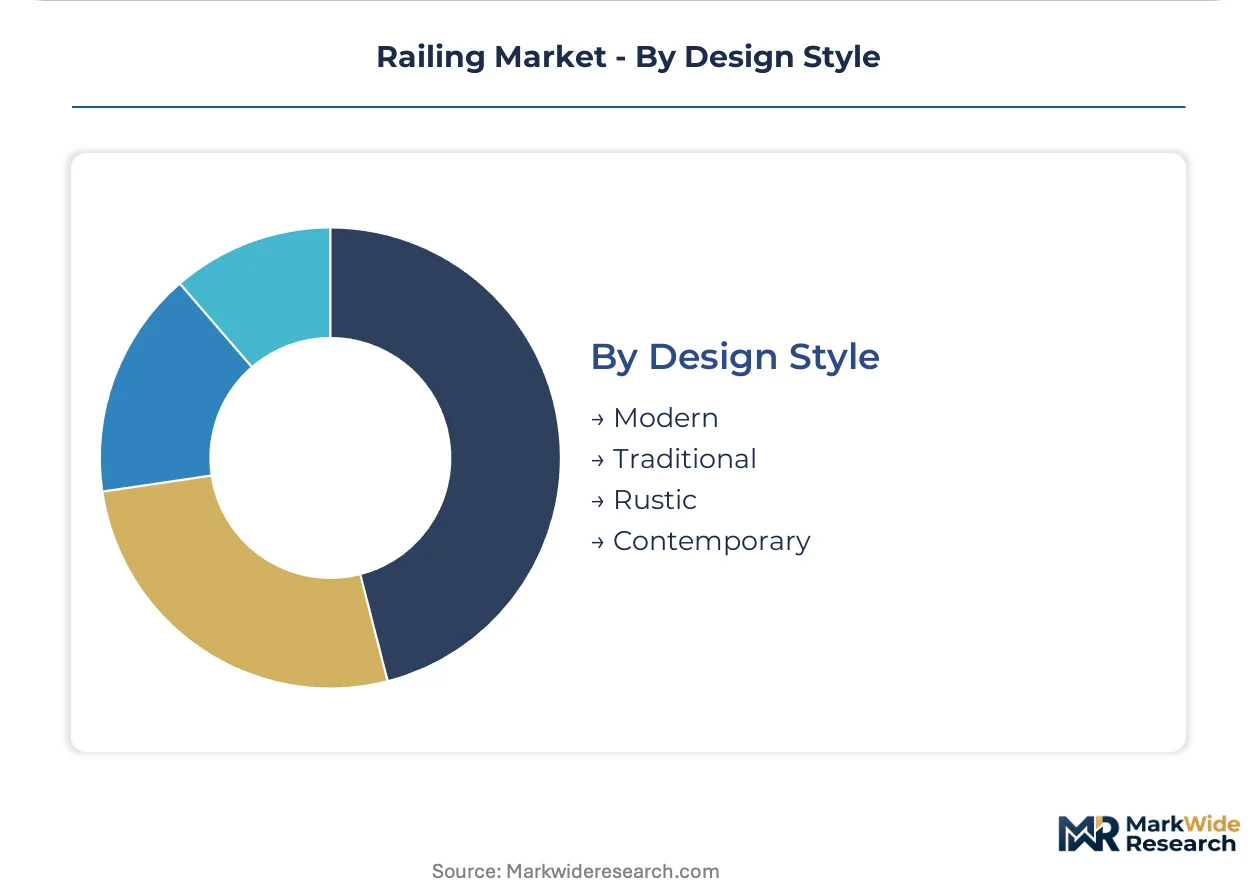
Traditional maintains volume dominance, with modern gaining specification share fastest in urban high-rise residential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Dallas-Fort Worth metroplex anchors North American railing fabrication capacity, with extrusion plants and powder-coating facilities clustering along Interstate 35 to serve sunbelt residential construction. Code harmonization pressures are intensifying across jurisdictions, reshaping where manufacturers locate testing and certification operations.
United States
Suburban retrofit cycles in Texas and Arizona are accelerating vinyl and composite railing volume through direct-to-contractor digital platforms. OSHA fall-protection mandates for warehouse mezzanines expand industrial guardrail specifications. The Southeast Florida corridor concentrates glass infill engineering for high-rise balcony applications.
Germany
EN 1090-compliant structural steel fabrication capacity remains undersupplied relative to Berlin and Munich high-rise construction pipelines. REACH chemical restrictions are compressing powder-coat supplier pools for architectural finishes. The Rhine-Ruhr industrial belt hosts specialized stainless steel railing fabricators serving Dutch and Belgian export markets.
China
GB standards for building envelope safety are tightening guardrail load-bearing requirements in tier-one cities. Yangtze River Delta manufacturers dominate aluminum extrusion output for Asia-Pacific export. Shenzhen and Guangzhou developers specify glass balustrade systems for luxury residential towers.
Canada
Provincial building code adoption of NBC guardrail amendments lags US IBC cycles by 12-18 months, delaying product launches. Ontario's Golden Horseshoe concentrates residential railing distribution through lumberyard networks. Vancouver coastal projects specify 316-grade stainless steel for salt-air corrosion resistance.
United Arab Emirates
Dubai's high-rise hospitality pipeline commands premium glass and stainless steel railing specifications for balcony and atrium applications. Abu Dhabi municipal codes are aligning with European EN standards for structural aluminum fabrication. Sharjah manufacturing zones host powder-coating facilities serving GCC export markets.
Railing Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue modular industrial guardrail systems and integrated outdoor-living bundles. The vendor base stratifies across three maturity levels: integrated material suppliers with captive extrusion capacity, specialized fabricators focused on code-certified commercial installations, and regional distributors leveraging digital specification platforms. Two dominant competitive moves are reshaping positioning: backward integration into polymer and composite raw material production, and geographic expansion through EN 1090-certified European fabrication capacity.
Among US-based material-integrated suppliers, Trex Company and The AZEK Company exemplify the bundled outdoor-living archetype, anchoring residential deck-railing coordination through captive polymer formulation and extrusion infrastructure. Q-railing occupies a position within the European commercial-specialist tier, representing stainless steel fabrication density and distribution network depth across German-speaking markets. Fortress Railing Systems sits within the mid-cap regional fabricator segment, illustrating powder-coated aluminum specialization for suburban replacement cycles.
| Leading Market Players |
|---|
| Fortress Railing Systems |
| Q-railing |
| Trex Company |
| Feeney Incorporated |
| Century Aluminum Railing |
| The AZEK Company |
| The Wagner Companies |
| Deckorators |
| C.R. Laurence (CRL) |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap fabricators with multi-generational ownership in the US Southeast and Germany's Rhine-Ruhr belt maintain pricing discipline through captive powder-coating capacity and long-term aluminum extrusion contracts. Their ownership structure insulates margin targets from quarterly earnings pressure, enabling sustained investment in IBC and EN 1090 certification ahead of price-competitive rivals.
Pricing Analysis
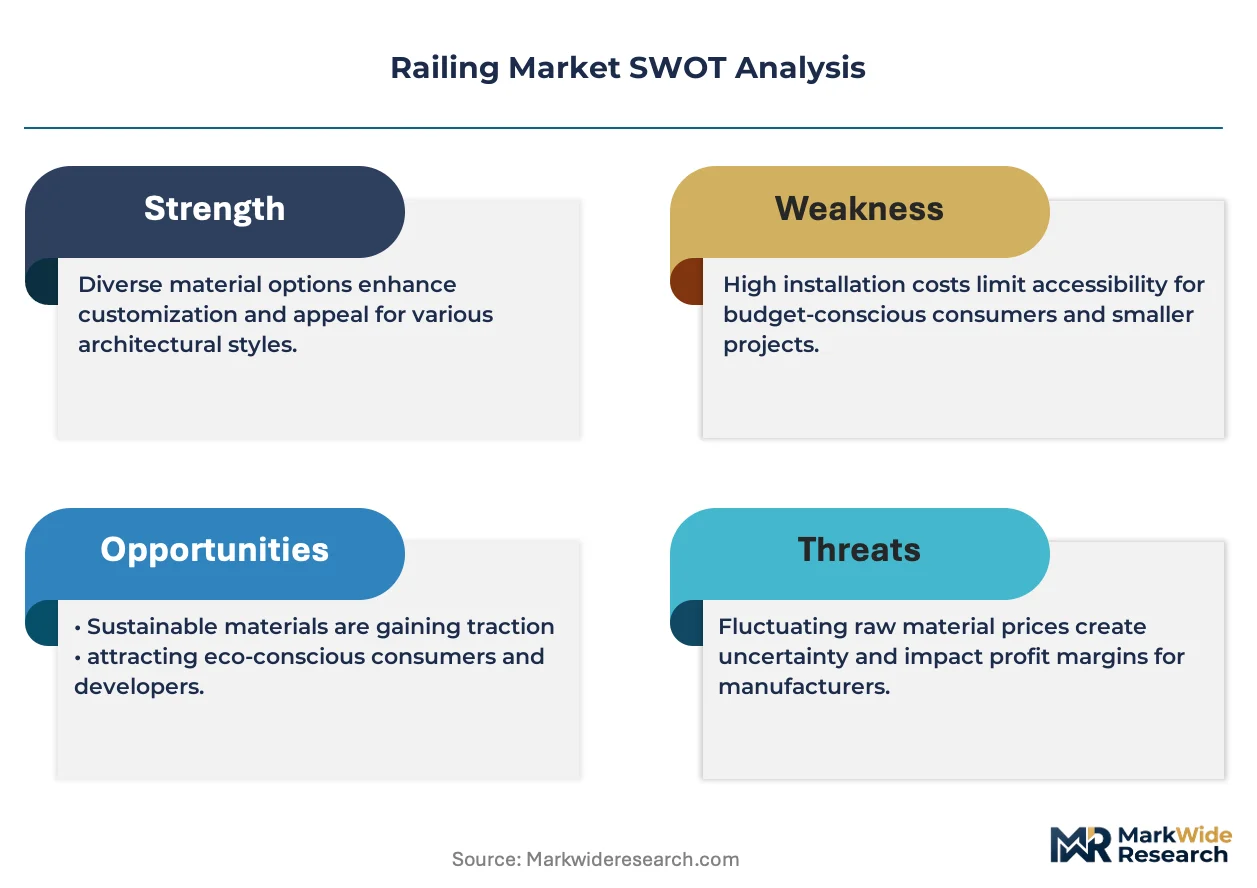
Input-cost pass-through from LME aluminum futures and 316-grade stainless steel spot markets governs contract renegotiation cycles for extrusion-dependent fabricators. Three-tier pricing structure across premium, standard, and economy levels separates glass infill systems with laminated safety documentation from commodity vinyl residential replacements. Pricing pressure stems from aluminum price volatility compressing margins for mid-tier suppliers without captive smelter relationships. Industrial warehouse buyers exhibit highest price sensitivity due to volume procurement protocols, while hospitality developers in coastal Florida and California absorb premiums for aesthetic transparency.
Supply Chain Analysis
Direct-to-contractor digital platforms and traditional two-step lumberyard distribution split downstream channel control across residential replacement cycles. Raw material sourcing draws from Yangtze River Delta aluminum extrusion, European 316-grade stainless steel mills, and US Gulf Coast pultruded FRP manufacturing. Distribution runs through Dallas-Fort Worth extrusion clusters for sunbelt residential construction and German EN 1090-certified fabricators for Berlin and Munich high-rise pipelines. Tariff exposure on European stainless steel concentrates supply risk for US coastal fabricators serving Florida waterfront developments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in railing systems rests on substitution-driven cost-down in vinyl formulations and premium-tier capture in glass infill specifications for hospitality towers.
For Market Incumbents: Acquire EN 1090-certified fabrication capacity in Germany to anchor European urban renewal positioning. Consolidate powder-coat formulation capabilities in-house to offset REACH compliance cost compression. Defensive moves must counter direct-to-contractor digital platforms fragmenting traditional lumberyard distribution in Texas and Arizona. For New Entrants and Emerging Players: Underserved industrial warehouse operators seeking bolt-free, tool-free guardrail reconfiguration present white-space penetration potential. Modular industrial guardrail systems for OSHA-mandated mezzanine applications offer fastest specification velocity. Channel entry through digital configuration platforms targeting Texas and Arizona residential retrofit cycles bypasses entrenched lumberyard intermediaries. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap aluminum fabricators without captive extrusion capacity or IBC certification infrastructure. Five-to-ten year viability favors suppliers with backward integration into polymer formulation and coastal corrosion-resistant product portfolios. Signal to monitor: IBC amendment adoption velocity across US jurisdictions compressing certification timelines for non-compliant product lines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Formulation | Trex Company and AZEK anchor bundled outdoor-living pricing power through captive extrusion infrastructure. |
| EN 1090 Certification Investment | German urban renewal pipelines reward compliant structural steel fabricators with undersupplied specification volume. |
| Direct-to-Contractor Platform Launch | Digital specification tools in Texas and Arizona fragment traditional lumberyard distribution for residential retrofit cycles. |
| Pultruded FRP Capacity Expansion | Florida and Gulf Coast municipalities specify salt-air durable systems for 50-year service life warranties. |
| Glass Infill Engineering Acquisition | Coastal high-rise hospitality developers in Florida and California prioritize laminated panel sightline preservation. |
Study Parameters
Multiple input streams — executive interviews with railing fabricators and extrusion plant managers, regulatory documentation from ICC and CEN, customs trade data on aluminum and stainless steel flows — were reconciled through bottom-up and top-down triangulation. Primary fieldwork engaged product engineering directors at captive polymer suppliers, commercial specification managers at hospitality developers, and procurement leads at industrial warehouse operators. Secondary validation drew from IBC amendment filings, EN 1090 certification registries, OSHA fall-protection enforcement data, and SEC disclosures from publicly traded building products companies.
Historical volume trajectories were cross-referenced against panel input from industry participants to anchor projection assumptions across the analysis window. Segmentation modeling incorporated product type, installation context, end-user procurement authority, and regional regulatory cluster. CAGRs were derived from slope analysis of material substitution curves and code amendment adoption patterns. Industry-specific forecast inputs included suburban deck infrastructure age profiles and coastal high-rise construction pipelines in Florida, California, and German tier-one cities.
Underlying measurement precision varies by segment; vinyl residential replacement and aluminum commercial specifications carry tighter precision than emerging FRP and glass infill categories. Forecasts reflect assumptions on regulatory amendment adoption timelines, raw material price stabilization, and installer labor availability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
North America Concrete Sealer Market
Building & Construction Materials
Pocket Door Market
Building & Construction Materials
Indonesia Cement Market
Building & Construction Materials
Cement Sacks Market
Building & Construction Materials
GRC Conduit Fittings Market
Building & Construction Materials
Africa Construction Chemicals Market
Building & Construction Materials
US Parking Deck Coatings Market
Building & Construction Materials
India Roofing Market
Building & Construction Materials
Building Acoustic Insulation Market
Building & Construction Materials
Global Roofing Market
Building & Construction Materials
Warm Mix Asphalt Market
Building & Construction Materials
Geosynthetics Market
Building & Construction Materials
North America Rainscreen Cladding Market
Building & Construction Materials
Global Concrete Repair Mortars Market
Building & Construction Materials
Sanitary Ware Market
Building & Construction Materials
Drywall and Gypsum Board Market