
 Sheet Piling Market | 2026-2036
Sheet Piling Market Size, Share, and Industry Trends Forecast 2026-2036
Sheet Piling Market Analysis
Port and marine infrastructure is pivoting toward deeper-water berth construction and flood defense upgrades, which intensifies demand for high-section-modulus sheet piles. ESC Group leverages its integrated manufacturing footprint across Southeast Asian fabrication hubs to serve harbor authority contracts. Nippon Steel & Sumitomo Metal sustains metallurgical leadership through proprietary high-yield-strength steel grades that reduce pile section requirements. Valiant Steel anchors North American supply security with domestic mill capacity and waterfront distribution terminals.
Sheet piling comprises interlocking structural sections—manufactured from hot-rolled steel, extruded vinyl, reinforced concrete, or fiber-reinforced composites—that are driven or vibrated into soil to form continuous retaining walls or cut-off barriers, with steel variants typically achieving yield strengths of 355–460 MPa and section moduli exceeding 5,000 cm³/m for heavy-duty marine applications. Steel sheet piling dominates installed volume due to its recyclability and structural efficiency in deep excavations, while vinyl segments occupy niche positions in chemically aggressive environments where corrosion resistance outweighs stiffness requirements. Heavy Duty and Ultra Heavy Duty load capacity tiers concentrate margin pools as coastal protection schemes and port deepening projects specify thicker interlocks and higher moment capacity.
ISO 12944 corrosion protection standards, EU CE marking under the Construction Products Regulation, and US Army Corps of Engineers EM 1110-2-2504 design manuals collectively govern material certification, coating durability benchmarks, and structural design methodologies for permanent marine installations. China's GB/T 20934 national standard and MEE environmental impact assessment protocols further condition product acceptance for domestic infrastructure tenders. Stakeholders must monitor evolving coastal resilience funding mechanisms and carbon-border adjustment trajectories that will restructure competitive cost positions between imported and regionally manufactured pile systems.
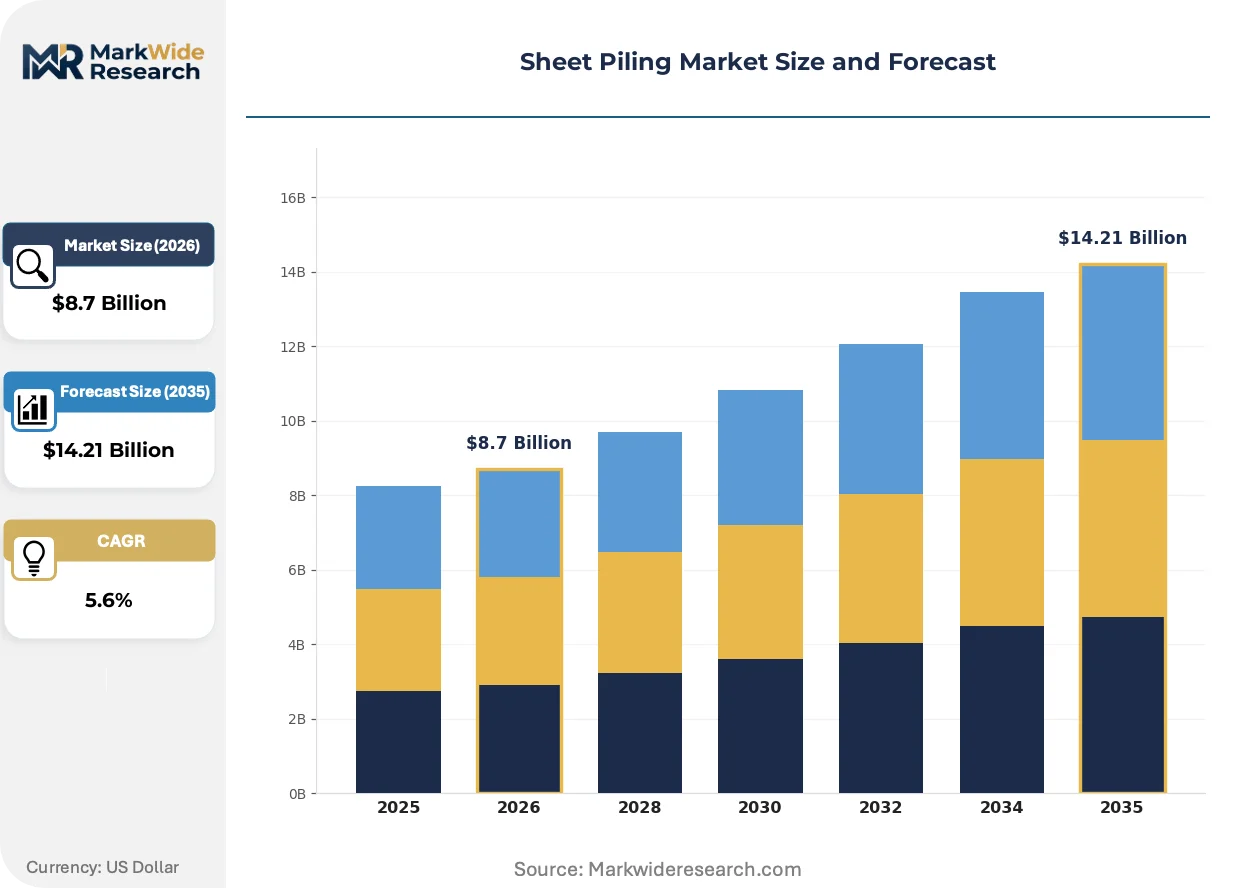
Market Dynamics
Port deepening projects and coastal resilience mandates are compressing project timelines and elevating performance specifications for interlocking retaining wall systems. Contractors now specify higher-yield-strength grades and corrosion-resistant coatings as standard rather than optional upgrades.
Growth Catalysts
- EU Green Deal coastal adaptation funding:Member states are unlocking capital for flood defense upgrades that specify permanent steel sheet pile installations with 100-year design lives.
- Fiber-reinforced composite pilings:Marine contractors in chemically aggressive ports are specifying vinyl and FRP alternatives where steel corrosion rates exceed maintenance budgets.
- China's MEE environmental protocols:Domestic infrastructure tenders now require lifecycle carbon assessments that favor recyclable steel piling over concrete alternatives.
Market Restraints
- Scrap steel price volatility:Electric arc furnace operators face margin compression when ferrous scrap benchmarks spike above hot-rolled coil contract prices.
- Asian mill concentration:Over half of global sheet pile rolling capacity sits within three integrated steel groups, creating supply security concerns for European harbor authorities.
- High-section-modulus fabrication limits:Only a handful of rolling mills can produce ultra-heavy-duty sections exceeding 6,000 cm³/m, constraining availability for megaproject tenders.
Strategic Opportunities
- US Army Corps coastal resilience appropriations:Post-hurricane reconstruction programs are specifying steel sheet pile floodwalls for Gulf Coast and Eastern Seaboard protection schemes.
- Modular combined wall systems:Integration of steel sheet piles with tubular king piles is opening design options for deeper berth constructions without custom fabrication.
- Carbon-border adjustment mechanisms:EU importers of Chinese-produced piling face exposure to embedded emissions tariffs, creating openings for regional European mill capacity.
Industry Challenges
- Geotechnical design software integration:Contractors struggle to align BIM models with proprietary pile driving analysis tools from equipment manufacturers.
- ISO 12944 coating inspector certification:Qualified applicators for C5-M marine corrosion categories remain scarce in emerging port construction markets.
- Interlock tolerance standardization:Metric and imperial section profiles create field-fit complications when combining European and North American pile inventories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sheet Piling Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel, Vinyl, Concrete, Composite Installation Method: Driving, Vibrating, Jetting, Excavating End User: Coastal Protection, Construction, Environmental, Transportation Load Capacity: Light Duty, Medium Duty, Heavy Duty, Ultra Heavy Duty |
| Companies Covered | ESC Group, Northwest Pipe Company, Nippon Steel & Sumitomo Metal, EVRAZ North America, Valiant Steel, JFE, TMK IPSCO, Shoreline Steel, Meever, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sheet Piling Market Emerging Trajectories
Digital fabrication and predictive corrosion modeling are compressing design-to-installation cycles for permanent marine structures. Material science advances are enabling thinner sections to achieve equivalent structural performance.
High-strength low-alloy steel grades with yield points exceeding 460 MPa are unifying structural and economic performance targets for deep excavation projects. Dutch harbor authorities specify these grades for Rotterdam Maasvlakte expansions to reduce pile count and driving energy. The technology is unifying contractor preferences around reduced-section solutions that lower installed cost per meter of wall.
China's GB/T 20934 national standard revisions are tightening dimensional tolerances and interlock geometry specifications for domestic infrastructure tenders. MIIT enforcement of these standards is disqualifying non-compliant imports from Southeast Asian fabricators. Domestic contractors must now source from certified mills with in-house rolling and coating capabilities.
Harbor authorities are consolidating procurement around design-build-operate contracts that bundle piling supply with long-term corrosion monitoring. European port operators lead this shift, replacing fragmented material-only tenders with integrated performance agreements. The Netherlands and Belgium exhibit the fastest contract structure evolution, with Rotterdam and Antwerp authorities requiring 25-year coating warranties as standard.
Sheet Piling Market Segmentation
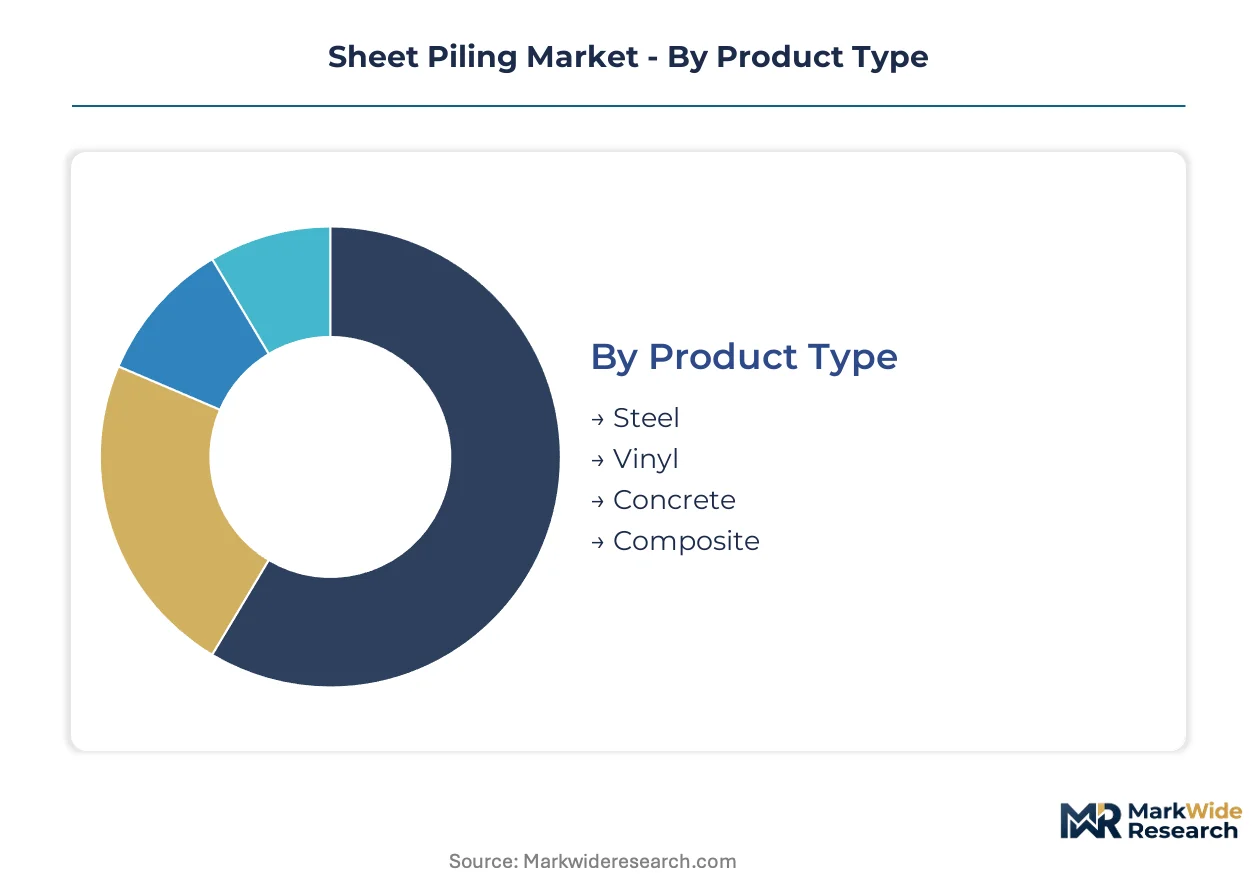
Sheet piling segmentation reveals how certification burdens, installation constraints, and load requirements reshape procurement patterns across marine and civil infrastructure. Material selection and capacity tiers determine which projects qualify for public agency tenders versus private development work.
Product Type:
ISO 12944 corrosion categories and national construction product regulations impose divergent certification timelines across material classes, with steel requiring CE marking under EU CPR and vinyl demanding REACH compliance for polymer additives.
- Steel:Hot-rolled structural sections achieve yield strengths of 355–460 MPa with full recyclability credentials that satisfy China's MEE lifecycle carbon protocols. Rotterdam harbor authorities specify high-yield grades for Maasvlakte expansions to reduce pile count and driving energy requirements.
- Vinyl:Extruded PVC and composite polymer sections deliver chemical resistance in aggressive port environments where steel corrosion rates exceed maintenance budgets. Marine contractors in the Netherlands specify vinyl for chemically aggressive berth foundations where coating durability cannot be guaranteed.
- Concrete:Precast reinforced sections provide mass stability for permanent floodwalls with 100-year design lives mandated by EU Green Deal coastal adaptation funding.
- Composite:Fiber-reinforced polymer pilings combine corrosion immunity with electromagnetic transparency for sensitive instrumentation zones near port facilities.
Steel sits at the top of the volume ranking, with composite climbing the fastest as harbor authorities bundle long-term corrosion monitoring into design-build-operate contracts.
Installation Method:
Equipment capital intensity and noise restrictions divide contractors by project scale, with vibration limits in urban waterfronts favoring specialized methodologies over conventional driving.
- Driving:Impact hammers deliver high-energy installation for dense soils and ultra-heavy-duty sections exceeding 6,000 cm³/m section modulus. Dutch contractors deploy hydraulic hammers for Rotterdam's deep berth constructions where refusal criteria demand precise energy control.
- Vibrating:High-frequency oscillators reduce ground-borne vibration for sensitive urban waterfronts and existing structure proximity. German equipment manufacturers dominate this segment with resonant-free technology that satisfies Hamburg harbor authority noise ordinances.
- Jetting:High-pressure water injection assists penetration in cohesionless sands where driving resistance would damage interlock geometry.
- Excavating:Trench-based placement enables precise alignment for combined wall systems integrating sheet piles with tubular king piles.
Driving commands the largest equipment fleet, though vibrating gains share fastest as European port cities tighten construction noise regulations.
End User:
Public procurement frameworks and design-life specifications concentrate margin pools in infrastructure categories with standardized performance warranties.
- Coastal Protection:Permanent floodwalls and sea defense schemes specify 100-year service lives under US Army Corps EM 1110-2-2504 design manuals. Gulf Coast reconstruction programs post-hurricane specify steel sheet pile floodwalls with cathodic protection systems.
- Construction:Temporary excavation support and basement retaining walls drive volume through standard-duty sections with shorter design horizons. Chinese contractors source domestic GB/T 20934 certified piles for metro and high-rise foundation work.
- Environmental:Cut-off walls for contaminated site remediation demand interlock seal integrity that prevents groundwater migration.
- Transportation:Bridge abutments and railway embankments specify sheet piling for scour protection and grade separation structures.
Coastal protection generates the highest per-meter pricing, while construction delivers the greatest unit volume through repeat project pipelines.
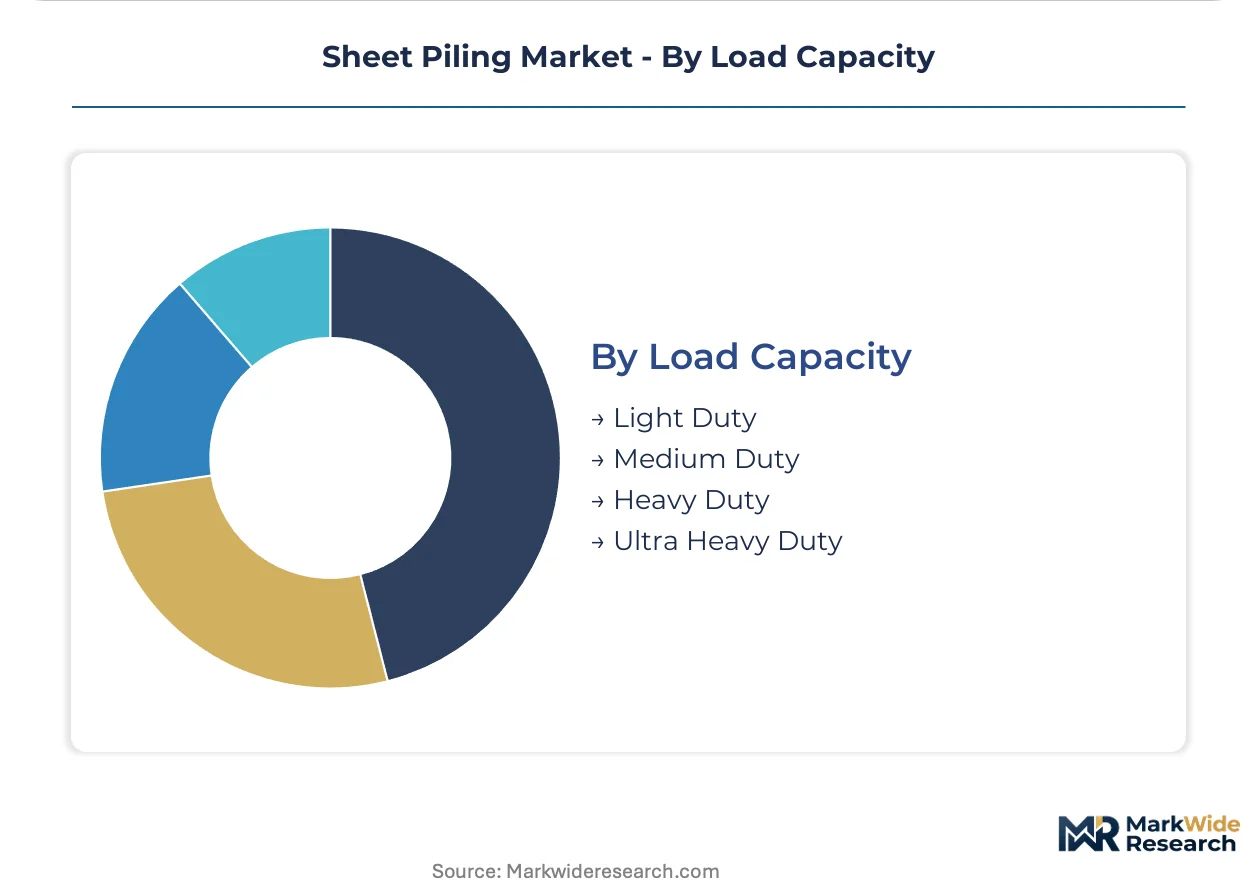
Load Capacity:
Section modulus availability and rolling mill capability constraints concentrate supply security concerns in the upper capacity tiers where only certified producers qualify.
- Heavy Duty:Sections achieving 4,000–6,000 cm³/m section modulus satisfy deep berth constructions and flood defense walls with combined hydrostatic and earth pressure loading. Antwerp authorities require 25-year coating warranties as standard for permanent marine installations in this tier.
- Ultra Heavy Duty:Custom-rolled sections exceeding 6,000 cm³/m serve megaproject tenders where pile count reduction justifies premium pricing. Only three integrated steel groups maintain rolling capacity for these specifications, creating supply security concerns for European harbor authorities.
- Light Duty:Standard sections below 2,000 cm³/m address temporary works and low-height retaining applications with minimal interlock stress.
- Medium Duty:Intermediate specifications bridge commercial and infrastructure applications with balanced cost-performance ratios.
Heavy Duty dominates permanent marine installation value, with Ultra Heavy Duty expanding most quickly as port deepening projects accelerate globally.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rotterdam harbor expansion anchors European demand for ultra-heavy-duty sections, while Chinese coastal megaprojects and US Gulf Coast resilience programs concentrate procurement volumes across three distinct regulatory environments.
China
Port deepening at Yangshan and Ningbo-Zhoushan drives specification of high-yield steel grades exceeding 460 MPa. MIIT enforcement of GB/T 20934 standards disqualifies non-compliant imports from Southeast Asian fabricators. Contractors in the Yangtze River Delta now source exclusively from certified domestic mills with integrated rolling and coating capabilities.
United States
Post-hurricane reconstruction programs along the Gulf Coast and Eastern Seaboard specify steel sheet pile floodwalls with 100-year design lives. US Army Corps EM 1110-2-2504 design manuals govern structural methodologies for permanent marine installations. Texas and Louisiana harbor authorities bundle cathodic protection systems into coastal protection tenders.
Netherlands
Rotterdam Maasvlakte expansions and Antwerp port deepening compress project timelines for interlocking retaining wall systems. EU Green Deal coastal adaptation funding unlocks capital for flood defense upgrades with 25-year coating warranties as standard. Dutch contractors deploy hydraulic hammers for deep berth constructions where refusal criteria demand precise energy control.
United Arab Emirates
Khalifa Port expansion and Dubai South logistics corridors intensify demand for high-section-modulus piles in aggressive marine environments. MOHAP environmental impact assessment protocols condition product acceptance for domestic infrastructure tenders. Abu Dhabi harbor authorities specify corrosion-resistant coatings as mandatory rather than optional upgrades.
Germany
Hamburg Elbe deepening and Bremen container terminal upgrades elevate performance specifications for interlocking systems. REACH compliance governs polymer additives in vinyl alternatives specified for chemically aggressive berth foundations. German equipment manufacturers dominate vibrating installation technology that satisfies municipal noise ordinances.
Sheet Piling Market Vendor Landscape
Capacity expansion dominates the current landscape as integrated steel groups and regional fabricators race to qualify for megaproject tenders. The vendor base concentrates around three rolling mill operators controlling ultra-heavy-duty section production above 6,000 cm³/m, with mid-tier specialists occupying temporary works and standard-duty segments. Strategic archetypes divide between metallurgical leaders with proprietary high-yield grades, integrated fabricators with Southeast Asian production footprints, and domestic mill operators securing regional supply security. Competitive moves center on backward integration into coating application capabilities and geographic expansion through waterfront distribution terminals.
Among Asia-Pacific metallurgical leaders, Nippon Steel & Sumitomo Metal and JFE occupy positions defined by proprietary steel grade development, while ESC Group exemplifies the integrated fabricator archetype with Southeast Asian production hubs serving harbor authority contracts. North American supply security anchors around EVRAZ North America and Valiant Steel, the latter securing domestic mill capacity and waterfront distribution infrastructure for US Army Corps coastal resilience programs.
| Leading Market Players |
|---|
| ESC Group |
| Northwest Pipe Company |
| Nippon Steel & Sumitomo Metal |
| EVRAZ North America |
| Valiant Steel |
| JFE |
| TMK IPSCO |
| Shoreline Steel |
| Meever |
| Others |
Supply Flow & Price Mechanics
High-strength low-alloy steel grade adoption exceeding 460 MPa yield thresholds simultaneously compresses per-meter installed costs and concentrates qualified supplier pools around integrated mills with proprietary metallurgical capabilities. This technology shift rewards harbor authorities with reduced pile counts while elevating pricing power for certified producers capable of GB/T 20934 or CE-marked output.
Pricing Analysis
Scrap steel benchmark volatility passes through directly to electric arc furnace operators, compressing margins when ferrous scrap spikes above hot-rolled coil contract prices. Three-tier pricing structure across premium, standard, and economy levels separates ISO 12944 C5-M certified piles with 25-year warranties from uncertified imports and temporary-works grades. Price differentiation hinges on section modulus tier and coating durability certification, with ultra-heavy-duty sections above 6,000 cm³/m commanding substantial premiums due to rolling mill scarcity. Cost compression in standard-duty segments intensifies as Chinese domestic capacity expands, while temporary-works contractors exhibit highest price sensitivity compared to permanent marine infrastructure buyers.
Supply Chain Analysis
CE marking under EU Construction Products Regulation and China's GB/T 20934 certification gate access to public infrastructure tenders, disqualifying non-compliant Southeast Asian fabricators from Rotterdam and Yangtze River Delta projects. Production concentrates in China, Japan, and South Korea, with over half of global ultra-heavy-duty rolling capacity controlled by three integrated steel groups. Raw material dependencies draw from ferrous scrap, hot-rolled coil, and zinc-aluminum coating alloys, with supply chain risk anchored in single-source vulnerability for specialized interlock geometries. Distribution runs through waterfront terminals serving harbor authority contracts, supplemented by regional fabricators for standard-duty construction segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sheet piling functions as a stable compounder anchored by irreversible coastal infrastructure investment cycles and 100-year design-life mandates from EU and US public agencies.
For Market Incumbents: Hedge against Asian mill concentration risk by securing captive coating application capabilities and qualifying alternative rolling partnerships in Europe or North America. Defensive moves center on backward integration into corrosion protection services and capacity expansion near US Gulf Coast Army Corps programs. The threat of carbon-border adjustment mechanisms elevates regional mill competitiveness against Chinese imports. For New Entrants and Emerging Players: Capture white-space in fiber-reinforced composite pilings for chemically aggressive port environments where steel corrosion rates exceed maintenance budgets. Vinyl and FRP alternatives remain underpenetrated in Middle Eastern and Southeast Asian harbor projects. A design-build-operate contract structure bundles material supply with long-term monitoring, opening procurement channels beyond traditional mill-direct relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among regional fabricators with waterfront distribution infrastructure and certified coating capabilities rather than integrated steel groups. The 5-10 year viability window favors acquisition targets with GB/T 20934 or CE-marking credentials and established harbor authority relationships. The signal to watch is carbon-border adjustment implementation timing, which would restructure import cost positions and elevate domestic European or North American mill valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coating Application | Captures margin pools from ISO 12944 C5-M certified marine installations required by Rotterdam and Antwerp authorities. |
| Capacity Expansion near US Gulf Coast | Positions supply security for US Army Corps post-hurricane coastal resilience appropriations along Texas and Louisiana. |
| Composite Piling Product Line Development | Addresses chemically aggressive berth foundations in UAE and Netherlands where steel corrosion exceeds maintenance budgets. |
| Long-term Supply Agreement with Harbor Authorities | Locks procurement volumes through design-build-operate contracts bundling 25-year coating warranties. |
| Certification Investment for GB/T 20934 Compliance | Enables access to Chinese domestic infrastructure tenders excluding non-compliant Southeast Asian imports. |
Methodological Framework
Coverage spans China, the United States, the Netherlands, Germany, and the United Arab Emirates, with primary inputs from each market cluster. The approach combines structured interviews with harbor authority procurement directors, marine contractor project managers, steel mill technical sales leads, and geotechnical engineering consultants with secondary validation. Sources include customs and trade flow databases, national standards body publications from MIIT and EU CPR frameworks, SEC filings from listed steel groups, and project development trackers for port expansion programs. Bottom-up demand modeling triangulates against top-down steel consumption forecasts.
Granularity-level modeling disaggregates volume and value across material type, load capacity tier, installation methodology, and end-use application throughout the forecast period. Segmentation dimensions include steel grade certification level, section modulus threshold, and regional regulatory cluster. CAGRs derive from project pipeline analysis and public agency capital appropriation trajectories. Industry-specific inputs incorporate US Army Corps EM 1110-2-2504 design manual adoption rates and EU Green Deal coastal adaptation funding disbursement patterns.
Scrap steel price volatility, carbon-border adjustment mechanism implementation, and rolling mill capacity constraints for ultra-heavy-duty sections are the dominant revision risks to modeled outputs. Forecasts reflect assumptions around continued public infrastructure investment prioritization and stable regulatory certification requirements. A model refresh is warranted upon material change in EU or Chinese environmental procurement protocols.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Insulated Wall Panels Market
Building & Construction Materials
US Steel Rebar Market
Building & Construction Materials
US Geosynthetics Market
Building & Construction Materials
Aluminum Curtain Wall Market
Building & Construction Materials
Temporary Storage Buildings Market
Building & Construction Materials
Corrugated Polycarbonate Panels Market
Building & Construction Materials
US Residential and Commercial Roofing Materials Market
Building & Construction Materials
Laminated Veneer Lumber (LVL) Market
Building & Construction Materials
Steel Sandwich Panels Market
Building & Construction Materials
Prestressed Concrete (PC) Wire and Strand Market
Building & Construction Materials
Australia Industrial Insulation Market
Building & Construction Materials
Global Rainscreen Cladding Market
Building & Construction Materials
Ball Iron Rods Market
Building & Construction Materials
Russia Ceramic Tiles Market
Building & Construction Materials
North America Rainscreen Cladding Market
Building & Construction Materials
North America Plywood Market