
 Wood Panel Market | 2026-2036
Wood Panel Market Size, Share, and Industry Trends Forecast 2026-2036
Wood Panel Market Analytics
Asset-light leasing models for veneer presses and continuous panel lines is reconfiguring capital barriers for mid-scale entrants. Weyerhaeuser Company leverages its captive timber base across the US South to sustain cost advantages in OSB and plywood. EGGER anchors European supply through specialized particle board and laminate production. Louisiana-Pacific Corporation competes via product-specific mills oriented toward structural panels.
Wood panels are engineered sheet materials manufactured from wood strands, fibers, or veneers bonded under heat and pressure, typically ranging from three millimeters to over forty millimeters in thickness depending on structural or decorative application. These products serve as primary substrates for furniture manufacturing, structural sheathing in construction, and interior surfacing across residential and commercial buildings. Plywood and OSB dominate structural applications in North American housing, while MDF leads in furniture and interior design due to its uniform density and machinability. Particle board occupies the economy tier of furniture substrates, with margin pools shifting toward laminated and veneered finish types as downstream buyers seek ready-to-assemble components.
EPA formaldehyde emission standards in the United States, CE marking requirements under the EU Construction Products Regulation, and China's GB standards for interior decoration materials collectively enforce bonding agent specifications and air quality thresholds. These frameworks elevate compliance costs for commodity producers while rewarding certified low-emission product lines. Stakeholders must monitor evolving cross-border timber legality verification systems and regional carbon accounting rules that will reshape supplier qualification criteria and mill location decisions.
Market Dynamics
Engineered wood technologies are compressing the cost-performance gap between commodity panels and solid timber, forcing incumbent producers to retool mills for cross-laminated timber and mass plywood while defending legacy particle board volumes against substitution.
Growth Catalysts
- CE marking under EU Construction Products Regulation:Mandatory performance declarations for structural panels are elevating certified producers above commodity competitors in European public procurement.
- Mass timber construction:Building codes in British Columbia and Oregon now permit 12-story wood structures, pulling cross-laminated timber demand from concrete and steel frames.
- Plantation fiber supply:Eucalyptus and acacia plantations in Brazil and Indonesia are securing raw material access for export-oriented MDF and particle board mills.
Market Restraints
- Adhesive input volatility:Urea-formaldehyde resin prices track methanol and natural gas benchmarks, compressing margins on commodity particle board during energy price spikes.
- Boreal forest supply concentration:Spruce-pine-fir veneer log access concentrates among Canadian provincial crown land licensees and Russian Far East operators, creating bottleneck risk.
- Concrete and steel substitution:Precast concrete sandwich panels and cold-formed steel framing retain cost advantages in fire-rated commercial construction above six stories.
Strategic Opportunities
- India furniture manufacturing:Production-linked incentive schemes for wood-based industries are attracting particle board and laminate investments to Gujarat and Punjab clusters.
- Digital printing on MDF:Direct-to-substrate UV inkjet systems are enabling short-run decorative surfacing without laminate overlay, opening custom interior markets.
- US Inflation Reduction Act:Tax credits for mass timber in federal buildings are accelerating CLT and glulam specification in GSA projects.
Industry Challenges
- Press operator skill scarcity:Continuous panel line automation requires technicians fluent in Siemens and Honeywell control systems, creating recruitment friction in rural mill locations.
- Forest Stewardship Council chain-of-custody audits:Multi-site certification complexity extends compliance timelines for mid-scale Asian exporters targeting EU and North American retail channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wood Panel Market |
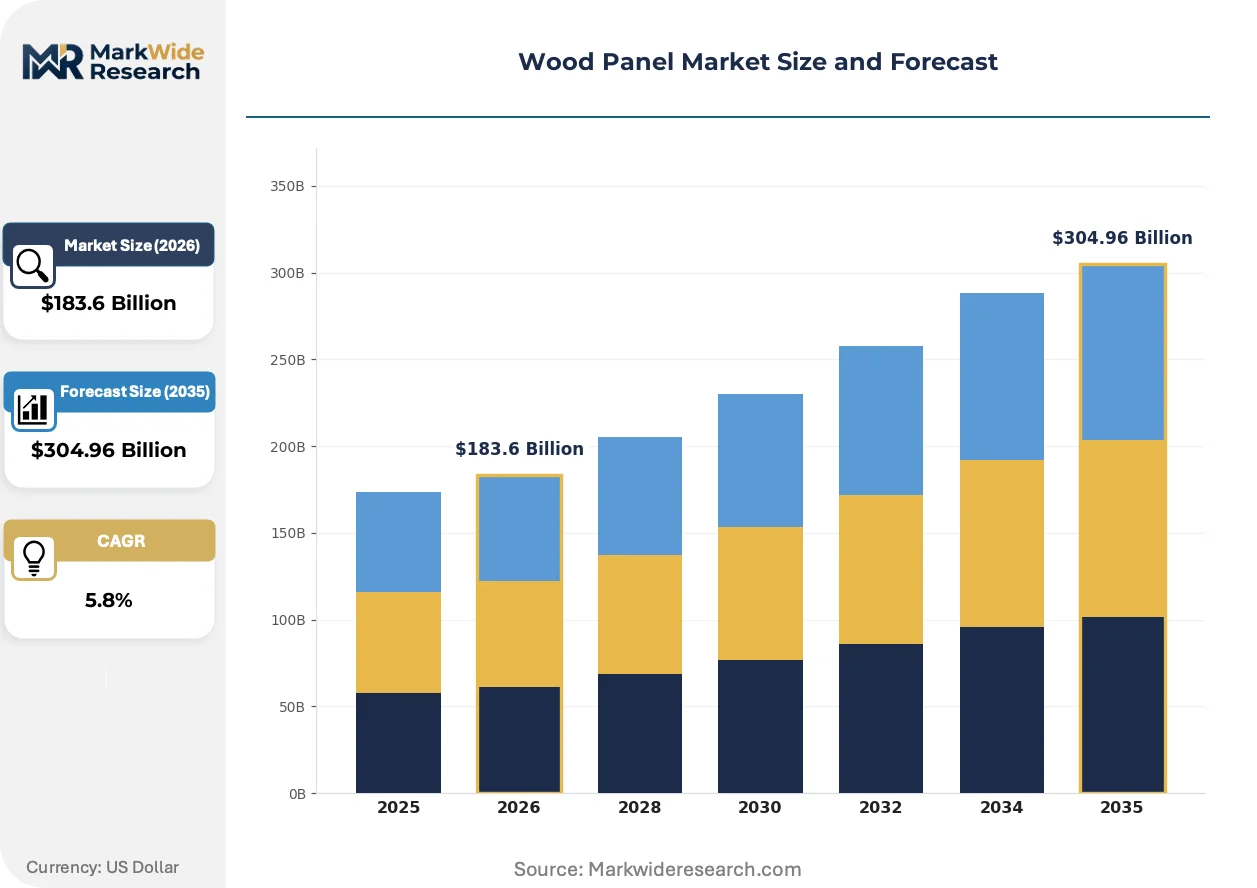
| Market Size in 2026 | $183.6 Billion |
| Market Size in 2035 | $304.96 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plywood, Particle Board, MDF, OSB End User: Furniture Industry, Construction, Interior Design, Packaging Thickness: Thin Panels, Medium Panels, Thick Panels, Custom Sizes Finish Type: Raw, Laminated, Veneered, Painted |
| Companies Covered | ARAUCO, Weyerhaeuser Company, Kronoplus Limited, Boise Cascade Company, Louisiana-Pacific Corporation, EGGER, Georgia-Pacific, Canfor Corporation, West Fraser Timber Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wood Panel Market Evolving Landscape
Digital manufacturing and bio-based chemistry are converging to reduce formaldehyde dependence while enabling mass customization of panel surfaces. These shifts are compressing batch sizes and shortening product development cycles across decorative applications.
Cross-laminated timber manufacturing is migrating from custom architectural projects to standardized multi-family housing components. Scandinavian and Pacific Northwest developers are specifying CLT floor cassettes for five-story repetitive structures. This technology is migrating from bespoke engineering toward commoditized supply, forcing equipment suppliers to develop smaller-scale press configurations for regional entrants.
EPA formaldehyde emission standards under the Toxic Substances Control Act Title VI are tightening bonding agent specifications for hardwood plywood and MDF sold in US markets. Composite panel producers must certify through third-party TPC audits to maintain import and distribution rights. California Air Resources Board thresholds continue to pull national standards downward, with laminate flooring retailers now demanding CARB Phase 2 documentation for all substrates.
Buyer concentration among ready-to-assemble furniture retailers is compressing supplier margins while demanding shorter lead times and mixed-load logistics. IKEA and Wayfair are consolidating panel procurement through direct mill relationships, displacing traditional distributors in North American and European supply chains. This consolidation is most visible in Poland and Vietnam, where dedicated production lines serve single-buyer contracts with 48-hour fulfillment windows.
Wood Panel Market Segmentation
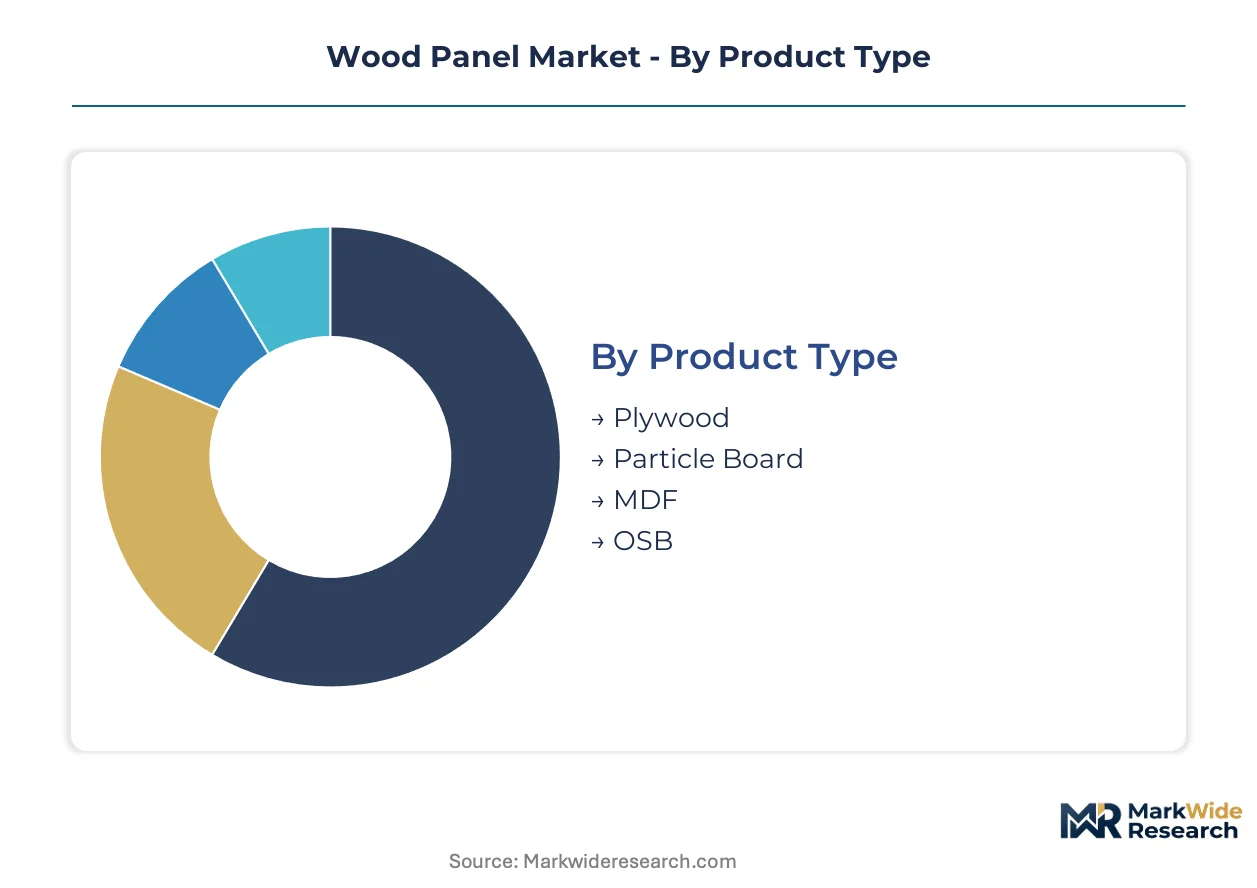
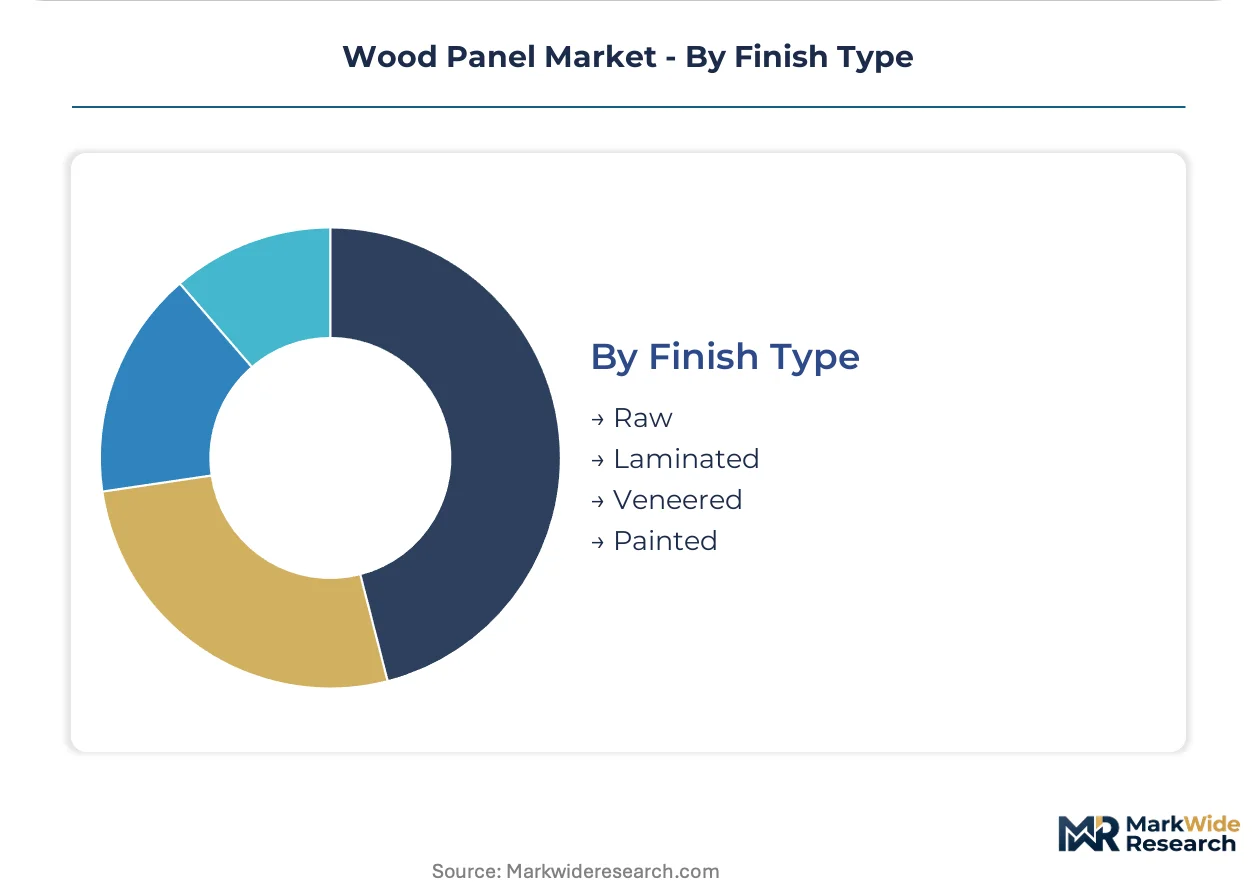
Wood panel segmentation reflects divergent technical requirements across structural and decorative applications. Product specifications vary dramatically by end-use performance demands, finish durability needs, and installation constraints.
Product Type:
Mature categories dominate volume while engineered alternatives reshape competitive dynamics.
- Plywood:Cross-laminated veneer construction delivers dimensional stability and structural shear strength. Demand concentrates in North American residential sheathing and concrete formwork, with pressure-treated grades commanding premium positioning in outdoor applications. Hurricane-resistant building codes in Florida and Gulf Coast states sustain specification rates.
- Particle Board:Wood particles bonded with thermosetting resins create economical substrates for furniture and cabinetry. Furniture manufacturing clusters in Poland and Vietnam absorb volume through IKEA-directed supply chains, though formaldehyde emission regulations tighten bonding agent specifications.
- MDF:Uniform density fiberboard enables precision machining and smooth surface finishing for interior millwork.
- OSB:Oriented strand board substitutes for plywood in wall sheathing and roof decking with cost advantages in commodity construction.
Plywood retains volume leadership; OSB holds the steepest expansion curve in residential construction substitution.
End User:
Application-specific performance standards create distinct procurement patterns and margin profiles.
- Furniture Industry:Laminated particle board and MDF substrates feed ready-to-assemble manufacturing with CARB Phase 2 compliance mandatory for US distribution. Flat-pack producers in Vietnam and Poland demand 48-hour fulfillment windows.
- Construction:Structural sheathing, subflooring, and roofing applications specify PS-2 graded plywood or OSB with APA certification. British Columbia and Oregon building codes now permit 12-story mass timber structures.
- Interior Design:Decorative wall paneling, ceiling systems, and architectural millwork favor veneered MDF and prefinished plywood.
- Packaging:Industrial crating and pallet manufacturing consumes lower-grade softwood plywood and OSB offcuts.
Construction absorbs the highest tonnage; furniture manufacturing generates the most complex supply chain requirements.
Thickness:
Panel thickness correlates directly with load-bearing function and fabrication method compatibility.
- Thin Panels:Three to six millimeter sheets serve backing material, drawer bottoms, and decorative surfacing with minimal structural duty.
- Medium Panels:Nine to eighteen millimeter specifications balance machinability with rigidity for cabinet carcasses and furniture components.
- Thick Panels:Twenty-five to forty millimeter construction supports countertops, shelving, and structural joinery with screw-holding strength requirements.
- Custom Sizes:Non-standard thicknesses accommodate specialized architectural millwork and industrial equipment enclosures.
Medium panels command the broadest application base; thick panels capture the highest per-unit value.
Finish Type:
Surface preparation determines downstream labor requirements and aesthetic differentiation.
- Raw:Unfinished panels require field sanding, sealing, and coating, appealing to custom fabricators and budget-conscious contractors.
- Laminated:Melamine-impregnated paper overlays provide durable, consistent decorative surfaces for furniture and cabinetry with minimal maintenance.
- Veneered:Natural wood faces deliver premium aesthetics for architectural millwork and high-end furniture with grain matching capabilities.
- Painted:Factory-applied coatings reduce field finishing labor for interior wall panels and commercial fixtures.
Laminated finishes dominate volume; veneered products maintain the strongest price positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Inflation Reduction Act tax credits for mass timber in federal buildings are accelerating cross-laminated timber specification across GSA projects. China's GB standards for interior decoration materials enforce bonding agent specifications that elevate compliance costs for commodity producers. Brazil's plantation fiber supply from eucalyptus and acacia plantations secures raw material access for export-oriented MDF and particle board mills.
United States
Hurricane-resistant building codes in Florida and Gulf Coast states sustain plywood specification rates for residential sheathing. EPA formaldehyde emission standards under TSCA Title VI tighten bonding agent specifications for hardwood plywood and MDF. The Pacific Northwest hosts mass timber manufacturing clusters where British Columbia and Oregon building codes now permit 12-story wood structures.
China
Residential construction expansion in emerging economies concentrates wood panel consumption for structural and decorative applications. GB standards for interior decoration materials enforce air quality thresholds that reward certified low-emission product lines. Manufacturing capacity and raw material access in Guangdong and Zhejiang provinces reshape trade flows for export-oriented producers.
Brazil
Plantation fiber supply from eucalyptus and acacia plantations secures raw material access for export-oriented MDF and particle board mills. The country's national forestry certification requirements alter procurement patterns for mid-scale entrants. Industrial clusters in Paraná and São Paulo states anchor particle board production for furniture manufacturing export chains.
Germany
CE marking under the EU Construction Products Regulation elevates certified producers above commodity competitors in European public procurement. The EU Green Deal carbon accounting rules reshape supplier qualification criteria and mill location decisions. Engineered wood technology specialists in Bavaria and Baden-Württemberg retool mills for cross-laminated timber and mass plywood production.
India
Production-linked incentive schemes for wood-based industries attract particle board and laminate investments to manufacturing clusters. BIS standards for interior decoration materials elevate compliance costs for commodity producers while rewarding certified low-emission product lines. Gujarat and Punjab furniture manufacturing clusters absorb volume through dedicated production lines with 48-hour fulfillment windows.
Wood Panel Market Competitive Landscape
On the supply side, the industry is tiered between integrated timberland owners, specialized engineered wood producers, and regional commodity fabricators. The vendor base spans captive timber operators in North America, European laminate specialists, and Asian export-oriented particle board mills. Three strategic archetypes dominate: timberland-integrated structural panel producers, decorative surfacing specialists, and plantation-backed MDF exporters. Competitive moves concentrate on backward integration into plantation fiber supply and technology licensing for continuous panel line automation.
Among North American timberland-integrated operators, Weyerhaeuser Company and Louisiana-Pacific Corporation exemplify the captive fiber-to-panel archetype. European laminate and particle board specialists include EGGER and Kronoplus Limited, representing the decorative surfacing tier. ARAUCO anchors the plantation-backed export model from South American eucalyptus fiber bases. These named entities occupy positions across the structural, decorative, and commodity substrate segments without exhaustive claims about specific product portfolios or strategic initiatives.
| Leading Market Players |
|---|
| ARAUCO |
| Weyerhaeuser Company |
| Kronoplus Limited |
| Boise Cascade Company |
| Louisiana-Pacific Corporation |
| EGGER |
| Georgia-Pacific |
| Canfor Corporation |
| West Fraser Timber Co. |
| Others |
Value Network & Pricing Analysis
Adhesive input volatility tied to methanol and natural gas benchmarks compresses margins on commodity particle board while simultaneously widening price spreads between certified low-emission grades and standard products, forcing procurement teams to rebalance inventory exposure across bonded and thermally fused alternatives.
Pricing Analysis
Certification level under EPA TSCA Title VI and CARB Phase 2 creates the primary spread between premium and economy tiers, with third-party TPC audited panels commanding substantial premiums over uncertified imports. Three-tier pricing structure across premium, standard, and economy levels stratifies by formaldehyde emission grade and chain-of-custody documentation depth. Cost compression in commodity particle board is intensifying because urea-formaldehyde resin prices track energy benchmarks, making furniture manufacturing clusters the most price-sensitive buyers while mass timber contractors for GSA projects show lowest sensitivity.
Supply Chain Analysis
Extended payment terms through supply-chain finance facilities have become standard for IKEA and Wayfair direct mill relationships, shifting working capital burdens upstream to particle board and MDF producers. Raw material supply concentrates in Brazil, Indonesia, and Canada, with eucalyptus and acacia plantation fiber feeding Asian export mills while Canadian crown land licensees control spruce-pine-fir veneer log access. Adhesive resins, decorative paper overlays, and timber legality verification documentation represent critical input dependencies. Single-source vulnerability concentrates in boreal forest veneer supply. Distribution runs through dedicated production lines with 48-hour fulfillment windows serving single-buyer contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power has concentrated among ready-to-assemble furniture retailers, with IKEA and Wayfair consolidating panel procurement through direct mill relationships that displace traditional distributors and compress supplier margins.
For Market Incumbents: Insulate structural panel positions by deepening captive timber supply in the US South and Pacific Northwest while accelerating CARB Phase 2 and FSC chain-of-custody certification investments to defend against emerging plantation-backed MDF exporters from South America. Cross-laminated timber capacity additions in British Columbia and Oregon building code jurisdictions represent the priority defensive lever against concrete and steel substitution above six stories. For New Entrants and Emerging Players: Establish a beachhead in India's Gujarat and Punjab furniture manufacturing clusters by leveraging production-linked incentive schemes for wood-based industries, where BIS standards compliance creates barrier-protected local demand. Digital printing on MDF for short-run decorative surfacing offers the most penetrable white-space target, with direct-to-substrate UV inkjet systems enabling custom interior markets without laminate overlay capital requirements. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors timberland-integrated structural panel producers with mass timber capabilities over commodity particle board operators exposed to adhesive cost volatility. Acquisition targets should screen for captive fiber supply, EPA TPC certification, and CLT press configurations. The signal to watch is building code adoption rates for 12-story wood structures across additional US states and Canadian provinces.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Fiber Supply | Eucalyptus and acacia plantations in Brazil and Indonesia secure raw material access for export-oriented MDF mills. |
| Mass Timber Manufacturing Scale-Up | CLT and glulam capacity expansion in British Columbia and Oregon serves GSA projects qualifying for US Inflation Reduction Act tax credits. |
| Low-Emission Certification Investment | EPA TSCA Title VI and CARB Phase 2 third-party TPC audits maintain import and distribution rights in US markets. |
| Continuous Panel Line Automation | Siemens and Honeywell control system deployment addresses press operator skill scarcity in rural mill locations. |
| Direct Retailer Supply Agreement | 48-hour fulfillment windows with IKEA and Wayfair displace traditional distributors in Poland and Vietnam clusters. |
Research Methodology
A spread of perspectives from mill operations directors, timberland asset managers, furniture procurement leads at ready-to-assemble retailers, adhesive R&D specialists, and building code officials converged on the working assumptions. Primary interviews combined with secondary validation from EPA formaldehyde emission filings, FSC chain-of-custody audit records, customs trade data on veneer and panel imports, and state-level building code amendment tracking. Bottom-up capacity and utilization estimates triangulated against top-down construction spending and furniture production indices.
Demand-supply balance modeling across the analysis window incorporated product type segmentation by structural versus decorative application, end-use concentration in residential construction versus furniture manufacturing, thickness specifications correlating with load-bearing function, and finish type differentiation by downstream labor requirements. CAGRs derived from regression against housing starts, commercial construction permits, and furniture export volumes with cross-validation against mill capacity expansion announcements.
Sensitivities concentrate around methanol and natural gas price spikes affecting urea-formaldehyde resin costs, building code adoption timelines for mass timber height allowances, and timber legality verification system enforcement intensity. Macroeconomic deviation in residential construction, regulatory tightening in formaldehyde emission standards, or breakthroughs in concrete and steel fire-rated alternatives would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Global Elastic Rail Fasteners Market
Building & Construction Materials
Drywall and Gypsum Board Market
Building & Construction Materials
Vapor Barriers Market
Building & Construction Materials
Moisture Resistant Gypsum Board Market
Building & Construction Materials
Global Convertible Roof System Market
Building & Construction Materials
US Glass Curtain Wall Market
Building & Construction Materials
Asia-Pacific Cross-Laminated Timber Market
Building & Construction Materials
Wood House Frame Market
Building & Construction Materials
Canada Facade Market
Building & Construction Materials
Europe AAC Blocks and Panels Market
Building & Construction Materials
Global Wooden Formwork Systems Market
Building & Construction Materials
Concrete Conditioner Market
Building & Construction Materials
Global Sandwich Panels Market
Building & Construction Materials
Waterproofing Solution Market
Building & Construction Materials
Window Film Market
Building & Construction Materials
Global Iron and Steel Casting Market