
 Plastic Roofing Tiles Market | 2026-2036
Plastic Roofing Tiles Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Roofing Tiles Market Analytics
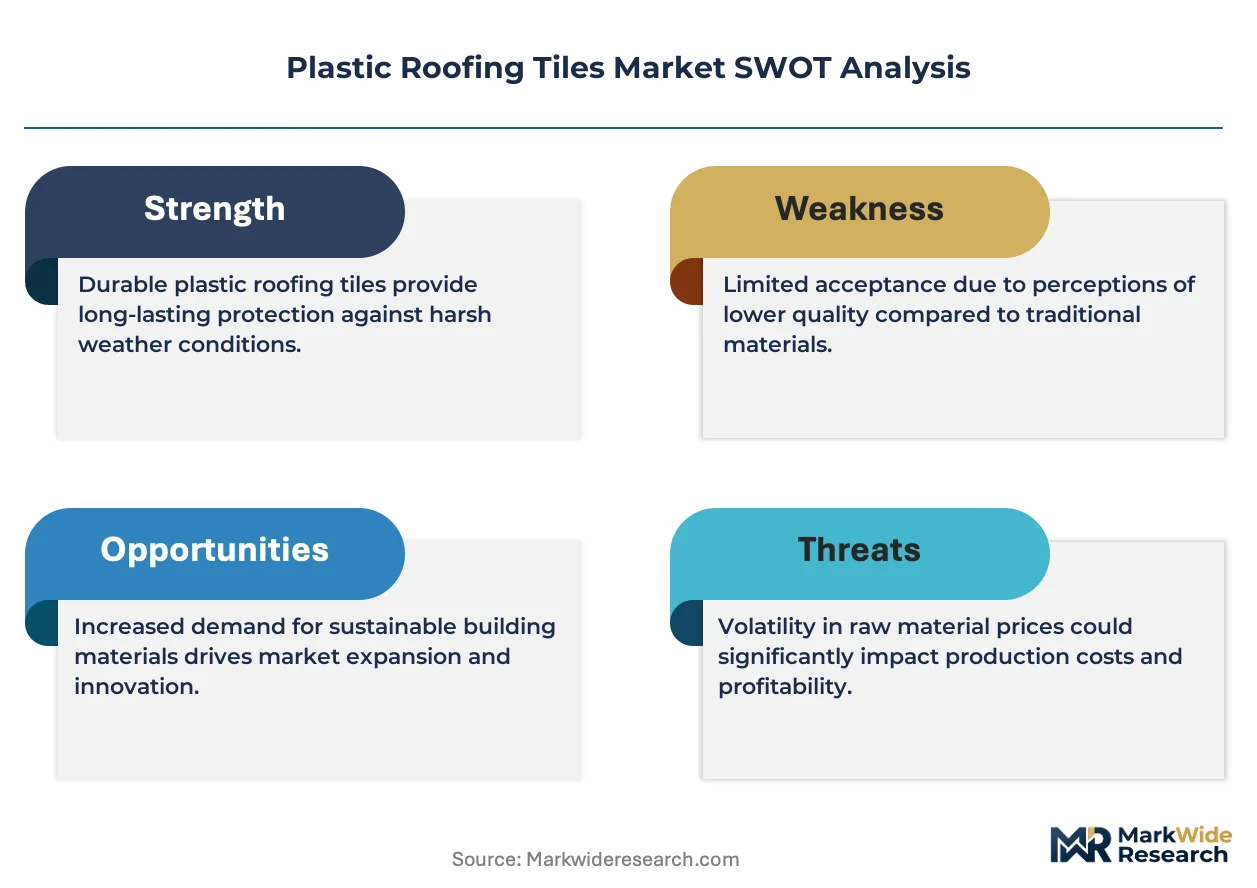
The capital-intensity gap between integrated resin producers and specialty compounders is bifurcating competitive tiers in plastic roofing tiles. GAF Materials Corporation leverages captive polymer supply chains to compress raw material volatility. EcoStar LLC differentiates through recycled-content formulations that command specification preference in LEED-targeted projects. CertainTeed Corporation anchors multi-channel distribution through contractor loyalty programs and big-box retail placement.
Plastic roofing tiles are synthetic polymer-based roof coverings, typically manufactured from PVC, polycarbonate, or thermoplastic olefin compounds through injection molding or extrusion processes, engineered to replicate clay or slate profiles while delivering impact resistance and UV stability. Their primary purpose is to provide durable, lightweight weather protection for structures in climates where traditional materials face freeze-thaw degradation or seismic load constraints. Composite product types now capture expanding specification share as architects balance aesthetic mimicry against structural load limits in retrofit applications. Snap-fit installation methods are gaining traction in residential end-user segments where labor shortages elevate prefabricated system appeal. The wholesale distribution channel still dominates volume flows, though direct-sales models are encroaching on large commercial and agricultural contracts.
Federal Emergency Management Agency building codes, ASTM D3161 wind-resistance standards, and EPA recycled-content procurement guidelines collectively shape product certification requirements and market access thresholds for plastic roofing tiles. State-level insurance commission mandates in coastal jurisdictions increasingly tie premium reductions to Class 4 impact-rated synthetic roofing, directly steering residential demand toward certified products. Stakeholders must monitor evolving polymer feedstock cost trajectories and regional code adoptions to time capacity commitments and formulation investments.
Market Dynamics
Insurance commission mandates in hurricane-prone US states are compressing specification timelines, forcing manufacturers to accelerate Class 4 impact certification cycles ahead of traditional product development cadences.
Growth Catalysts
- ASTM D3161 wind-resistance standards:Coastal building codes in Florida and Texas now require documented uplift resistance, pulling premium synthetic tile volumes into certified supply chains.
- LEED-targeted commercial construction:Recycled-content formulations command specification preference among architects pursuing green building certification thresholds.
- Seismic load constraints:Lightweight polymer systems displace clay and concrete alternatives in California retrofit markets where structural engineering limits govern material selection.
Market Restraints
- Petrochemical feedstock volatility:PVC and polycarbonate resin prices fluctuate with crude oil derivatives, compressing compounder margins during upstream supply shocks.
- Single-source geography risk:Gulf Coast resin production concentration exposes tile manufacturers to hurricane-related supply interruptions.
- Clay tile aesthetic persistence:High-end residential segments in historic districts maintain specification preference for traditional materials despite performance trade-offs.
Strategic Opportunities
- Agricultural outbuilding retrofits:Dairy and poultry operations in the Midwest seek corrosion-resistant roofing for high-humidity environments where metal systems fail.
- Direct-to-contractor digital platforms:E-commerce channels bypass wholesale markups for large commercial projects with predictable volume requirements.
- IRA energy-efficiency tax credits:Cool-roof formulations qualifying for federal incentives penetrate residential markets previously price-locked to asphalt shingles.
Industry Challenges
- Certification timeline compression:Florida Product Approval and Miami-Dade County protocols demand extended testing cycles that delay regional market entry.
- Installation workforce gaps:Specialized snap-fit training requirements outpace union apprenticeship pipeline capacity in fast-growth construction markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Roofing Tiles Market |
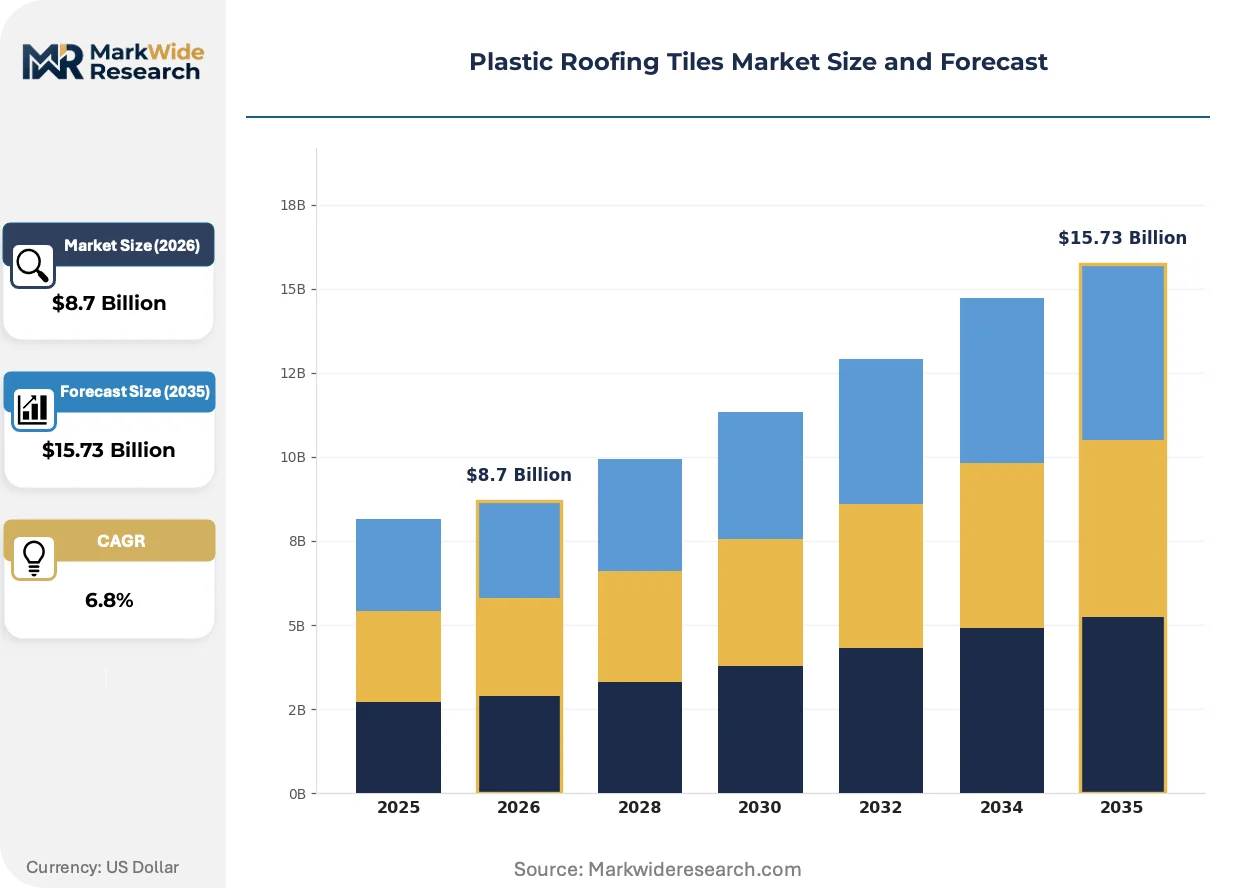
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polycarbonate, PVC, TPO, Composite Installation Method: Snap-Fit, Bolt-On, Adhesive, Interlocking End User: Residential, Commercial, Industrial, Agricultural Distribution Channel: Direct Sales, Online Retail, Wholesale, Distributors |
| Companies Covered | GAF Materials Corporation, EcoStar LLC., CertainTeed Corporation, TAMKO Building Products, Brava Roof Tile LLC., IKO Industries Ltd., Sika AG, Monier, Boral Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Roofing Tiles Market Evolving Landscape
Material science advances and procurement digitization are restructuring how synthetic roofing systems penetrate specification channels and contractor workflows.
Co-extruded capstock technology is bifurcating product tiers by embedding UV-stabilized acrylic layers over recycled-content cores. Residential contractors in Texas and Florida specify these dual-layer systems for warranty-backed performance in extreme exposure zones. The technology is bifurcating market positioning between premium certified lines and commodity imports lacking weathering documentation.
EPA stormwater runoff rules are tightening permeability standards for roofing materials in combined sewer overflow districts. Manufacturers must reformulate surface textures to satisfy low-impact development criteria in municipal procurement specifications. Northeast and Pacific Northwest metropolitan areas now require documented runoff coefficients for public infrastructure bids.
Big-box retail placement is capturing growing specification influence among homeowner-driven renovation projects. Contractor loyalty programs anchored through pro-desk relationships now compete with traditional wholesale distribution for residential volume flows. This channel rotation concentrates in Sun Belt markets where insurance-mandated upgrades drive emergency replacement cycles.
Plastic Roofing Tiles Market Segmentation
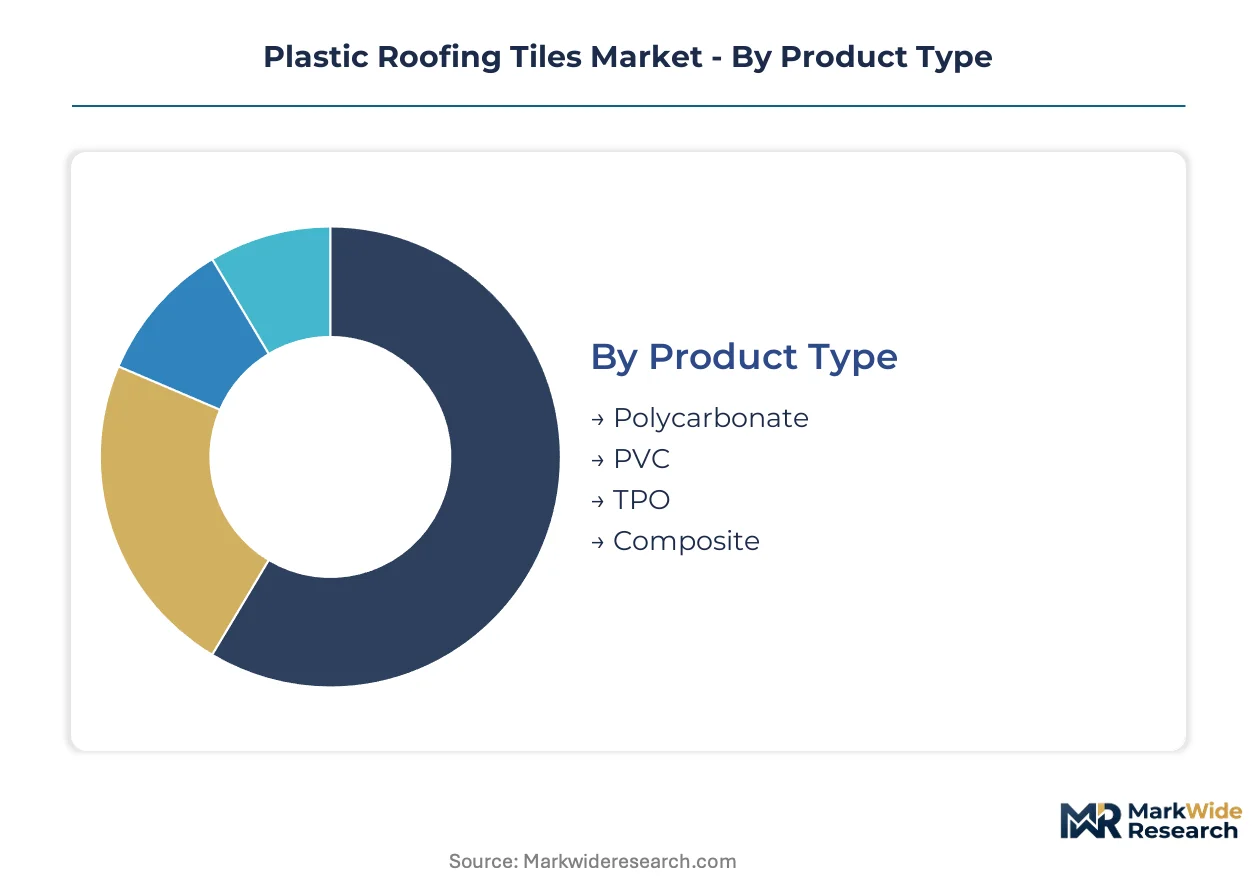
Segmentation in plastic roofing tiles reveals how material specifications, installation economics, and channel access create distinct competitive battlegrounds. Each dimension carries unique regulatory triggers and margin profiles that shape manufacturer resource allocation.
Product Type:
ASTM D3161 and Miami-Dade County certification protocols create divergent compliance burdens across polymer chemistries, compressing development timelines for wind-rated formulations.
- Polycarbonate:High-impact thermoplastic with optical-grade clarity retention and Class 4 hail resistance ratings. Demand concentrates in Texas hill country residential estates where insurance mandates drive specification toward documented impact performance. UV-stabilized grades command specification preference in high-altitude Colorado markets with intense solar exposure.
- PVC:Chlorinated polymer compound with inherent flame resistance and chemical stability in corrosive environments. Agricultural processing facilities in Iowa and Nebraska specify PVC systems for ammonia-rich ventilation exhaust zones where metal roofing degrades rapidly. Recycled-content formulations penetrate LEED-targeted commercial construction in California.
- TPO:Thermoplastic olefin blends offering weldable seams and reflective cool-roof properties qualifying for IRA tax credits.
- Composite:Multi-layer engineered systems combining polymer cores with mineral fillers for slate and clay aesthetic replication.
Polycarbonate handles the majority of throughput in certified impact-rated applications; TPO is climbing the fastest as cool-roof incentives expand across Sun Belt states.
Installation Method:
Labor cost trajectories and union apprenticeship pipeline constraints are elevating prefabricated connection systems over traditional mechanical fastening in high-wage construction markets.
- Snap-Fit:Tongue-and-groove interconnection eliminating field drilling and sealant application. Residential contractors in Florida's Collier and Lee counties specify snap-fit systems where hurricane-season installation windows compress project timelines. The method reduces skilled labor hours by eliminating torque-specified fastener sequences.
- Bolt-On:Through-fastened mechanical attachment with engineered washer systems for uplift resistance. Commercial roofing contractors in Oklahoma anchor bolt-on specifications for warehouse and distribution center envelopes where insurance underwriters demand documented pull-out strength.
- Adhesive:Structural bonding agents enabling seamless surface continuity in low-slope architectural profiles.
- Interlocking:Three-dimensional geometric engagement creating multi-point load distribution across tile arrays.
Snap-Fit captures the dominant share of new residential volume; Adhesive is expanding most quickly in architectural retrofit segments seeking minimal penetration.
End User:
FEMA building code adoption cycles and state insurance commission mandates create asynchronous demand pulses across structural occupancy categories.
- Residential:Single-family and multi-family housing applications governed by ICC-ES evaluation reports and local amendment adoptions. Florida's statewide building code triggers replacement cycles in coastal counties where Citizens Property Insurance requires Class 4 documentation for continued coverage. Texas windstorm certification drives parallel specification in Gulf Coast counties from Corpus Christi to Beaumont.
- Commercial:Retail, office, and hospitality structures with membrane roofing overlays and aesthetic facade requirements. California Title 24 energy standards push cool-roof specifications in Los Angeles and San Diego metropolitan construction.
- Industrial:Manufacturing and logistics facilities prioritizing corrosion resistance and rapid installation.
- Agricultural:Dairy, poultry, and equipment storage structures in high-humidity environments.
Residential absorbs the largest absolute volume; Agricultural is gaining share fastest as Midwest livestock operators replace failing metal systems.
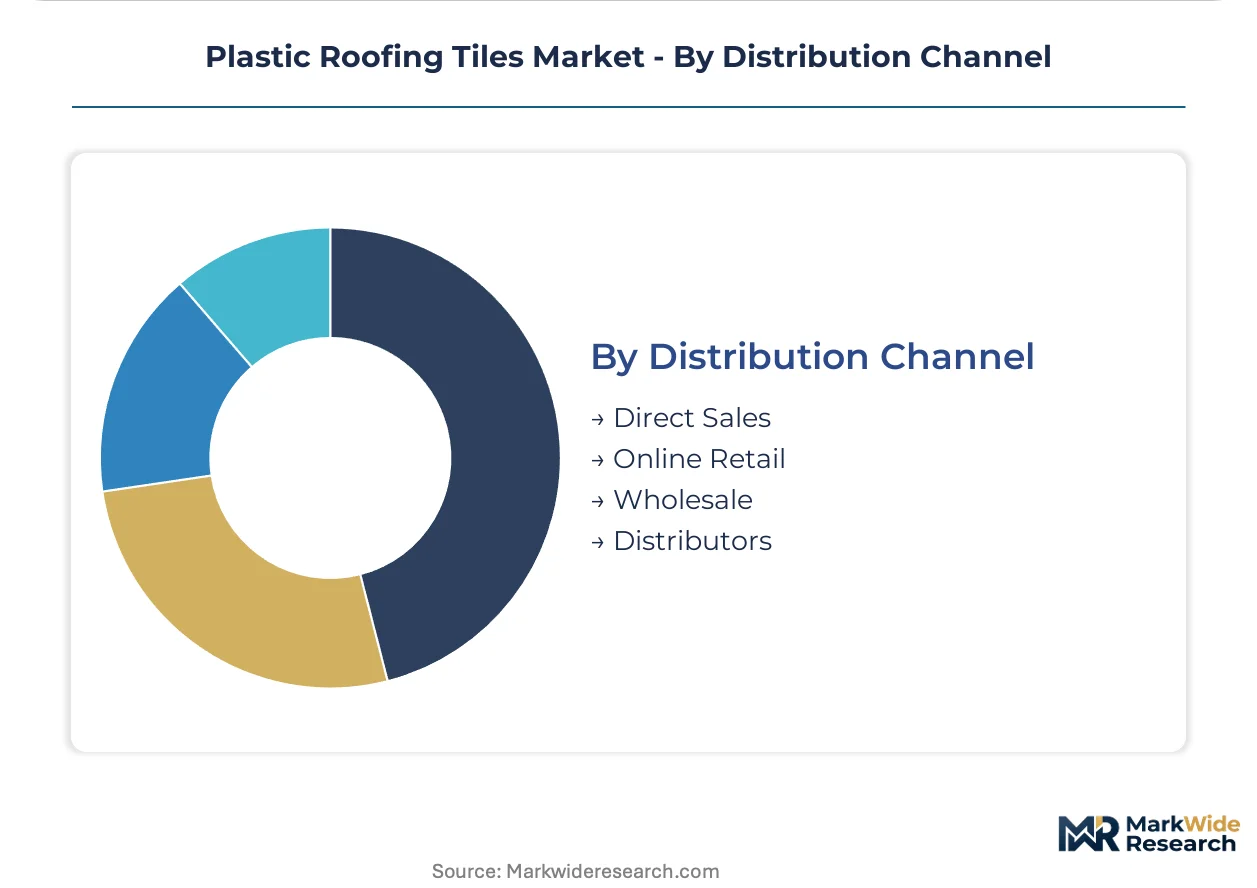
Distribution Channel:
Channel economics bifurcate between specification-influencing retail presence and project-scale direct procurement with divergent working capital requirements.
- Direct Sales:Manufacturer-to-contractor relationships for large commercial and agricultural contracts with predictable volume schedules. GAF Materials Corporation and CertainTeed Corporation anchor national account programs bypassing wholesale markups for multi-site retail rollouts. Direct channels concentrate in Texas and Florida where emergency replacement cycles demand rapid material mobilization.
- Wholesale:Regional distribution centers serving contractor yards with inventory float and credit terms. ABC Supply and Beacon Roofing Supply dominate Sun Belt wholesale flows with pro-desk specification influence.
- Online Retail:E-commerce platforms with contractor verification systems and volume pricing tiers.
- Distributors:Independent stocking distributors with local market knowledge and installation training capabilities.
Wholesale maintains the dominant throughput position; Direct Sales is expanding most quickly as large contractors consolidate procurement across multi-state footprints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in hurricane-exposed US coastal markets where insurance mandates accelerate specification velocity, while European markets trade certification burden for margin compression under REACH compliance costs.
United States
Florida's statewide building code and Texas windstorm certification create dual demand anchors for Class 4 impact-rated systems. EPA stormwater runoff rules tighten permeability thresholds for municipal procurement in combined sewer overflow districts. The Gulf Coast corridor from Corpus Christi to Tampa concentrates emergency replacement volume during compressed hurricane-season installation windows.
Germany
Energy-efficient building retrofits under the EU Green Deal accelerate cool-roof specifications for commercial envelopes. REACH regulations constrain recycled-content formulations through phthalate restrictions on PVC compounds. The Rhine-Ruhr industrial cluster hosts formulation R&D centers serving Central European distribution networks.
China
Rapid urbanization in Yangtze River Delta megacities drives demand for lightweight seismic-resistant roofing in high-rise residential construction. GB standards for building materials enforce flame-resistance testing that favors PVC chemistry over polycarbonate alternatives. Guangdong Province manufacturing bases supply cost-competitive exports to Southeast Asian construction markets.
Australia
Bushfire-prone regions in New South Wales and Victoria specify non-combustible roofing materials under AS 3959 construction standards. Cool-roof rebate programs in Queensland accelerate reflective TPO adoption for residential energy efficiency. Perth's mining boom corridors concentrate industrial warehouse construction demanding rapid-installation polymer systems.
Brazil
São Paulo's commercial construction sector specifies synthetic slate aesthetics for upscale retail and hospitality facades. ANVISA pharmaceutical manufacturing standards indirectly shape clean-room roofing specifications for industrial facilities. The Southeast region's dairy belt drives agricultural outbuilding demand for corrosion-resistant ventilation systems.
Plastic Roofing Tiles Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the plastic roofing tiles sector. Integrated resin producers leverage captive polymer supply chains to compress raw material volatility, while specialty compounders differentiate through recycled-content formulations and LEED-targeted specification capture. The competitive structure fragments across three strategic tiers: multinational building materials conglomerates with multi-channel distribution, regional compounders serving insurance-mandated replacement cycles, and import-dependent price competitors in non-certified segments. Dominant competitive moves include backward integration into resin production and contractor loyalty program anchoring through pro-desk retail placement.
Among North American building materials specialists, GAF Materials Corporation, CertainTeed Corporation, and EcoStar LLC occupy positions reflecting divergent strategic archetypes. GAF exemplifies the integrated multinational with upstream polymer control and national account direct sales penetration. CertainTeed represents multi-channel distribution scale through wholesale and big-box retail placement. EcoStar sits within the sustainability-focused tier, anchoring specification preference in green building certification projects. These three entities collectively illustrate how competitive positioning bifurcates between cost-structure defense and premium-tier specification capture.
| Leading Market Players |
|---|
| GAF Materials Corporation |
| EcoStar LLC. |
| CertainTeed Corporation |
| TAMKO Building Products |
| Brava Roof Tile LLC. |
| IKO Industries Ltd. |
| Sika AG |
| Monier |
| Boral Limited |
| Others |
Value Network & Pricing Analysis
Florida Product Approval and Miami-Dade County certification protocols gate both supply qualification and price differentiation simultaneously, compressing development timelines while stratifying certified manufacturers above commodity imports lacking weathering documentation. Manufacturers must absorb extended testing cycles and documentation costs that translate directly into premium positioning for Class 4 impact-rated systems.
Pricing Analysis
The customization-premium spread separates configured-to-order Class 4 certified systems from standard-grade commodity tiles lacking impact documentation. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume commitment, with large contractors commanding favorable terms through multi-site procurement consolidation. Price differentiation hinges on ASTM D3161 wind-resistance documentation and Miami-Dade County product approval status. Pricing pressure stems from petrochemical feedstock volatility compressing compounder margins during upstream supply shocks. Agricultural end-users exhibit highest price sensitivity due to thin operating margins in livestock operations, while coastal residential buyers in Florida and Texas show lowest sensitivity given insurance-mandated replacement cycles.
Supply Chain Analysis
Inbound logistics costs from Gulf Coast resin production concentration expose tile manufacturers to hurricane-related supply interruptions and port congestion along Houston-Galveston and Tampa Bay trade lanes. Raw material sourcing draws from chlor-alkali producers in Louisiana, polycarbonate resin manufacturers in Texas, and TPO compounders in Ohio. Supply chain risk centers on single-source geography concentration for PVC and polycarbonate feedstocks. Distribution runs through wholesale regional centers serving contractor yards with inventory float and credit terms, though direct-sales models are encroaching on large commercial and agricultural contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plastic roofing tiles sit in early-cycle expansion as insurance commission mandates in hurricane-prone states accelerate specification velocity beyond traditional product development cadences. This regulatory tailwind compresses procurement timelines and elevates certified supply scarcity.
For Market Incumbents: Secure captive polymer supply chains through backward integration into resin production or long-term offtake agreements with Gulf Coast chlor-alkali producers. Defend channel position by anchoring contractor loyalty programs through pro-desk retail placement at ABC Supply and Beacon Roofing Supply locations. Accelerate Class 4 impact certification cycles ahead of evolving ASTM standards to maintain specification preference against emerging recycled-content specialists. For New Entrants and Emerging Players: Anchor in agricultural outbuilding retrofits across Iowa, Nebraska, and Wisconsin dairy belts where corrosion-resistant PVC systems displace failing metal roofing. Target direct-to-contractor digital platforms for large commercial projects with predictable volume requirements, bypassing wholesale markups that compress margins. Pursue LEED-targeted specification capture in California commercial construction through recycled-content formulations that command architect preference. For Investors and Strategic Acquirers: IRA energy-efficiency tax credit expansion reshapes the acquisition landscape by elevating cool-roof formulation specialists above commodity tile producers. Long-term viability favors compounders with demonstrated Miami-Dade County and Florida Product Approval credentials that serve as durable competitive moats. Watch state insurance commission mandate adoptions across Gulf Coast jurisdictions as the primary inflection signal for demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive PVC and polycarbonate supply compresses raw material volatility exposure for compounders. |
| Class 4 Impact Certification Acceleration | Miami-Dade County approval unlocks Florida coastal markets with insurance-mandated replacement cycles. |
| Direct-to-Contractor Digital Platform Launch | E-commerce channels bypass wholesale markups for large agricultural and commercial volume contracts. |
| Recycled-Content Formulation Investment | LEED-targeted specifications command premium positioning in California commercial construction. |
| Pro-Desk Retail Placement Expansion | Contractor loyalty programs at ABC Supply and Beacon Roofing Supply anchor residential specification influence. |
Research Methodology
The analysis maps polycarbonate, PVC, TPO, and composite product segments, each validated through plant managers at resin production facilities, procurement leads at roofing contractors, distribution channel partners, and technical R&D directors at compounders. Primary interviews with these stakeholders combined with secondary validation from ASTM standards documentation, EPA stormwater runoff rule filings, state insurance commission mandate records, and SEC 10-K disclosures from building materials conglomerates. Bottom-up volume estimates triangulated against top-down market sizing across polymer chemistry and installation method dimensions.
Consistency checks validated outputs against external benchmarks including customs and trade data flows, ACC resin production reports, and contractor association membership surveys. The projection horizon spans product type, installation method, end-user category, and distribution channel segmentation with regional regulatory cluster overlays. CAGRs derived from regression analysis of historical adoption curves adjusted for code adoption cycle timing. Industry-specific forecast inputs include FEMA building code amendment schedules and state-level insurance mandate propagation patterns.
Material uncertainties — polymer feedstock cost trajectories, regional code adoption delays, and hurricane-season supply disruption frequency — sit outside the modeled envelope. Forecasts reflect assumptions regarding certification timeline compression and contractor workforce pipeline capacity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Global Panelized and Modular Building System Market
Building & Construction Materials
Acoustical Ceiling Market
Building & Construction Materials
Rubber Expansion Joints Market
Building & Construction Materials
Cement Grinding Aids Market
Building & Construction Materials
Saudi Arabia Concealed Cistern Market
Building & Construction Materials
Saudi Arabia Tiles Market
Building & Construction Materials
Urethane Concrete Sealer Market
Building & Construction Materials
Warm Mix Asphalt Market
Building & Construction Materials
Germany Construction Chemicals Market
Building & Construction Materials
Fire Rated Glass Market
Building & Construction Materials
United States Gutter Guards Market
Building & Construction Materials
Cement Sacks Market
Building & Construction Materials
Concrete Sealer Market
Building & Construction Materials
North America Concrete Conditioner Market
Building & Construction Materials
Runway Pavement Grade Asphalt Market
Building & Construction Materials
North America Concrete Superplasticizer Market