
 Italy Ceramic Tiles Market | 2026-2036
Italy Ceramic Tiles Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Ceramic Tiles Market Foresight
The EU Green Deal's embodied carbon requirements for construction materials is recalibrating procurement criteria across Italian building supply chains. Florim Ceramiche S.p.A. leverages vertical integration from raw material extraction to finished slab distribution, sustaining cost control across volatile energy markets. Panariagroup Industrie Ceramiche S.p.A. anchors its competitive position through concentrated R&D spending on thin-profile large-format porcelain, while Marazzi Group dominates heritage design licensing that commands premium positioning in heritage restoration projects.
Italy ceramic tiles are sintered clay-based surfacing materials fired at temperatures exceeding 1,100°C, with porcelain variants achieving water absorption below 0.5% through vitrification of kaolin-rich bodies. These products serve as structural and decorative finishes for floors, walls, and facades across residential, commercial, and infrastructure applications. Porcelain tiles now lead volume contribution due to frost resistance and through-body color consistency that reduces lifecycle replacement costs in outdoor spaces. Residential applications retain the largest value share, though commercial specifications for hospitality and healthcare are expanding fastest as anti-bacterial surface finishes gain specification traction among architects.
Italy's Ministry of Enterprises and Made in Italy enforces CE marking compliance under the Construction Products Regulation, while ECHA REACH restrictions on crystalline silica in manufacturing processes are reshaping workplace safety investments and raw material sourcing protocols. The EU Ecodesign for Sustainable Products Regulation will soon mandate digital product passports that trace environmental performance across supply chains. Stakeholders must monitor how forthcoming carbon border adjustments reshape export competitiveness for Sassuolo-cluster producers serving Middle Eastern and North African project markets.
Market Dynamics
The Sassuolo ceramic district's kiln technology transition under EU Green Deal embodied carbon mandates is restructuring capital allocation across Emilia-Romagna's clustered producers. Natural gas price volatility and REACH crystalline silica compliance costs are forcing simultaneous process reengineering and workplace safety investments.
Growth Catalysts
- EU Green Deal embodied carbon thresholds:Procurement criteria across Italian construction supply chains now prioritize low-carbon kiln outputs, redirecting public and private project specifications toward certified domestic manufacturers.
- Large-format thin-profile porcelain:Architectural specifications for reduced material weight in high-rise facades and heritage renovations are expanding addressable square-meterage per project.
- Milan and Rome luxury residential renovation:Premium property refurbishment cycles in these metropolitan cores are sustaining specification rates for designer-grade porcelain surfaces.
Market Restraints
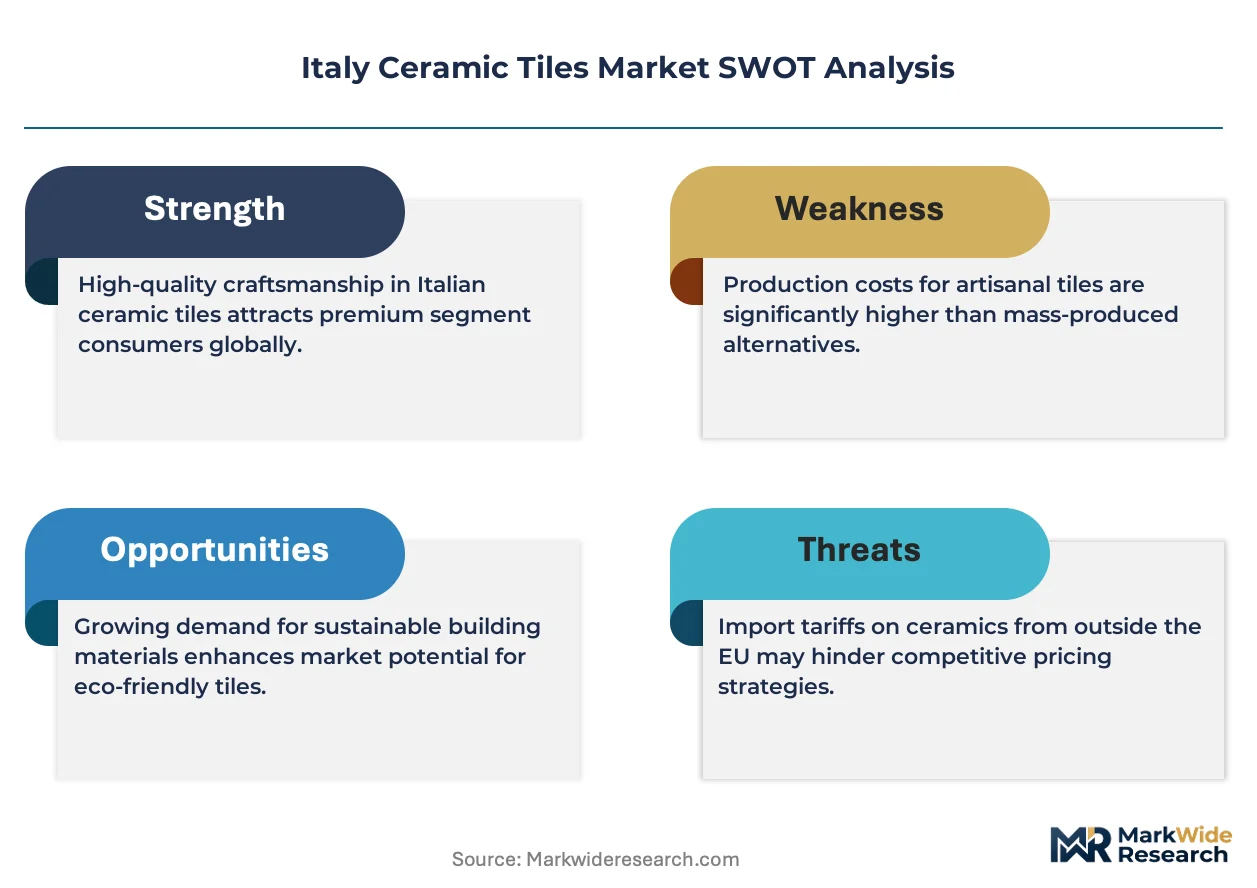
- Natural gas input cost volatility:Kiln firing energy requirements expose margin structures to wholesale gas price swings that ceramic producers cannot fully pass through to fixed-price construction contracts.
- Sassuolo supplier concentration:Geographic clustering of specialized equipment vendors and technical labor pools creates systemic vulnerability to localized supply disruptions or labor actions.
- Vinyl and laminate flooring substitution:Lower-cost resilient flooring alternatives capture economy-tier residential renovation volume, compressing entry-level ceramic tile addressable market.
Strategic Opportunities
- Southern Italy commercial hospitality:Underpenetrated resort and hotel development corridors in Puglia and Sicily present specification growth for frost-resistant outdoor porcelain.
- Digital product passports:EU Ecodesign for Sustainable Products Regulation mandates will advantage early-adopting Italian producers with traceable supply chain data for export markets.
- Healthcare anti-bacterial surfaces:Hospital and clinic renovation cycles are creating new specification channels for silver-ion or photocatalytic tile finishes.
Industry Challenges
- Kiln engineer and ceramic technician talent pipeline:Specialized firing process expertise is aging out faster than vocational training programs replenish qualified personnel.
- CE marking and ECHA REACH compliance timelines:Documentation and testing protocols for construction product regulation adherence extend new product development cycles.
- Legacy natural gas kiln asset stranding:Electrification and hydrogen pilot investments risk premature depreciation of recently upgraded conventional firing equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Ceramic Tiles Market |
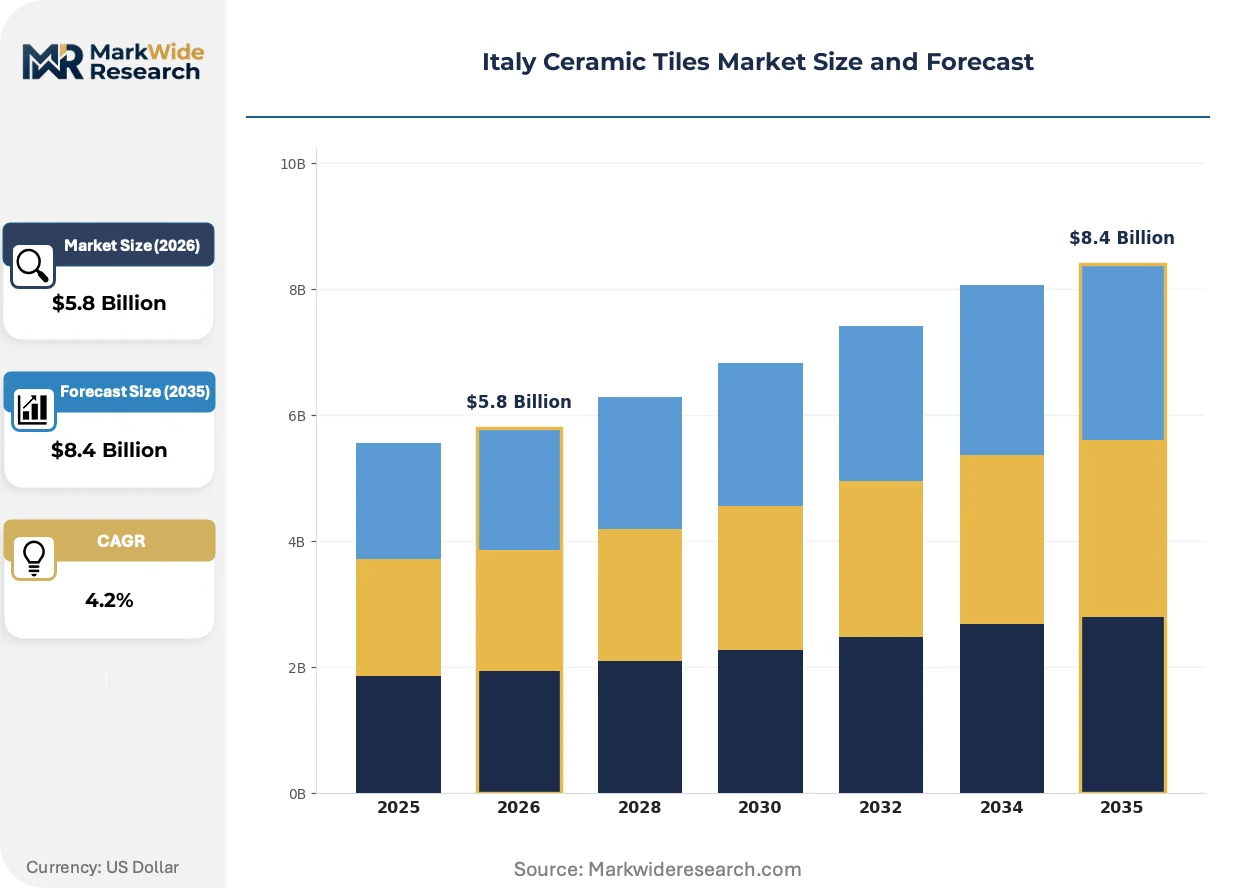
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $8.4 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glazed Tiles, Unglazed Tiles, Porcelain Tiles, Stoneware Tiles End Use: Residential Applications, Commercial Applications, Industrial Uses, Outdoor Spaces Thickness: Thin Tiles, Standard Tiles, Thick Tiles, Double Thickness Surface Finish: Polished, Matt, Satin, Textured |
| Companies Covered | Florim Ceramiche S.p.A., Panariagroup Industrie Ceramiche S.p.A., ABK Group Industrie Ceramiche S.p.A, Marazzi Group, Iris Ceramica Group, Ceramiche Atlas Concorde Spa, Gruppo Concorde, Casalgrande Padana S.p.A., Cooperativa Ceramica d'Imola, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Ceramic Tiles Market Shifts & Advancements
Italian ceramic tile manufacturing is converging digital surface decoration, low-carbon firing, and health-certified finishes into unified product platforms. These technical trajectories are reshaping how architects specify and how distributors inventory.
Continuous inkjet digital printing is unifying aesthetic variation with production efficiency. Hospitality and retail designers now specify unlimited pattern repeats without minimum order constraints. This technology is compressing lead times from design conception to installed surface, enabling just-in-time project staging that reduces distributor inventory carrying costs.
EU Ecodesign for Sustainable Products Regulation digital passport requirements are mandating supply chain traceability infrastructure. Italian manufacturers must deploy batch-level environmental data collection from raw material extraction through firing. Ceramic tile exporters to Middle Eastern and North African project markets face accelerated compliance investments to maintain specification eligibility.
Architects are consolidating specification authority around health-certified surface finishes. Anti-bacterial and air-purifying tile properties are displacing untreated alternatives in healthcare and premium residential verticals. This preference shift concentrates most visibly in Lombardy and Lazio metropolitan renovation markets where building certification schemes reward indoor environmental quality metrics.
Italy Ceramic Tiles Market Segmentation
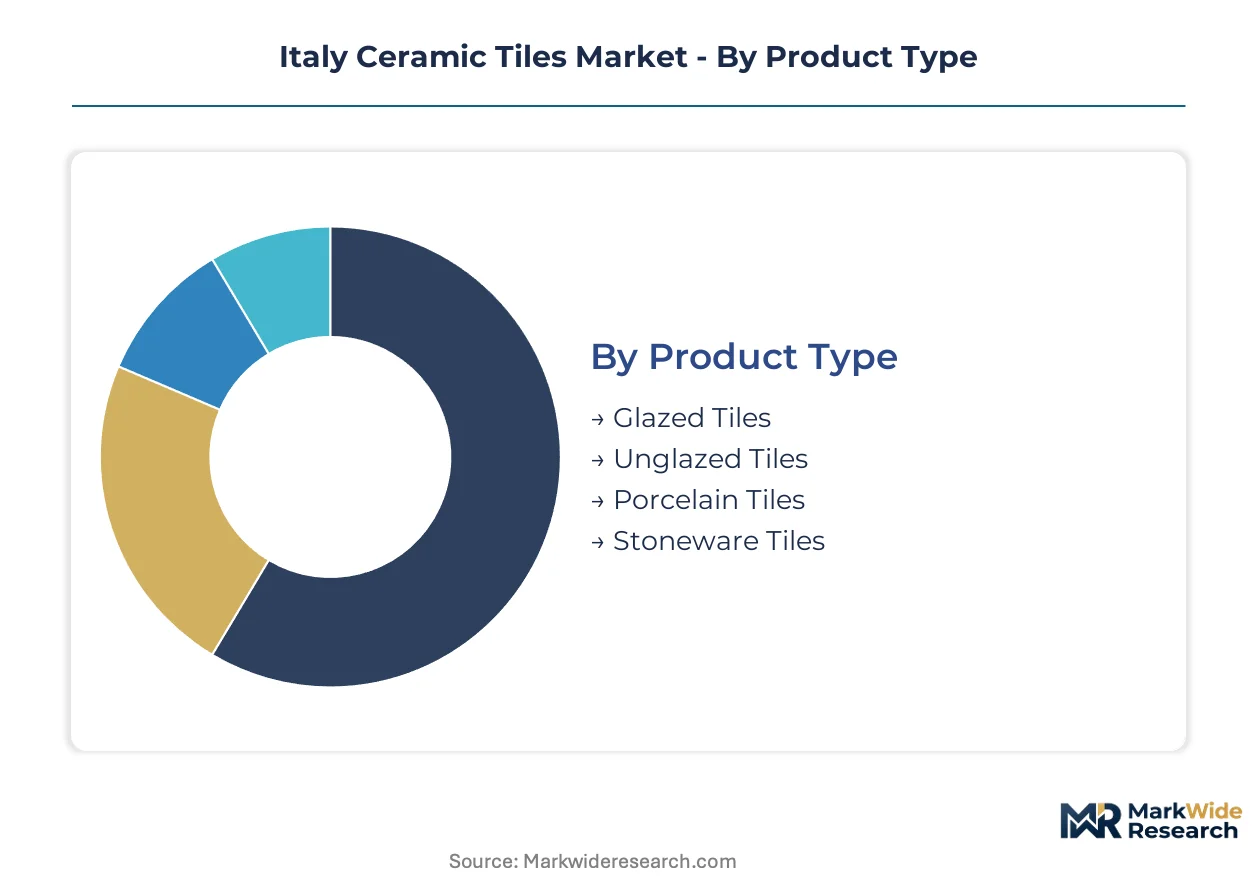
Segmentation reveals how Italian ceramic tile demand fragments across technical specifications and installation contexts. Upgrade cycles differ dramatically between heritage restoration requiring thick-format heritage reproductions and high-rise facades demanding thin-profile large-format porcelain.
Product Type:
Replacement timelines stretch from 15-20 years for standard glazed wall tiles to 40-plus years for vitrified porcelain in exterior applications, conditioning manufacturer inventory strategies and distributor stocking depths.
- Porcelain Tiles:Vitrified bodies fired above 1,200°C achieve water absorption below 0.5%, delivering frost resistance for Emilia-Romagna's outdoor specifications. Milan and Rome luxury residential renovations specify through-body color consistency that eliminates visible wear patterns in high-traffic zones.
- Glazed Tiles:Glass-based surface coatings enable unlimited digital pattern variation through continuous inkjet printing. Sassuolo-cluster producers concentrate glazed tile output for rapid-turn hospitality refurbishment cycles where aesthetic refresh outlasts structural lifespan.
- Unglazed Tiles:Natural clay surfaces without vitreous coating retain slip resistance for wet-area commercial specifications. Quarry tile formats serve industrial kitchen and food processing installations requiring thermal shock resistance.
- Stoneware Tiles:Dense, low-porosity bodies bridge performance tiers between standard ceramics and full porcelain. Regional distributors stock stoneware for mid-market residential flooring where budget constraints preclude porcelain specification.
Volume placements concentrate in glazed tiles for interior vertical surfaces; the faster expansion belongs to porcelain tiles capturing exterior and high-traffic specifications.
End Use:
Application context dictates performance certification requirements, with healthcare and hospitality segments demanding anti-bacterial surface treatments that residential specifications rarely require.
- Residential Applications:Floor and wall finishes across single-family homes and multi-unit housing constitute the foundational demand base. Lombardy and Lazio metropolitan renovation markets sustain premium specification rates for large-format porcelain in open-plan living spaces.
- Commercial Applications:Retail, hospitality, and healthcare installations specify certified slip resistance and load-bearing capacity. Hotel development corridors in Puglia and Sicily are expanding frost-resistant outdoor porcelain specifications for resort pool decks and terraces.
- Industrial Uses:Chemical-resistant quarry tiles and heavy-duty pavers serve manufacturing floors and warehousing facilities. Food processing plants require unglazed surfaces that withstand thermal cycling and aggressive cleaning protocols.
- Outdoor Spaces:Freeze-thaw durability and slip resistance certification dominate specification criteria. Public infrastructure projects under Italy's National Recovery and Resilience Plan are recalibrating procurement toward low-carbon kiln outputs for plaza and pedestrian zone surfacing.
Residential Applications retain the largest installed base; Commercial Applications are climbing the fastest as hospitality development accelerates across Southern Italy.
Thickness:
Material volume per square meter directly impacts freight costs, installation labor, and structural load calculations, creating distinct supply chain economics for each thickness tier.
- Thin Tiles:Profiles below 6mm reduce material weight for high-rise facade cladding and heritage building renovations where structural load limits constrain specification. Large-format thin porcelain enables faster installation with reduced adhesive consumption.
- Standard Tiles:8-10mm thickness dominates residential flooring and wall applications where conventional installation methods prevail. Sassuolo producers optimize kiln throughput around this dimensional sweet spot that balances durability with material efficiency.
- Thick Tiles:12-15mm profiles serve commercial and light industrial flooring requiring enhanced impact resistance. Retail and hospitality specifications favor thick tiles for areas with rolling load traffic and heavy fixture placement.
- Double Thickness:20mm-plus pavers enable dry-installation systems for exterior raised flooring and rooftop terraces. Outdoor hospitality specifications in coastal resort markets specify double-thickness porcelain for pedestal-mounted installations that manage drainage and conceal utilities.
Standard Tiles dominate production volume; Thin Tiles are gaining share fastest as architectural specifications prioritize material efficiency in vertical construction.
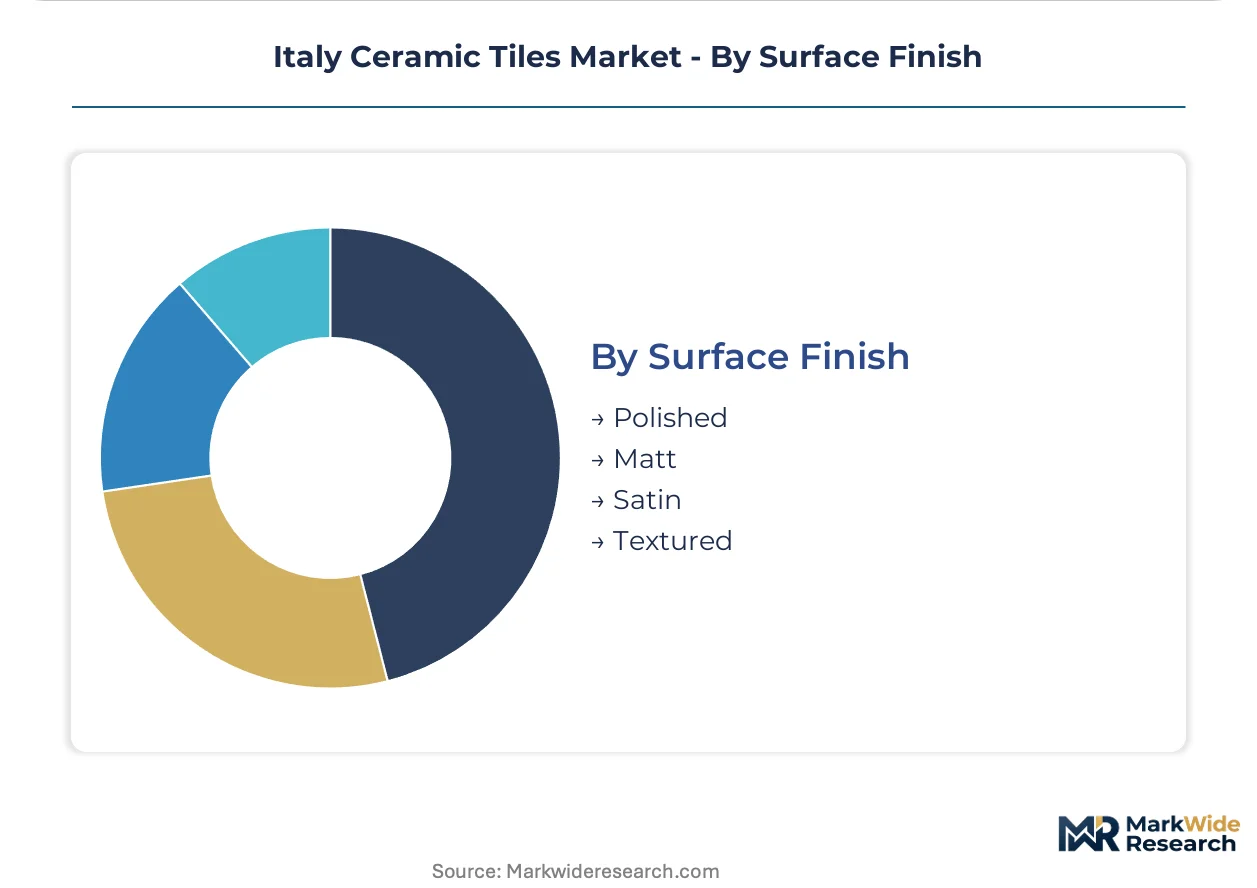
Surface Finish:
Finish selection determines both aesthetic positioning and functional performance, with slip resistance certification increasingly mandatory for commercial and outdoor specifications.
- Polished:Mechanical surface grinding creates mirror-like reflectivity that amplifies spatial perception in residential and hospitality interiors. Polished porcelain commands premium positioning in Milan luxury renovation markets where visual impact drives specification.
- Matt:Low-sheen surfaces balance aesthetic subtlety with practical maintenance across residential and commercial applications. Matt finishes dominate contemporary architectural specifications seeking reduced glare and fingerprint concealment.
- Satin:Intermediate sheen levels bridge polished and matt aesthetics for transitional design schemes. Satin specifications concentrate in hospitality interiors where lighting design requires controlled reflectivity without high-maintenance polishing.
- Textured:Physical surface relief enhances slip resistance for wet-area and outdoor installations. Pool surrounds, spa facilities, and exterior ramps specify textured finishes to meet safety certification requirements under CE marking protocols.
Matt finishes capture the broadest specification base; Textured finishes are expanding most quickly as outdoor and wet-area safety regulations tighten across Italian construction codes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sassuolo anchors Italy's ceramic tile production, with the Emilia-Romagna cluster commanding export logistics and design innovation pipelines that feed Milan and Rome renovation markets.
Lombardy
Milan's luxury residential renovation cycle sustains premium porcelain specification for open-plan living spaces. CE marking compliance under the Construction Products Regulation shapes procurement criteria for high-end property developments. The metropolitan core concentrates architect-specified large-format thin tiles for heritage building adaptations.
Lazio
Rome's heritage restoration projects drive demand for thick-format reproduction tiles and through-body color consistency. Italy's National Recovery and Resilience Plan green building incentives redirect public project specifications toward low-carbon kiln outputs. The capital's clustered design studios influence national aesthetic trends for hospitality and residential verticals.
Emilia-Romagna
The Sassuolo ceramic district's kiln technology transition under EU Green Deal embodied carbon mandates restructures capital allocation across clustered producers. ECHA REACH crystalline silica restrictions reshape workplace safety investments and raw material sourcing protocols. This industrial corridor maintains captive supply of specialized equipment vendors and technical labor pools.
Piedmont
Turin's commercial hospitality development expands specification channels for frost-resistant outdoor porcelain in hotel and resort projects. Regional distributors stock mid-market stoneware for residential flooring where budget constraints preclude full porcelain specification. The sub-region's logistics infrastructure supports export staging to French and Swiss border markets.
Southern Italy
Puglia and Sicily resort corridors present underpenetrated growth for anti-bacterial surface finishes in pool decks and terraces. Public infrastructure projects recalibrate procurement toward certified slip resistance for plaza surfacing. Coastal hospitality specifications favor double-thickness pedestal-mounted installations that manage drainage and conceal utilities.
Italy Ceramic Tiles Market Competitive Landscape
The competitive structure tilts toward vertically integrated specialists with backward integration into raw material extraction. Sassuolo-clustered producers dominate through geographic concentration of firing expertise and design talent. Three archetypes prevail: heritage-design licensors, thin-profile porcelain innovators, and export-focused volume manufacturers. Capacity electrification and digital passport compliance investments constitute the dominant competitive moves reshaping capital allocation.
Among Emilia-Romagna-based integrated producers, Florim Ceramiche S.p.A., Panariagroup Industrie Ceramiche S.p.A., and Marazzi Group exemplify the three strategic archetypes. Florim occupies a position anchored in upstream control over raw material extraction through finished slab distribution. Panariagroup sits within the innovation-driven tier, representing concentrated R&D positioning on thin-profile large-format formats. Marazzi anchors the heritage-design licensing vector, exemplifying premium positioning through controlled aesthetic reproduction rights.
| Leading Market Players |
|---|
| Florim Ceramiche S.p.A. |
| Panariagroup Industrie Ceramiche S.p.A. |
| ABK Group Industrie Ceramiche S.p.A |
| Marazzi Group |
| Iris Ceramica Group |
| Ceramiche Atlas Concorde Spa |
| Gruppo Concorde |
| Casalgrande Padana S.p.A. |
| Cooperativa Ceramica d'Imola |
| Others |
Supply & Pricing Matrix
Natural gas futures volatility cascades through Sassuolo-cluster production costs into three-tier pricing structure across premium, standard, and economy levels. Kiln firing intensity draws from wholesale energy markets, compressing margins for producers locked into fixed-price construction contracts while rewarding backward-integrated operators with captive clay reserves.
Pricing Analysis
Value-based pricing anchored to lifecycle durability commands premium positioning for through-body porcelain in heritage restoration and high-traffic commercial specifications. Price differentiation hinges on CE marking compliance tier and frost-resistance certification, with Milan and Rome luxury residential buyers showing lowest sensitivity. Cost compression in economy-tier glazed wall tiles intensifies due to vinyl flooring substitution, while public procurement under Italy's National Recovery and Resilience Plan favors certified low-carbon outputs at modest premiums.
Supply Chain Analysis
Regional distribution centers in Modena and Reggio Emilia orchestrate hub-and-spoke patterns feeding Milan, Rome, and export corridors to France and Switzerland. Production gravity centers on Italy's Emilia-Romagna cluster, with secondary clay processing in Spain and Turkey. Raw material dependencies encompass kaolin deposits, feldspar, and natural gas feedstock. Single-source vulnerability concentrates in specialized kiln engineering talent pools. Distribution runs through architect-specified channels for premium tiers and builder-merchant networks for residential volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italy's ceramic tile sector operates as a cost-of-compliance story where EU Ecodesign for Sustainable Products Regulation digital passport mandates erect barrier-to-entry moats for early-adopting producers with traceable supply chain infrastructure.
For Market Incumbents: Anticipate natural gas price volatility and REACH crystalline silica enforcement by accelerating kiln electrification pilots and securing long-term renewable power purchase agreements. Consolidation around digital passport-ready batch tracking systems will defend position against emerging Polish and Turkish competitors with lower compliance burdens. Prioritize captive supply of specialized ceramic technicians through vocational partnerships. For New Entrants and Emerging Players: EU Green Deal embodied carbon thresholds in Italy open a window for specification capture in Southern Italy's underpenetrated Puglia and Sicily hospitality corridors. Target anti-bacterial surface finishes for healthcare renovation cycles where certification requirements deter low-cost imports. Enter through design-studio specification relationships rather than distributor price competition. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale producers in Emilia-Romagna with intact clay reserves and legacy kiln assets suitable for hydrogen retrofit. Long-term viability hinges on digital passport compliance infrastructure and export logistics access to North African project markets. Monitor carbon border adjustment mechanism announcements as inflection indicator for Sassuolo-cluster export competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Kiln Electrification Investment | EU Green Deal compliance secures specification eligibility in public procurement channels. |
| Digital Product Passport Deployment | Ecodesign Regulation adherence enables continued access to Middle Eastern export markets. |
| Anti-Bacterial Surface Certification | Silver-ion and photocatalytic finishes capture healthcare specification growth in Lombardy. |
| Thin-Profile Large-Format Capacity Expansion | Reduced material weight specifications penetrate high-rise facade and heritage renovation segments. |
| Clay Reserve Backward Integration | Captive raw material supply insulates margin structures from volatile energy input costs. |
Research Methodology
Multi-period observation of kiln technology transitions, natural gas input costs, and CE marking compliance timelines anchored the trend analysis, supplemented by interviews with ceramic plant managers, architect specification consultants, distributor inventory planners, and ECHA regulatory affairs specialists. Secondary validation drew from Italy's Ministry of Enterprises filings, EU Construction Products Regulation documentation, Sassuolo ceramic district trade association reports, and Emilia-Romagna industrial energy consumption data. Bottom-up production capacity modeling and top-down construction spend allocation triangulated volume estimates.
Input-output matrices mapped clay extraction through finished tile distribution across product type, end-use application, thickness tier, and surface finish segmentation dimensions. CAGRs derived from installed base replacement cycles, construction permit trajectories, and export order book trends. Forecast inputs incorporated EU carbon border adjustment mechanism implementation assumptions and National Recovery and Resilience Plan disbursement schedules.
The model assumes a particular technology adoption path for hydrogen and electrified kiln deployment; alternative pathways for conventional natural gas firing with carbon capture would alter the outlook for asset stranding risk. Forecasts reflect documented assumptions regarding regulatory timeline adherence and energy price normalization. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Fire Hydrant System Market
Building & Construction Materials
Middle-East and Africa Construction Adhesives Market
Building & Construction Materials
Global Anchors and Grouts Market
Building & Construction Materials
Aluminum Curtain Wall Market
Building & Construction Materials
Concrete Resurfacer Market
Building & Construction Materials
Plastic Roofing Tiles Market
Building & Construction Materials
North America Industrial Flooring Market
Building & Construction Materials
India Stainless Steel Plumbing Pipes and Fittings Market
Building & Construction Materials
Building and Construction Sealants Market
Building & Construction Materials
Prefabricated Bathroom Modules Market
Building & Construction Materials
Acoustic Plasterboard Market
Building & Construction Materials
Seal Coat Market
Building & Construction Materials
Acoustic Doors Market
Building & Construction Materials
Concrete Repair Product Market
Building & Construction Materials
Global Intelligent Sanitary Ware Market
Building & Construction Materials
Brick Market