
 Asphalt Modifiers Market | 2026-2036
Asphalt Modifiers Market Size, Share, and Industry Trends Forecast 2026-2036
Asphalt Modifiers Market Analysis
Government agencies are rotating procurement priorities toward climate-resilient pavement specifications across federal and state programs. Kraton Corporation leverages styrenic block copolymer expertise to dominate high-performance grade supply chains in North America. BASF SE sustains R&D intensity in reactive modifier chemistry for polymer-modified binder applications. Dow anchors warm mix additive production through integrated polyethylene amine platforms serving contractors directly.
Asphalt modifiers are specialty chemical additives blended into bitumen to alter rheological properties, with polymer modifiers typically comprising 3–8% styrene-butadiene-styrene or ethylene-vinyl-acetate by weight to improve elasticity and rutting resistance at elevated temperatures. Their primary purpose is extending pavement service life while reducing maintenance frequency in heavy-traffic corridors. Polymer modifiers occupy the largest value pool due to established specification in Superpave performance grades, while warm mix additives represent the fastest-growing category as agencies mandate lower production temperatures for emissions compliance. Chemical modifiers concentrate margin in premium oxidation-resistant formulations for tropical climates.
The Federal Highway Administration enforces Superpave binder specifications through AASHTO M320, directly determining which modifier chemistries qualify for interstate funding across the United States. State DOTs in California, Texas, and Florida layer additional performance tests that favor polymer-modified binders in high-shear environments. Stakeholders must monitor specification divergence between federal baseline requirements and emerging state-level low-carbon procurement mandates that could requalify additive portfolios.
Market Dynamics
Federal and state transportation agencies are tightening performance-grade specifications for polymer-modified binders, forcing contractors to upgrade additive portfolios while warm mix chemistry gains regulatory preference for emissions reduction.
Growth Catalysts
- Superpave M320 Specifications:The Federal Highway Administration's binder grading system mandates polymer modifiers for interstate highway funding, locking in additive demand across heavy-traffic corridors.
- China Highway Rehabilitation:Provincial transportation budgets in Shandong and Guangdong prioritize polymer-modified asphalt for urban expressway reconstruction, concentrating modifier procurement.
- Warm Mix Additive Chemistry:Polyethylene amine formulations enable production temperature reductions that satisfy state-level emissions compliance mandates without sacrificing performance grades.
Market Restraints
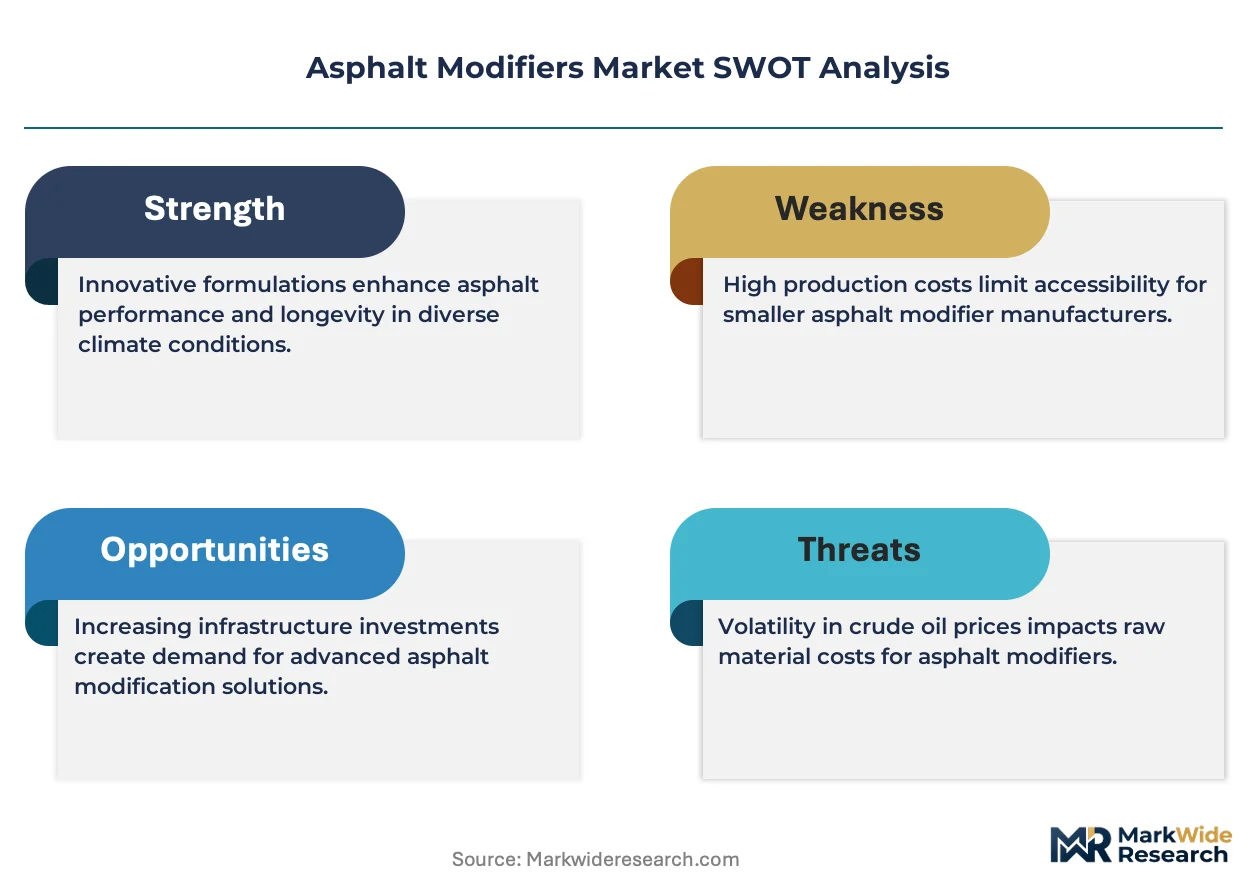
- Styrene-Butadiene Input Volatility:SBS polymer feedstock costs fluctuate with butadiene monomer supply from petrochemical crackers, compressing modifier blend margins during crude price spikes.
- Supplier Concentration Risk:Specialty chemical production for reactive modifiers clusters among integrated petrochemical complexes in the US Gulf Coast and Germany's Rhine-Ruhr corridor.
- Portland Cement Substitution:Full-depth reclamation with cement stabilization competes for pavement rehabilitation budgets in municipalities with limited polymer-modified asphalt expertise.
Strategic Opportunities
- India National Highway Expansion:The Ministry of Road Transport's Bharatmala program specifies polymer-modified binders for high-altitude and high-rainfall corridors, opening import substitution potential for domestic formulation plants.
- Recycled Asphalt Integration:Rejuvenator chemistry that restores aged binder properties enables higher reclaimed asphalt pavement content while maintaining Superpave performance grades.
- California Low-Carbon Procurement:The state's Buy Clean California Act creates preference margins for warm mix additives with verified lifecycle emissions reductions.
Industry Challenges
- Performance-Grade Testing Bottlenecks:Dynamic shear rheometer and bending beam rheometer certification for new modifier formulations requires 12-18 month validation cycles at state DOT laboratories.
- Blending Equipment Retrofit Costs:Terminal and hot-mix plant upgrades for polymer-modified binder storage and metering demand capital outlays that strain mid-sized paving contractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asphalt Modifiers Market |
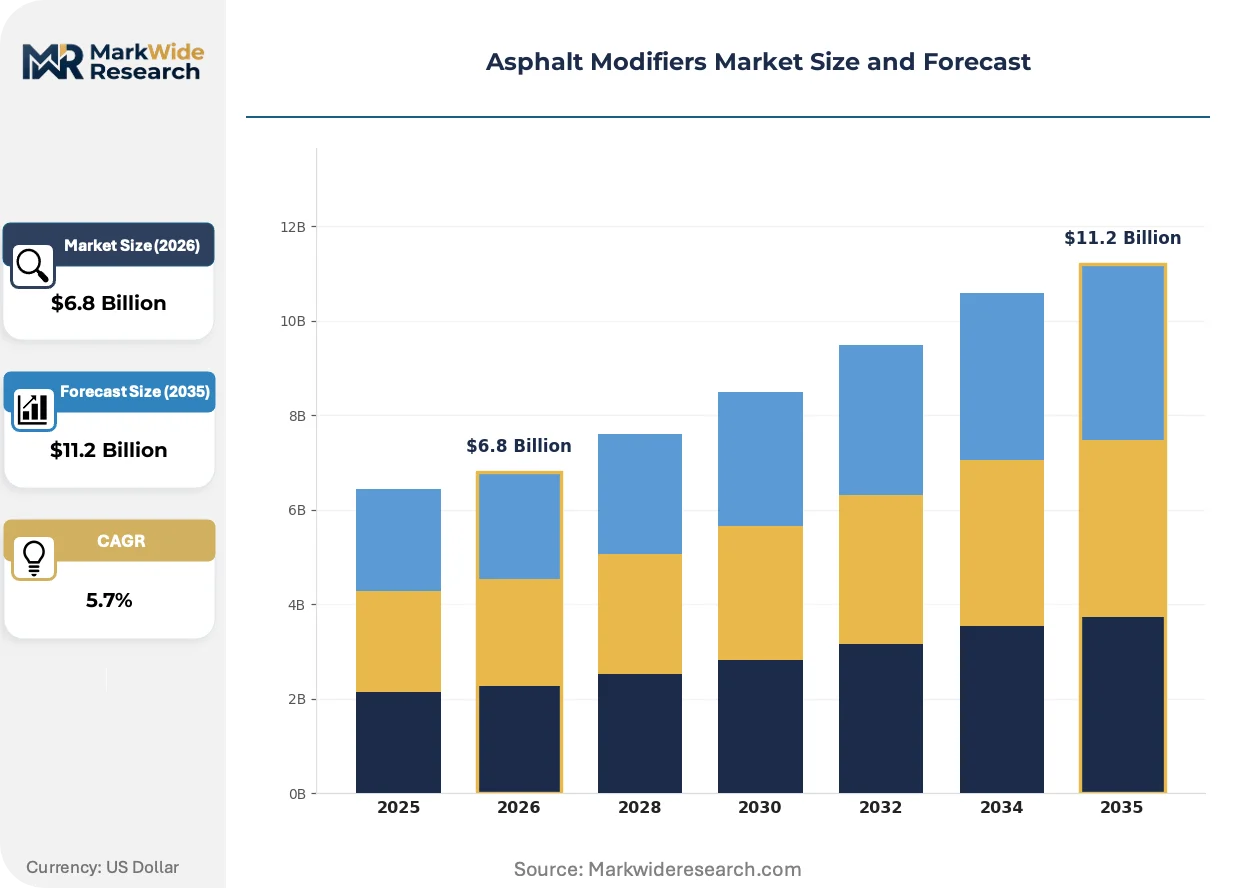
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer Modifiers, Chemical Modifiers, Reactive Modifiers, Warm Mix Additives Application: Road Construction, Airport Runways, Parking Lots, Footpaths Technology: Hot Mix, Warm Mix, Cold Mix, Dense Graded End User: Construction Companies, Government Agencies, Private Developers, Infrastructure Firms |
| Companies Covered | Kraton Corporation, Nouryon, BASF SE, Exxon Mobil Corporation, Honeywell International Inc., Arkema, Evonik Industries AG, Sasol, Dow, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asphalt Modifiers Market Emerging Trajectories
Warm mix additive chemistry is compressing the traditional temperature-performance tradeoff in asphalt production, while regulatory agencies embed lifecycle emissions criteria into material specifications and procurement models evolve toward performance-based contracting.
Bio-based rejuvenator formulations derived from tall oil and waste vegetable oil streams are supplanting petroleum-derived recycling agents in high-RAP content mixes. State DOTs in Minnesota and Texas now specify bio-rejuvenators for pavement preservation contracts. The shift is enabling 40-50% reclaimed asphalt pavement inclusion without grade degradation, compressing demand for virgin polymer modifiers in maintenance applications.
The EU Green Deal's construction materials sustainability criteria are mandating Environmental Product Declarations for asphalt modifiers used in Trans-European Transport Network projects. EPD verification requires third-party lifecycle assessment documentation for polymer and chemical modifier supply chains. German and French infrastructure tenders now weight EPD scores at 15-20% of technical evaluation criteria, favoring suppliers with certified low-carbon production pathways.
Long-term pavement performance warranties are displacing traditional method-based specifications for highway rehabilitation contracts. State DOTs in Florida and Illinois now procure 10-year performance guarantees from contractors, who in turn demand modifier suppliers share liability for binder grade compliance. The model concentrates specification authority among integrated modifier-paving firms with in-house testing and quality assurance capabilities.
Asphalt Modifiers Market Segmentation
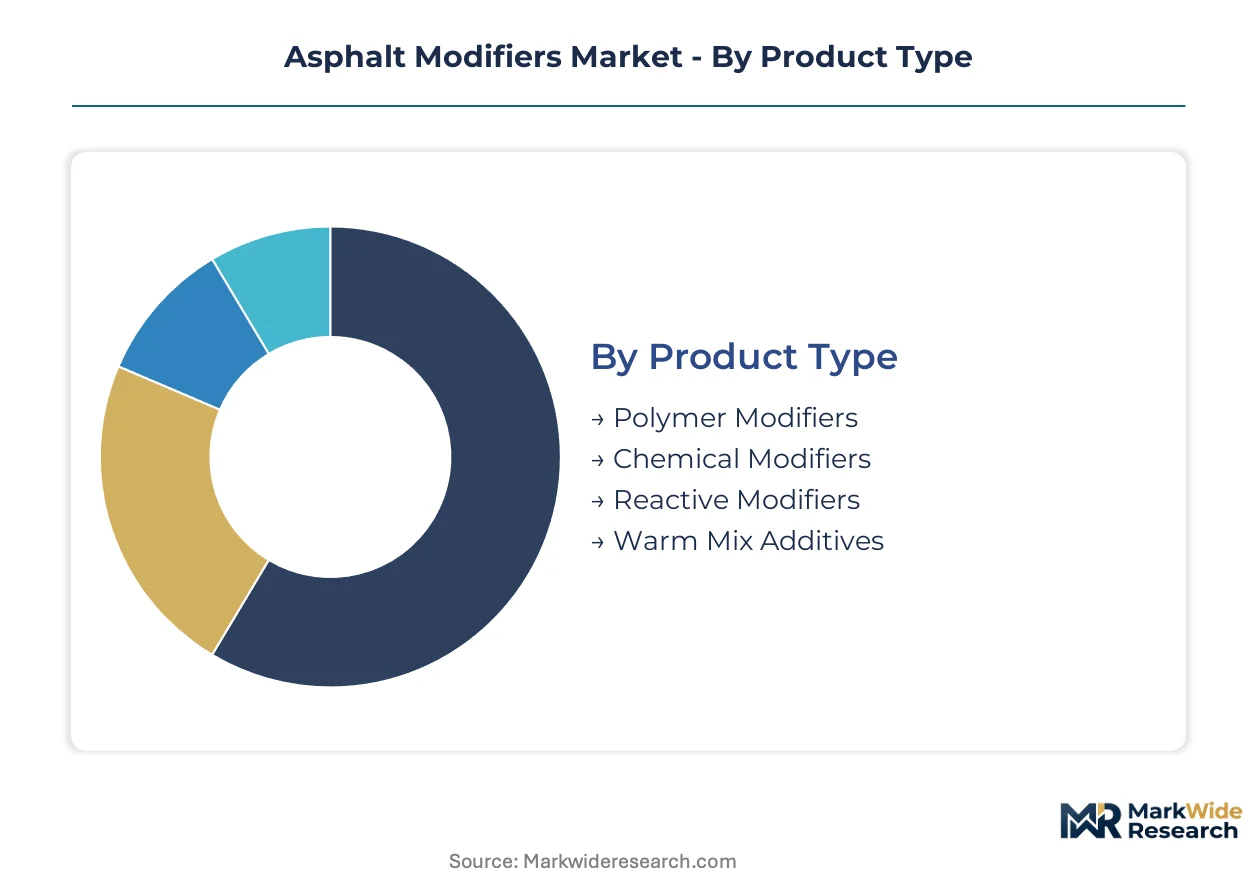
Modifier chemistry and application environment dictate specification authority across the asphalt additives value chain. Segmentation reveals where procurement budgets concentrate and which formulation categories capture premium pricing versus commodity volume.
Product Type:
Margin pools concentrate in high-performance polymer formulations where Superpave compliance commands specification premiums, while warm mix additives capture expanding regulatory preference for emissions reduction.
- Polymer Modifiers:Styrene-butadiene-styrene and ethylene-vinyl-acetate formulations comprise 3–8% by weight of modified binder blends. Highway rehabilitation budgets in China, India, and the United States lock in procurement for heavy-traffic corridors where rutting resistance specifications are non-negotiable.
- Warm Mix Additives:Polyethylene amine chemistry enables 20–40°C production temperature reductions without performance grade degradation. State-level emissions mandates in California and Texas are accelerating contractor adoption as agencies tighten procurement criteria for carbon-intensive hot-mix processes.
- Chemical Modifiers:Oxidation-resistant formulations serve tropical climate specifications where ultraviolet degradation accelerates pavement aging.
- Reactive Modifiers:Sulfur and maleic anhydride grafting chemistries improve binder-polymer compatibility in high-RAP content mixes.
The dominant share belongs to Polymer Modifiers, while Warm Mix Additives is closing the gap fastest.
Application:
Volume concentrates in arterial road networks where federal funding eligibility determines modifier specification, while specialized airport applications sustain premium pricing tiers.
- Road Construction:Interstate highways and urban expressways absorb the majority of polymer-modified binder volume. The Federal Highway Administration's AASHTO M320 specifications mandate performance-graded modifiers for federal aid eligibility, locking formulation chemistry across heavy-traffic corridors.
- Airport Runways:Jet fuel resistance and high-shear rutting specifications demand premium SBS polymer loadings. Federal Aviation Administration pavement design standards enforce stricter binder grades than highway applications, concentrating procurement among specialized contractors with in-house testing capabilities.
- Parking Lots:Commercial development specifications favor cost-optimized modified binders with shorter warranty periods than public infrastructure.
- Footpaths:Municipal maintenance budgets prioritize economy-grade formulations with minimal polymer content.
Road Construction holds the volume base, with Airport Runways commanding the steepest price premiums per ton.
Technology:
Production temperature thresholds segment equipment requirements and emissions profiles, determining contractor retrofit economics and regulatory compliance pathways.
- Hot Mix:Conventional 150–180°C production remains dominant where existing plant infrastructure and performance-grade specifications resist change. State DOTs in Texas and Florida maintain hot-mix preference for high-shear environments despite emissions penalties.
- Warm Mix:Additive-enabled temperature reduction satisfies emerging procurement mandates without capital-intensive plant replacement. The Federal Highway Administration's Every Day Counts program promotes warm-mix adoption through accelerated project delivery incentives.
- Cold Mix:Emulsion-based formulations serve remote maintenance applications where plant proximity is uneconomical.
- Dense Graded:Continuous gradation specifications concentrate in urban resurfacing contracts where surface texture requirements are stringent.
Hot Mix retains installed base dominance, though Warm Mix is gaining specification share fastest in coastal states with binding emissions targets.
End User:
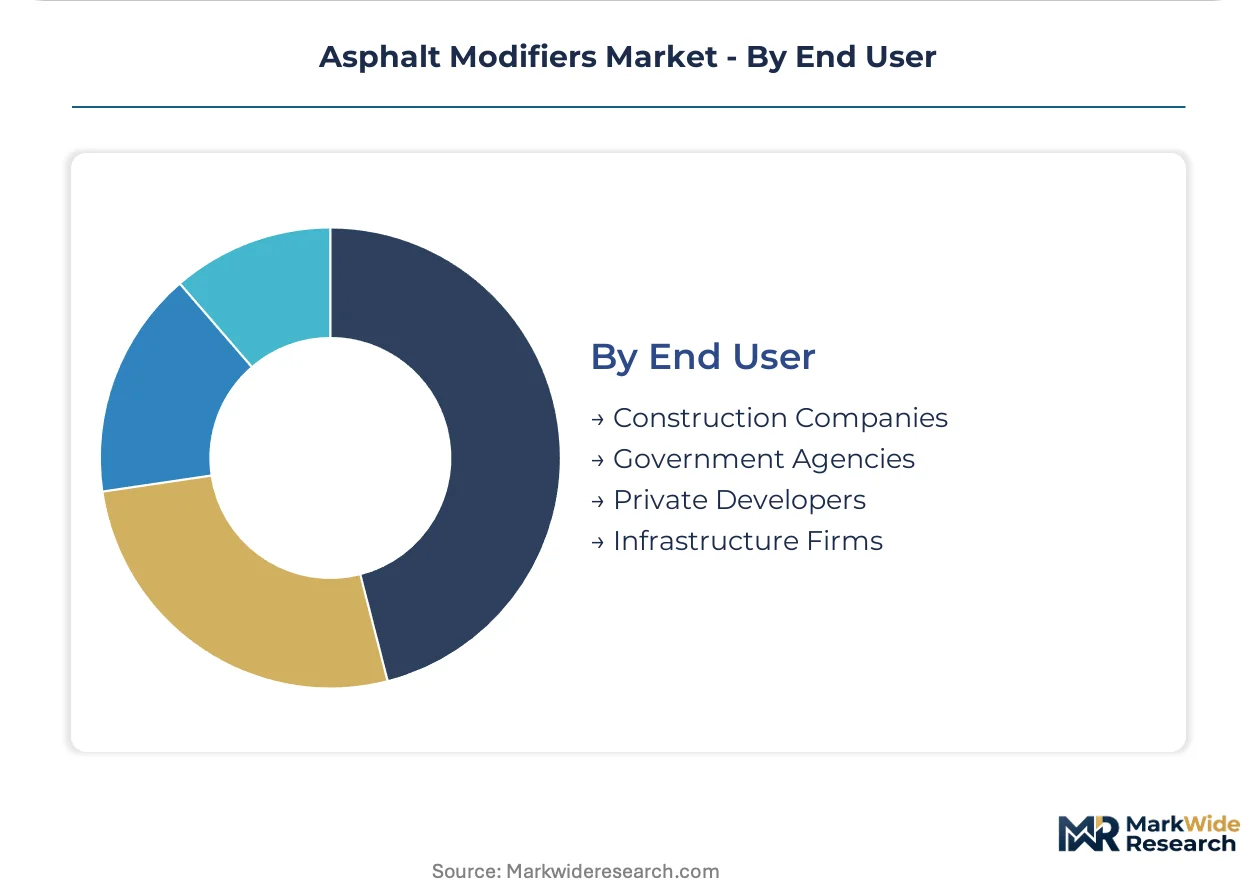
Procurement authority splits between public agencies with specification-setting power and private developers with cost-optimization incentives.
- Government Agencies:Federal and state transportation departments enforce performance-grade standards that determine qualified modifier chemistries. The Federal Highway Administration's Superpave binder specifications cascade through state DOT laboratories, creating uniform demand for certified polymer modifiers across interstate corridors.
- Construction Companies:Large paving contractors with in-house terminal blending capabilities capture margin through direct modifier procurement rather than binder purchase from refiners. Performance-based contracting in Florida and Illinois concentrates specification authority among integrated firms with quality assurance infrastructure.
- Infrastructure Firms:Design-build consortia prioritize lifecycle cost optimization over first-cost minimization, favoring premium modifier loadings with extended warranty terms.
- Private Developers:Commercial and residential parking specifications tolerate lower polymer content than public infrastructure, prioritizing initial capital expenditure over service life extension.
Government Agencies anchor specification authority, while Construction Companies are consolidating procurement leverage through vertical integration into terminal blending.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Infrastructure procurement authorities concentrate modifier demand in federal highway programs and provincial rehabilitation budgets. The United States, China, India, Germany, and Saudi Arabia absorb the majority of polymer-modified binder volume through specification-driven public tenders.
United States
The Federal Highway Administration's Superpave M320 specifications mandate polymer modifiers for interstate funding eligibility. State DOTs in California, Texas, and Florida layer additional performance tests that favor styrenic block copolymer formulations. The US Gulf Coast petrochemical corridor hosts integrated modifier production serving domestic highway rehabilitation contractors.
China
Provincial transportation budgets in Shandong and Guangdong prioritize polymer-modified asphalt for urban expressway reconstruction. The Ministry of Transport's 14th Five-Year Plan accelerates high-altitude corridor upgrades requiring cold-climate binder grades. Yangtze River Delta manufacturing clusters supply SBS modifiers to domestic paving consortia bidding on Belt and Road infrastructure exports.
India
The Ministry of Road Transport's Bharatmala program specifies polymer-modified binders for high-rainfall and high-altitude highway segments. National highway authority tenders increasingly require performance-grade certification from domestic blending terminals. Gujarat and Maharashtra host emerging formulation plants targeting import substitution for specialty modifier chemistries.
Germany
The EU Green Deal's construction materials sustainability criteria mandate Environmental Product Declarations for asphalt modifiers in Trans-European Transport Network projects. Federal transport infrastructure tenders weight lifecycle emissions at 15-20% of technical evaluation scores. The Rhine-Ruhr corridor concentrates reactive modifier production serving Central European highway maintenance contracts.
Saudi Arabia
The National Infrastructure Fund prioritizes warm mix additive formulations to reduce production emissions in desert climate paving operations. Municipal tenders in Riyadh and the Eastern Province specify oxidation-resistant modifiers for ultraviolet degradation resistance. NEOM construction contracts create demand for premium polymer loadings in high-temperature performance specifications.
Asphalt Modifiers Market Vendor Landscape
Player mix skews toward integrated petrochemical conglomerates with captive styrenic block copolymer supply and specialty chemical houses with reactive modifier expertise. The market structure concentrates specification authority among firms with in-house rheological testing and state DOT certification capabilities. Two strategic archetypes dominate: upstream-integrated polymer suppliers capturing margin through feedstock control, and formulation specialists leveraging rejuvenator chemistry for recycled asphalt integration. Capacity expansion and backward integration into SBS production represent the dominant competitive moves as feedstock volatility compresses blend margins.
Among North American petrochemical-based suppliers, Kraton Corporation and Dow exemplify the integrated polymer modifier archetype with styrenic block copolymer production platforms. BASF SE anchors the European specialty chemical tier through reactive modifier chemistry capabilities serving polymer-modified binder applications. These three firms represent distinct competitive positioning vectors: feedstock-integrated volume leadership, specification-grade formulation expertise, and emissions-compliant warm mix additive platforms.
| Leading Market Players |
|---|
| Kraton Corporation |
| Nouryon |
| BASF SE |
| Exxon Mobil Corporation |
| Honeywell International Inc. |
| Arkema |
| Evonik Industries AG |
| Sasol |
| Dow |
| Others |
Supply Flow & Price Mechanics
Bio-based rejuvenator substitution for petroleum-derived recycling agents is redrawing supply geography toward tall oil and waste vegetable oil processing clusters while compressing pricing premiums for virgin polymer modifiers in maintenance applications.
Pricing Analysis
Hot-mix additive pricing anchors the current-generation baseline, warm mix formulations command 15-25% premiums for emissions compliance value, and next-generation bio-rejuvenators are resetting price floors through lifecycle certification advantages. Three-tier pricing structure across performance-grade certified, standard specification, and economy-grade unmodified tiers dominates procurement. Price differentiation hinges on Superpave M320 certification status and volume scale commitments from state DOT contractors. Cost compression in economy-grade segments is intensifying because Portland cement stabilization competes for municipal rehabilitation budgets. Small paving contractors exhibit highest price sensitivity, while integrated terminal operators with in-house blending tolerate premium loadings for warranty-backed performance guarantees.
Supply Chain Analysis
The United States Gulf Coast and Germany's Rhine-Ruhr corridor anchor integrated petrochemical production of styrenic block copolymers and reactive modifier chemistries. Specialty modifier formulation draws from butadiene monomer feedstocks, polyethylene amine platforms, and bio-based recycling agents sourced from Scandinavian pulp processing. Single-source vulnerability concentrates in SBS polymer supply from integrated crackers, with limited qualified alternatives for Superpave-certified grades. Distribution runs through refinery terminals and hot-mix plant direct procurement channels, bypassing traditional chemical distributor networks for volume accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face a substitution defense imperative as bio-rejuvenator chemistry and full-depth reclamation with cement stabilization capture share in pavement preservation budgets.
For Market Incumbents: Compound specification authority through captive SBS production and state DOT laboratory certification partnerships that lock out unqualified competitors. Deepen backward integration into butadiene supply or tall oil processing to hedge feedstock volatility and bio-based substitution threats. Prioritize warm mix additive platforms that satisfy emerging low-carbon procurement mandates. For New Entrants and Emerging Players: AASHTO M320 certification fast-track through university laboratory partnerships opens procurement eligibility without 12-18 month state DOT validation cycles. Target India's Bharatmala program corridors where import substitution incentives and high-altitude performance specifications create white-space for domestic formulation plants. Lead with rejuvenator chemistry that enables 40-50% RAP content compliance. For Investors and Strategic Acquirers: The market sits at a specification consolidation phase that favors integrated modifier-paving firms with in-house testing infrastructure and performance warranty capabilities. Long-term viability centers on supply chains with verified Environmental Product Declarations for EU Green Deal compliance and California Buy Clean Act preference margins. Monitor state-level low-carbon procurement mandate adoption rates as inflection indicators for warm mix additive demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SBS Production | Captures margin compression from butadiene feedstock volatility at US Gulf Coast crackers. |
| State DOT Certification Partnership | Accelerates AASHTO M320 validation cycles that otherwise lock out new formulations. |
| Warm Mix Additive Platform Expansion | Positions for California and Texas emissions mandate procurement preferences. |
| Bio-Rejuvenator Formulation Development | Captures 40-50% RAP content specifications from Minnesota and Texas DOT contracts. |
| Environmental Product Declaration Certification | Unlocks EU Green Deal tender weighting for Trans-European Transport Network projects. |
Methodological Framework
Initial hypotheses were tested against primary input from asphalt terminal managers, state DOT materials engineers, paving contractor procurement leads, and petrochemical R&D directors and refined through secondary validation against AASHTO specification databases, FHWA project funding records, SEC 10-K filings from listed modifiers suppliers, and EU construction materials sustainability registries. Bottom-up volume estimates from individual state rehabilitation budgets were triangulated against top-down petrochemical capacity assessments across the analysis window.
Variance decomposition across product type, application environment, technology generation, and end-user procurement authority shaped the analytical framework. CAGRs were derived from segment-level volume trajectories weighted by pricing tier evolution, with specific inputs including Superpave specification adoption curves, state-level emissions mandate implementation schedules, and highway rehabilitation budget appropriations from China, India, and the United States.
Underlying assumptions cover sustained federal highway funding eligibility tied to polymer-modified binder specifications, with deviation risk concentrated in accelerated Portland cement substitution and bio-rejuvenator certification fast-tracks. Recalibration cycles align with material shifts in state DOT low-carbon procurement mandates and EU Green Deal construction materials criteria enforcement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Stone Veneer Market
Building & Construction Materials
Australia and New Zealand Industrial Flooring Market
Building & Construction Materials
Fire Rated Duct Market
Building & Construction Materials
Nordic Solar Shades Market
Building & Construction Materials
North America Concrete Conditioner Market
Building & Construction Materials
Clay Roof Tiles Market
Building & Construction Materials
United States Roofing Market
Building & Construction Materials
Travertine Tiles Market
Building & Construction Materials
Remodeling Market
Building & Construction Materials
Sink Float Tank Market
Building & Construction Materials
Ceramic Wall Tiles Market
Building & Construction Materials
North Africa Cement Market
Building & Construction Materials
Canada Facade Market
Building & Construction Materials
Tower Bolt Market
Building & Construction Materials
Point Fixing Glass Curtain Wall Market
Building & Construction Materials
Architectural Acoustic Panels Market