
 Tape Measure Market | 2026-2036
Tape Measure Market Size, Share, and Industry Trends Forecast 2026-2036
Tape Measure Market Analytics
Buyer concentration among national construction contractors is pivoting toward integrated tool-procurement platforms that bundle measuring instruments with fleet management software. Stanley leverages its century-old brand equity to sustain premium positioning in professional channels. Milwaukee anchors the cordless-ecosystem strategy by bundling electronic tape measures with its battery platform. Tajima specializes in precision-engineered blades for carpentry specialists across East Asian markets.
A tape measure is a graduated length-measuring instrument comprising a metal, fiberglass, or composite ribbon coiled within a spring-return housing, typically marked in millimetre, centimetre, inch, or foot graduations with a hooked end-piece for accurate internal and external measurements. Steel tape variants dominate commercial construction for their durability and resistance to stretching under tension, while electronic tape models incorporating laser distance sensors and Bluetooth data logging are gaining share in layout and inspection workflows where dimensional traceability matters. Fiberglass tapes retain strong positions in electrical utility and surveying applications where non-conductive properties prevent arc hazards. Magnetic tape configurations compete aggressively in structural steel fabrication for hands-free operation on ferrous surfaces.
ISO 9001 quality management standards and national metrology institute certifications govern commercial-grade accuracy classes across major manufacturing jurisdictions. OSHA workplace safety regulations in the United States mandate fall-protection planning that increasingly references laser-based remote measurement to reduce elevated-work exposure. The EU Machinery Directive and CE marking requirements shape product liability frameworks for electronic measuring devices sold into European professional channels. Stakeholders must monitor how building-information-modeling integration demands reshape R&D priorities for connectivity-enabled measurement tools.
Market Dynamics
Construction contractors are consolidating tool procurement through national distributor accounts, compressing vendor margins while demanding integrated fleet management capabilities that bundle measurement instruments with software platforms.
Growth Catalysts
- OSHA fall-protection mandates:Remote laser measurement reduces elevated-work exposure in commercial construction, accelerating replacement of manual tapes with electronic alternatives in United States job sites.
- Building-information-modeling integration:Dimensional traceability requirements in layout and inspection workflows pull Bluetooth-enabled data logging into specification sheets for infrastructure maintenance cycles.
- Residential renovation activity:Germany's housing stock refurbishment sustains replacement purchase velocity for precision-engineered steel tape variants among carpentry specialists.
Market Restraints
- Steel input cost volatility:Fluctuations in cold-rolled steel pricing compress margins on commercial-grade tape measure production, forcing manufacturers to absorb or pass through material swings.
- Supplier concentration in East Asian blade fabrication:Precision coiling and graduation printing capacity clusters in China and Taiwan, creating exposure to regional logistics disruptions.
- Laser sensor calibration limitations:Electronic tape accuracy degrades in high-ambient-light conditions, restricting deployment in outdoor structural steel fabrication during daylight hours.
Strategic Opportunities
- Underpenetrated electrical utility maintenance:Non-conductive fiberglass tape adoption remains below saturation in United States transmission line work, where arc hazard prevention drives specification shifts.
- EU Machinery Directive compliance tailwind:CE marking requirements for electronic measuring devices create barrier-to-entry protection for certified manufacturers serving European professional channels.
- Convergence of laser sensing with augmented reality:Spatial measurement data overlaid on job-site visualizations promises workflow integration for layout contractors in Japanese commercial construction.
Industry Challenges
- Metrology technician skill scarcity:Calibration and repair expertise for electronic tape models concentrates in manufacturer service centers, lengthening turnaround times for field failures.
- ISO 9001 certification timeline compression:Third-party audit backlogs delay quality management accreditation for mid-tier suppliers seeking entry into national distributor accounts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tape Measure Market |
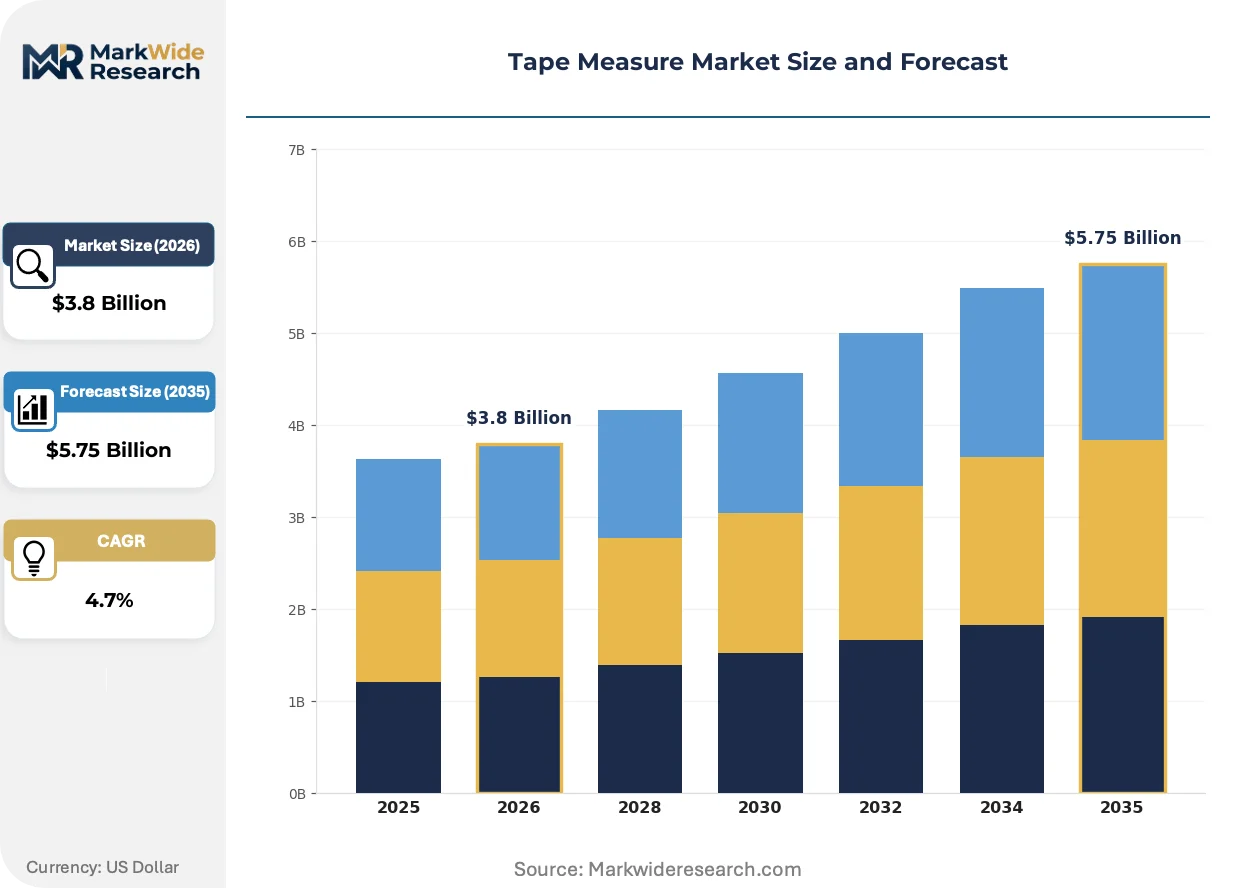
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel Tape, Fiberglass Tape, Magnetic Tape, Electronic Tape End User: Construction, Manufacturing, DIY Enthusiasts, Carpentry Application: Height Measurement, Distance Measurement, Layout, Inspection Measurement System: Imperial, Metric, Dual, Custom |
| Companies Covered | DeWalt, Komelon, Stanley, Tajima, Craftsman, Crescent Lufkin, Irwin, Reekon, Milwaukee, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tape Measure Market Evolving Landscape
Digital measuring technologies and Bluetooth-enabled job-site tracking are reshaping specification requirements, forcing traditional tape measure architectures to accommodate connectivity layers that were previously absent from handheld instruments.
Laser distance sensing paired with onboard memory is unifying dimensional capture and documentation into single-device workflows. Commercial contractors in the United States are specifying these units for layout verification at accelerating rates. This convergence is compressing the addressable market for standalone manual tapes in professional channels while expanding total spend per measurement tool.
REACH substance restrictions in Europe are tightening the chemical composition envelope for tape measure housings and blade coatings. Manufacturers must reformulate polymer formulations to eliminate restricted phthalates and heavy metal stabilizers. Electronic measuring device categories face heightened scrutiny under the EU Machinery Directive, with notified bodies extending conformity assessment timelines for products incorporating radio-frequency modules.
Consolidated national accounts are disintermediating regional tool distributors that historically stocked breadth of manual tape SKUs. Large construction contractors in Germany now route measuring instrument purchases through centralized procurement platforms that bundle fleet tracking software. This concentration is most visible in infrastructure maintenance verticals, where standardization across dispersed job sites overrides local preference for specific tape brands.
Tape Measure Market Segmentation
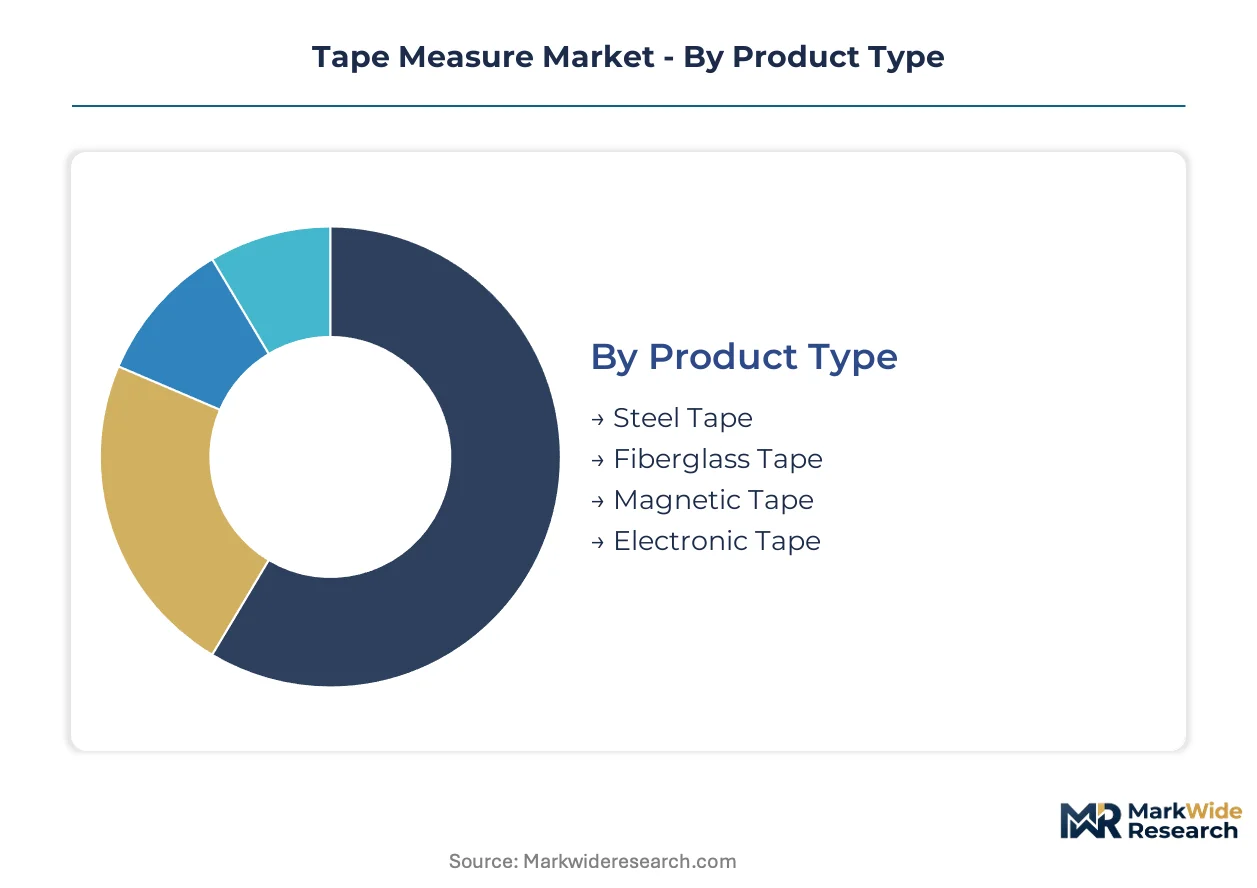
Segmentation in the tape measure market reveals how distinct user workflows and material specifications drive upgrade cycles. Replacement velocity varies dramatically across product architectures and end-use environments, creating tiered demand patterns that manufacturers must address through differentiated portfolio strategies.
Product Type:
Upgrade cycles diverge sharply across material and technology architectures, with electronic variants compressing replacement intervals through rapid feature iteration while steel tapes persist on decade-long durability timelines.
- Steel Tape:Cold-rolled steel ribbon with etched or painted graduations delivers tensile stability under mechanical stress for commercial construction layout. Demand concentrates among United States infrastructure maintenance contractors where OSHA fall-protection planning favors durable manual instruments for ground-level verification.
- Electronic Tape:Laser distance sensing paired with onboard memory and Bluetooth data logging unifies measurement capture with digital documentation. Adoption accelerates in German commercial construction where building-information-modeling integration mandates dimensional traceability across dispersed job sites.
- Fiberglass Tape:Non-conductive composite ribbon prevents arc hazards in electrical utility applications where metallic instruments create safety exposure.
- Magnetic Tape:Ferrous hook attachments enable hands-free operation on structural steel surfaces, serving fabrication shops with specialized workflow requirements.
Steel Tape sits at the top of the volume ranking, with Electronic Tape climbing the fastest.
End User:
Customer type determines procurement channel access and price elasticity, with consolidated national accounts extracting volume discounts while fragmented specialist segments sustain premium positioning.
- Construction:General contractors and specialty trades deploy tape measures across layout, verification, and quality control workflows. Specification authority in the United States increasingly centralizes through national distributor accounts that bundle measuring instruments with fleet management software.
- Carpentry:Precision specialists in Germany and Japan demand graduated accuracy classes for finish work where cumulative measurement error compounds across complex assemblies.
- Manufacturing:Industrial quality departments employ tape measures for incoming material verification and dimensional audit sampling.
- DIY Enthusiasts:Residential renovation activity in mature housing markets sustains replacement purchases through retail channels.
Construction commands the largest revenue pool, with Carpentry offering the steepest margin expansion trajectory.
Application:
Use-case specificity determines instrument selection criteria, with accuracy requirements and environmental exposure dictating material and technology choices.
- Layout:Initial dimensional positioning for structural elements and utility routing demands repeatable accuracy across extended measurement ranges.
- Inspection:Quality verification and as-built documentation increasingly specifies electronic instruments with data logging for audit trails.
- Distance Measurement:Linear span determination for material ordering and cut planning represents the core functional requirement across all user segments.
- Height Measurement:Vertical dimension capture for clearance verification and elevation planning.
Layout dominates current specification activity, with Inspection gaining share fastest through compliance-driven digitization.
Measurement System:
Graduation standards reflect geographic regulatory environments and trade integration patterns, with dual-system instruments addressing cross-border procurement standardization.
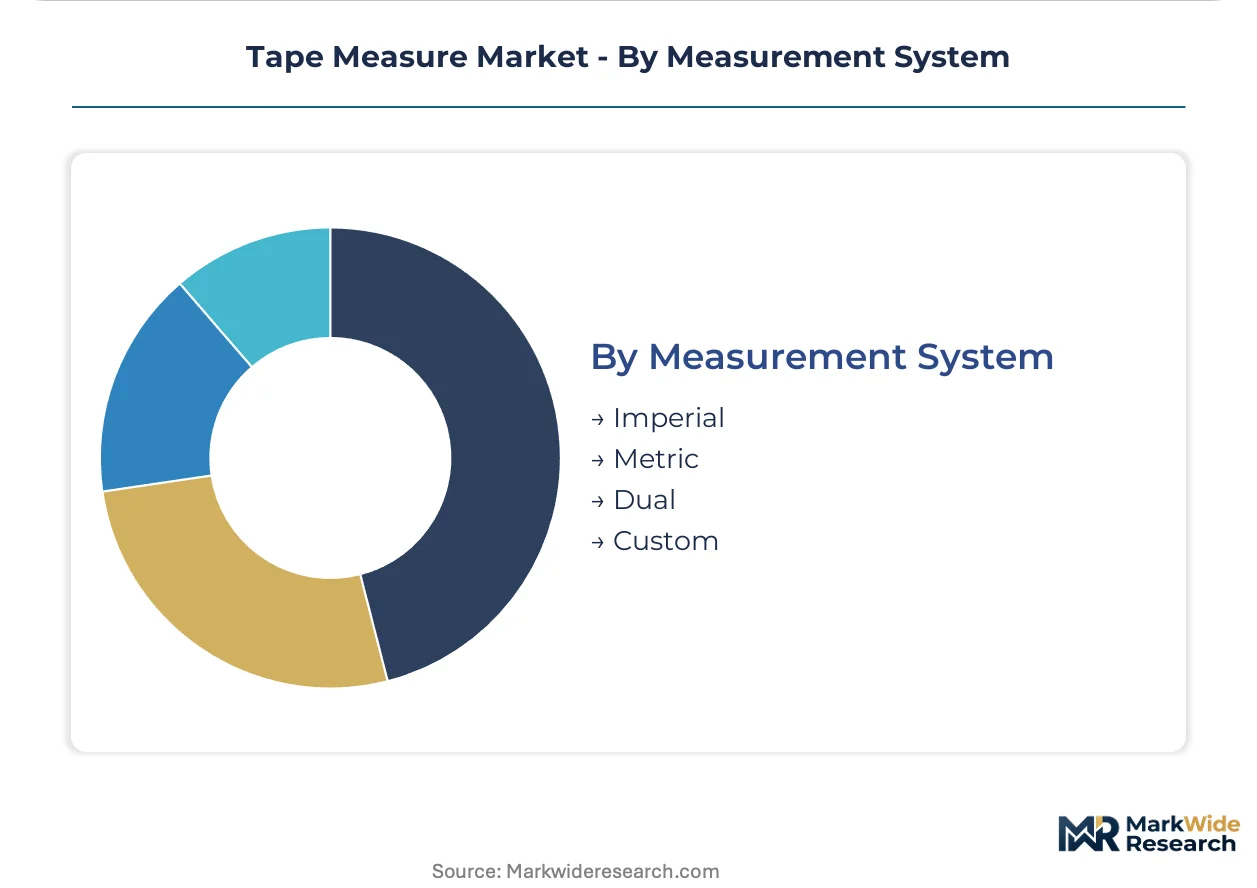
- Metric:Millimetre and centimetre graduations align with ISO standards and dominate professional channels in Germany, China, and most industrialized markets outside North America.
- Imperial:Inch and foot markings persist in United States construction through entrenched building material dimensional standards.
- Dual:Combined metric-imperial graduations serve international contractors and equipment import markets where specification translation errors carry cost penalties.
- Custom:Specialized graduation patterns for surveying, maritime, or heritage restoration applications with non-standard reference systems.
Metric configurations anchor professional volume, with Dual-system instruments expanding most quickly through cross-border project standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled construction labor pools in the United States, Germany, China, Japan, and India anchor regional demand patterns for precision measuring instruments across commercial and residential building cycles.
United States
OSHA fall-protection mandates accelerate laser-based remote measurement adoption among commercial contractors seeking to reduce elevated-work exposure. Infrastructure maintenance cycles sustain replacement velocity for durable steel tape variants in ground-level verification workflows. Texas and Florida construction corridors concentrate procurement through national distributor accounts bundling fleet management software.
Germany
Residential renovation activity across aging housing stock drives specification of precision-engineered steel tapes among carpentry specialists. REACH substance restrictions tighten chemical composition requirements for tape measure housings and blade coatings. Bavarian manufacturing clusters reformulate polymer formulations to eliminate restricted phthalates ahead of enforcement deadlines.
China
Precision coiling and graduation printing capacity clusters in coastal manufacturing zones serving domestic infrastructure buildouts and export markets. GB standards govern commercial-grade accuracy classifications for professional channels. Yangtze River Delta fabrication centers supply blade components to multinational tool brands while developing domestic electronic measuring capabilities.
Japan
Commercial construction contractors specify Bluetooth-enabled data logging for building-information-modeling integration across dispersed job sites. METI industrial standards shape quality management accreditation timelines for mid-tier suppliers. Kanto region tool distributors consolidate inventory breadth as national accounts disintermediate traditional procurement channels.
India
Urban infrastructure expansion and affordable housing programs sustain demand for manual and electronic measuring instruments among emerging contractor segments. BIS certification requirements create compliance thresholds for commercial-grade accuracy classes. Maharashtra and Gujarat construction corridors concentrate procurement through regional distributor networks transitioning toward integrated procurement platforms.
Tape Measure Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Tool manufacturers with century-old brand equity anchor premium professional channels through established distributor relationships. Electronic measurement specialists disrupt traditional architectures with laser-sensing and connectivity-enabled portfolios. Consolidation pressures intensify as national construction accounts demand bundled hardware-software procurement solutions.
Among heritage-branded tool manufacturers, Stanley and Milwaukee occupy positions exemplifying divergent ecosystem strategies. Stanley leverages brand equity sustained through professional channel presence. Milwaukee anchors cordless-platform bundling that integrates electronic measurement with battery compatibility. Tajima represents precision-specialist positioning focused on graduated accuracy for finish carpentry across East Asian markets.
| Leading Market Players |
|---|
| DeWalt |
| Komelon |
| Stanley |
| Tajima |
| Craftsman |
| Crescent Lufkin |
| Irwin |
| Reekon |
| Milwaukee |
| Others |
Value Network & Pricing Analysis
Cold-rolled steel pricing volatility cascades through tape measure manufacturing tiers, compressing margins on commercial-grade steel variants while electronic segments absorb sensor cost deflation through scale. Procurement consolidation among United States national contractor accounts extracts volume concessions that propagate upstream to blade fabrication clusters in China and Taiwan.
Pricing Analysis
The bundled-vs-unbundled service split separates hardware-only transactions from fleet-management-software integrations that command premium positioning. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 9001 certification grade and Bluetooth connectivity inclusion. Pricing pressure stems from national distributor account consolidation extracting standardized terms across dispersed job sites. DIY enthusiasts through retail channels exhibit highest price sensitivity; German carpentry specialists demonstrate lowest elasticity due to graduated accuracy requirements.
Supply Chain Analysis
Workforce-availability constraints in Yangtze River Delta precision coiling operations and Taiwan graduation-printing facilities tighten capacity allocation for blade components. Supply concentrates in China, Taiwan, and Germany for cold-rolled steel ribbon, laser sensor modules, and polymer housing formulations. Raw material dependencies rest on cold-rolled steel, fiberglass composite feedstock, and semiconductor laser diodes. Single-source vulnerability in East Asian blade fabrication creates exposure to regional logistics disruptions. Distribution runs through national distributor accounts disintermediating regional tool wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tape measure market reads as a late-cycle quality story where specification authority migrates toward Bluetooth-enabled dimensional traceability and building-information-modeling integration. Premium electronic variants displace commodity manual tapes in professional channels.
For Market Incumbents: Lock in distributor relationships through exclusive fleet-software bundling that raises switching costs for consolidated national accounts. Deepen backward integration into precision blade fabrication to offset East Asian supply concentration. Defend against electronic measurement specialists by accelerating laser-sensor feature iteration cycles. For New Entrants and Emerging Players: Electrical utility maintenance crews represent an underserved buyer archetype where non-conductive fiberglass tape adoption remains below saturation. Target United States transmission line contractors with arc-hazard-compliant specifications and utility-specific certification pathways. Pursue direct procurement relationships bypassing consolidated construction distributor networks. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier suppliers lack ISO 9001 accreditation timelines to access national distributor accounts. Long-term viability favors manufacturers with captive blade fabrication and electronic measurement R&D capabilities. Monitor CE marking assessment timelines under EU Machinery Directive as inflection indicator for European market access friction.| Strategic Initiative | Industry Significance |
|---|---|
| Bluetooth Data Logging Integration | Enables building-information-modeling traceability for German infrastructure contractors. |
| Laser Sensor Module Sourcing Agreement | Secures component supply for electronic tape production against semiconductor allocation volatility. |
| ISO 9001 Certification Investment | Unlocks national distributor account access compressed by procurement consolidation. |
| Fiberglass Tape Capacity Expansion | Captures electrical utility maintenance specification shifts away from conductive steel variants. |
| Fleet Management Software Partnership | Bundles measurement hardware with contractor workflow platforms in United States commercial construction. |
Research Methodology
Direct dialogue with procurement directors at national construction distributors, plant managers at blade fabrication facilities, and metrology technicians at manufacturer service centers grounded qualitative findings. Secondary validation drew from OSHA regulatory filings, EU Machinery Directive conformity assessments, customs trade data for steel ribbon imports, and SEC disclosures from diversified tool manufacturers. Bottom-up segment sizing triangulated against top-down construction spending allocation models.
Segment-level projections across product type, end user, application, and measurement system dimensions combined with regional infrastructure maintenance cycle analysis produced volume and value estimates across the modeling period. CAGRs derived from replacement velocity differentials between steel tape decade-long durability and electronic tape compressed upgrade intervals. Forecast inputs incorporated Bluetooth adoption curves in commercial construction and REACH substance restriction compliance timelines.
Underlying measurement precision varies by segment; electronic tape and Bluetooth-enabled categories carry tighter precision than commodity steel variants due to sensor cost transparency and feature iteration visibility. Forecasts reflect documented assumptions on infrastructure spending continuity and regulatory enforcement intensity. Material deviation in OSHA fall-protection mandate expansion or East Asian logistics disruption severity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Hand Tools and Woodworking Tools Market
Tools
Automatic Heat Press Machines Market
Tools
Cordless Impact Wrench Market
Tools
Vise-Grip Pliers Market
Tools
Turning Centers Market
Tools
Telescopic Tool Boxes Market
Tools
Industrial Hand Tools Market
Tools
Bar Clamp Market
Tools
Wood Router Market
Tools
United States Machine Tools Market
Tools
Pneumatic Marking Machines Market
Tools
Gas Cutting Machine Market
Tools
Coil Fed Punching and Cutting Machines Market
Tools
Painting Tools Market
Tools
Fatigue Testing Machine Market
Tools
Industrial Floor Scrubber Market