
 Central & South America Iron Casting Market | 2026-2036
Central & South America Iron Casting Market Size, Share, and Industry Trends Forecast 2026-2036
Central & South America Iron Casting Market Analytics
Project finance tied to equipment-leasing pools is fragmenting competitive access across Central and South America iron casting. Tupy leverages captive foundry capacity to anchor long-term supply contracts with agricultural OEMs. Fundición Regali Brasil competes through geographic dominance in Brazil's southeastern industrial belt. Grupo Industrial Saltillo specializes in high-volume automotive castings for Tier 1 suppliers operating near the US-Mexico border.
Central and South America iron casting encompasses ferrous metal components produced by pouring molten iron alloys into molds, typically achieving tensile strengths from 20,000 psi in gray iron to over 80,000 psi in ductile grades, serving load-bearing and wear-resistant applications across transportation and capital equipment industries. Sand casting occupies the dominant share of regional output due to its suitability for large engine blocks and pump housings requiring complex internal geometries. Ductile iron is displacing gray iron in agricultural frames and construction valves where fatigue resistance commands premium pricing. Die casting captures thinner-walled applications in automotive pump housings, though its share remains constrained by energy costs in the region.
Brazil's INMETRO certification and Mexico's NOM-001-SEDE electrical standards shape product specifications for export-bound castings, while Peru's OSINERGMIN monitors energy-intensive foundry operations for compliance. Argentina's IRAM standards and Chile's SEC certifications create divergent testing requirements that fragment cross-border product homologation. Stakeholders must monitor how Brazil's potential carbon-border adjustments and Mexico's nearshoring incentive programs redistribute foundry investment between domestic capacity expansion and import substitution strategies.
Market Dynamics
Gray-to-ductile conversion investments are compressing legacy foundry economics across Brazil and Mexico, as agricultural OEMs and automotive Tier 1 suppliers demand fatigue-resistant castings that command premium pricing in precision tillage equipment and heavy-duty engine blocks.
Growth Catalysts
- INMETRO certification pathways:Brazil's conformity assessment framework for industrial equipment exports is accelerating foundry modernization programs in São Paulo's heavy equipment cluster.
- Precision tillage equipment:Agricultural machinery OEMs are specifying nodular iron grades for replaceable wear components in soil-engaging implements.
- NOM energy-efficiency standards:Mexico's furnace efficiency mandates are forcing gray iron capacity retirements and ductile iron replacement investments in Monterrey's automotive supplier corridor.
Market Restraints
- Scrap metal price volatility:Ferrous scrap input costs fluctuate with export demand from Asian steel mills, squeezing margin structures for independent Brazilian foundries.
- Electrode supply concentration:Graphite electrode manufacturing concentrates in China, exposing Central American foundries to supply interruption risks during trade friction periods.
- Aluminum substitution in powertrain:EV thermal management components and hybrid engine blocks are shifting toward aluminum die castings in passenger vehicle applications.
Strategic Opportunities
- Peru's mining capital equipment:Open-pit copper and gold operations require high-chrome white iron wear parts that regional foundries currently import from North American suppliers.
- Nearshoring incentive programs:Mexico's IMMEX maquiladora framework and tariff preference programs are attracting automotive casting investments for US-bound component supply.
- Digital mold design convergence:Simulation software and 3D sand printing are collapsing prototype-to-production timelines for complex internal geometries in pump housings.
Industry Challenges
- Certification timeline compression:Brazil's INMETRO and Mexico's NOM-001-SEDE parallel testing requirements extend product homologation cycles for cross-border casting shipments.
- Foundry engineering talent scarcity:Metallurgical process control and solidification simulation expertise concentrates in aging workforce cohorts across Argentina's industrial belt.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Central & South America Iron Casting Market |
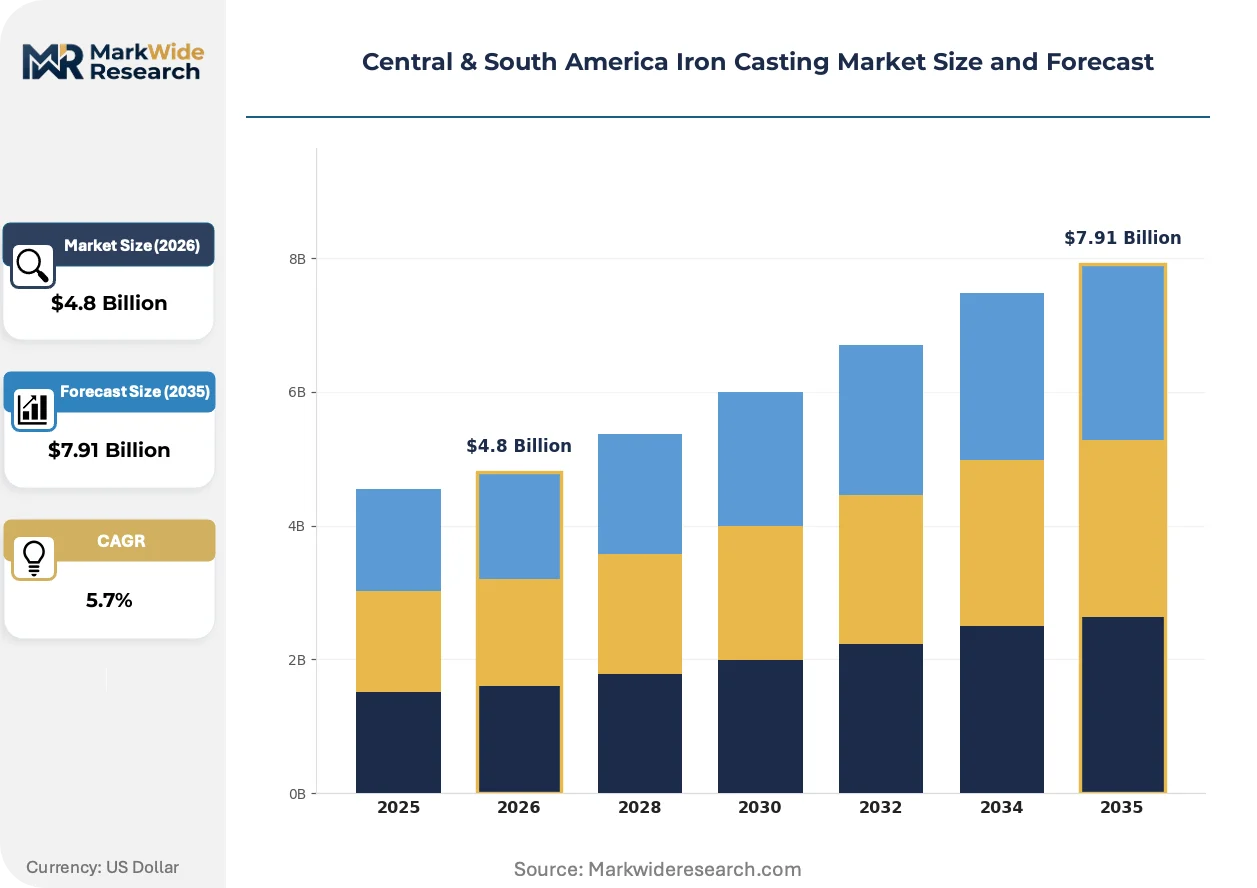
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gray Iron, Ductile Iron, White Iron, Malleable Iron End User: Automotive, Construction, Machinery, Agriculture Application: Engine Blocks, Pump Housings, Frames, Valves Manufacturing Process: Sand Casting, Investment Casting, Die Casting, Centrifugal Casting |
| Companies Covered | Fundición Callao SA, Industrias Ascheri & Cia., Tupy, Fagor Ederlan, Grupo Industrial Saltillo, Boherdi Foundry, Funvesa, Fundição Regali Brasil, CALMET, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Central & South America Iron Casting Market Evolving Landscape
Ductile iron metallurgy and digital manufacturing workflows are restructuring competitive advantage in Central and South American foundries, compressing traditional lead-time advantages and enabling precision-grade output from mid-scale operations.
Induction furnace melting paired with in-mold nodularization is collapsing the capital barrier between gray iron commodity production and engineered ductile iron grades. Agricultural machinery suppliers in Brazil's southeastern industrial belt are adopting these hybrid systems to capture premium pricing on fatigue-critical frame components. The technology is collapsing the historical volume threshold required for ductile iron economic viability, enabling smaller foundries to serve precision tillage OEMs previously locked to multinational suppliers.
Brazil's potential carbon-border adjustment mechanism and Mexico's NOM-001-SEDE electrical efficiency standards are forcing furnace technology retrofits across the region's energy-intensive foundry base. Industrial consequence includes accelerated retirement of cupola melting capacity in favor of induction systems with power-factor correction. Gray iron engine block producers in Monterrey's automotive corridor face the steepest compliance timelines, with several operations consolidating melting capacity to amortize scrubber and filter investments across higher throughput.
Consolidated procurement by multinational agricultural OEMs is compressing supplier qualification cycles and unbundling aftermarket casting supply from original equipment contracts. Equipment-leasing pools in Brazil's soybean belt now specify component-level traceability requirements that favor foundries with integrated machining and heat-treatment capability. This pattern concentrates sourcing decisions in São Paulo state, where captive foundry operations and independent suppliers compete for long-term supply agreements with tiered pricing structures tied to volume commitments and metallurgical certification grades.
Central & South America Iron Casting Market Segmentation
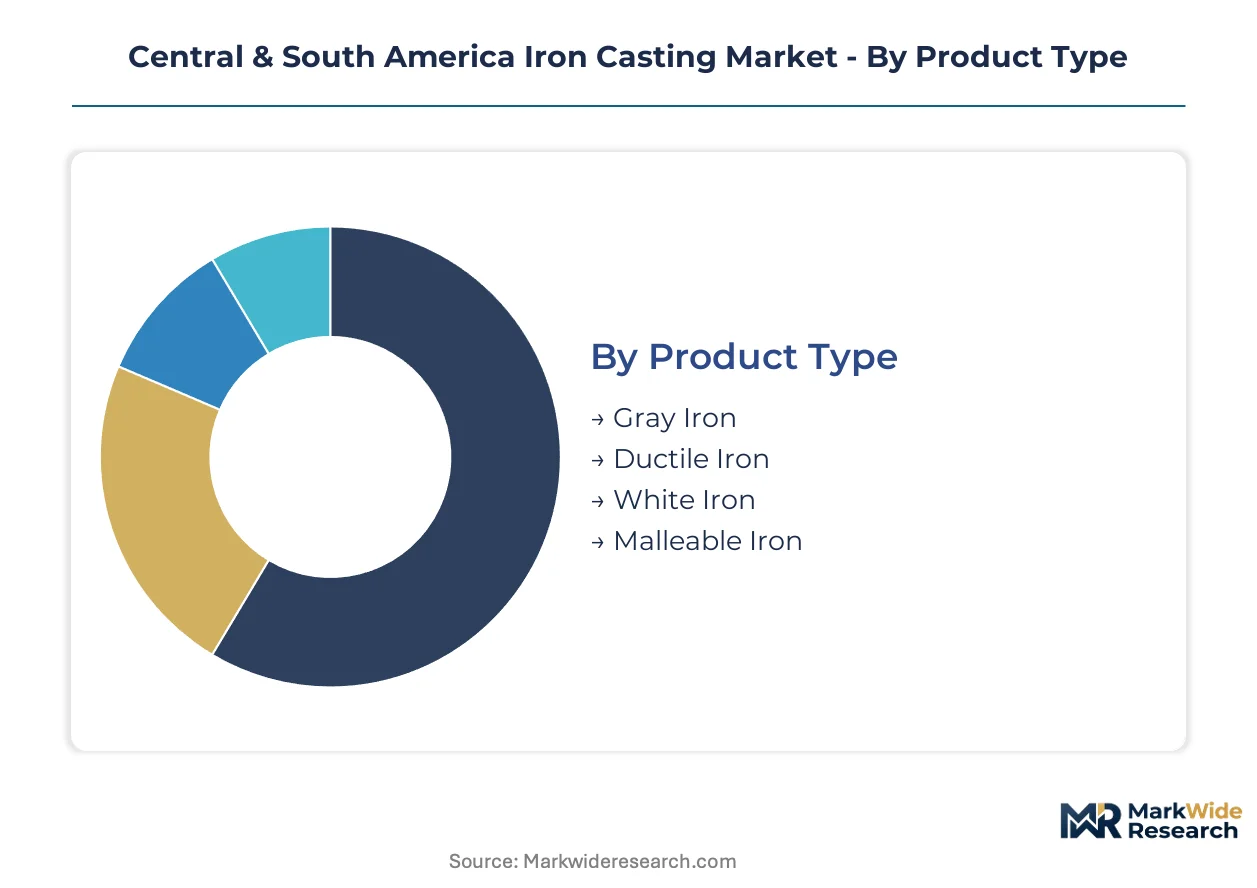
Iron casting segmentation across Central and South America reflects divergent metallurgical requirements between commodity gray iron and engineered ductile grades. Procurement patterns split between high-volume automotive contracts in Mexico and precision agricultural components in Brazil's southeastern cluster.
Product Type:
Material cost tiers separate commodity production from premium-engineered grades capable of fatigue-critical applications.
- Gray Iron:Carbon-silicon alloys with flake graphite morphology deliver compressive strength for engine blocks and pump housings at the lowest material cost point. São Paulo's heavy equipment cluster consumes the bulk of regional output for legacy machinery frames where tensile requirements remain modest.
- Ductile Iron:Nodular graphite microstructures achieve 60,000-80,000 psi tensile strength through magnesium treatment, enabling suspension components and precision tillage frames. Monterrey's automotive corridor specifies these grades for Tier 1 supplier contracts requiring fatigue resistance certification.
- White Iron:Cementite-rich structures provide extreme wear resistance for mining slurry pumps and cement mill liners.
- Malleable Iron:Heat-treated white iron converts to ferritic or pearlitic matrices for thin-section pipe fittings and hardware requiring ductility.
Gray iron commands the established base. The steepest expansion runs through ductile iron displacement of steel fabrications in agricultural equipment.
End User:
Customer concentration patterns concentrate demand in capital equipment sectors with long replacement cycles and specification rigidity.
- Automotive:OEM and Tier 1 procurement drives high-volume ductile iron consumption for engine blocks, suspension knuckles, and brake calipers. NOM-001-SEDE compliance costs in Mexico favor suppliers with integrated melting and machining capability near the US border.
- Agriculture:Precision tillage OEMs specify nodular iron for soil-engaging implements subjected to cyclic loading. Brazil's soybean belt equipment-leasing pools now require component-level metallurgical traceability that favors captive foundry operations.
- Construction:Valve and fitting demand tracks infrastructure investment cycles with lower specification barriers to entry.
- Machinery:General industrial castings face substitution pressure from fabricated steel and aluminum in weight-sensitive applications.
Automotive procurement anchors volume commitments. Agriculture is climbing the fastest as precision equipment replaces legacy tillage implements.
Application:
Functional geometry complexity determines process selection and supplier qualification thresholds.
- Engine Blocks:Cylinder block castings require sand cores for water jacket passages and camshaft tunnels, demanding foundries with in-house core making and leak-testing capability.
- Pump Housings:Complex internal volutes and mounting interfaces favor sand casting with 3D-printed core assemblies for prototype-to-production compression.
- Frames:Agricultural and construction equipment structures prioritize fatigue resistance over dimensional precision.
- Valves:Pressure-containing geometries for water and hydrocarbon service specify tighter dimensional tolerances.
Engine blocks concentrate melting capacity investments. Pump housings are gaining share fastest through digital mold design adoption.
Manufacturing Process:
Process maturity and capital intensity create distinct competitive strata across the regional foundry base.
- Sand Casting:Green sand and chemically bonded systems dominate large, complex geometries including engine blocks and pump housings. The technology accommodates Brazil's agricultural machinery scale requirements with tooling costs that amortize across multi-year production runs.
- Die Casting:High-pressure metal injection captures thin-walled automotive pump housings and bracketry where dimensional precision reduces machining burden. Energy costs in Central America constrain capacity expansion relative to Asian competitors.
- Investment Casting:Ceramic shell processes serve specialized valve and fitting applications requiring near-net-shape accuracy.
- Centrifugal Casting:Rotational casting produces cylindrical pressure vessels and pipe segments with directional solidification control.
Sand casting maintains the installed capacity base. Die casting faces the steepest expansion constraints from regional electricity pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Central and South America iron casting market runs a structural trade deficit in high-specification grades, with Brazil and Mexico absorbing engineered ductile iron imports while exporting commodity gray iron to regional partners. Import substitution dynamics vary sharply by country metallurgical capability and end-use concentration.
Brazil
Agricultural machinery OEMs in São Paulo state drive ductile iron consumption for precision tillage frames and soil-engaging implements. INMETRO certification requirements for industrial equipment exports force foundry modernization investments in the southeastern industrial belt. São Paulo's heavy equipment cluster hosts both captive foundry operations and independent suppliers competing for long-term supply contracts with tiered pricing tied to volume commitments.
Mexico
Automotive Tier 1 suppliers near the US-Mexico border specify fatigue-resistant ductile iron grades for engine blocks and suspension components. NOM-001-SEDE electrical efficiency standards accelerate cupola furnace retirements in favor of induction melting systems. Monterrey's automotive supplier corridor concentrates gray-to-ductile conversion investments as compliance timelines compress margin structures for legacy producers.
Argentina
Domestic agricultural equipment manufacturers source gray iron pump housings and valve bodies from local foundries serving replacement parts markets. IRAM standards create divergent testing requirements that fragment cross-border product homologation with Brazilian and Chilean markets. Buenos Aires province and Córdoba host the principal foundry concentrations, though metallurgical process control expertise concentrates in aging workforce cohorts.
Chile
SEC certifications govern product specifications for mining capital equipment castings, particularly high-chrome white iron wear parts for copper extraction operations. Regional foundries currently import these specialized grades from North American suppliers. Antofagasta and Santiago metropolitan area equipment distributors represent the primary demand concentration for wear-resistant castings in open-pit mining applications.
Peru
OSINERGMIN monitoring of energy-intensive foundry operations shapes compliance costs for independent producers serving construction valve and fitting markets. Mining capital equipment demand for slurry pump wear parts outstrips domestic metallurgical capability, creating import dependency for high-chrome white iron grades. Lima's industrial corridor and Arequipa region concentrate limited domestic foundry capacity.
Central & South America Iron Casting Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in a fragmented supply base where scale advantages concentrate in captive foundry operations. The vendor landscape splits between multinational agricultural OEMs with in-house melting capacity and independent suppliers competing on geographic proximity and certification breadth. Three archetypes dominate: vertically integrated equipment manufacturers, independent regional foundries with machining capability, and specialized wear-parts producers serving extractive industries. Competitive moves center on gray-to-ductile conversion investments and consolidation of melting capacity to amortize environmental compliance costs.
Within the captive foundry tier, Tupy anchors long-term supply relationships through dedicated capacity serving agricultural OEMs. Fundição Regali Brasil exemplifies geographic dominance strategies in Brazil's southeastern industrial belt. Grupo Industrial Saltillo occupies a position among automotive-focused suppliers near the US-Mexico border, representing the nearshoring-driven investment archetype in Monterrey's supplier corridor.
| Leading Market Players |
|---|
| Fundición Callao SA |
| Industrias Ascheri & Cia. |
| Tupy |
| Fagor Ederlan |
| Grupo Industrial Saltillo |
| Boherdi Foundry |
| Funvesa |
| Fundição Regali Brasil |
| CALMET |
| Others |
Value Network & Pricing Analysis
The Santos-Paranaguá maritime corridor shapes ferrous scrap logistics costs across Brazil's southeastern foundry belt, concentrating supply-side leverage among coastal melting operations while forcing inland competitors to absorb differential freight burdens in their ductile iron quotations.
Pricing Analysis
Industrial OEM buyers anchor contract structures across three-tier pricing stratification across premium certified, standard commercial, and economy commodity grades. Price differentiation rests on INMETRO certification level and annual volume commitments above five thousand metric tons. Cost compression in gray iron commodity tiers is intensifying because Asian export demand for ferrous scrap is elevating input costs faster than finished casting prices adjust. Tier 1 automotive suppliers near Monterrey exhibit lowest price sensitivity, while construction valve distributors in Peru's informal channel demonstrate highest elasticity.
Supply Chain Analysis
Ferrous scrap feedstock draws from Brazil's domestic demolition and automotive shredder streams, Chinese graphite electrode manufacturing, and Mexican domestic steel mill offcuts. Raw material dependencies center on high-quality pig iron, magnesium nodularization agents, and ceramic sand for core production. Single-source vulnerability concentrates in graphite electrode supply from Chinese producers, exposing regional foundries to trade friction disruption. Distribution runs through captive foundry direct supply to agricultural OEMs, independent distributor networks for replacement parts, and maquiladora assembly plants for automotive Tier 1 integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from cyclical compression in agricultural capital equipment investment, with precision tillage replacement cycles in Brazil's soybean belt providing the demand inflection.
For Market Incumbents: Insulate margin structures by consolidating melting capacity across São Paulo state to amortize NOM-001-SEDE compliance investments across higher throughput volumes. Backward integration into ferrous scrap collection networks reduces exposure to Asian export demand volatility. Prioritize INMETRO certification maintenance as aluminum substitution threatens passenger vehicle engine block contracts. For New Entrants and Emerging Players: Establish a beachhead in Peru's mining wear parts segment where high-chrome white iron castings currently import from North American suppliers. Target Arequipa region copper operations with slurry pump components as the most penetrable white space. Pursue digital mold design capabilities to compress prototype-to-production timelines as the primary go-to-market differentiator against established foundry relationships. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational agricultural OEMs seeking to divest non-core captive foundry operations in Brazil's southeastern industrial belt. Long-term viability favors mid-scale ductile specialists with integrated machining capability over commodity gray iron producers facing regulatory obsolescence. Watch Brazilian carbon-border adjustment mechanism announcements as the signal indicating accelerated domestic capacity consolidation versus import substitution strategies.| Strategic Initiative | Industry Significance |
|---|---|
| Gray-to-Ductile Conversion Investment | Captures premium pricing from agricultural OEMs specifying fatigue-resistant nodular iron grades. |
| Induction Furnace Retrofit Program | Meets NOM-001-SEDE electrical efficiency mandates while retiring cupola melting capacity. |
| Captive Scrap Collection Network | Reduces input cost volatility exposure from Asian steel mill export demand swings. |
| Digital Mold Design Adoption | Collapses prototype timelines for complex pump housing geometries via 3D sand printing. |
| INMETRO Certification Expansion | Unlocks export-bound industrial equipment contracts requiring conformity assessment framework compliance. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with foundry operations managers, agricultural OEM procurement directors, automotive Tier 1 supplier quality engineers, and mining equipment maintenance superintendents. Secondary validation drew from INMETRO certification registries, Mexican customs trade data, Brazilian foundry association production surveys, and SEC filings from publicly traded equipment manufacturers. Bottom-up volume estimates from individual facility capacities were triangulated against top-down demand models from end-use sector consumption patterns.
Calibration against historical production data and announced capacity investments anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include metallurgical grade tier, end-use industry concentration, manufacturing process technology, and regional regulatory cluster. CAGRs were derived from fitted trend extrapolation moderated by input cost elasticity assumptions. Industry-specific forecast inputs incorporated agricultural machinery replacement cycle timing and nearshoring-driven automotive supplier corridor expansion.
Stress conditions across ferrous scrap price volatility, graphite electrode supply interruption, and Brazilian carbon-border implementation timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory compliance cost trajectories and substitution elasticity between iron and aluminum powertrain materials. Cross-checking against Brazilian foundry association capacity utilization surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Acoustic Panel Market
Building & Construction Materials
US Geosynthetics Market
Building & Construction Materials
Russia Ceramic Tiles Market
Building & Construction Materials
Ceiling Tiles Market
Building & Construction Materials
Decks Market
Building & Construction Materials
Global Cool Roofs Market
Building & Construction Materials
Europe Sandwich Panels Market
Building & Construction Materials
Non-Residential Polished Concrete Market
Building & Construction Materials
Roofing Liners Market
Building & Construction Materials
Mexico Oriented Strand Board Market
Building & Construction Materials
Temporary Storage Buildings Market
Building & Construction Materials
Global Door Market
Building & Construction Materials
Air Barrier Market
Building & Construction Materials
Runway Pavement Grade Asphalt Market
Building & Construction Materials
Clay Roof Tiles Market
Building & Construction Materials
Floor Screeds Market