
 Residential and Commercial Smart Glass Market | 2026-2036
Residential and Commercial Smart Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Residential and Commercial Smart Glass Market Analytics
The split between premium electrochromic facade systems and commodity thermochromic retrofit films is realigning procurement patterns across the construction value chain. Saint-Gobain leverages its integrated flat glass and coatings infrastructure to control cost positions in large commercial projects. Gentex Corporation anchors its position through captive automotive expertise that extends into residential skylight applications. View, Inc. competes on software-defined tinting protocols that differentiate its full-building installations.
Residential and commercial smart glass comprises active glazing systems whose light-transmission properties change in response to electrical signals, thermal gradients, or incident solar radiation, typically incorporating tungsten-oxide electrochromic layers or suspended-particle devices with switching speeds under three minutes. Electrochromic windows dominate new commercial construction due to superior optical clarity and programmable control, while SPD technology leads in retrofit residential skylights where installation speed matters. Photovoltaic-integrated smart glass represents the fastest-expanding margin pool as building-integrated generation mandates spread.
California's Title 24 energy code and the EU F-Gas Regulation shape product specifications by penalizing static glazing in new construction and restricting high-global-warming-potential gases in manufacturing processes. The EPA Energy Star certification program and REACH compliance requirements in Europe further filter market access for imported components. Stakeholders must monitor evolving net-zero building mandates and decide whether to prioritize electrochromic R&D or SPD manufacturing scale as regulatory thresholds tighten.
Market Dynamics
Electrochromic glazing is displacing static facades as California's Title 24 energy code and the EU F-Gas Regulation impose hard performance thresholds on building envelopes. Developers now face binary compliance choices that favor active tinting systems over conventional low-E glass.
Growth Catalysts
- California Title 24 energy code:New construction mandates in the state require dynamic envelope solutions that reduce HVAC loads. Commercial developers specify electrochromic systems to meet prescriptive thermal performance targets.
- Germany's KfW green building program:Subsidized retrofit financing accelerates dynamic glazing adoption in existing commercial stock. Property owners combine envelope upgrades with energy efficiency audits.
- Photovoltaic-integrated smart glass:Building-integrated generation mandates in multiple jurisdictions pull this technology category into mainstream specification. Architects specify dual-function facades that offset operational carbon.
Market Restraints
- Tungsten oxide supply concentration:Electrochromic layer production depends on limited precursor chemical suppliers. Price volatility in specialty metal oxides compresses manufacturing margins.
- High capital intensity of SPD manufacturing:Suspended-particle device fabrication requires cleanroom infrastructure and precision film coating equipment. Scale economics favor incumbent producers with captive capacity.
- REACH compliance friction:European chemical registration requirements delay new coating formulations from entering the market. Imported components face extended certification timelines.
Strategic Opportunities
- Underpenetrated residential retrofit segment:Single-family homeowners represent unserved demand for thermochromic window films. DIY installation channels could democratize access to dynamic glazing.
- Convergence of electrochromic and IoT building management:Software-defined tinting protocols enable grid-responsive facades. Utility demand-response programs create revenue stacking for building operators.
- India's PLI scheme for advanced materials:Domestic manufacturing incentives could localize smart glass production for South Asian construction markets. Green building certification uptake drives specification pull.
Industry Challenges
- Electrochromic coating technician shortage:Specialized vacuum deposition skills are scarce in construction labor markets. Training pipelines lag behind installation demand curves.
- Integration complexity with legacy BAS protocols:Existing building automation systems use proprietary communication standards. Retrofit projects require custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Residential and Commercial Smart Glass Market |
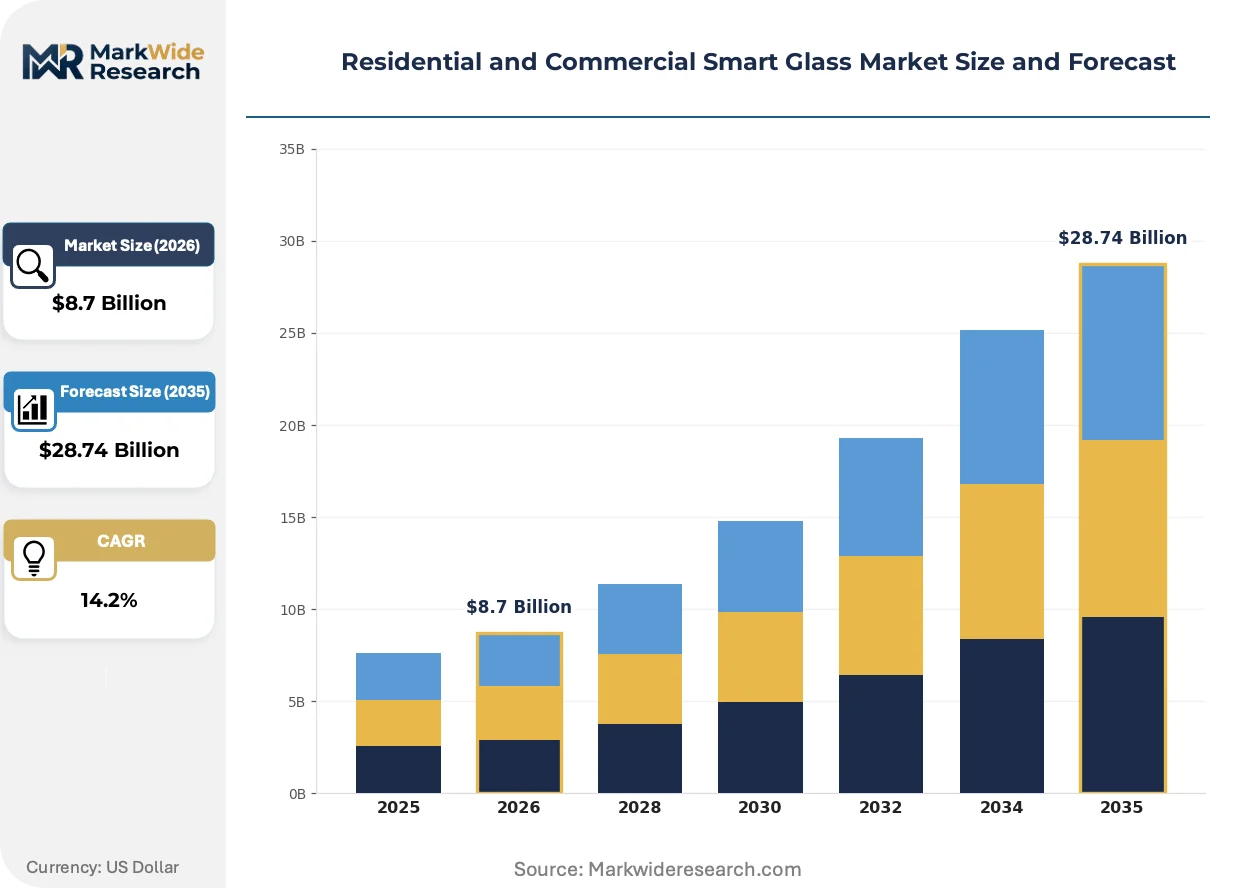
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrochromic, Thermochromic, Photovoltaic, SPD Application: Windows, Skylights, Facades, Solar Panels Technology: Nano-coating, Liquid Crystal, Polymer, Adaptive End User: Residential Buildings, Commercial Spaces, Automotive, Aviation |
| Companies Covered | Saint-Gobain, AGC Inc., Gentex Corporation, View, Inc., Polytronix, Inc., PPG Industries, Corning Incorporated, Research Frontiers Inc., Kinestral Technologies, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Residential and Commercial Smart Glass Market Evolving Landscape
Software-defined building envelopes are redefining how facade performance is procured, monetized, and operated. Three concurrent developments are compressing the traditional specification cycle.
Photovoltaic-integrated electrochromic glass is integrating generation and modulation functions into single-pane architectures. High-rise developers in Dubai and Manhattan specify these systems to meet net-zero carbon targets while preserving visual transparency. The technology is integrating BIPV mandates with dynamic thermal control, collapsing what were separate procurement categories.
The EU F-Gas Regulation is restricting hydrofluorocarbon use in glazing manufacturing processes. European producers reformulate coating chemistries to eliminate high-GWP blowing agents and solvents. German facade fabricators face compressed compliance deadlines that accelerate R&D spending on aqueous-based deposition methods.
Outcome-based facade performance contracting is displacing traditional capital expenditure models for commercial envelopes. Real estate investment trusts in California and New York now procure glazing-as-a-service agreements that bundle installation, maintenance, and energy savings guarantees. This shift transfers technology risk from building owners to systems integrators.
Residential and Commercial Smart Glass Market Segmentation
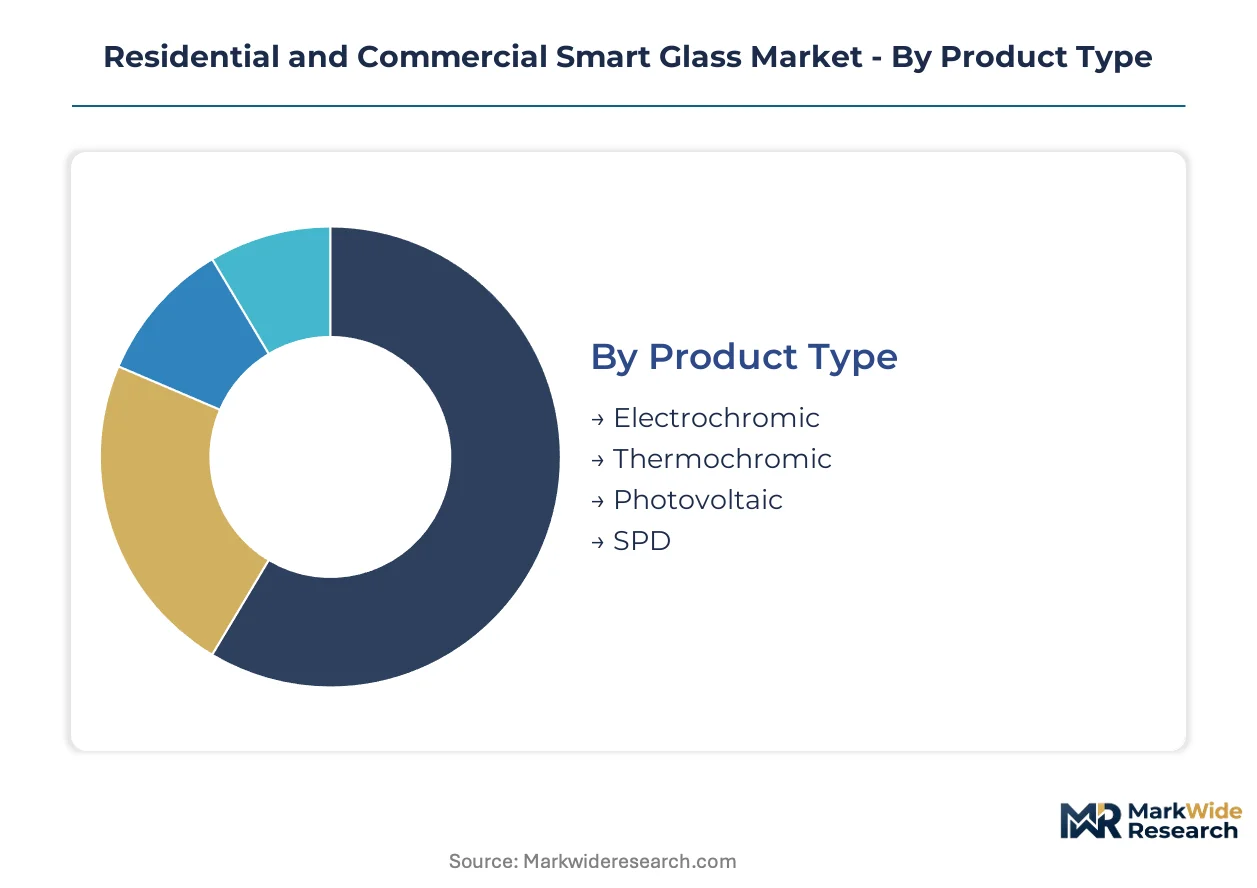
Smart glass procurement patterns diverge sharply across product architectures and installation contexts. Specification decisions cascade through distinct technical, regulatory, and economic filters depending on whether the project involves new commercial facades or residential retrofits.
Product Type:
Supply concentration in tungsten oxide precursors and vacuum deposition equipment shapes competitive positioning across electrochromic manufacturing.
- Electrochromic:Tungsten-oxide layered systems switch transmission via electrical charge with optical clarity above 90% in clear state. Manhattan and Dubai luxury high-rise developers specify these for net-zero carbon compliance under prescriptive envelope codes. California Title 24 mandates pull specification volume fastest in new commercial construction.
- Thermochromic:Temperature-responsive films require no electrical infrastructure, enabling rapid retrofit installation. Single-family homeowners in Germany's KfW-subsidized programs adopt these for skylight upgrades where wiring costs would dominate project economics.
- Photovoltaic:Dual-function generation-modulation glass integrates building-integrated mandates with dynamic thermal control.
- SPD:Suspended-particle devices achieve sub-three-minute switching speeds through liquid crystal dispersion in polymer matrices.
Today's leader: Electrochromic. Tomorrow's challenger: Photovoltaic.
Application:
Installation geometry determines whether glazing serves thermal modulation, daylight harvesting, or structural envelope functions.
- Windows:Operable and fixed glazing units comprise the volume base across both residential and commercial building stock. Germany's KfW green building program channels retrofit financing toward window replacement in existing commercial properties, combining envelope upgrades with mandatory energy audits.
- Facades:Curtain wall and storefront systems integrate active tinting across entire building elevations. Dubai developers specify photovoltaic-integrated electrochromic facades to meet operational carbon targets while preserving visual transparency for premium office leasing.
- Skylights:Overhead glazing applications prioritize SPD technology where installation speed and minimal electrical routing matter most.
- Solar Panels:Building-integrated generation mandates in multiple jurisdictions pull dual-function glazing into mainstream architectural specification.
Facade applications command premium specification economics. Window retrofits offer volume scaling potential.
Technology:
Coating chemistry and device architecture separate patent-protected premium positions from commodity manufacturing.
- Nano-coating:Atomic-layer deposition of metal oxides enables precise optical switching with manufacturing scale concentrated among vacuum equipment specialists. REACH compliance friction in Europe delays new formulation entry, extending incumbent technology leadership windows.
- Liquid Crystal:SPD devices leverage nematic crystal orientation in polymer matrices for rapid switching without ionic migration degradation.
- Polymer:Thermochromic films embed temperature-responsive dyes in flexible substrates for DIY residential channels.
- Adaptive:Software-defined tinting protocols enable grid-responsive facades through IoT building management integration.
Nano-coating holds current manufacturing depth. Adaptive protocols are climbing the fastest as utility demand-response programs expand.
End User:
Customer type dictates whether procurement flows through construction general contractors, automotive OEMs, or aftermarket retail channels.
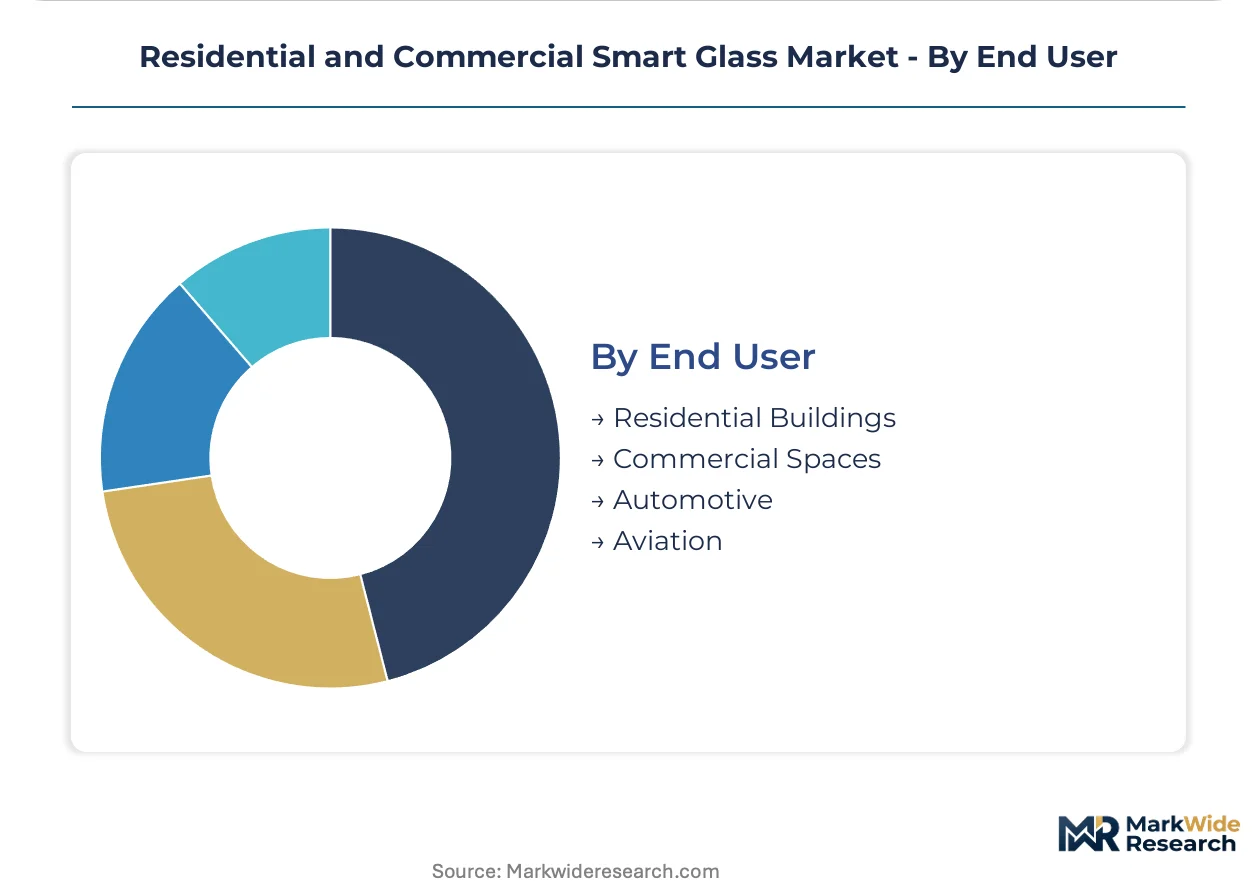
- Residential Buildings:Single-family and multi-family homeowners access smart glass through retrofit contractors and emerging DIY film channels. Underpenetrated demand concentrates in thermochromic window films where installation avoids specialized electrical labor.
- Commercial Spaces:Office, retail, and hospitality developers specify full-building electrochromic systems under California Title 24 and EU energy performance standards. Outcome-based facade performance contracting now transfers technology risk from REITs to systems integrators.
- Automotive:Sunroof and glazing applications leverage captive SPD manufacturing expertise from adjacent electronics supply chains.
- Aviation:Cabin window dimming systems prioritize electrochromic reliability under pressurization cycling and electromagnetic interference standards.
Commercial spaces anchor revenue concentration. Residential retrofits represent the steepest expansion trajectory for democratized access channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's KfW green building program accelerates dynamic glazing retrofits faster than California's Title 24 mandates pull new construction demand. Construction codes in Dubai and Manhattan luxury high-rises now specify electrochromic facades at comparable intensities.
United States
California's Title 24 energy code imposes prescriptive thermal performance thresholds that commercial developers meet through electrochromic system specification. The EPA Energy Star certification program filters market access for imported smart glass components. Manhattan luxury high-rise developers anchor demand concentration for full-building electrochromic installations.
Germany
Property owners combine envelope upgrades with mandatory energy efficiency audits under the KfW green building program's subsidized retrofit financing. The EU F-Gas Regulation restricts high-global-warming-potential gases in glazing manufacturing processes. German facade fabricators face compressed compliance deadlines that accelerate aqueous-based deposition R&D.
United Arab Emirates
Dubai developers specify photovoltaic-integrated electrochromic facades to meet operational carbon targets while preserving visual transparency for premium office leasing. The country's national building regulator enforces net-zero mandates for new commercial construction. Luxury high-rise clusters in Dubai Marina and Downtown Dubai concentrate specification volume.
China
Dual carbon goals drive building-integrated generation mandates that pull dual-function glazing into mainstream architectural specification. The Ministry of Ecology and Environment enforces manufacturing emissions standards that filter coating chemistry formulations. Yangtze River Delta construction markets concentrate demand for electrochromic facade systems.
India
The PLI scheme for advanced materials incentivizes domestic manufacturing localization for South Asian construction markets. Green building certification uptake drives specification pull from commercial developers. Maharashtra and Gujarat industrial corridors anchor emerging fabrication capacity for thermochromic retrofit films.
Residential and Commercial Smart Glass Market Competitive Landscape
Top-tier vendors anchor integrated flat glass and coatings infrastructure, while specialized electrochromic technology developers compete on software-defined tinting protocols. The vendor base separates into three strategic archetypes: diversified materials conglomerates controlling cost positions through captive supply chains, automotive electronics specialists extending expertise into architectural applications, and pure-play smart glass developers monetizing building management system integration. Dominant competitive moves include backward integration into tungsten oxide precursor supply and strategic partnerships with real estate investment trusts for outcome-based facade performance contracting.
Within the diversified materials tier, Saint-Gobain and AGC Inc. represent archetypes of integrated flat glass producers leveraging coatings infrastructure for large commercial project cost control. Gentex Corporation and View, Inc. exemplify technology specialists translating adjacent electronics expertise into architectural specification. PPG Industries and Corning Incorporated occupy positions bridging commodity coatings and advanced materials innovation. These six entities collectively illustrate the competitive tension between manufacturing scale and software-defined differentiation.
| Leading Market Players |
|---|
| Saint-Gobain |
| AGC Inc. |
| Gentex Corporation |
| View, Inc. |
| Polytronix, Inc. |
| PPG Industries |
| Corning Incorporated |
| Research Frontiers Inc. |
| Kinestral Technologies, Inc. |
| Others |
Value Network & Pricing Analysis
Captive backward integration into tungsten oxide precursor supply anchors Saint-Gobain's cost position in large commercial projects while insulating its pricing power from specialty metal oxide volatility. This integration choice simultaneously secures manufacturing margin and enables competitive positioning against pure-play electrochromic developers dependent on external chemical suppliers.
Pricing Analysis
Capacity additions in India's Maharashtra and Gujarat industrial corridors are reshaping price floors for thermochromic retrofit films as domestic manufacturing under the PLI scheme reduces import dependency. Three-tier pricing structure across premium electrochromic facade systems, standard SPD skylight modules, and economy thermochromic DIY films stratifies by installation complexity and certification tier. Cost compression in commodity thermochromic segments is intensifying because polymer substrate suppliers compete on volume scale. Single-family homeowners in residential retrofit channels exhibit highest price sensitivity, while Manhattan and Dubai luxury high-rise developers prioritize optical clarity and programmable control over unit economics.
Supply Chain Analysis
REACH compliance friction in Europe gates market access for imported coating formulations, extending certification timelines and filtering supplier participation. Manufacturing concentration centers on Germany for electrochromic vacuum deposition equipment, China for photovoltaic-integrated glass substrates, and Japan for precision liquid crystal polymer matrices. Raw material dependencies draw from tungsten oxide precursors, indium tin oxide conductive layers, and temperature-responsive dye formulations. Single-source vulnerability in specialty vacuum deposition equipment creates supply chain risk for scale expansion. Distribution runs through construction general contractors for commercial facades, retrofit installation specialists for residential channels, and automotive OEMs for SPD sunroof applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Residential and Commercial Smart Glass Market functions as a stable compounder, with building-integrated generation mandates and net-zero envelope codes driving steady specification pull across multiple geographies and construction cycles.
For Market Incumbents: Cement control over tungsten oxide precursor supply through backward integration or long-term offtake agreements with limited specialty chemical suppliers. Deepen software-defined tinting protocol development to defend against pure-play electrochromic developers competing on IoT building management integration. Capacity additions in India under the PLI scheme represent the priority geographic lever for cost position defense in emerging South Asian markets. For New Entrants and Emerging Players: Single-family homeowners in underpenetrated residential retrofit segments offer the most accessible white-space target, particularly for thermochromic window films deployable through DIY installation channels. Germany's KfW-subsidized retrofit financing creates immediate specification pull for envelope upgrade solutions. India's Maharashtra industrial corridor provides manufacturing localization opportunity with lower competitive density than established European and North American markets. A direct-to-consumer digital sales platform with installation partner networks enables rapid channel buildout without incumbent contractor relationships. For Investors and Strategic Acquirers: Roll-up economics work for regional facade systems integrators because outcome-based performance contracting transfers technology risk from building owners to service providers, creating recurring revenue streams and customer captivity. The 5-10 year viability window favors targets with established relationships with real estate investment trusts in California and New York. Acquisition priority rests on electrochromic technology developers with software-defined tinting protocols and utility demand-response program integration. The signal to watch is tightening EU F-Gas Regulation compliance deadlines accelerating aqueous-based deposition R&D spending among European fabricators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tungsten Oxide Supply | Secures manufacturing margin against specialty metal oxide price volatility from limited precursor suppliers. |
| Software-Defined Tinting Protocol Development | Enables grid-responsive facades through IoT building management integration under California Title 24 mandates. |
| Aqueous-Based Deposition R&D Investment | Addresses compressed EU F-Gas Regulation compliance deadlines restricting hydrofluorocarbon use in coating processes. |
| DIY Installation Channel Buildout | Democratizes thermochromic film access for single-family homeowners in Germany's KfW-subsidized retrofit programs. |
| Photovoltaic-Integrated Product Line Expansion | Captures building-integrated generation mandate pull from Dubai developers meeting net-zero carbon targets. |
Research Methodology
Multiple input streams — primary interviews with facade engineers and glazing procurement managers, regulatory filing analysis, and construction project databases — were reconciled to construct segment-level demand estimates. Primary fieldwork engaged electrochromic coating technicians, building automation systems integrators, real estate development executives, and KfW program administrators. Secondary validation drew from EPA Energy Star certification records, EU ECHA REACH registration databases, California Title 24 compliance filings, and Indian PLI scheme beneficiary disclosures. Bottom-up project pipeline analysis and top-down construction spend allocation were triangulated to cross-check volume assumptions.
Data-stream reconciliation across product architecture, installation context, and geographic regulatory cluster anchored the analytical framework throughout the projection horizon. Segmentation dimensions modeled include electrochromic versus thermochromic versus photovoltaic product types, new construction versus retrofit application contexts, and nano-coating versus liquid crystal versus polymer technology categories. CAGRs were derived from regression analysis against building code adoption curves and green building certification uptake rates. Forecast inputs incorporated tungsten oxide precursor supply constraints, REACH compliance timeline friction, and utility demand-response program expansion trajectories.
Underlying measurement precision varies by segment; electrochromic facade systems in commercial new construction carry tighter precision than emerging photovoltaic-integrated categories with limited installation history. Forecasts reflect assumptions regarding regulatory enforcement consistency, subsidy program continuity, and coating chemistry formulation approval timelines. A model refresh is warranted upon material change in EU F-Gas Regulation implementation schedules or California Title 24 prescriptive threshold adjustments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Aerated Autoclaved Concrete (AAC) Market
Building & Construction Materials
North America Concrete Sealer Market
Building & Construction Materials
Concrete Aggregate Market
Building & Construction Materials
Runway Pavement Grade Asphalt Market
Building & Construction Materials
Precast Concrete Pile Market
Building & Construction Materials
Africa Vinyl Windows Market
Building & Construction Materials
Brick Market
Building & Construction Materials
Outside Door Handle Market
Building & Construction Materials
Corrugated Polycarbonate Panels Market
Building & Construction Materials
Wood Truss Market
Building & Construction Materials
North America Luxury Vinyl Tile (LVT) Market
Building & Construction Materials
US Metal Stadium Seating Market
Building & Construction Materials
Bamboo Engineered Wood Market
Building & Construction Materials
Pre-Insulated Pipes Market
Building & Construction Materials
Acoustic Insulation Market
Building & Construction Materials
India Luxury Vinyl Tile (LVT) Market