
 Indonesia Ceramic Tiles Market | 2026-2036
Indonesia Ceramic Tiles Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Ceramic Tiles Market Foresight
Market Dynamics
Premium-grade large-format porcelain is rotating toward the center of Indonesian project specifications. KIA Keramik Tbk leverages captive clay reserves to sustain cost leadership in Java's manufacturing belt. Granito (PT Citra Granito) anchors its position through vertical control over glazing lines. Arwana Citramulia Tbk differentiates via specialized digital printing capabilities for hospitality interiors.
Product and Segment Structure
Ceramic tiles are fired clay or porcelain slabs, typically measuring 300x300 mm to 800x1600 mm, with water absorption rates below 0.5% for vitrified grades and surface hardness rated by Mohs scale for commercial durability. Flooring applications dominate volume, while wall and backsplash segments command margin premiums in Jakarta's luxury residential towers. Porcelain leads product-type value pools due to its density and frost resistance for outdoor specification. Distributor channels still control rural penetration, though direct-sales contracts with property developers are gaining share in Surabaya and Bandung.
Regulatory Environment and Outlook
BIS-equivalent SNI standards enforced by Indonesia's national standardization body govern dimensional tolerance and lead-content limits, while the Ministry of Public Works mandates green-building material ratings for government-funded infrastructure. The country's ceramic cluster around Gresik faces tightening MEE air-quality benchmarks for kiln emissions. Stakeholders must monitor pending revisions to SNI glazing standards and assess whether captive gas supplies can absorb energy-cost volatility across Java's production base.
Market Dynamics
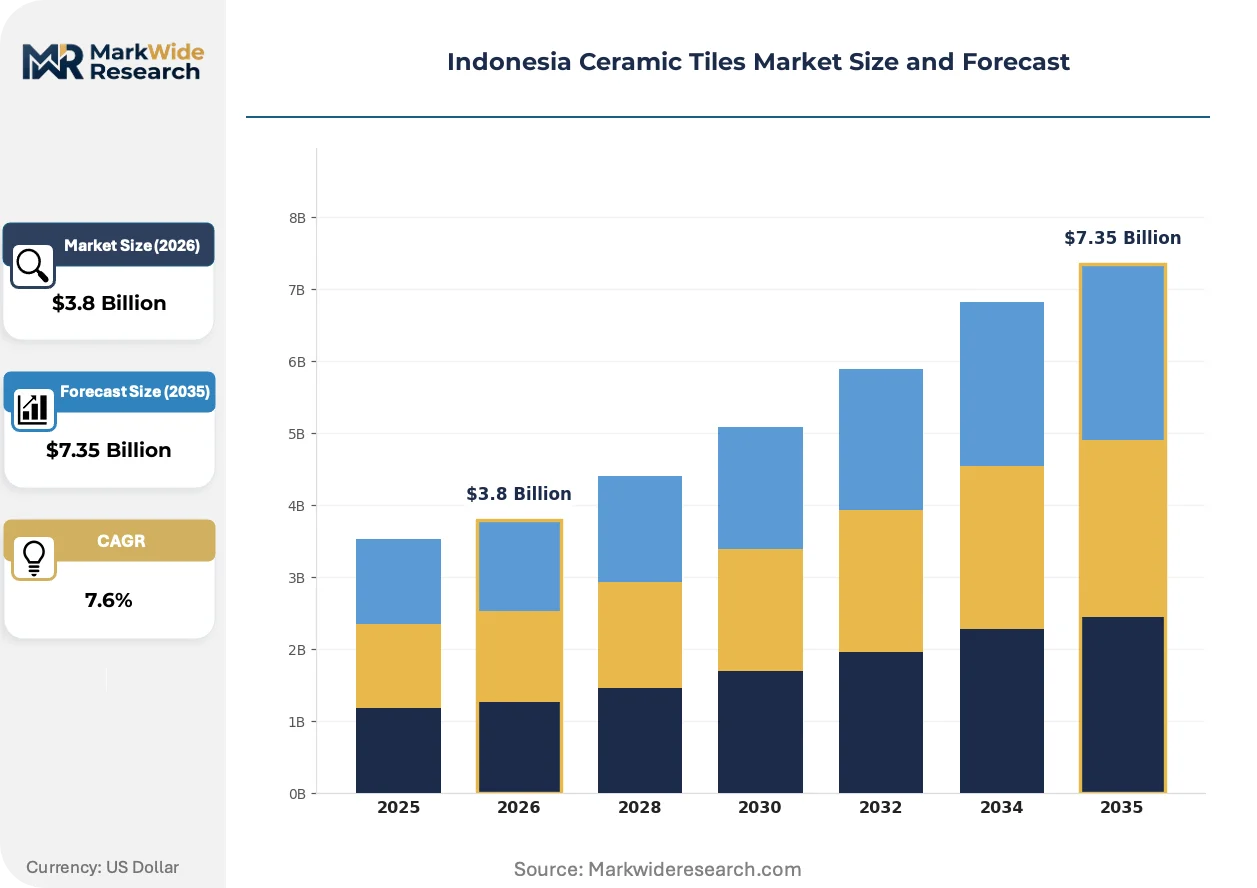
SNI mandatory certification for ceramic products is compressing Indonesia's manufacturing base toward standardized quality tiers, eliminating sub-scale producers while rewarding capital-intensive players with captive gas and clay reserves.
Growth Catalysts
- Urban Residential Construction:High-rise towers across Greater Jakarta and Surabaya specify large-format porcelain slabs for flooring and facade cladding, absorbing premium-grade domestic output.
- Green-Building Mandates:Indonesia's Ministry of Public Works requires green-building material ratings for government-funded infrastructure, tilting procurement toward low-emission vitrified tile suppliers.
- MEE Air-Quality Benchmarks:Tightening kiln emission standards around Gresik are accelerating consolidation, concentrating volume among producers with installed scrubber systems and captive gas contracts.
Market Restraints
- Natural Gas Price Volatility:Java's ceramic cluster depends on subsidized pipeline gas; tariff rebalancing threatens kiln operating margins for mid-scale manufacturers without long-term supply agreements.
- Import-Grade Specification Gap:Commercial high-rise projects in Jakarta's central business district specify imported vitrified tiles, capping domestic premium pricing power.
- Clay Reserve Access Concentration:Captive mining licenses concentrate among legacy producers, raising entry barriers for new capacity in East Java's manufacturing belt.
Strategic Opportunities
- Digital Printing Specialization:Hospitality interiors across Bali and Lombok demand customized surface aesthetics, opening margin pools for producers with in-house glaze formulation and inkjet capabilities.
- Direct Developer Contracts:Property developers in Surabaya and Bandung are bypassing distributor networks, creating channel restructuring opportunities for manufacturers with project sales teams.
- SNI Export Alignment:Indonesia's national standardization body is harmonizing glazing standards with ASEAN technical regulations, enabling cross-border shipment to Vietnam and Philippines markets.
Industry Challenges
- Skilled Kiln Operator Scarcity:Temperature profiling and firing curve optimization require experienced technicians; training pipelines lag capacity expansion timelines across Java.
- Certification Timeline Compression:SNI renewal cycles and factory audit queues create working capital strain for producers scaling output to meet project deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Ceramic Tiles Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Porcelain, Glazed, Unglazed, Vitrified End User: Residential, Commercial, Industrial, Institutional Distribution Channel: Direct Sales, Retail Stores, Online, Distributors Application: Flooring, Wall, Backsplash, Outdoor |
| Companies Covered | KIA Keramik Tbk, Granito (PT Citra Granito), Arwana Citramulia Tbk, Surya Toto Indonesia Tbk, Diamond Keramik Indonesia, Mulia Keramik Indahraya, Roman Ceramic International, Intikeramik Alamasri Industri Tbk, Platinum Ceramics Industry, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Ceramic Tiles Market Shifts & Advancements
Large-format porcelain slab technology is rotating production economics and specification patterns across Indonesia's construction value chain, compressing traditional tile dimensions toward obsolescence.
Continuous roller kiln technology with single-firing cycles is displacing intermittent tunnel kiln methods in Java's manufacturing belt. Arwana Citramulia and Granito have retrofitted Gresik facilities to process slabs up to 1600 mm length. This capital shift is compressing unit energy consumption per square meter while raising minimum efficient scale thresholds for new entrants.
Indonesia's national standardization body is revising SNI glazing standards to align with ASEAN mutual recognition arrangements. The regulatory adjustment forces manufacturers to retest lead-content limits and dimensional tolerances for export-bound production. Producers with existing laboratory certification partnerships are accelerating compliance documentation ahead of enforcement deadlines.
Property developers in Jakarta's luxury residential segment are consolidating procurement decisions into centralized technical teams, bypassing traditional distributor relationships. Direct sales contracts now specify performance warranties and batch consistency guarantees previously handled through wholesale channels. This concentration is most visible in South Jakarta's premium tower developments, where single-source supplier agreements cover entire facade and flooring packages.
Indonesia Ceramic Tiles Market Segmentation
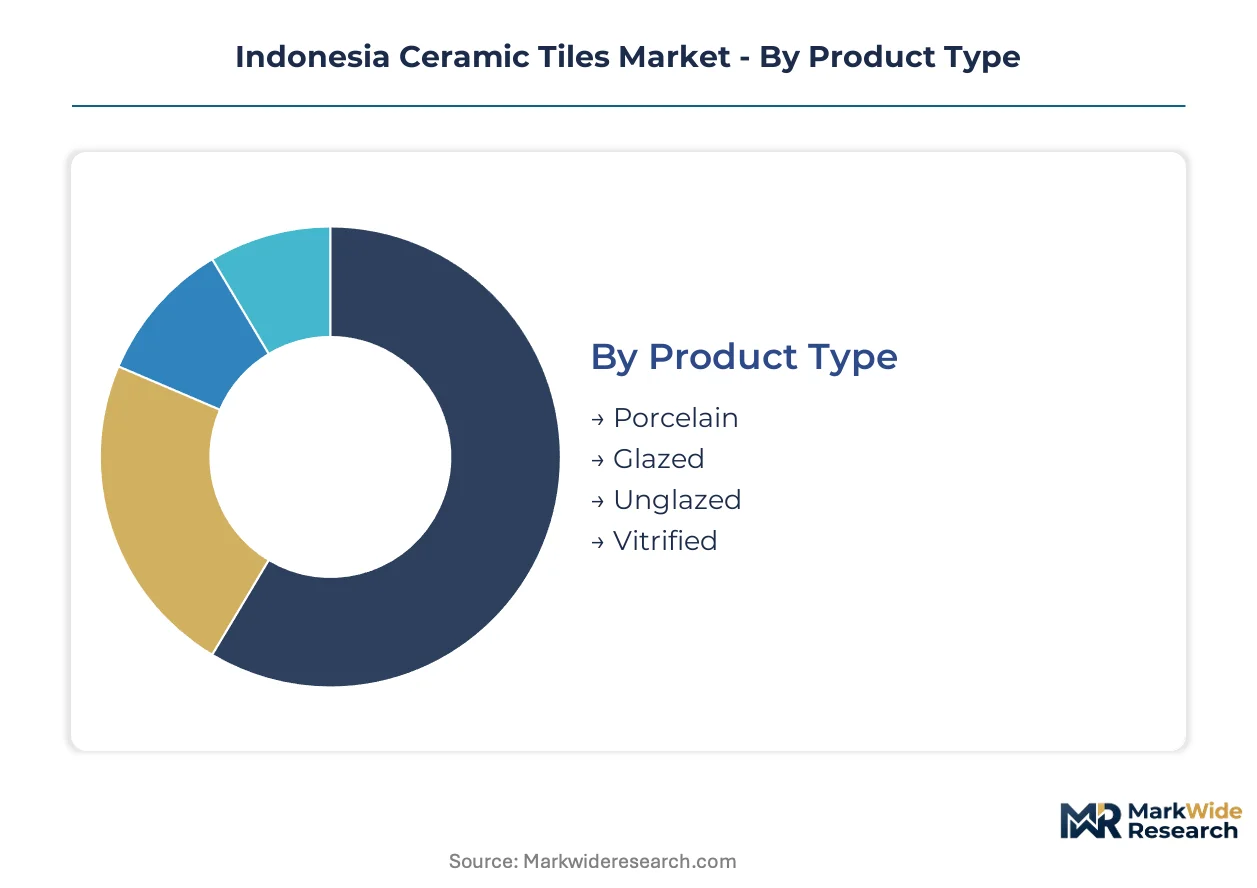
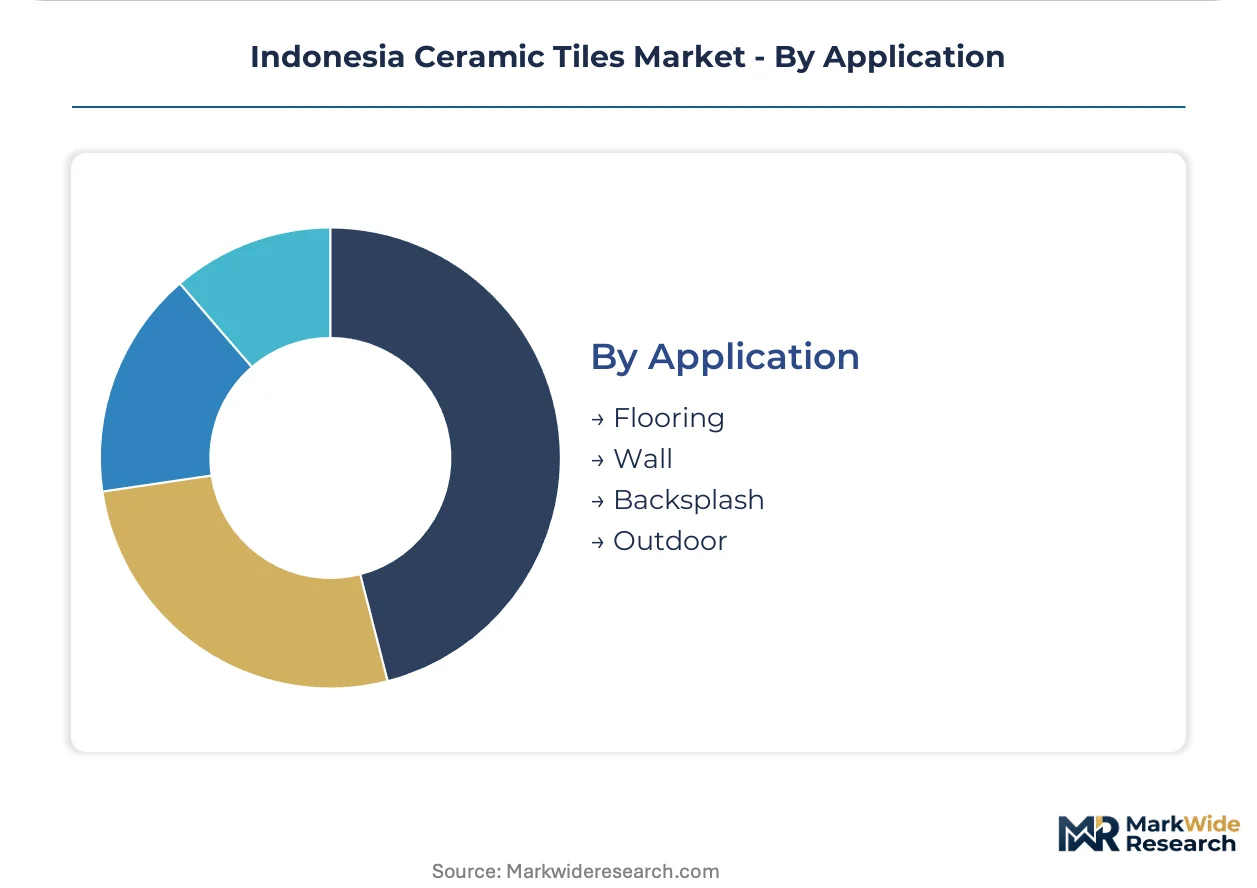
Segmentation in Indonesia's ceramic tiles market reveals how product specifications, end-use requirements, and channel economics interlock. Manufacturers calibrate kiln output and inventory allocation against these dimensions to capture margin pools across Java's construction corridor.
Product Type:
Distributor channels in rural East Java and Central Java push standard glazed and unglazed volumes, while direct sales contracts in Greater Jakarta concentrate on premium porcelain and vitrified grades for high-rise specifications.
- Porcelain:Dense, low-porosity ceramic fired above 1200°C with water absorption below 0.5%. Surabaya's luxury residential towers specify large-format porcelain slabs for flooring and facade cladding, absorbing output from Gresik's retrofitted continuous roller kilns.
- Vitrified:Fully vitrified tiles achieve near-zero porosity through extended firing cycles. Commercial high-rise projects in Jakarta's central business district import these grades for lobby and common-area specifications, capping domestic pricing power.
- Glazed:Surface-coated tiles with decorative glaze layers applied before single-firing. Hospitality interiors across Bali demand customized glaze aesthetics.
- Unglazed:Through-body tiles without surface coating, valued for slip resistance in industrial flooring applications.
By volume, Glazed leads through distributor penetration. By growth pace, Porcelain is ahead.
End User:
Cost tier separation drives procurement patterns, with institutional and commercial buyers commanding volume discounts while residential purchasers absorb premium markups for specialized finishes.
- Residential:High-rise towers across Greater Jakarta and Surabaya absorb large-format porcelain for flooring and backsplash applications. Property developers in South Jakarta consolidate procurement through centralized technical teams, bypassing traditional wholesale channels.
- Commercial:Office and retail specifications prioritize Mohs hardness ratings and batch consistency for high-traffic areas. Direct sales contracts now specify performance warranties previously handled through distributor networks.
- Industrial:Manufacturing facilities specify unglazed or heavy-duty vitrified grades for chemical resistance and load-bearing capacity.
- Institutional:Government-funded infrastructure projects require green-building material ratings under Ministry of Public Works mandates, tilting procurement toward low-emission domestic suppliers.
Residential commands absolute volume. Commercial is climbing the fastest as Jakarta's central business district expands.
Distribution Channel:
Geography determines channel viability, with distributor networks essential for rural Java penetration while direct contracts dominate urban project clusters.
- Direct Sales:Property developers in Surabaya and Bandung bypass distributor markups through project-specific contracts. Technical teams specify batch consistency guarantees and performance warranties for entire facade and flooring packages.
- Distributors:Wholesale networks control rural penetration across Central and East Java, stocking standard glazed and unglazed inventories for smaller contractors.
- Retail Stores:Showroom channels serve renovation and replacement demand in Jakarta's affluent suburbs.
- Online:Digital procurement platforms capture specification research and sample ordering, though bulk volume still flows through established trade channels.
Distributors still handle the greatest transaction volume. Direct Sales is gaining share fastest among premium-grade producers.
Application:
Margin structure varies sharply by installation location, with vertical surfaces commanding glaze specialization premiums and outdoor specifications requiring frost resistance certification.
- Flooring:Dominates absolute volume across all product types, with porcelain and vitrified grades specified for high-traffic commercial and residential applications. Jakarta's luxury towers absorb premium large-format slabs for seamless visual continuity.
- Wall:Backsplash and vertical installations command margin premiums for digital printing capabilities. Arwana Citramulia's specialized inkjet lines capture hospitality demand across Bali and Lombok.
- Backsplash:Kitchen and bathroom vertical surfaces require glaze formulation expertise for moisture resistance and aesthetic customization.
- Outdoor:Facade cladding and terrace applications specify frost-resistant vitrified grades with slip-resistant surface treatments, subject to SNI durability testing.
Flooring leads by square meters installed. Wall applications show the steepest expansion trajectory as hospitality construction accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Java's manufacturing belt concentrates Indonesia's ceramic tile production capacity, with East Java's Gresik cluster hosting the majority of continuous roller kiln installations. The country's regulatory framework through SNI certification and MEE emissions standards is compressing regional supply toward standardized quality tiers.
Greater Jakarta
Luxury residential towers in South Jakarta absorb large-format porcelain slabs for seamless flooring and facade cladding. The Ministry of Public Works mandates green-building material ratings for government-funded infrastructure in the capital corridor. Centralized technical teams at property developers now consolidate procurement decisions, bypassing traditional distributor networks for direct manufacturer contracts.
East Java
Surabaya's commercial high-rise sector specifies imported-grade vitrified tiles for lobby and common-area applications. SNI mandatory certification enforced by Indonesia's national standardization body governs dimensional tolerance and lead-content limits for domestic production. The Gresik ceramic cluster faces tightening MEE air-quality benchmarks for kiln emissions, accelerating consolidation among producers with installed scrubber systems.
Central Java
Semarang and surrounding districts serve as distribution nodes for rural penetration of standard glazed and unglazed inventories. Distributor networks control wholesale channels across smaller contractor markets in the region. The manufacturing base here supplies mid-tier residential construction with water absorption rates above vitrified grades but below premium porcelain specifications.
Bali and Lombok
Hospitality interiors across these islands demand customized surface aesthetics with specialized digital printing capabilities. Arwana Citramulia's inkjet lines capture margin premiums from resort and hotel developments. The segment relies on direct sales contracts rather than distributor markups, with batch consistency guarantees for large-scale renovation projects.
West Java
Bandung's property developers are bypassing distributor networks through project-specific direct sales contracts. The region absorbs output from captive clay reserves controlled by legacy producers with mining licenses. Energy-cost volatility from subsidized natural gas tariff rebalancing threatens kiln operating margins for mid-scale manufacturers without long-term supply agreements.
Indonesia Ceramic Tiles Market Competitive Landscape
Concentration sits with capital-intensive producers possessing captive gas contracts and clay reserves, while sub-scale manufacturers face elimination under SNI compliance costs. The market structure tilts toward tiered competition between premium-grade specialists and volume-driven standard producers. Three archetypes dominate: vertically integrated clay-to-kiln operators, digital printing specialists for hospitality, and distributor-dependent rural suppliers. Competitive moves center on retrofitting continuous roller kilns for large-format slabs and securing direct developer contracts in Surabaya and Bandung.
Among Indonesia-based producers, KIA Keramik Tbk, Granito, and Arwana Citramulia Tbk occupy distinct positions within this structure. KIA Keramik Tbk exemplifies the integrated archetype through captive clay reserve control. Granito represents vertical control over glazing line operations. Arwana Citramulia Tbk anchors the specialization vector through digital printing capabilities for customized hospitality interiors. These three collectively illustrate how regulatory compression toward SNI standards rewards capital deployment and technical differentiation over distributor-scale reach.
| Leading Market Players |
|---|
| KIA Keramik Tbk |
| Granito (PT Citra Granito) |
| Arwana Citramulia Tbk |
| Surya Toto Indonesia Tbk |
| Diamond Keramik Indonesia |
| Mulia Keramik Indahraya |
| Roman Ceramic International |
| Intikeramik Alamasri Industri Tbk |
| Platinum Ceramics Industry |
| Others |
Supply & Pricing Matrix
Continuous roller kiln scale economies at Gresik facilities compress unit costs per square meter while raising minimum efficient scale thresholds for new entrants. This concentration of installed capacity among legacy producers with captive gas contracts and clay mining licenses shapes price floors across Java's manufacturing belt, squeezing mid-scale competitors without backward integration into raw material reserves.
Pricing Analysis
SNI mandatory certification dictates the pricing tier structure across Indonesia's ceramic tiles market. Three-tier pricing separates premium large-format porcelain for Jakarta luxury towers from standard glazed volumes distributed through rural wholesale networks and economy-grade unglazed industrial flooring. Price differentiation rests on certification grade compliance costs and volume scale, with project-based direct sales commanding premiums over distributor channels. Pricing pressure stems from subsidized natural gas tariff rebalancing threatening kiln operating margins. Property developers in Surabaya and Bandung show lowest price sensitivity due to consolidated technical procurement teams, while smaller contractors across Central Java remain highly price-sensitive.
Supply Chain Analysis
Indonesia anchors ceramic tile production through East Java's Gresik cluster, with supplementary capacity in West Java's Bandung corridor and Central Java's Semarang district. The supply chain draws from captive clay reserves concentrated among legacy producers, imported glaze formulations for digital printing specialization, and pipeline natural gas feeding continuous roller kiln operations. Single-source vulnerability sits with subsidized gas supply contracts concentrated among integrated operators. Distribution runs through dual-channel structures: direct sales contracts with property developers in urban corridors and wholesale distributor networks penetrating rural contractor markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through centralized technical procurement teams at Jakarta and Surabaya property developers, consolidating formerly fragmented distributor-mediated purchasing into direct manufacturer negotiations. This shift compresses margin pools for channel-dependent suppliers while rewarding producers with project sales capabilities and batch consistency guarantees.
For Market Incumbents: Consolidate position through retrofitting continuous roller kilns for large-format slab production and securing long-term captive gas supply agreements ahead of tariff rebalancing. Threat from import-grade vitrified tile specifications in Jakarta's central business district demands certification investment to close quality perception gaps. Priority lever rests on direct developer contract penetration in Bandung and Surabaya to bypass distributor margin compression. For New Entrants and Emerging Players: Anchor in digital printing specialization for Bali-Lombok hospitality interiors, where customized glaze aesthetics command premium pricing and batch consistency requirements deter commodity competition. Most penetrable white-space sits in Surabaya's direct sales channel restructuring, where property developers bypass wholesale networks. Go-to-market angle emphasizes project-specific technical team engagement with performance warranty offerings. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among producers with direct developer contracts and captive clay-gas integration. Long-term viability across the projection horizon favors acquisition targets with installed scrubber systems compliant with tightening MEE air-quality benchmarks and existing SNI laboratory certification partnerships. Signal to watch is SNI glazing standard harmonization with ASEAN technical regulations enabling export pivot to Vietnam and Philippines markets.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Roller Kiln Retrofit | Large-format slab capability at Gresik facilities compresses energy consumption per square meter while raising scale thresholds. |
| Captive Clay Reserve Acquisition | Mining license control in East Java's manufacturing belt secures input cost stability against volatile imported material exposure. |
| Direct Developer Contract Expansion | Surabaya and Bandung property technical teams consolidate procurement away from distributor markups into single-source agreements. |
| Digital Printing Line Investment | Specialized inkjet capabilities capture hospitality margin pools across Bali and Lombok renovation cycles. |
| SNI Export Alignment Preparation | ASEAN technical regulation harmonization enables cross-border shipment qualification to Vietnam and Philippines construction markets. |
Research Methodology
Desk research of trade customs data, BIS-equivalent SNI certification records, and Ministry of Public Works green-building procurement disclosures preceded structured interviews with plant operations managers at Gresik cluster facilities, procurement leads at Jakarta property development firms, distributor network heads across Central Java, and technical directors specializing in digital printing glaze formulation. Primary fieldwork combined with secondary validation through continuous roller kiln technology assessments and captive gas contract analysis. Bottom-up production capacity modeling triangulated against top-down construction sector absorption estimates across the analysis window.
Variance decomposition across product type, end-user segment, distribution channel, and application dimensions structured the analytical framework. Modeled segmentation captured porcelain versus vitrified grade splits, residential-commercial-institutional demand patterns, direct sales versus distributor channel economics, and flooring-wall-outdoor installation specifications. CAGRs derived from production capacity expansion timelines against urban residential construction permit trajectories in Greater Jakarta and Surabaya. Industry-specific forecast inputs incorporated MEE emission compliance cost burdens and SNI certification renewal queue dynamics.
Decision-makers should treat outputs as directional under assumptions of sustained natural gas subsidy levels and stable SNI enforcement timelines; material deviation in either would warrant model refresh. Specific risk factors include abrupt tariff rebalancing, accelerated import-grade specification adoption in commercial high-rises, and clay reserve license revocation. Recalibration cycles align with material shifts in regulatory enforcement intensity and energy pricing policy.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Global Sandwich Panels Market
Building & Construction Materials
Door Hardware Market
Building & Construction Materials
Timber Floor Joist Market
Building & Construction Materials
Sandwich Panel System Market
Building & Construction Materials
Window Film Market
Building & Construction Materials
Construction Sustainable Materials Market
Building & Construction Materials
Asia-Pacific Gypsum Board Market
Building & Construction Materials
Ultra High Performance Concrete (UHPC) Market
Building & Construction Materials
Travertine Market
Building & Construction Materials
India Manufacturing Market
Building & Construction Materials
Roofing Liners Market
Building & Construction Materials
Sawn and Profiled Wood Products Market
Building & Construction Materials
Watertight Doors Market
Building & Construction Materials
Clay Roof Tiles Market
Building & Construction Materials
Seal Coat Market
Building & Construction Materials
Australia Industrial Insulation Market