
 Asia-Pacific Cross-Laminated Timber Market | 2026-2036
Asia-Pacific Cross-Laminated Timber Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Cross-Laminated Timber Market Insights
A capital-intensity divergence between automated CLT pressing lines and conventional batch curing is unwinding competitive tiers across the Asia-Pacific region. Stora Enso leverages its integrated Nordic-to-Pacific fiber supply chain to sustain volume commitments in Australian commercial projects. Sumitomo Forestry dominates Japan's precision-engineered segment through in-house glulam-to-CLT backward integration. XLam Australia Pty Ltd anchors Oceania demand with domestically certified manufacturing scale.
Cross-laminated timber consists of dimension lumber layers stacked perpendicular to adjacent plies and bonded with structural adhesives, typically achieving panel thicknesses from 50mm to 500mm for load-bearing wall, floor, and roof applications. The structural product category leads value capture due to engineering certification requirements in seismic zones, while acoustic-grade CLT is gaining fastest in mixed-use developments where code mandates inter-floor sound attenuation. Residential buildings consume the dominant application share, though educational institutions represent a concentrated margin pool driven by government timber-first procurement mandates.
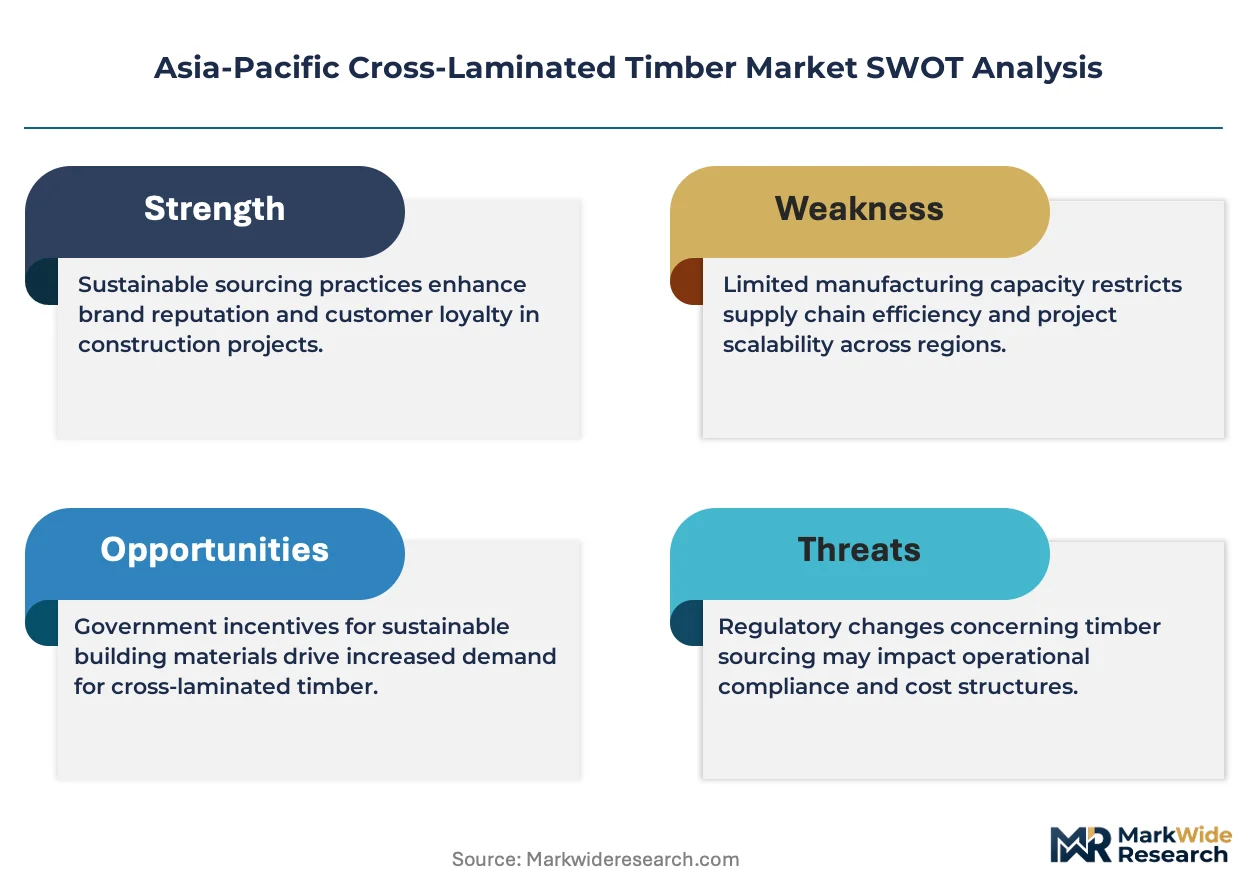
Japan's Ministry of Land, Infrastructure, Transport and Tourism (MLIT) enforces the Building Standards Act, which governs fire resistance ratings and height exemptions for combustible materials, directly governing CLT building envelopes. Australia's National Construction Code, administered by the Australian Building Codes Board, mandates structural performance standards that imported European CLT must meet through local equivalency certification. New Zealand's Building Act, overseen by the Ministry of Business, Innovation and Employment, incorporates specific engineered timber provisions post-Christchurch seismic revisions. Stakeholders must monitor evolving fire engineering pathways and adhesive emission thresholds as these determine which suppliers retain specification access across jurisdictions.
Market Dynamics
Japan's 2024 Building Standards Act amendments permitting 11-story timber structures are compressing project feasibility timelines and redirecting capital from steel-concrete hybrid systems toward mass timber envelopes across the Asia-Pacific region.
Growth Catalysts
- Seismic retrofit mandates:New Zealand's post-Christchurch Building Act revisions require engineered timber in public building upgrades, creating specification pull for CLT shear walls and diaphragm systems.
- Urban infill density targets:Australian state planning instruments in Victoria and New South Wales fast-track approval for mid-rise timber residential towers, reducing holding costs for developers.
- Mass timber fire engineering pathways:Performance-based fire resistance assessment methods are replacing prescriptive char-rate tables, expanding allowable building heights for combustible construction.
Market Restraints
- Phenol-resorcinol-formaldehyde cost volatility:Adhesive input prices fluctuate with petrochemical feedstock indices, compressing margins for non-integrated CLT manufacturers.
- Nordic fiber supply concentration:European spruce and pine log availability constraints create volume-commitment risk for Asia-Pacific projects requiring imported lamstock.
- Cross-laminated timber-steel hybrid substitution:Post-tensioned concrete slab systems retain cost advantage above eight stories in Australian commercial developments.
Strategic Opportunities
- Philippines green building incentives:The country's BERDE certification system awards density bonuses for biogenic material content, opening specification access for imported CLT in Metro Manila mixed-use towers.
- Acoustic-grade CLT in healthcare:Inter-floor sound attenuation requirements in Australian aged-care facilities create premium pricing for cross-laminated timber with integrated resilient layers.
- Hybrid CLT-glulam manufacturing convergence:Combined pressing lines serving both product categories improve capacity utilization across project-type demand cycles.
Industry Challenges
- Mass timber fire safety engineering talent scarcity:Qualified structural fire engineers capable of performance-based char modeling remain concentrated in Australia and Japan, creating project bottleneck risk in emerging markets.
- Multi-jurisdiction certification complexity:Australian Building Codes Board equivalency assessments for European-manufactured CLT extend lead times by 4-6 months versus domestic-certified supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Cross-Laminated Timber Market |
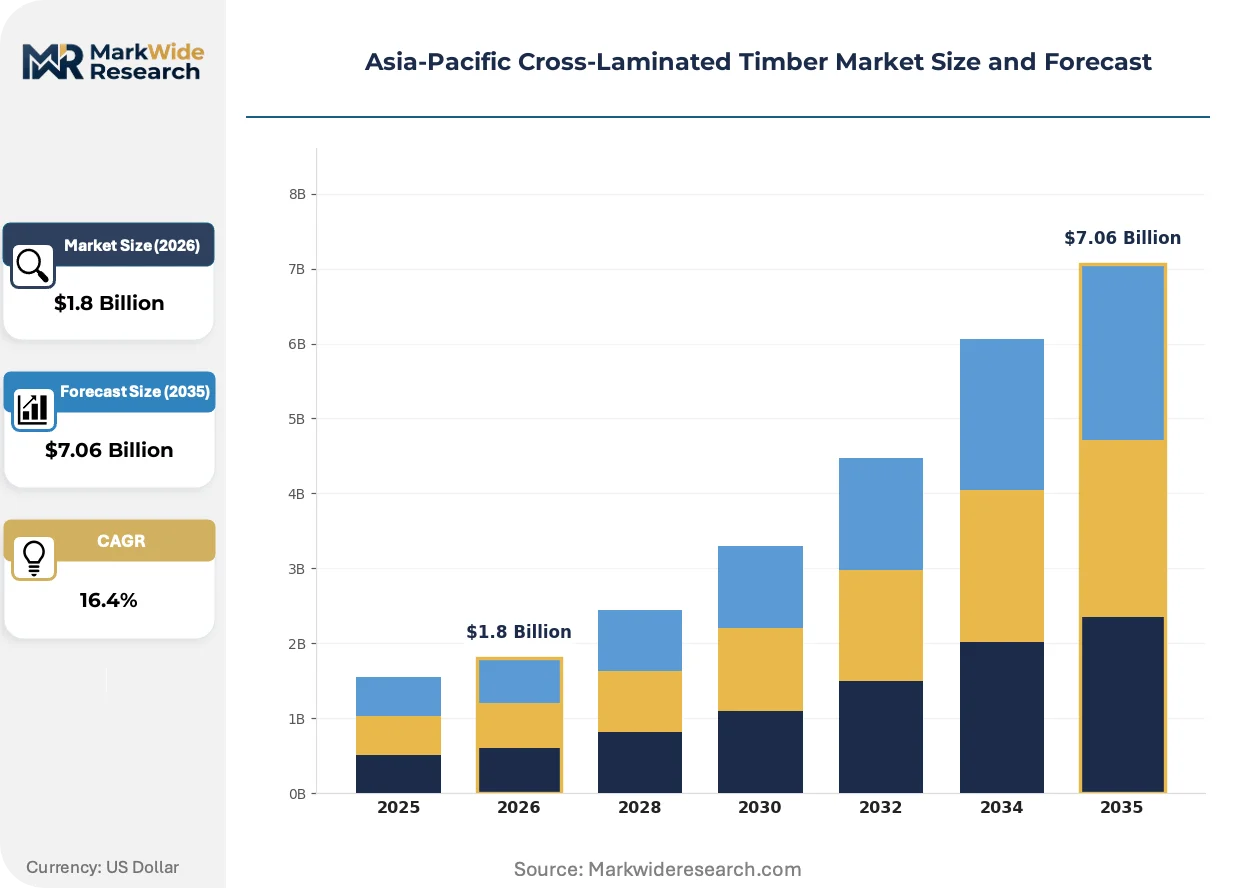
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Structural, Non-Structural, Decorative, Acoustic Application: Residential Buildings, Commercial Spaces, Educational Institutions, Industrial Facilities End User: Architects, Contractors, Developers, Builders Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Timberlink Australia & New Zealand, SEIHOKU CORPORATION, Stora Enso, AGROP NOVA a.s., XLam Australia Pty Ltd, HASSLACHER Holding GmbH, Holmen, Sumitomo Forestry, KLH Massivholz GmbH, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Cross-Laminated Timber Market Trends and Innovations
Digital fabrication workflows and adhesive chemistry advances are compressing production cycles while expanding the performance envelope of cross-laminated timber in high-load and high-moisture applications across the Asia-Pacific region.
Computer-numerical-controlled five-axis routing integrated with BIM-to-fabrication data pipelines is displacing manual panel cutting and field modification in Australian multi-story residential projects. Melbourne and Sydney developers specify CNC-processed CLT floor cassettes with pre-integrated MEP penetrations to compress on-site assembly schedules. This precision is displacing traditional platform framing in mid-rise infill corridors where labor rates and site constraints favor prefabricated timber systems.
Australia's National Construction Code 2025 preview documents propose expanded fire resistance rating pathways for exposed timber surfaces in commercial occupancies, directly affecting specification decisions for office and retail envelopes. The Australian Building Codes Board consultation process signals alignment with European char-rate engineering methods, reducing reliance on encapsulation requirements. Queensland and Western Australian projects are pre-positioning for these provisions through early-adopter performance-based designs with fire engineering peer review.
Timber-first procurement mandates in Australian state education departments are consolidating demand around pre-qualified CLT suppliers with established local equivalency certification. New South Wales and Victorian school infrastructure programs now require mass timber primary structure for projects above specified value thresholds, bypassing conventional competitive tender processes for steel and concrete alternatives. This specification lock-in is most visible in Melbourne's inner-north education precinct and Sydney's growth-area primary school rollout.
Asia-Pacific Cross-Laminated Timber Market Segmentation
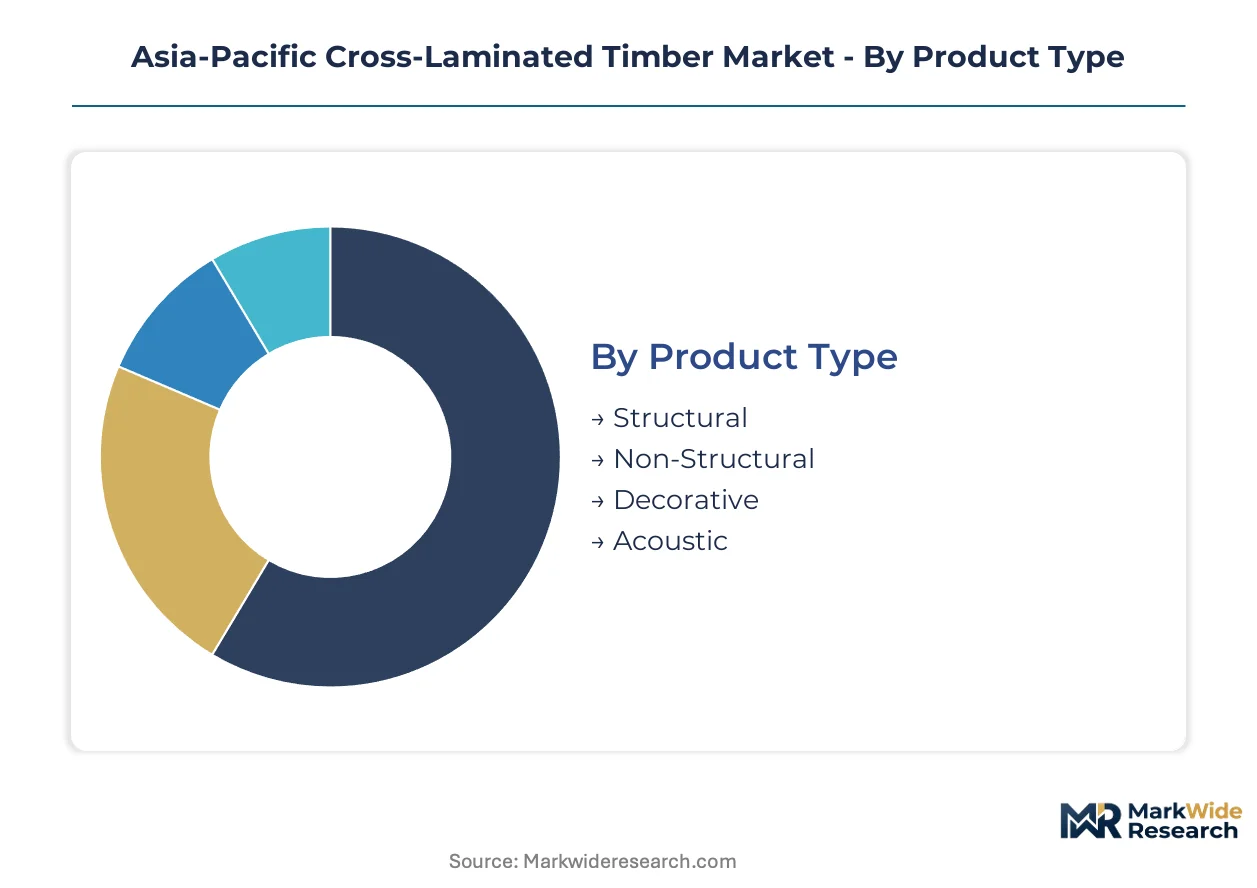
Cross-laminated timber flows through distinct specification channels where product certification, project scale, and procurement authority determine which segments capture margin. Channel alignment with end-user decision-making power separates volume leaders from value concentrators across Japan, Australia, and New Zealand construction markets.
Product Type:
Structural-grade CLT moves primarily through direct sales to project engineers requiring seismic certification, while acoustic and decorative grades route through distributors serving renovation contractors and interior specialists.
- Structural:Engineered for load-bearing wall, floor, and roof applications with perpendicular lamination achieving 50mm to 500mm thicknesses. Japan's MLIT-certified projects in Tokyo and Osaka specify structural CLT for 11-story envelopes under amended Building Standards Act provisions. By volume, structural leads. By growth pace, acoustic is ahead.
- Acoustic:Integrates resilient interlayers for inter-floor sound attenuation in mixed-use developments. Australian aged-care facilities in Melbourne and Sydney specify acoustic-grade CLT where National Construction Code mandates exceed standard performance thresholds.
- Non-Structural:Used for partition walls and secondary framing where engineering certification is not required. Australian urban infill projects specify non-structural CLT for speed of assembly.
- Decorative:Exposed timber surfaces for aesthetic applications in commercial interiors. New Zealand hospitality projects specify decorative CLT for biogenic material visibility.
Structural-grade pricing correlates with seismic certification tier, while acoustic and decorative grades command premiums based on finish quality and integrated performance layers.
Application:
Cost tier separation is pronounced: residential and educational projects optimize for standardized panel dimensions, while commercial and industrial applications absorb customization costs for fire-engineered envelopes.
- Residential Buildings:Mid-rise towers in Australian urban infill corridors specify CLT floor cassettes with pre-integrated MEP penetrations. Victorian and New South Wales state planning instruments fast-track approval for timber residential structures above four stories.
- Educational Institutions:Australian state education departments mandate mass timber primary structure for projects above specified value thresholds. New South Wales and Victorian school infrastructure programs bypass competitive tender for steel and concrete alternatives.
- Commercial Spaces:Office and retail envelopes in Australian CBDs specify exposed timber surfaces where National Construction Code 2025 preview documents expand fire resistance pathways.
- Industrial Facilities:Warehouse and logistics structures in New Zealand specify CLT for speed of erection and seismic performance post-Christchurch Building Act revisions.
Educational procurement mandates concentrate demand around pre-qualified suppliers, while residential volume spreads across competing certification pathways.
End User:
Customer type determines specification authority: architects control early-stage material selection, while contractors and developers dominate value engineering and procurement execution phases.
- Developers:Control material selection in Australian urban infill projects where holding cost reduction drives prefabricated timber system adoption. Melbourne and Sydney mid-rise towers specify CLT to compress construction schedules.
- Architects:Specify exposed timber surfaces and biogenic material content in New Zealand commercial projects where BERDE-equivalent sustainability metrics influence design awards and tenant attraction.
- Contractors:Execute procurement for Japanese multi-story residential projects where MLIT certification requirements constrain supplier pools to pre-approved manufacturers.
- Builders:Engage CLT for single-story and low-rise residential construction in Australian regional markets where distributor availability determines specification access.
Developer-led projects concentrate volume in standardized structural grades, while architect-driven commercial work generates premium demand for aesthetic and acoustic performance tiers.
Distribution Channel:
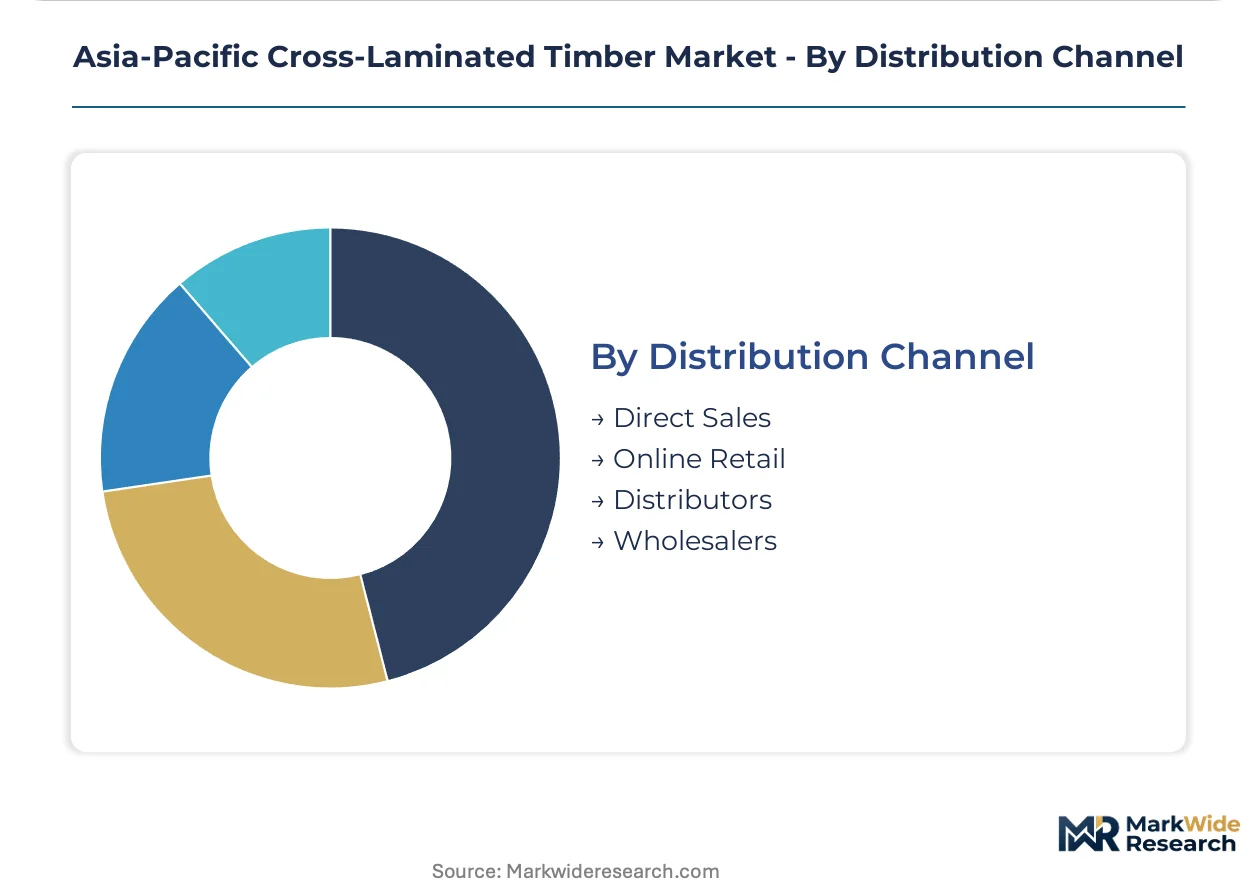
Supply concentration varies by channel: direct sales tie to large-project volume commitments, while distributor networks fragment procurement across smaller contractors and regional builders.
- Direct Sales:Large Australian commercial developers and Japanese general contractors negotiate volume commitments with manufacturers for multi-story projects. Stora Enso and Sumitomo Forestry sustain direct relationships for certified structural supply.
- Distributors:Serve Australian regional builders and New Zealand contractors where project scale does not justify manufacturer-direct procurement. XLam Australia anchors distributor availability through domestic certification scale.
- Wholesalers:Aggregate demand from smaller contractors in Australian secondary cities where CLT specification is emerging but not yet standardized.
- Online Retail:Facilitates specification of non-structural and decorative grades for renovation contractors and interior specialists seeking rapid procurement.
Direct sales capture the majority of structural-grade value, while distributor and wholesale channels expand geographic penetration for emerging specification segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Australian urban infill corridors show the highest price elasticity, compressing margins for standardized structural grades, while Japanese developers absorb premiums for MLIT-certified seismic performance. New Zealand's post-Christchurch reconstruction programs prioritize engineering certification over cost minimization. Philippine green building incentives create emerging demand at mid-tier price points.
Japan
Multi-story residential towers in Tokyo and Osaka drive specification volume as amended Building Standards Act provisions permit 11-story timber structures. MLIT certification requirements constrain supplier pools to pre-approved manufacturers, elevating procurement costs. The Kanto region concentrates project activity where general contractors negotiate direct volume commitments with integrated forestry-to-CLT producers.
Australia
State planning instruments in Victoria and New South Wales fast-track approval for mid-rise timber residential above four stories, reducing developer holding costs. The Australian Building Codes Board mandates structural performance standards that imported European CLT must meet through local equivalency certification. Melbourne and Sydney anchor demand for CNC-processed floor cassettes with pre-integrated MEP penetrations.
New Zealand
Post-Christchurch Building Act revisions require engineered timber in public building upgrades, creating specification pull for CLT shear walls. Seismic retrofit programs concentrate demand in Wellington and Christchurch where diaphragm systems replace legacy concrete frames. The Ministry of Business, Innovation and Employment oversees specific engineered timber provisions that govern commercial envelope design.
Philippines
BERDE certification awards density bonuses for biogenic material content, opening specification access for imported CLT in Metro Manila mixed-use towers. Green building incentives attract foreign manufacturers seeking volume commitments outside saturated Australian and Japanese markets. Quezon City and Makati CBD developments represent the primary concentration of early-adopter projects.
Asia-Pacific Cross-Laminated Timber Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Asia-Pacific CLT market. Nordic integrated forestry groups sustain volume commitments through captive fiber supply chains, while Japanese precision-engineered specialists dominate seismic certification tiers. The market structure fragments across three strategic archetypes: backward-integrated timber multinationals, domestic-certified regional fabricators, and adhesive-chemistry-integrated specialists. Capacity expansion and certification pathway investments constitute the dominant competitive moves as manufacturers pre-position for Australian Building Codes Board equivalency reforms.
Among Asia-Pacific-based specialists, XLam Australia Pty Ltd occupies a position within the domestic-certified regional fabricator tier, exemplifying scale-driven manufacturing proximity to Australian urban infill corridors. Sumitomo Forestry represents the backward-integrated archetype, anchoring Japan's precision-engineered segment through in-house glulam-to-CLT production control. Stora Enso sits within the Nordic-originated multinational group, leveraging integrated fiber supply chains to sustain project commitments across Australian commercial developments. These three exemplify how geographic origin and integration depth determine specification access across divergent national regulatory frameworks.
| Leading Market Players |
|---|
| Timberlink Australia & New Zealand |
| SEIHOKU CORPORATION |
| Stora Enso |
| AGROP NOVA a.s. |
| XLam Australia Pty Ltd |
| HASSLACHER Holding GmbH |
| Holmen |
| Sumitomo Forestry |
| KLH Massivholz GmbH |
| Others |
Pricing and Supply Chain Analysis
Australia's Building Codes Board equivalency certification gates both supplier qualification and price differentiation simultaneously, compressing procurement timelines for domestic-certified manufacturers while extending lead times and elevating landed costs for European imports seeking specification access.
Pricing Analysis
After-sales engineering support and extended warranty coverage drive lifetime value in structural-grade CLT procurement. Three-tier pricing structure across premium, standard, and economy levels separates MLIT-certified seismic performance from acoustic-grade mixed-use specifications and non-structural partition applications. Cost compression in standard structural grades is intensifying because Australian developers optimize for holding cost reduction in urban infill corridors. Residential developers in Melbourne and Sydney show highest price sensitivity, while Japanese general contractors absorb premiums for precision-engineered seismic certification.
Supply Chain Analysis
Nordic spruce and pine log availability through Baltic Sea ports underwrites volume commitments for Asia-Pacific commercial projects requiring imported lamstock. Manufacturing concentrates in Austria, Germany, and Finland for European supply, with emerging scale in Japan and Australia for regional certification compliance. Adhesive chemistry inputs draw from petrochemical feedstock indices in Northeast Asia and the Middle East. Single-source vulnerability in phenol-resorcinol-formaldehyde supply creates margin compression risk for non-integrated manufacturers. Distribution runs through direct sales for large-project volume commitments and distributor networks for regional builder access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's amended Building Standards Act permitting 11-story timber structures constitutes a regulatory inflection accelerating mass timber disruption across residential construction, compressing project feasibility timelines and redirecting capital from conventional steel-concrete hybrid systems.
For Market Incumbents: Secure captive fiber supply through long-term Nordic log commitments or domestic plantation partnerships to defend against European import volume-commitment risk. Invest in automated pressing line capacity to compress production cycles and sustain margin position against emerging regional fabricators in Australia and New Zealand. Certification pathway diversification across Australian Building Codes Board, Japan's MLIT, and New Zealand's Ministry of Business, Innovation and Employment specifications reduces single-jurisdiction dependency. For New Entrants and Emerging Players: Differentiate on acoustic-grade CLT with integrated resilient interlayers for Australian aged-care and healthcare verticals where code-mandated sound attenuation creates premium pricing power. Target Philippine green building incentives under BERDE certification for Metro Manila mixed-use towers where density bonuses for biogenic material content reduce effective procurement cost. Pursue hybrid CLT-glulam manufacturing convergence to improve capacity utilization across project-type demand cycles. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across automated pressing line deployments, enabling mid-scale regional fabricators to achieve viable unit economics. Five-to-ten year viability favors manufacturers with backward integration into glulam production or captive forestry assets. Acquisition target archetype: domestic-certified regional fabricators with established Australian Building Codes Board equivalency and CNC fabrication capabilities. Monitor adhesive chemistry patent filings and fire engineering talent migration as inflection indicators for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Glulam Production | Sumitomo Forestry's in-house glulam-to-CLT control anchors Japan's precision-engineered seismic certification tier. |
| Automated Pressing Line Deployment | Stora Enso's Nordic-to-Pacific fiber supply chain sustains volume commitments in Australian commercial developments. |
| Multi-Jurisdiction Certification Investment | XLam Australia's domestic certification scale anchors distributor availability across Oceania demand corridors. |
| Hybrid CLT-Glulam Manufacturing Convergence | Combined pressing lines serving both product categories improve capacity utilization across project-type demand cycles. |
| Fire Engineering Pathway Pre-Positioning | Queensland and Western Australian projects adopt performance-based designs ahead of National Construction Code 2025 provisions. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with CLT manufacturers, structural engineers, fire safety consultants, and procurement directors at Australian and Japanese general contractors; and secondary validation through building code submission databases, timber certification registries, and customs trade records for lamstock imports. The research combined bottom-up project pipeline tracking across Melbourne, Sydney, Tokyo, and Osaka construction markets with top-down triangulation against regional forestry production statistics and adhesive chemistry trade flows.
Across the analysis window, the forecasting framework modeled volume and value outputs through segmentation across product type, application, end user, and distribution channel dimensions. CAGRs were derived from project pipeline velocity, regulatory amendment timelines, and capacity expansion announcements. Industry-specific forecast inputs included seismic retrofit program budgets in New Zealand, Australian state education department procurement thresholds, and Japanese Ministry of Land, Infrastructure, Transport and Tourism certification queue data.
Material uncertainties — adhesive feedstock price volatility, Nordic log availability constraints, and fire engineering talent scarcity — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory alignment between Australian Building Codes Board and European char-rate engineering methods. Practitioners should keep alternative scenarios live as Philippine BERDE incentive durability and Japanese Building Standards Act enforcement consistency evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Building Vibration Isolation Market
Building & Construction Materials
Plastic Formwork Market
Building & Construction Materials
Russia Cross Laminated Timber Market
Building & Construction Materials
Insulating Glass Window Market
Building & Construction Materials
Ultra High Performance Concrete (UHPC) Market
Building & Construction Materials
Vitrified Tiles Market
Building & Construction Materials
UPVC Doors and Windows Market
Building & Construction Materials
Hydraulic Binder Market
Building & Construction Materials
North America Balustrade Market
Building & Construction Materials
US Prefabricated Steel Market
Building & Construction Materials
Concrete Densifier Market
Building & Construction Materials
Asia-Pacific Ceramic Sanitary Ware Market
Building & Construction Materials
India Manufacturing Market
Building & Construction Materials
Barn Door Hardware Market
Building & Construction Materials
Warm Mix Asphalt Market
Building & Construction Materials
US Parking Deck Coatings Market