
 Canada Facade Market | 2026-2036
Canada Facade Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Facade Market Outlook
Aluminum composite panel systems is consolidating share against traditional masonry in mid-rise commercial construction across Ontario and Quebec. Saint-Gobain Corporation leverages its integrated glass and insulation portfolio to capture specification-driven projects in Toronto's downtown core. Flynn Group of Companies sustains national installation coverage through coast-to-coast service infrastructure. Kawneer Company Inc anchors its position in curtain wall engineering for institutional clients requiring thermal break performance.
A facade constitutes the exterior envelope system of a building, integrating cladding, glazing, insulation layers, and weatherproofing membranes to manage thermal transfer, air infiltration, and structural loads while enabling daylight penetration. Manufacturing processes encompass unitized curtain wall prefabrication, stick-built aluminum framing, and insulated metal panel lamination, with performance measured by U-value ratings and air leakage coefficients. Glass dominates specification in commercial high-rises where solar heat gain coefficient optimization drives material selection, while aluminum framing leads renovation activity due to retrofit compatibility. Pre-fabricated installation methods are gaining traction as labor scarcity on Canadian job sites accelerates demand for factory-assembled envelope modules that reduce field installation hours.
Health Canada and the National Research Council Canada enforce National Building Code compliance for fire resistance and thermal performance in facade assemblies, while provincial authorities such as Ontario's Ministry of Municipal Affairs and Housing administer local energy efficiency standards that exceed federal baselines. The British Columbia Energy Step Code creates a phased regulatory ladder that pushes facade U-values lower with each tier adoption, compelling manufacturers to recalibrate insulation configurations. Stakeholders must monitor whether the proposed 2025 National Building Code tiered energy standard achieves provincial adoption momentum, as uneven regulatory uptake would fragment specification requirements across Canadian construction markets.
Market Dynamics
The National Building Code's tiered energy standard is compressing specification timelines across Canadian provinces, forcing facade manufacturers to recalibrate insulation configurations before provincial adoption deadlines create fragmented compliance requirements.
Growth Catalysts
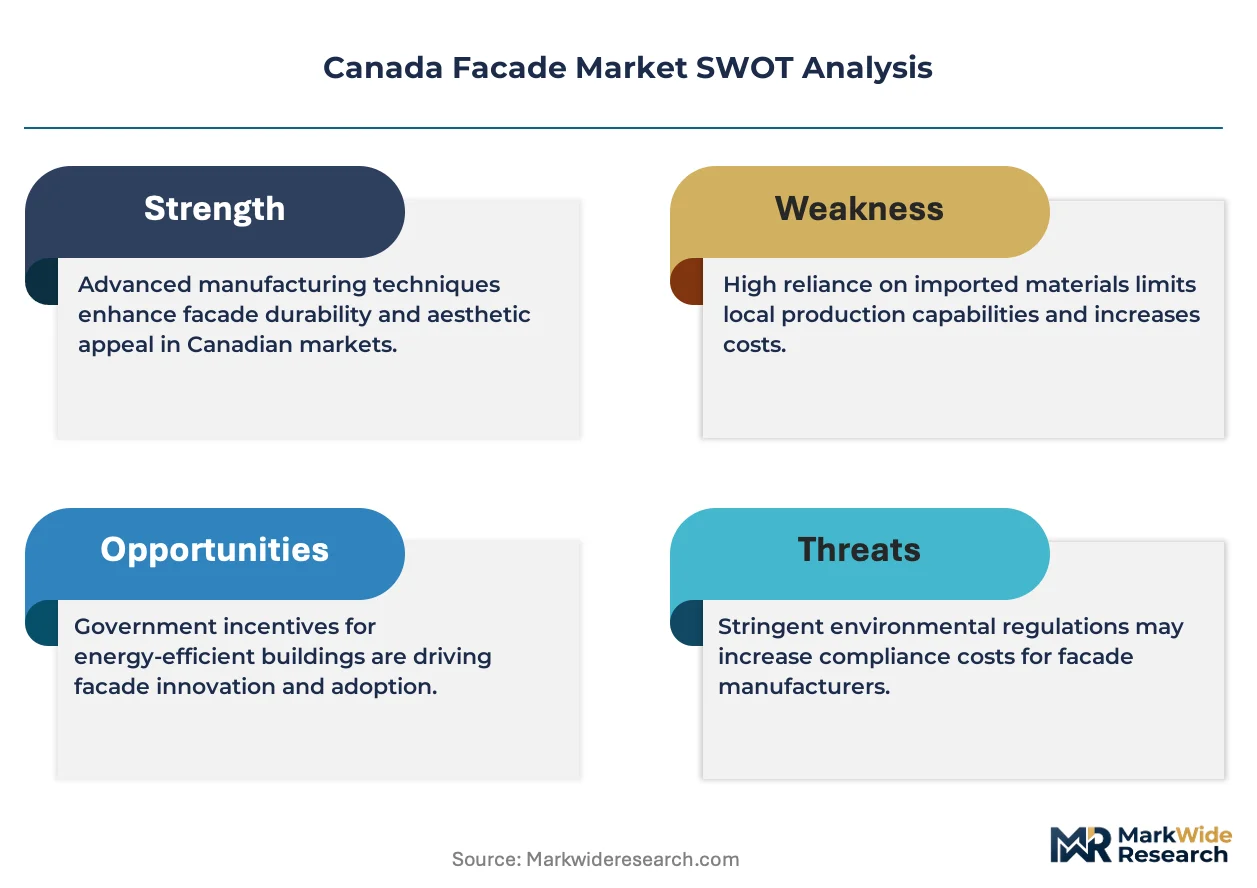
- British Columbia Energy Step Code:The phased regulatory ladder mandates progressively lower U-values, compelling developers in Vancouver to specify high-performance curtain wall systems ahead of Tier 5 deadlines.
- Toronto high-rise residential:Tower developers pursuing LEED Gold certification are specifying triple-glazed unitized systems to meet thermal performance targets while maximizing rentable floor area.
- Prefabrication methods:Factory-assembled envelope modules are reducing field installation hours as labor scarcity on Ontario job sites accelerates adoption of panelized cladding systems.
Market Restraints
- Aluminum price volatility:Input cost swings for extruded framing components are compressing margins for curtain wall fabricators serving mid-rise commercial segments.
- Quebec supply concentration:Insulated metal panel production clusters in Greater Montreal create geographic vulnerability for Western Canada projects requiring long-haul logistics.
- Fire resistance testing backlog:National Research Council Canada certification queues for combustible cladding alternatives are extending project timelines by six to nine months.
Strategic Opportunities
- Alberta institutional retrofit:Calgary and Edmonton school boards are bundling envelope upgrades with HVAC replacements, creating specification entry points for integrated facade-MECH contractors.
- Mass timber hybrid construction:Cross-laminated timber commercial buildings in Vancouver require specialized curtain wall interfaces that conventional aluminum systems cannot accommodate without engineering modification.
- Federal Greener Homes Initiative:Deep retrofit subsidies for multi-unit residential buildings are unlocking demand for high-performance window wall replacements in 1970s rental stock.
Industry Challenges
- Certified installer scarcity:Unitized curtain wall erection demands specialized rigging crews that Toronto-area contractors struggle to field at scale.
- Legacy building interface complexity:Renovation projects in Montreal's concrete-frame housing stock require custom-engineered anchoring systems that delay fabrication schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Facade Market |
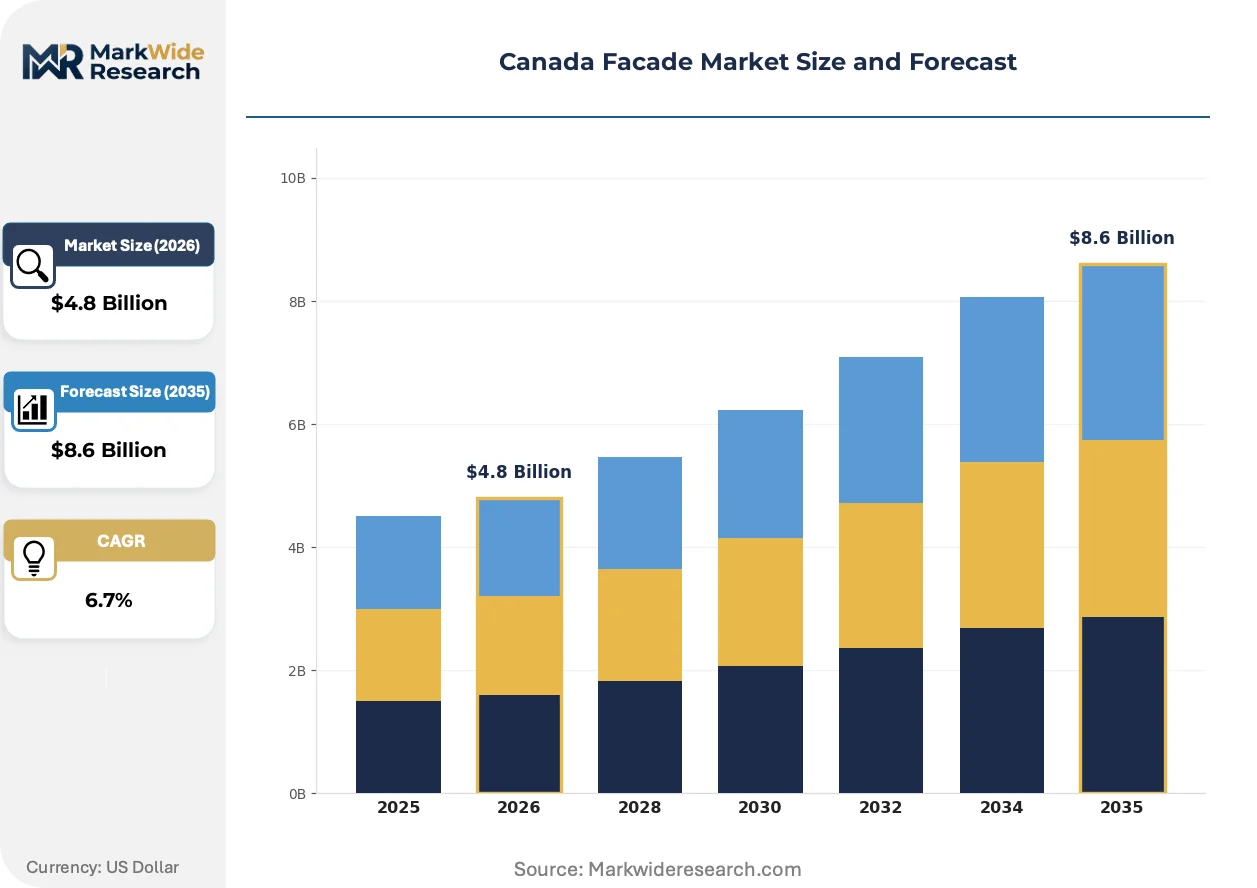
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Aluminum, Glass, Stainless Steel, Wood Application Type: Commercial, Residential, Institutional, Industrial Design Style: Modern, Traditional, Minimalist, Eclectic Installation Type: Renovation, New Construction, Pre-Fabricated, Custom |
| Companies Covered | Saint-Gobain Corporation, AGC Glass North America, Flynn Group of Companies, Enclos Corp., Permasteelisa North America, YKK AP Inc, Kawneer Company Inc, Schuco International KG, Norsk Hydro ASA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Facade Market Strategic Shifts
Digital fabrication and performance modeling are compressing the traditional design-bid-build envelope for Canadian facade projects, enabling earlier manufacturer involvement in schematic design phases.
Unitized curtain wall systems with integrated photovoltaic glazing are modularizing the relationship between envelope and energy generation, allowing Toronto office developers to meet Toronto Green Standard Tier 2 requirements without rooftop solar constraints. Institutional clients in Ottawa are specifying these systems for net-zero-ready buildings. The technology is modularizing how mechanical engineers size HVAC loads, reducing equipment tonnage by fifteen to twenty percent in pilot projects.
The proposed 2025 National Building Code tiered energy standard is creating compliance uncertainty as provinces signal divergent adoption timelines, fragmenting specification requirements across Ontario, British Columbia, and Alberta markets. Manufacturers are maintaining parallel product lines to serve jurisdictions at different code tiers simultaneously. Quebec's Ministry of Municipal Affairs has indicated conditional adoption contingent on federal funding, delaying investment decisions for Montreal-area fabricators.
Developer procurement for Vancouver rental towers is consolidating around design-assist contracts that transfer performance risk to envelope subcontractors earlier in project timelines. General contractors are accepting lump-sum guarantees on air leakage targets that were previously owner-retained risks. This pattern is most visible in Burnaby and Surrey high-rise clusters where CMHC financing incentives reward accelerated project delivery.
Canada Facade Market Segmentation
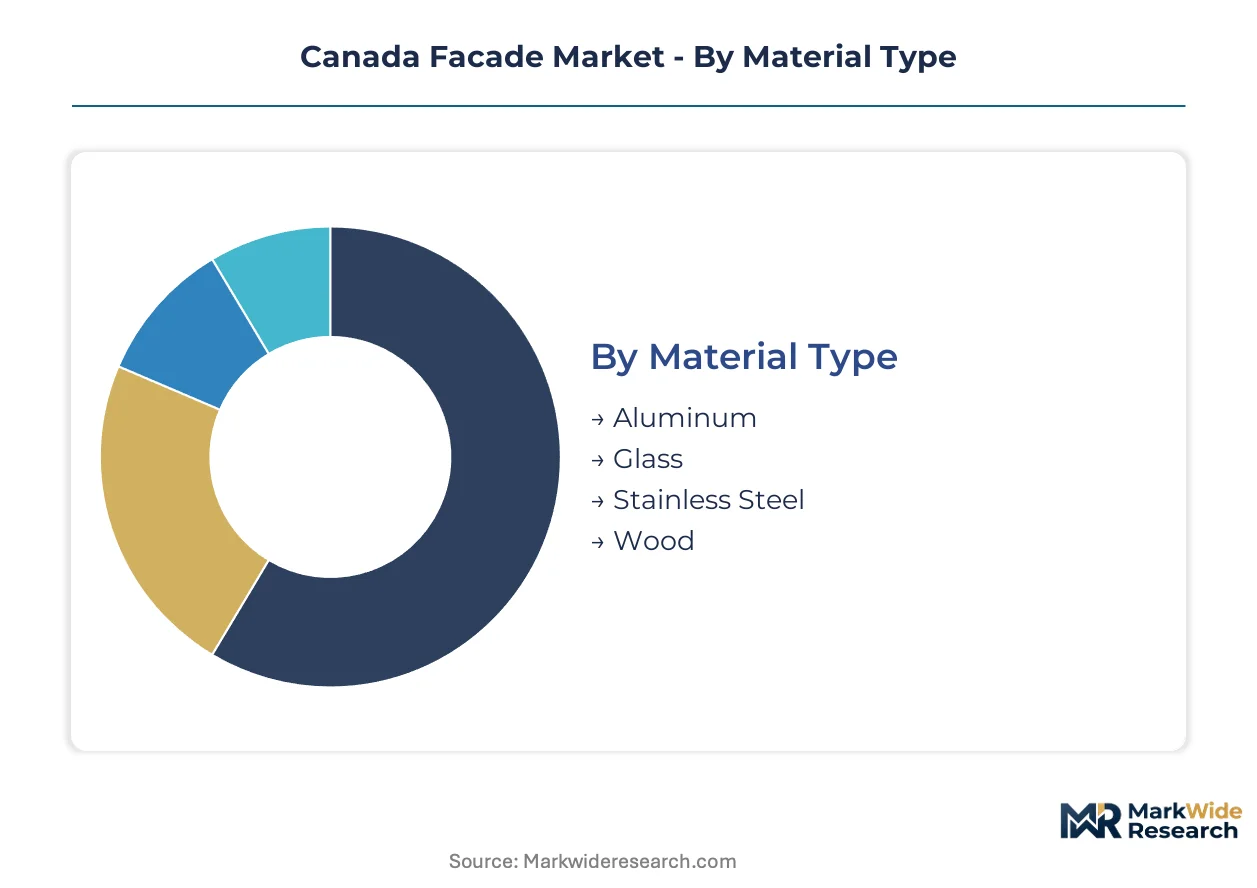
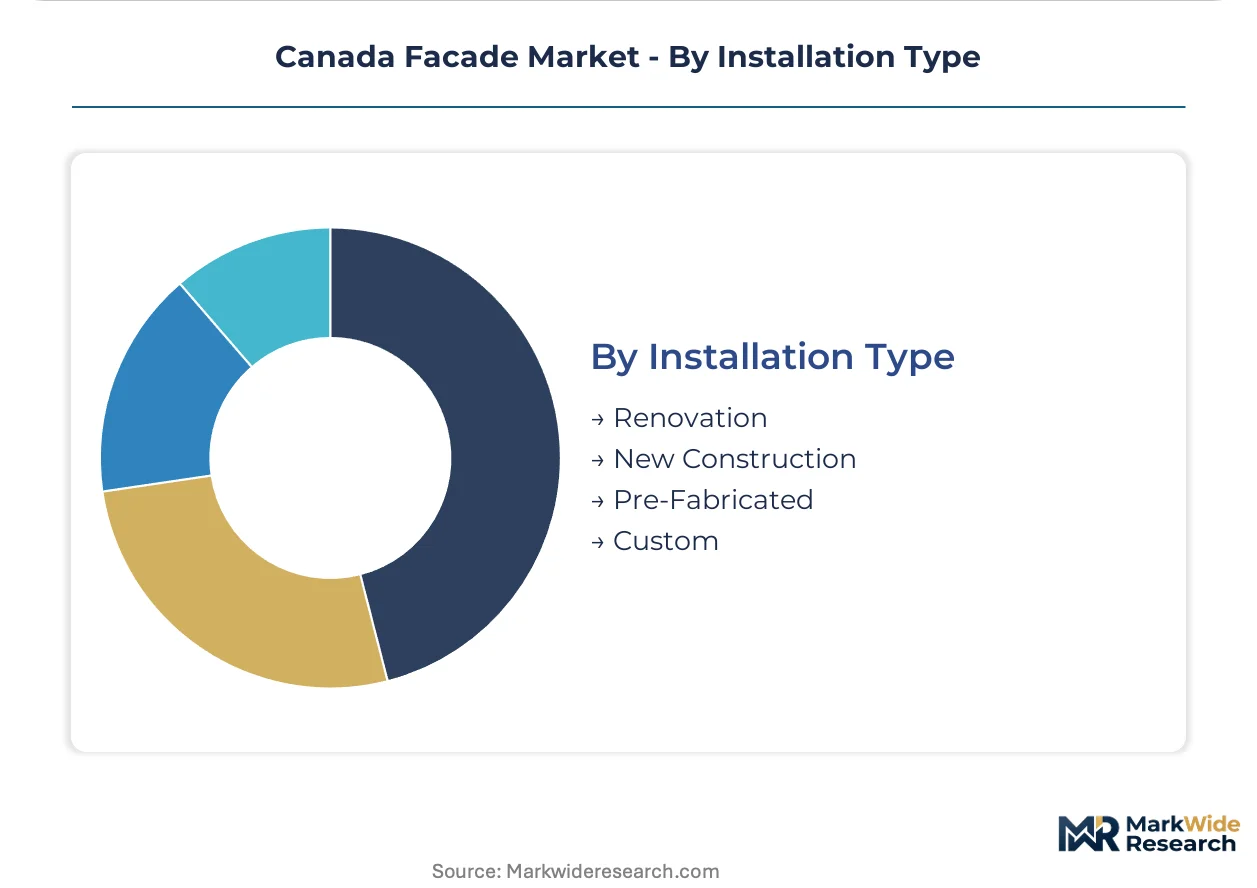
Material selection and installation methodology determine thermal performance compliance and project economics across Canadian facade procurement. Specification patterns diverge sharply between new high-rise construction and retrofit activity, with regulatory tiers forcing recalibration of segment priorities.
Material Type:
Specification decisions pivot on thermal break engineering and U-value ratings as provincial energy codes tighten.
- Aluminum:Extruded framing systems with polyamide thermal breaks dominate curtain wall assemblies for Toronto and Vancouver high-rises. British Columbia Energy Step Code Tier 4 mandates are accelerating demand for thermally improved profiles in Burnaby rental towers.
- Glass:Triple-glazed units with low-emissivity coatings command specification in LEED-targeted office developments. Solar heat gain coefficient optimization drives selection for west-facing elevations in Calgary's downtown core.
- Stainless Steel:Cladding panels and structural support elements serve institutional clients requiring extended service life. Ottawa federal buildings specify grade 316 alloys for coastal exposure resistance.
- Wood:Cross-laminated timber interfaces and accent panels integrate with mass timber structural systems. Vancouver commercial projects employ engineered wood for biophilic design compliance.
Aluminum leads on scale; glass leads on momentum.
Application Type:
End-use verticals exhibit divergent procurement timelines and performance risk tolerances.
- Commercial:Office and retail developments in Toronto's PATH network prioritize unitized curtain wall systems for accelerated envelope closure. Developer procurement consolidates around design-assist contracts with air leakage guarantees.
- Residential:High-rise rental towers in Vancouver and Montreal drive volume for window wall systems. CMHC financing incentives reward projects achieving Tier 3 energy performance or higher.
- Institutional:School boards and healthcare authorities in Alberta bundle envelope upgrades with mechanical replacements. Calgary and Edmonton projects specify integrated facade-MECH packages.
- Industrial:Warehouse and logistics facilities in Ontario's Golden Horseshoe employ insulated metal panels for rapid enclosure. Cost-driven procurement favors single-source panel and installation contracts.
Commercial commands specification value; residential expands most quickly.
Design Style:
Aesthetic positioning intersects with thermal performance engineering in urban core developments.
- Modern:Flush glazing and minimal sightline aluminum framing dominate Toronto financial district towers. Specification demands integrated photovoltaic compatibility for Toronto Green Standard compliance.
- Traditional:Masonry-veneer systems with aluminum backup persist in Ottawa government and institutional projects. Heritage district overlays in Montreal constrain material substitution.
- Minimalist:Panelized cladding with concealed fasteners serves Vancouver luxury residential. Burnaby high-rises specify large-format porcelain for reduced joint maintenance.
- Eclectic:Mixed-material assemblies combine metal, glass, and wood elements for distinctive architectural identity. Toronto mid-rise commercial projects employ this approach for rental differentiation.
Modern dominates specification frequency; minimalist gains share fastest.
Installation Type:
Project delivery methodology determines labor exposure and schedule risk allocation.
- Renovation:Window wall replacement in 1970s multi-unit residential stock accelerates under Federal Greener Homes Initiative subsidies. Montreal concrete-frame buildings require custom anchoring engineering.
- New Construction:Stick-built and unitized curtain wall erection serves high-rise ground-up development. Toronto contractors face certified installer scarcity for complex rigging operations.
- Pre-Fabricated:Factory-assembled envelope modules reduce field hours as Ontario labor scarcity intensifies. Panelized systems gain traction in Edmonton institutional projects.
- Custom:Bespoke engineered solutions address mass timber hybrid interfaces and heritage constraints. Vancouver cross-laminated timber commercial buildings demand specialized curtain wall adaptation.
New construction maintains volume leadership; pre-fabricated climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ontario's Golden Horseshoe corridor concentrates the bulk of Canadian facade demand, driven by Toronto's high-rise residential tower pipeline and institutional procurement in Ottawa. Provincial energy codes and federal retrofit incentives are redistributing activity across Canada's five major economic regions.
Ontario
Toronto's PATH network and downtown office core sustain specification volume for unitized curtain wall systems. The Ontario Ministry of Municipal Affairs and Housing administers energy efficiency standards that exceed federal baselines. Kitchener-Waterloo fabrication clusters supply panelized cladding to projects across the Golden Horseshoe.
British Columbia
Vancouver rental tower developers pursue LEED Gold certification through triple-glazed envelope specifications. The British Columbia Energy Step Code mandates progressively lower U-values through Tier 5 adoption. Burnaby and Surrey high-rise clusters consolidate procurement around design-assist contracts with air leakage guarantees.
Quebec
Montreal's concrete-frame housing stock drives renovation demand for custom-engineered window wall replacements. Heritage district overlays constrain material substitution in the urban core. Greater Montreal production clusters manufacture insulated metal panels for distribution across Eastern Canada.
Alberta
Calgary and Edmonton school boards bundle envelope upgrades with HVAC replacements, creating integrated procurement packages. Provincial institutional retrofit programs accelerate specification timelines for facade-MECH contractors. Edmonton projects increasingly specify pre-fabricated envelope modules to offset labor scarcity.
Atlantic Canada
Halifax commercial development and federal government buildings in Ottawa generate steady demand for high-performance glazing. Federal Greener Homes Initiative subsidies unlock deep retrofit activity in 1970s multi-unit residential stock. Local contractors face extended logistics chains for specialized curtain wall components.
Canada Facade Market Competitive Environment
Capacity expansion dominates the current landscape as fabricators scale prefabrication capabilities to serve labor-constrained job sites. The vendor base exhibits moderate consolidation, with national installation networks competing against regional specialists for specification control. Three archetypes define competitive positioning: integrated material-installation conglomerates, engineering-focused curtain wall specialists, and regional prefabrication contractors. M&A activity and vertical integration into installation services represent the dominant competitive vectors reshaping market structure.
Among North American material suppliers, Saint-Gobain Corporation and AGC Glass North America exemplify the integrated portfolio archetype, combining glass manufacturing with insulation and coating technologies. Kawneer Company Inc occupies a position within the engineering-specialist tier, anchoring specification-driven projects requiring thermal break performance. These three companies represent distinct strategic approaches to capturing value across Canada's tightening energy code environment.
| Leading Market Players |
|---|
| Saint-Gobain Corporation |
| AGC Glass North America |
| Flynn Group of Companies |
| Enclos Corp. |
| Permasteelisa North America |
| YKK AP Inc |
| Kawneer Company Inc |
| Schuco International KG |
| Norsk Hydro ASA |
| Others |
Value Chain & Pricing Dynamics
London Metal Exchange aluminum prices cascade through Canadian facade supply chains, compressing margins for extruded framing fabricators while amplifying cost differentials between domestic and imported glass units. Provincial energy code tiers fragment procurement budgets as developers in British Columbia absorb premium thermal break specifications that Ontario mid-rise projects defer.
Pricing Analysis
Input-cost pass-through from aluminum billet and low-emissivity glass coatings stratifies pricing across project tiers. Three-tier pricing structure across premium, standard, and economy levels separates LEED-targeted curtain wall specifications from warehouse metal panel procurement. Cost compression in mid-rise commercial segments intensifies as Quebec fabricators compete on lump-sum envelope guarantees. Institutional buyers exhibit lowest price sensitivity due to bundled facade-MECH procurement, while industrial warehouse developers drive hardest unit-cost negotiations.
Supply Chain Analysis
Regional distribution centers in Greater Montreal and Kitchener-Waterloo anchor hub-and-spoke patterns serving Ontario and Quebec construction corridors. Manufacturing concentrates in Canada and the United States, with specialty glass coatings sourced from Germany and Japan. Raw material dependencies span aluminum extrusion billets, polyamide thermal break strips, and silicone structural glazing. Single-source vulnerability around low-emissivity coating technology exposes projects to extended lead times. Distribution runs through fabricator-direct channels for large commercial towers and distributor networks for renovation contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Canada facade market compounds returns through regulatory ratchet effects, with the British Columbia Energy Step Code Tier 5 deadline compressing specification timelines and forcing premature replacement cycles in lower-tier provinces.
For Market Incumbents: Extend thermal break engineering capabilities to capture British Columbia Energy Step Code Tier 5 specifications ahead of provincial adoption waves. Backward integration into polyamide thermal break extrusion defends margin position against aluminum price volatility. Capacity addition in Edmonton addresses Alberta institutional retrofit demand before design-assist procurement consolidates around national installation networks. For New Entrants and Emerging Players: Begin with pre-fabricated envelope modules for Ontario school boards and Edmonton healthcare authorities where certified installer scarcity constrains incumbent response. Mass timber hybrid commercial projects in Vancouver offer the most penetrable specification entry point. Go-to-market positioning as integrated facade-MECH contractors unlocks bundled procurement decisions. For Investors and Strategic Acquirers: Asymmetric upside sits with regional prefabrication contractors possessing coast-to-coast installation partnerships. Long-term viability hinges on regulatory adoption momentum across provincial energy code tiers. Acquisition targets should demonstrate National Research Council Canada fire resistance certification pipelines. Watch provincial Ministry of Municipal Affairs adoption announcements for National Building Code tiered standards as inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Prefabrication Capacity Expansion | Factory-assembled envelope modules reduce field hours as Ontario labor scarcity intensifies. |
| Backward Integration into Thermal Breaks | In-house polyamide extrusion insulates margin compression from aluminum price swings. |
| Design-Assist Contracting Capability | Lump-sum air leakage guarantees transfer performance risk from general contractors. |
| Integrated Facade-MECH Packaging | Bundle envelope upgrades with HVAC replacements for Alberta institutional procurement. |
| Photovoltaic Glazing Certification | Toronto Green Standard Tier 2 compliance positions systems for net-zero-ready buildings. |
Study Parameters
Coverage spans Ontario, British Columbia, Quebec, Alberta, and Atlantic Canada, with primary inputs from each region weighted by construction permit volume. Primary interviews with curtain wall fabricators, glazing contractors, institutional procurement officers, and building envelope consultants combined with secondary validation from National Research Council Canada technical bulletins, provincial Ministry of Municipal Affairs code adoption records, and CMHC financing disclosure data. Bottom-up project pipeline analysis triangulated against top-down construction spending forecasts.
Rate-of-change decomposition across material type, application vertical, design style, and installation methodology segments informed volume projections. CAGRs derived from regression analysis of historical permit data against regulatory adoption timelines. Industry-specific forecast inputs include British Columbia Energy Step Code tier transition schedules and Federal Greener Homes Initiative subsidy allocation patterns across the projection horizon.
Several conditions sit outside the modeled scope, including extreme aluminum price volatility scenarios and accelerated National Building Code federal adoption beyond provincial willingness. Forecasts reflect documented assumptions around regulatory implementation pacing. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Roof Window Market
Building & Construction Materials
Artificial Wood Beams Market
Building & Construction Materials
Autoclaved Aerated Concrete (AAC) Blocks Market
Building & Construction Materials
Clean Room Panels Market
Building & Construction Materials
Sheet Piling Market
Building & Construction Materials
US Geosynthetics Market
Building & Construction Materials
Asphalt Shingles Market
Building & Construction Materials
North America Rainscreen Cladding Market
Building & Construction Materials
Electrochromic Glass for Construction Market
Building & Construction Materials
Plumbing Fixtures and Fittings Manufacturing Market
Building & Construction Materials
Sawn Timber Market
Building & Construction Materials
Asia-Pacific Gypsum Board Market
Building & Construction Materials
Reclaimed Lumber Market
Building & Construction Materials
Floor Screeds Market
Building & Construction Materials
Asia-Pacific Ceramic Sanitary Ware Market
Building & Construction Materials
Steel Roofing Market