
 Ready-Mix Concrete Market | 2026-2036
Ready-Mix Concrete Market Size, Share, and Industry Trends Forecast 2026-2036
Ready-Mix Concrete Market Intelligence
A scarcity of skilled batch plant operators and quality control technicians is bifurcating the market between automated, high-spec providers and traditional local suppliers. Holcim leverages its global network and digital platforms to optimize logistics and ensure consistent quality across diverse projects. CEMEX SAB de CV differentiates through its focus on specialized concrete solutions, including sustainable and high-performance mixes for urban development.
Ready-mix concrete is a precisely batched construction material, manufactured in a central plant and delivered to a worksite in a plastic or unhardened state. Its composition includes cement, water, aggregates, and often chemical admixtures to control properties like setting time and workability. High-strength concrete products command premium pricing due to their use in demanding infrastructure projects and high-rise commercial buildings. The residential buildings application segment remains the volume leader, though with lower margins compared to specialized industrial facility work.
Producers navigate complex regulations, including EPA standards on dust and water runoff in the United States and the EU Green Deal's circular economy principles. China's dual carbon goals are pushing for low-carbon cement and concrete formulations. Success hinges on innovating with low-carbon materials while managing the logistical complexities of on-demand delivery.
Market Dynamics
The ready-mix concrete market is defined by a fundamental tension between its hyper-local, perishable supply chain and the global push for decarbonization. This dynamic forces producers to innovate with low-carbon materials while managing the intense logistical constraints of on-demand delivery to construction sites.
Growth Catalysts
- Government Infrastructure Programs:National-level infrastructure investment, such as housing initiatives in India and transport upgrades in the United States, creates sustained, high-volume demand for consistent quality ready-mix concrete.
- Advanced Concrete Technologies:The development of self-consolidating concrete and ultra-high-performance mixes allows for use in increasingly complex architectural designs and demanding infrastructure, opening new applications and commanding premium prices.
- Urbanization in Developing Economies:Rapid urban expansion and the construction of new high-rise residential and commercial buildings, particularly in Southeast Asia and Africa, require a reliable supply of ready-mix concrete.
Market Restraints
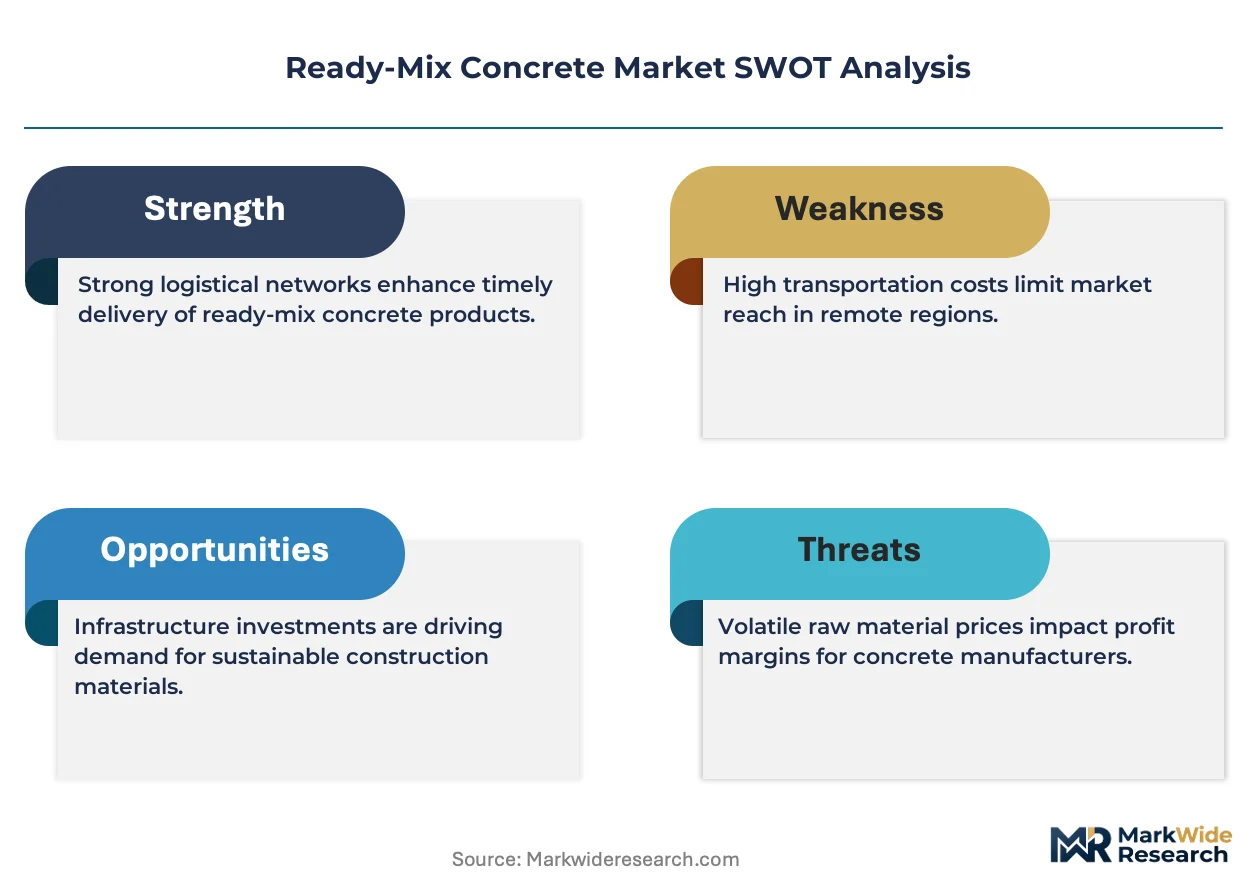
- Input Cost Volatility:Producer margins are sensitive to price fluctuations in key raw materials, particularly Portland cement, aggregates, and chemical admixtures, which are subject to regional supply and energy cost pressures.
- Inherent Logistical Limitations:The material's limited workability time, typically 90 minutes, restricts delivery to a small radius around a batching plant, fragmenting the market and preventing broader economies of scale.
- Substitution from Alternative Materials:The increasing use of cross-laminated timber and structural steel in mid-rise construction projects presents a viable substitute, particularly in regions with stringent building emissions targets.
Strategic Opportunities
- Digitalization of Logistics:Implementing GPS tracking, automated dispatching, and real-time quality monitoring systems can optimize fleet utilization, reduce waste, and provide customers with verifiable quality assurance data.
- Low-Carbon Concrete Formulations:Developing and scaling concrete mixes that incorporate supplementary cementitious materials, recycled aggregates, and CO2 mineralization technologies creates a distinct, high-value product line.
- Service Expansion into Testing and Certification:Offering on-site testing, quality verification, and material lifecycle consulting services provides a new revenue stream and deepens relationships with engineering and construction clients.
Industry Challenges
- Skilled Labor Scarcity:A persistent shortage of qualified batch plant operators, quality control technicians, and drivers hampers operational efficiency and the ability of producers to guarantee consistent product quality across shifts.
- Navigating Disparate Environmental Regulations:Producers must comply with a complex and varying web of regulations, from EPA standards on dust control in the US to the EU Green Deal's circular economy mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ready-Mix Concrete Market |
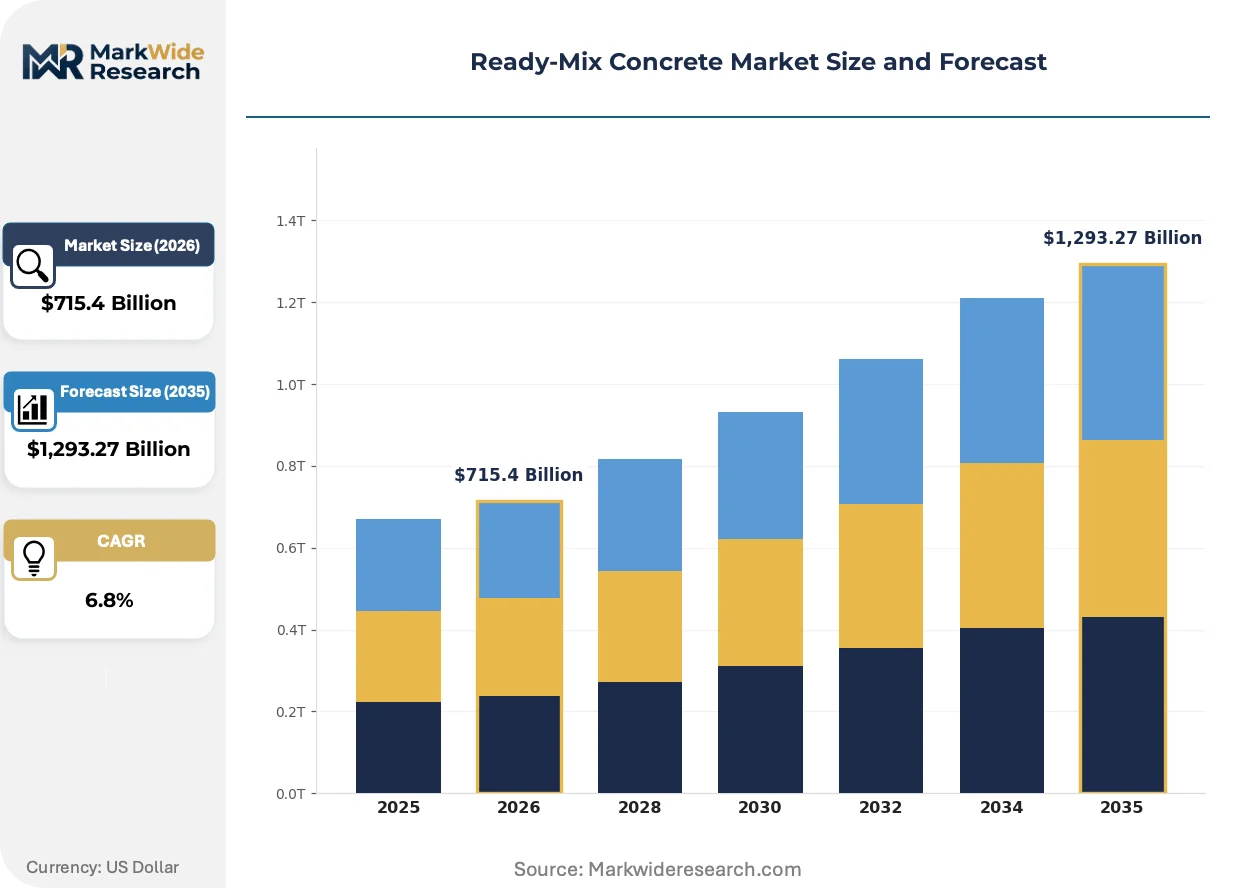
| Market Size in 2026 | $715.4 Billion |
| Market Size in 2035 | $1,293.27 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Normal Concrete, High-Strength Concrete, Fiber Reinforced Concrete, Self-Consolidating Concrete, Lightweight Concrete Application: Infrastructure Projects, Commercial Buildings, Residential Buildings, Industrial Facilities, Public Works End User: Construction Contractors, Real Estate Developers, Government Agencies, Engineering Firms, Municipal Authorities Distribution Channel: Direct Sales, Dealers & Distributors, Online Platforms, Retail Outlets, Project-Based Procurement |
| Companies Covered | Heidelberg Materials, Buzzi Unicem, CRH, China National Building Material Group Corporation, Martin Marietta Materials, CEMEX SAB de CV, LafargeHolcim, Votorantim Cimentos, Holcim, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ready-Mix Concrete Market Strategic Shifts & Innovations
The industry's competitive landscape is being redefined by the dual pressures of sustainability mandates and digital transformation. This forces a shift from selling a commodity product to delivering a performance-guaranteed material with a documented environmental footprint.
Technology and Product Evolution
The use of supplementary cementitious materials (SCMs) like fly ash and ground granulated blast-furnace slag is a primary method for reducing the carbon intensity of concrete. Infrastructure and commercial developers are increasingly specifying mixes with high SCM content to meet sustainability goals. This adoption is decomposing the market's traditional dependence on ordinary Portland cement, creating new supply chain challenges for sourcing and validating these alternative industrial byproducts.
Regulatory and Policy Shifts
China's dual carbon goals are directly impacting cement and concrete production through stricter emissions limits and mandates for greater industrial efficiency. This policy is forcing consolidation among smaller, less efficient producers and accelerating investment in waste heat recovery and alternative fuel technologies at cement plants. The concrete segment is most affected through the constrained supply and rising cost of compliant, low-carbon cement.
Demand-Side and Behavioral Shifts
A move toward performance-based specifications is altering procurement dynamics for large-scale projects. Instead of purchasing based on prescriptive mix designs, asset owners now specify long-term durability outcomes, such as chloride ion penetration resistance or specific service-life targets. This disrupts the traditional transactional sale, favoring suppliers who can provide engineering support and lifecycle performance modeling. This trend is most visible in major public infrastructure projects in North America and Europe.
Ready-Mix Concrete Market Segmentation
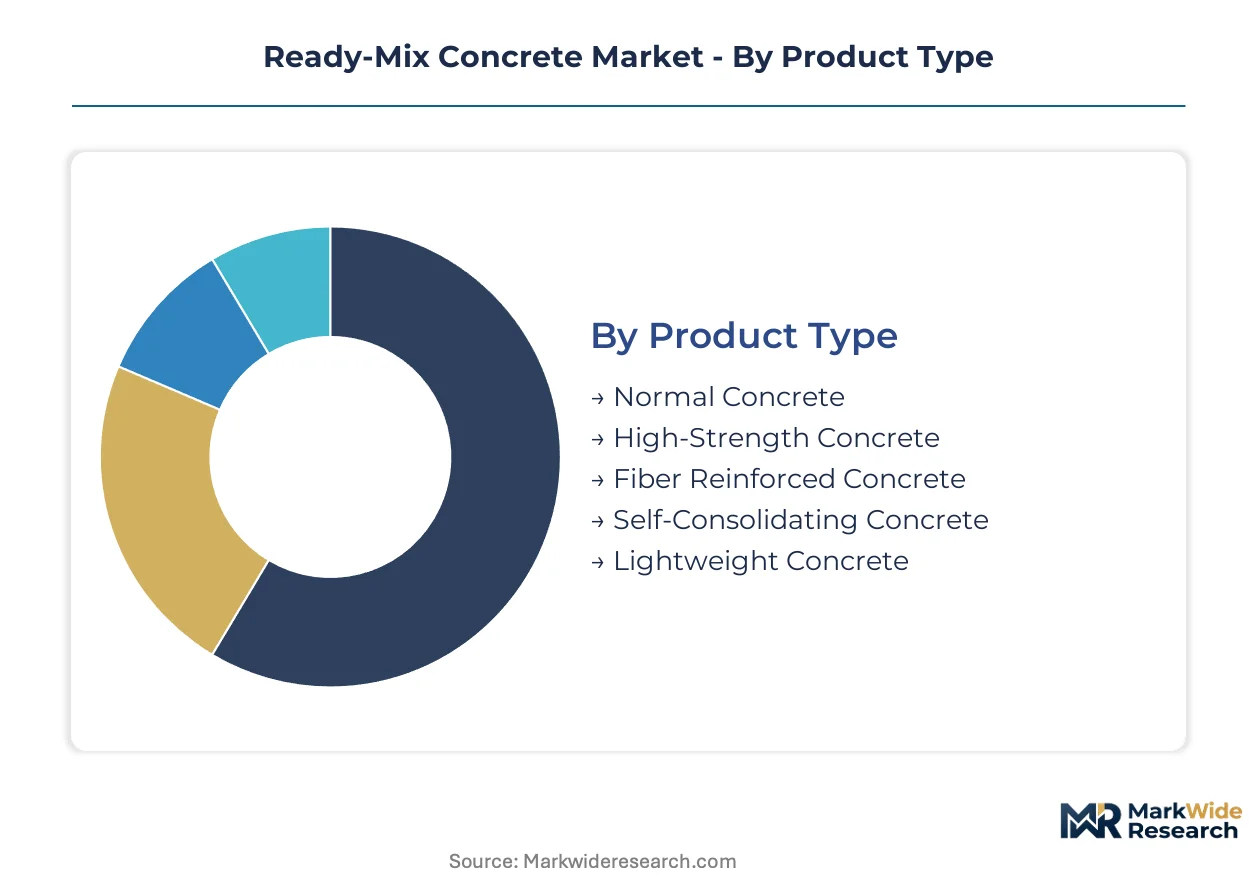
The ready-mix concrete market serves a diverse range of construction needs, necessitating a granular understanding of its various segments. Categorizing the market by product type, application, end user, and distribution channel reveals distinct demand patterns and operational requirements. This segmentation highlights areas of premium value and volume leadership across the industry.
Product Type:
Regulatory bodies increasingly influence product specifications for ready-mix concrete, driving demand for specialized formulations.
- High-Strength Concrete:This concrete is engineered for superior compressive strength, often exceeding 6,000 psi, using optimized aggregate ratios and advanced admixtures. Demand concentrates in demanding infrastructure projects and high-rise commercial buildings in North America, where structural integrity is paramount.
- Self-Consolidating Concrete:Formulated to flow and compact under its own weight without external vibration, this concrete contains superplasticizers and viscosity-modifying admixtures. Complex architectural designs and congested rebar structures in European urban developments increasingly specify this efficient material.
- Normal Concrete:This standard mix forms the backbone of most general construction, comprising cement, aggregates, water, and basic admixtures for workability.
- Fiber Reinforced Concrete:Incorporates steel, synthetic, or glass fibers to enhance tensile strength, crack resistance, and ductility in industrial floor slabs.
- Lightweight Concrete:Utilizes lightweight aggregates like expanded shale or clay to reduce density, often specified for non-load-bearing elements and precast applications.
Established volume favors Normal Concrete; emerging adoption favors Self-Consolidating Concrete.
Application:
Demand for ready-mix concrete concentrates across diverse construction applications, each driven by distinct project requirements.
- Residential Buildings:This segment consumes the largest volume of ready-mix concrete for foundations, slabs, and structural elements in single-family homes and multi-story apartments. Rapid urbanization and government housing initiatives in India contribute significantly to this high-volume demand.
- Infrastructure Projects:Large-scale public works, including roads, bridges, dams, and tunnels, require consistent, high-quality concrete with specific durability and performance characteristics. Government investment in transport upgrades across the United States drives substantial demand for these specialized mixes.
- Commercial Buildings:This application covers office towers, retail centers, and hotels, requiring concrete for structural frames, parking garages, and architectural finishes.
- Industrial Facilities:Concrete for factories, warehouses, and power plants often needs chemical resistance, extreme flatness, or high load-bearing capacity.
- Public Works:This segment includes municipal projects like sidewalks, street improvements, and utility infrastructure, demanding reliable, standard-grade concrete.
The largest volume of concrete flows into Residential Buildings, while Infrastructure Projects often command premium mixes.
End User:
Procurement patterns for ready-mix concrete vary significantly among different end-user types, reflecting project scale and complexity.
- Construction Contractors:These entities are the primary purchasers, responsible for on-site execution and direct material procurement for diverse projects. Their purchasing decisions are influenced by project timelines, material specifications, and supplier reliability.
- Government Agencies:Public sector bodies, including national and local departments, procure ready-mix concrete for large-scale infrastructure and public building projects. Their procurement processes often involve competitive bidding, stringent quality controls, and long-term contracts.
- Real Estate Developers:These firms specify concrete types and quantities for their residential and commercial developments, influencing supplier selection through their general contractors.
- Engineering Firms:While not direct purchasers, engineering firms design structures and specify concrete performance, indirectly guiding material selection for their clients.
- Municipal Authorities:Local government bodies purchase concrete for smaller-scale public works, such as street repairs, sidewalks, and local utility upgrades.
Construction Contractors represent the primary purchasers, with Government Agencies setting long-term demand through public works.
Distribution Channel:
Logistical efficiency and customer relationships define the effectiveness of ready-mix concrete distribution channels.
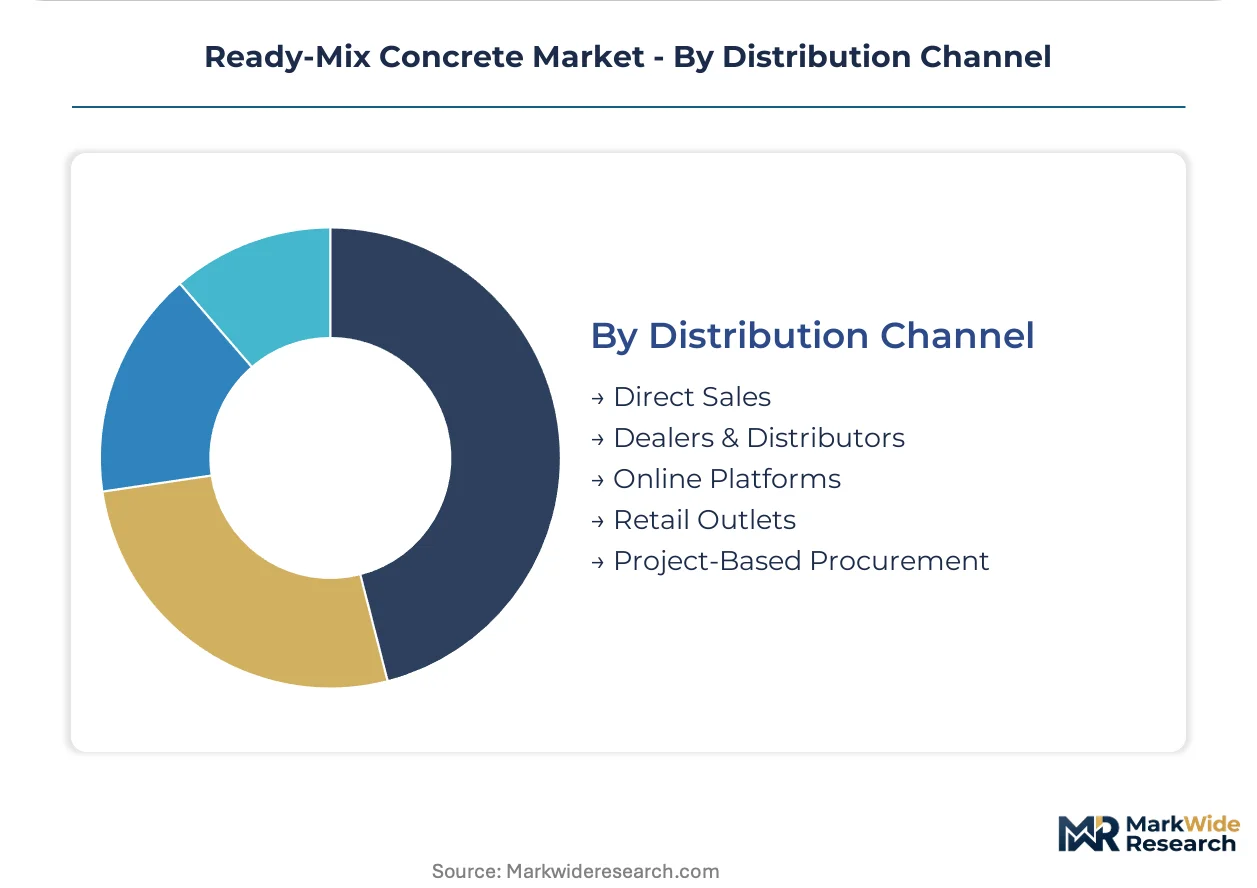
- Direct Sales:Producers directly manage sales and delivery to construction sites, enabling customized mixes, technical support, and real-time logistics for large-scale projects. This channel ensures consistent quality control for major infrastructure developments.
- Project-Based Procurement:This channel involves tailored supply agreements for specific, often long-duration, construction projects, emphasizing reliability and dedicated fleet management. Major commercial building projects frequently utilize this integrated approach.
- Dealers & Distributors:These intermediaries stock and resell ready-mix concrete, serving smaller contractors and projects with less complex requirements.
- Online Platforms:Digital platforms facilitate ordering and delivery of standard concrete mixes, catering to smaller jobs and enhancing convenience for local builders.
- Retail Outlets:Limited quantities of bagged concrete or specialized mixes are available through retail channels for very small-scale repairs or DIY projects.
Direct Sales remains the dominant channel for large projects, while Online Platforms are gaining traction for smaller, on-demand deliveries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States Environmental Protection Agency (EPA) standards influence ready-mix concrete production across North America, driving demand for compliant materials. Regional growth in the market reflects diverse infrastructure spending and urbanization patterns. Producers navigate local regulatory landscapes while addressing the logistical challenges inherent to concrete delivery.
United States
Demand for ready-mix concrete in the United States stems from extensive transport upgrades and commercial building projects. Federal initiatives like the Infrastructure Investment and Jobs Act stimulate sustained demand for high-quality mixes. Major metropolitan areas such as New York City and Los Angeles drive significant volume for high-rise construction and urban renewal.
India
India's ready-mix concrete market expands significantly due to government-led urban infrastructure and housing initiatives. The Bureau of Indian Standards (BIS) regulates concrete quality, ensuring material consistency for large-scale developments. Rapid urbanization in cities like Mumbai and Delhi fuels continuous demand for residential and commercial construction.
China
China's market for ready-mix concrete is shaped by ambitious urban expansion and industrial facility construction. The country's dual carbon goals, enforced by the Ministry of Ecology and Environment (MEE), push for low-carbon cement and concrete formulations. The Yangtze River Delta region, including Shanghai, sees concentrated investment in advanced manufacturing and high-density housing.
Germany
Germany's ready-mix concrete sector benefits from a focus on sustainable urban development and demanding civil engineering projects. The EU Green Deal and its circular economy principles influence material specifications and production methods. Industrial regions like North Rhine-Westphalia require specialized concrete for advanced manufacturing facilities and public transport networks.
Brazil
Brazil's ready-mix concrete market is supported by ongoing residential construction and public works programs. National infrastructure investment drives demand for consistent material supply across diverse projects. Major urban centers such as São Paulo and Rio de Janeiro generate substantial volume for both new construction and urban renewal initiatives.
Ready-Mix Concrete Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, defining the ready-mix concrete market structure. Global players leverage extensive networks and technological capabilities. Strategic archetypes include large multinational corporations, regional powerhouses, and local niche providers specializing in unique concrete formulations. Dominant competitive moves involve digitalization of logistics and investment in sustainable concrete innovation.
Among global integrated players, Holcim (formerly LafargeHolcim) exemplifies a multinational presence with a focus on digital platforms and consistent quality. CEMEX SAB de CV, a prominent Mexican-based company, differentiates itself through specialized concrete solutions, including sustainable and high-performance mixes. CRH, an Irish-domiciled building materials group, represents a major player with a strong regional footprint and diversified product offerings across various construction applications.
| Leading Market Players |
|---|
| Heidelberg Materials |
| Buzzi Unicem |
| CRH |
| China National Building Material Group Corporation |
| Martin Marietta Materials |
| CEMEX SAB de CV |
| LafargeHolcim |
| Votorantim Cimentos |
| Holcim |
| Others |
Cost & Logistics Intelligence
EU Green Deal principles gate both concrete supply qualification and price differentiation. These regulations mandate specific material compositions, impacting production costs and market access for compliant low-carbon mixes.
Pricing Analysis
Regional price spreads for ready-mix concrete vary significantly due to localized production costs and demand dynamics. Project-based pricing dominates, with long-term contracts common for major infrastructure developments. Quality grade, including specific certifications, and geographic delivery costs are primary differentiation drivers. Pricing softness stems from intense competition among local suppliers and capacity oversupply in certain regions. Residential building projects often exhibit the highest price sensitivity, contrasting with specialized infrastructure work demanding premium mixes.
Supply Chain Analysis
Just-in-time delivery defines the ready-mix concrete supply chain, driven by the material's limited workability time. Raw material supply concentrates locally for aggregates, while cement production relies on major global hubs like China, India, and the US. Key dependencies include Portland cement, various aggregates, and chemical admixtures. Commodity price volatility for these essential inputs represents a significant structural risk. Direct sales and project-based procurement form the dominant distribution model, ensuring tailored supply to large construction sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ready-mix concrete market is experiencing a cyclical recovery, primarily driven by renewed global infrastructure spending. This resurgence presents strategic opportunities and challenges for all market participants.
For Market Incumbents: Consolidate regional operations to achieve greater economies of scale and optimize logistical networks. Invest in advanced batching technology to counter skilled labor scarcity and ensure consistent quality across diverse projects. Counter the threat from alternative materials like cross-laminated timber by developing superior low-carbon concrete formulations. Deepen vertical integration into supplementary cementitious materials to secure supply and manage input cost volatility.
For New Entrants and Emerging Players: Lead with specialized, high-performance concrete solutions targeting complex architectural designs and demanding infrastructure projects. Focus on underserved local markets with advanced digital platforms for efficient order management and delivery. The self-consolidating concrete segment represents a penetrable niche due to its efficiency benefits. Offer comprehensive material lifecycle consulting as a distinct go-to-market angle.
For Investors and Strategic Acquirers: China's dual carbon goals reshape the acquisition landscape, favoring firms with proven low-carbon cement and concrete technologies. The market offers long-term viability, underpinned by urbanization and infrastructure needs. Target regional specialists demonstrating strong intellectual property in sustainable formulations or advanced logistics. A critical signal to watch is the widespread adoption of CO2 mineralization technologies.
| Strategic Initiative | Industry Significance |
|---|---|
| Digitalize Logistics and Fleet Management | Optimizes delivery routes and reduces fuel consumption, enhancing profitability for global players like Holcim. |
| Invest in Low-Carbon Concrete R&D | Develops high-value product lines incorporating SCMs and CO2 mineralization, meeting EU Green Deal mandates. |
| Expand Specialized Concrete Production | Addresses demand for high-strength and self-consolidating mixes in complex urban developments. |
| Acquire Regional Batch Plant Networks | Secures local market share and improves delivery radius efficiency against local competitors. |
| Offer Material Testing and Certification Services | Generates new revenue streams and strengthens relationships with engineering firms and construction contractors. |
Research Approach
The analysis maps product types, application segments, and regional markets, each validated through extensive primary interviews with industry experts. Stakeholders included batch plant operators, project managers, procurement leads, and environmental compliance officers. Secondary validation leveraged US EPA standards, BIS regulations, company reports, and construction project databases. This approach integrated bottom-up data collection with top-down market sizing for robust triangulation.
Consistency checks against external benchmarks validated all quantitative outputs across the analysis window. The analytical framework modeled market dynamics across product type, application, end user, and distribution channel. It also considered regional infrastructure spending patterns. Compound annual growth rates were derived from historical trends and projected economic indicators. Government infrastructure budgets and urbanization rates served as key forecast inputs.
Forecasts assume regulatory continuity in US EPA and EU Green Deal regimes; material policy shifts would require re-modeling. The analysis reflects current market conditions and known technological trajectories. Input cost volatility and sudden shifts in environmental regulations represent specific risk factors. Revision becomes warranted when infrastructure investment commitments cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Artificial Bowling Surface Market
Building & Construction Materials
South Africa Wall Putty Market
Building & Construction Materials
Concrete Floating Floors System Market
Building & Construction Materials
Industrial Thermal Insulation Market
Building & Construction Materials
Concrete Form Oil Market
Building & Construction Materials
Stone Veneer Market
Building & Construction Materials
Articulated Concrete Block Mattresses Market
Building & Construction Materials
Mineral Wool Ceiling Tiles Market
Building & Construction Materials
Drywall and Gypsum Board Market
Building & Construction Materials
Carbon Steel IBC Market
Building & Construction Materials
North America Prefab Wood Building Market
Building & Construction Materials
Travertine Tiles Market
Building & Construction Materials
Reclaimed Lumber Market
Building & Construction Materials
Acoustical Ceiling Market
Building & Construction Materials
Prestressed Concrete (PC) Wire and Strand Market
Building & Construction Materials
North America Mineral Wool Ceiling Tiles Market