
 India BOPP Films Market | 2026-2036
India BOPP Films Market Size, Share, and Industry Trends Forecast 2026-2036
India BOPP Films Market Foresight
Gujarat's petrochemical corridor is reshaping raw material access for BOPP film extruders along the western coast. Cosmo Films leverages captive resin sourcing to sustain margin stability across transparent and metallized grades. Jindal Poly Films anchors large-format capacity serving pan-India flexible packaging converters. Uflex competes through backward integration into resin compounding and adhesive coating operations.
Biaxially oriented polypropylene films are thermoplastic polymer sheets stretched in machine and transverse directions to achieve tensile strength between 100-250 MPa, clarity above 90%, and moisture vapor transmission rates below 1.0 g/m²/day, serving primarily as barrier layers in flexible packaging, labels, and overwrap applications. Transparent films dominate volume shipments due to universal adoption in snack lamination, while metallized variants command premium positioning in biscuit and confectionery barrier structures where oxygen and light protection determine shelf life. Coated grades are gaining traction in medical and pharmaceutical blister lidding where heat-seal performance and pinhole resistance meet stringent migration limits.
BIS standards for food-contact plastics, FSSAI migration limits, and the Plastic Waste Management Rules collectively mandate compositional transparency and recyclability declarations from domestic film suppliers. The Central Pollution Control Board's extended producer responsibility frameworks are pushing converters to document mono-material sourcing, directly favoring BOPP over multi-polymer laminates in secondary packaging tiers. Stakeholders must monitor BIS notification timelines for revised food-contact additive positive lists and assess captive recycling investments before compliance deadlines tighten material traceability requirements.
Market Dynamics
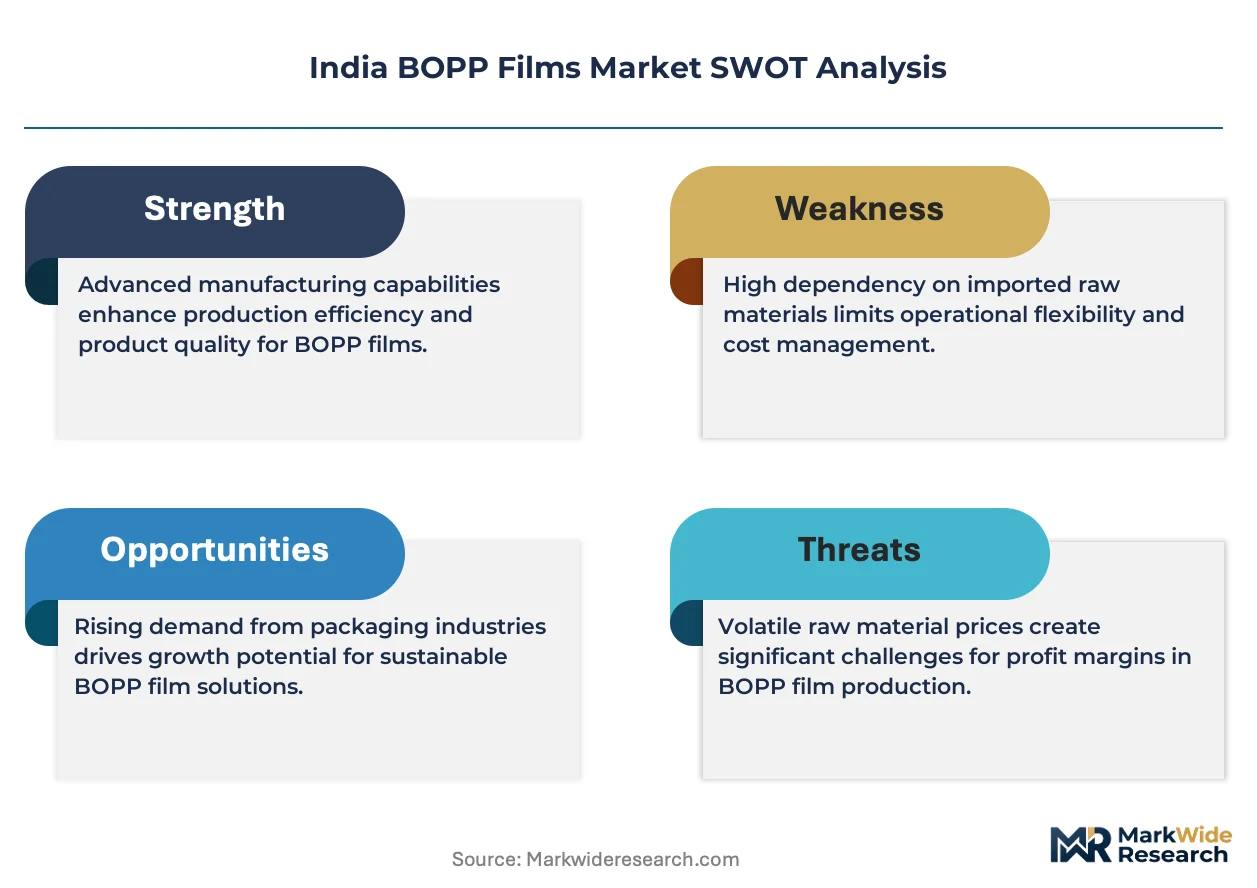
Polymer processing clusters along Gujarat's petrochemical corridor are consolidating raw material access, enabling captive resin sourcing that compresses cost structures for film extruders serving Maharashtra and Gujarat converters.
Growth Catalysts
- Snack Packaging Expansion:Ready-to-eat food manufacturers in western India are scaling lamination-grade transparent film orders for extended shelf-life formats.
- BIS Certification Mandates:FSSAI migration limits and BIS food-contact standards are redirecting procurement toward certified domestic suppliers with documented traceability.
- Mono-Material Recyclability:Central Pollution Control Board extended producer responsibility frameworks favor BOPP over multi-polymer laminates in secondary packaging tiers.
Market Restraints
- Propylene Feedstock Volatility:Crude-linked naphtha and propane pricing swings transmit directly to film extrusion margins, compressing working capital cycles.
- Western Capacity Concentration:Vadodara-Pune-Mundra clusters anchor over two-thirds of domestic extrusion capacity, creating geographic supply risk during monsoon logistics disruptions.
- Metallized Grade Technical Ceiling:Oxygen transmission rates below 0.5 cc/m²/day remain difficult to achieve without aluminum oxide coating investments that strain mid-scale extruders.
Strategic Opportunities
- Southern India Underpenetration:Tamil Nadu and Karnataka flexible packaging converters rely heavily on western supply chains, creating white space for regional extrusion investments.
- Pharmaceutical Blister Lidding:CDSCO heat-seal performance requirements and pinhole resistance standards are opening certified coated-grade niches beyond commodity snack films.
- PLI Scheme Incentives:Domestic manufacturing incentives for specialty chemicals and advanced materials support captive adhesive coating and resin compounding integration.
Industry Challenges
- Specialized Extrusion Talent Scarcity:Machine-direction and transverse-direction stretching process engineers with tenter frame optimization experience command premium compensation in Vadodara and Pune clusters.
- BIS Notification Timeline Uncertainty:Revised food-contact additive positive lists lack definitive implementation schedules, freezing long-term formulation investments.
- Legacy Lamination Equipment Compatibility:Converter solvent-based adhesive lines require retrofitting for water-based and solventless systems compatible with high-clarity BOPP surfaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India BOPP Films Market |
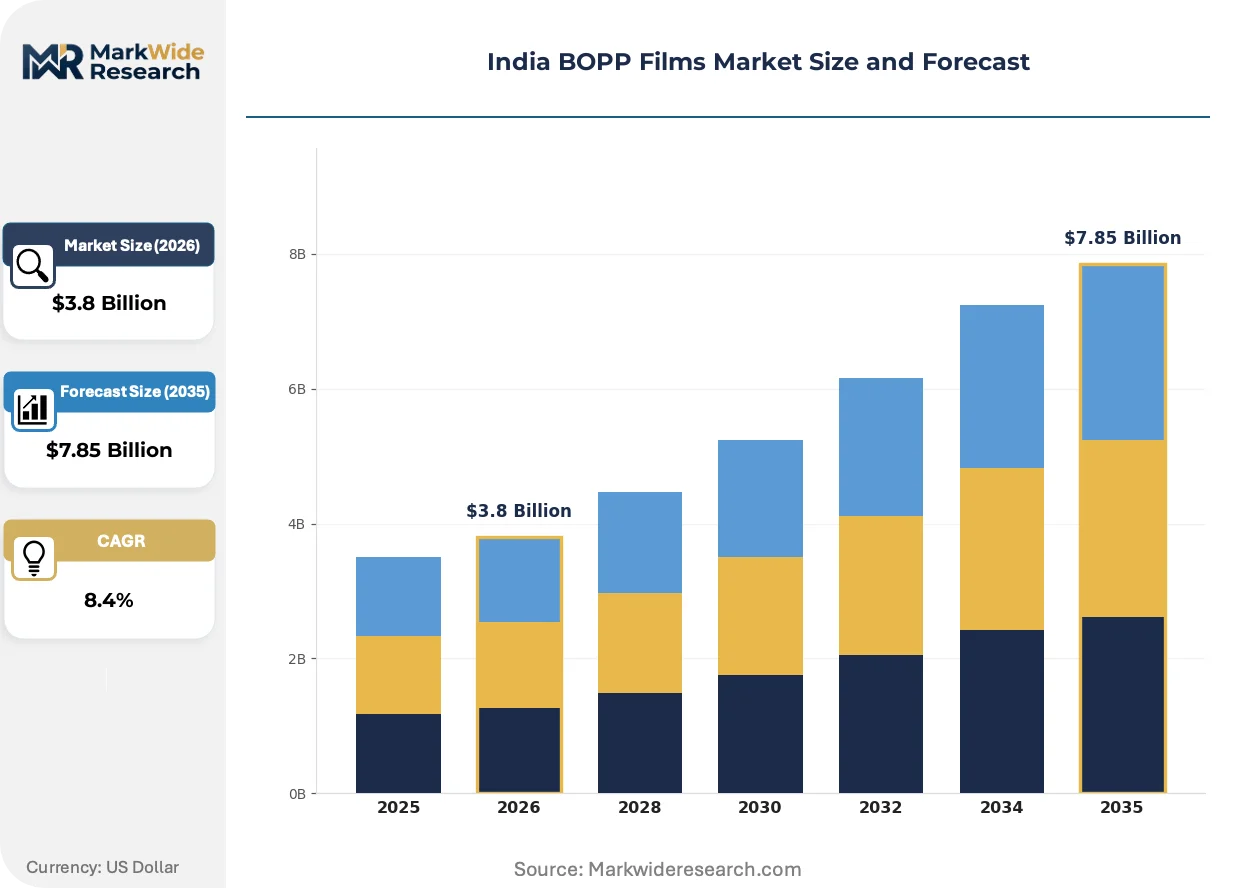
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.85 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transparent, Matte, Metallized, Coated End Use: Food Packaging, Consumer Goods, Labeling, Medical Thickness: 15 Micron, 25 Micron, 50 Micron, 70 Micron Distribution Channel: Direct Sales, Online, Wholesale, Retail |
| Companies Covered | Satyendra Packaging, Jindal Films, Cosmo Films, Flex Industries, SRF, Jindal Poly Films, Polyplex, GANPATI Films, Uflex, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India BOPP Films Market Shifts & Advancements
Film extrusion technology and regulatory compliance frameworks are converging to reshape competitive positioning across transparent, metallized, and coated grade segments serving food and pharmaceutical packaging.
Thin-gauge downgauging technology is collapsing material intensity requirements for snack lamination applications. Transparent film specifications below 12 micron are gaining adoption among Maharashtra-based flexible packaging converters seeking yield optimization. This compression is collapsing per-unit material costs while maintaining tensile performance above 150 MPa.
FSSAI migration limit notifications are tightening compositional disclosure requirements for food-contact film suppliers. BIS certification timelines now mandate third-party testing for heavy metal and primary aromatic amine content before market placement. Western India extruders with in-house analytical laboratories are compressing certification cycle times versus competitors relying on external testing facilities.
Converter procurement patterns are rotating toward mono-material sourcing declarations demanded by brand owners under Plastic Waste Management Rules compliance. Direct contracting between snack manufacturers and certified film suppliers is displacing distributor-mediated spot purchasing in Gujarat and Maharashtra. This channel compression is most visible in biscuit and confectionery barrier structures where recyclability documentation determines supplier qualification.
India BOPP Films Market Segmentation
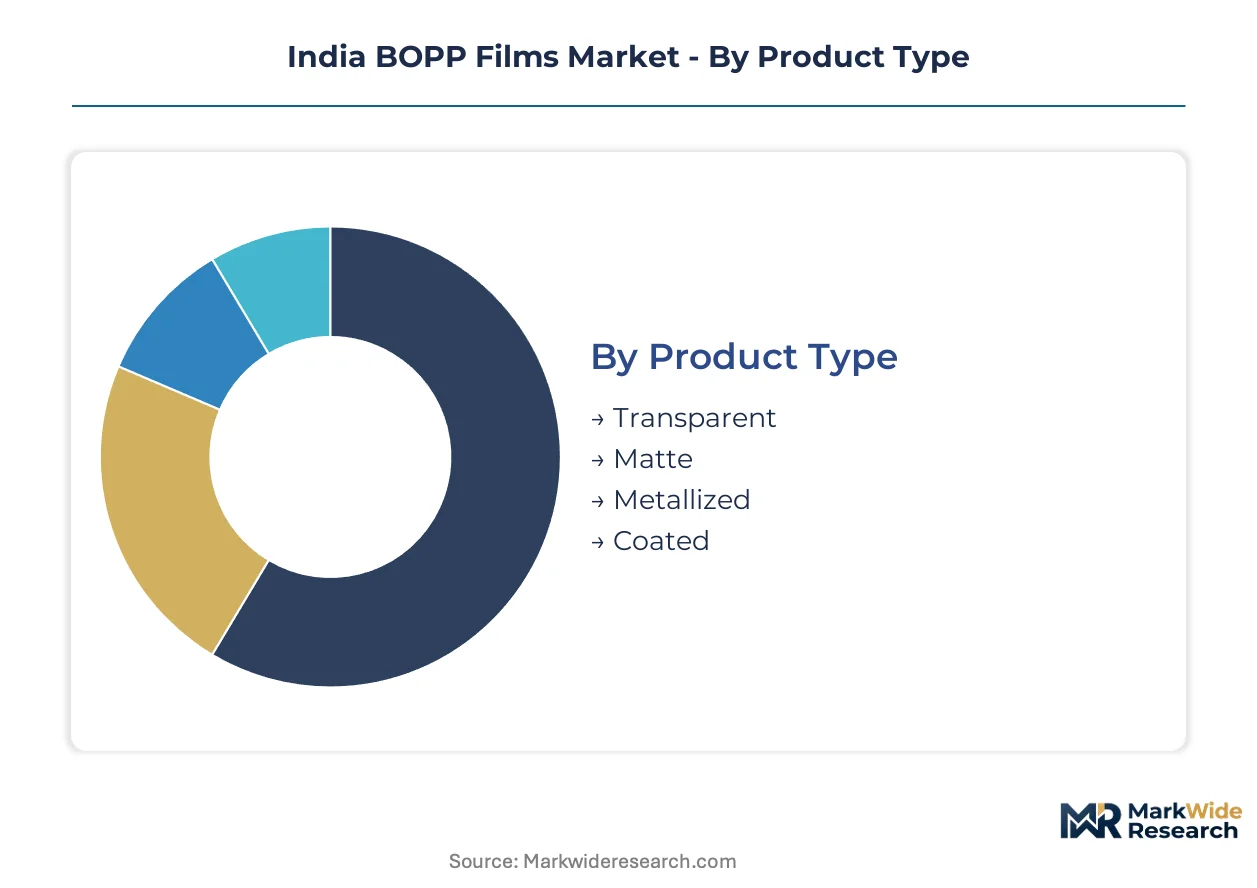
India BOPP Films Market segmentation reveals how technical specifications and procurement channels align with end-use performance requirements across Maharashtra and Gujarat processing clusters. Distinct film grades serve laminated snack barriers, pharmaceutical blisters, and adhesive labels with divergent clarity, seal strength, and migration compliance demands.
Product Type:
Use-case spectrum spans commodity snack lamination through specialized pharmaceutical barriers, with optical properties and metallization depth determining application fit.
- Transparent:Crystal-clear biaxially oriented sheets with haze below 2% and gloss exceeding 90 GU serve universal snack and confectionery lamination across Pune and Vadodara converter bases. Maharashtra flexible packaging manufacturers specify 12-20 micron gauges for extended shelf-life biscuit and namkeen formats where product visibility drives consumer appeal.
- Metallized:Vacuum-deposited aluminum layers achieve oxygen transmission rates below 1.0 cc/m²/day and light blocking above 99%, commanding premium positioning in western India biscuit and chocolate barrier structures where shelf life determines brand owner procurement.
- Matte:Surface-roughened films with gloss reduction to 10-30 GU enable high-end label and overwrap applications requiring tactile differentiation and reduced glare under retail lighting.
- Coated:Extrusion-coated or solvent-coated variants with tailored heat-seal initiation temperatures serve CDSCO-compliant pharmaceutical blister lidding where pinhole resistance and migration limits govern supplier qualification.
Established volume favors Transparent; emerging adoption favors Coated.
End Use:
Customer procurement patterns concentrate in food-contact applications, with regulatory compliance thresholds fragmenting supply qualification across FSSAI-governed and CDSCO-governed segments.
- Food Packaging:Dominant demand channel spanning laminated pouches, flow wraps, and stand-up bags for ready-to-eat snacks, biscuits, and confectionery across Gujarat and Maharashtra brand manufacturing. BIS food-contact certification and FSSAI migration documentation now gate supplier approval for direct contracting with ITC, Parle, and regional snack processors.
- Labeling:Pressure-sensitive adhesive face stocks and in-mold labels for FMCG bottles and containers, with clarity and dimensional stability specifications set by Mumbai and Ahmedabad label converters serving beverage and personal care brand owners.
- Consumer Goods:Overwrap and twist-wrap applications for textiles, stationery, and tobacco products where optical properties matter less than yield optimization and seal integrity.
- Medical:Sterilizable barrier films and pharmaceutical blister lidding requiring CDSCO drug master file alignment, with coated grades penetrating this segment fastest as domestic extruders invest in cleanroom coating capacity.
Procurement volume concentrates in Food Packaging; qualification complexity escalates fastest in Medical.
Thickness:
Material intensity trade-offs between yield optimization and mechanical performance segment converter preferences across high-speed lamination and deep-draw blister forming.
- 15 Micron:Ultra-thin gauge for lightweight snack overwrap and twist-wrap where downgauging technology has collapsed per-unit resin consumption while maintaining 120+ MPa tensile strength for high-speed packaging line compatibility.
- 25 Micron:Workhorse specification balancing stiffness and conformability for general-purpose lamination and label face stock across western India flexible packaging converters.
- 50 Micron:Heavy-duty barrier and thermoformable grades for deep-draw pharmaceutical blister packs and industrial textile wrapping where puncture resistance outweighs material cost sensitivity.
- 70 Micron:Rigid structural films for specialized industrial and agricultural applications with limited penetration in mainstream packaging.
Downgauging momentum favors 15 Micron; barrier performance requirements sustain 50 Micron.
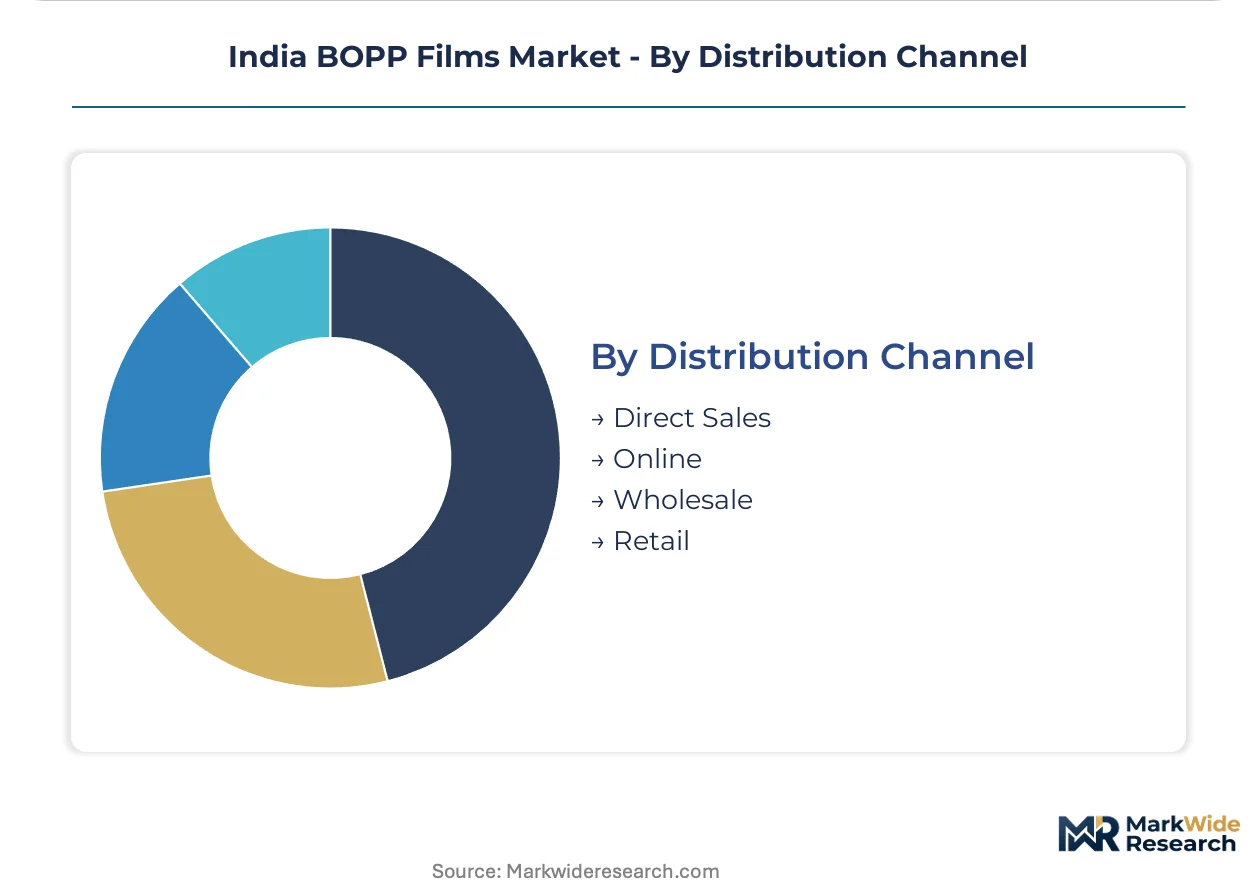
Distribution Channel:
Channel structure reflects procurement scale and compliance documentation intensity, with Plastic Waste Management Rules traceability demands reshaping relationship patterns.
- Direct Sales:Contractual supply relationships between certified extruders and large-format converters or brand owners, now dominant in Gujarat and Maharashtra as EPR documentation requirements displace spot purchasing. Cosmo Films and Jindal Poly Films anchor this channel with dedicated account management for volume snack and biscuit manufacturers.
- Wholesale:Distributor-mediated supply for mid-tier converters lacking scale for direct mill contracting, concentrated in secondary cities across Karnataka and Tamil Nadu where regional extrusion capacity remains underdeveloped.
- Online:Digital procurement platforms for standardized transparent grades and sample ordering, gaining traction among small label converters and startup flexible packaging operations in Tier-2 cities.
- Retail:Minimal presence; limited to specialty film shops serving prototype and R&D requirements in Mumbai and Ahmedabad industrial supply districts.
Compliance documentation is consolidating procurement into Direct Sales; geographic gaps sustain Wholesale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
BIS certification mandates and FSSAI migration limits anchor western India's dominance in BOPP film production and consumption. The analysis covers five sub-regions where polymer processing infrastructure, converter density, and regulatory compliance requirements concentrate demand.
Maharashtra
Pune and Mumbai flexible packaging converters drive lamination-grade transparent film demand for ITC and Parle biscuit lines. FSSAI food-contact documentation requirements now gate direct supplier contracting. The Bhiwandi-Pune corridor hosts the densest converter cluster outside Gujarat, with snack manufacturers scaling metallized barrier orders.
Gujarat
Vadodara and Mundra anchor over two-thirds of domestic extrusion capacity, with petrochemical feedstock integration compressing resin costs for film producers. BIS standards for food-contact plastics mandate third-party heavy metal testing before market placement. The Dahej-Vadodara belt concentrates backward-integrated extruders with captive compounding operations.
Karnataka
Bangalore-based label converters and flexible packaging operations rely on western supply chains, creating logistics cost premiums and inventory lead time disadvantages. CDSCO pharmaceutical packaging regulations drive coated-grade demand for blister lidding applications. The Peenya industrial zone hosts emerging converter investments seeking regional film sourcing alternatives.
Tamil Nadu
Chennai and Coimbatore food processors import metallized films from Gujarat and Maharashtra, exposing supply chains to monsoon logistics disruptions. Plastic Waste Management Rules EPR frameworks push brand owners toward mono-material sourcing declarations. The Sriperumbudur-Oragadam belt hosts automotive and consumer goods packaging demand with limited local extrusion response.
Delhi-NCR
Noida and Gurugram converters serve northern India snack and confectionery brand owners with distributor-mediated procurement from western extruders. DGFT import policy shifts and BIS certification timelines create supplier qualification bottlenecks. The region's packaging machinery ecosystem supports film lamination but lacks upstream extrusion investment.
India BOPP Films Market Competitive Landscape
Backward-integrated resin compounders and specialized coating operators split the market into margin-stable and premium-positioned tiers. The vendor base clusters around two strategic archetypes: petrochemical-captive extruders leveraging feedstock integration, and technology-focused specialists investing in metallization and cleanroom coating capacity. Competitive moves concentrate on captive resin sourcing consolidation and pharmaceutical-grade certification acquisition.
Among western India-based integrated producers, Cosmo Films, Jindal Poly Films, and Uflex occupy positions spanning transparent commodity grades through specialized barrier films. Cosmo Films exemplifies the petrochemical-captive archetype with resin sourcing integration. Jindal Poly Films anchors large-format capacity serving pan-India converter networks. Uflex represents the backward-integrated model extending into adhesive compounding operations.
| Leading Market Players |
|---|
| Satyendra Packaging |
| Jindal Films |
| Cosmo Films |
| Flex Industries |
| SRF |
| Jindal Poly Films |
| Polyplex |
| GANPATI Films |
| Uflex |
| Others |
Supply & Pricing Matrix
The Dahej-Vadodara freight corridor compresses resin transport costs for western India extruders while amplifying price spreads against southern converters sourcing from Gujarat. This logistics differential feeds into a supply chain where captive petrochemical integration anchors margin stability for transparent grades, yet metallized and coated variants command premiums reflecting technical complexity and certification overhead.
Pricing Analysis
Geographic price spreads between Gujarat-based extruders and Karnataka-Tamil Nadu converters run 8-12% for standard transparent grades, reflecting rail freight and inventory carrying cost differentials. Three-tier pricing structure across premium, standard, and economy levels segments the market: metallized barrier films with oxygen transmission below 1.0 cc/m²/day sit at premium tiers, commodity 12-20 micron transparent films occupy standard bands, and distributor-mediated wholesale supply serves economy positioning. Pricing pressure stems from propylene feedstock volatility transmitting naphtha and propane cost swings directly to film extrusion margins. Mid-tier converters in Maharashtra demonstrate highest price sensitivity, while pharmaceutical blister manufacturers prioritize heat-seal performance and migration compliance over unit cost.
Supply Chain Analysis
Upstream polypropylene resin supply anchors in Saudi Arabia, South Korea, and domestic Reliance Industries output from Gujarat's Jamnagar complex. Film extrusion draws from propylene monomer, specialty masterbatch additives, and vacuum metallization aluminum feedstock. Single-source vulnerability concentrates in metallization equipment and coating chemistry imports, with European and Japanese suppliers dominating tenter frame and vacuum deposition technology. Distribution runs through direct mill contracting for certified volume buyers, distributor networks for secondary city converters, and emerging digital platforms for standardized grade procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts for heat-seal optimization and migration testing represent a service-attach opportunity expanding faster than base film tonnage, as FSSAI documentation requirements convert extruders into compliance partners.
For Market Incumbents: Harden defensible positioning through captive resin compounding investments that insulate margin structures from propylene volatility, while accelerating in-house analytical laboratory capacity to compress BIS certification cycle times against competitors relying on external testing. Prioritize pharmaceutical-grade cleanroom coating certifications as CDSCO requirements fragment supply qualification. For New Entrants and Emerging Players: Southern India converter demand in Tamil Nadu and Karnataka represents the most penetrable entry point, with regional extrusion investments capturing logistics cost premiums currently paid to western suppliers. Target pharmaceutical blister lidding as a qualification-intensive niche where coated-grade technical barriers limit commodity competition, deploying CDSCO-aligned technical service capabilities as primary go-to-market differentiation. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors metallization and coating specialists with pharmaceutical certification moats over transparent commodity extruders facing feedstock margin compression. Long-term viability hinges on mono-material recyclability alignment with Plastic Waste Management Rules enforcement trajectories. Watch BIS notification timelines for revised food-contact additive positive lists as inflection indicators for formulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Resin Compounding Integration | Reliance Industries feedstock access anchors margin stability for Gujarat-based extruders against import-dependent competitors. |
| Pharmaceutical Coating Certification | CDSCO drug master file alignment opens blister lidding segments beyond commodity snack film competition. |
| Southern India Extrusion Capacity | Tamil Nadu and Karnataka regional supply reduces logistics premiums currently paid to western India producers. |
| In-House Analytical Laboratory Investment | BIS third-party testing mandates compress certification cycles for extruders with internal heavy metal and migration analysis capability. |
| Mono-Material Recyclability Positioning | Central Pollution Control Board EPR frameworks favor BOPP over multi-polymer laminates in brand owner sourcing decisions. |
Research Methodology
Two parallel data streams informed the analysis: primary engagement with polymer processing executives, flexible packaging procurement leads at ITC and Parle, CDSCO regulatory affairs specialists, and BIS certification laboratory directors; alongside secondary validation through customs trade data, FSSAI notification registers, SEC filings from listed film producers, and Plastic Waste Management Rules implementation circulars. Bottom-up extrusion capacity modeling and top-down converter demand estimation were triangulated against petrochemical feedstock flow analysis.
Forecast inputs considered product type segmentation across transparent, metallized, matte, and coated grades; end-use fragmentation between food packaging, labeling, consumer goods, and medical applications; thickness tier adoption curves; and distribution channel evolution toward direct contracting. CAGRs were derived from elasticity-adjusted demand projections and capacity expansion announcements across the analysis window. Industry-specific inputs incorporated BIS certification timeline assumptions and PLI scheme incentive trajectories for specialty chemicals.
Macroeconomic conditions sit as an overlay; deviation in crude-linked naphtha pricing, monsoon logistics disruption severity, or BIS implementation pace would shift the trajectory. Forecasts reflect documented assumptions about feedstock cost transmission and regulatory enforcement intensity. Cross-checking against Central Pollution Control Board EPR registration data and FSSAI food-contact approval databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Starch-Based Plastic Films Market
Poly film
Global Reclosable Films Market
Poly film
Polyethylene Furanoate Films Market
Poly film
Poly Coated Paper Market
Poly film
Formable Films Market
Poly film
Polycoated Packaging Market
Poly film
Foamed Polypropylene Films Market
Poly film
Polyethylene Film Market
Poly film
Polymer Dispersed Liquid Crystal (PDLC) Film Market
Poly film
Resealable Films Market
Poly film
PVC Films Market
Poly film
High Density Polyethylene Film Market
Poly film
Soft Touch Lamination Film Market
Poly film
Polymer Waterproof Rolls Market
Poly film
Australia and New Zealand Plastic Packaging Film Market
Poly film
Europe Ethylene-Vinyl Alcohol Copolymer (EVOH) Packaging Films Market