
 Spouted Pouches Market | 2026-2036
Spouted Pouches Market Size, Share, and Industry Trends Forecast 2026-2036
Spouted Pouches Market Analytics
Asset-light contract manufacturing and third-party pouch converting partnerships is reconfiguring competitive entry barriers for mid-sized food brands that lack in-house filling lines. Amcor plc leverages its integrated film-to-pouch supply chain to sustain cost leadership across European retail private-label programs. Mondi Group anchors its position through specialty kraft-paper laminate expertise that meets emerging fiber-content mandates. ProAmpac competes by dominating short-run custom printing for regional craft food startups.
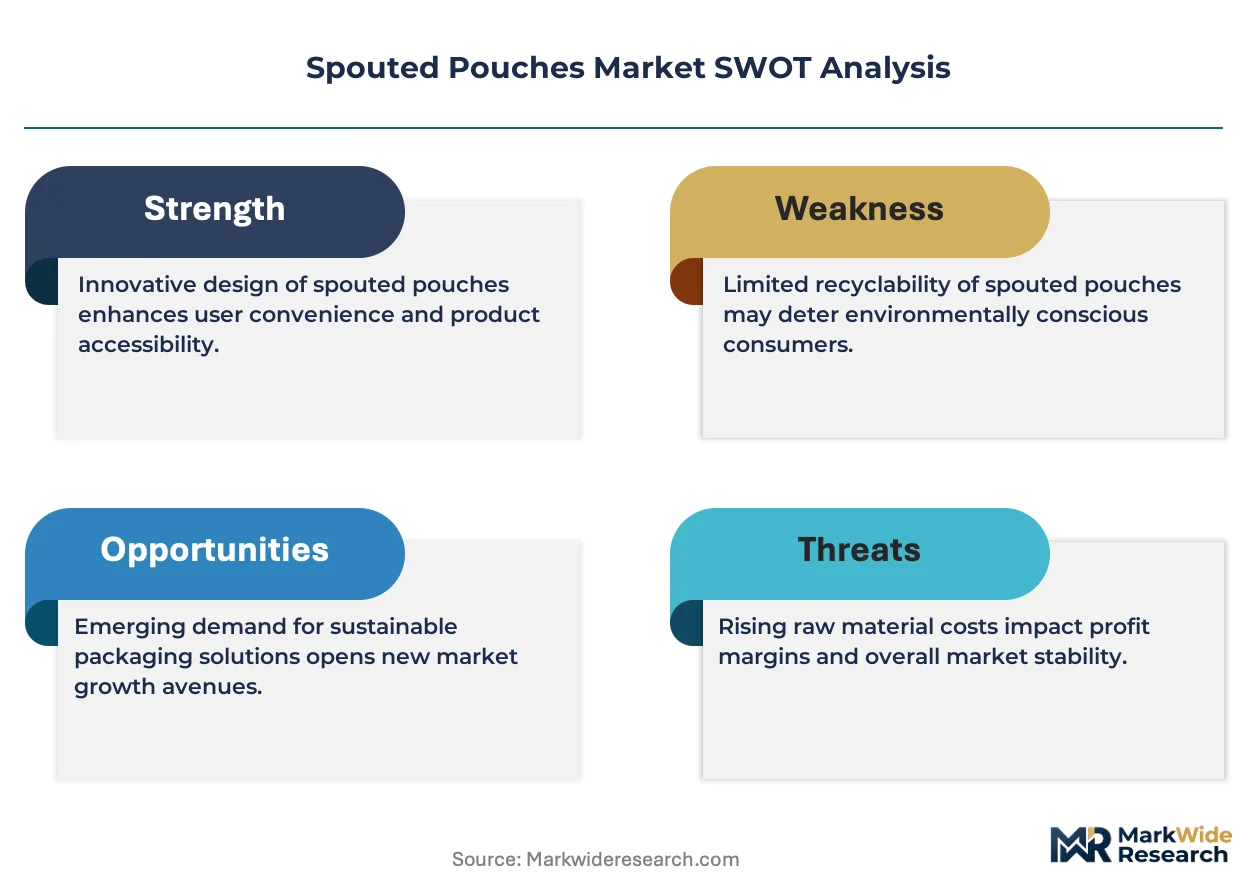
Spouted pouches are flexible laminated containers incorporating a welded dispensing fitment, typically constructed from coextruded PE or PP films with oxygen-barrier layers, designed for single-hand dispensing of liquids, semi-solids, or flowable powders. Stand-up pouch configurations with bottom gussets occupy the largest volume share due to shelf stability and retail visibility, though flat pouch formats are gaining traction in pharmaceutical unit-dose applications where shipping cube efficiency matters. Plastic mono-material structures lead material demand as recyclability protocols tighten, while metalized films sustain premium cosmetic and retort-food segments where extended shelf life commands price premiums.
FDA food-contact substance regulations and EU REACH compliance frameworks govern adhesive and ink chemistries in North American and European supply chains, directly influencing converter qualification timelines and raw-material substitution rates. The EU Packaging and Packaging Waste Regulation (PPWR) recyclability targets are forcing redesign of multi-layer barrier constructions toward compatible polymer families. Stakeholders must monitor evolving extended-producer-responsibility fee structures and state-level recycled-content mandates to anticipate which material platforms will retain cost competitiveness.
Market Dynamics
EU PPWR recyclability mandates and the EU Single-Use Plastics Directive are forcing immediate material redesign across converter supply chains, compressing qualification timelines and elevating mono-material PE and PP platforms over legacy multi-layer barrier constructions.
Growth Catalysts
- Regulatory Compliance Deadlines:The EU Packaging and Packaging Waste Regulation recyclability targets are accelerating converter investment in compatible polymer families and adhesive substitution programs ahead of enforcement windows.
- Logistics Cost Arbitrage:Food and beverage brands are capturing freight and warehousing savings by replacing rigid containers with flexible spouted formats that collapse when empty and cube more efficiently in outbound distribution.
- German Retail Format Standardization:Private-label baby food and organic puree brands in Germany have established spouted pouches as the default shelf presentation, creating template effects across European retail chains.
Market Restraints
- Resin Price Volatility:PE and PP feedstock exposure to naphtha and natural gas liquids creates margin compression for converters locked into annual pricing contracts with CPG customers.
- Barrier Performance Trade-offs:Mono-material structures sacrifice oxygen and moisture protection versus metalized or EVOH multi-layer alternatives, limiting penetration in retort and extended-shelf-life applications.
- Mechanical Recycling Infrastructure Gaps:Curbside collection and sortation systems in France, Italy, and Spain lack the optical and density separation capability to handle spouted pouch formats at scale.
Strategic Opportunities
- Pharmaceutical Unit-Dose Expansion:Flat pouch configurations with minimal headspace are displacing blister packs in liquid oral medications where shipping density and child-resistance drive specification.
- Paper-Fiber Hybrid Platforms:Emerging fiber-content mandates in France and the Netherlands are creating pull for kraft-paper laminate structures with thin polymer barrier layers.
- Short-Run Digital Printing:Regional craft food startups require 5,000-50,000 unit production runs with variable graphics, opening service-model differentiation for converters with HP Indigo or Xeikon installed capacity.
Industry Challenges
- Adhesive and Ink Chemistry Reformulation:FDA food-contact substance notifications and EU REACH compliance frameworks require 12-18 month validation cycles for new chemistries, delaying product launches.
- Fitment-Pouch Weld Integrity:High-speed rotary filling lines at 300+ pouches per minute stress the spout-to-laminate seal, demanding precise temperature and pressure control that narrows qualified equipment suppliers.
- Extended Producer Responsibility Fee Uncertainty:Evolving EPR fee structures in Germany, Italy, and the UK complicate pricing models and contract terms for multi-year supply agreements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spouted Pouches Market |
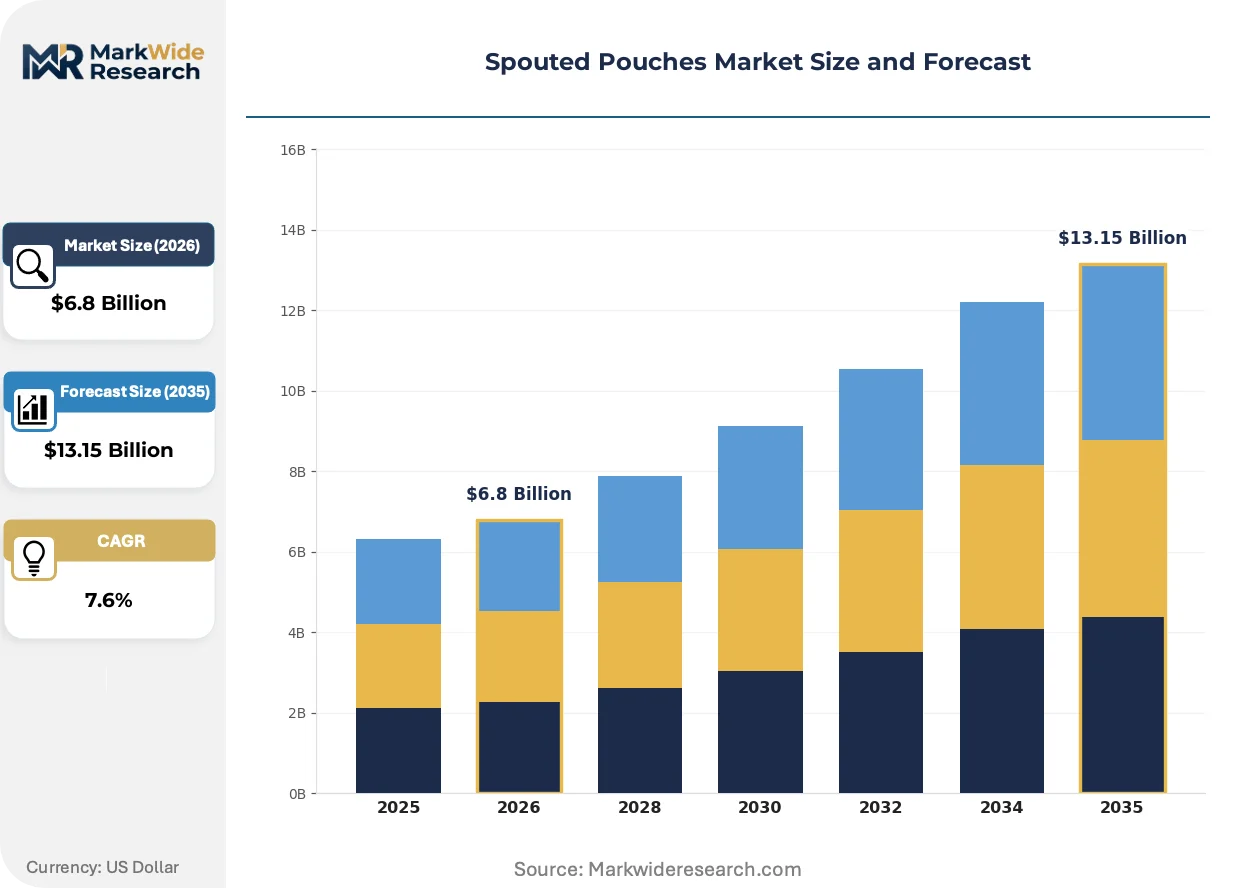
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
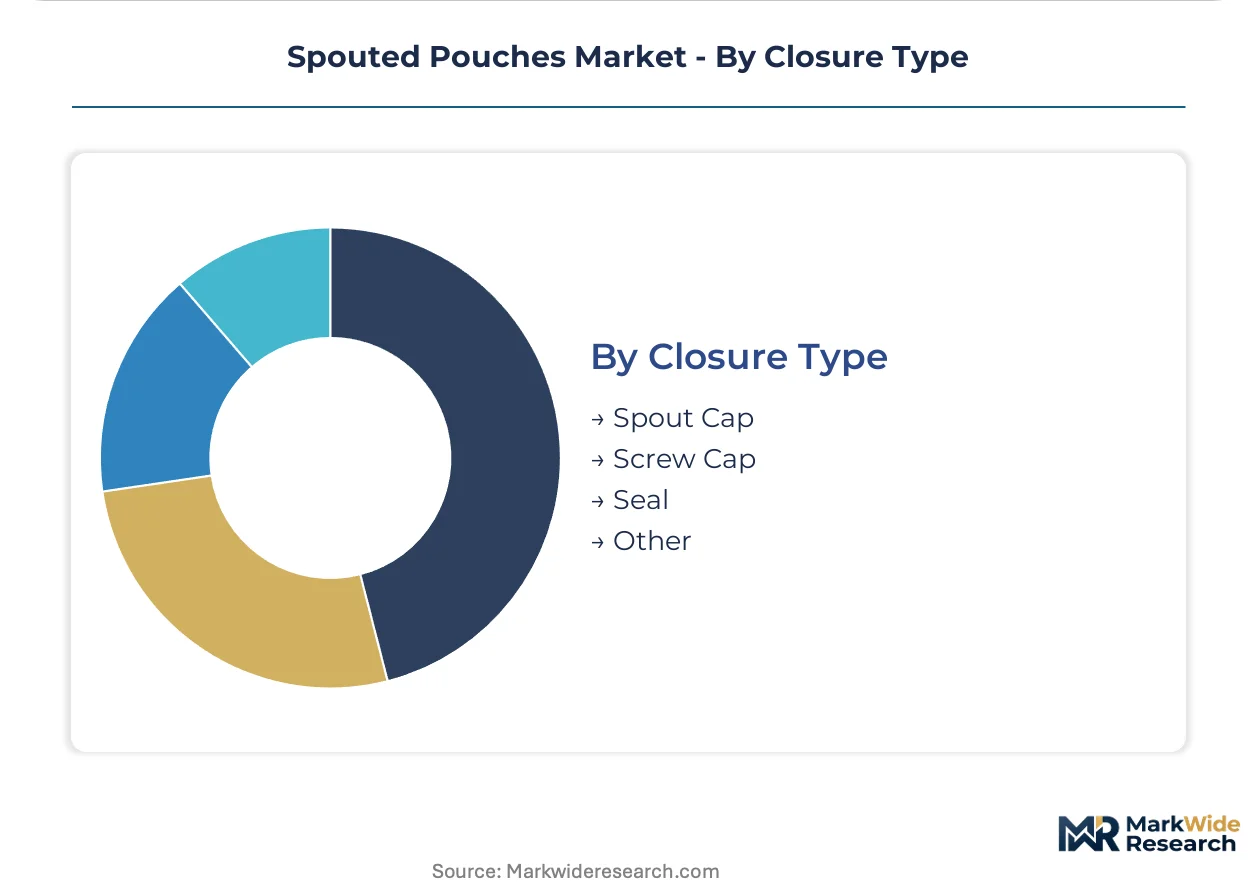
| Segmentation | Product Type: Stand-Up Pouches, Flat Pouches, Gusseted Pouches, Zipper Pouches Material: Plastic, Metalized Films, Paper, Composites End User: Food & Beverage, Personal Care, Pharmaceuticals, Household Products Closure Type: Spout Cap, Screw Cap, Seal, Other |
| Companies Covered | Amcor plc, Berry Global, Mondi Group, ProAmpac, Glenroy Inc., Sonoco Products Company, AptarGroup Inc., Gualapack S.p.A., Huhtamaki, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spouted Pouches Market Evolving Landscape
Digital workflow integration across pre-press, converting, and filling operations is collapsing lead times and enabling mass customization that was structurally impossible under analog plate-based production systems.
Digital printing with water-based or UV-curable inks is virtualizing the traditional gravure cylinder investment and plate-making timeline. Mid-sized organic food brands in Scandinavia and the Netherlands are adopting 72-hour turnaround specifications for seasonal promotions and limited-edition SKUs. This technology is virtualizing the minimum-economic-order-quantity constraint that historically locked out small brands from flexible packaging.
EU REACH restrictions on per- and polyfluoroalkyl substances are eliminating fluorinated grease-resistant treatments from paper-based spouted pouch constructions. Converters are substituting with clay-coated or bio-wax barrier layers that sacrifice some moisture protection but maintain regulatory compliance. Premium pet food and cosmetic segments in Germany and Austria are absorbing the 8-12% material cost premium to retain fiber-content marketing claims.
CPG procurement teams are unbundling film extrusion, pouch converting, and filling operations that were historically captive within integrated manufacturers. This fragmentation is creating intermediary specification roles for third-party packaging engineers who audit weld integrity, barrier performance, and recyclability claims. The phenomenon is most visible in UK and Irish contract manufacturing arrangements where asset-light brand owners outsource entire supply chain management.
Spouted Pouches Market Segmentation
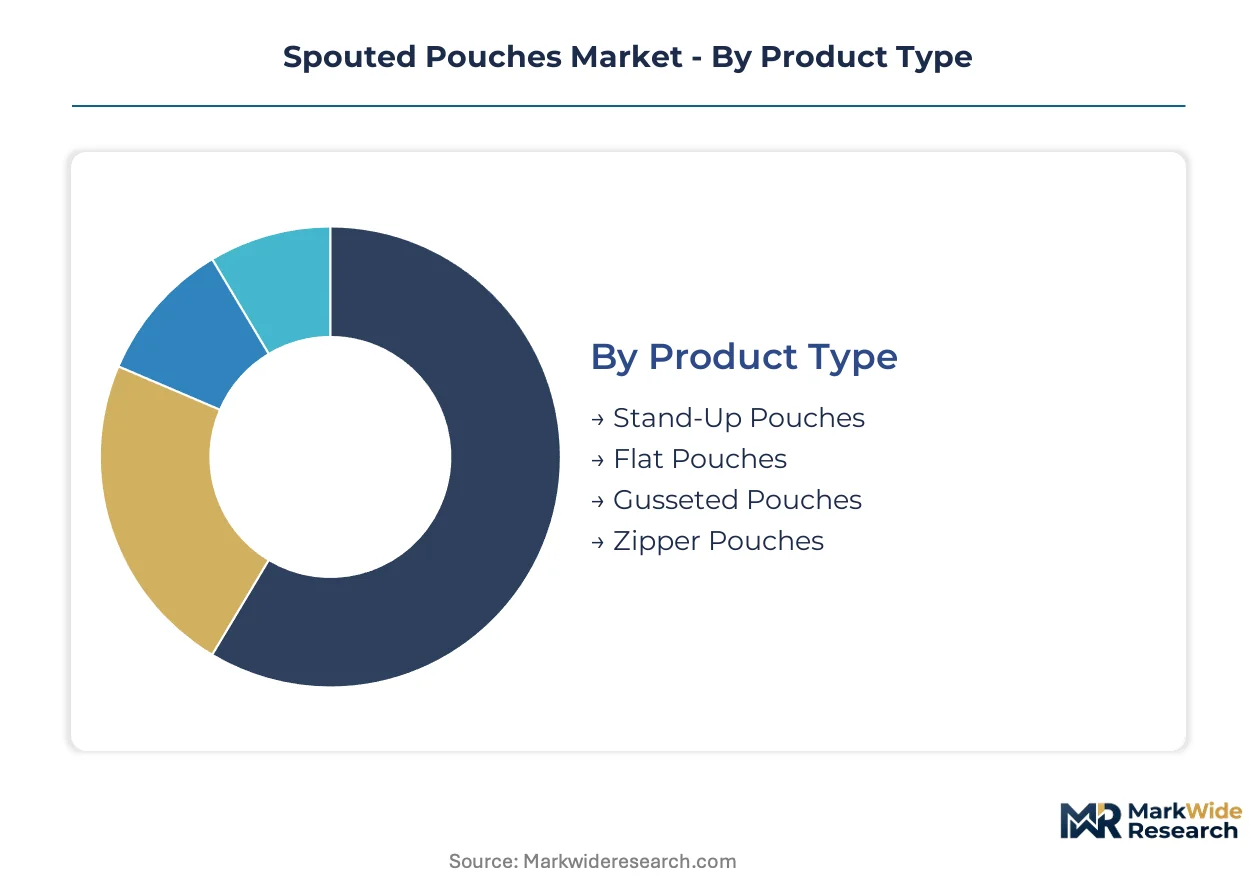
Spouted pouch configurations diverge sharply across retail visibility requirements, barrier performance needs, and regulatory compliance burdens. Material platforms and closure mechanisms further stratify the competitive landscape, with mono-material recyclability mandates reshaping investment priorities across converter supply chains.
Product Type:
Stand-up formats dominate shelf-stable retail applications where vertical presentation drives purchase conversion, while flat and gusseted variants serve specialized logistics and dispensing requirements.
- Stand-Up Pouches:Bottom-gusseted structures with welded spout fitments provide vertical shelf stability and 360-degree print branding surface. German and Austrian organic puree brands have standardized this format as the default retail presentation, compressing specification cycles for private-label entrants.
- Flat Pouches:Minimal-headspace configurations optimize shipping cube density and displace blister packs in liquid oral medications where child-resistance and unit-dose accuracy command priority. Pharmaceutical procurement in Switzerland and the Netherlands is expanding specifications for this format.
- Gusseted Pouches:Side-seal expansions accommodate bulk dry goods and flowable powders with improved fill volumes versus standard stand-up geometries. Industrial chemical and agricultural supplement segments in Belgium specify these for refill and institutional channels.
- Zipper Pouches:Reclosable interlocking tracks layered beneath the spout fitment enable multi-use dispensing for premium cosmetic and personal care applications. French skincare brands absorb the 15-20% cost premium to support sustainability marketing claims around product preservation.
Established volume favors stand-up configurations; emerging adoption favors flat pouch geometries.
Material:
Barrier performance requirements and recyclability mandates create divergent cost-technology trade-offs across converter investment programs.
- Plastic:Coextruded PE and PP mono-material structures dominate volume as EU PPWR recyclability deadlines force abandonment of incompatible multi-layer constructions. Oxygen barrier limitations constrain penetration in retort applications.
- Metalized Films:Aluminum oxide or metallized PET layers deliver extended shelf life for premium pet food and cosmetic segments where 12-18 month stability commands price premiums. German and Austrian brands sustain this specification despite limited mechanical recycling pathways.
- Paper:Kraft-paper laminates with thin polymer barrier layers satisfy emerging fiber-content mandates in France and the Netherlands. Clay-coated barrier substitutions replace fluorinated grease-resistant treatments eliminated under EU REACH restrictions.
- Composites:Hybrid structures combining fiber webs with biopolymer seal layers target compostable certification for organic food and specialty agricultural markets. Italian and Spanish converters pilot these for regional brand differentiation.
Plastic mono-materials capture mainstream volume; paper-fiber hybrids are climbing the fastest.
End User:
Regulatory stringency and dispensing ergonomics shape specification divergence across consumer and institutional channels.
- Food & Beverage:Single-hand dispensing of purees, sauces, and ready-to-drink formulations drives the largest addressable volume. Baby food and organic smoothie brands in Germany have made spouted pouches the default retail format, creating template effects across European chains.
- Personal Care:Shampoo, conditioner, and lotion applications prioritize reclosable fitments and premium tactile substrates. Scandinavian brands specify matte-laminate finishes with soft-touch varnishes to support shelf differentiation.
- Pharmaceuticals:Unit-dose liquid medications and oral suspensions require child-resistant closures and precise dose metering. Swiss and Dutch regulators enforce tamper-evident standards that narrow qualified converter pools.
- Household Products:Concentrated detergents, cleaning solutions, and automotive fluids demand chemical resistance and high-temperature fill compatibility. UK contract manufacturers specify these for private-label hard-surface cleaner programs.
Food and beverage commands installed capacity; pharmaceutical applications are gaining share fastest.
Closure Type:
Dispensing ergonomics, reclosability requirements, and regulatory child-resistance standards stratify fitment specification across end-use segments.
- Spout Cap:Snap-fit polyethylene closures with tethered lids provide single-hand operation for on-the-go consumption. Food and beverage brands in Germany and the Netherlands standardize this geometry for 100-250ml puree and smoothie formats.
- Screw Cap:Threaded polypropylene fitments enable secure reclosure for multi-use personal care and household chemical applications. French cosmetic brands specify these for shampoo and body wash refills.
- Seal:Peelable foil or membrane barriers beneath over-caps provide tamper evidence and extended shelf life for pharmaceutical and premium food segments. Swiss pharmaceutical packaging regulations mandate this configuration for liquid oral doses.
- Other:Specialized fitments including dosing pumps, spray actuators, and precision nozzles serve niche industrial and medical applications. Belgian and Dutch agricultural chemical distributors specify these for concentrated fertilizer and pesticide formulations.
Spout cap configurations dominate unit volume; screw cap specifications are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in spouted pouches tilt toward net-exporting converters in Germany and Austria, while import-dependent markets in Southern and Eastern Europe source specialized barrier films from Swiss and Dutch suppliers. Regional specialization clusters around regulatory compliance capabilities and retail format standardization.
Germany
Private-label baby food and organic puree brands have entrenched stand-up spouted pouches as the default retail format, compressing specification cycles for new entrants. The national packaging regulator enforces strict extended producer responsibility fee structures that favor mono-material PE constructions. The Baden-Württemberg converter cluster around Stuttgart specializes in high-speed rotary filling line integration for 300+ pouches per minute output.
France
Personal care brands specify reclosable zipper pouches with matte-laminate finishes, absorbing 15-20% cost premiums for sustainability marketing claims. ANSM and environmental agencies enforce emerging fiber-content mandates that pull converters toward kraft-paper laminate structures. The Lyon-Auvergne-Rhône-Alpes corridor hosts specialty converters piloting clay-coated barrier layers to replace fluorinated treatments banned under EU REACH.
Netherlands
Pharmaceutical procurement in Amsterdam and Rotterdam expands flat pouch specifications for unit-dose liquid medications where shipping density commands priority. The Dutch national environmental agency enforces optical sortation infrastructure requirements that shape material platform selection. The Eindhoven-Tilburg converting belt concentrates digital printing capacity for 5,000-50,000 unit short runs serving regional craft food startups.
Switzerland
Swissmedic regulations mandate tamper-evident seal configurations for liquid oral doses, narrowing qualified converter pools to barrier-film specialists. Premium pet food and cosmetic segments sustain metalized film specifications despite limited mechanical recycling pathways. The Basel-Zürich corridor anchors cross-border supply chains serving German and Austrian brand owners with extended-shelf-life barrier constructions.
United Kingdom
Contract manufacturing arrangements in the UK and Ireland fragment film extrusion, pouch converting, and filling operations historically captive within integrated manufacturers. Evolving EPR fee structures complicate multi-year supply agreement pricing models. The Midlands packaging belt specializes in third-party engineering audits of weld integrity and recyclability claims for asset-light brand owners.
Spouted Pouches Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in film extrusion, fitment molding, and adhesive formulation. The vendor base stratifies across three tiers: integrated multinationals with captive film-to-pouch supply chains, regional converters with specialty barrier expertise, and digital-native shops serving short-run custom segments. Dominant competitive moves include strategic partnerships between brand owners and third-party packaging engineers, plus capacity expansion in mono-material PE and PP platforms ahead of EU PPWR enforcement windows.
Among integrated packaging specialists, Amcor plc and Mondi Group occupy positions that exemplify divergent strategic archetypes. Amcor leverages film-to-pouch supply chain integration to sustain cost leadership across European retail private-label programs. Mondi anchors its competitive position through specialty kraft-paper laminate expertise aligned with fiber-content mandates in France and the Netherlands. ProAmpac sits within the short-run custom tier, competing through digital printing capacity for regional craft food startups requiring rapid turnaround specifications.
| Leading Market Players |
|---|
| Amcor plc |
| Berry Global |
| Mondi Group |
| ProAmpac |
| Glenroy Inc. |
| Sonoco Products Company |
| AptarGroup Inc. |
| Gualapack S.p.A. |
| Huhtamaki |
| Others |
Value Network & Pricing Analysis
EU PPWR recyclability deadlines compressing converter qualification timelines determine both pricing tier spreads and supply chain shape, forcing rapid substitution of legacy multi-layer barrier constructions toward mono-material PE and PP platforms that trade barrier performance for regulatory compliance.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing across European private-label programs, with three-tier pricing structure across premium, standard, and economy levels differentiated by barrier performance grade and volume scale commitments. Cost compression in standard-tier mono-material constructions is intensifying because resin price volatility tied to naphtha and natural gas liquids feedstock exposure strains converters locked into annual pricing contracts. Private-label baby food brands exhibit highest price sensitivity, while premium cosmetic and pharmaceutical segments absorb material cost premiums for metalized film specifications.
Supply Chain Analysis
Contract manufacturing concentration in Germany, Austria, and the Netherlands holds capacity for high-speed rotary filling line integration and digital short-run production. Raw material dependencies draw from PE and PP resin extrusion, oxygen-barrier adhesive formulations, and precision-molded spout fitments. Single-source vulnerability concentrates in qualified equipment suppliers capable of 300+ pouches per minute weld integrity. Distribution runs through converter-direct relationships with retail private-label programs and third-party packaging engineering audits for asset-light brand owners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against rigid container formats that retain barrier performance advantages in retort and extended-shelf-life applications, requiring incumbents to articulate clear total-cost-of-ownership economics to procurement teams.
For Market Incumbents: Insulate market position through captive film-to-pouch supply chain integration that sustains cost leadership against fragmented contract manufacturers, while accelerating mono-material platform R&D to preempt EU PPWR enforcement windows that threaten multi-layer barrier product lines. Prioritize certification investment in FDA food-contact substance notifications and EU REACH compliance to narrow qualified competitor pools. For New Entrants and Emerging Players: Pursue pharmaceutical unit-dose flat pouch specifications in Switzerland and the Netherlands where tamper-evident mandates and shipping density requirements create specification gaps underserved by incumbent food-focused converters. Target short-run digital printing capacity for Scandinavian craft food startups requiring 72-hour turnaround seasonal promotions as the most penetrable service-model entry point. For Investors and Strategic Acquirers: EU PPWR recyclability targets reshape the acquisition landscape toward converters with demonstrated mono-material PE and PP qualification timelines and installed digital printing capacity. Long-term viability across the analysis window favors specialty barrier-film expertise that can pivot toward paper-fiber hybrid platforms as fiber-content mandates expand. Watch optical sortation infrastructure deployment progress in France, Italy, and Spain as the signal indicating mechanical recycling pathway viability for spouted pouch formats.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Platform Conversion | EU PPWR compliance deadlines force abandonment of incompatible multi-layer constructions ahead of enforcement windows. |
| Digital Printing Capacity Expansion | HP Indigo and Xeikon installations capture regional craft food startup demand for 5,000-50,000 unit short runs. |
| Paper-Fiber Hybrid R&D Investment | France and Netherlands fiber-content mandates pull converters toward kraft-paper laminate structures with thin polymer barriers. |
| Pharmaceutical Unit-Dose Certification | Swissmedic and Dutch regulations mandate tamper-evident seals that narrow qualified converter pools. |
| Third-Party Engineering Audit Services | UK and Irish contract manufacturing fragmentation creates intermediary specification roles for packaging engineers. |
Research Methodology
The analysis maps spouted pouch configurations, material platforms, closure mechanisms, and end-use segments, each validated through converter operations directors, CPG procurement leads, packaging engineers, and retail category buyers. Primary interview findings triangulate against secondary sources including EU regulatory filings, customs and trade data, SEC 10-K disclosures from listed packaging multinationals, and industry association technical reports. Bottom-up volume modeling across product type, material, end user, and closure type dimensions reconciles with top-down market sizing.
Assumptions held fixed include EU PPWR enforcement timelines and existing mechanical recycling infrastructure capabilities, while variables include resin price volatility trajectories and optical sortation deployment rates across member states. Segmentation dimensions modeled encompass product configuration, material platform, end-use industry, closure mechanism, and regional regulatory cluster. CAGRs derive from segment-level volume projections calibrated to historical substitution rates of rigid containers by flexible formats. Industry-specific inputs include rotary filling line capacity utilization rates and adhesive chemistry reformulation validation cycles.
Sensitivities concentrate around EU PPWR implementation timing, optical sortation infrastructure deployment in Southern Europe, and resin feedstock price volatility. Forecasts reflect documented assumptions regarding regulatory enforcement and recycling pathway development. Quarterly review of converter qualification timelines and EPR fee structure announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Retort Pouch Packaging Market
Pouch
2 Seal Pouches Market
Pouch
Box Pouch Market
Pouch
Middle East and Africa Pouch Packaging Market
Pouch
Utility Pouches Market
Pouch
Open Mouth Sacks Market
Pouch
North America Stand-Up Pouch Packaging Market
Pouch
Flexible Plastic Pouches Market
Pouch
PPWR-Compliant Recyclable PE/PP Stand-Up Pouch Recycling Systems Market
Pouch
Rice Paper Stand Up Pouch Market
Pouch
Dual-Chamber Pouches Market
Pouch
Foil Pouch Packaging Market
Pouch
Child Resistant Single Dose Pouches Market
Pouch
OPP Pouches Market
Pouch
Vietnam Pouch Packaging Market
Pouch
Inflatable Pouches Market