
 PE Foam Films Market | 2026-2036
PE Foam Films Market Size, Share, and Industry Trends Forecast 2026-2036
PE Foam Films Market Outlook
Polymer chemist availability is collapsing across European foam converting hubs, forcing producers to automate batch formulation or relocate technical operations. POLY TECH -Verpackungen GmbH leverages its German manufacturing base to sustain specialized roll foam output for automotive tier-one suppliers. Pregis competes through North American packaging solutions scale, while Supreme Industries anchors Indian demand with construction insulation films tailored to tropical climates.
PE foam films are closed-cell polyethylene extrusions, typically manufactured through blown or cast foam processes with densities ranging from 25 to 150 kg/m³, engineered for cushioning, thermal insulation, and surface protection across industrial supply chains. Sheet foam dominates margin pools in electronics protection where anti-static grades command premium positioning, while roll foam sustains volume leadership in packaging solutions through distributor-driven replenishment cycles. Custom shapes represent the fastest-growing product type as medical device and aerospace contractors adopt CNC-cut foam inserts for precision fitment.
The EPA governs volatile organic compound emissions from foam extrusion facilities in the United States, while REACH and RoHS constrain plasticizer and additive chemistry across European supply chains. BIS certification requirements in India create compliance friction for imported PE foam films, redirecting procurement toward domestic extruders. Stakeholders must monitor how evolving extended producer responsibility frameworks reshape recycling infrastructure investments and raw material sourcing strategies.
Market Dynamics
Automotive OEMs in Germany's Stuttgart corridor are consolidating cushioning specifications around lower-density PE foam formulations, compressing supplier margins while accelerating batch automation investments across European converting hubs.
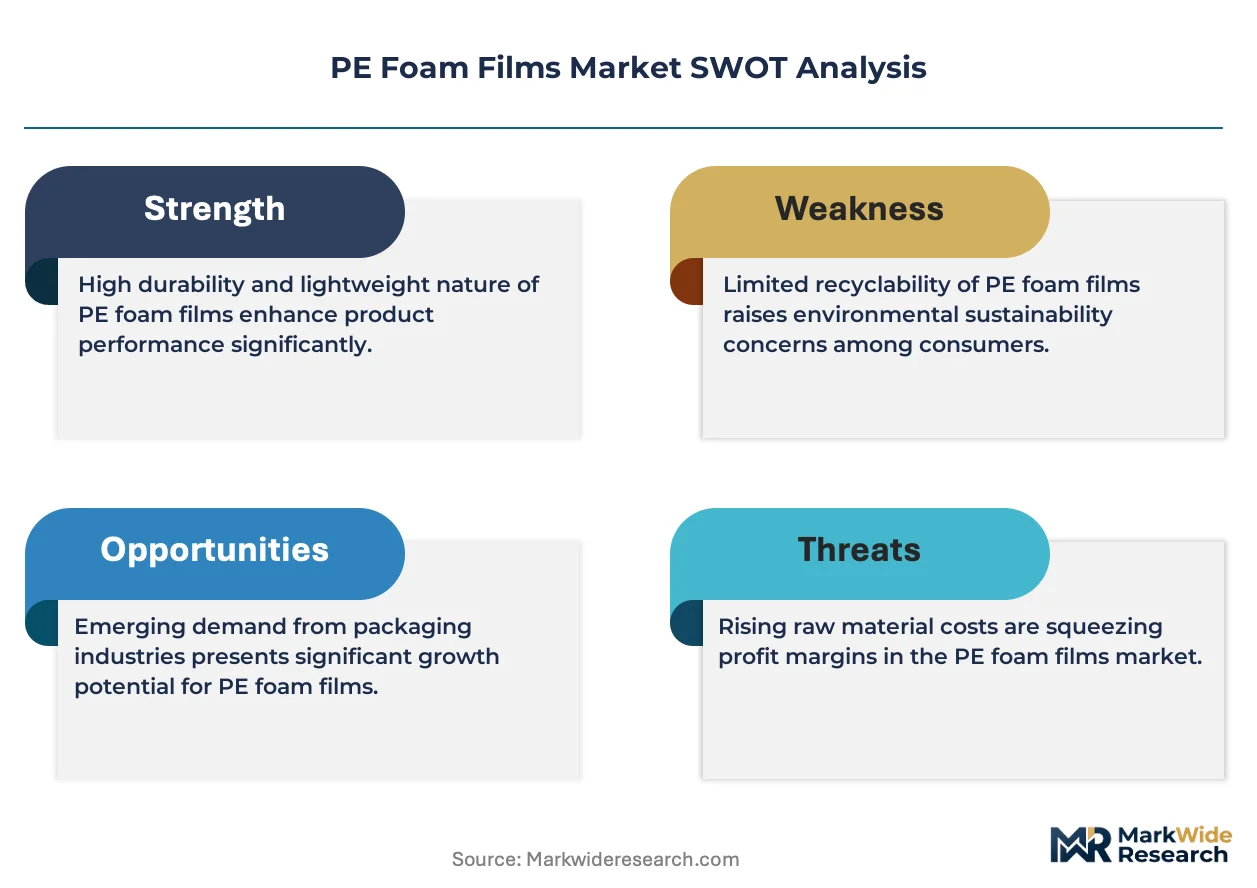
Growth Catalysts
- REACH low-emission mandates:ECHA pressure on volatile organic compounds is pulling converters toward water-blown extrusion systems and eliminating legacy azo-based blowing agents from automotive interior supply chains.
- Electronics protection demand:Anti-static PE foam grades are penetrating semiconductor packaging workflows as chip fabricators in Taiwan and South Korea tighten electrostatic discharge protocols for wafer shipment.
- Medical device precision fitment:CNC-cut foam inserts are displacing thermoformed trays in orthopedic implant kits as contract manufacturers seek customizable cushioning geometries without tooling lead times.
Market Restraints
- Ethylene feedstock volatility:Naphtha-cracker margins in Rotterdam and Singapore are transmitting price swings directly to foam film converters, destabilizing six-month supply agreements with automotive tier-ones.
- Polymer chemist scarcity:European foam formulation expertise is concentrating at three German technical universities, creating recruitment bottlenecks for mid-scale extruders seeking batch consistency engineers.
- Polypropylene substitution in thermal insulation:Biaxially oriented PP foam is capturing cold-chain packaging share from PE films in refrigerated logistics applications where moisture resistance outweighs cushioning requirements.
Strategic Opportunities
- Indian construction insulation:BIS certification barriers for imports are creating captive demand for domestic PE foam film extruders serving Mumbai and Bangalore infrastructure projects with tropical-climate formulations.
- EU Green Deal circularity incentives:Extended producer responsibility frameworks are subsidizing chemical recycling investments for post-industrial foam scrap, opening margin recovery pools for vertically integrated converters.
- Aerospace precision logistics:Satellite component handlers are specifying CNC-machined PE foam cradles for cleanroom transport, displacing legacy polyurethane systems in high-value payload protection.
Industry Challenges
- Multi-jurisdiction certification timelines:Simultaneous EPA VOC compliance, REACH substance registration, and BIS mark acquisition are extending product qualification cycles for exporters serving automotive and medical verticals.
- Legacy extrusion asset retrofitting:Converting cast foam lines to blown foam capability for thinner-gauge electronics films demands seven-figure capital commitments with uncertain payback periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PE Foam Films Market |
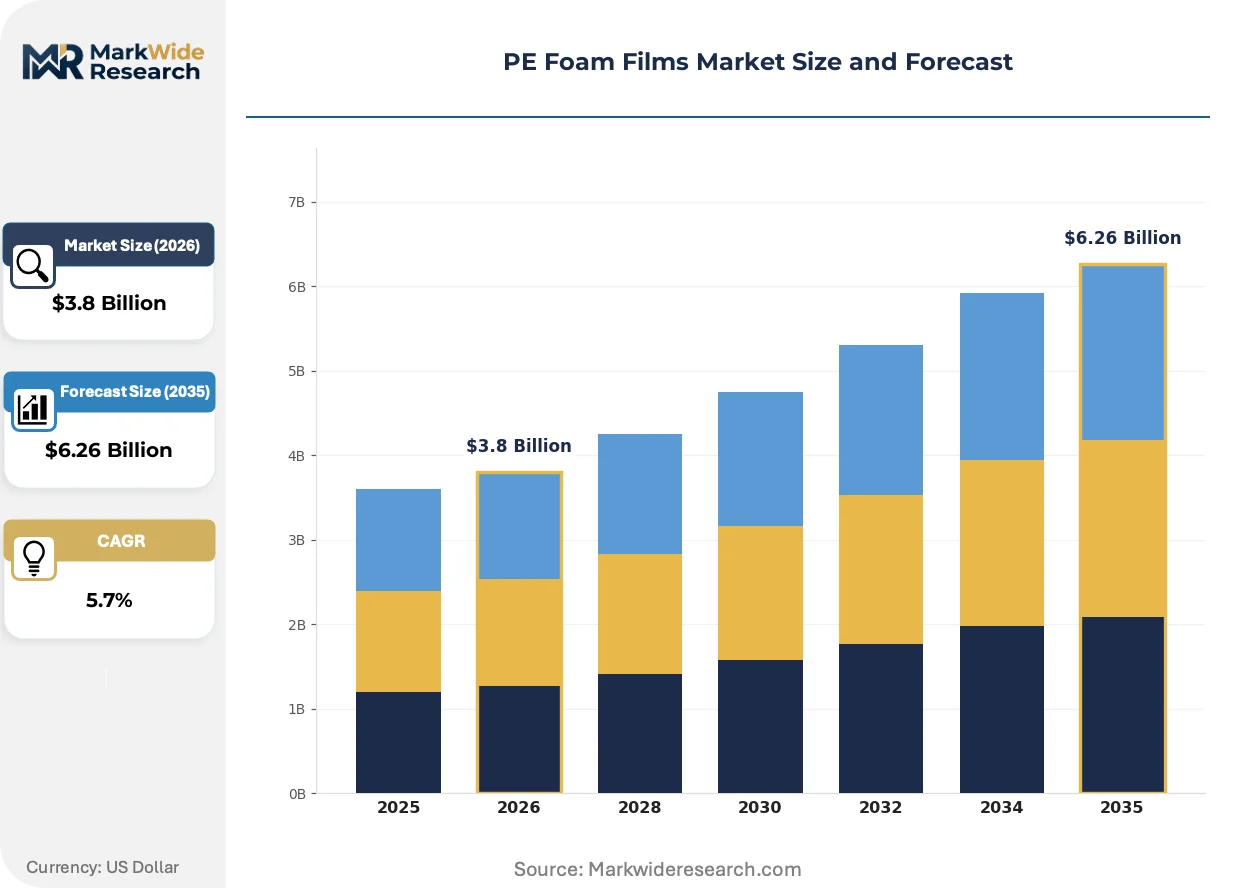
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Continuous Foam, Sheet Foam, Roll Foam, Custom Shapes Application: Automotive Interiors, Packaging Solutions, Construction Insulation, Electronics Protection End User: Manufacturers, Distributors, Contractors, Retailers Thickness: Thin, Medium, Thick, Extra Thick |
| Companies Covered | POLY TECH -Verpackungen GmbH, Pregis, Supreme Industries, Essen Multipack, Komex, Ailena, JSC Komex, Pioneer Enterprises, SJ ENTERPRISES, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PE Foam Films Market Strategic Shifts
Extrusion technology and regulatory chemistry are converging to redefine material specifications across cushioning applications, with automation and sustainability mandates compressing traditional formulation-development cycles.
Physical foaming with supercritical CO2 is displacing chemical blowing agents in high-volume automotive interior production, with Stuttgart-based tier-one suppliers qualifying the process for headliner and door-panel substrates. The technology is miniaturizing cell structures to sub-50-micron diameters, enabling 15% density reductions without sacrificing compression-set performance.
EPA enforcement of National Emission Standards for Hazardous Air Pollutants is tightening volatile organic compound limits at US foam extrusion facilities, forcing capital deployment into thermal oxidizers and closed-loop solvent recovery. Midwestern packaging converters serving appliance manufacturers are absorbing the steepest compliance costs, accelerating consolidation toward integrated resin-to-film operations with captive emission controls.
Consolidated procurement desks at German automotive OEMs are compressing supplier panels from twelve foam film vendors to three approved partners per interior subsystem, centralizing volume allocation and technical collaboration. Tier-one seating and trim suppliers are responding with dedicated account engineering teams co-located at Wolfsburg and Ingolstadt development centers, embedding formulation expertise directly into customer platforms.
PE Foam Films Market Segmentation
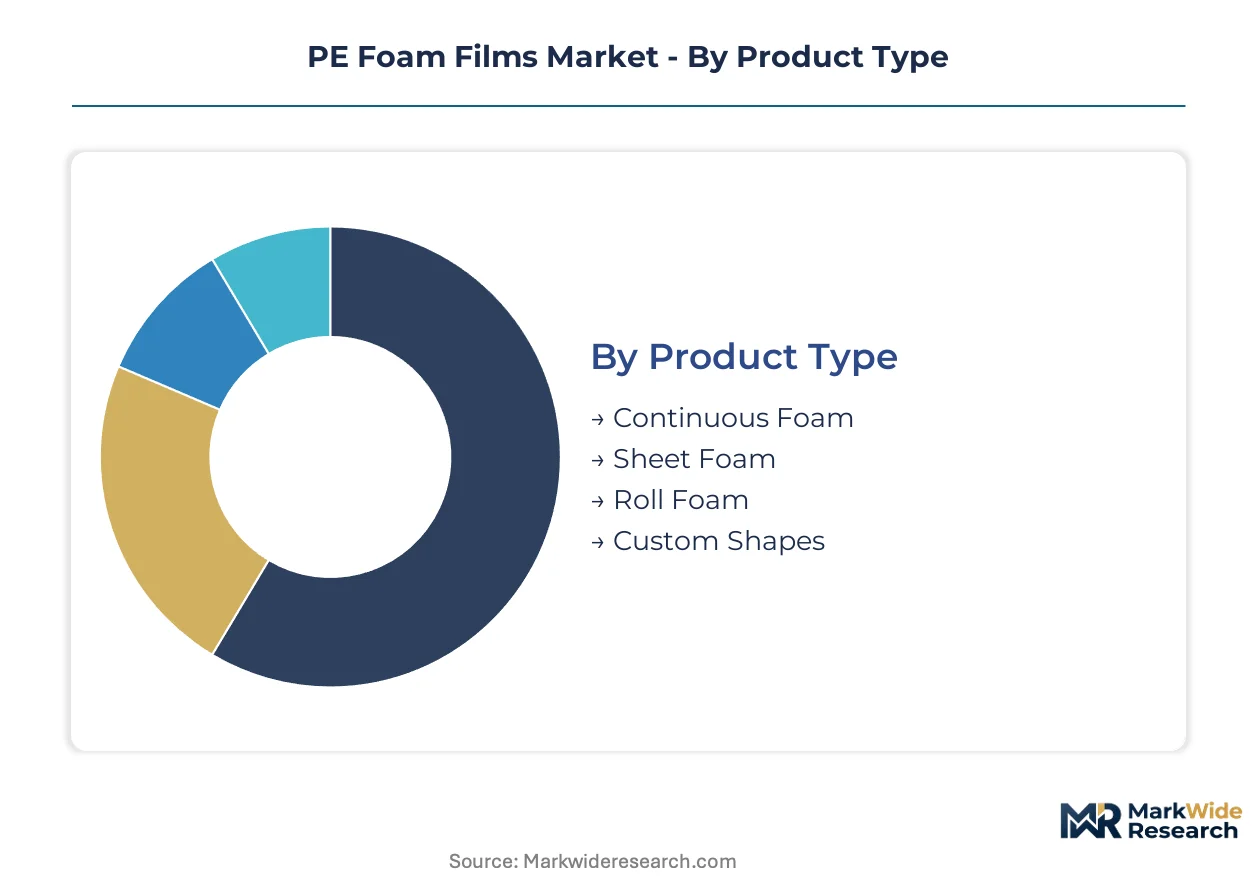
PE foam film segmentation reveals distinct margin architectures across form factors and customer interfaces. Product geometry and supply chain position determine vulnerability to polypropylene substitution and automation investment requirements.
Product Type:
Sheet foam and roll foam face diverging substitution pressures from biaxially oriented polypropylene in thermal applications, while custom shapes defend position through CNC machining barriers.
- Continuous Foam:Extruded in uninterrupted lengths for high-volume lamination and composite panel manufacturing. German automotive tier-ones around Stuttgart specify continuous foam for headliner substrates where REACH low-emission mandates favor water-blown extrusion systems.
- Sheet Foam:Flat-panel extrusions with thickness precision for die-cutting and thermoforming operations. Anti-static grades command premium positioning in Taiwan semiconductor packaging workflows where electrostatic discharge protocols are tightening.
- Roll Foam:Wound cylindrical formats optimized for automated packaging lines and rapid deployment. Distributor-driven replenishment cycles sustain volume leadership across North American appliance protection applications.
- Custom Shapes:CNC-machined or water-jet cut geometries for precision fitment. Medical device contractors in orthopedic implant kits adopt these for customizable cushioning without thermoforming tooling lead times.
Roll foam retains volume leadership; custom shapes hold the steepest expansion curve.
Application:
Automotive and electronics applications concentrate specification power with OEMs, while construction and packaging serve more fragmented procurement desks.
- Automotive Interiors:Door panels, headliners, and seating substrates requiring compression-set resistance. Wolfsburg and Ingolstadt development centers are consolidating supplier panels from twelve vendors to three approved partners per interior subsystem.
- Packaging Solutions:Surface protection and cushioning for consumer durables and industrial components. Midwestern US converters serving appliance manufacturers absorb the steepest EPA compliance costs for volatile organic compound emissions.
- Construction Insulation:Thermal and acoustic barriers for building envelopes. Mumbai and Bangalore infrastructure projects generate captive demand for domestic Indian extruders with tropical-climate formulations.
- Electronics Protection:Anti-static and conductive grades for semiconductor wafer shipment. South Korean chip fabricators are tightening electrostatic discharge protocols, pulling converters toward specialized masterbatch formulations.
Packaging solutions anchor volume; electronics protection delivers the most rapid specification upgrades.
End User:
Technical sophistication and formulation access separate manufacturer-direct relationships from distributor-mediated transactions.
- Manufacturers:Tier-one automotive seating suppliers and electronics contract assemblers with captive engineering teams. Co-location at customer development centers embeds formulation expertise directly into platform specifications.
- Distributors:Inventory-carrying intermediaries serving mid-scale packaging converters and construction contractors. Roll foam replenishment cycles concentrate margin recovery through volume rebates and logistics efficiency.
- Contractors:Installation-focused buyers in construction and renovation with price-sensitive procurement. Indian BIS certification barriers redirect procurement toward domestic extruders with established mark acquisition.
- Retailers:Private-label and branded packaging material resellers with limited technical specification involvement. Price competition intensifies as e-commerce fulfillment drives standardization of protective formats.
Manufacturers command formulation collaboration; distributors aggregate fragmented construction and packaging demand.
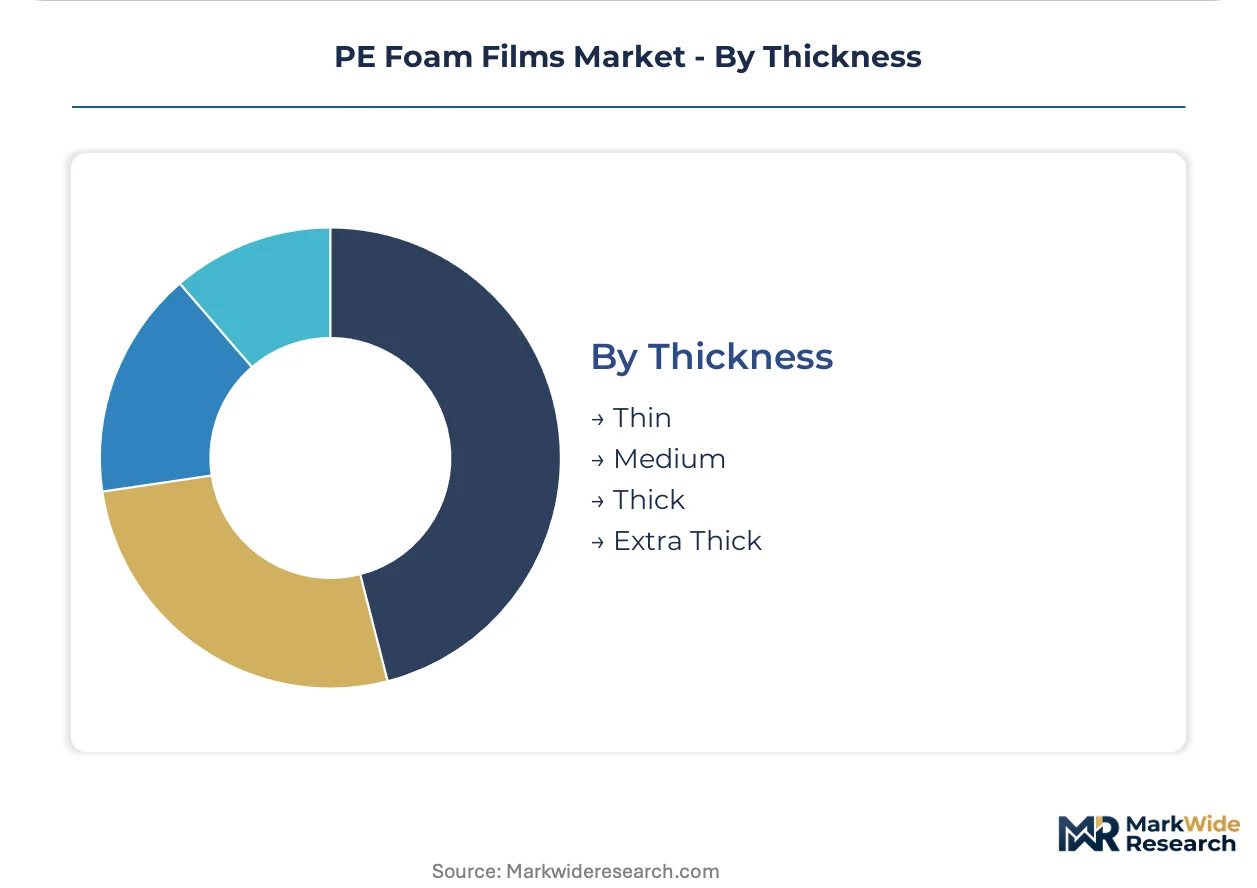
Thickness:
Thin-gauge segments compete with film laminates and non-wovens, while thick sections defend against structural foam and fiberboard.
- Thin:Sub-2mm gauges for surface protection films and lightweight cushioning. Electronics protection applications in Taiwan and South Korea drive specification toward sub-50-micron cell structures for density reduction without performance sacrifice.
- Medium:2-5mm range balancing flexibility and cushioning depth. Automotive interior laminations favor medium thickness for headliner and door-panel substrates where physical foaming with supercritical CO2 is displacing chemical blowing agents.
- Thick:5-10mm sections for impact absorption in appliance and furniture protection. Construction insulation in Indian tropical climates specifies thick foam for thermal performance where moisture resistance requirements are elevated.
- Extra Thick:Above 10mm for heavy-duty crating and aerospace payload protection. Satellite component handlers specify CNC-machined extra-thick cradles for cleanroom transport, displacing legacy polyurethane systems.
Medium thickness dominates automotive procurement; extra thick sections are climbing fastest in aerospace qualification pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes PE foam films primarily for automotive interior lamination, while India deploys identical material for tropical construction insulation—a consumption-mix differential that shapes formulation requirements and supply chain configuration across both markets.
Germany
Automotive tier-one suppliers around Stuttgart and Wolfsburg are consolidating supplier panels from twelve vendors to three approved partners per interior subsystem. ECHA REACH enforcement on volatile organic compounds is accelerating water-blown extrusion adoption for headliner substrates. Physical foaming with supercritical CO2 is qualifying at Ingolstadt development centers for 15% density reduction in door-panel applications.
United States
Midwestern packaging converters serving appliance manufacturers absorb the steepest EPA National Emission Standards for Hazardous Air Pollutants compliance costs. EPA enforcement is forcing capital deployment into thermal oxidizers and closed-loop solvent recovery systems. Chicago-area extrusion clusters are consolidating toward integrated resin-to-film operations with captive emission controls.
India
Mumbai and Bangalore infrastructure projects generate captive demand for domestic extruders with tropical-climate formulations. BIS certification requirements create compliance friction for imported PE foam films, redirecting procurement toward domestic suppliers with established mark acquisition. Construction contractors in Maharashtra and Karnataka specify thick-gauge foam for thermal performance where moisture resistance requirements are elevated.
South Korea
Semiconductor packaging workflows in Gyeonggi Province are tightening electrostatic discharge protocols for wafer shipment. Chip fabricators are pulling converters toward specialized anti-static masterbatch formulations. Seoul Capital Area electronics assemblers are qualifying sub-50-micron cell structures for density reduction without cushioning performance sacrifice.
Japan
Medical device contractors in the Kanto region are adopting CNC-cut foam inserts for orthopedic implant kits. METI standards for precision logistics are displacing thermoformed trays with customizable cushioning geometries that eliminate tooling lead times. Tokyo-area aerospace handlers are specifying CNC-machined cradles for satellite component cleanroom transport.
PE Foam Films Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in the PE foam films market, with scale advantages concentrated among resin-to-film operators and technical differentiation residing with formulation-focused converters. The vendor base separates into three strategic archetypes: German automotive-focused extruders with REACH-compliant water-blown systems, North American packaging-scale suppliers with distributor-driven replenishment networks, and Indian domestic players leveraging BIS certification barriers. Competitive moves center on backward integration into resin compounding and geographic co-location at customer development centers.
Among Germany-based specialists, POLY TECH -Verpackungen GmbH exemplifies the automotive-tier technical archetype, occupying a position within the Stuttgart supply corridor. Pregis represents the North American packaging-scale model, sitting within distributor-mediated volume channels. Supreme Industries anchors the India-domestic tier, exemplifying BIS-certified tropical-formulation capability. These three occupy distinct competitive spaces without direct overlap in customer specifications or geographic served markets.
| Leading Market Players |
|---|
| POLY TECH -Verpackungen GmbH |
| Pregis |
| Supreme Industries |
| Essen Multipack |
| Komex |
| Ailena |
| JSC Komex |
| Pioneer Enterprises |
| SJ ENTERPRISES |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements between German automotive tier-ones and Stuttgart corridor foam converters lock in supply access while anchoring price visibility against ethylene feedstock volatility from Rotterdam naphtha crackers. These contracts embed volume commitments with REACH-compliant water-blown formulations, insulating qualified suppliers from spot market turbulence while compressing margins for non-integrated extruders.
Pricing Analysis
Contract-based long-term offtake structures dominate automotive interior supply chains, with price differentiation hinging on REACH certification tier and volume scale commitments to Wolfsburg development centers. Cost compression in mid-density roll foam is intensifying because polypropylene substitution in cold-chain packaging is forcing PE converters to absorb ethylene price swings without pass-through mechanisms. Distributor-mediated packaging buyers exhibit the sharpest price sensitivity, while medical device contractors purchasing CNC-cut custom shapes tolerate premium positioning for precision fitment without tooling lead times.
Supply Chain Analysis
Strategic stockpile preferences concentrate among German automotive tier-ones buffering against REACH compliance bottlenecks, while just-in-time replenishment cycles dominate North American packaging distributors serving appliance manufacturers. Supply concentrates in Germany, the United States, and India, with raw material dependencies tethered to naphtha-derived ethylene, specialized anti-static masterbatches, and supercritical CO2 blowing agent systems. Single-source vulnerability from polymer chemist scarcity at German technical universities threatens batch consistency for mid-scale extruders. Distribution runs through resin-to-film integrated operators with captive emission controls and distributor networks carrying roll foam inventory for rapid deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as German automotive OEMs collapse supplier panels from twelve foam film vendors to three approved partners per interior subsystem, extracting formulation collaboration and co-location commitments from surviving converters.
For Market Incumbents: Consolidate backward integration into resin compounding to capture margin recovery from post-industrial foam scrap under EU Green Deal circularity incentives. Deepen co-location at Ingolstadt and Wolfsburg development centers to embed technical teams directly within customer platform specifications, defending against polypropylene substitution in thermal insulation applications. For New Entrants and Emerging Players: Precision logistics service gaps in aerospace satellite component handling present white-space opportunities where legacy polyurethane systems remain entrenched. Target Indian construction insulation with BIS-certified tropical-climate formulations for Mumbai and Bangalore infrastructure projects, leveraging certification barriers that redirect procurement from imports. Lead with CNC machining capabilities for medical device orthopedic implant kits, offering customizable cushioning geometries without thermoforming tooling investments. For Investors and Strategic Acquirers: Capital is best deployed toward resin-to-film integrated operators with captive emission controls and established REACH compliance infrastructure across the analysis window. Acquisition candidates should demonstrate qualified water-blown extrusion systems and dedicated account engineering teams at German automotive development centers. The signal to monitor is consolidation velocity in supplier panels at Stuttgart corridor OEMs, which indicates pricing power inflection for qualified partners.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captures circularity incentives under EU Green Deal extended producer responsibility frameworks for foam scrap recovery. |
| Water-Blown Extrusion System Deployment | Qualifies suppliers for ECHA REACH low-emission mandates at Stuttgart automotive tier-one development centers. |
| CNC Machining Capability Expansion | Addresses METI precision logistics standards for orthopedic implant kit cushioning in Japan's Kanto medical device corridor. |
| BIS Certification Investment | Unlocks captive demand from Indian construction contractors in Maharashtra and Karnataka infrastructure projects. |
| Anti-Static Masterbatch Formulation Partnership | Aligns with South Korean chip fabricator electrostatic discharge protocol tightening in Gyeonggi Province semiconductor packaging. |
Study Parameters
Two parallel data streams informed the analysis: primary field engagement with foam extrusion plant managers, automotive tier-one procurement leads, medical device contract manufacturers, and distribution channel partners; and secondary validation through customs trade data, EPA enforcement records, ECHA substance registration databases, and SEC filings from integrated resin-to-film operators. Bottom-up volume modeling across product geometries and applications was cross-checked against top-down ethylene consumption patterns and regional automotive production forecasts.
Across the projection horizon, the analytical framework modeled segmentation dimensions including foam form factor, end-use industry vertical, thickness gauge, and geographic regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating substitution dynamics from polypropylene foam and physical foaming technology diffusion. Forecast inputs included naphtha-cracker margin trajectories at Rotterdam and Singapore hubs, plus REACH compliance cost pass-through assumptions for European converters.
Forecasts assume regulatory continuity in EPA National Emission Standards for Hazardous Air Pollutants, ECHA REACH substance restrictions, and BIS certification requirements; material policy shifts would require re-modeling. Specific risks that could force forecast revision include accelerated polypropylene substitution in cold-chain logistics, polymer chemist recruitment failures at German technical universities, or ethylene feedstock disruption from refinery capacity rationalization. Revision becomes warranted when supplier panel consolidation at German automotive OEMs crosses threshold velocity that eliminates viable independent extruder participation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Polyester Film Market
Poly film
Isotropic Film Market
Poly film
Polysaccharide Films Market
Poly film
Europe Ethylene-Vinyl Alcohol Copolymer (EVOH) Packaging Films Market
Poly film
Bundling Film Market
Poly film
Polymer Dispersed Liquid Crystal (PDLC) Film Market
Poly film
Soft Touch Lamination Film Market
Poly film
Foamed Polypropylene Films Market
Poly film
Anti Fog Polycarbonate Films and Sheets Market
Poly film
Cleanroom Film and Bags Market
Poly film
Poly Coated Kraft Paper Market
Poly film
LDPE Films Market
Poly film
Nylon Films Market
Poly film
China Plastic Packaging Film Market
Poly film
Polyvinyl Alcohol (PVA) Films Market
Poly film
Poland Plastic Packaging Films Market