
 Colourless Polyimide Films Market | 2026-2036
Colourless Polyimide Films Market Size, Share, and Industry Trends Forecast 2026-2036
Colourless Polyimide Films Market Outlook
Glass is consolidating its displacement by colourless polyimide across foldable display cover layers and flexible printed circuit substrates. Kaneka Corporation leverages captive monomer synthesis to sustain cost discipline across Asian supply corridors. DuPont de Nemours anchors North American qualification pipelines for aerospace-grade transparent PI. SK Innovation competes through integrated polyimide-to-battery-film operations that share precursor chemistry.
Colourless polyimide films are aromatic polymer substrates engineered for optical transparency above 85% in the visible spectrum while retaining thermal stability beyond 300 degrees Celsius, produced primarily through solution casting of polyamic acid precursors followed by thermal imidization. Flexible Films dominates current volume as display manufacturers standardize on 25-50 micron cover window specifications for foldable smartphones. Solution Casting technology leads margin capture due to its compatibility with ultra-thin, defect-free optical grades, whereas Chemical Vapor Deposition remains confined to niche aerospace applications demanding atomic-level thickness control.
REACH registration requirements in Europe and Korea's K-REACH framework constrain aromatic dianhydride sourcing, pushing manufacturers toward closed-loop solvent recovery systems. The US FAA and Japan METI maintain divergent flame-resistance certifications for aviation interiors, fragmenting product qualification paths. Stakeholders must monitor imide ring-halogenation bans under emerging EU Green Deal chemical restrictions that threaten incumbent flame-retardant formulations.
Market Dynamics
The displacement of glass substrates by colourless polyimide in foldable electronics is compressing qualification timelines and forcing solvent-free process migrations across Asian manufacturing corridors.
Growth Catalysts
- K-REACH Framework:South Korea's chemical registration requirements are accelerating closed-loop solvent recovery investments among domestic formulators, tightening environmental compliance while securing feedstock access.
- Foldable Display Substrate Demand:Electronics manufacturers in Gyeonggi Province and Shenzhen are standardizing on 25-50 micron cover window specifications, pulling volume through dedicated polyimide-to-panel supply chains.
- Solution Casting Compatibility:This thermal imidization route enables ultra-thin optical grades with defect densities below 0.1 per square meter, matching aerospace transparency requirements without CVD equipment costs.
Market Restraints
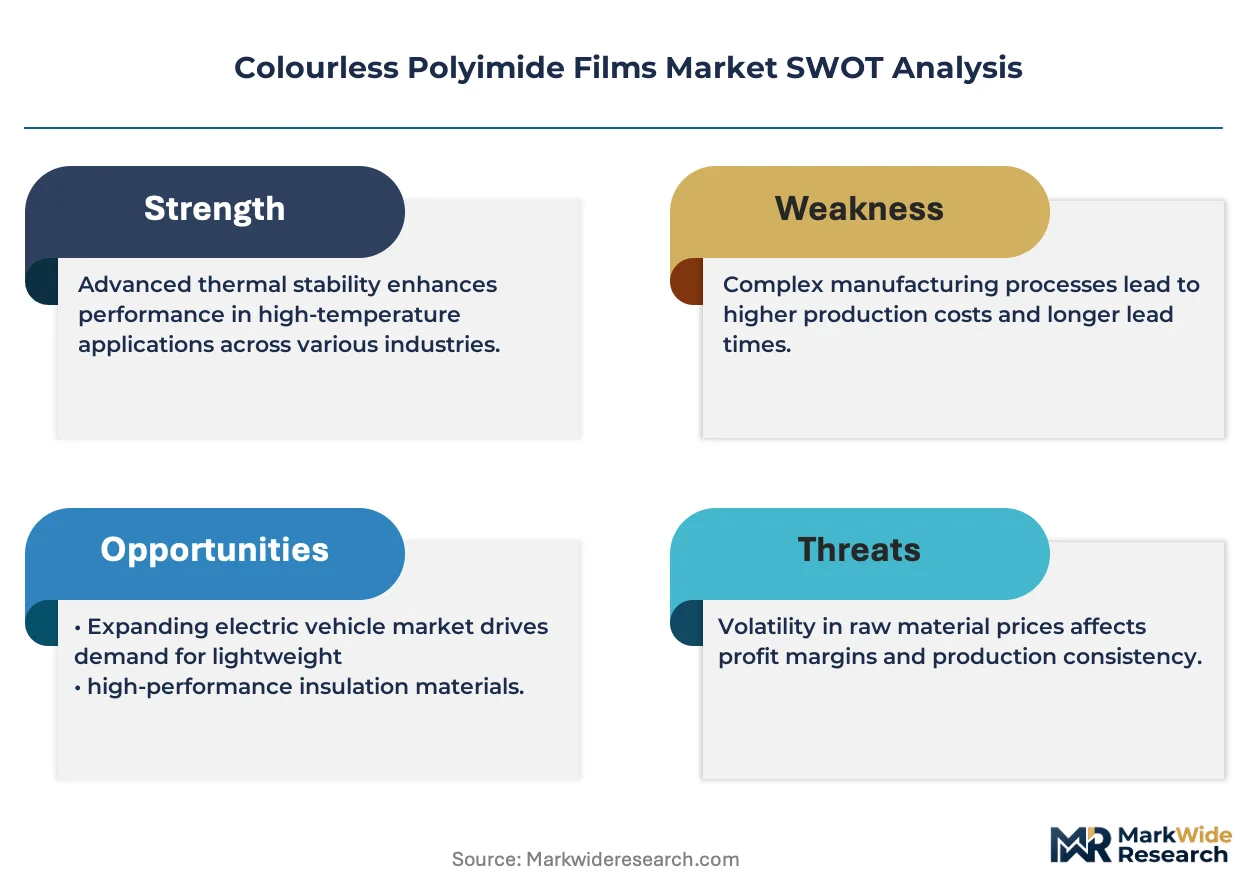
- Aromatic Dianhydride Concentration:Feedstock synthesis remains concentrated among Japanese and Korean chemical conglomerates, exposing non-integrated film producers to allocation risk during monomer supply disruptions.
- REACH Registration Friction:ECHA's data requirements for novel dianhydride chemistries extend new entrant qualification timelines by 18-24 months, reinforcing incumbent lock-in across European procurement channels.
- Glass-Ceramic Hybrid Substitution:Corning and SCHOTT are advancing chemically strengthened ultra-thin glass laminates that replicate polyimide bend radii at comparable unit economics for mid-tier smartphone tiers.
Strategic Opportunities
- Aviation Interior Certification Path:Divergent FAA and METI flame-resistance standards create arbitrage potential for dual-qualified film grades serving trans-Pacific OEM supply chains.
- India Display Manufacturing:PLI scheme incentives for semiconductor and display fabrication in Gujarat and Tamil Nadu are attracting polyimide precursor investments ahead of panel line commissioning.
- EU Green Deal Chemical Restrictions:Emerging imide ring-halogenation bans threaten incumbent flame-retardant formulations, opening formulation partnerships for phosphorus-nitrogen alternatives.
Industry Challenges
- Imidization Kinetics Expertise:Thermal profile optimization for sub-20 micron films without residual stress cracking requires polymer scientists with 10+ years aromatic PI experience, a talent pool concentrated at Kaneka, DuPont, and SK Innovation.
- Multi-Site Qualification Burden:Display panel fabs in Taichung, Seoul, and Shenzhen each demand distinct cleanliness and dimensional tolerance certifications, fragmenting quality systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Colourless Polyimide Films Market |
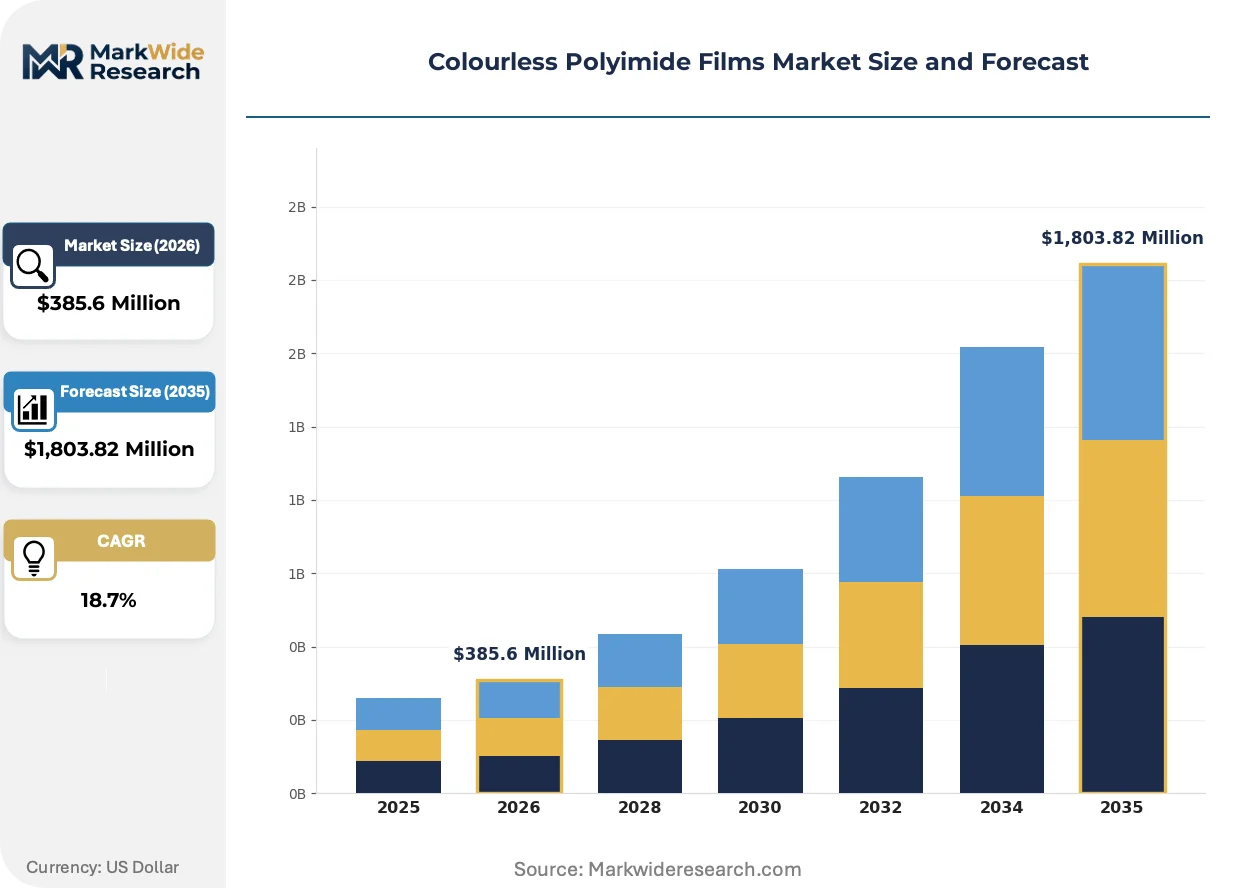
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $1,803.82 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Films, Rigid Films, Adhesive Films, Coated Films End User: Aerospace, Electronics, Automotive, Telecommunications Technology: Thermal Curing, Chemical Vapor Deposition, Solution Casting, Extrusion Application: Insulation, Circuit Boards, Flexible Displays, High-Temperature Components |
| Companies Covered | Kaneka Corporation, DuPont de Nemours, Inc, Kolon Industries Inc., SK Innovation Co., Ltd., Sumitomo Chemical Company Ltd., PI Advanced Materials Co. Ltd., Toray Industries, Inc., Industrial Summit Technology Corporation, NeXolve Holding Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Colourless Polyimide Films Market Strategic Shifts
Process intensification and regulatory chemistry bans are reshaping how colourless polyimide films achieve optical performance without legacy halogenated additives or solvent-heavy production routes.
Roll-to-roll thermal imidization with in-line optical inspection is automating defect detection at web speeds exceeding 10 meters per minute. Display panel manufacturers in Shenzhen and Gyeonggi Province are adopting these systems to compress cover window qualification from 12 months to under 6 months. The technology is automating away batch-based quality sampling that previously required destructive testing of finished rolls.
REACH Annex XVII restrictions on persistent organic pollutants are forcing reformulation of brominated flame-retardant additives in aerospace-grade transparent PI. ECHA's 2023-2024 substance evaluation roadmap specifically targets halogenated imide derivatives used in cabin interior films. European aviation suppliers are responding with phosphorus-based alternatives that maintain FAA 25.853 burn-through compliance at 5-8% cost premiums.
Direct procurement of polyamic acid precursors by display fabs is displacing merchant film purchases in high-volume foldable smartphone programs. Samsung Display and BOE Technology are qualifying in-house imidization lines that source dianhydride-diamine solutions rather than finished film. This pattern concentrates most visibly in South Korea's Giheung and Tangjeong clusters, where captive supply agreements now cover 60% of substrate volume.
Colourless Polyimide Films Market Segmentation
Colourless polyimide films serve divergent performance specifications across electronics, aerospace, and automotive end-uses. Segmentation reveals how thermal stability requirements, optical transparency thresholds, and processing economics fragment demand into distinct procurement tiers.
Product Type:
Buyers in this category differentiate by mechanical compliance needs and integration complexity with adjacent materials.
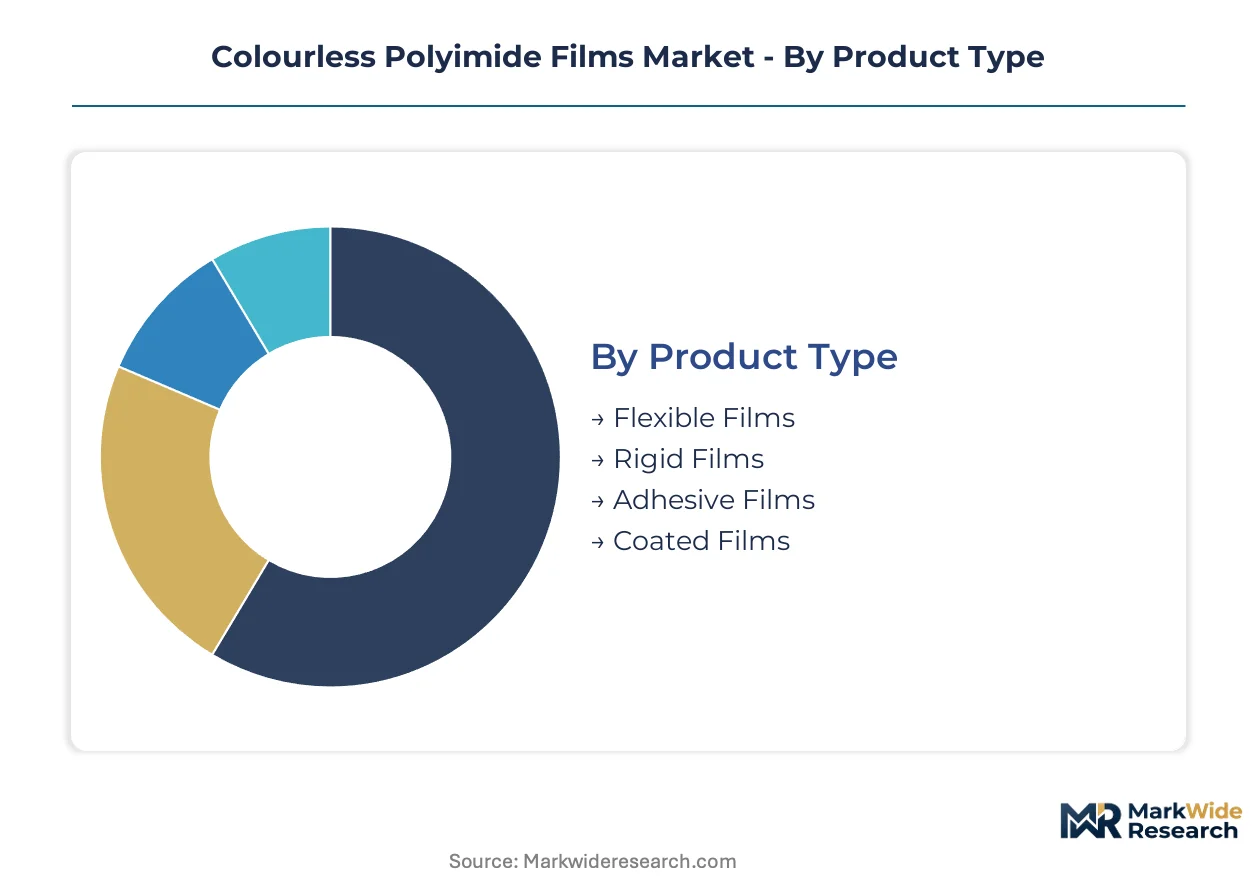
- Flexible Films:Aromatic polymer substrates engineered for sub-50 micron thickness with bend radii below 3 millimeters. Display manufacturers in Gyeonggi Province and Shenzhen standardize on 25-50 micron cover windows for foldable smartphones, pulling volume through dedicated polyimide-to-panel supply chains. Volume sits with Flexible Films; growth tilts toward Adhesive Films.
- Adhesive Films:Pressure-sensitive or thermally activated bonding layers co-extruded with base polyimide to eliminate separate lamination steps. Electronics assemblers in Taichung adopt these for multi-layer flexible circuit stack-ups where delamination risks drive specification toward integrated adhesive grades.
- Rigid Films:Higher modulus substrates with glass transition temperatures exceeding 350 degrees Celsius for structural applications requiring dimensional stability.
- Coated Films:Surface-functionalized grades with hardcoat or anti-reflective layers applied via roll-to-roll processing.
Flexible Films dominate current procurement volumes; adhesive-integrated formats are climbing the fastest as assembly step reduction becomes a priority.
End User:
End-use concentration follows certification intensity and qualification timeline differentiation across sectors.
- Electronics:Display substrate and flexible circuit applications demanding 85%+ visible spectrum transparency alongside thermal cycling resistance. Panel fabs in Shenzhen, Giheung, and Tangjeong drive specification standardization toward 25-50 micron optical grades with defect densities below 0.1 per square meter.
- Aerospace:Cabin interior and transparent insulation applications requiring FAA 25.853 or METI-equivalent flame-resistance certification. Dual-qualified film grades command pricing premiums serving trans-Pacific OEM supply chains fragmented by divergent regulatory paths.
- Automotive:Battery module insulation and flexible sensor substrates exposed to under-hood thermal profiles.
- Telecommunications:High-frequency flexible antenna substrates and base station insulation components.
Electronics captures the dominant revenue share; aerospace represents the steepest expansion trajectory as aviation interior refresh cycles accelerate.
Technology:
Process selection hinges on thickness precision requirements and capital equipment access constraints.
- Solution Casting:Thermal imidization of polyamic acid precursors cast onto continuous webs, enabling ultra-thin optical grades without CVD equipment costs. Display manufacturers adopt roll-to-roll systems with in-line optical inspection compressing qualification timelines from 12 months to under 6 months.
- Thermal Curing:Batch or continuous oven-based imidization for thicker films where optical perfection is secondary to mechanical properties.
- Chemical Vapor Deposition:Atomic-level thickness control for niche aerospace applications demanding sub-micron precision.
- Extrusion:Melt-processing routes for filled or modified polyimide compounds where optical clarity requirements are relaxed.
Solution Casting anchors current margin capture; Thermal Curing retains volume leadership in industrial-grade applications.
Application:
Application segmentation reflects the tension between electrical insulation performance and optical transparency requirements.
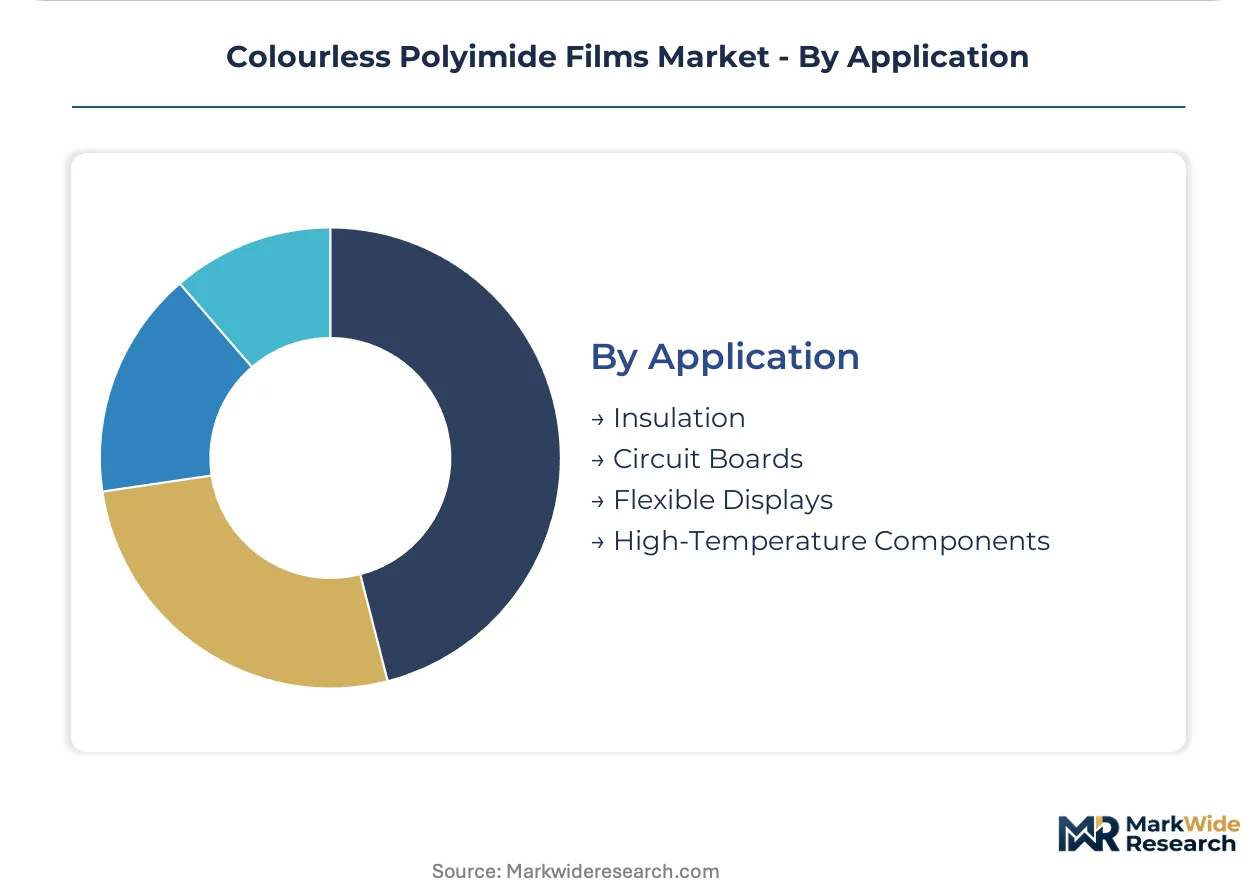
- Flexible Displays:Cover window and substrate applications where 85%+ transparency must coexist with fold endurance exceeding 200,000 cycles. Samsung Display and BOE Technology are qualifying in-house imidization lines sourcing polyamic acid precursors rather than finished film.
- Insulation:Electrical barrier applications in motors, transformers, and battery modules where thermal class ratings (180-220 degrees Celsius) outweigh optical considerations.
- Circuit Boards:Flexible printed circuit substrates requiring dimensional stability during solder reflow at 260+ degrees Celsius.
- High-Temperature Components:Seals, gaskets, and thermal barriers for aerospace propulsion and automotive exhaust systems.
Insulation holds the established volume base; Flexible Displays are gaining share fastest as foldable device penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foldable display substrate demand concentrates in East Asian manufacturing corridors, where panel fabrication clusters in South Korea, China, and Taiwan pull polyimide film through dedicated supply chains. Regulatory chemistry frameworks in Europe and East Asia are accelerating solvent-free process migrations among formulators serving these markets.
South Korea
Samsung Display and LG Display drive substrate specifications for foldable smartphones, standardizing on 25-50 micron cover windows. K-REACH chemical registration requirements tighten aromatic dianhydride sourcing, pushing domestic formulators toward closed-loop solvent recovery. Manufacturing concentrates in Gyeonggi Province's Giheung and Tangjeong clusters, where captive precursor agreements now cover 60% of substrate volume.
China
BOE Technology and TCL CSOT expand foldable panel capacity, pulling optical-grade polyimide through Shenzhen and Chengdu corridors. Stricter VOC emission rules under MEE oversight accelerate water-based polyamic acid formulation adoption. Display fabrication in Shenzhen's Bao'an district and Hefei's Xinzhan high-tech zone anchors regional procurement volumes.
Japan
Toray Industries and Sumitomo Chemical maintain aerospace-grade transparent PI qualification pipelines for aviation interior applications. METI flame-resistance certification diverges from FAA standards, fragmenting product qualification paths for trans-Pacific OEM supply chains. Production concentrates in Chiba and Ibaraki prefectures, where integrated monomer-to-film operations serve both electronics and aviation tiers.
United States
DuPont de Nemours anchors North American qualification for aerospace-grade transparent PI serving Boeing and Gulfstream supply chains. FAA 25.853 burn-through compliance requirements sustain premium pricing for dual-certified film grades. Manufacturing and R&D concentrate in Delaware and Virginia corridors, where polymer scientists with decade-plus aromatic PI experience remain concentrated.
Taiwan
Panel fabs in Taichung and Tainan demand distinct cleanliness and dimensional tolerance certifications for flexible display substrates. Electronics assemblers adopt adhesive-integrated polyimide formats for multi-layer flexible circuit stack-ups. The Taichung Science Park anchors regional demand, with qualification timelines compressing from 12 months to under 6 months through roll-to-roll thermal imidization adoption.
Colourless Polyimide Films Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated chemical conglomerates holding feedstock advantage in optical grades while merchant film producers compete on formulation flexibility. The structure tilts toward consolidation at the precursor synthesis tier and fragmentation at the finishing tier. Three archetypes dominate: captive monomer producers, aerospace qualification specialists, and display-dedicated formulators. Competitive moves concentrate on backward integration into dianhydride synthesis and geographic expansion toward emerging display fabrication clusters.
Among Japanese and Korean chemical conglomerates, Kaneka Corporation, Toray Industries, and Sumitomo Chemical occupy positions defined by integrated monomer-to-film operations. These entities exemplify the captive synthesis archetype, securing feedstock access against allocation risk during supply disruptions. DuPont de Nemours represents the aerospace qualification specialist tier, anchoring North American certification pipelines. SK Innovation and Kolon Industries sit within the display-dedicated formulator category, competing through proximity to Korean panel fabrication clusters.
| Leading Market Players |
|---|
| Kaneka Corporation |
| DuPont de Nemours, Inc |
| Kolon Industries Inc. |
| SK Innovation Co., Ltd. |
| Sumitomo Chemical Company Ltd. |
| PI Advanced Materials Co. Ltd. |
| Toray Industries, Inc. |
| Industrial Summit Technology Corporation |
| NeXolve Holding Company |
| Others |
Value Chain & Pricing Dynamics
Display panel fabs in Gyeonggi Province and Shenzhen anchor procurement volumes through captive precursor agreements, compressing merchant film pricing power toward cost-plus structures for non-integrated suppliers. This buyer concentration forces pricing discipline that rewards backward integration into dianhydride synthesis while squeezing formulation-only margins.
Pricing Analysis
Volume leadership sits with flexible film grades serving foldable smartphone cover windows, while margin capture concentrates in aerospace-certified transparent PI carrying FAA 25.853 or METI-equivalent burn-through compliance. Price differentiation hinges on certification tier and volume scale, with dual-qualified aviation grades commanding premiums over display substrate volumes. Cost compression in mid-tier electronics grades is intensifying because BOE Technology and Samsung Display are qualifying in-house imidization lines sourcing polyamic acid directly. Merchant film producers face the sharpest price sensitivity as captive precursor agreements now cover the majority of Korean substrate volume.
Supply Chain Analysis
Regional distribution centers in Chiba, Gyeonggi Province, and Delaware anchor hub-and-spoke patterns serving panel fabrication clusters and aviation OEM corridors. Feedstock synthesis concentrates in Japan and South Korea, with aromatic dianhydride production controlled by Toray Industries, Sumitomo Chemical, and Kaneka Corporation. Merchant film producers draw from these concentrated monomer sources, exposing them to allocation risk during supply disruptions. Single-source vulnerability in dianhydride precursors represents the dominant structural risk. Distribution runs through dedicated polyimide-to-panel supply chains in East Asian manufacturing corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Colourless polyimide films occupy a technology-transition phase as solution casting displaces legacy batch thermal imidization, and as in-house precursor processing displaces merchant film purchases at major display fabs.
For Market Incumbents: Extend captive monomer synthesis advantages by locking long-term dianhydride supply agreements with non-integrated competitors before K-REACH registration requirements tighten further. Invest in roll-to-roll thermal imidization with in-line optical inspection to compress qualification timelines from 12 months to under 6 months, defending against glass-ceramic hybrid substitution from Corning and SCHOTT. Backward integration into solvent recovery systems secures environmental compliance while tightening feedstock control. For New Entrants and Emerging Players: The price-point gap between aerospace-certified transparent PI and standard display substrate grades offers entry space for mid-tier formulators targeting automotive battery module insulation and flexible circuit applications. India represents the most penetrable geography, with PLI scheme incentives for semiconductor and display fabrication in Gujarat and Tamil Nadu attracting precursor investments ahead of panel line commissioning. A qualification-light go-to-market angle focuses on thermal curing routes for industrial-grade insulation where optical perfection is secondary. For Investors and Strategic Acquirers: The window for entry favors polymer scientists with decade-plus aromatic PI experience concentrated at incumbent laboratories, as imidization kinetics expertise for sub-20 micron films remains scarce. Long-term viability rests on positioning for EU Green Deal chemical restrictions that will ban halogenated imide derivatives, favoring phosphorus-nitrogen flame-retardant alternatives. Watch for dual FAA-METI certification investments as the inflection indicator for trans-Pacific aviation interior supply chain arbitrage.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dianhydride Synthesis | Kaneka Corporation and Toray Industries secure feedstock access against K-REACH allocation constraints. |
| Roll-to-Roll Thermal Imidization Deployment | Shenzhen and Gyeonggi Province panel fabs compress cover window qualification timelines through automation. |
| Phosphorus-Nitrogen Flame-Retardant Partnership | European aviation suppliers respond to ECHA Annex XVII halogenated imide derivative restrictions. |
| India Precursor Manufacturing Investment | PLI scheme incentives in Gujarat attract polyamic acid capacity ahead of display panel commissioning. |
| Dual FAA-METI Certification Pursuit | DuPont de Nemours and Japanese producers capture trans-Pacific OEM supply chain premiums. |
Study Parameters
Multi-period observation of dianhydride feedstock pricing, captive precursor agreement penetration, and qualification timeline compression anchored the trend analysis, supplemented by interviews with polymer synthesis directors at integrated chemical conglomerates, procurement leads at display panel fabs, regulatory affairs specialists navigating K-REACH and REACH frameworks, and technical R&D directors at aerospace-grade film producers. Secondary validation drew from ECHA substance evaluation roadmaps, FAA 25.853 certification databases, Korean chemical registration filings, and SEC 10-K disclosures from listed materials suppliers. Bottom-up volume builds across end-use segments triangulated against top-down chemical industry production data.
Segment-weighting applied product type splits between flexible, adhesive, rigid, and coated film formats, crossed with end-use concentrations in electronics, aerospace, automotive, and telecommunications. Technology differentiation between solution casting, thermal curing, chemical vapor deposition, and extrusion routes informed margin assumptions. CAGRs were derived from elasticity-adjusted demand projections across the analysis window, incorporating foldable smartphone penetration curves and aviation interior refresh cycles as industry-specific forecast inputs.
Inputs from primary stakeholder interviews and regulatory filing databases were available through the study window; gaps in real-time captive precursor agreement terms and undisclosed in-house imidization line capacities introduce uncertainty bands around merchant film volume forecasts. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Tube Laminating Films Market
Poly film
Australia and New Zealand Plastic Packaging Film Market
Poly film
Automotive Wrap Films Market
Poly film
Global BOPP Films Market
Poly film
Bundling Film Market
Poly film
PVC Films Market
Poly film
Hexacomb Packaging Market
Poly film
Resealable Films Market
Poly film
Printed Plastic Films Market
Poly film
Polypropylene Film Market
Poly film
Asia Pacific Plastic Packaging Film Market
Poly film
Egypt Plastic Packaging Films Market
Poly film
Global Thermoplastic Films Market
Poly film
United Kingdom Plastic Packaging Films Market
Poly film
Recyclable Lidding Films Market
Poly film
EVOH Encapsulation Film Market