
 PVC Film for Medical Market | 2026-2036
PVC Film for Medical Market Size, Share, and Industry Trends Forecast 2026-2036
PVC Film for Medical Market Analytics
Aftermarket service revenue for sterilization validation is rewriting margin capture in medical-grade PVC film supply. Tekni-Plex leverages its North American manufacturing footprint to sustain film consistency for IV container producers. Klöckner Pentaplast Group anchors European demand through specialized barrier coatings for surgical drape applications. Shin-Etsu Chemical Co Ltd differentiates via high-purity resin control across Asian medical packaging channels.
PVC film for medical use denotes flexible polyvinyl chloride sheeting formulated with plasticizers and stabilizers to achieve biocompatibility, typically ranging from 50µm to 200µm thickness, produced via calendering or extrusion processes for sterile contact applications. Sterile barrier films command premium positioning due to validation burdens and terminal sterilization compatibility requirements. Adhesive film segments for surgical drape applications exhibit faster expansion than non-adhesive alternatives, while laminated film structures concentrate margin pools through multi-layer coextrusion complexity that limits supplier proliferation.
FDA 21 CFR Part 177.2600 compliance governs resin and additive selections for US-bound medical PVC film, while EMA's MDR and REACH Annex XVII restrictions on phthalate plasticizers reshape European formulation strategies. ISO 10993 biocompatibility testing frameworks create cross-border harmonization pressure that favors laboratories with established cytotoxicity and sensitization protocols. Stakeholders must monitor regulatory divergence between phthalate-restrictive European standards and FDA's continued allowance of DEHP in critical life-support applications.
Market Dynamics
REACH Annex XVII phthalate restrictions and FDA 21 CFR Part 177.2600 compliance requirements are bifurcating formulation strategies between European and North American medical PVC film supply chains.
Growth Catalysts
- Surgical center expansion:Ambulatory surgical centers in the United States are scaling sterile barrier film procurement to support same-day discharge protocols. Terminal sterilization compatibility requirements lock in qualified suppliers.
- MDR compliance deadlines:EMA's Medical Device Regulation is forcing device manufacturers to revalidate packaging materials, creating replacement demand for ISO 10993-tested film grades.
- Calendering precision advances:Thickness control improvements down to ±2µm are enabling thinner gauge films for IV containers without sacrificing burst strength.
Market Restraints
- Plasticizer input volatility:DEHP and alternative plasticizer feedstock costs fluctuate with petrochemical pricing, compressing margin predictability for film converters.
- Resin supply concentration:High-purity medical-grade PVC resin production clusters in Japan and Germany, exposing buyers to single-source geographic risk.
- Polyolefin substitution:Multilayer coextruded polyethylene films are capturing non-critical packaging applications where sterilization validation burdens are lower.
Strategic Opportunities
- India medical device manufacturing:CDSCO's phased MDR alignment and PLI scheme incentives are attracting contract manufacturers needing localized film supply.
- Adhesive surgical drape films:Pressure-sensitive coating integration creates higher-margin SKUs for operating room disposable kits.
- Digital printing compatibility:Laser-markable film surfaces enable unit-level traceability for FDA UDI compliance without secondary labeling.
Industry Challenges
- Biocompatibility testing bottlenecks:ISO 10993-5 cytotoxicity and ISO 10993-10 sensitization study queues at accredited laboratories extend product launch timelines by 8-14 months.
- Legacy extrusion asset retrofitting:Medical-grade cleanroom specifications for film production require capital redeployment that mid-scale converters struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PVC Film for Medical Market |
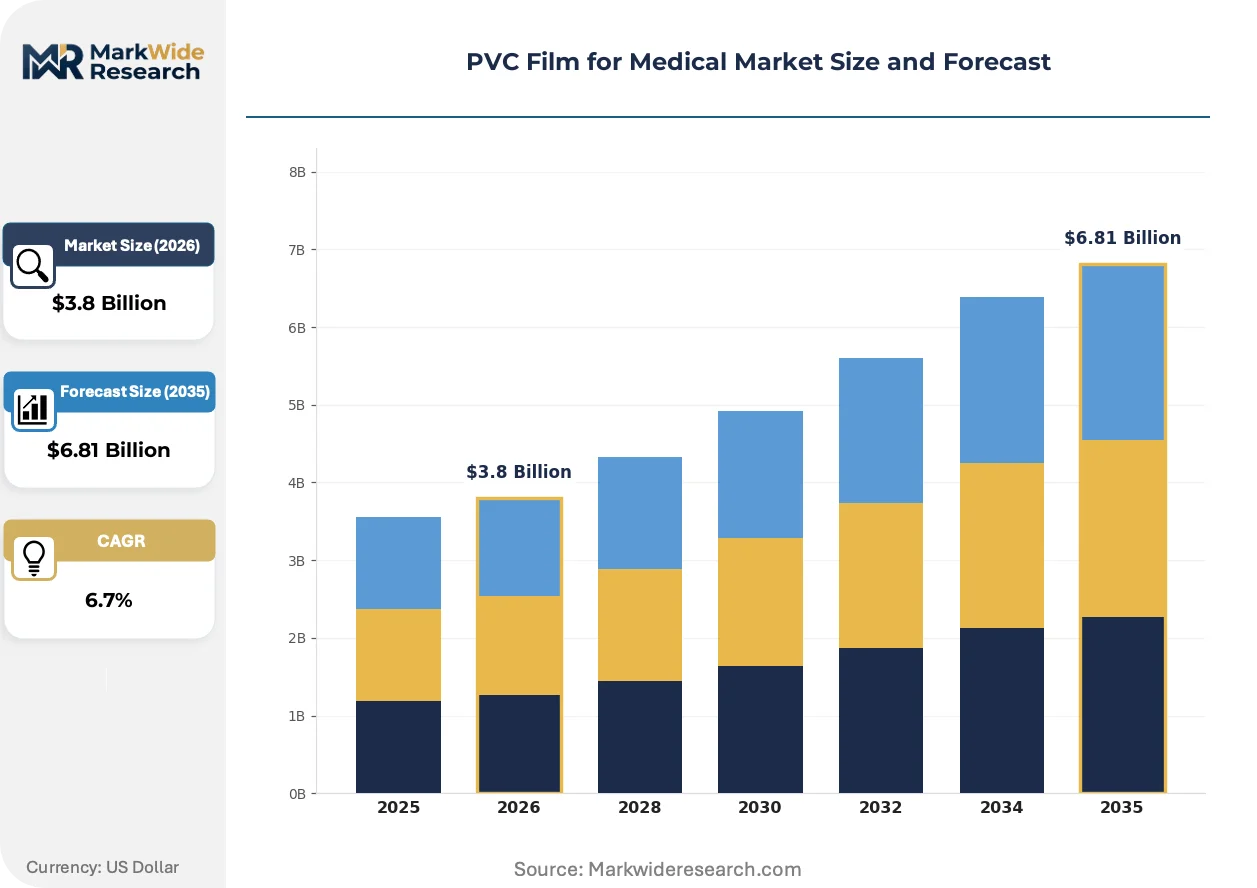
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sterile Barrier, Adhesive Film, Laminated Film, Non-Adhesive Film Application: Medical Packaging, Surgical Drapes, IV Containers, Disposable Products End User: Hospitals, Clinics, Laboratories, Surgical Centers Thickness: 50µm, 100µm, 150µm, 200µm |
| Companies Covered | Achilles Corporation, Tekni-Plex, Presco, Formosa Plastics Corporation, Shin-Etsu Chemical Co Ltd, Klöckner Pentaplast Group, C.I. TAKIRON Corporation, Nanya Plastics Corporation, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PVC Film for Medical Market Evolving Landscape
Non-phthalate plasticizer systems and multi-layer coextrusion architectures are redefining performance benchmarks for sterile medical packaging.
Epoxidized soybean oil and DINCH plasticizer formulations are rendering obsolete legacy DEHP-based films in European wound care and dialysis applications. German device manufacturers are qualifying these alternatives ahead of REACH enforcement windows. The transition is compressing demand for conventional phthalate-containing grades in export-bound production.
EMA's MDR Article 10 technical documentation requirements are forcing film suppliers to maintain design dossiers and clinical evaluation reports. This documentation burden favors suppliers with established regulatory affairs functions. Small converters without dedicated compliance teams are exiting the surgical drape film segment.
Hospital procurement consolidation is shifting purchasing authority to centralized materials management departments. Group purchasing organizations in the United States are bundling sterile barrier films with device contracts, squeezing standalone film distributors. This concentration is most visible in the Southeast and Midwest hospital networks.
PVC Film for Medical Market Segmentation
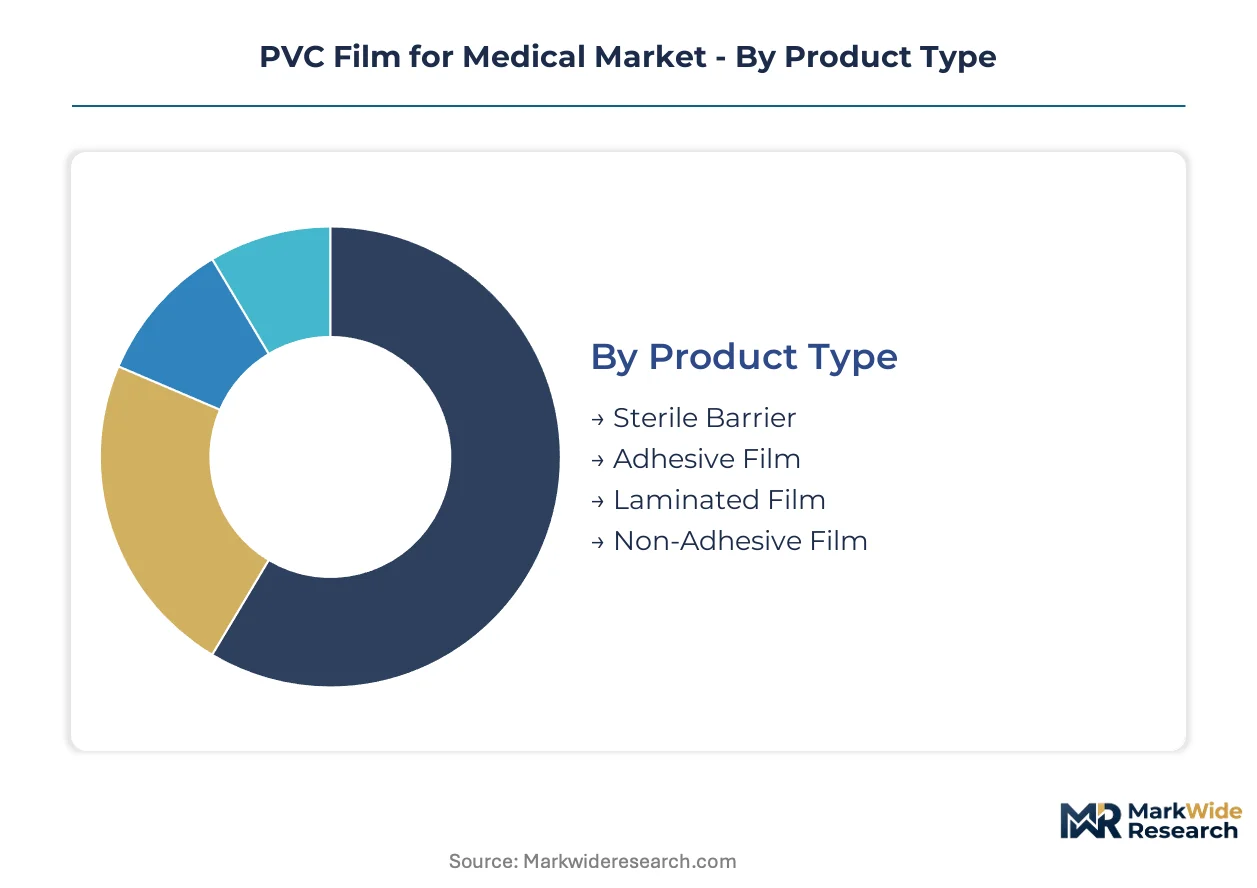
PVC film segmentation in medical applications follows distinct procurement cycles and technical validation requirements. Each dimension—product architecture, clinical use case, facility type, and physical specification—creates separate margin pools and supplier qualification pathways.
Product Type:
Cycle times vary sharply: sterile barrier films require 18-24 month validation protocols, while non-adhesive commodity grades turn inventory quarterly.
- Sterile Barrier:Multi-layer calendered constructions with terminal sterilization compatibility (ethylene oxide, gamma, steam) dominate critical device packaging. Demand concentrates in German surgical instrument manufacturing corridors where EMA MDR revalidation is forcing material upgrades.
- Adhesive Film:Pressure-sensitive coated grades for surgical drape applications integrate antimicrobial layers and controlled peel adhesion. United States ambulatory surgical centers are expanding procurement fastest as same-day discharge protocols multiply procedure volumes.
- Laminated Film:Coextruded multi-ply structures combine PVC with polyolefin barrier layers for enhanced moisture protection.
- Non-Adhesive Film:Standard calendered grades for secondary packaging and non-sterile applications face polyolefin substitution pressure.
Sterile barrier dominates installed base. Adhesive film is where expansion concentrates.
Application:
Margin structures diverge by sterilization burden—IV containers demand burst strength precision, while disposable products prioritize cost minimization.
- Medical Packaging:Primary sterile packaging for devices and pharmaceuticals requires ISO 11607 compliance and accelerated aging validation. Japanese pharmaceutical exporters are qualifying thinner-gauge films to reduce shipping cube.
- Surgical Drapes:Large-format adhesive films with fenestration and reinforcement zones command premium positioning in United States hospital group purchasing contracts.
- IV Containers:Blow-fill-seal compatible films with ±2µm thickness control and DEHP or DINCH plasticizer options serve parenteral solution packaging.
- Disposable Products:Specimen collection bags, oxygen tubing, and non-critical disposables compete against polyethylene alternatives on converter cost.
Medical packaging anchors revenue. Surgical drapes are climbing the fastest.
End User:
Procurement authority centralization is reshaping segment economics—hospital systems consolidate purchasing while surgical centers remain fragmented.
- Hospitals:Integrated delivery networks in the United States Southeast and Midwest bundle sterile barrier films with device contracts through group purchasing organizations, squeezing standalone distributors.
- Surgical Centers:Freestanding ambulatory facilities in Germany and the United States scale sterile film procurement fastest as outpatient migration accelerates.
- Clinics:Physician office laboratories and specialty clinics purchase lower volumes with less stringent validation requirements.
- Laboratories:Diagnostic and research facilities demand film clarity and chemical resistance for specimen handling applications.
Hospitals control volume. Surgical centers are gaining share fastest.
Thickness:
Calendering precision advances are compressing demand toward thinner gauges without sacrificing mechanical performance.
- 100µm:The workhorse specification balances burst strength and material economy across IV container and general packaging applications. German converters are qualifying this gauge for previously 150µm-specified applications.
- 150µm:Surgical drape and heavy-duty packaging applications specify this mid-range thickness for puncture resistance and handling durability.
- 50µm:Emerging ultra-thin grade for cost-sensitive disposable products and secondary packaging layers.
- 200µm:Specialized applications including oxygen reservoir bags and reinforced surgical drapes requiring maximum mechanical integrity.
150µm holds installed base. 100µm is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography: German manufacturers prioritize REACH-compliant non-phthalate formulations for wound care exports, while United States converters maintain DEHP-based production for critical life-support devices under FDA 21 CFR Part 177.2600. Japanese pharmaceutical exporters drive demand for ultra-thin gauge films to optimize shipping cube efficiency.
United States
Ambulatory surgical centers in Texas and Florida are scaling sterile barrier film procurement fastest as same-day discharge protocols multiply procedure volumes. FDA 21 CFR Part 177.2600 continues permitting DEHP plasticizers in critical IV applications, preserving formulation continuity for domestic manufacturers. The Southeast hospital network corridor concentrates group purchasing organization bundling activity, squeezing standalone distributors.
Germany
EMA MDR Article 10 technical documentation deadlines are forcing device manufacturers to revalidate packaging materials, creating replacement demand for ISO 10993-tested film grades. REACH Annex XVII phthalate restrictions are rendering DEHP-based films obsolete in export-bound production. The Baden-Württemberg surgical instrument manufacturing corridor anchors European demand for specialized barrier coatings.
Japan
PMDA alignment with ISO 11607 standards is accelerating qualification of thinner-gauge films for pharmaceutical export packaging. METI industrial policy supports high-purity resin control investments across medical packaging channels. The Kanto region surrounding Tokyo concentrates pharmaceutical film converter capacity serving export markets.
India
CDSCO's phased MDR alignment and PLI scheme incentives are attracting contract manufacturers needing localized film supply for surgical drape and IV container applications. Maharashtra's medical device manufacturing clusters in Pune and Mumbai are emerging as procurement hubs for domestic and export production.
China
NMPA medical device registration reforms are tightening biocompatibility documentation requirements for imported film grades. The Yangtze River Delta pharmaceutical packaging corridor is scaling domestic calendering capacity to reduce reliance on Japanese resin imports. Shanghai-based converters are qualifying multilayer coextrusion lines for sterile barrier applications.
PVC Film for Medical Market Competitive Landscape
Capability concentration sits with specialized resin and coating innovators; scale advantage sits with integrated film converters possessing continental manufacturing footprints. The market structures around three tiers: multinational chemical conglomerates controlling high-purity resin supply, mid-scale regional converters with validated cleanroom assets, and specialized coating specialists serving surgical drape applications. Dominant competitive moves include backward integration into captive resin production and geographic expansion through distributor partnerships in emerging medical device manufacturing corridors.
Within the multinational chemical tier, Shin-Etsu Chemical Co Ltd exemplifies high-purity resin control strategies, while BASF SE occupies a position spanning plasticizer chemistry through film additive systems. Among integrated converters, Klöckner Pentaplast Group represents European barrier coating specialization, and Tekni-Plex anchors North American supply consistency for IV container producers. Achilles Corporation and C.I. TAKIRON Corporation sit within the Asia-Pacific specialist tier focused on pharmaceutical-grade film clarity and thickness precision.
| Leading Market Players |
|---|
| Achilles Corporation |
| Tekni-Plex |
| Presco |
| Formosa Plastics Corporation |
| Shin-Etsu Chemical Co Ltd |
| Klöckner Pentaplast Group |
| C.I. TAKIRON Corporation |
| Nanya Plastics Corporation |
| BASF SE |
| Others |
Value Network & Pricing Analysis
Japanese and German high-purity resin concentration funnels margin capture toward film converters possessing captive plasticizer compounding capabilities and ISO 10993-validated cleanroom assets. Buyers face asymmetric leverage when sourcing sterile barrier grades requiring terminal sterilization compatibility documentation.
Pricing Analysis
Long-term offtake contracts dominate sterile barrier film procurement, with 18-24 month validation protocols locking hospital systems and device manufacturers to qualified suppliers. Price differentiation rests on ISO 10993 certification tier and calendering precision down to ±2µm gauge control. Cost compression in non-adhesive commodity grades is intensifying as polyolefin alternatives capture secondary packaging applications. Ambulatory surgical centers exhibit highest price sensitivity due to fragmented purchasing authority, while integrated delivery networks leverage group purchasing organization bundling for standard-grade leverage.
Supply Chain Analysis
Upstream vinyl chloride monomer and high-purity PVC resin production clusters in Japan, Germany, and the United States Gulf Coast. Medical-grade film manufacturing draws from DEHP, DINCH, and epoxidized soybean oil plasticizer feedstocks alongside specialized stabilizer additive packages. Single-source geographic vulnerability concentrates in Japanese pharmaceutical-grade resin supply serving Asian export markets. Distribution runs through medical device contract manufacturers and converter-direct relationships with hospital group purchasing organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polyolefin multilayer substitution threatens PVC film incumbents in non-critical packaging tiers where sterilization validation burdens remain lower. Defense requires differentiation through biocompatibility certification depth and barrier performance that alternatives cannot replicate.
For Market Incumbents: Entrench position through backward integration into captive DINCH and non-phthalate plasticizer production, insulating margin from petrochemical feedstock volatility. Acquire ISO 10993 testing capabilities in-house to compress 8-14 month biocompatibility study queues that delay product launches. Prioritize adhesive surgical drape film capacity expansion in United States Southeast and Midwest corridor where ambulatory surgical center growth concentrates procurement.
For New Entrants and Emerging Players: Build out localized supply presence in Maharashtra's Pune and Mumbai clusters to serve CDSCO-aligned contract manufacturers qualifying for PLI scheme incentives. Target adhesive film segments for surgical drape applications where pressure-sensitive coating integration creates higher-margin SKUs resistant to polyolefin displacement. Pursue digital printing compatibility certification as entry wedge for FDA UDI compliance-driven hospital system contracts.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale regional converters with validated cleanroom assets and established EMA MDR technical documentation functions. The 5-10 year viability window favors suppliers possessing both European REACH-compliant formulation capabilities and FDA DEHP-tolerant production flexibility. Watch for CDSCO MDR alignment acceleration in India as inflection signal for localized supply demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plasticizer Production | Captive DINCH supply secures margin against petrochemical volatility for REACH-compliant grades. |
| ISO 10993 Testing Capability Acquisition | In-house cytotoxicity protocols compress 8-14 month laboratory queue delays for surgical drape launches. |
| Adhesive Film Coating Line Expansion | Pressure-sensitive antimicrobial layers command premium positioning in United States ASC procurement. |
| India Manufacturing Footprint Establishment | Maharashtra-based capacity captures CDSCO PLI scheme contract manufacturer demand. |
| Digital Printing Surface Qualification | Laser-markable films enable FDA UDI compliance without secondary labeling for hospital GPO contracts. |
Research Methodology
Operator-level perspectives from film converter plant managers, medical device procurement leads, hospital GPO contracts managers, and regulatory affairs directors anchored the qualitative base. Primary interview insights combined with customs trade data, FDA 510(k) filings, EMA MDR technical documentation databases, and SEC filings from resin suppliers. Bottom-up demand modeling across thickness specifications and top-down supply verification through calendering capacity assessments provided triangulation discipline.
Scenario-bracketing around REACH phthalate enforcement timing and FDA DEHP policy continuity shaped projection boundaries across the analysis window. Segmentation dimensions modeled include product architecture, clinical application, end-user facility type, and thickness specification alongside regional regulatory cluster alignment. CAGRs derived from validated supplier shipment data and hospital procurement database trending. Forecast inputs incorporated ambulatory surgical center expansion trajectories and MDR revalidation replacement demand cycles.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese calendering specialists or accelerated polyolefin barrier performance improvements would shift outcomes. Cross-checking against CDSCO MDR implementation pace and Japanese pharmaceutical export volume trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
APET Film Market
Poly film
North America Polyimide Films Market
Poly film
Morocco Plastic Packaging Films Market
Poly film
Multi-Layer Blown Films Market
Poly film
PP Film Blowing Machine Market
Poly film
Global Fluoropolymer Films Market
Poly film
PE Foam Films Market
Poly film
Latin America Plastic Packaging Films Market
Poly film
Polyurethane (PU) Film Market
Poly film
India BOPP Films Market
Poly film
Blown Film Extruder Market
Poly film
Australia and New Zealand Plastic Packaging Film Market
Poly film
Polyethylene Furanoate Films Market
Poly film
Japan Polypropylene Packaging Films Market
Poly film
Egypt Plastic Packaging Films Market
Poly film
Silicone Release Films Market