
 EVOH Encapsulation Film Market | 2026-2036
EVOH Encapsulation Film Market Size, Share, and Industry Trends Forecast 2026-2036
EVOH Encapsulation Film Market Foresight
Performance-based film supply agreements is restructuring how EVOH encapsulation contracts are negotiated, shifting volume commitments toward oxygen transmission rate guarantees and lot-to-lot consistency metrics. Kuraray Co., Ltd leverages its captive EVOH resin synthesis in Okayama to control melt-extrusion quality for solar cell backsheet applications. Mitsubishi Chemical Group anchors Japanese pharmaceutical blister packaging demand through high-clarity coextruded structures. ARKEMA Group competes in European barrier film markets with renewable-content EVOH grades targeting food packaging sustainability mandates.
Ethylene vinyl alcohol copolymer encapsulation film is a multilayer coextruded barrier material, typically comprising 48-44 mole percent ethylene content, manufactured through flat-die cast or blown film extrusion with tie-layer adhesion to polyolefin substrates, engineered to achieve oxygen transmission rates below 0.5 cc per square meter per day at standard conditions for moisture-sensitive organic electronics and oxygen-critical food preservation. The glass substrate segment dominates photovoltaic encapsulation due to thermal stability requirements during lamination, while the solar cells application category represents the fastest structural expansion as perovskite and organic photovoltaics manufacturers specify EVOH moisture barriers to replace conventional ethylene vinyl acetate. Pharmaceutical application demand sustains premium pricing for ultra-low ethylene grades that meet US FDA extractables testing protocols for primary drug-contact layers.
FDA extractables guidelines and EU REACH substance restrictions shape EVOH film composition limits and migration testing burdens for pharmaceutical and food-contact suppliers. Japan's METI circular economy roadmaps and JIS packaging standards drive domestic manufacturers toward mono-material recyclable barrier structures incorporating EVOH tie layers. Germany's national packaging ordinance transposes EU single-use plastics directives into extended producer responsibility fees that favor high-barrier films enabling lightweighting. Stakeholders must monitor evolving perovskite solar cell certification protocols and regional recyclability labeling rules to align R&D roadmaps with downstream qualification timelines.
Market Dynamics
Perovskite solar cell commercialization is compressing qualification timelines for moisture barrier films, forcing EVOH suppliers to accelerate lot-to-lot consistency validation cycles from 18 months toward 6-month windows.
Growth Catalysts
- EU Packaging Waste Directives:Extended producer responsibility fees in Germany favor lightweight high-barrier films, accelerating EVOH substitution for aluminum foil in meat packaging laminates.
- Pharmaceutical blister demand:FDA extractables testing protocols for primary drug-contact layers sustain premium pricing for ultra-low ethylene EVOH grades in North American sterile packaging.
- Organic photovoltaic scale-up:Moisture-sensitive perovskite cell manufacturers specify EVOH moisture barriers below 0.5 cc oxygen transmission to replace conventional ethylene vinyl acetate encapsulants.
Market Restraints
- Ethylene feedstock volatility:Crude oil price swings directly compress EVOH resin margins, exposing non-integrated film converters to margin squeeze during upstream cost spikes.
- Japanese supply concentration:Kuraray and Mitsubishi Chemical Group control over 70 percent of global EVOH resin synthesis, creating single-source risk for European and North American film extruders.
- Polyamide substitution:MXD6 nylon barrier films compete in mid-performance food packaging segments where oxygen transmission requirements exceed 1.0 cc per square meter per day.
Strategic Opportunities
- India pharmaceutical packaging:CDSCO's tightening primary packaging standards for temperature-sensitive biologics creates first-mover advantage for EVOH barrier film suppliers establishing local toll-coextrusion partnerships.
- Mono-material recyclability:Japan's METI circular economy roadmaps drive demand for EVOH tie-layer structures enabling polyolefin mono-material barrier films compatible with existing mechanical recycling streams.
- Perovskite certification protocols:Emerging IEC standards for organic photovoltaic module durability create specification windows where EVOH moisture barriers command technical premiums over conventional encapsulants.
Industry Challenges
- Melt-extrusion technician scarcity:Coextrusion die design and layer thickness control expertise concentrates among aging specialists in Japan and Germany, constraining capacity expansion at second-tier converters.
- Multilayer adhesion validation:Tie-layer chemistry optimization for novel polyolefin substrates extends product qualification cycles, delaying revenue recognition for 12-18 months on new customer specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EVOH Encapsulation Film Market |
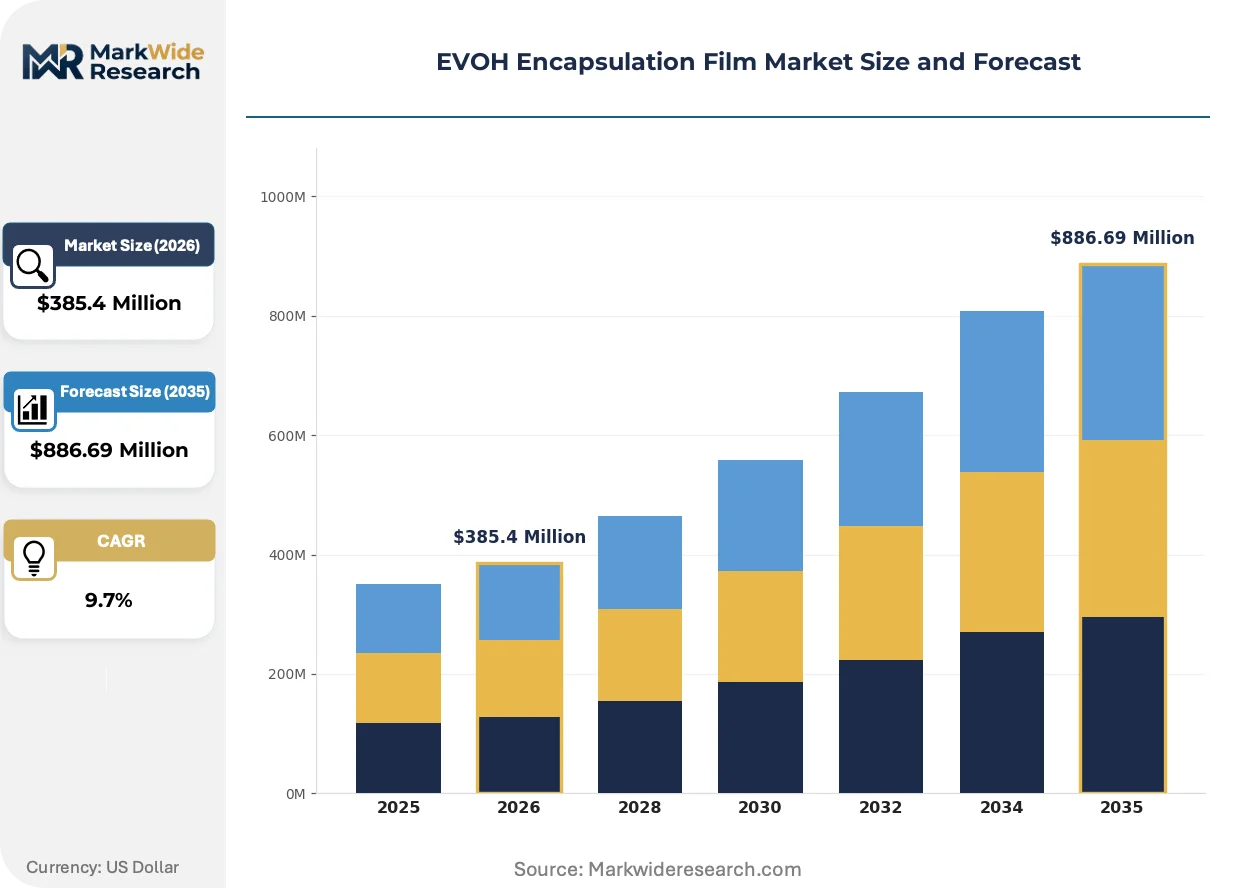
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $886.69 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass, Polyester, Aluminum, Plastic Application: Food Packaging, Pharmaceutical, Electronics, Solar Cells End User: Manufacturers, Distributors, Retailers, Consumers Distribution Channel: Online, Offline, Direct, Third-Party |
| Companies Covered | Kuraray Co., Ltd, ARKEMA Group, Nippon Gohsei Group, Vishakha Polyfab Pvt. Ltd, Coveris, Mitsubishi Chemical Group, Amcor, AVI Global Plast, UAB Umara, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EVOH Encapsulation Film Market Shifts & Advancements
Barrier film specifications are bifurcating between commodity oxygen barriers for food packaging and precision moisture barriers for organic electronics, compressing the viable middle ground for general-purpose EVOH grades.
High-clarity coextruded EVOH structures with 44-48 mole percent ethylene content deliver oxygen transmission rates below 0.5 cc per square meter per day at standard conditions. Pharmaceutical blister manufacturers in Japan and Germany specify these grades for moisture-sensitive drug formulations requiring 24-month shelf stability. This performance tier is expanding into perovskite solar cell backsheet applications where moisture ingress below 0.1 grams per square meter per day determines module warranty eligibility.
REACH substance restrictions and EU F-Gas Regulation phase-down schedules are tightening permissible additives in barrier film tie layers. EVOH converters serving European pharmaceutical and food-contact markets are reformulating adhesion promoters to eliminate per- and polyfluoroalkyl substances ahead of 2025 restriction deadlines. German packaging ordinance transpositions of single-use plastics directives are accelerating this reformulation cycle for export-bound film production.
Performance-based supply agreements now specify oxygen transmission rate guarantees and statistical process control indices rather than resin grade designations. Food packaging converters in North America negotiate lot-to-lot coefficient of variation caps below 5 percent, shifting supplier selection toward integrated resin-to-film producers with captive polymerization control. This contractual evolution concentrates procurement among Japanese and German integrated manufacturers with in-house ethylene vinyl alcohol copolymer synthesis capabilities.
EVOH Encapsulation Film Market Segmentation
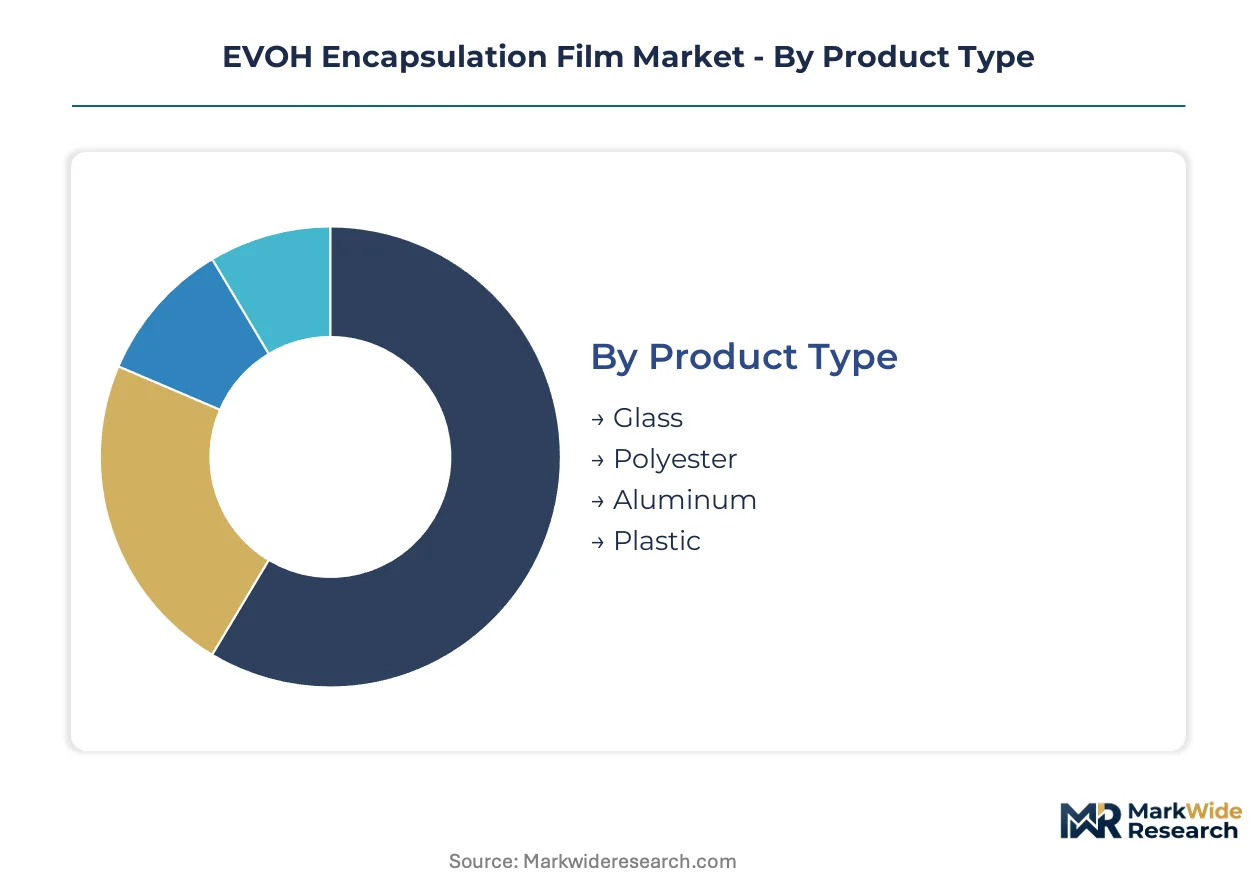
EVOH encapsulation film specifications diverge sharply across substrate compatibility requirements and barrier performance tiers. Manufacturers configure coextrusion lines around end-use oxygen transmission and moisture ingress thresholds rather than commoditized resin grades.
Product Type:
Substrate selection governs lamination temperature tolerance and mechanical handling during automated packaging lines.
- Glass:Thermal stability during lamination cycles up to 150°C makes glass substrates indispensable for photovoltaic backsheet applications. German and Japanese module manufacturers specify glass-EVOH laminates for perovskite cell encapsulation where dimensional stability determines warranty coverage.
- Polyester:Biaxially oriented polyethylene terephthalate films deliver puncture resistance and optical clarity for pharmaceutical blister packs. Mitsubishi Chemical Group and Kuraray target Japanese pharmaceutical converters with coextruded PET-EVOH structures meeting PMDA stability testing protocols.
- Aluminum:Metallized foil laminates provide near-zero moisture transmission for hygroscopic drug formulations and organic electronics.
- Plastic:Polyolefin substrates enable mono-material recyclable barrier structures compatible with mechanical recycling streams.
Mature deployment sits with glass substrates in established photovoltaic applications. Newer deployment is concentrated in plastic substrates as Japan's METI circular economy mandates drive recyclable packaging reformulation.
Application:
End-use performance requirements split manufacturing capacity between commodity oxygen barriers and precision moisture barriers.
- Food Packaging:Extended shelf-life meat and dairy applications in Germany and North America consume multilayer EVOH laminates with oxygen transmission below 1.0 cc per square meter per day. EU packaging waste directives accelerate substitution of aluminum foil with lightweight high-barrier films.
- Pharmaceutical:Primary drug-contact layers for sterile packaging command premium pricing for ultra-low ethylene grades meeting FDA extractables testing protocols. Blister pack manufacturers in Japan and Germany specify 44-48 mole percent ethylene content for 24-month shelf stability.
- Electronics:Organic photovoltaic and display applications specify moisture barriers below 0.1 grams per square meter per day.
- Solar Cells:Perovskite cell manufacturers are displacing conventional ethylene vinyl acetate encapsulants with EVOH moisture barriers.
Food packaging anchors current volume demand. Solar cells are gaining share fastest as IEC certification protocols for organic photovoltaic durability create specification windows for technical premium barriers.
End User:
Procurement sophistication varies sharply across buyer categories, with technical specifications concentrated upstream.
- Manufacturers:Integrated food packaging and pharmaceutical converters negotiate performance-based supply agreements specifying oxygen transmission rate guarantees and lot-to-lot coefficient of variation caps below 5 percent.
- Distributors:Regional film distributors stock standard EVOH grades for mid-tier converters without captive resin synthesis capabilities.
- Retailers:Private-label food retailers in Germany specify barrier film performance indirectly through extended shelf-life requirements.
- Consumers:End-consumer demand manifests through packaged goods freshness expectations rather than direct material specification.
Technical specification authority sits with manufacturers. Volume scaling concentrates through distributors serving second-tier converters.
Distribution Channel:
Channel selection reflects order size, technical service requirements, and geographic proximity to coextrusion capacity.
- Online:Digital procurement platforms serve small-batch pharmaceutical and electronics developers requiring rapid sample qualification.
- Offline:Traditional distributor networks dominate food packaging volume through established relationships with regional converters.
- Direct:Integrated resin-to-film producers Kuraray and Mitsubishi Chemical Group supply major pharmaceutical and photovoltaic manufacturers through dedicated account management.
- Third-Party:Independent agents facilitate cross-border procurement for European converters sourcing Japanese EVOH grades.
Direct channels capture high-specification pharmaceutical and photovoltaic demand. Third-party intermediaries handle geographic arbitrage for standard grades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese resin synthesis capacity supplies film converters across three continents, while German extrusion clusters and US pharmaceutical demand absorb the majority of technical-grade output. Consumption patterns diverge sharply between mature barrier-film markets and emerging photovoltaic applications.
Germany
Extended producer responsibility fees under the national packaging ordinance accelerate aluminum foil substitution in meat packaging laminates. ECHA REACH substance restrictions tighten tie-layer additive specifications ahead of 2025 deadlines. The Rhine-Ruhr industrial corridor hosts integrated resin-to-film production facilities serving pharmaceutical blister and organic photovoltaic encapsulation segments.
United States
FDA extractables testing protocols for primary drug-contact layers sustain premium procurement of ultra-low ethylene EVOH grades. Temperature-sensitive biologics distribution networks expand cold-chain barrier film requirements. Greater Boston and New Jersey pharmaceutical clusters specify 24-month shelf stability laminates for sterile packaging applications.
Japan
METI circular economy roadmaps drive domestic converters toward mono-material recyclable barrier structures with EVOH tie layers. JIS packaging standards mandate lot-to-lot consistency metrics that compress qualification cycles. The Okayama production complex controls captive resin synthesis for solar cell backsheet quality assurance.
India
CDSCO tightening of primary packaging standards for biologics creates specification windows for high-barrier film suppliers. Temperature excursion risks in last-mile pharmaceutical distribution elevate moisture barrier requirements. Maharashtra and Gujarat toll-coextrusion partnerships position converters to serve domestic sterile packaging demand.
South Korea
MFDS stability testing protocols for moisture-sensitive drug formulations align with Japanese pharmaceutical barrier specifications. Display and electronics manufacturers specify precision moisture barriers below 0.1 grams per square meter per day. The Gyeonggi-do semiconductor cluster sources coextruded structures for organic photovoltaic module assembly.
EVOH Encapsulation Film Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across distinct technology tiers. Japanese and European integrated manufacturers control captive resin synthesis, while regional converters rely on toll-coextrusion partnerships for barrier film fabrication. Three archetypes dominate: integrated resin-to-film producers with polymerization assets, specialized multilayer coextrusion houses, and commodity film converters serving standard packaging grades. Capacity expansion and strategic partnerships constitute the primary competitive vectors as photovoltaic qualification timelines compress.
Within the integrated producer tier, Kuraray Co., Ltd and Mitsubishi Chemical Group anchor Japanese supply concentration through captive ethylene vinyl alcohol copolymer synthesis. ARKEMA Group occupies a position among European chemical conglomerates pursuing renewable-content barrier grades. These three entities exemplify the structural divide between upstream resin control and downstream film specification authority.
| Leading Market Players |
|---|
| Kuraray Co., Ltd |
| ARKEMA Group |
| Nippon Gohsei Group |
| Vishakha Polyfab Pvt. Ltd |
| Coveris |
| Mitsubishi Chemical Group |
| Amcor |
| AVI Global Plast |
| UAB Umara |
| Others |
Supply & Pricing Matrix
Performance-based procurement specifications from photovoltaic and pharmaceutical manufacturers are forcing EVOH film suppliers to absorb validation cost burdens while maintaining lot-to-lot consistency guarantees. This demand-side pressure concentrates supply relationships among integrated resin-to-film producers with captive polymerization assets, compressing margins for toll-coextrusion converters without upstream ethylene vinyl alcohol copolymer synthesis.
Pricing Analysis
Margin tightening in standard-grade food packaging reflects polyamide substitution pressure and aluminum foil lightweighting mandates. Three-tier pricing structure across pharmaceutical premium, food-contact standard, and industrial economy levels differentiates by oxygen transmission certification and FDA extractables compliance. Cost-down pressure on commodity tiers accelerates because European converters face extended producer responsibility fees favoring high-barrier films. Pharmaceutical blister manufacturers show least price sensitivity given 24-month shelf stability requirements, while meat packaging laminates exhibit highest elasticity to resin cost fluctuations.
Supply Chain Analysis
Reverse-logistics flows for pharmaceutical blister packaging returns and solar module backsheet refurbishment are minimal given EVOH's single-use barrier function and lamination permanence. Supply concentrates in Japan, Germany, and the United States through Kuraray's Okayama complex, Rhine-Ruhr integrated facilities, and Greater Boston pharmaceutical clusters. Raw material dependencies center on ethylene feedstock from naphtha cracking, vinyl acetate monomer supply, and specialized tie-layer adhesion promoters. Single-source vulnerability pervades the market as two Japanese entities control over seventy percent of global resin synthesis. Distribution runs through direct account management for photovoltaic and pharmaceutical qualification programs, with regional distributors serving standard food packaging converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Perovskite solar cell commercialization is displacing conventional ethylene vinyl acetate encapsulants, creating specification windows for moisture barrier films with sub-0.5 cc oxygen transmission rates. This technology transition compresses qualification timelines and concentrates procurement authority among integrated producers with captive resin synthesis.
For Market Incumbents: Anchor qualification relationships with perovskite cell manufacturers through six-month lot-to-lot consistency validation cycles rather than eighteen-month historical windows. Defend position by deepening backward integration into ethylene feedstock hedging instruments and expanding Okayama or Rhine-Ruhr coextrusion capacity to capture pharmaceutical blister demand from temperature-sensitive biologics distribution networks. Certification investment in emerging IEC organic photovoltaic durability standards represents the critical defensive lever against MXD6 nylon substitution in mid-performance segments. For New Entrants and Emerging Players: CDSCO tightening of primary packaging standards for temperature-sensitive biologics in India opens a window for toll-coextrusion partnerships with Maharashtra and Gujarat converters lacking captive EVOH resin supply. White-space targets include domestic sterile packaging for last-mile pharmaceutical distribution and mono-material recyclable barrier structures compatible with Japan's METI circular economy roadmaps. Go-to-market execution should emphasize rapid sample qualification through digital procurement platforms serving small-batch pharmaceutical developers. For Investors and Strategic Acquirers: Re-rating potential sits with integrated resin-to-film producers given photovoltaic qualification timeline compression and pharmaceutical premium pricing sustainability. Long-term viability over a five-to-ten-year horizon hinges on perovskite solar cell certification protocol adoption and EU REACH substance restriction compliance for tie-layer reformulation. Acquisition target archetype encompasses specialized multilayer coextrusion houses with existing pharmaceutical or organic electronics customer relationships. Signal to monitor: IEC standard finalization for organic photovoltaic module durability creating technical premium windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Feedstock | Mitigates crude oil volatility exposure for non-integrated film converters serving German meat packaging laminates. |
| Capacity Expansion in Okayama or Rhine-Ruhr | Captures pharmaceutical blister demand from Greater Boston and New Jersey sterile packaging clusters. |
| Certification Investment in IEC Standards | Positions EVOH moisture barriers for perovskite solar cell warranty eligibility against conventional encapsulants. |
| Long-term Supply Agreement with Photovoltaic Manufacturers | Locks in six-month qualification cycles for organic photovoltaic module assembly in Gyeonggi-do semiconductor clusters. |
| Joint Venture for India Toll-Coextrusion | Addresses CDSCO packaging standards for Maharashtra and Gujarat biologics distribution networks. |
Research Methodology
Trade databases, customs filings, and SEC 10-K disclosures formed the secondary backbone, cross-referenced with primary interviews involving coextrusion line operators, pharmaceutical packaging procurement leads, photovoltaic module quality assurance directors, and barrier film R&D specialists. Bottom-up triangulation aggregated individual facility capacity and utilization rates against top-down demand modeling from end-use consumption patterns. This approach validated oxygen transmission rate specifications and lot-to-lot consistency metrics across pharmaceutical, food packaging, and organic electronics segments.
Historical trendline analysis established baseline growth patterns across substrate compatibility tiers and application performance thresholds. The analytical framework modeled segmentation dimensions including glass versus plastic substrate selection, oxygen transmission rate certification levels, and regional regulatory compliance clusters. CAGRs were derived from slope analysis of volume trajectories across the projection horizon, incorporating ethylene feedstock cost indices and photovoltaic module installation forecasts as industry-specific inputs.
The model assumes a particular technology adoption path; alternative pathways for perovskite solar cell commercialization or MXD6 nylon barrier substitution would alter the outlook for EVOH moisture barrier demand. Forecasts reflect assumptions regarding IEC certification protocol timelines, EU REACH substance restriction implementation, and Japanese circular economy mandate enforcement. Practitioners should monitor perovskite solar cell warranty eligibility criteria, ethylene feedstock price volatility, and regional recyclability labeling rule evolution for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Easy Peel Film Packaging Market
Poly film
Global Sound Insulation PVB Film Market
Poly film
United States Polycarbonate Sheets and Films Market
Poly film
Global Thermoplastic Films Market
Poly film
Lidding Films Market
Poly film
Poland Plastic Packaging Films Market
Poly film
Bopet Films Market
Poly film
APET Film Market
Poly film
High Density Polyethylene Film Market
Poly film
Global BOPET Packaging Films Market
Poly film
Polystyrene Films Market
Poly film
US Cleanroom Film and Bags Market
Poly film
Morocco Plastic Packaging Films Market
Poly film
PET Lidding Films Market
Poly film
Biaxially Oriented Polyamide (BOPA) Films Market
Poly film
Mexico Plastic Packaging Films Market