
 Continuous Thread Metal Cap Market | 2026-2036
Continuous Thread Metal Cap Market Size, Share, and Industry Trends Forecast 2026-2036
Continuous Thread Metal Cap Market Outlook
The EU Packaging and Packaging Waste Regulation is recalibrating how brand owners specify metal closures across European food and pharmaceutical supply chains. Silgan Holdings leverages its North American manufacturing footprint to sustain volume leadership in standard and specialty continuous thread formats. Crown Holdings anchors its position through captive aluminum supply and deep beverage industry relationships. Guala Closures Group differentiates via premium wine and spirits closure designs that command specification loyalty.
A continuous thread metal cap is a helically threaded closure, typically formed from aluminum, steel, or tinplate, that mates with a corresponding thread profile on a container neck to create a resealable seal; common specifications include 38mm and 43mm neck finishes with torque values engineered to prevent leakage while enabling hand removal. These closures serve primary containment, shelf-life extension, and consumer safety functions across liquid and semi-solid packaged goods. Aluminum dominates material selection for pharmaceutical and personal care applications where lightweighting and corrosion resistance carry premium value, while steel and tinplate sustain cost-competitive positions in mass-market food and household product segments. Tamper-evident and child-resistant cap types are capturing disproportionate margin pools as regulatory stringency rises in pharmaceutical and cannabis-adjacent packaging.
The U.S. FDA enforces child-resistant packaging standards under 16 CFR 1700 that mandate specific torque and opening-force parameters for continuous thread closures on regulated substances. The EU REACH regulation and F-Gas Framework constrain coating chemistries and volatile compound emissions in metal cap manufacturing processes. Stakeholders must monitor evolving extended producer responsibility schemes and material passport requirements that will determine which closure specifications retain market access across major economies.
Market Dynamics
Pharmaceutical serialization mandates and EU Packaging and Packaging Waste Regulation recyclability thresholds are forcing specification-intensive procurement of tamper-evident aluminum continuous thread caps across European and North American supply chains.
Growth Catalysts
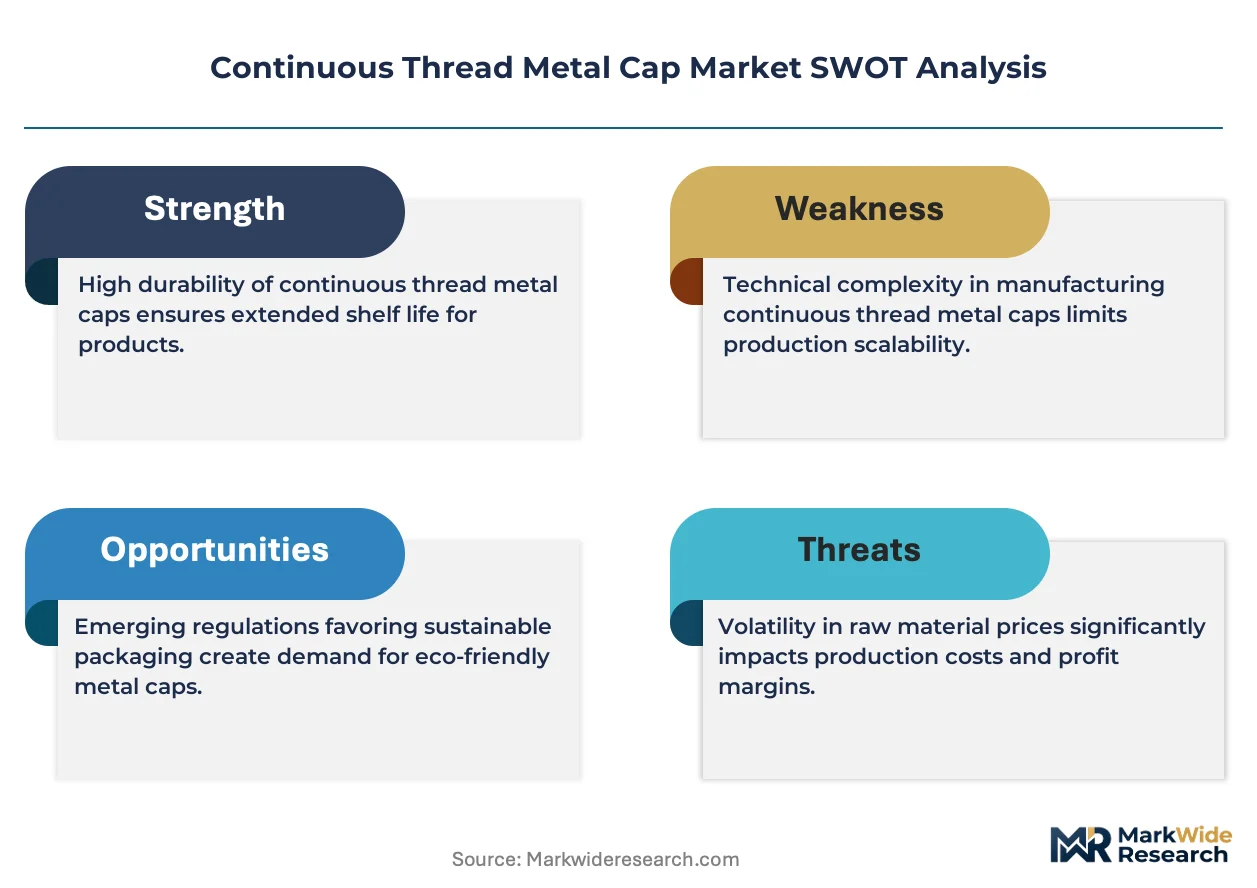
- REACH coating chemistry constraints:ECHA restrictions on volatile compound emissions in metal cap manufacturing are accelerating water-based coating adoption, creating specification premiums for compliant suppliers.
- Pharmaceutical contract manufacturing expansion:Germany's dense cluster of CDMO facilities drives concentrated demand for child-resistant 38mm aluminum closures with integrated desiccant functionality.
- Cannabis packaging regulatory maturation:State-level mandates in the US for tamper-evident child-resistant closures are extending metal cap specifications into previously plastic-dominated dispensary channels.
Market Restraints
- Aluminum ingot price volatility:LME aluminum fluctuations compress margin predictability for converters serving fixed-price beverage contracts.
- Steel closure supply concentration:Tinplate sourcing dependence on integrated European steel mills creates vulnerability to energy cost pass-throughs.
- Plastic closure substitution in mass-market food:Polypropylene flip-top designs undercut metal on unit economics in private-label condiment segments.
Strategic Opportunities
- India pharmaceutical export packaging:CDSCO's alignment with US FDA child-resistant standards creates specification convergence for aluminum CR closures serving ANDA filings.
- Smart closure NFC integration:Convergence of printed electronics with helical metal forms enables authentication and cold-chain monitoring in biologics distribution.
- EU Green Deal EPR incentives:Extended producer responsibility schemes reward mono-material aluminum designs with reduced compliance fees versus multi-component alternatives.
Industry Challenges
- Torque specification calibration talent:Shortage of packaging engineers fluent in 16 CFR 1700 opening-force testing protocols delays US market entry for European converters.
- Legacy capping equipment retrofit costs:Pharmaceutical lines require capital-intensive chuck modifications to handle new-generation linerless aluminum designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Continuous Thread Metal Cap Market |
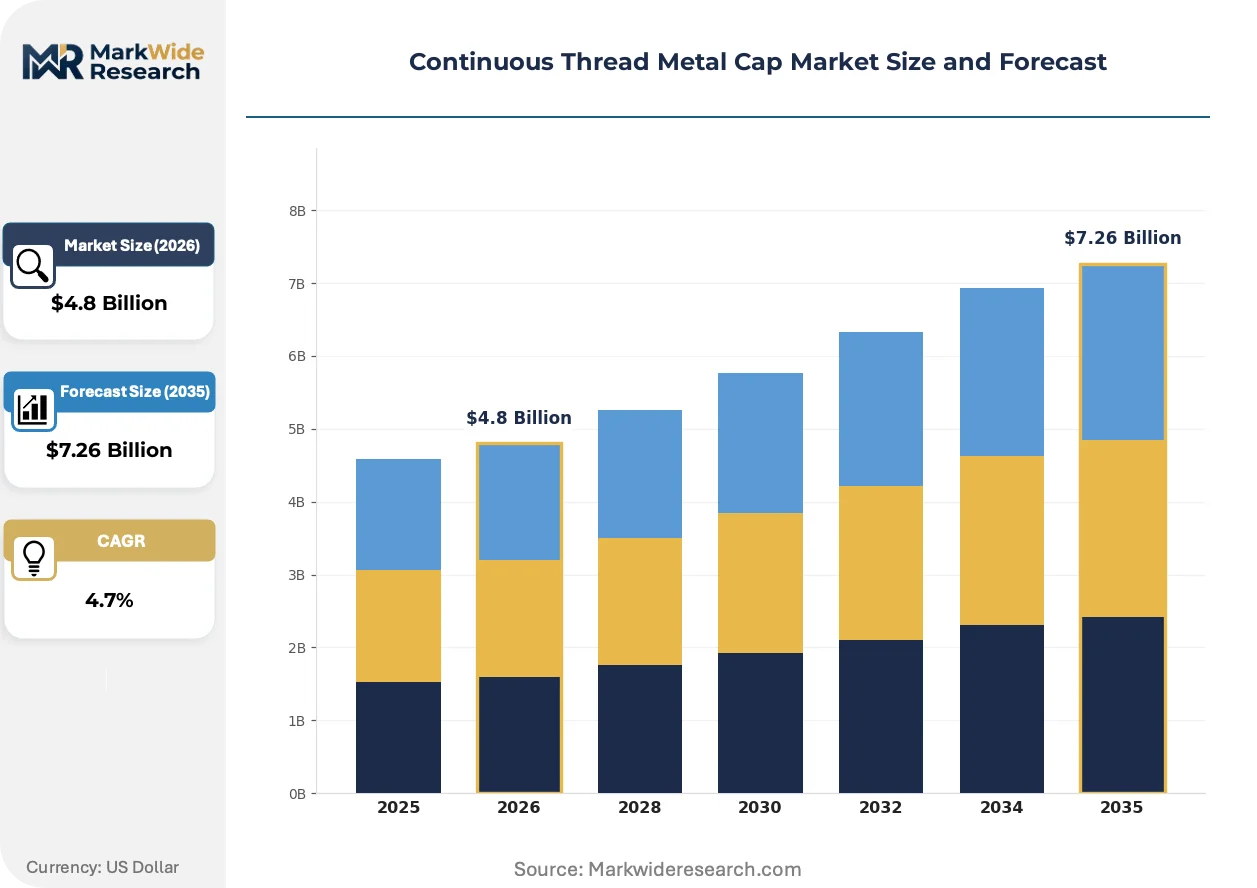
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.26 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Cap Type: Standard Caps, Tamper Evident Caps, Child-Resistant Caps, Specialty Caps Material: Aluminum, Steel, Tinplate, Composite Materials Application: Food & Beverages, Pharmaceuticals, Household Products, Personal Care Closure Size: 40mm, 50mm, 60mm, 70mm |
| Companies Covered | Silgan Holdings Inc., Crown Holdings Inc., Amcor Limited, Guala Closures Group, Berlin Packaging, O.Berk Company, Closure Systems International, Tecnocap Group, Pelliconi & C. S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Continuous Thread Metal Cap Market Strategic Shifts
Digital printing and inline quality verification systems are compressing minimum order quantities and lead times, enabling mass customization of metal closure graphics without die-changeover penalties.
Laser-etched serialization is rewriting how pharmaceutical brand owners manage supply chain traceability. Pfizer and Merck procurement teams now specify GS1-compliant 2D codes directly onto aluminum cap crowns. This capability is compressing the addressable market for plain unmarked closures in regulated drug packaging.
The EU F-Gas Regulation's phasedown of hydrofluorocarbon propellants in coating applications is forcing solvent system transitions across metal closure finishing lines. German and Italian converters face accelerated capital cycles for UV-cure and powder-coat infrastructure. Premium wine and spirits segments absorb cost pass-throughs more readily than mass-market food categories.
Direct-to-contract-manufacturer procurement is consolidating specification authority away from brand owner headquarters. CDMO procurement teams in North Carolina and Bavaria now negotiate aluminum closure terms directly, bypassing traditional distributor intermediaries. This channel compression is most advanced in sterile injectable packaging where lot-traceability requirements demand supplier intimacy.
Continuous Thread Metal Cap Market Segmentation
Continuous thread metal cap procurement splits sharply between commodity-grade beverage specifications and precision-engineered pharmaceutical formats. Understanding where customization premiums accrue versus where scale economies dominate determines supplier positioning and margin capture across converter portfolios.
Cap Type:
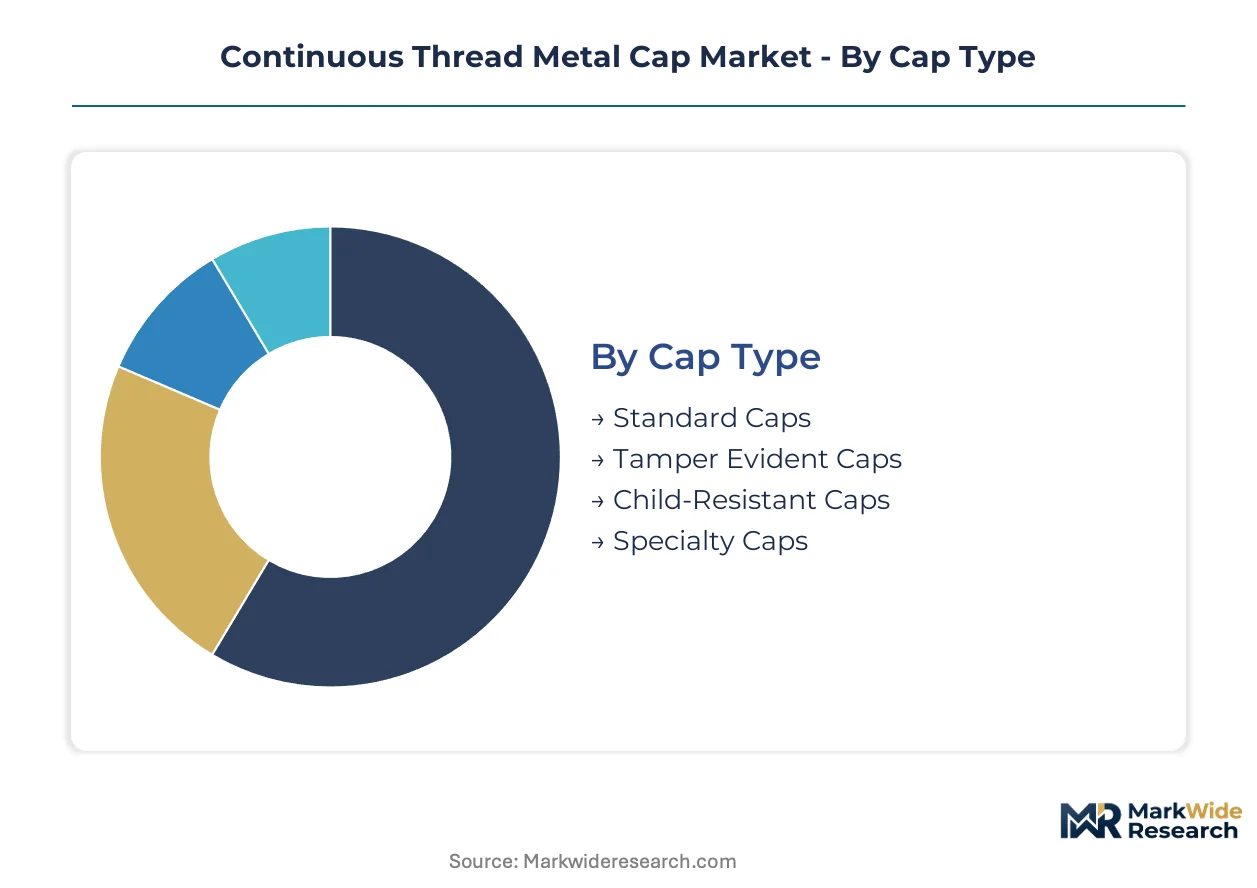
Standardization dominates high-volume beverage lines while tamper-evident and child-resistant variants command specification premiums in regulated end-uses.
- Standard Caps:These helical aluminum or steel closures serve mass-market carbonated beverages and condiments with minimal functional differentiation. German beverage bottlers in Bavaria and Baden-Württemberg specify 38mm aluminum standards in multi-billion-unit annual contracts where hundredths-of-a-cent per-unit pricing shifts determine supplier selection.
- Tamper Evident Caps:Break-band or shrink-sleeve integrated designs provide visible post-fill integrity verification. FDA 21 CFR enforcement on over-the-counter pharmaceuticals and state-level cannabis packaging mandates in California and Colorado are displacing plain closures in dispensary supply chains.
- Child-Resistant Caps:Push-and-turn or squeeze-and-turn mechanisms meeting 16 CFR 1700 opening-force protocols. CDMO procurement teams in Research Triangle Park, North Carolina negotiate directly for 38mm aluminum CR formats with integrated desiccant chambers.
- Specialty Caps:Custom thread pitches, linerless designs, or embossed branding for premium spirits and niche personal care applications.
Most installed capacity flows through Standard Caps. Expansion is steepest in Child-Resistant Caps.
Material:
Cost-performance tradeoffs separate lightweight corrosion-resistant grades from commodity tinplate in price-sensitive food categories.
- Aluminum:Drawn or impact-extruded 1050/1060 series alloys deliver weight savings and inertness for pharmaceutical and personal care applications. REACH coating chemistry constraints on volatile compound emissions are accelerating water-based lacquer adoption across German and Italian converter lines.
- Steel:Cold-rolled tinplate or TFS (tin-free steel) sustains cost-competitive positions in mass-market food packaging. European integrated steel mill energy cost pass-throughs are compressing converter margins on fixed-price condiment contracts.
- Tinplate:Traditional electrolytic tin coating provides solderability and corrosion resistance for acidic food products. Japanese cannery specifications in Kanto and Kansai regions retain this material for heritage brand continuity despite aluminum displacement elsewhere.
- Composite Materials:Aluminum-polymer laminates or steel-plastic hybrids for specialized barrier requirements.
Aluminum commands the dominant share of specification-intensive procurement. Composite Materials are climbing the fastest as smart closure integration demands expand.
Application:
Regulatory stringency and shelf-life requirements fragment demand across divergent torque, coating, and traceability specifications.
- Food & Beverages:Carbonated soft drinks, juices, and condiments drive volume concentration with 38mm and 43mm standard formats. Mexican bottling clusters in Querétaro and Guanajuato specify aluminum closures for export-oriented premium tequila and mezcal brands.
- Pharmaceuticals:Solid oral dose and liquid prescription packaging mandates child-resistant and tamper-evident aluminum designs. Serialization requirements under EU Falsified Medicines Directive and US DSCSA are forcing laser-etched 2D codes onto cap crowns.
- Household Products:Cleaning agents and automotive chemicals utilize steel or tinplate closures where chemical compatibility outweighs lightweighting priorities.
- Personal Care:Cosmetics and hair care applications favor aluminum for corrosion resistance against active formulations.
Food & Beverages absorbs the majority of production volume. Pharmaceuticals is gaining share fastest on regulatory premium capture.
Closure Size:
Neck finish standardization creates format lock-in while emerging beverage categories drive incremental diameter expansion.
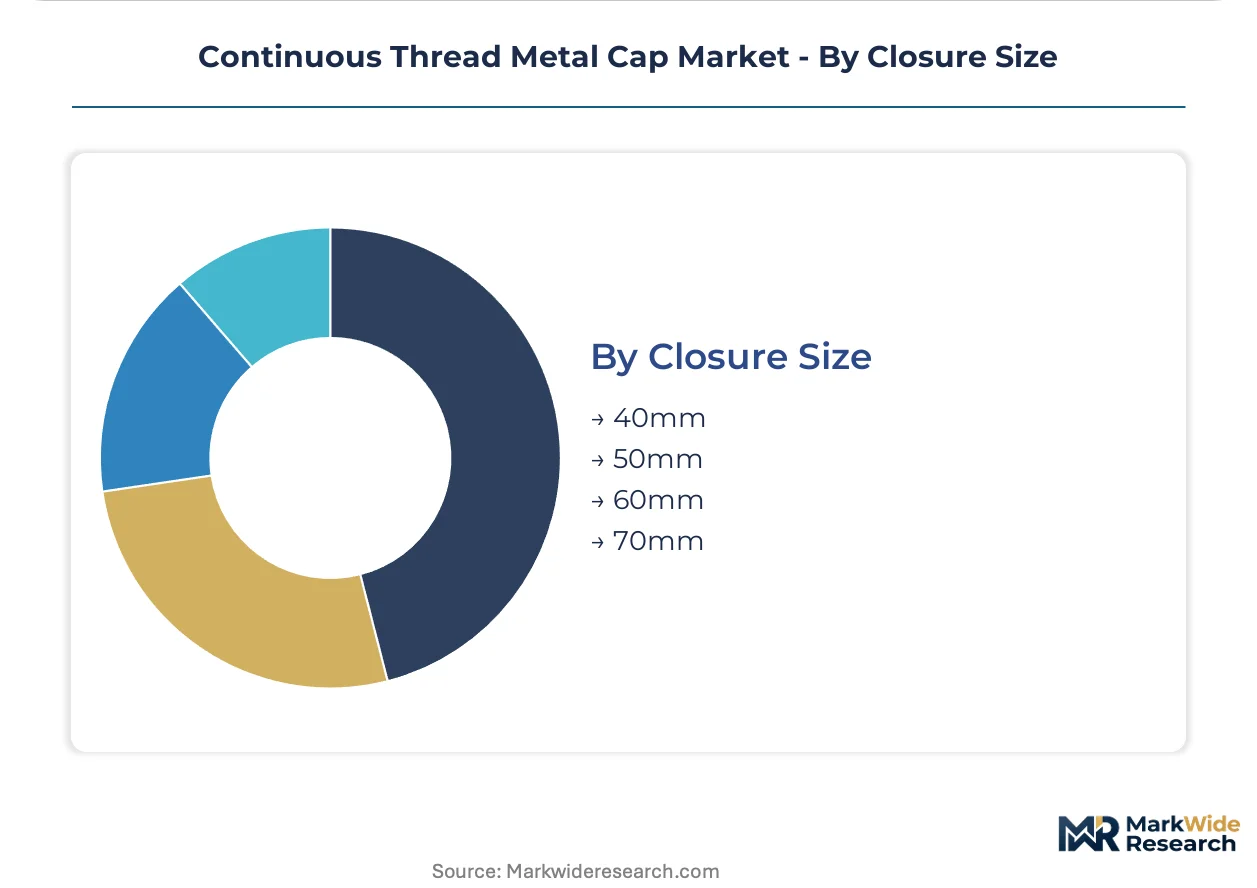
- 40mm:Dominant pharmaceutical and premium spirits specification with established capping equipment compatibility. Bavarian contract manufacturers standardize on 40mm aluminum CR caps for sterile injectable packaging.
- 50mm:Mass-market beverage and food service formats. Indian pharmaceutical exporters targeting ANDA filings are converging on 50mm as CDSCO aligns with US FDA dimensional standards.
- 60mm:Wide-mouth jars and sports nutrition containers. Energy drink brands in Austria and Switzerland specify 60mm aluminum for powder scoop access.
- 70mm:Industrial and institutional packaging with heavy-wall container requirements.
40mm maintains the deepest installed equipment base. 50mm is expanding most quickly on emerging market pharmaceutical export growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The continuous thread metal cap industry traces its modern scale to post-war European beverage packaging standardization, with German aluminum rolling mills and Italian closure tooling shops establishing the foundational supply architecture that persists today.
Germany
Bavarian pharmaceutical contract manufacturers and Baden-Württemberg beverage bottlers drive specification-intensive procurement of 38mm and 40mm aluminum closures. The EU Packaging and Packaging Waste Regulation (PPWR) is recalibrating recyclability thresholds for metal closures across German member state implementations. Stuttgart-area converter clusters are accelerating water-based coating line investments to meet ECHA volatile compound emission constraints.
United States
North Carolina's Research Triangle Park CDMOs and California cannabis packaging distributors are expanding purchases of child-resistant and tamper-evident aluminum formats. FDA enforcement of 16 CFR 1700 opening-force protocols mandates specific torque parameters for continuous thread closures on regulated substances. Mexican bottling clusters in Querétaro and Guanajuato supply aluminum closures for export-oriented premium tequila brands entering US distribution.
Italy
Emilia-Romagna and Lombardy-based converters serve premium wine and spirits brands with specification-loyal closure designs. The EU F-Gas Regulation's phasedown of hydrofluorocarbon propellants is forcing solvent system transitions across Italian metal closure finishing lines. Bologna-area equipment manufacturers are shipping laser-etching systems for pharmaceutical serialization compliance.
India
Maharashtra and Gujarat pharmaceutical exporters are converging on 50mm aluminum child-resistant caps as CDSCO aligns with US FDA dimensional standards for ANDA filings. The country's national pharmaceutical regulator is tightening packaging integrity requirements for sterile injectable exports. Mumbai-Pune corridor contract manufacturers are negotiating direct procurement terms with aluminum closure suppliers, bypassing traditional distributor channels.
Japan
Kanto and Kansai region cannery specifications retain tinplate closures for heritage brand continuity despite aluminum displacement elsewhere. METI industrial standards govern thread profile tolerances for food-contact metal closures in domestic distribution. Osaka-area packaging engineers are retrofitting legacy capping equipment to handle linerless aluminum designs for personal care applications.
Continuous Thread Metal Cap Market Competitive Environment
Premium-margin players sit above commodity-margin players across specification complexity and regulatory certification depth. The vendor base stratifies into three tiers: integrated multinationals with captive aluminum supply, regional specialists with deep beverage or pharmaceutical relationships, and emerging converters serving price-sensitive mass-market segments. Consolidation pressure concentrates among mid-scale European operators facing energy cost pass-throughs from integrated steel mills. Dominant competitive moves include backward integration into aluminum rolling and geographic expansion into Indian pharmaceutical export corridors.
Within the integrated multinational tier, Silgan Holdings Inc., Crown Holdings Inc., and Guala Closures Group occupy positions defined by manufacturing footprint scale and end-use specialization. Silgan exemplifies North American volume leadership through standard and specialty continuous thread formats. Crown anchors its competitive position via captive aluminum supply arrangements and established beverage industry relationships. Guala sits within the premium design tier, representing specification-loyal positioning in wine and spirits closure categories where graphic customization commands sustained margin premiums.
| Leading Market Players |
|---|
| Silgan Holdings Inc. |
| Crown Holdings Inc. |
| Amcor Limited |
| Guala Closures Group |
| Berlin Packaging |
| O.Berk Company |
| Closure Systems International |
| Tecnocap Group |
| Pelliconi & C. S.p.A. |
| Others |
Value Chain & Pricing Dynamics
Water-based coating line conversions across German and Italian converter facilities are simultaneously elevating capital intensity and consolidating supply among ECHA-compliant operators capable of absorbing compliance costs. This technological transition compresses margin pools for smaller European converters while concentrating pricing power among integrated multinationals with captive coating infrastructure.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade aluminum CR closures with integrated desiccant functionality from mass-market beverage standards and commodity tinplate food formats. Price differentiation hinges on certification tier (16 CFR 1700 compliance for US pharmaceutical access) and volume scale (billion-unit beverage contracts versus sterile injectable lot sizes). Cost compression in standard beverage closures is intensifying because LME aluminum volatility exposes converters to margin squeeze on fixed-price annual contracts. Mass-market food bottlers exhibit highest price sensitivity, while CDMO procurement teams in sterile injectable packaging demonstrate lowest sensitivity due to lot-traceability requirements.
Supply Chain Analysis
Packaging engineer shortages in Bavaria and North Carolina are constraining torque specification calibration capacity for new market entrants. Supply concentrates in Germany, Italy, and the United States, with raw material dependencies on LME-traded aluminum ingot, European tinplate from integrated steel mills, and water-based coating chemistries. Single-source vulnerability runs through German pharmaceutical contract manufacturing clusters where specification-intensive procurement locks buyers into qualified supplier relationships. Distribution runs through direct-to-CDMO channels in sterile injectable packaging, bypassing traditional distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Packaging and Packaging Waste Regulation recyclability thresholds and US FDA child-resistant packaging mandates continuously elevate specification barriers and consolidate demand among certified suppliers.
For Market Incumbents: Deepen backward integration into aluminum rolling and water-based coating infrastructure to defend margin position against energy cost pass-throughs from European steel mills. Prioritize certification maintenance for 16 CFR 1700 compliance as plastic substitution threats intensify in mass-market food segments. Capacity addition in Maharashtra and Gujarat pharmaceutical corridors captures ANDA filing growth as CDSCO aligns with US FDA standards. For New Entrants and Emerging Players: The price-point gap between premium wine and spirits closures and commodity beverage standards offers white-space targeting for mid-tier pharmaceutical converters seeking qualified secondary suppliers. Focus penetration on Indian pharmaceutical export packaging where CDSCO regulatory alignment creates specification convergence for aluminum CR closures. Pursue direct procurement relationships with Research Triangle Park CDMOs as channel compression accelerates. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale European converters facing energy cost pass-through pressure from integrated steel mills. Long-term viability favors operators with ECHA-compliant coating lines and established pharmaceutical certification depth. Monitor EU Green Deal extended producer responsibility scheme implementation as an inflection indicator for mono-material aluminum design premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Coating Line Conversion | ECHA volatile compound emission constraints force capital deployment among German and Italian converters. |
| Pharmaceutical Serialization Infrastructure | FDA DSCSA and EU Falsified Medicines Directive mandate laser-etching capability for cap crown traceability. |
| Direct CDMO Procurement Channel Development | Bypassing distributor intermediaries captures sterile injectable lot-traceability requirements in Bavaria and North Carolina. |
| Indian Pharmaceutical Export Certification | CDSCO alignment with US FDA child-resistant standards opens ANDA filing opportunities for aluminum CR closures. |
| Mono-Material Aluminum Design Investment | EU Green Deal EPR incentives reward recyclable single-material formats with reduced compliance fees. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with pharmaceutical packaging engineers, CDMO procurement directors, beverage bottler supply chain managers, and metal converter plant operators with secondary validation. Trade data from EUROSTAT and USITC, ECHA regulatory filings, FDA 510(k) and NDA packaging supplements, and aluminum industry association reports anchor quantitative foundations. Bottom-up segment sizing triangulates against top-down macroeconomic drivers.
Granularity-level modeling operates at cap type, material grade, application, closure size, and regional regulatory cluster dimensions across the analysis window. CAGRs derive from segment-level volume and value build-ups incorporating aluminum ingot price scenarios, pharmaceutical contract manufacturing expansion rates, and regulatory implementation timelines. Industry-specific inputs include ECHA coating chemistry restriction phase-in schedules and CDSCO harmonization progress with US FDA dimensional standards.
Caveats apply where LME aluminum price volatility, EU PPWR implementation divergence across member states, or pharmaceutical serialization deadline extensions could materially shift the outlook. Forecasts reflect assumptions regarding regulatory enforcement consistency and CDMO capital expenditure cycles. Practitioners should monitor ECHA restriction proposal comment periods and CDSCO technical guideline releases for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Japan Plastic Caps and Closures Market
Caps and Closures
Dispensing Spouts Market
Caps and Closures
Snap Cap Vials Market
Caps and Closures
United Kingdom Plastic Caps and Closures Market
Caps and Closures
Fixed Length Seals Market
Caps and Closures
Plastic Caps and Closure Market
Caps and Closures
Sport Caps and Closures Market
Caps and Closures
PET Dome Lids Market
Caps and Closures
Ribbed Phenolic Caps Market
Caps and Closures
Clic Loc Closure Market
Caps and Closures
Child Resistant Dropper Caps Market
Caps and Closures
Bag Closures Market
Caps and Closures
Cuvette Caps Market
Caps and Closures
Spain Plastic Cap and Closure Market
Caps and Closures
Pressure Sensitive Wads Market
Caps and Closures
Latin America Plastic Caps and Closure Market