
 Plastic Water Storage Tank Market | 2026-2036
Plastic Water Storage Tank Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Water Storage Tank Market Analysis
The premium-commodity split in plastic water storage tanks is rebalancing around resin grade and wall thickness specifications, not merely branding. Grupo Rotoplas leverages its vertically integrated resin compounding to command pricing power in rotational-molded premium tanks. Norwesco competes through high-volume blow-molded commodity tanks distributed through farm supply cooperatives. Sintex Industries anchors its position in India's fragmented municipal sector with modular panel tanks designed for rapid assembly.
Plastic water storage tanks are rotationally molded, blow molded, or thermoformed vessels constructed from high-density polyethylene, linear low-density polyethylene, or cross-linked polyethylene, typically featuring UV-stabilized walls between 3 mm and 10 mm thick and designed for static liquid containment at ambient temperatures. Above ground tanks dominate residential and commercial installations due to lower excavation costs and simplified maintenance access, while underground configurations capture premium margin pools in urban commercial developments where space constraints apply. The agricultural end user segment shows the fastest structural expansion as drip irrigation adoption and rainwater harvesting mandates multiply tank deployments across semi-arid farming zones.
EPA's Safe Drinking Water Act and NSF/ANSI Standard 61 govern potable water contact surfaces in the United States, while India's BIS IS 12701 standard mandates specific migration limits for polyethylene tanks used in public water supply. The EU's REACH regulation and F-Gas Directive indirectly shape material selection by restricting certain plasticizers and blowing agents in tank manufacturing processes. Stakeholders must monitor evolving state-level rainwater harvesting mandates and building code amendments that increasingly specify minimum storage capacities for new construction permits.
Market Dynamics
Municipal water management authorities in drought-prone regions are accelerating procurement of large-capacity polyethylene tanks as climate adaptation budgets expand and rainwater harvesting mandates tighten. This structural pull is compressing traditional lead times and forcing resin suppliers to prioritize rotational molding grades over blow molding feedstock.
Growth Catalysts
- Drip irrigation expansion:Agricultural corridors in semi-arid farming zones are deploying tank networks to support precision water delivery systems. India's western states and Australia's wheat belts are driving this demand.
- BIS IS 12701 compliance mandates:India's Bureau of Indian Standards is tightening migration limits for polyethylene tanks in public water supply. Municipal procurement now requires certified potable-grade materials.
- Urban space constraints:Underground tank configurations are capturing premium margin pools in commercial developments where excavation costs are offset by land value premiums.
Market Restraints
- HDPE resin volatility:Feedstock costs for high-density polyethylene fluctuate with crude oil derivatives and naphtha cracking margins. Tank manufacturers lack pricing power to pass through input spikes.
- Rotational molding capacity concentration:Production of large-capacity tanks clusters with specialized molders in Gujarat and Texas. Geographic concentration creates supply bottlenecks during seasonal demand surges.
- Concrete cistern substitution:Commercial developers in Middle Eastern markets favor precast concrete for fire-rated underground storage. Plastic tanks face specification barriers in high-rise building codes.
Strategic Opportunities
- Modular panel tank systems:Rapid-assembly designs for municipal emergency water storage are penetrating India's fragmented urban infrastructure sector. Sintex Industries has established assembly protocols for disaster relief deployments.
- EU F-Gas Directive alignment:Tank manufacturers adopting low-GWP blowing agents for insulated variants qualify for green procurement preferences in European municipal tenders.
- Farm supply cooperative channels:Agricultural end users are consolidating purchases through cooperative buying groups. Direct-to-grower distribution bypasses traditional plumbing merchant markups.
Industry Challenges
- Rotational molding technician scarcity:Skilled operators for large-format polyethylene molding are aging out of the workforce. Training pipelines have not kept pace with seasonal production ramps.
- NSF/ANSI Standard 61 certification timelines:Potable water contact certification requires extended leachate testing protocols. New product development cycles stretch months beyond commercial readiness.
- Legacy tank replacement logistics:Decommissioning fiberglass and metal cisterns involves hazardous material handling. Installers face liability exposure and disposal cost uncertainty.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Water Storage Tank Market |
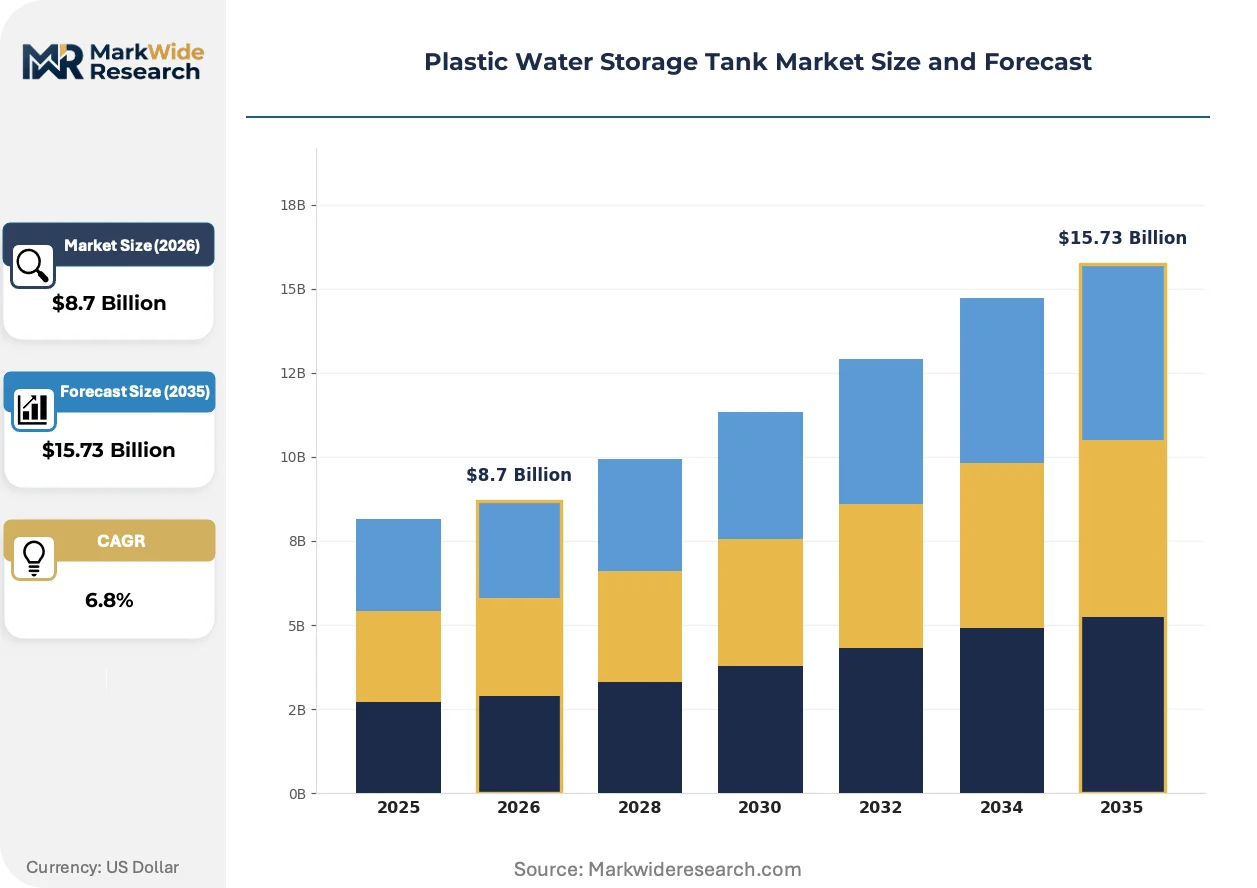
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Above Ground, Underground, Collapsible, Modular End User: Residential, Commercial, Industrial, Agricultural Size: 1000 Liters, 2000 Liters, 5000 Liters, 10000 Liters Application: Potable Water, Irrigation, Fire Protection, Wastewater |
| Companies Covered | Chem-Tainer Industries, Grupo Rotoplas, A. O. Smith, Norwesco, Plasson, Snyder Industries, Poly Processing Company, Supreme Industries, Sintex Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Water Storage Tank Market Emerging Trajectories
Cross-linked polyethylene formulations are displacing conventional linear low-density grades in premium tank segments. Material science advances and regulatory pressure on potable water safety are converging to reshape competitive positioning around resin specification rather than brand recognition.
Triple-layer co-extrusion technology is unifying UV stabilization, impact resistance, and potable-grade inner surfaces into single-pass manufacturing. Agricultural buyers in Australia's Murray-Darling Basin are specifying these tanks for exposed installations. The technology is compressing price premiums between commodity and mid-tier product lines.
EPA's Safe Drinking Water Act enforcement is tightening third-party verification requirements for potable water contact surfaces. Tank distributors in the United States now face liability exposure for uncertified imports. The commercial segment is responding by consolidating supplier relationships around NSF-certified domestic manufacturers.
Cooperative buying groups are consolidating agricultural procurement decisions away from traditional plumbing merchants. Farm supply cooperatives in the US Midwest and Australian grain belts now specify tank capacity and resin grade directly. This channel shift is most visible in orders for 5,000+ liter capacity for center-pivot irrigation systems.
Plastic Water Storage Tank Market Segmentation
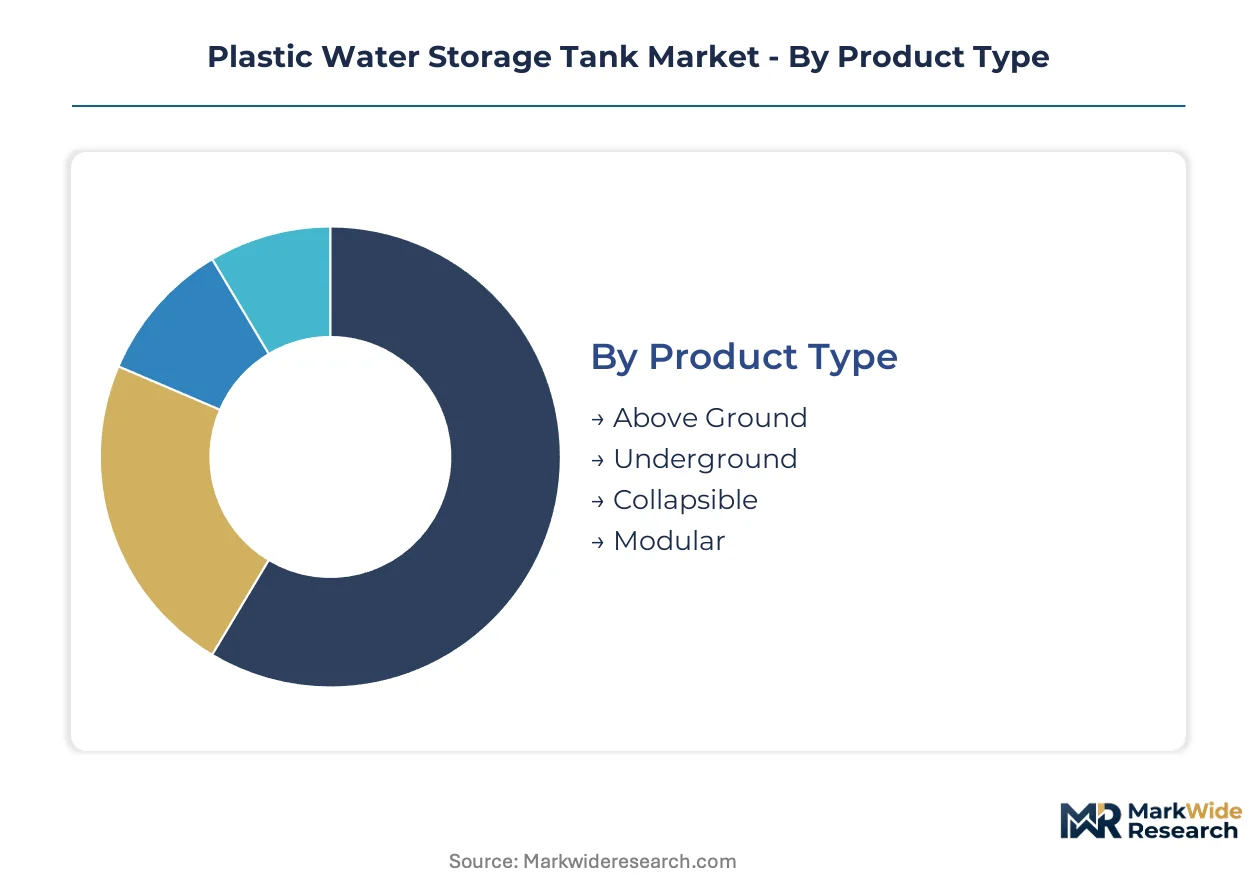
Segmentation in plastic water storage tanks reveals how resin specification, installation constraints, and regulatory exposure partition value capture. Manufacturers align production assets against these divisions rather than pursuing undifferentiated volume.
Product Type:
Capital intensity escalates sharply from collapsible fabric tanks through rotational-molded underground systems requiring precision excavation tolerances and structural load certification.
- Above Ground:Rotational-molded polyethylene vessels with UV-stabilized walls between 3 mm and 10 mm dominate residential and commercial installations. India's western states and Australia's agricultural corridors drive procurement for rainwater harvesting and drip irrigation feed systems.
- Underground:Cross-linked polyethylene or reinforced HDPE configurations withstand soil loading and groundwater pressure. Urban commercial developments in space-constrained markets absorb premium pricing where land value justifies excavation costs.
- Collapsible:Flexible PVC or TPU fabric tanks deploy for emergency water storage and military logistics. Rapid deployment requirements favor low capital entry for temporary applications.
- Modular:Panel-assembled systems from bolted steel or polymer composites enable field customization. India's municipal sector specifies these for disaster relief and urban infrastructure gaps.
Most installed capacity flows through Above Ground. Expansion is steepest in Modular.
End User:
Customer procurement sophistication separates price-sensitive residential buyers from agricultural cooperatives consolidating volume and industrial purchasers enforcing NSF/ANSI Standard 61 or BIS IS 12701 compliance.
- Residential:Individual homeowners purchase through plumbing merchants and hardware retailers. Tank selection prioritizes UV resistance and warranty terms over resin grade certification.
- Commercial:Property developers and facility managers specify underground configurations for fire suppression and landscaping reserves. Building code amendments increasingly mandate minimum storage capacities for new construction permits.
- Industrial:Process water and cooling tower applications require chemical compatibility testing. EPA Safe Drinking Water Act enforcement tightens third-party verification for potable contact surfaces.
- Agricultural:Farm supply cooperatives in the US Midwest and Australian grain belts consolidate purchases for center-pivot irrigation. Orders concentrate at 5,000+ liter capacities with direct-to-grower distribution bypassing traditional merchant markups.
Procurement volume concentrates in Agricultural. Margin compression is deepest in Residential.
Size:
Manufacturing scale economies favor high-volume production of mid-range capacities while extreme sizes require specialized molds and extended lead times.
- 1000 Liters:Compact rotational-molded units serve residential rainwater harvesting and small-scale gardening. Distribution runs through retail hardware channels with minimal installation service attachment.
- 2000 Liters:Standard residential and light commercial capacity balancing mold utilization efficiency with transport logistics. India's BIS certification requirements for potable water contact materials tighten specification at this threshold.
- 5000 Liters:Agricultural sweet spot for drip irrigation buffer storage. Farm cooperatives specify this capacity for center-pivot system feeds across semi-arid farming zones.
- 10000 Liters:Large-format rotational molding requiring specialized equipment and skilled technicians. Municipal procurement in drought-prone geographies accelerates demand as climate adaptation budgets expand.
Production throughput peaks at 2000 Liters. Specification complexity escalates most rapidly at 10000 Liters.
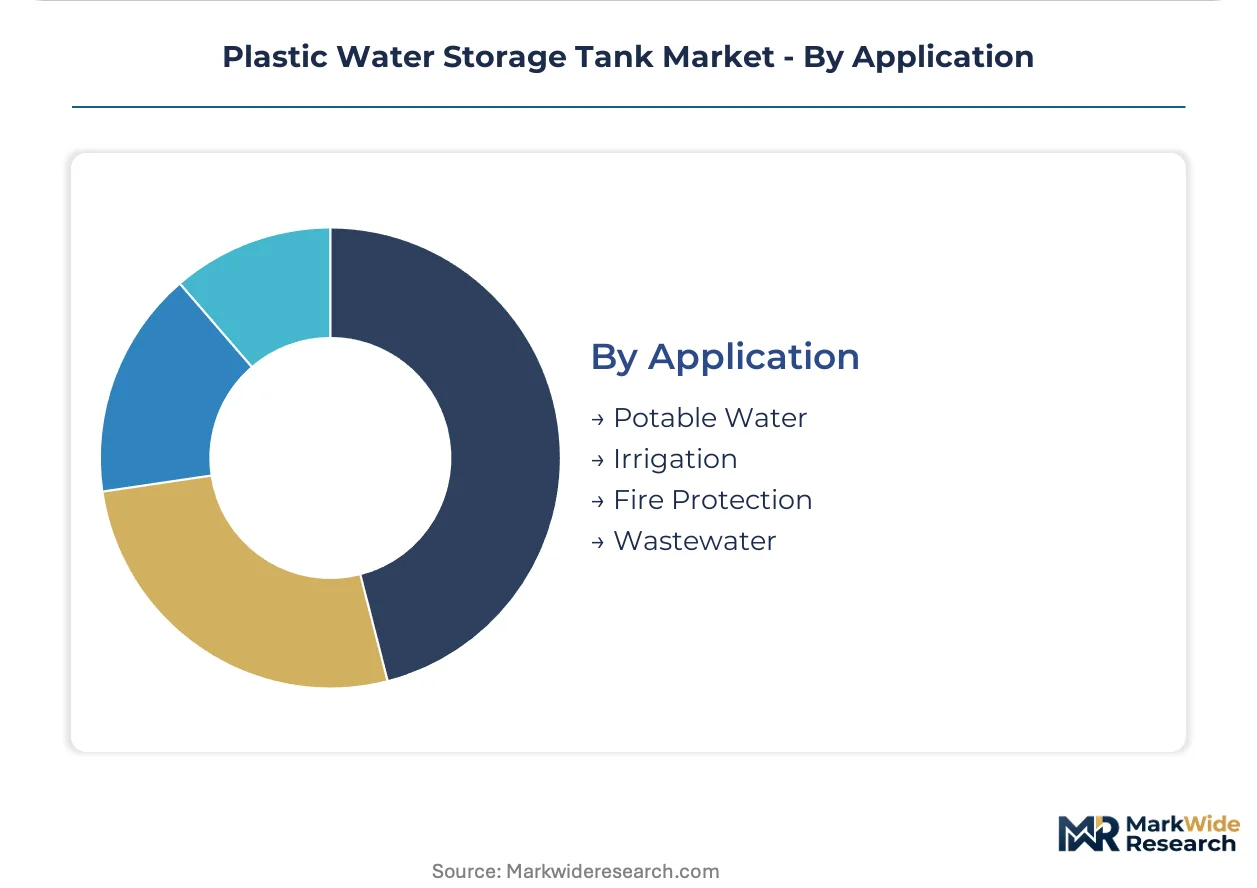
Application:
Regulatory jurisdiction fragments the application landscape with potable water contact surfaces governed by migration limits and fire protection systems subject to building code fire ratings.
- Potable Water:NSF/ANSI Standard 61 and BIS IS 12701 mandate specific leachate testing protocols. Certification timelines extend product development cycles months beyond commercial readiness.
- Irrigation:Agricultural deployment in Australia's Murray-Darling Basin and India's western states specifies triple-layer co-extrusion for UV stabilization and impact resistance. Precision water delivery systems multiply tank network deployments.
- Fire Protection:Commercial building codes in Middle Eastern markets favor precast concrete for underground fire-rated storage. Plastic tanks face specification barriers in high-rise applications.
- Wastewater:Chemical resistance requirements favor cross-linked polyethylene formulations. Industrial process water and septic applications drive demand for corrosion-resistant containment.
Certification burden weighs heaviest on Potable Water. Deployment velocity is highest in Irrigation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rotational molding technicians cluster in Gujarat and Texas, anchoring production capacity for large-format polyethylene tanks. Their geographic concentration shapes supply responsiveness during seasonal demand surges across drought-prone agricultural corridors.
United States
Farm supply cooperatives in the Midwest consolidate procurement for center-pivot irrigation systems. EPA's Safe Drinking Water Act enforcement tightens third-party verification requirements for potable water contact surfaces. Texas hosts specialized rotational molders serving municipal climate adaptation budgets.
India
Municipal authorities in western states accelerate large-capacity tank procurement as rainwater harvesting mandates tighten. BIS IS 12701 standards mandate specific migration limits for polyethylene tanks in public water supply. Gujarat's industrial corridor concentrates rotational molding capacity for rapid-assembly modular panel systems.
Australia
Agricultural buyers in the Murray-Darling Basin specify triple-layer co-extrusion tanks for exposed installations. State-level building code amendments increasingly mandate minimum storage capacities for new construction permits. Wheat belt farm cooperatives drive 5,000+ liter capacity orders for drip irrigation networks.
Germany
Commercial developers favor underground configurations where land value justifies excavation costs. EU F-Gas Directive alignment qualifies manufacturers adopting low-GWP blowing agents for green procurement preferences. Industrial clusters in North Rhine-Westphalia supply insulated tank variants to municipal tender markets.
Brazil
Semi-arid farming zones multiply tank deployments for precision water delivery systems. ANVISA regulates potable water contact materials for public health applications. São Paulo's manufacturing base serves agricultural cooperatives consolidating volume purchases away from traditional merchant channels.
Plastic Water Storage Tank Market Vendor Landscape
Top-tier vendors anchor premium resin specification tiers, while mid-scale fabricators compete on rotational molding throughput and geographic proximity to agricultural demand clusters. The vendor base organizes around three strategic archetypes: vertically integrated resin compounders commanding pricing power, high-volume blow molders distributing through cooperative channels, and modular panel specialists targeting municipal emergency storage. Capacity expansion and backward integration into resin compounding represent the dominant competitive moves as feedstock volatility compresses margins.
Among North American fabricators, Norwesco exemplifies the high-volume cooperative channel archetype, while Chem-Tainer Industries occupies a position within the specialized chemical containment tier. Grupo Rotoplas anchors the vertically integrated premium segment with captive resin compounding capabilities. These three entities represent distinct strategic postures without implying specific market share claims or operational details beyond their evident geographic and structural positioning.
| Leading Market Players |
|---|
| Chem-Tainer Industries |
| Grupo Rotoplas |
| A. O. Smith |
| Norwesco |
| Plasson |
| Snyder Industries |
| Poly Processing Company |
| Supreme Industries |
| Sintex Industries |
| Others |
Supply Flow & Price Mechanics
HDPE resin feedstock costs flow from naphtha cracking margins through rotational molding grades to downstream pricing tiers, with Gujarat and Texas molders capturing margin premiums during seasonal demand surges while blow-molded commodity producers absorb volatility through cooperative channel contracts.
Pricing Analysis
Bundled installation services separate premium rotational-molded tanks from unbundled commodity offerings sold through farm supply cooperatives. Three-tier pricing structure across premium, standard, and economy levels stratifies by resin grade certification and wall thickness specifications. Cost compression in the commodity tier intensifies because HDPE feedstock volatility outpaces manufacturer pricing power. Agricultural cooperatives consolidating 5,000+ liter orders demonstrate lowest price sensitivity, while individual residential buyers through hardware retailers exhibit highest elasticity.
Supply Chain Analysis
Freight costs from Gujarat and Texas production clusters to drought-prone agricultural corridors in India and Australia constrain margin capture for large-format tanks exceeding 10,000 liters. Raw material supply draws from Saudi and Qatari petrochemical feedstock, South Korean LLDPE resin imports, and domestic Indian polyethylene compounding. Single-source vulnerability concentrates in specialized rotational molding technician pools aging out of the workforce. Distribution runs through farm supply cooperatives bypassing traditional plumbing merchant markups in the US Midwest and Australian wheat belts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The plastic water storage tank market functions as a stable compounder anchored by municipal climate adaptation budgets expanding procurement cycles across drought-prone geographies.
For Market Incumbents: Lock in resin compounding capabilities through backward integration into captive polyethylene production, securing margin insulation against naphtha derivative volatility. Expand rotational molding capacity in Texas and Gujarat to compress lead times during seasonal agricultural demand surges. Prioritize NSF/ANSI Standard 61 and BIS IS 12701 certification investments to defend positioning as regulatory migration limits tighten. For New Entrants and Emerging Players: BIS IS 12701 compliance mandates in India open a window for rapid-assembly modular panel tank systems targeting fragmented municipal procurement in western states. Exploit technician scarcity among incumbent rotational molders by deploying automated blow-molding lines for standardized 2,000-liter agricultural capacity. Pursue direct-to-grower distribution partnerships with farm supply cooperatives to bypass entrenched plumbing merchant channels. For Investors and Strategic Acquirers: Consolidation pressure builds where family-owned rotational molding operations lack succession planning and resin compounding capabilities. Target acquisition archetypes include mid-scale Gujarat-based molders with municipal relationships and Texas producers serving climate adaptation budgets. Monitor BIS certification enforcement intensity as the inflection signal for premium-grade resin specification premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive HDPE supply insulates margins from naphtha cracking volatility in Gujarat production clusters. |
| Automated Blow-Molding Capacity Expansion | Standardized 2,000-liter throughput addresses farm cooperative procurement consolidation in US Midwest corridors. |
| NSF/ANSI Standard 61 Certification Investment | Third-party verification defends distributor relationships against EPA Safe Drinking Water Act liability exposure. |
| Modular Panel Tank Assembly Protocols | Rapid-deployment designs penetrate India's fragmented municipal emergency water storage procurement. |
| Farm Supply Cooperative Channel Partnerships | Direct-to-grower distribution bypasses traditional plumbing merchant markups in Australian grain belts. |
Methodological Framework
Bottom-up agricultural and municipal procurement modeling reconciled against top-down resin consumption tracking forms the analytical core of this study. Primary interviews with rotational molding plant managers, farm supply cooperative procurement leads, municipal water authority engineers, and HDPE resin distribution channel partners combined with secondary validation from BIS certification registries, EPA enforcement disclosures, customs trade data, and agricultural cooperative purchasing records. Triangulation across these sources ensures demand-side estimates align with supply-side production capacity assessments.
Historical trendline analysis of rotational molding output and agricultural tank deployment patterns informed projection frameworks across the analysis window. Segmentation dimensions modeled include installation configuration, end-user procurement sophistication, capacity tier, and application regulatory jurisdiction. CAGRs derived from weighted average of bottom-up demand build and top-down supply capacity constraints, incorporating drip irrigation adoption curves and rainwater harvesting mandate implementation timelines as industry-specific inputs.
Revisions become necessary when BIS enforcement intensity shifts, HDPE resin volatility exceeds historical bands, or rotational molding technician attrition accelerates beyond replacement training pipeline capacity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Egypt Plastic Packaging Market
Plastic Packaging
Polyethylene Mailers Market
Plastic Packaging
Packaging Industry in South Africa Market
Plastic Packaging
MDPE Bottles Market
Plastic Packaging
Morocco Plastic Bottles Market
Plastic Packaging
Global Plastic Container Market
Plastic Packaging
Global Single Use Plastic Packaging Market
Plastic Packaging
Post-Consumer Recycled Plastic Packaging Market
Plastic Packaging
Cast Stretch Films Market
Plastic Packaging
Rewritable PVC Cards Market
Plastic Packaging
Corrugated Plastic Trays Market
Plastic Packaging
Nigeria Plastic Bottles Market
Plastic Packaging
Australia and New Zealand Plastic Bottles Market
Plastic Packaging
United Arab Emirates Plastic Bottles Market
Plastic Packaging
Europe Plastic Packaging Films Market
Plastic Packaging
Blow Molded Bottles Market