
 Global EVOH Films for Packaging Market | 2026-2036
Global EVOH Films for Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Global EVOH Films for Packaging Market Analysis
REACH compliance is pivoting the cost-of-entry calculus for EVOH film converters across Europe, forcing reformulation of adhesive tie layers and recyclability certification. Kuraray Co., Ltd. leverages captive ethylene vinyl alcohol resin production to sustain margin control across blown and cast film grades. Mitsubishi Chemical Corporation anchors its position through deep R&D intensity in high-barrier co-extrusion architectures. Berry Global competes on manufacturing scale, operating multiple extrusion lines optimized for pharmaceutical and food barrier specifications.
Ethylene vinyl alcohol films for packaging are high-oxygen-barrier polymer sheets manufactured via blown film extrusion, cast extrusion, or co-extrusion with polyolefin tie layers, typically exhibiting oxygen transmission rates below 1 cc/m²/day at 23°C and 0% relative humidity to preserve perishable contents. Their primary commercial purpose centers on extending shelf life in sensitive food, pharmaceutical, and beverage applications where oxidative degradation drives spoilage or potency loss. Co-extruded film dominates structural volume due to its integration into multilayer retort and vacuum pouches, while blown film extrusion technology leads equipment investment as converters retrofit lines for thinner gauge output. Food packaging occupies the deepest margin pool given processor willingness to pay for barrier performance in red meat, processed cheese, and ready-meal segments.
The EPA governs volatile organic compound emissions from solvent-based lamination processes in the United States, while EFSA and REACH jointly shape migration limits and substance authorization across European food-contact applications. Japan's METI promotes circular economy roadmaps that incentivize mono-material EVOH-compatible structures with improved sortability. Stakeholders must monitor evolving extended producer responsibility frameworks and decide whether to prioritize chemical recycling partnerships or mechanical recycling-compatible film designs.
Market Dynamics
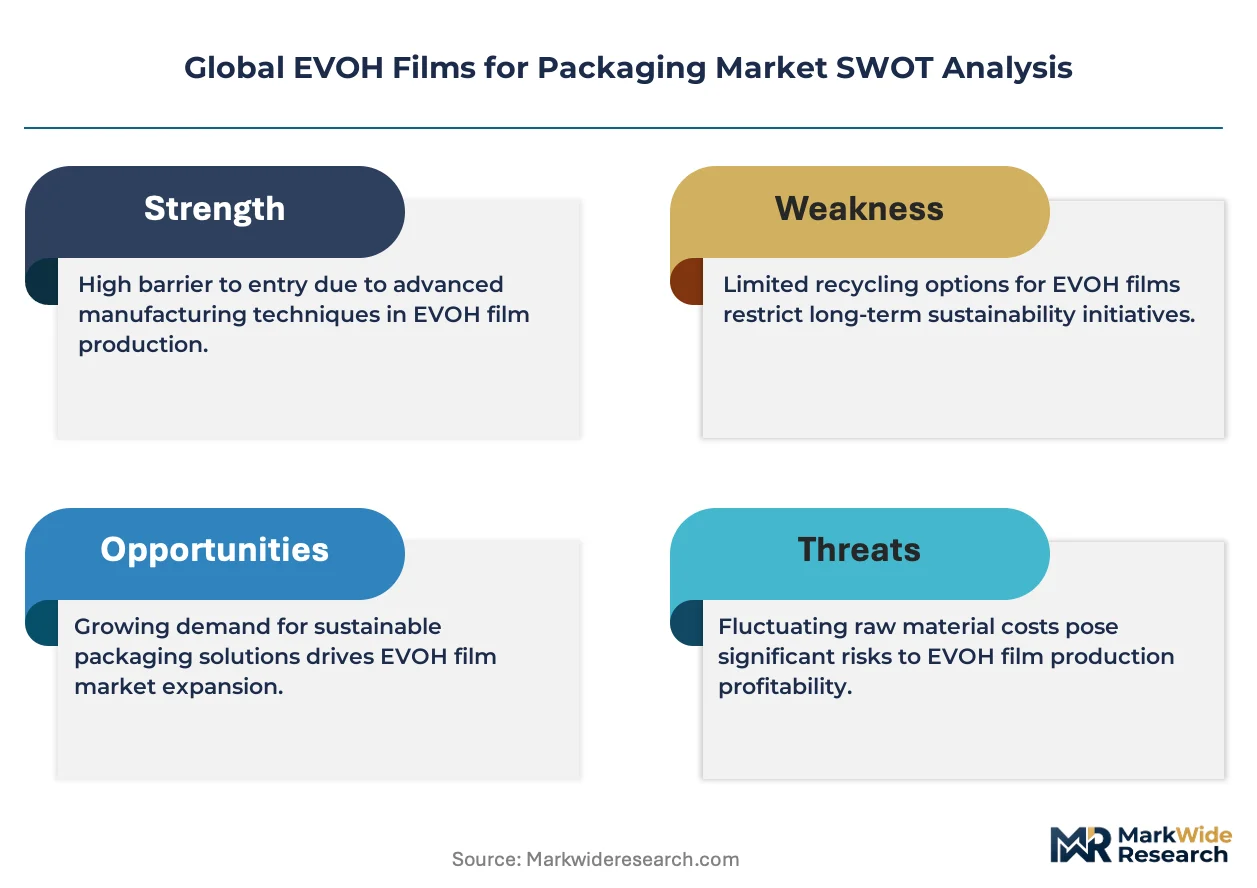
Recyclability mandates under the EU Green Deal are forcing converters to redesign multilayer EVOH structures, eliminating incompatible adhesives and certifying mono-material compatibility while preserving oxygen barrier performance below 1 cc/m²/day.
Growth Catalysts
- REACH substance authorization:ECHA's tightening restrictions on perfluorinated compounds are redirecting food-contact film demand toward EVOH barrier layers as compliant alternatives in vacuum pouch applications.
- Red meat processor requirements:Extended shelf-life specifications for case-ready beef and pork are absorbing higher EVOH film volumes in modified atmosphere packaging configurations.
- Japan's circular economy roadmap:METI incentives for sortable packaging structures are accelerating adoption of EVOH-compatible mono-material films with improved mechanical recycling yields.
Market Restraints
- Ethylene vinyl alcohol resin supply concentration:Captive production by Asian petrochemical conglomerates limits third-party converter access to specialty copolymer grades during supply shocks.
- Co-extrusion equipment capex intensity:Seven-layer blown film lines with precision gauge control require capital commitments that exclude mid-scale regional converters from barrier film certification.
- Polyamide substitution in retort:Nylon-MXD6 barrier layers are capturing select high-temperature sterilization applications where EVOH hydrolysis limits performance.
Strategic Opportunities
- Pharmaceutical blister underpenetration:Germany's centralized drug distribution hubs present untapped demand for EVOH cold-form foil replacements in moisture-sensitive solid dose packaging.
- Digital printing convergence:Integration of HP Indigo and EVOH co-extrusion lines enables short-run customized barrier films for craft food brands seeking rapid SKU rotation.
- US state extended producer responsibility laws:California and Oregon packaging fee structures reward converters demonstrating mechanical recycling compatibility for EVOH-containing structures.
Industry Challenges
- Multilayer delamination expertise gap:Adhesive tie layer formulation chemistry requires polymer scientists scarce in regional extrusion clusters outside Germany, Japan, and the United States.
- Migration testing timeline compression:EFSA compliance documentation for novel co-extruded structures extends commercialization cycles by 18-24 months versus standard polyolefin films.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global EVOH Films for Packaging Market |
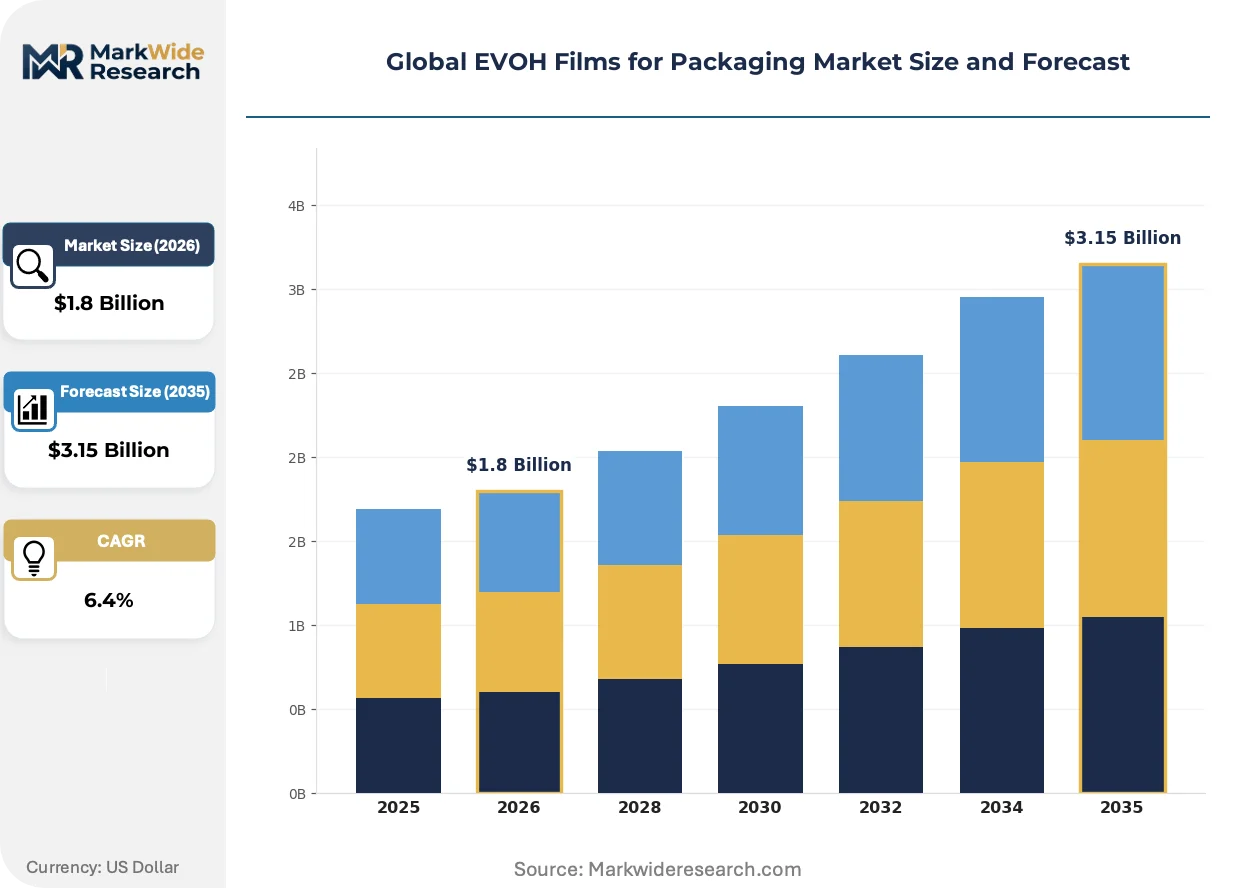
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blown Film, Cast Film, Co-extruded Film, Laminated Film End Use Industry: Food Packaging, Pharmaceutical Packaging, Beverage Packaging, Industrial Packaging Thickness: Below 20 Microns, 20-50 Microns, 50-100 Microns, Above 100 Microns Technology: Vacuum Coating, Extrusion Coating, Injection Molding, Blown Film Extrusion |
| Companies Covered | Kuraray Co., Ltd., Winpak, Mondi, Mitsubishi Chemical Corporation, Berry Global, Coveris, ARKEMA Group, Nippon Gohsei Group, BUERGOFOL GMBH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global EVOH Films for Packaging Market Emerging Trajectories
Active barrier technologies and regulatory redesign requirements are compressing product development cycles while expanding the addressable application set for high-performance oxygen barrier films.
Thin-gauge blown film extrusion is overtaking conventional cast methods in EVOH barrier production. Meat and dairy processors in Germany and the United States are specifying 12-micron and thinner structures to reduce material intensity per package. This gauge compression is overtaking historical thickness norms and forcing equipment suppliers to retrofit cooling and haul-off systems for stable bubble formation at reduced wall thickness.
REACH Annex XIV authorization procedures are tightening scrutiny on adhesive substances in food-contact laminates. ECHA's 2023-2024 candidate list updates are excluding several conventional tie-layer chemistries from authorized use. European converters serving ready-meal and processed cheese segments are responding with accelerated validation of bio-based adhesive alternatives compatible with EVOH-polyolefin co-extrusion.
Retailer sustainability scorecards are restructuring procurement priorities for barrier film buyers. Walmart's packaging sustainability index and similar programs at Ahold Delhaize are displacing price-only supplier selection with certified recyclability metrics. This behavioral shift is most visible in United States private-label food packaging, where converters must demonstrate mechanical recycling compatibility to maintain volume allocations.
Global EVOH Films for Packaging Market Segmentation
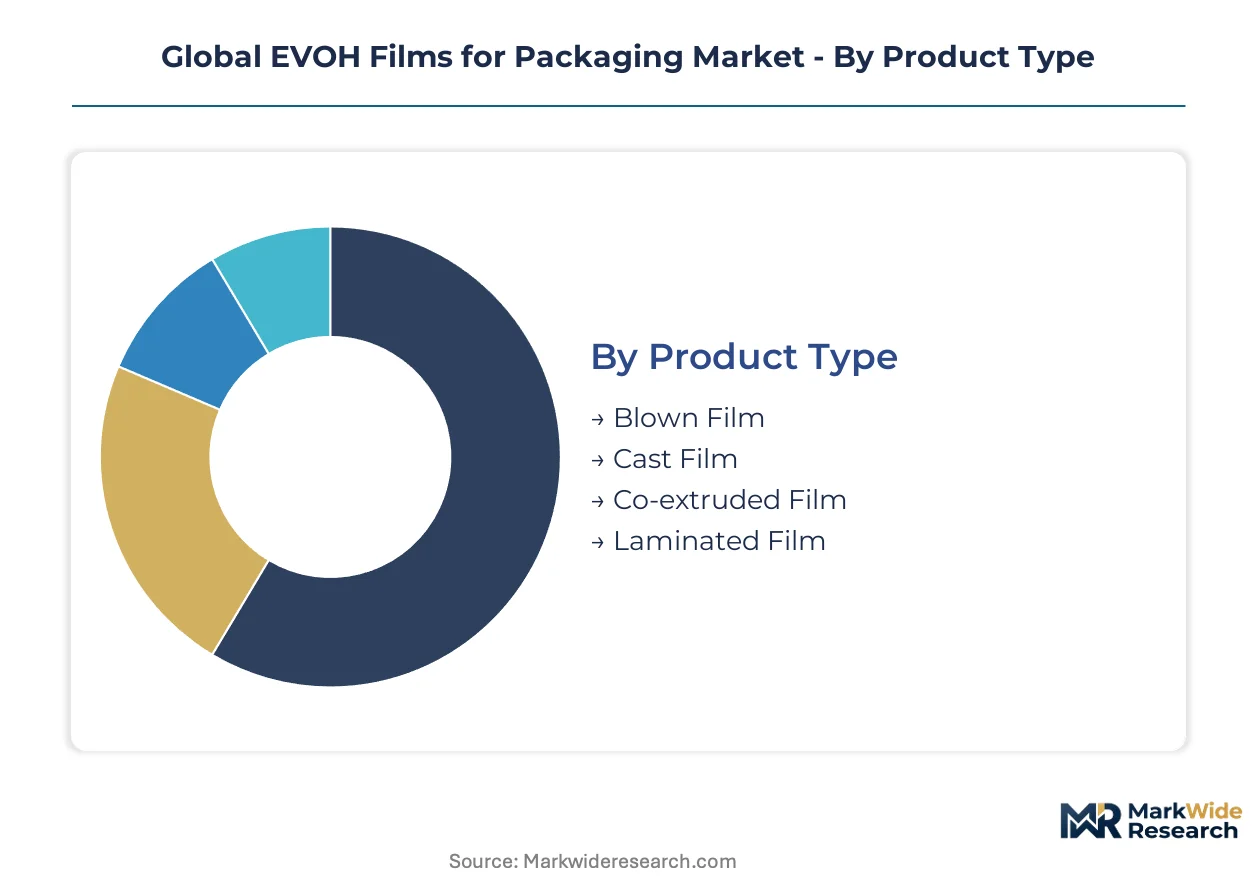
EVOH film converters configure production lines around distinct technical specifications that govern barrier performance, processing economics, and regulatory compliance. Each segmentation dimension carries discrete margin profiles and capital requirements that reshape competitive positioning across food, pharmaceutical, and industrial applications.
Product Type:
Customization intensity varies sharply across this category, with co-extruded multilayer structures demanding precise tie-layer chemistry versus standardized blown film grades.
- Co-extruded Film:Multilayer architectures integrate EVOH with polyolefin tie layers through simultaneous extrusion, achieving oxygen transmission rates below 1 cc/m²/day. Demand concentrates in Germany and Japan where meat processors specify retort-compatible structures for extended shelf-life beef and pork applications. REACH Annex XIV scrutiny on adhesive substances is accelerating validation of bio-based tie-layer alternatives.
- Blown Film:Tubular extrusion through annular dies produces biaxially oriented barrier layers with superior puncture resistance. United States dairy processors are absorbing thinner 12-micron specifications to reduce material intensity per cheese package. Equipment suppliers are retrofitting cooling and haul-off systems for stable bubble formation at reduced wall thickness.
- Cast Film:Flat die extrusion onto chilled rolls yields uniform gauge distribution for high-clarity pharmaceutical applications.
- Laminated Film:Adhesive bonding of pre-formed EVOH layers with PET or aluminum substrates serves high-barrier blister and pouch formats.
Leading the category by volume: Co-extruded Film. Expanding most quickly: Blown Film.
End Use Industry:
Margin capture follows spoilage sensitivity, with oxygen-critical applications commanding premium pricing over industrial protective formats.
- Food Packaging:Modified atmosphere and vacuum configurations for red meat, processed cheese, and ready-meals absorb the deepest volume pools. Walmart's packaging sustainability index is displacing price-only supplier selection with certified recyclability metrics in United States private-label procurement.
- Pharmaceutical Packaging:Cold-form foil replacements and moisture-sensitive solid dose barriers present untapped demand in Germany's centralized drug distribution hubs. EFSA compliance documentation for novel co-extruded structures extends commercialization cycles versus standard polyolefin films.
- Beverage Packaging:Aseptic carton and pouch applications preserve flavor stability in sensitive juice and dairy alternatives.
- Industrial Packaging:Protective wraps for electronics and chemicals leverage EVOH barrier properties against oxidative corrosion.
Dominating revenue contribution: Food Packaging. Steepest expansion trajectory: Pharmaceutical Packaging.
Thickness:
Downgauging pressure from sustainability mandates is compressing historical thickness norms while demanding precision equipment upgrades.
- Below 20 Microns:Ultra-thin specifications require advanced gauge control systems to maintain barrier integrity. Japanese converters are prioritizing these grades under METI circular economy incentives for sortable mono-material structures.
- 20-50 Microns:Mid-range thickness dominates current food pouch and vacuum bag production across European retail supply chains.
- 50-100 Microns:Heavy-duty specifications serve industrial protective and pharmaceutical cold-form applications.
- Above 100 Microns:Structural rigidity for deep-draw thermoforming and industrial drum liners.
Current volume leader: 20-50 Microns. Gaining share fastest: Below 20 Microns.
Technology:
Equipment investment intensity separates scalable extrusion platforms from specialized coating operations serving niche barrier requirements.
- Blown Film Extrusion:Seven-layer lines with precision gauge control dominate equipment investment as converters retrofit for thinner output. Capital commitments exclude mid-scale regional converters from barrier film certification in emerging production clusters.
- Extrusion Coating:Continuous EVOH layer deposition onto moving substrates serves high-volume lamination operations.
- Vacuum Coating:Vapor deposition of supplemental barrier layers onto EVOH substrates addresses ultra-high-performance specifications.
- Injection Molding:Limited EVOH application due to thermal degradation sensitivity during melt processing.
Primary equipment base: Blown Film Extrusion. Climbing the fastest: Extrusion Coating.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated film extrusion clusters in Germany, Japan, and the United States concentrate EVOH film capacity near meat, dairy, and pharmaceutical packaging demand centers. Tax incentives for circular economy infrastructure in the European Union and METI-backed recycling roadmaps in Japan accelerate regional specialization.
Germany
Red meat processors in Lower Saxony and Bavaria specify retort-compatible EVOH structures for extended shelf-life beef and pork applications. REACH Annex XIV authorization procedures force converters to validate bio-based adhesive tie-layer alternatives. The Düsseldorf-Cologne industrial corridor hosts multilayer co-extrusion facilities serving centralized European retail distribution.
Japan
METI circular economy roadmaps incentivize mono-material EVOH-compatible structures with improved mechanical recycling yields. Tokyo-Osaka pharmaceutical packaging clusters absorb high-barrier films for moisture-sensitive solid dose applications. Chubu region converters retrofit blown film lines for sub-20-micron gauge output under sustainability mandates.
United States
EPA volatile organic compound regulations govern solvent-based lamination processes in food-contact applications. California and Oregon extended producer responsibility laws reward mechanical recycling compatibility for EVOH-containing structures. Midwest dairy processors in Wisconsin and Minnesota specify thinner 12-micron cheese packaging films to reduce material intensity.
China
Dual carbon goals and GB standards for food-contact materials reshape barrier film specifications in Yangtze River Delta processing hubs. Shanghai and Jiangsu province converters expand co-extrusion capacity for domestic ready-meal packaging demand. NMPA pharmaceutical packaging regulations drive adoption of high-oxygen-barrier structures in regional drug distribution networks.
France
EU Green Deal recyclability mandates eliminate incompatible adhesives from multilayer EVOH structures in Île-de-France packaging operations. ANSM migration limits for food-contact substances extend commercialization timelines for novel co-extruded architectures. Auvergne-Rhône-Alpes specialty chemical clusters supply bio-based tie-layer formulations for compliant laminate production.
Global EVOH Films for Packaging Market Vendor Landscape
Japanese and German producers anchor one tier; North American specialists hold manufacturing scale advantages in pharmaceutical and food barrier specifications. The vendor base concentrates around integrated resin producers and diversified packaging conglomerates with captive extrusion assets. Three archetypes dominate: petrochemical-backed resin-to-film integrators, diversified multinational packaging suppliers, and regional co-extrusion specialists. Competitive moves center on backward integration into ethylene vinyl alcohol resin supply and retrofitting of seven-layer blown film lines for thin-gauge certification.
Within the integrated-resin tier, Kuraray Co., Ltd. and Mitsubishi Chemical Corporation occupy positions shaped by captive ethylene vinyl alcohol copolymer production. Berry Global exemplifies the scale-driven multinational archetype with multiple extrusion lines optimized for barrier specifications. Among European specialists, Mondi and Coveris represent converters navigating REACH compliance through redesigned multilayer architectures with certified recyclability.
| Leading Market Players |
|---|
| Kuraray Co., Ltd. |
| Winpak |
| Mondi |
| Mitsubishi Chemical Corporation |
| Berry Global |
| Coveris |
| ARKEMA Group |
| Nippon Gohsei Group |
| BUERGOFOL GMBH |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap converters in Germany and Japan anchor supply discipline through multi-generational resin procurement relationships, translating captive ethylene vinyl alcohol access into pricing power that shields specialty grades from spot-market volatility. This ownership pattern concentrates margin capture among integrated producers while forcing independent converters toward thinner-gauge specifications to defend position.
Pricing Analysis
Short lead-time premiums separate urgent pharmaceutical orders from standard food-packaging contracts, with three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on REACH certification status and volume scale, with certified recyclability commanding margin premiums. Cost compression in standard-grade blown film intensifies because Asian resin conglomerates restrict third-party copolymer access. Food processors exhibit highest price sensitivity; pharmaceutical buyers accept premiums for documented migration compliance.
Supply Chain Analysis
Dual-sourcing requirements from Walmart and Ahold Delhaize procurement teams mandate multi-supplier qualification for EVOH tie-layer chemistries, preventing single-source dependence. Geographic supply concentrates in Japan, Germany, and the United States where integrated extrusion clusters serve regional meat and dairy packaging hubs. Raw material dependencies center on ethylene vinyl alcohol resin, polyolefin tie layers, and bio-based adhesive alternatives. Single-source vulnerability from captive Asian resin production threatens converter margins. Distribution runs through regional film distributors serving processor co-manufacturing networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around REACH compliance investments that exhaust mid-scale converter capital reserves. EFSA migration testing timelines and seven-layer equipment capex intensity force weaker players toward exit or acquisition.
For Market Incumbents: Acquire distressed seven-layer blown film lines in the United States Midwest to capture dairy processor volume migrating toward thinner specifications. Backward integration into bio-based tie-layer formulation secures REACH Annex XIV positioning against adhesive substitution threats. Channel control through direct mill relationships with red meat processors in Lower Saxony defends margin pools from Asian resin-to-film integrators. For New Entrants and Emerging Players: Digital printing convergence routes enable short-run customized barrier films for craft food brands seeking rapid SKU rotation without legacy extrusion asset burdens. Pharmaceutical blister underpenetration in Germany presents the most penetrable white-space target, with cold-form foil replacement demand absorbing premium-grade co-extruded structures. Go-to-market positioning through HP Indigo integration partnerships bypasses seven-line capital barriers. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional co-extrusion specialists with validated recyclability certifications in France and Germany. Long-term viability across the analysis window hinges on mechanical recycling compatibility demonstrated through retailer sustainability scorecards. The signal to watch is California extended producer responsibility fee structures expanding to additional states, accelerating compliant-converter valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Supply | Kuraray and Mitsubishi Chemical sustain margin control through captive ethylene vinyl alcohol production. |
| Thin-Gauge Equipment Retrofit | Converters in Wisconsin and Minnesota deploy 12-micron specifications to reduce material intensity per cheese package. |
| Bio-Based Tie-Layer Validation | Auvergne-Rhône-Alpes chemical clusters supply REACH-compliant adhesive alternatives for European laminate production. |
| Digital Printing Line Integration | HP Indigo convergence enables short-run barrier films for craft food brands requiring rapid SKU rotation. |
| Recyclability Certification Investment | Walmart's packaging sustainability index rewards mechanical recycling compatibility with volume allocation priority. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this study, supplemented by primary interviews with extrusion plant managers, procurement leads at meat and dairy processors, distribution channel partners, and technical R&D directors. EFSA substance authorization databases, EPA volatile organic compound emission records, METI circular economy roadmap documentation, and Kuraray and Mitsubishi Chemical securities disclosures provided validation layers. Bottom-up capacity estimates from regional co-extrusion clusters were reconciled against top-down resin consumption figures.
Data-stream reconciliation across production volume, trade flow, and end-use absorption metrics shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include product type architecture, end-use industry spoilage sensitivity, thickness gauge tier, and regional regulatory cluster. CAGRs derived from historical trajectory analysis adjusted for REACH redesign mandates and thin-gauge adoption curves. Industry-specific forecast inputs incorporated seven-layer line installation rates and pharmaceutical blister conversion timelines.
Inputs from ECHA candidate list updates and NMPA pharmaceutical packaging regulations were available through the study window; gaps in private converter margin disclosure introduce uncertainty bands around profitability estimates. Forecasts reflect assumptions regarding bio-based adhesive validation timelines and extended producer responsibility law expansion. Deviation in ethylene vinyl alcohol resin supply concentration or EFSA migration testing compression would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Polyethylene Terephthalate (PET) Shrink Films Market
Poly film
Nylon Films for Liquid Packaging Market
Poly film
Cast Stretch Packaging Films Market
Poly film
Timber Wrap Films Market
Poly film
Global Reclosable Films Market
Poly film
Printed Plastic Films Market
Poly film
Silicone-Coated PET Films Market
Poly film
Global Biaxially Oriented Polypropylene (BOPP) in Films and Sheets Market
Poly film
Co Extruded Films Market
Poly film
Polypropylene Film Market
Poly film
Global Polyethylene Packaging Market
Poly film
Biaxially Oriented Polypropylene (BOPP) Films Market
Poly film
PVC Films Market
Poly film
India BOPP Films Market
Poly film
Morocco Plastic Packaging Films Market
Poly film
Formable Films Market