
 Plastic Films Market | 2026-2036
Plastic Films Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Films Market Intelligence
The BRCGS for Packaging Materials certification is rotating market access towards suppliers with documented quality management systems. Amcor plc leverages its global manufacturing footprint to serve multinational food and beverage clients. Berry Global Group specializes in engineered materials for healthcare and personal care applications. Sealed Air Corporation differentiates through its portfolio of protective and food packaging solutions which address complex logistical requirements.
Plastic films are thin, continuous polymeric materials, often with a thickness below 0.25 millimeters. Their primary function is to provide a barrier against moisture, oxygen, and contaminants in packaging and industrial applications. Polyethylene and polypropylene films dominate the product landscape due to their versatility and cost-effectiveness in flexible packaging. The agriculture application, while smaller, shows significant potential for specialized films used in greenhouses and for mulching to improve crop yields.
Regulations from the US Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) govern material composition for food-contact applications. Concurrently, the EU's REACH framework and China's GB standards impose strict controls on chemical substances used in film production. Future profitability for film converters will hinge on developing cost-effective, recyclable, and compliant materials for a circular economy.
Market Dynamics
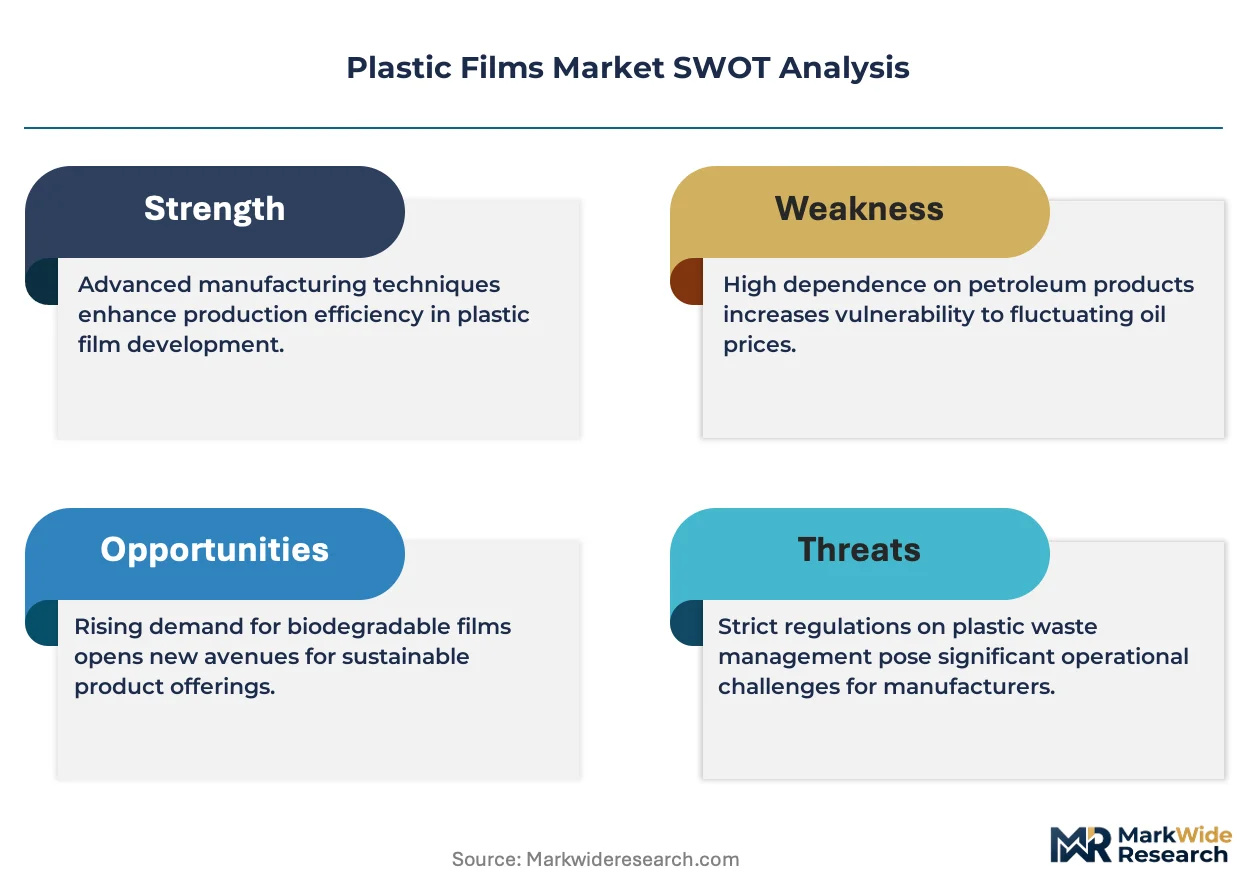
The plastic films market is defined by the structural tension between demand for higher-performance barrier materials in sensitive applications and intensifying regulatory pressure to design for a circular economy. This dynamic forces innovation toward materials that are simultaneously functional and recyclable.
Growth Catalysts
- Sustainable Policy Mandates:Initiatives like the EU Green Deal are creating regulatory pull for mono-material and recycled-content films, compelling brand owners to transition packaging portfolios and stimulating new material development.
- Pharmaceutical Packaging Demand:The need for high-barrier, sterile packaging for medications, particularly in unit-dose formats like blister packs, drives consumption of specialized PVC, PVDC, and advanced polyolefin films.
- Food Sector Expansion in Asia:Rising disposable incomes in Southeast Asian nations, including Vietnam and Indonesia, are boosting demand for flexible food packaging that extends shelf life and improves food safety.
Market Restraints
- Feedstock Price Volatility:Film production costs are directly tied to the fluctuating prices of petrochemical feedstocks like naphtha and natural gas, creating margin pressure and pricing uncertainty for converters. li>Chemical Substance Regulations: Frameworks such as the EU's REACH and China's GB standards impose stringent controls and high compliance costs on the chemical additives used to impart specific properties to films.
- Threat from Paper-Based Alternatives:Growing consumer and regulatory preference for materials perceived as more sustainable is increasing the substitution risk from paper and fiber-based packaging solutions in certain applications.
Strategic Opportunities
- Biodegradable Agricultural Films:Significant opportunity exists in developing and scaling biodegradable mulching films that enhance crop yields but do not require post-season collection, addressing labor costs and plastic waste in agriculture.
- Smart Packaging Integration:Converging high-barrier film technology with printed electronics like NFC or RFID tags offers a path to value-added solutions for supply chain traceability and anti-counterfeiting in the pharmaceutical sector.
- African Consumer Goods Market:The underpenetrated market for packaged consumer goods in several fast-growing African economies presents a long-term opportunity for establishing flexible packaging infrastructure for essential food and personal care items.
Industry Challenges
- Circular Economy Infrastructure Gap:A primary operational hurdle is the lack of scaled, efficient collection, sorting, and advanced recycling infrastructure capable of processing flexible post-consumer film waste back into high-quality resin.
- Certification Compliance Burden:Achieving and maintaining certifications like the BRCGS for Packaging Materials requires significant upfront investment in quality management systems, documentation, and audits, posing a challenge for smaller converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Films Market |
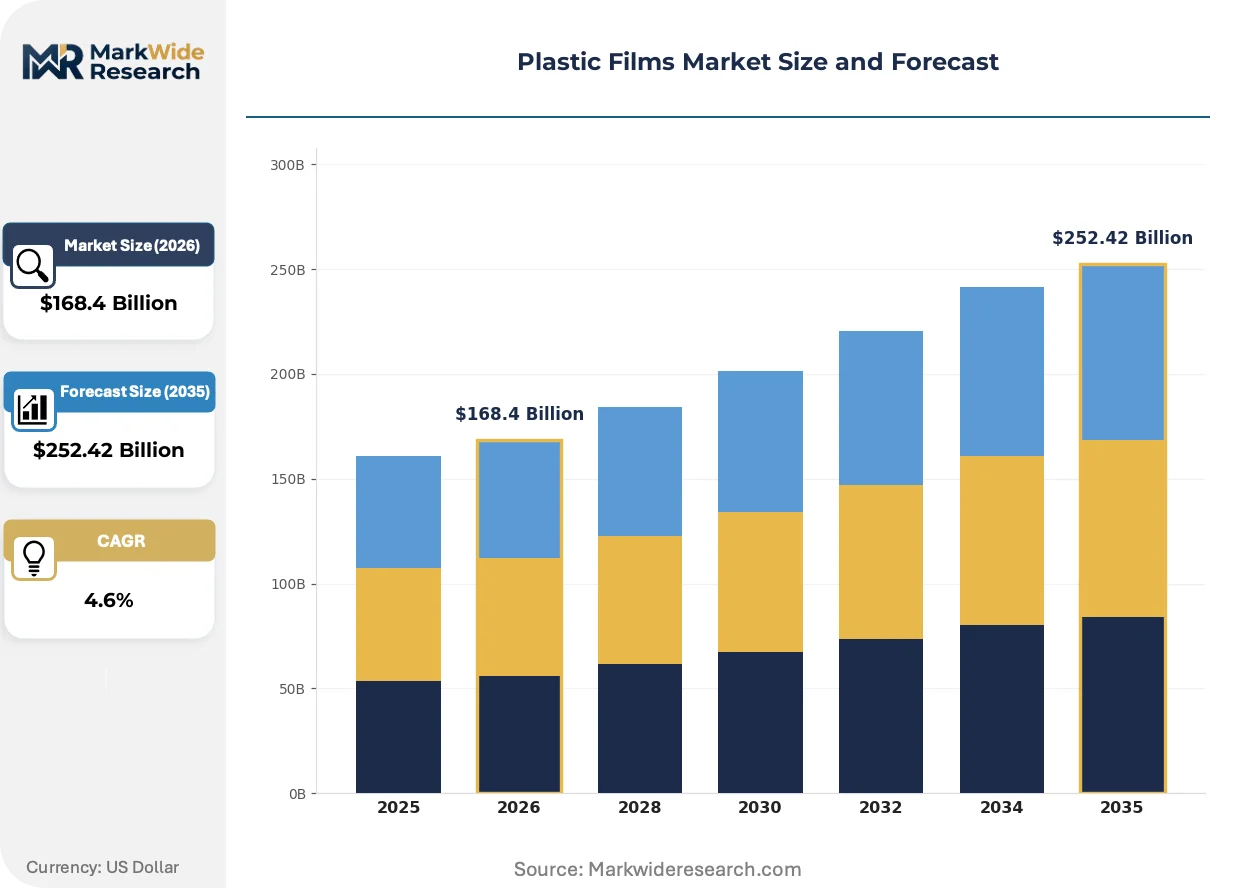
| Market Size in 2026 | $168.4 Billion |
| Market Size in 2035 | $252.42 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Polyvinyl Chloride, Polyester, Nylon, Polycarbonate Application: Packaging, Labeling, Agriculture, Insulation, Lamination, Protective Coverings End User Industry: Food & Beverage, Electronics, Pharmaceuticals, Construction, Personal Care, Textiles Packaging Type: Rolls, Sheets, Pouches, Bags, Blister Packs, Wraps |
| Companies Covered | Amcor plc, Berry Global Group, Sealed Air Corporation, Toray Industries, SABIC, DuPont, Uflex, Jindal Poly Films, Novolex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Films Market Strategic Shifts & Innovations
Material science advancements are focused on achieving enhanced functionality with less material, while regulatory frameworks simultaneously push the industry toward greater circularity. This dual pressure is accelerating the development of novel film structures and recycling technologies.
Multi-layer co-extrusion technology creates composite films by combining distinct layers for barrier, sealant, and structural properties into a single, cohesive material. Food and medical device manufacturers are adopting these advanced films to extend product shelf life and ensure package integrity. This technology is miniaturizing the total material required for a given performance specification, reducing overall package weight and resource consumption.
The US Food and Drug Administration (FDA) is actively updating its requirements for using post-consumer recycled (PCR) content in food-contact packaging applications. This regulatory evolution compels film converters to validate the purity of their recycled material streams through extensive testing and process control. The flexible packaging segment for fresh produce and ready-to-eat meals is most impacted, driving investment in advanced decontamination technologies.
A visible shift in purchasing criteria is elevating the importance of suppliers holding globally recognized quality and safety certifications. This trend is displacing procurement models based solely on price, particularly within the pharmaceutical and infant nutrition end-use markets. The BRCGS for Packaging Materials standard is becoming a prerequisite for market access when serving multinational consumer goods clients across Europe and North America.
Plastic Films Market Segmentation
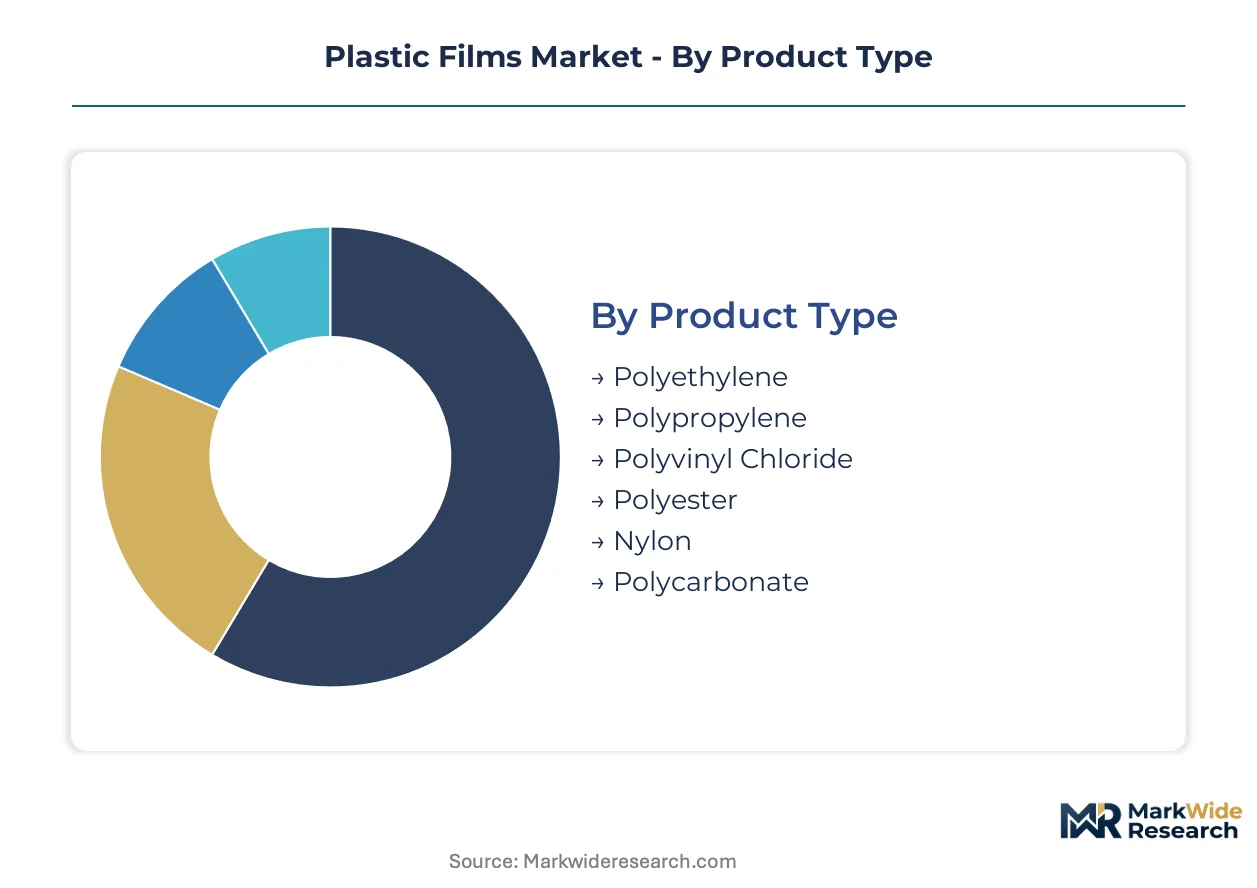
Plastic films market segmentation provides a granular view of material preferences, application drivers, and end-user requirements shaping industry dynamics. Understanding these distinct segments is vital for converters to align product development with specific market demands and regulatory shifts. This detailed breakdown highlights areas of sustained growth and emerging opportunities for specialized film solutions.
Product Type:
The product type segment faces varying degrees of substitution pressure from alternative materials and evolving sustainability mandates.
- Polyethylene:This versatile thermoplastic polymer is widely used in flexible packaging for its excellent moisture barrier, heat sealability, and cost-effectiveness. Demand for polyethylene films remains high in food packaging and agricultural applications due to its broad utility.
- Polypropylene:Known for its high stiffness, clarity, and barrier properties against oxygen and moisture, polypropylene films are essential in snack packaging, bakery items, and medical device sterilization. Its performance characteristics drive consistent demand across sensitive applications.
- Polyvinyl Chloride:PVC films offer good clarity and impact resistance, finding use in blister packaging for pharmaceuticals and some fresh food wraps.
- Polyester:These films provide high tensile strength and temperature resistance, making them suitable for lidding films and retort pouches in demanding food applications.
- Nylon:Nylon films deliver superior puncture resistance and oxygen barrier, often used in vacuum packaging for meats and cheeses to extend shelf life.
- Polycarbonate:Characterized by high impact strength and optical clarity, polycarbonate films are deployed in specialized applications like electronic displays and graphic overlays.
Polyethylene retains volume leadership; Polypropylene holds the steepest expansion curve.
Application:
Demand for plastic films across applications is driven by specific functional requirements and evolving consumer needs.
- Packaging:This application dominates the market, encompassing flexible packaging for food, beverages, and consumer goods, focusing on barrier properties, shelf-life extension, and product protection. Regulatory shifts toward mono-materials influence innovation in this segment.
- Agriculture:Films in agriculture include greenhouse covers, silage films, and mulching films, designed to enhance crop yields, conserve water, and protect against pests. Biodegradable innovations offer significant future growth potential in this sector.
- Labeling:Plastic films provide durable and moisture-resistant substrates for product labels across various industries, ensuring brand visibility and regulatory compliance.
- Insulation:Films are used in construction and industrial settings for thermal and electrical insulation, contributing to energy efficiency and safety.
- Lamination:Lamination applications involve bonding films to other materials to enhance strength, barrier properties, or aesthetic appeal in printed media and packaging.
- Protective Coverings:These films safeguard surfaces during manufacturing, transport, or storage, preventing scratches, contamination, and damage in industrial and consumer goods.
Packaging applications command the largest share, while agriculture demonstrates significant growth potential through specialized film development.
End User Industry:
Regulatory frameworks and specific product protection needs significantly influence film selection across end-user industries.
- Food & Beverage:This industry relies heavily on plastic films for preserving freshness, extending shelf life, and ensuring food safety for a vast range of products. Regulations from the US FDA and EFSA govern material composition for food-contact applications.
- Pharmaceuticals:The pharmaceutical sector demands high-barrier, sterile films for blister packs, sachets, and medical device packaging, ensuring product integrity and patient safety. Unit-dose formats drive specialized film consumption.
- Electronics:Films are used for protective packaging of sensitive electronic components, anti-static applications, and as dielectric layers in various devices.
- Construction:Films serve as vapor barriers, protective membranes, and insulation components in building and infrastructure projects.
- Personal Care:This sector utilizes films for packaging toiletries, cosmetics, and hygiene products, focusing on aesthetic appeal and product protection.
- Textiles:Films are employed in textile packaging, garment bags, and protective covers for fabrics and apparel.
The Food & Beverage industry represents the largest volume consumer, with Pharmaceuticals driving demand for advanced barrier technologies.
Packaging Type:
Packaging type is often dictated by the product's form factor, required protection, and logistical considerations for end-users.
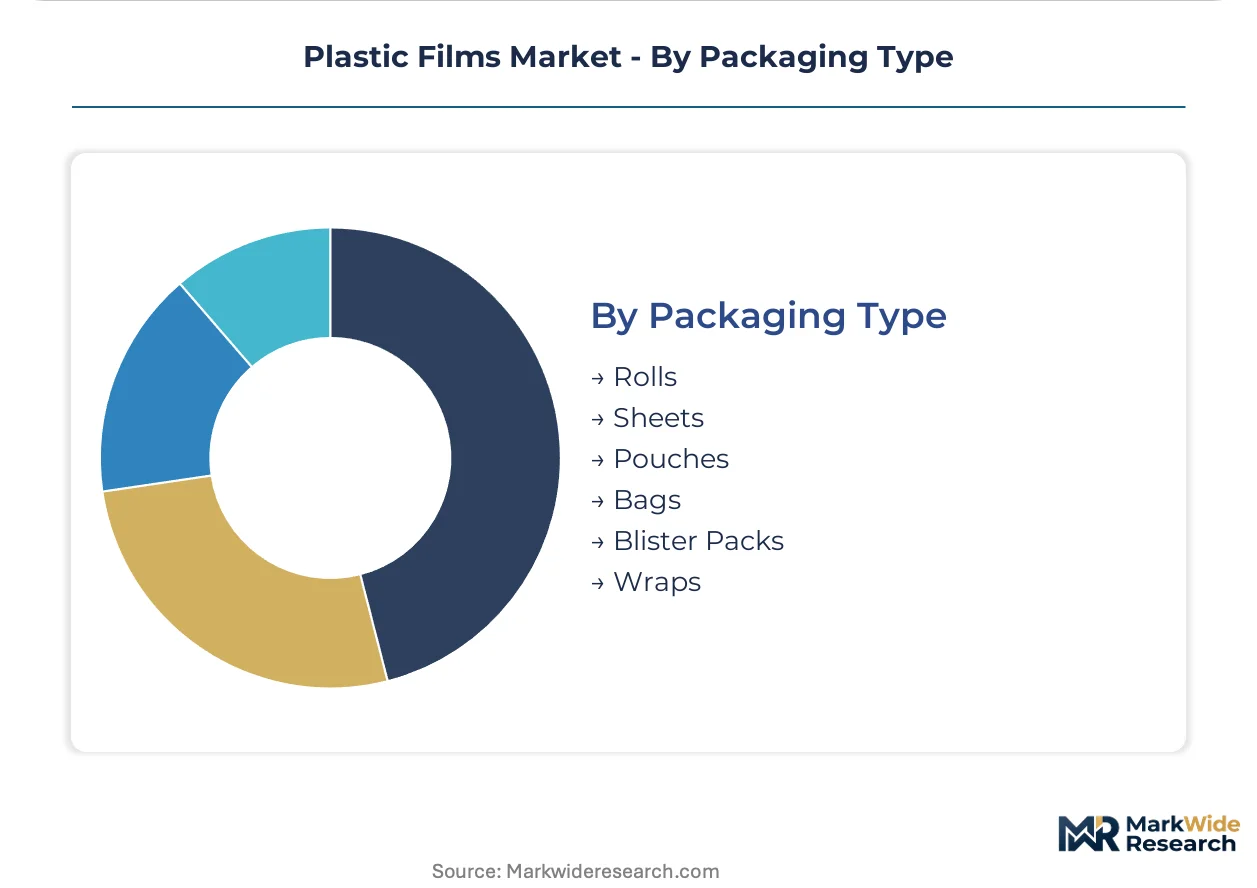
- Rolls:Films in roll form are primary inputs for automated packaging lines, enabling efficient high-volume production of flexible packaging formats.
- Sheets:Plastic film sheets are used for thermoforming applications, creating trays, clamshells, and other rigid or semi-rigid packaging structures.
- Pouches:Flexible pouches offer lightweight, convenient, and resource-efficient packaging for food, beverages, and personal care products.
- Bags:Bags, including stand-up pouches and shopping bags, are widely used for consumer goods due to their versatility and cost-effectiveness.
- Blister Packs:These rigid or semi-rigid packages, often for pharmaceuticals or small consumer items, provide individual product protection and tamper evidence.
- Wraps:Films used as wraps provide protective covering for palletized goods, food items, and industrial components, ensuring containment and cleanliness.
Rolls and sheets form the foundational supply, while pouches and blister packs command premium value due to their specialized functionality.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer-archetype concentration from the food and beverage and pharmaceutical sectors drives significant plastic film demand across diverse global regions. These industries require specialized packaging solutions for product protection and shelf-life extension. Regulatory frameworks and evolving consumer preferences further influence regional market dynamics for film converters.
United States
The United States market for plastic films is propelled by robust demand from the food packaging and pharmaceutical industries. The US Food and Drug Administration (FDA) actively updates requirements for post-consumer recycled content in food-contact applications, compelling material innovation. Major industrial clusters in the Midwest and Southeast are investing in advanced recycling infrastructure for flexible packaging waste.
Germany
Germany's plastic films market benefits from strong pharmaceutical packaging requirements and advanced manufacturing capabilities. The EU Green Deal and national circular economy initiatives are creating regulatory pull for sustainable mono-material films. The Rhine-Ruhr region, a hub for chemical production, concentrates research and development efforts in high-performance and recyclable polymer films.
China
China exhibits substantial demand for plastic films, fueled by its vast consumer goods market and expanding e-commerce sector. China's GB standards impose strict controls on chemical substances, influencing film production and material composition. Industrial zones in the Yangtze River Delta and Pearl River Delta are expanding capacity for flexible packaging to meet domestic and export needs.
Vietnam
Vietnam's plastic films market is experiencing rapid expansion due to rising disposable incomes and a burgeoning food processing industry. Government policies supporting foreign investment in manufacturing contribute to increased production capabilities. Ho Chi Minh City and Hanoi concentrate significant flexible packaging operations, catering to both local consumption and export markets across Southeast Asia.
India
India's plastic films consumption is driven by a large and growing population, increasing urbanization, and a developing organized retail sector. The Bureau of Indian Standards (BIS) sets quality and safety benchmarks for packaging materials, influencing local production. Gujarat and Maharashtra are key manufacturing hubs for plastic films, serving the food, personal care, and agricultural sectors.
Plastic Films Market Key Industry Players
Player mix skews toward established global manufacturers with extensive production capabilities and specialized material science firms. The market structure exhibits a tiered consolidation, with a few large integrated players alongside numerous regional specialists. Key competitive moves include strategic acquisitions to expand technology portfolios and significant investments in developing sustainable and recyclable film solutions.
Among global manufacturers, Amcor plc and Berry Global Group exemplify companies leveraging their broad geographic reach and diversified product offerings to serve multinational clients. Sealed Air Corporation occupies a position focused on differentiated protective and food packaging solutions, addressing complex logistical requirements. These firms anchor the market by providing a wide range of film types and packaging formats, from basic polyethylene to advanced barrier materials, while navigating evolving regulatory landscapes and sustainability pressures.
| Leading Market Players |
|---|
| Amcor plc |
| Berry Global Group |
| Sealed Air Corporation |
| Toray Industries |
| SABIC |
| DuPont |
| Uflex |
| Jindal Poly Films |
| Novolex |
| Others |
Cost & Logistics Intelligence
Paper-based alternatives replacing plastic films simultaneously reshapes the supply geography towards pulp-producing regions and alters pricing economics for packaging solutions. Converters must balance cost-effectiveness with regulatory mandates for sustainable materials, influencing both their sourcing strategies and final product pricing.
Pricing Analysis
Cost-plus contract patterns with named feedstock indexation dominate pricing for plastic films, reflecting raw material volatility. Price differentiation stems from quality grade, such as BRCGS certification status, and the volume scale of procurement. Pricing softness stems from intense competition among converters and the fluctuating prices of petrochemical feedstocks like naphtha. The Food & Beverage sector typically exhibits the highest price sensitivity, while the Pharmaceutical industry prioritizes performance and compliance over cost.
Supply Chain Analysis
The global energy market underwrites the supply chain for plastic films, as petrochemical feedstocks remain primary inputs. Geographic supply concentrates in major chemical production hubs like the US, China, and Germany. The industry draws heavily from raw materials such as polyethylene and polypropylene resins. Commodity price volatility presents a significant structural risk, impacting production costs and margins. Distribution runs through a dual model of direct sales to large-volume converters and a network of specialized distributors serving smaller clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires significant investment in circular economy infrastructure, representing a critical asset gap for flexible film recycling. This capability scarcity limits the industry's ability to meet escalating sustainability mandates and process post-consumer waste effectively.
For Market Incumbents: Shield existing market share by investing heavily in advanced recycling technologies for flexible films, particularly in regions like the US and Europe. Secure long-term contracts for sustainable feedstocks and bio-based polymers to mitigate supply chain risks. Prioritize BRCGS certification and other quality management system investments to reinforce market access and differentiate offerings against emerging threats from paper-based alternatives.
For New Entrants and Emerging Players: Anchor in specialized niches that leverage novel material science or address specific sustainability gaps. The biodegradable agricultural films segment in regions with high labor costs, such as North America, presents a penetrable application. Focus on developing cost-effective, compliant materials for circular economy models, utilizing innovative go-to-market strategies like direct engagement with agricultural cooperatives or specialized packaging brands.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-sized, specialized film converters that possess unique material science expertise or advanced recycling IP. The long-term viability of this market hinges on the successful transition to a circular economy model for packaging. Target companies with strong R&D pipelines in mono-materials or advanced barrier solutions. The signal to watch is the scaling of efficient, economically viable flexible film recycling infrastructure in key markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Advanced Recycling Infrastructure | Supports circular economy goals and reduces reliance on virgin petrochemical feedstocks for film production. |
| Develop Mono-Material Film Solutions | Addresses EU Green Deal mandates and simplifies post-consumer recycling processes for packaging. |
| Expand Biodegradable Agricultural Film Production | Captures growth in sustainable farming practices and reduces plastic waste in agriculture. |
| Integrate Smart Packaging Technologies | Enhances supply chain traceability and anti-counterfeiting measures for pharmaceutical products. |
| Obtain BRCGS for Packaging Materials Certification | Secures market access and strengthens competitive positioning with multinational food clients. |
Research Approach
A standing panel of film converters, brand owners, packaging engineers, and regulatory compliance officers provided ongoing calibration and validation for market insights. This primary research was complemented by extensive secondary data from sources including FDA filings, EFSA reports, industry association publications, and company financial reports. The analysis employed both bottom-up and top-down triangulation to ensure data accuracy and comprehensive market coverage.
Consistency checks against external benchmarks validated the analytical framework used to project market dynamics across the analysis window. Segmentation dimensions modeled included product type, application, end-user industry, packaging type, and regional regulatory cluster. Compound annual growth rates were derived from historical trends and future projections, with key forecast inputs including petrochemical feedstock prices and evolving regulatory mandates for sustainable materials.
Decision-makers should treat outputs as directional under assumptions of a stable regulatory environment and consistent technological development; material deviation would warrant model refresh. Forecasts reflect these base assumptions, but geopolitical instability or unforeseen material science breakthroughs represent specific risk factors. Practitioners should keep alternative scenarios live as market conditions and technological advancements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Germany Plastic Packaging Market
Plastic Packaging
E-Commerce Plastic Packaging Market
Plastic Packaging
PE Blow Molded Products Market
Plastic Packaging
Europe Personal Care Plastic Tube Packaging Market
Plastic Packaging
Latin America Plastic Bottles Market
Plastic Packaging
Banding Stretch Film Market
Plastic Packaging
United Kingdom Plastic Bottles Market
Plastic Packaging
Plastic T-Shirt Bags Market
Plastic Packaging
Plastic Liners Market
Plastic Packaging
Reusable Plastic Water Bottles Market
Plastic Packaging
Brazil Plastic Packaging Market
Plastic Packaging
South Africa Flexible Packaging Market
Plastic Packaging
Polyethylene Corrugated Packaging Market
Plastic Packaging
Canada Plastic Packaging Market
Plastic Packaging
China Plastic Bottles Market
Plastic Packaging
Plastic Ampoules Market