
 SSD Controller Market | 2026-2036
SSD Controller Market Size, Share, and Industry Trends Forecast 2026-2036
SSD Controller Market Intelligence
The sourcing model favoring in-house controller development by integrated storage device manufacturers is hardening. This trend solidifies the market position of vertically integrated firms like Samsung Electronics Co., Ltd., which controls its entire SSD technology stack. In contrast, Phison Electronics Corporation specializes in providing turnkey controller solutions to a broad customer base. Marvell Technology Inc. differentiates by focusing on high-performance controllers for the enterprise and data center segments.
An SSD controller is a dedicated processor that orchestrates data storage and retrieval on a solid-state drive. It executes critical firmware functions, including wear-leveling algorithms and advanced error correction code (ECC), to manage the NAND flash memory and interface with the host system. NVMe controllers are rapidly displacing older SATA interfaces, capturing the majority of new design wins. While data centers remain the primary application, demand from edge computing and gaming systems represents the fastest-growing segment.
Product design is influenced by security specifications such as the TCG Opal Storage Specification, which mandates hardware-based encryption. Environmental compliance, governed by regulations like the EU's RoHS directive and China's GB standards, dictates material composition and disposal protocols for electronic components. Vendor success will hinge on navigating the complex trade-offs between developing proprietary controller IP and leveraging third-party solutions to accelerate time-to-market.

Market Dynamics
The central dynamic shaping the SSD controller market is the technological transition towards higher-bandwidth interfaces and denser flash memory. The industry-wide migration to PCIe 5.0 and the increasing use of QLC NAND require sophisticated controller architectures with advanced signal processing and error correction capabilities.
Growth Catalysts
- Enterprise Data Center Expansion:The build-out of hyperscale data centers to support AI and cloud computing workloads creates sustained demand for high-performance NVMe controllers capable of delivering low latency and high throughput.
- PCIe Interface Adoption:The transition from PCIe 4.0 to PCIe 5.0 and the forthcoming PCIe 6.0 standard in client and enterprise systems necessitates new controller designs, driving a significant technology refresh cycle across the market.
- Advanced Semiconductor Ecosystems:Geographic concentration of demand in manufacturing hubs like South Korea provides a powerful catalyst, as local storage device manufacturers require a steady supply of cutting-edge controllers for their SSD production lines.
Market Restraints
- Intensive R&D Investment:Developing next-generation controller SoCs for new NAND types and PCIe standards requires substantial, high-risk R&D expenditure, creating a significant barrier to entry for firms without deep capital resources.
- NAND Flash Market Volatility:The SSD controller market is indirectly constrained by the cyclicality and price fluctuations of the NAND flash memory market, which can impact SSD end-market demand and investment cycles.
- Firmware Complexity and Validation:The increasing complexity of firmware, which manages functions like wear-leveling and garbage collection, leads to longer development and validation cycles, slowing time-to-market for new controller products.
Strategic Opportunities
- Automotive and Industrial IoT:The integration of SSDs into automotive infotainment systems, autonomous driving platforms, and industrial equipment opens a new market for controllers designed for ruggedness, reliability, and extended temperature ranges.
- Computational Storage:Integrating processing capabilities directly onto the SSD controller allows for in-situ data processing, creating a significant opportunity to serve applications in edge computing and real-time analytics by reducing data movement.
- Data Security Mandates:Growing enforcement of data protection regulations like GDPR is fueling demand for controllers with built-in, hardware-based encryption compliant with standards such as TCG Opal, creating a value-added opportunity.
Industry Challenges
- Firmware Engineering Talent Scarcity:A persistent shortage of experienced firmware engineers and verification specialists capable of developing and debugging complex controller code represents a critical operational bottleneck for vendors.
- Interoperability Across Ecosystems:Ensuring seamless compatibility of a single controller design across a wide array of NAND flash from different suppliers and diverse host system platforms remains a significant and resource-intensive engineering challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | SSD Controller Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PCIe Controllers, SATA Controllers, NVMe Controllers, SAS Controllers, Embedded Controllers Technology: 3D NAND, SLC, MLC, TLC, QLC Application: Enterprise Servers, Data Centers, Gaming Systems, Consumer Electronics, Edge Computing End User: Original Equipment Manufacturers, Cloud Service Providers, Hyperscale Companies, Data Storage Vendors, System Integrators |
| Companies Covered | Samsung Electronics Co., Ltd., Western Digital Corporation, Marvell Technology Inc., Intel Corporation, SK hynix Inc., Kioxia Holdings Corporation, Phison Electronics Corporation, Silicon Motion Technology Corporation, Micron Technology Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
SSD Controller Market Strategic Shifts & Innovations
The evolution of the SSD controller is defined by its transformation from a simple data traffic manager into an intelligent processing unit. This shift is driven by the need to manage increasingly complex NAND physics and to offload tasks from the host CPU for greater system efficiency.
Computational storage represents a major product evolution, embedding processing cores directly within the controller's silicon. Hyperscale data centers and scientific research institutions are the primary adopters, seeking to minimize data movement for analytics and AI workloads. The intelligent controller is absorbing processing functions, such as database queries and compression, that were traditionally executed by the host system's main processor.
Security standards are profoundly influencing controller architecture, particularly the TCG Opal Storage Specification. This framework effectively mandates hardware-level data encryption, shifting security from an optional software layer to a fundamental, always-on feature of the device. Enterprise and government procurement for laptops and servers is most affected, compelling controller vendors to integrate certified AES encryption engines into their core designs.
Demand patterns are pivoting toward workload-specific controller optimization, especially in the enterprise segment. Buyers are moving away from procuring general-purpose controllers, instead specifying designs tailored for either read-intensive or write-intensive applications to maximize performance and endurance. This trend is most visible within hyperscale cloud providers, who co-develop custom firmware to tune storage behavior for their unique software stacks.
SSD Controller Market Segmentation
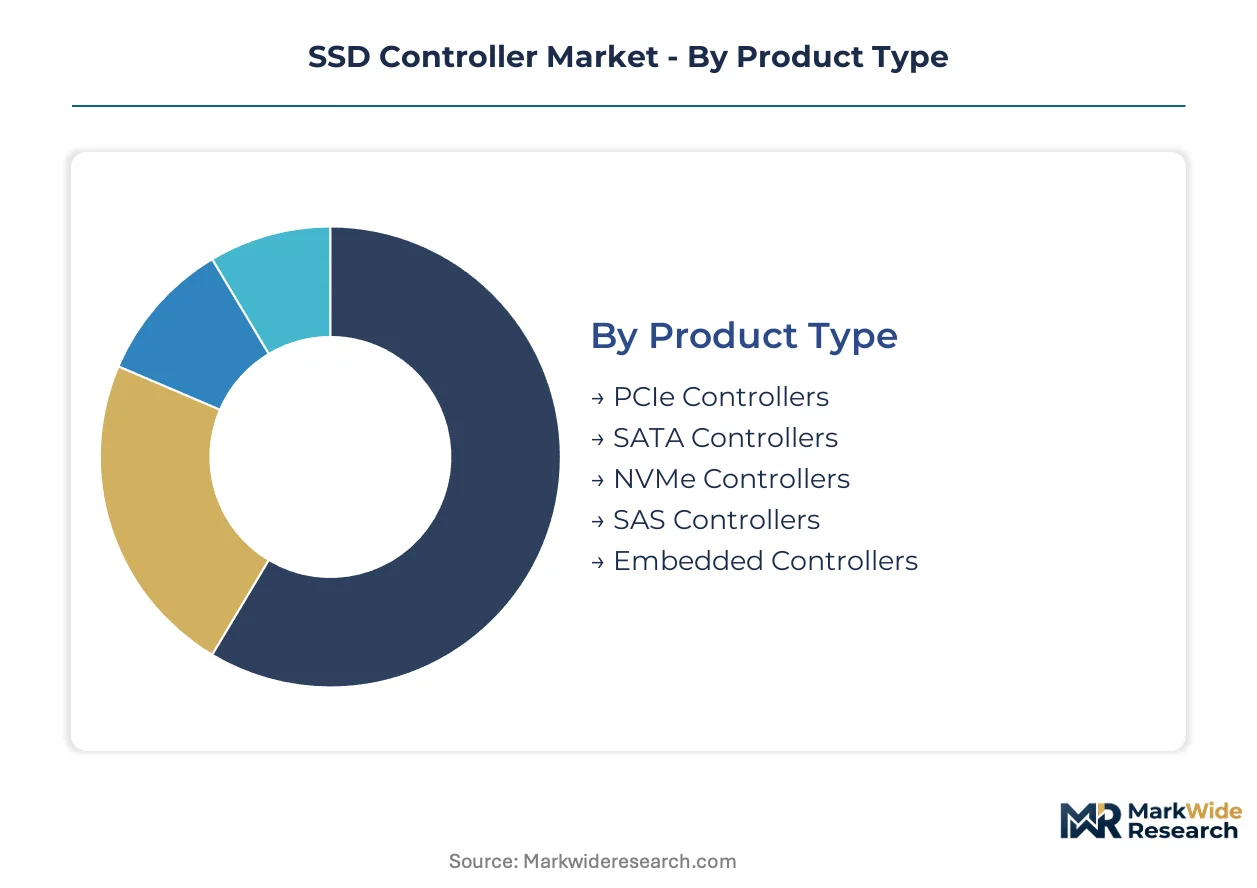
The SSD controller market segmentation reveals distinct pathways for technological advancement and commercialization. Understanding these segments helps identify specific demand drivers and competitive landscapes. This analysis outlines key categories shaping product development and market penetration strategies.
Product Type:
The market for SSD controllers distinguishes between high-performance, premium interfaces and more cost-effective, volume-oriented solutions.
- NVMe Controllers:These controllers utilize the Non-Volatile Memory Express protocol, offering significantly reduced latency and increased throughput compared to older interfaces. Demand concentrates in enterprise data centers and high-end gaming systems, driven by requirements for faster data access and parallel processing capabilities.
- PCIe Controllers:These controllers leverage the Peripheral Component Interconnect Express bus for high-speed data transfer, with PCIe 5.0 and 6.0 standards driving next-generation designs. Enterprise server upgrades and new client computing platforms are adopting PCIe controllers to maximize system performance.
- SATA Controllers:Serial Advanced Technology Attachment controllers offer a mature and cost-effective solution for mainstream consumer SSDs and legacy systems.
- SAS Controllers:Serial Attached SCSI controllers serve specialized enterprise storage arrays requiring high reliability and dual-port redundancy.
- Embedded Controllers:These controllers integrate directly into system-on-chip designs for compact and power-efficient applications in IoT and industrial devices.
Today's leader: NVMe Controllers. Tomorrow's challenger: Embedded Controllers.
Technology:
Technology segmentation highlights the impact of NAND flash advancements on controller design and functionality.
- QLC:Quad-Level Cell NAND stores four bits per cell, offering the highest density and lowest cost per gigabyte among current technologies. Hyperscale data centers and consumer storage are adopting QLC to achieve massive storage capacities.
- 3D NAND:This technology stacks memory cells vertically, increasing density and improving endurance and performance over planar NAND. Enterprise SSDs and high-capacity consumer drives widely utilize 3D NAND architectures.
- SLC:Single-Level Cell NAND stores one bit per cell, providing the highest endurance and fastest performance for mission-critical applications.
- MLC:Multi-Level Cell NAND stores two bits per cell, balancing cost and performance for enterprise and high-end consumer products.
- TLC:Triple-Level Cell NAND stores three bits per cell, offering a good balance of cost and capacity for mainstream consumer SSDs.
Innovations in QLC technology are driving cost-effective capacity, while 3D NAND remains foundational for performance and density scaling.
Application:
Application segments illuminate where high-performance and specialized controller features are most critical across diverse computing environments.
- Data Centers:These facilities require controllers optimized for high throughput, low latency, and continuous operation to manage vast amounts of enterprise and cloud data. Hyperscale cloud providers in South Korea and the US drive demand for custom-tuned solutions.
- Edge Computing:This segment demands rugged, power-efficient controllers capable of real-time processing and data analytics closer to the source. Industrial IoT deployments and autonomous vehicle platforms represent the fastest-growing segment.
- Enterprise Servers:These systems utilize controllers designed for reliability and data integrity in business-critical environments.
- Gaming Systems:High-performance gaming PCs and consoles demand controllers with low latency to enhance user experience.
- Consumer Electronics:This segment includes laptops, desktops, and portable devices, requiring cost-effective and energy-efficient controller solutions.
Demand shifts toward Edge Computing are influencing new controller designs, with Data Centers remaining foundational for market volume.
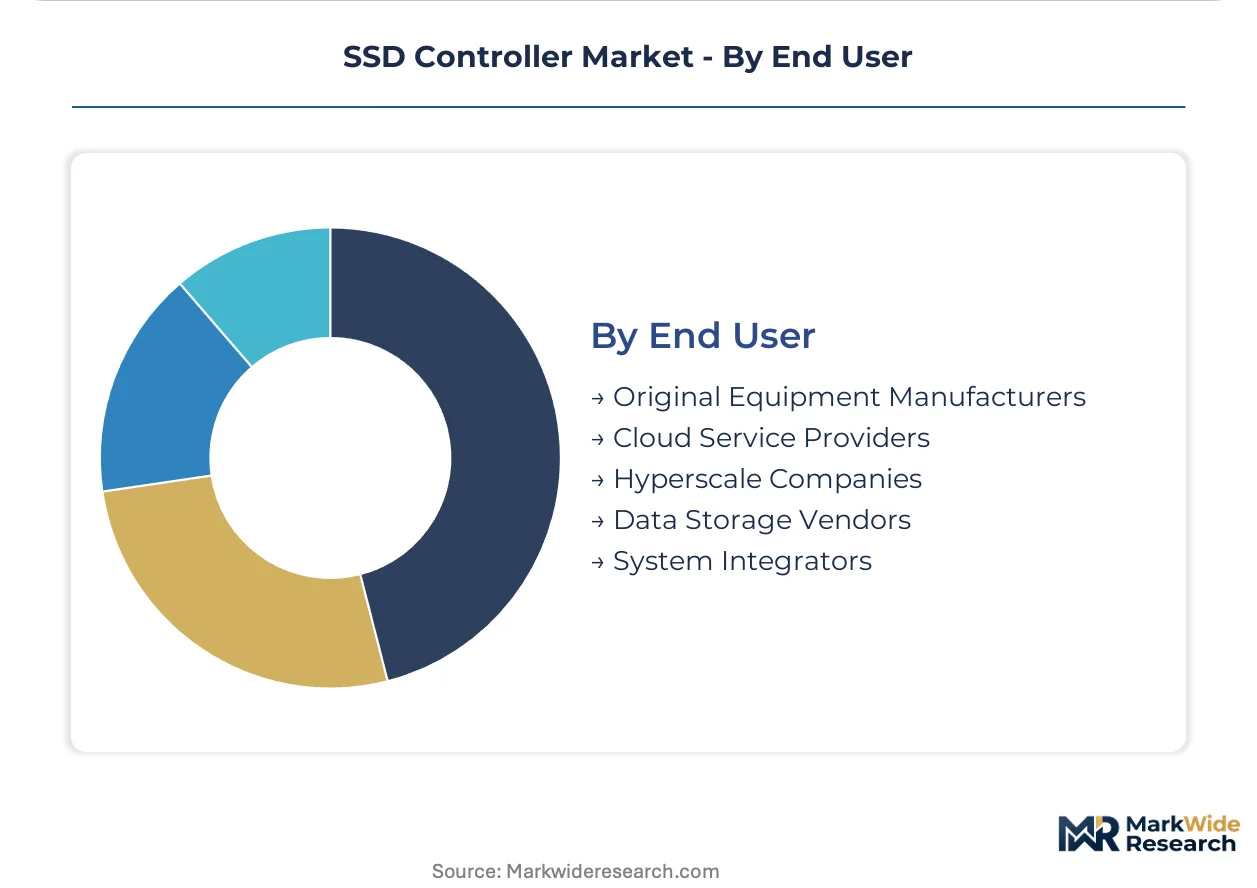
End User:
End-user types define procurement models and the strategic importance of proprietary versus third-party controller solutions.
- Cloud Service Providers:These entities, including hyperscale companies, often co-develop custom firmware for controllers to optimize performance within their unique software stacks. Major players like those in the US and China focus on captive supply for their data centers.
- Original Equipment Manufacturers:OEMs integrate SSDs into a wide range of products, driving demand for both standardized and custom controller solutions. Firms like Samsung Electronics Co., Ltd. exemplify the trend of in-house controller development.
- Hyperscale Companies:These large-scale data center operators require massive volumes of high-performance controllers for their cloud infrastructure.
- Data Storage Vendors:These companies develop and sell storage products, often procuring controllers from specialized providers like Phison Electronics Corporation.
- System Integrators:SIs assemble complete IT solutions for clients, selecting controllers based on performance, cost, and compatibility requirements.
Cloud Service Providers define market structure, while Data Storage Vendors present new growth avenues through diverse product offerings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's advanced semiconductor manufacturing ecosystem serves as a central hub for the SSD controller market. This region's technological prowess drives significant demand for cutting-edge controllers. This concentration supports local storage device production and fosters continuous technological innovation.
South Korea
Demand for advanced NVMe controllers stems from South Korea's leading position in NAND flash production and SSD manufacturing. The South Korean government actively supports its semiconductor industry through strategic investments and R&D incentives. Major technology parks in the Seoul Capital Area host key players in SSD and controller development.
United States
The United States drives demand for high-performance controllers through its vast hyperscale data centers and rapidly expanding cloud computing infrastructure. The US CHIPS Act provides significant funding to bolster domestic semiconductor manufacturing and R&D. Silicon Valley and Texas technology hubs remain critical centers for controller design and application.
China
Expanding data centers and a robust domestic electronics manufacturing sector fuel China's demand for SSD controllers. China's GB standards for electronic components influence material composition and product safety. The Yangtze River Delta and Pearl River Delta regions concentrate numerous electronics manufacturers and data center operators.
Japan
Japan's market for SSD controllers is characterized by demand from high-performance computing, industrial automation, and automotive electronics. METI initiatives encourage innovation in advanced electronics and digital transformation across industries. Technology clusters in Tokyo and Osaka are crucial for controller development and integration.
Germany
Germany's strong automotive industry and industrial IoT sector create specific demand for rugged and reliable SSD controllers. The EU's RoHS directive governs the material composition of electronic components, impacting controller design. Industrial technology clusters in Bavaria and Baden-Württemberg lead in automotive and industrial applications.
SSD Controller Market Key Industry Players
Global majors compete with regional champions across technological innovation and market reach. The SSD controller market exhibits a tiered structure, with vertically integrated firms alongside specialized component providers. This structure features integrated storage device manufacturers, independent controller solution providers, and high-performance enterprise specialists. Companies often pursue proprietary IP development while also forming strategic partnerships to accelerate time-to-market and expand their product portfolios.
Specialization in controller solutions defines several market participants. Samsung Electronics Co., Ltd. exemplifies the vertically integrated model, controlling its entire SSD technology stack from NAND production to final product. Phison Electronics Corporation represents a dedicated provider of turnkey controller solutions, serving a broad customer base with its expertise. Marvell Technology Inc. occupies a position as a high-performance controller specialist, primarily focusing on advanced solutions for the enterprise and data center segments. These firms collectively shape the competitive dynamics through their distinct business models and market focus.
| Leading Market Players |
|---|
| Samsung Electronics Co., Ltd. |
| Western Digital Corporation |
| Marvell Technology Inc. |
| Intel Corporation |
| SK hynix Inc. |
| Kioxia Holdings Corporation |
| Phison Electronics Corporation |
| Silicon Motion Technology Corporation |
| Micron Technology Inc. |
| Others |
Cost & Logistics Intelligence
Hyperscale companies' concentrated purchasing power drives contract-based pricing models for high-performance SSD controllers. This dynamic emphasizes long-term supply agreements and value-based negotiations, rather than purely transactional pricing.
Pricing Analysis
Input-cost pass-through mechanisms influence SSD controller pricing, particularly for specialized components and advanced semiconductor processes. Value-based pricing dominates the enterprise segment, differentiating based on performance tiers, firmware customization, and robust security certifications like TCG Opal. Pricing pressure stems from the increasing adoption of lower-cost QLC NAND, necessitating cost optimization in controller designs. Consumer electronics manufacturers exhibit the highest price sensitivity, while hyperscale data centers prioritize performance and reliability over marginal cost savings.
Supply Chain Analysis
Dual-sourcing requirements for critical components are standard practice among major SSD manufacturers to mitigate risk and ensure supply continuity. Geographic supply concentration centers on South Korea for advanced NAND flash production and Taiwan for specialized semiconductor fabrication. Raw material dependencies include silicon wafers, rare earth elements for manufacturing, and specialized packaging materials. Single-source vulnerability for advanced process technology represents a structural risk. Distribution runs primarily through direct sales channels to large OEMs and cloud service providers, with specialized distributors serving smaller integrators.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder, driven by the sustained expansion of enterprise data centers and the continuous demand for faster storage solutions.
For Market Incumbents: Lock in long-term supply agreements with key NAND flash manufacturers to stabilize input costs and ensure material availability. Invest heavily in PCIe 6.0 controller R&D to maintain a technological lead against emerging competitors. Deepen vertical integration through in-house production of critical firmware components to safeguard proprietary IP against rising firmware complexity. Focus on acquiring specialized talent in advanced signal processing to counter talent scarcity.
For New Entrants and Emerging Players: Specialized industrial distributors represent a viable channel to penetrate the ruggedized embedded controller segment. Target niche applications in automotive infotainment systems and industrial IoT devices, which demand specific reliability and extended temperature ranges. Develop controllers compliant with specific regional security mandates, such as China's GB standards, to gain a competitive edge. Emphasize value propositions centered on enhanced data security features.
For Investors and Strategic Acquirers: Vertically integrated storage device manufacturers are the most active acquirers in this space, seeking to consolidate technology and talent. Long-term viability remains strong over the next five to ten years, supported by persistent data growth. Acquisition targets should include firms with proprietary computational storage IP or advanced firmware development capabilities. Watch the adoption rate of PCIe 6.0 in enterprise systems as a key inflection indicator for next-generation controller demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Accelerate PCIe 6.0 Controller Development | Ensures market leadership in high-performance computing and enterprise data centers. |
| Invest in Computational Storage IP | Captures value from edge computing and real-time analytics by reducing data movement. |
| Expand Embedded Controller Portfolio | Addresses growing demand from automotive and industrial IoT segments with tailored solutions. |
| Strengthen Firmware Engineering Teams | Mitigates operational bottlenecks arising from increasing firmware complexity and validation. |
| Pursue TCG Opal Certification | Meets stringent hardware-based encryption requirements for government and enterprise procurement. |
Research Approach
Direct dialogue with SSD manufacturers, data center architects, NAND flash suppliers, and firmware engineers forms the qualitative grounding for this analysis. Primary interviews are combined with secondary validation from company annual reports, semiconductor industry association publications, technology news archives, and regulatory filings. This approach ensures a comprehensive understanding, triangulating insights from both top-down market perspectives and bottom-up technological developments.
Market sizing and forecast outputs are generated through a robust quantitative model, projecting market trends across the analysis window. Segmentation dimensions include product type (NVMe, SATA), technology (QLC, 3D NAND), application (data centers, edge computing), end user (cloud service providers, OEMs), and regional demand. Compound annual growth rates are derived through regression analysis, incorporating market share shifts and competitive dynamics. Industry-specific forecast inputs include NAND flash pricing trends and the PCIe interface roadmap.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to geopolitical trade policies and rapid shifts in NAND technology. Forecasts reflect assumptions regarding technological adoption curves and R&D investment levels. Deviation in global semiconductor supply chain stability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
Data Storage Devices Market
Data Storage
Enterprise-Class Hybrid Storage Market
Data Storage
Next Generation Data Storage Market
Data Storage
Serial (SPI) NOR Flash Market
Data Storage
Global Portable Data Storage Market
Data Storage
Next-Generation Storage Market
Data Storage
USB Key Market
Data Storage
Recordable Optical Disc Market
Data Storage
Electrochromic Storage Devices Market
Data Storage
External Storage Market
Data Storage
Hybrid Flash Storage Market
Data Storage
Object-Based Storage Market
Data Storage
Blu-Ray Optical Disk Market
Data Storage
Europe Flash Memory Market
Data Storage
Portable Storage Device Control Software Market
Data Storage
Solid State Drive (SSD) Market