
 Global Portable Data Storage Market | 2026-2036
Global Portable Data Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Global Portable Data Storage Market Foresight
Aftermarket firmware and encryption service revenue is fragmenting across hardware vendors as buyers seek security subscriptions rather than one-time purchases. Samsung Electronics Co Ltd leverages its vertically integrated NAND fabrication to control cost curves across portable SSD lines. Kingston Technology Corporation anchors its position in USB flash drives through direct channel relationships with enterprise IT procurement teams. Western Digital Corporation competes by sustaining broad portfolio coverage from entry-level memory cards to professional-grade external storage arrays.
Portable data storage encompasses self-contained, bus-powered devices that retain digital information through flash memory cells, magnetic platters, or solid-state architectures, typically connecting via USB-C, Thunderbolt, or wireless protocols to host systems. These devices serve primary functions including offline backup, cross-platform file transfer, and working media for video production workflows where cloud latency proves unacceptable. Solid state drives now command the fastest expansion trajectory within the technology dimension as falling per-gigabyte costs displace mechanical hard disks in mobile professional use cases. External hard drives retain residual dominance in cost-per-terabyte archiving scenarios among creative professionals managing uncompressed video libraries. Memory cards sustain entrenched demand from camera manufacturers and drone operators requiring removable, standardized form factors.
The FCC in the United States imposes electromagnetic emissions standards that constrain enclosure design and shielding costs for devices sold into North American channels. Ecodesign requirements under the EU framework push manufacturers toward recyclable aluminum housings and standardized battery compartments where applicable. China's SAMR enforces national encryption standards that foreign vendors must integrate for commercial market access. Stakeholders must monitor how divergent data sovereignty mandates across these jurisdictions reshape regional product configurations and certification budgets.
Market Dynamics
Enterprise edge computing migration is compressing procurement cycles for ruggedized storage while EU circular economy mandates force enclosure redesigns, creating simultaneous pull and push pressures on manufacturer R&D budgets.
Growth Catalysts
- Edge Computing Architectures:Field operations teams in energy and logistics sectors require dust-resistant, shock-proof external SSDs for data collection at remote sites. This hardware refresh cycle sustains replacement demand independent of consumer trends.
- Ecodesign for Sustainable Products Regulation:The EU framework mandates modular, repairable designs with standardized screws and accessible battery compartments. Manufacturers complying early capture preferential placement in public sector tenders.
- China's Cloud-Adjacent Backup Habits:Domestic consumers maintain local copies of streaming and gaming libraries despite cloud availability. This behavioral pattern insulates the country's portable drive demand from pure subscription-model displacement.
Market Restraints
- NAND Flash Supply Concentration:Fabrication capacity clusters in Taiwan and South Korea, exposing procurement costs to geopolitical transit risks and water-intensive production constraints during drought periods.
- Mechanical Hard Disk Residual Lock-In:Creative professionals managing uncompressed 8K video libraries face 4-6x cost penalties for solid-state archiving at multi-terabyte scales, slowing full category transition.
- SAMR Encryption Mandates:China's national cryptographic standards require foreign vendors to integrate SM4 algorithms and undergo domestic certification, extending product launch timelines by 8-14 months.
Strategic Opportunities
- India's PLI Scheme for Electronics:Manufacturing-linked incentives for semiconductor assembly and testing attract portable storage brands seeking tariff-advantaged export hubs serving Middle East and African markets.
- Wireless Protocol Convergence:Wi-Fi 6E and emerging UWB chipsets enable cable-free high-speed transfers between mobile devices and external storage, opening automotive infotainment and drone field-download applications.
- Subscription Security Services:Enterprise buyers prefer firmware-encryption-as-a-service with remote wipe capabilities over perpetual licenses, creating recurring revenue streams detached from hardware refresh cycles.
Industry Challenges
- FCC Pre-Certification Bottlenecks:Electromagnetic emissions testing for USB-C and Thunderbolt enclosures requires 12-16 week lab queues, compressing seasonal product launch windows and inventory planning horizons.
- Legacy Interface Support Burden:Professional video workflows demand backward compatibility with USB 3.0 and Thunderbolt 2 hosts, forcing multi-controller architectures that increase BOM complexity and thermal design constraints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Portable Data Storage Market |
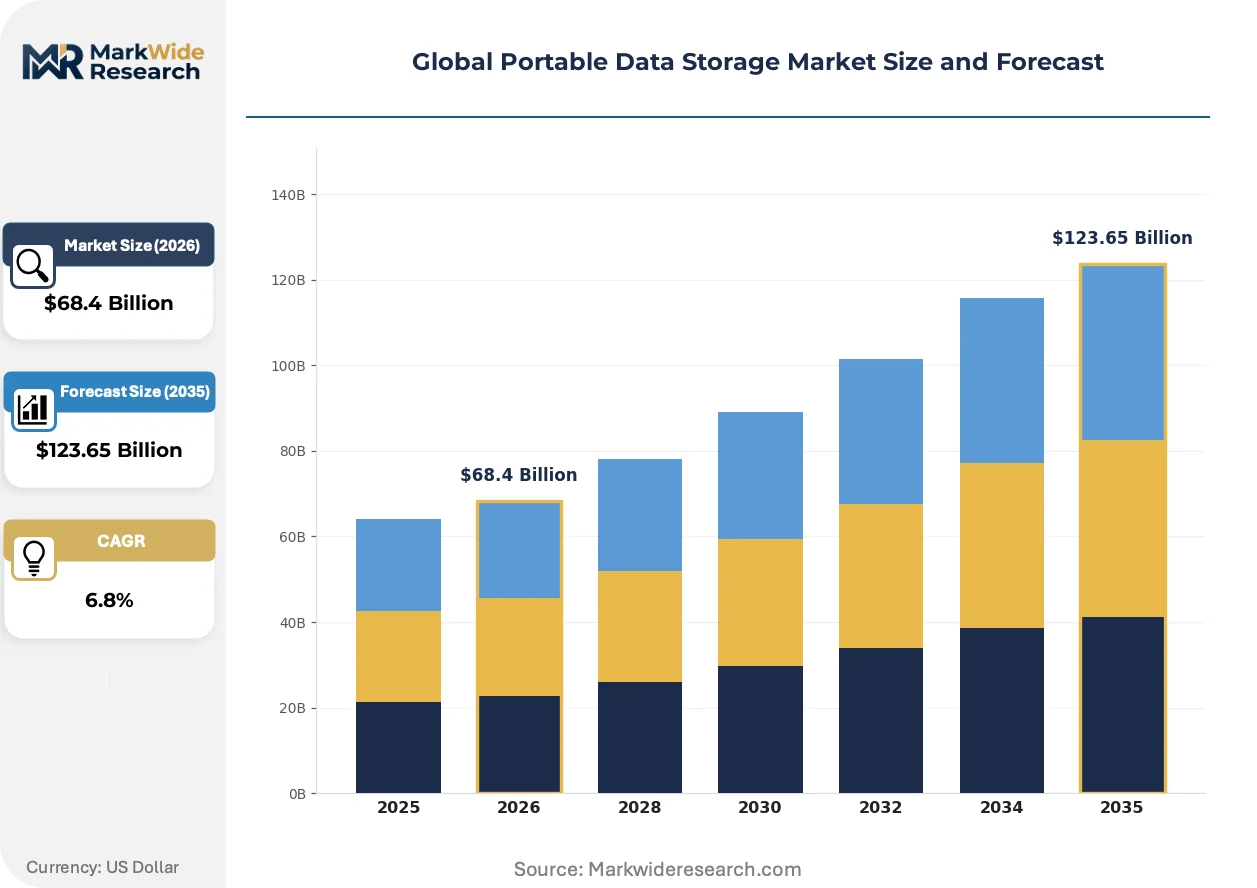
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: USB Flash Drive, External Hard Drive, Solid State Drive, Memory Card Technology: Flash Memory, HDD, SSD, Hybrid Storage End User: Consumers, IT Professionals, Enterprises, Creative Professionals Capacity: 64GB, 128GB, 1TB, 2TB |
| Companies Covered | Western Digital Corporation, Samsung Electronics Co Ltd, Seagate Technology PLC, Kingston Technology Corporation, Transcend Information, Inc., Toshiba Corporation, Sony Corporation, ADATA Technology, PNY Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Portable Data Storage Market Shifts & Advancements
QLC NAND die stacking is collapsing cost-per-gigabyte floors while regulatory jurisdictions impose divergent sustainability and encryption mandates, forcing SKU proliferation. Buyer preferences simultaneously fragment across subscription security models and hardware ownership.
QLC NAND with 176-layer vertical stacking is collapsing the cost differential between solid-state and mechanical storage for mobile professional workloads. Freelance video editors and independent production houses now specify external SSDs for active project folders previously relegated to hard disks. This transition compresses the residual market for 2.5-inch external hard drives to pure archival applications.
REACH substance restrictions and RoHS amendments are eliminating specific brominated flame retardants from PCB assemblies and enclosure plastics. German and French environmental agencies now prioritize repairability scoring in public procurement evaluations. Vendors are responding with aluminum unibody designs that permit user-accessible thermal pads and modular port boards.
Enterprise IT departments now unbundle hardware procurement from encryption key management, contracting separate security vendors for centralized policy enforcement. Value-added distributors in the United States and Germany are building managed service wrappers around commodity external SSDs. This disintermediation of manufacturer control compresses brand loyalty and shifts margin capture toward channel partners.
Global Portable Data Storage Market Segmentation
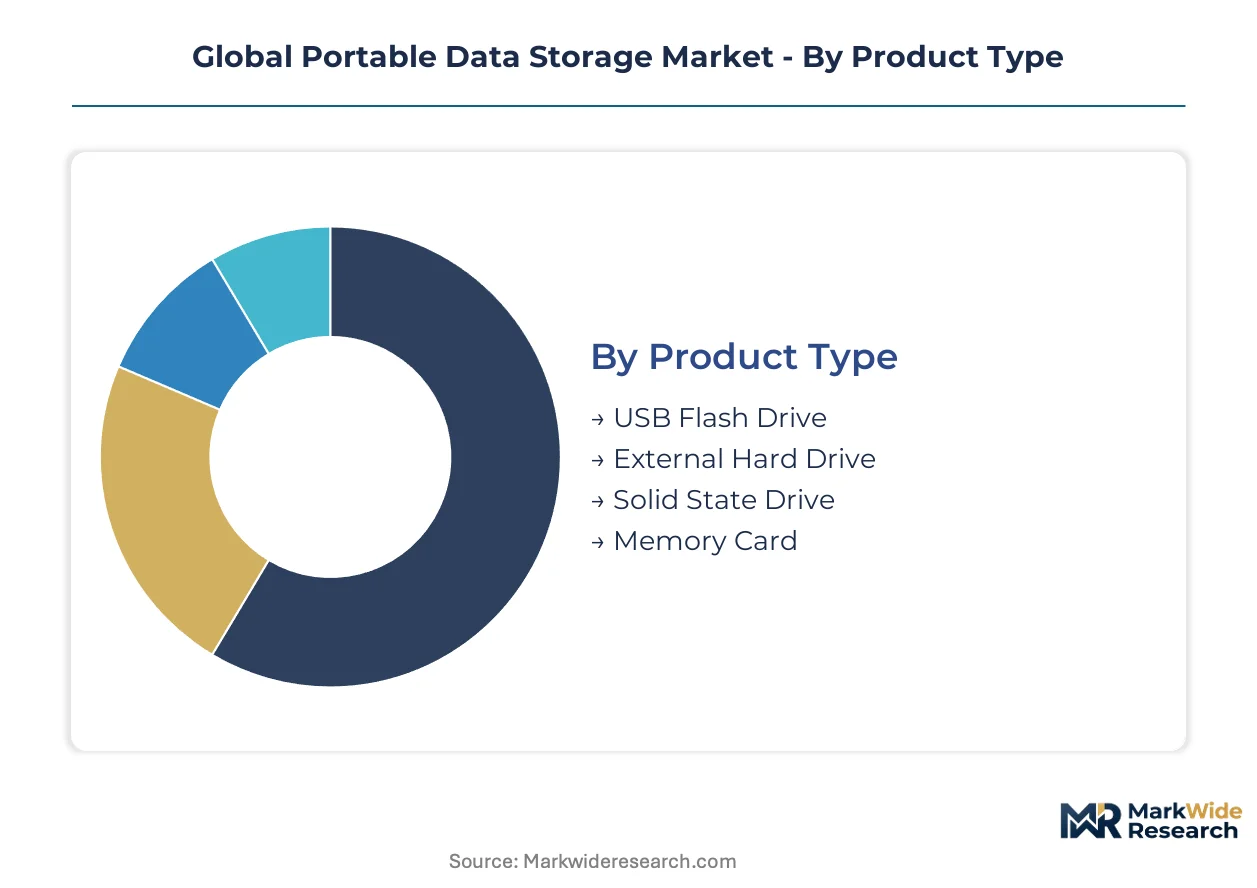
Portable data storage segmentation reveals divergent hardware requirements across professional workflows and consumer backup habits. Technology maturity varies sharply between established magnetic storage and emerging solid-state architectures.
Product Type:
Mature form factors dominate unit shipments while emerging designs reshape revenue composition across field operations and creative workflows.
- Solid State Drive:Bus-powered enclosures utilizing NAND flash arrays deliver shock resistance and sustained transfer rates for 4K video editing workflows. Procurement from energy sector field teams is accelerating as edge computing deployments expand.
- External Hard Drive:Rotating magnetic platters in 2.5-inch and 3.5-inch form factors retain cost-per-terabyte advantages for uncompressed media archiving. Creative professionals managing 8K video libraries in Los Angeles and Mumbai continue specifying these for cold storage tiers.
- USB Flash Drive:Thumb-sized NAND devices serve cross-platform file transfer and bootable recovery media functions.
- Memory Card:Standardized SD and microSD formats sustain entrenched demand from camera manufacturers and drone operators requiring removable storage.
External hard drives retain volume leadership; solid state drives hold the steepest expansion curve.
Technology:
Cost tier stratification separates premium solid-state architectures from economy magnetic alternatives across professional and consumer purchase decisions.
- SSD:Controller-managed NAND arrays with wear-leveling algorithms support sustained write endurance for professional video capture. Enterprise IT procurement in Germany and Japan is prioritizing these for mobile workstation deployments.
- Flash Memory:Raw NAND dies without sophisticated controllers populate entry-level USB drives and memory cards. Chinese manufacturing clusters supply the majority of controller chips and flash wafers for this tier.
- HDD:Magnetic recording technology with actuator arm assemblies persists in high-capacity external enclosures.
- Hybrid Storage:NAND cache layers atop magnetic platters attempt to bridge latency gaps.
Flash memory dominates unit economics; SSD commands the premium tier expansion trajectory.
End User:
Application intensity varies from casual file backup to mission-critical field data collection across user categories.
- Creative Professionals:Video editors and colorists require sustained throughput for raw footage playback. Post-production houses in London and Seoul specify Thunderbolt-connected external SSDs for DIT carts and on-set ingest stations.
- Enterprises:IT departments procure ruggedized storage for compliance-mandated offline backups. Logistics and energy sector field teams in Texas and Alberta require IP-rated enclosures for remote site data collection.
- Consumers:Individual buyers maintain local copies of streaming libraries and personal media archives.
- IT Professionals:Systems administrators deploy portable storage for imaging, recovery, and diagnostic workflows.
Consumers retain volume leadership; creative professionals hold the steepest expansion curve.
Capacity:
Volume scale separates entry-level personal backup from professional-grade media workflows across capacity tiers.
- 2TB:Multi-terabyte enclosures accommodate uncompressed video project archives and system image backups. Independent production companies in Toronto and Sydney specify these for active project folders requiring random access performance.
- 1TB:Mid-range capacity points balance portability with sufficient headroom for photography portfolios and software development environments. Remote workers in Spain and Italy are standardizing on this tier for primary backup duties.
- 128GB:Compact capacity serves document archives and bootable utility drives.
- 64GB:Entry-level tier supports basic file transfer and promotional distribution use cases.
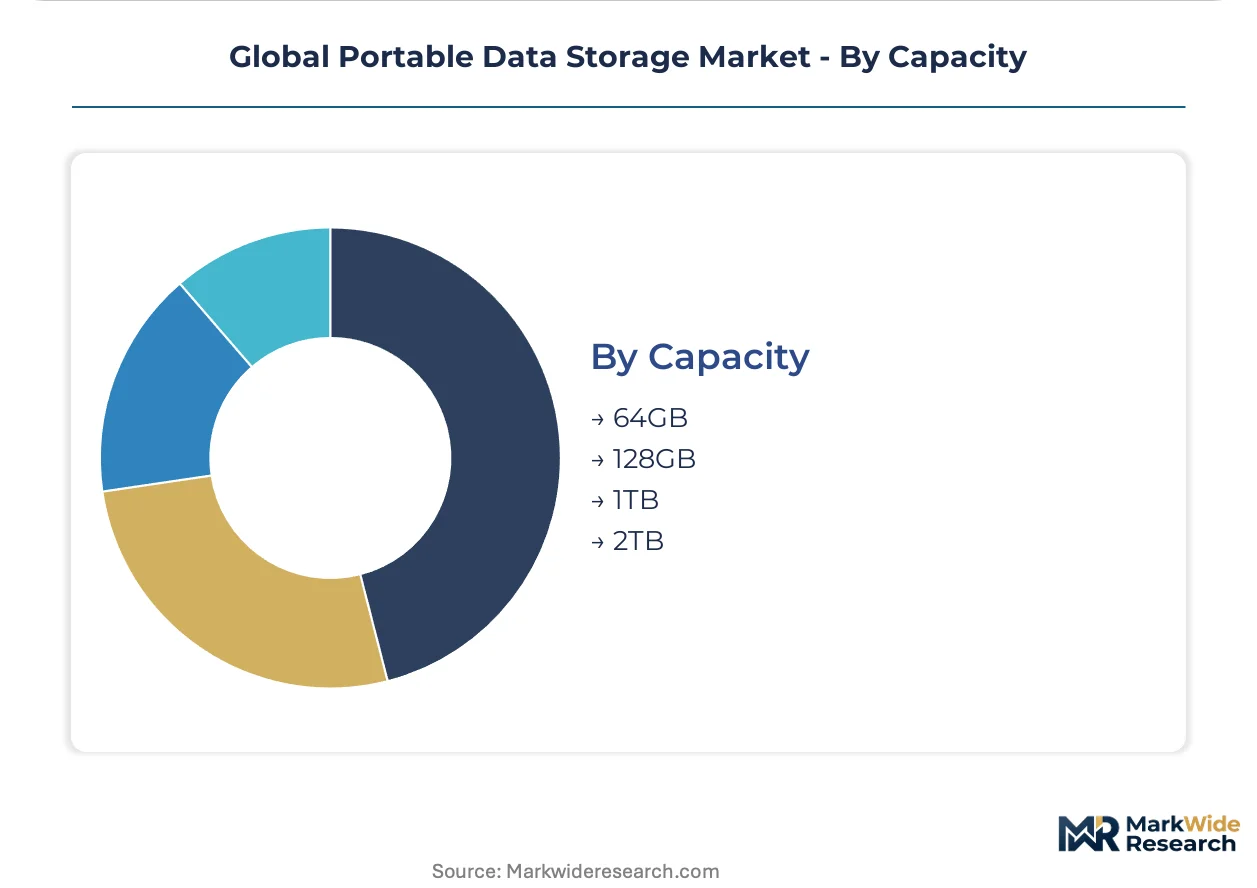
1TB retains volume leadership; 2TB holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. Chinese consumers exhibit low price sensitivity for high-capacity backup drives. German enterprise buyers prioritize durability certifications over per-gigabyte cost. Indian procurement teams optimize for landed cost in tariff-adjusted sourcing decisions.
United States
Energy sector field operations in Texas and North Dakota drive ruggedized SSD procurement for remote data collection. FCC electromagnetic emissions standards constrain enclosure design and shielding costs for North American channels. Post-production houses in Los Angeles specify Thunderbolt-connected external SSDs for on-set digital imaging technician carts.
China
Domestic cloud-adjacent backup habits sustain strong consumer uptake of high-capacity portable drives despite streaming availability. SAMR enforces national SM4 encryption standards that extend foreign vendor product launch timelines by 8-14 months. Manufacturing clusters in Shenzhen and Dongguan supply controller chips and flash wafer assemblies for entry-level storage tiers.
Germany
Enterprise IT procurement prioritizes modular, repairable designs for mobile workstation deployments. Ecodesign for Sustainable Products Regulation mandates standardized screws and accessible battery compartments for public sector tender eligibility. Environmental agencies in Berlin and Munich prioritize repairability scoring in procurement evaluations.
India
Remote workers in Bangalore and Hyderabad standardize on 1TB capacity points for primary backup duties. PLI scheme manufacturing-linked incentives attract portable storage brands seeking tariff-advantaged export hubs. Assembly and testing operations in Tamil Nadu serve Middle East and African distribution channels.
Japan
Creative professionals in Tokyo and Osaka require sustained throughput for raw footage playback in post-production workflows. METI standards influence industrial design priorities for professional-grade external storage. Enterprise procurement in Nagoya and Fukuoka emphasizes shock resistance and thermal performance specifications.
Global Portable Data Storage Market Competitive Landscape
Vertically integrated NAND fabricators and specialist assembly houses split the market into distinct capability tiers. Concentration is moderate, with three to four players controlling advanced controller silicon while dozens compete in enclosure assembly and distribution. Strategic archetypes span captive wafer producers, brand-anchored system integrators, and contract-manufacturing distributors. Dominant competitive moves include backward integration into NAND fabrication and geographic diversification of final assembly to capture trade-advantaged routing.
Within the captive-supply tier, Samsung Electronics Co Ltd exemplifies wafer-to-enclosure cost curve control. Kingston Technology Corporation and Western Digital Corporation anchor distinct positioning vectors—Kingston through direct channel relationships with enterprise IT procurement teams, Western Digital through portfolio breadth spanning entry-level memory cards to professional-grade external storage arrays. These three entities represent the primary competitive anchors around which mid-tier specialists and regional assemblers orbit.
| Leading Market Players |
|---|
| Western Digital Corporation |
| Samsung Electronics Co Ltd |
| Seagate Technology PLC |
| Kingston Technology Corporation |
| Transcend Information, Inc. |
| Toshiba Corporation |
| Sony Corporation |
| ADATA Technology |
| PNY Technologies |
| Others |
Supply & Pricing Matrix
Shenzhen's controller chip and flash wafer assembly clusters determine downstream pricing power across entry-level storage tiers. NAND fabrication capacity concentration in Taiwan and South Korea feeds cost volatility through the value chain, while tariff-advantaged assembly hubs in Tamil Nadu reshape regional pricing differentials.
Pricing Analysis
Aftermarket firmware subscriptions and encryption-as-a-service now drive lifetime value beyond hardware margins. Three-tier pricing structure across premium, standard, and economy levels separates Thunderbolt-connected professional enclosures from USB-C consumer tiers and entry-level flash sticks. Pricing pressure stems from QLC NAND die stacking collapsing cost-per-gigabyte floors. Enterprise IT buyers show lowest price sensitivity due to compliance mandates; independent production houses face acute cost compression.
Supply Chain Analysis
Export-control regimes on advanced lithography equipment constrain capacity expansion for 176-layer NAND architectures. Taiwan, South Korea, and China dominate wafer fabrication; Malaysia, Vietnam, and India host final assembly and testing. Raw material dependencies include silicon wafers, rare gases for etching, and aluminum for thermal enclosures. Single-source vulnerability concentrates in advanced controller silicon. Distribution runs through value-added distributors building managed service wrappers around commodity hardware.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Edge computing migration and EU circular economy mandates are reshaping procurement specifications faster than incumbent product cycles can adapt. QLC NAND cost trajectories and wireless protocol convergence create dual technology inflections.
For Market Incumbents: Insulate controller silicon supply through captive wafer allocations or long-term foundry partnerships against geopolitical transit risks. Accelerate modular enclosure designs with standardized screws and user-accessible thermal pads to capture Ecodesign-compliant public sector tenders before compliance deadlines harden.
For New Entrants and Emerging Players: Establish a beachhead in India's PLI-advantaged assembly ecosystem for tariff-optimized export to Middle East and African markets. Target ruggedized SSD procurement from energy sector field operations where incumbent refresh cycles lag edge computing deployment timelines. Differentiate through wireless-enabled automotive infotainment storage bypassing cable-dependent legacy architectures.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors controller-specialist firms with firmware-encryption-as-a-service capabilities over pure enclosure assemblers. Long-term viability hinges on recurring revenue detachment from hardware refresh cycles. Watch for SM4 certification completion timelines as the inflection signal separating China-accessible from China-excluded vendor tiers.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Enclosure Redesign | Captures Ecodesign-compliant public sector tenders in Germany and France. |
| Controller Silicon Backward Integration | Reduces exposure to Taiwan and South Korea fabrication bottlenecks. |
| Wireless Protocol Product Line | Opens automotive infotainment and drone field-download revenue streams. |
| Encryption-as-a-Service Launch | Shifts enterprise buyers from perpetual licenses to recurring revenue models. |
| PLI Scheme Manufacturing Footprint | Secures tariff-advantaged export positioning for Middle East and African distribution. |
Research Methodology
The analysis maps solid-state drives, external hard drives, USB flash drives, and memory cards, each validated through procurement managers at post-production houses, IT directors at logistics firms, and channel partners at value-added distributors. Primary interviews with field operations leads in Texas energy corridors and Berlin enterprise IT departments combined with secondary validation from SEC 10-K filings, customs trade data, and Ecodesign regulatory databases. Bottom-up unit shipment estimates triangulated against top-down NAND wafer supply forecasts.
Assumptions held fixed include EU Ecodesign implementation timelines and China's SAMR encryption certification pathways; variables stress-tested included NAND fabrication capacity utilization and wireless protocol adoption curves. The analytical framework modeled technology, capacity, end user, and regional segmentation dimensions across the projection horizon. CAGRs derived from price elasticity functions tied to per-gigabyte cost trajectories and replacement cycle compression in professional video workflows.
Stress conditions across NAND supply concentration, regulatory certification delays, and edge computing deployment rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions. Material shifts in export-control regime stringency or SM4 certification reciprocity agreements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
Recordable Optical Disc Market
Data Storage
Global Digital Storage Devices Market
Data Storage
Australia Data Center Storage Market
Data Storage
Ceph Storage Solutions Market
Data Storage
Americas Flash Memory Market
Data Storage
Distributed Storage System Market
Data Storage
Solid State Drive (SSD) Market
Data Storage
Storage Virtualization Market
Data Storage
Data Storage Devices Market
Data Storage
North America AMH and Storage Systems Market
Data Storage
Enterprise Hard Drive Market
Data Storage
NAND Flash Market
Data Storage
North America Next Generation Storage Market
Data Storage
Multiprotocol Storage Market
Data Storage
Global Personal and Entry Level Storage (PELS) Market
Data Storage
Universal Flash Storage Market