
 Hybrid Flash Storage Market | 2026-2036
Hybrid Flash Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Hybrid Flash Storage Market Analytics
Enterprise buyers are unwinding legacy all-disk procurement patterns in favor of hybrid architectures that blend flash speed with disk economics. Dell Technologies leverages its integrated server-storage portfolio to control large-account relationships across North American data centers. NetApp specializes in cloud-adjacent hybrid arrays that anchor multi-environment deployments for Fortune 500 workloads.
Hybrid flash storage combines NAND flash solid-state drives with mechanical hard disk drives within unified array controllers, typically achieving sub-millisecond latency for hot data while tiering colder payloads to spinning media. The primary purpose is cost-optimized performance for mixed workloads ranging from transactional databases to virtual desktop infrastructure. All-flash array segments capture premium pricing in financial services latency applications, while hybrid arrays dominate mid-market refresh cycles where cost-per-gigabyte governs selection. NVMe technology is displacing SAS and SATA interconnects in new installations, concentrating margin pools with vendors who control controller firmware and flash translation layer intellectual property.
FCC equipment authorization requirements shape electromagnetic compatibility standards for storage systems deployed in US federal environments, while EU Green Deal energy efficiency directives constrain idle power draw for arrays sold across Europe. Japan's METI promotes domestic semiconductor supply chain resilience, indirectly supporting local flash module sourcing for Hitachi Vantara and Fujitsu product lines. Stakeholders must monitor how evolving national data sovereignty laws fragment procurement specifications across jurisdictions they serve.
Market Dynamics
NVMe protocol adoption is compressing legacy SAS interconnect margins while EU Green Deal energy mandates force idle power recertification across installed European base arrays.
Growth Catalysts
- EU Green Deal efficiency mandates:Idle power draw limits for storage arrays sold across Europe accelerate refresh cycles in German and French enterprise data centers.
- AI training infrastructure buildouts:United States hyperscalers deploy hybrid flash tiers to balance checkpoint storage costs against GPU cluster throughput requirements.
- NVMe-oF fabric extension:Disaggregation of storage from compute nodes enables Japanese financial services firms to consolidate distributed SAN architectures.
Market Restraints
- NAND flash supply concentration:Korean and Taiwanese foundry output fluctuations create 90-day pricing volatility that distorts array OEM margin planning.
- Mechanical disk dependency:Cold tier capacity requirements lock hybrid architectures to spinning media supply chains with shrinking vendor diversity.
- FCC electromagnetic compatibility:Equipment authorization timelines for federal deployments extend sales cycles by 4-6 months versus commercial segments.
Strategic Opportunities
- India sovereign cloud expansion:MeitY data localization requirements drive public sector procurement of on-premise hybrid arrays with domestic certification.
- Computational storage convergence:FPGA-accelerated flash controllers enable in-situ processing for edge AI inference workloads.
- Japan METI semiconductor resilience:Domestic flash module sourcing incentives strengthen local supply chains for Hitachi Vantara and Fujitsu arrays.
Industry Challenges
- Firmware engineering scarcity:Controller-level flash translation layer expertise concentrates at legacy HDD vendors and pure-play SSD designers.
- Legacy array migration complexity:Heterogeneous data tiering policies across SATA, SAS, and NVMe media require application-level requalification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hybrid Flash Storage Market |
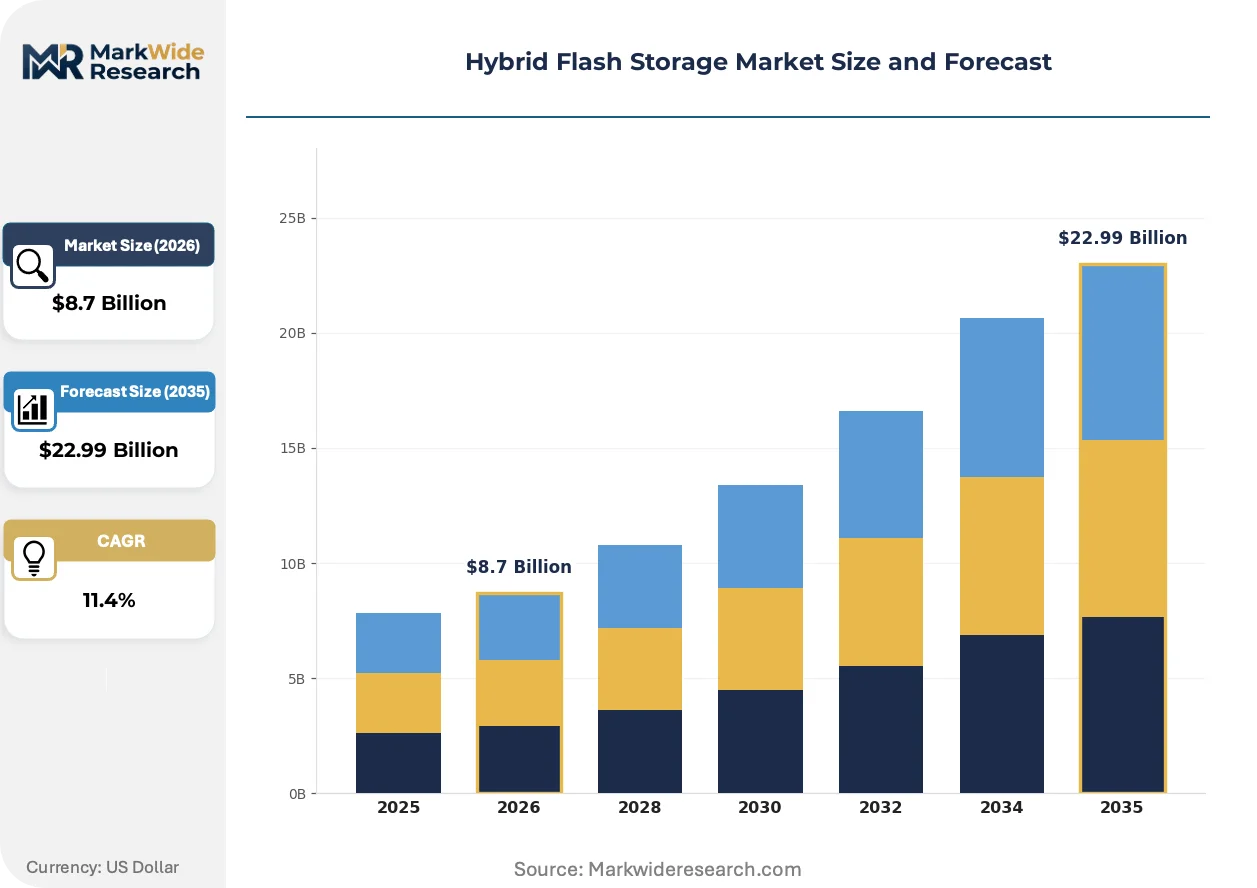
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: All-Flash Array, Hybrid Array, Storage Area Network, Direct Attached Storage Application: Data Center, Virtualization, Cloud Computing, Big Data Analytics Technology: NVMe, PCIe, SAS, SATA End User: Enterprises, SMBs, Educational Institutions, Government Agencies |
| Companies Covered | Dell Technologies, Hewlett Packard Enterprise, NetApp, IBM, Huawei Technologies, Lenovo, Fujitsu, Hitachi Vantara, Supermicro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hybrid Flash Storage Market Evolving Landscape
Controller firmware sophistication is becoming the primary differentiation vector as hardware commoditization accelerates across enterprise storage tiers.
NVMe over Fabrics is displacing traditional Fibre Channel and iSCSI interconnects in new data center deployments. United States hyperscalers and financial services firms now specify NVMe-oF as default for greenfield storage networks. This protocol shift is compressing margins for legacy SAN switch vendors while concentrating value with array controllers that embed RDMA offload engines.
EU Green Deal energy efficiency directives now mandate maximum idle power consumption thresholds for storage systems sold across member states. German and French procurement specifications already incorporate these limits, with Netherlands and Italy following in 2026. Array vendors must recertify existing product lines or face exclusion from public sector and regulated utility tenders.
Enterprise buyers now unbundle hardware acquisition from operational support contracts, favoring multi-year service agreements with outcome-based SLA structures. Systems integrators and cloud-adjacent resellers capture this margin pool in North American and Western European markets. Japanese and South Korean enterprises maintain bundled procurement patterns, creating regional channel strategy divergence.
Hybrid Flash Storage Market Segmentation
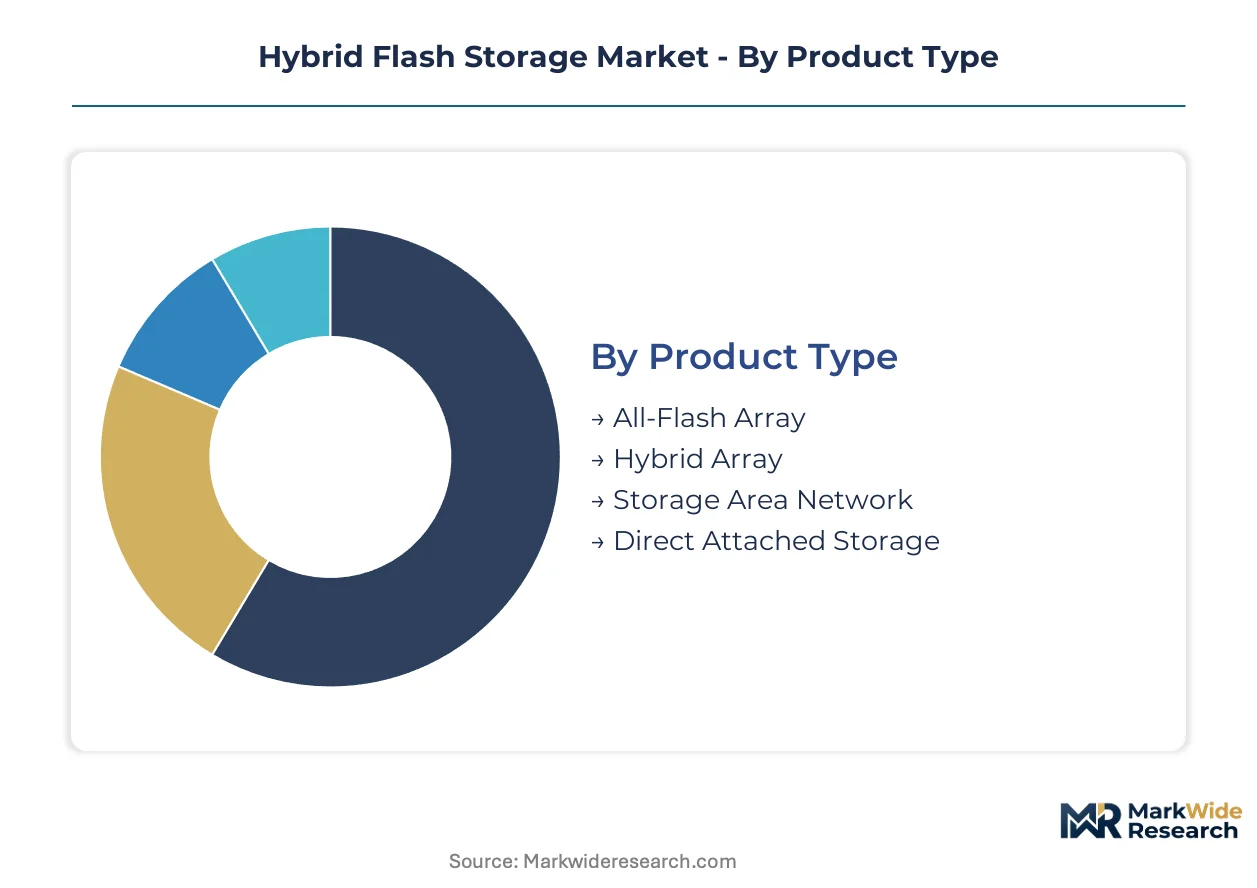
Hybrid flash storage procurement varies sharply by workload intensity, infrastructure maturity, and regulatory exposure. Buyers segment solutions across performance tiers, interconnect protocols, and operational scale rather than treating storage as a commodity category.
Product Type:
Margin pools concentrate with vendors controlling controller firmware and flash translation layer intellectual property, while hardware assembly yields compress toward contract manufacturers.
- All-Flash Array:Pure NAND flash configurations deliver sub-100 microsecond latency for financial services trading platforms and real-time fraud detection systems. United States hyperscalers deploy these for AI training checkpoint storage where GPU idle time costs exceed flash capacity premiums. NVMe interconnects now dominate new installations, displacing legacy SAS backplanes.
- Hybrid Array:Tiered architectures combine flash hot tiers with mechanical disk cold storage, achieving cost-per-gigabyte targets for mid-market data center refreshes. German enterprise buyers favor these systems under EU Green Deal power mandates that penalize idle consumption of fully flash configurations. Automated tiering software determines competitive differentiation.
- Storage Area Network:Networked block storage consolidates capacity across virtualized server farms, with Fibre Channel giving way to NVMe-oF fabrics in new Japanese financial services deployments.
- Direct Attached Storage:Server-internal drive bays persist in edge computing nodes and legacy application servers where network storage overhead is unacceptable.
Hybrid Array holds installed capacity across enterprise data centers. All-Flash Array is rotating up the share rankings as AI infrastructure buildouts accelerate.
Application:
Volume concentration follows cloud service provider expansion patterns, with sovereign cloud mandates in Europe and Asia fragmenting procurement specifications.
- Data Center:Centralized facilities consolidate mixed workloads from virtualization, databases, and analytics platforms. United States colocation providers specify hybrid flash tiers to balance tenant performance SLAs against power density constraints in aging facilities.
- Virtualization:VMware and Hyper-V environments demand consistent low latency for VDI and server consolidation projects. Indian public sector tenders under MeitY data localization rules specify on-premise hybrid arrays for virtualized citizen service portals.
- Cloud Computing:Service providers deploy disaggregated storage fabrics to separate compute scaling from capacity planning. Japanese regional cloud operators favor domestic-certified arrays under METI supply chain resilience guidelines.
- Big Data Analytics:Hadoop and Spark workloads sequential-read cold data from disk tiers while caching hot partitions in flash. Query response time requirements determine flash-to-disk ratios.
Data Center absorbs the largest shipment volumes. Cloud Computing is expanding most quickly as sovereign infrastructure buildouts multiply.
Technology:
Protocol transitions are redrawing competitive boundaries, with interconnect intellectual property becoming decisive for margin retention.
- NVMe:PCIe-based protocol eliminates SCSI translation overhead, saturating host bandwidth with flash-native parallelism. New installations in United States hyperscale and financial services environments specify NVMe as default, compressing legacy SAS switch margins.
- PCIe:Direct CPU attachment bypasses storage controllers entirely for ultra-low latency requirements in high-frequency trading and AI inference.
- SAS:Serial Attached SCSI persists in installed base refresh cycles where controller replacement costs outweigh performance gains from protocol migration.
- SATA:Legacy interconnect survives in cold archival tiers and budget-constrained SMB deployments where bandwidth requirements remain modest.
SAS retains installed base presence. NVMe is climbing the fastest as greenfield specifications harden around RDMA-capable fabrics.
End User:
Customer scale determines pricing architecture, with enterprise accounts demanding outcome-based SLAs while smaller buyers accept bundled hardware-support packages.
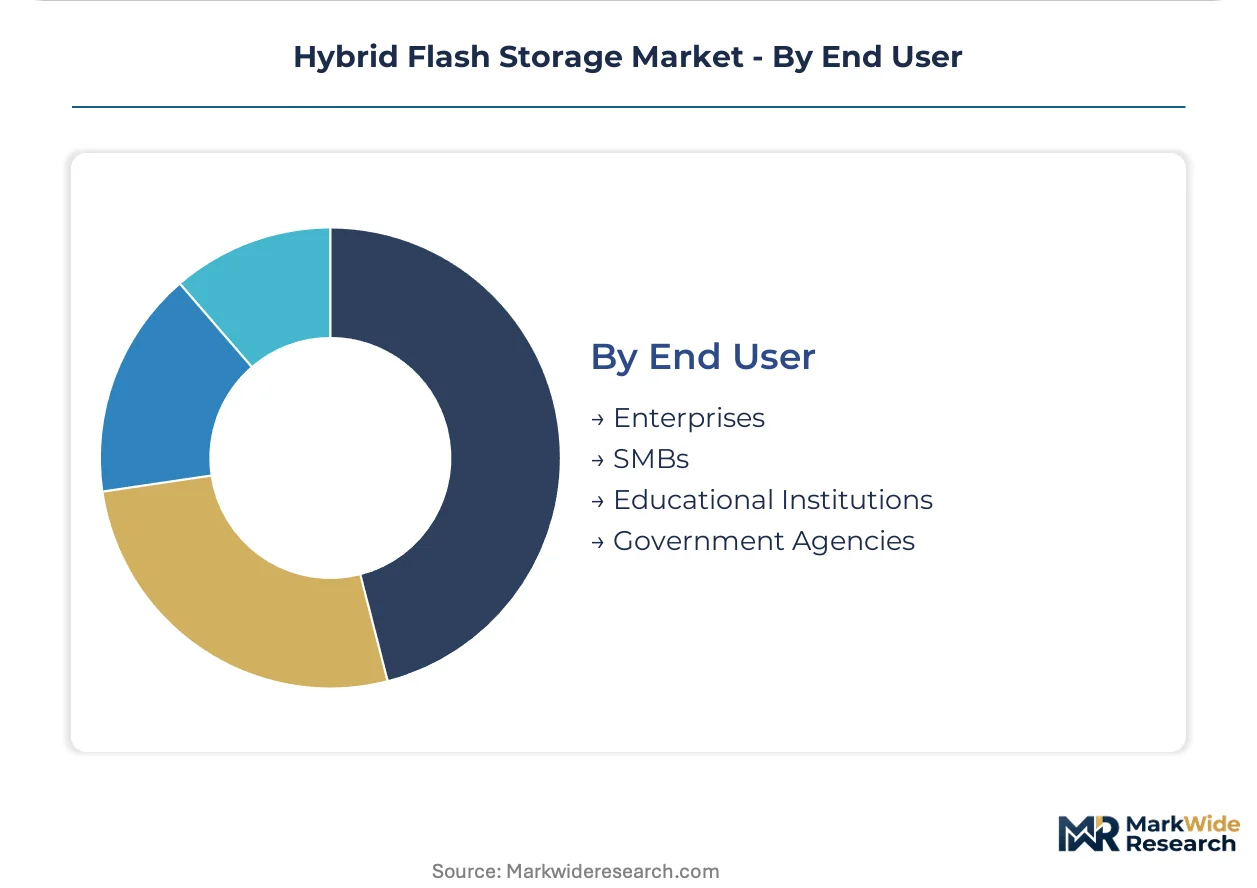
- Enterprises:Fortune 500 procurement teams unbundle hardware acquisition from operational support, favoring multi-year service agreements with availability guarantees. German automotive manufacturers specify hybrid arrays with predictive failure analytics to maintain production line continuity.
- SMBs:Mid-market buyers prioritize cost-per-gigabyte and simplified management interfaces over advanced tiering capabilities. Channel partners capture margin through integrated deployment services.
- Educational Institutions:University research computing clusters require burst capacity for grant-funded projects with unpredictable duration. United States NSF-funded facilities specify NVMe-oF to support distributed scientific workflows.
- Government Agencies:Federal deployments face extended FCC equipment authorization timelines, stretching sales cycles four to six months beyond commercial segments. Security certification requirements dominate vendor selection.
Enterprises command the deepest vendor relationships. Government Agencies represent the steepest expansion trajectory as data sovereignty laws harden procurement localization requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ashburn-Loudoun data center corridor underwrites United States dominance in hybrid flash procurement, with fiber density and power substation access drawing hyperscaler investment. Sovereign cloud buildouts in Frankfurt and Tokyo extend this infrastructure logic across regulatory jurisdictions.
United States
Hyperscale AI training clusters and financial services latency requirements drive NVMe-oF deployment across Virginia and Texas data center zones. FCC equipment authorization timelines extend federal sales cycles four to six months beyond commercial segments. Northern Virginia's Ashburn corridor concentrates procurement volume for cloud-adjacent hybrid arrays serving federal and enterprise tenants.
Germany
Automotive manufacturing continuity requirements and EU Green Deal idle power mandates accelerate hybrid array refresh cycles in Bavaria and Baden-Württemberg. KBA industrial standards intersect with EU Green Deal efficiency thresholds for storage systems deployed in regulated facilities. Frankfurt's financial district anchors NVMe-oF consolidation projects among Commerzbank and Deutsche Börse infrastructure operators.
Japan
METI semiconductor supply chain resilience programs incentivize domestic flash module sourcing for data center operators in Tokyo and Osaka. Financial services firms deploy disaggregated storage fabrics under FIEA operational continuity guidelines. Kanto region hyperscalers specify Hitachi Vantara and Fujitsu arrays with local certification for sovereign cloud workloads.
India
MeitY data localization rules mandate on-premise hybrid storage for public sector virtualization projects in Maharashtra and Karnataka. BIS certification requirements govern procurement specifications for citizen service portal infrastructure. Mumbai-Pune corridor data centers absorb mid-market hybrid array shipments for banking and telecom consolidation.
South Korea
Memory foundry supply concentration creates pricing volatility that distorts array OEM margin planning for domestic cloud operators. MFDS data integrity standards intersect with financial sector procurement for trading infrastructure in Seoul. Pangyo Techno Valley anchors NVMe deployment among Naver and Kakao platform operators.
Hybrid Flash Storage Market Competitive Landscape
Listed leaders compete with private specialists across controller firmware intellectual property, with public equity pressure favoring margin defense over share capture. The vendor base stratifies between integrated server-storage portfolios, cloud-adjacent array specialists, and contract manufacturing-dependent challengers. Two archetypes dominate: vertically integrated incumbents controlling flash translation layer IP, and modular assemblers sourcing controllers from merchant silicon vendors. Competitive moves concentrate on predictive analytics integration and energy efficiency recertification for EU market access.
Within the integrated-systems tier, Dell Technologies and Hewlett Packard Enterprise occupy positions defined by server-storage bundling relationships across North American enterprise accounts. NetApp exemplifies the cloud-adjacent specialist archetype, anchoring multi-environment deployments through software-defined storage controllers. Huawei Technologies represents the vertically integrated challenger pattern, with captive flash supply and domestic certification advantages in Asia-Pacific procurement.
| Leading Market Players |
|---|
| Dell Technologies |
| Hewlett Packard Enterprise |
| NetApp |
| IBM |
| Huawei Technologies |
| Lenovo |
| Fujitsu |
| Hitachi Vantara |
| Supermicro |
| Others |
Value Network & Pricing Analysis
Foundry-scale economies in NAND flash manufacturing concentrate margin pools with Korean and Taiwanese suppliers, compressing array OEM pricing power while establishing hard cost floors for hybrid configurations. Capacity utilization swings at memory foundries transmit directly to module pricing, forcing storage vendors to absorb volatility or pass through via quarterly contract adjustments.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs procurement, with NVMe all-flash arrays commanding certification-grade premiums for FCC-authorized federal deployments while SATA-based hybrid systems compete on cost-per-gigabyte in mid-market refreshes. Price differentiation hinges on protocol generation and energy efficiency certification under EU Green Deal thresholds, with German automotive buyers least sensitive to flash premiums due to production-line continuity requirements. Cost compression in economy-tier SATA arrays is intensifying because merchant controller silicon commoditizes firmware differentiation. SMB buyers exhibit highest price sensitivity, prioritizing bundled hardware-support packages over advanced tiering capabilities.
Supply Chain Analysis
Port congestion on Asia-Pacific trade lanes elevates inbound logistics costs for flash modules and controller components, extending lead times for array assembly facilities in Mexico and Eastern Europe. Supply concentrates in South Korea, Taiwan, and Japan for NAND flash wafers, with controller ASICs sourcing from Taiwanese foundries and firmware development anchored in the United States and Israel. Raw material dependencies span silicon wafers, rare earth elements for controller manufacturing, and cobalt for power management circuits. Single-source vulnerability in advanced node foundry capacity presents structural risk. Distribution runs through systems integrators and cloud-adjacent resellers in North America, direct enterprise sales in Japan, and domestic-certified channel partners in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise buyer consolidation around hyperscale and sovereign cloud operators shifts negotiating leverage toward volume purchasers capable of dictating custom firmware roadmaps. Fortune 500 procurement teams now unbundle hardware from support, fragmenting incumbent margin pools.
For Market Incumbents: Compound controller firmware IP advantages through predictive analytics integration and EU Green Deal recertification investments to defend against merchant silicon challengers. Prioritize captive flash translation layer expertise as legacy HDD engineering talent pools shrink. Capacity addition in India under MeitY localization requirements secures public sector tender access. For New Entrants and Emerging Players: Cloud-adjacent managed service gaps in mid-market edge deployments offer white-space entry, with NVMe-oF disaggregation expertise penetrating Japanese financial services consolidation projects. Target Indian sovereign cloud buildouts where domestic certification barriers exclude unqualified competitors. Lead with outcome-based SLA structures rather than hardware-centric positioning. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated specialists with captive controller firmware and flash module sourcing. Long-term viability over the projection horizon rests on RDMA offload engine IP and energy efficiency certification breadth. Watch NVMe-oF adoption velocity in United States financial services as inflection indicator for protocol transition timing.| Strategic Initiative | Industry Significance |
|---|---|
| NVMe-oF Fabric Certification | Enables RDMA-capable storage networks for United States hyperscaler deployments. |
| EU Green Deal Recertification | Secures German and French public sector tender eligibility under idle power mandates. |
| Controller Firmware Acquisition | Consolidates flash translation layer IP against merchant silicon commoditization. |
| India Domestic Certification | Unlocks MeitY-mandated public sector procurement for sovereign cloud infrastructure. |
| Edge AI Inference Optimization | Positions FPGA-accelerated arrays for computational storage convergence workloads. |
Research Methodology
Cross-validation between primary fieldwork and secondary data sources anchors the qualitative findings in this study. Structured interviews with data center infrastructure directors, storage procurement officers at Fortune 500 enterprises, channel partner technical leads, and cloud operator capacity planners informed demand-side dynamics. Secondary validation drew from hyperscaler capex disclosures, SEC 10-K filings of listed storage vendors, EU equipment efficiency certification databases, and national trade registries. Bottom-up shipment estimates triangulated against top-down addressable market calculations.
Sensitivity analysis around NAND flash pricing volatility and protocol transition timelines shapes the analytical framework. Segmentation dimensions modeled include product architecture, interconnect protocol, deployment scale, end-use vertical, and regional regulatory cluster. CAGRs derive from installed base refresh cycle analysis and greenfield specification trends. Forecast inputs incorporate foundry capacity expansion schedules and sovereign cloud infrastructure buildout pipelines.
Forecasts assume regulatory continuity in EU Green Deal implementation, FCC equipment authorization procedures, and Japan METI supply chain incentives; material policy shifts would require re-modeling. NAND flash supply concentration and geopolitical trade restrictions represent specific revision risks. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
SSD Controller Market
Data Storage
Storage Virtualization Market
Data Storage
Global Personal and Entry Level Storage (PELS) Market
Data Storage
External Storage Market
Data Storage
HDD Head Assembly Market
Data Storage
USB 3.1 Flash Drive Market
Data Storage
Electrochromic Storage Devices Market
Data Storage
AI Powered Storage Market
Data Storage
SAS Hard Disk Drives Market
Data Storage
Universal Flash Storage Market
Data Storage
Data Center Ssds Market
Data Storage
Recordable Optical Disc Market
Data Storage
Ethernet Storage Market
Data Storage
North America Next Generation Storage Market
Data Storage
Ceph Storage Solutions Market
Data Storage
Powered Storage Devices Market