
 Blu-Ray Optical Disk Market | 2026-2036
Blu-Ray Optical Disk Market Size, Share, and Industry Trends Forecast 2026-2036
Blu-Ray Optical Disk Market Insights
Japan is fragmenting as a production hub for high-capacity optical media while South Korea and Taiwan sustain parallel manufacturing ecosystems. Sony Corporation leverages its proprietary disc mastering technology to anchor premium archival segments. Panasonic Corporation dominates professional-grade BDXL production for broadcast and cinema archiving. Samsung Electronics competes through backward integration into polycarbonate substrate supply.
A Blu-Ray Optical Disk is a high-density optical storage medium employing a 405 nm blue-violet laser to read and write data across polycarbonate layers with capacities from 25 GB to 128 GB, engineered for long-term archival integrity and high-definition content distribution. BD-R write-once formats lead consumer home entertainment channels with mature pricing structures, while BDXL quad-layer discs represent the fastest-growing technology tier among enterprise data archiving and media production end users seeking century-scale retention. Professional use applications command the most concentrated margin pools due to certification requirements and low substitution elasticity.
FCC equipment authorization rules in the United States govern laser emission safety in optical disc drives, while Japan's METI enforces recycling directives under home appliance legislation that shape end-of-life collection obligations. China's SAMR oversees national standard compliance for imported optical media durability. Stakeholders must monitor regulatory divergence around material recyclability mandates versus archival longevity standards as jurisdictions prioritize divergent sustainability timelines.
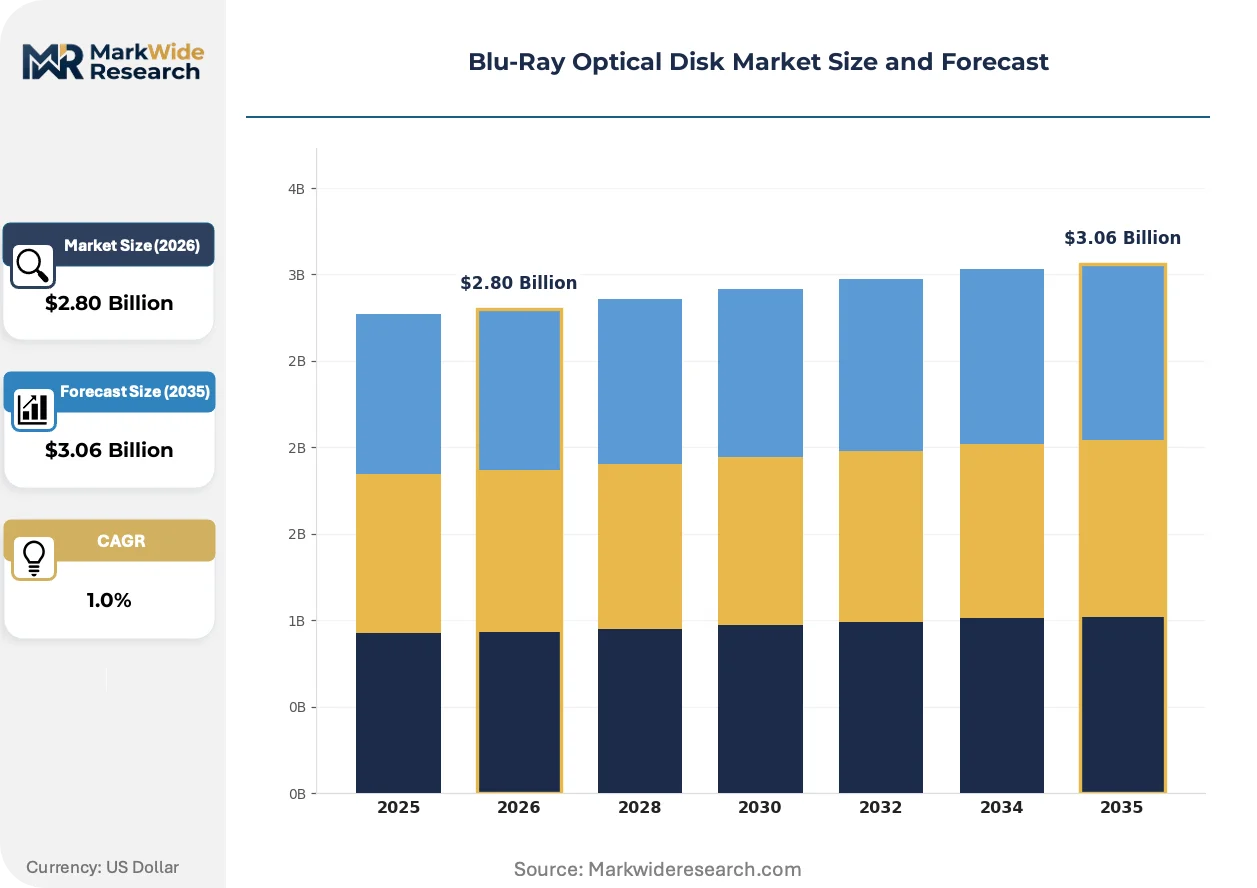
Market Dynamics
Archival data retention mandates from financial regulators and broadcast heritage institutions are compressing procurement cycles for century-scale optical media, while polycarbonate substrate supply bottlenecks in East Asia constrain volume elasticity.
Growth Catalysts
- Enterprise Archiving Mandates:Banking regulators in Switzerland and Singapore require immutable cold storage for transaction records, driving institutional procurement of BDXL formats with verified 50-year integrity specifications.
- REACH Material Compliance:The EU's RoHS and REACH directives are phasing out hazardous substrates in consumer electronics, accelerating certified green-polycarbonate disc adoption across German and French distribution channels.
- Cinema Preservation Standards:Film heritage institutions in Los Angeles, Mumbai, and Lagos are digitizing analog masters to quad-layer BDXL under studio contractual obligations, creating sustained demand for professional-grade mastering services.
Market Restraints
- Polycarbonate Price Volatility:Bisphenol-A feedstock costs fluctuate with crude oil indices, compressing margins for disc replicators dependent on spot-market resin procurement.
- Japanese Supply Concentration:Premium archival-grade substrate production clusters in Osaka and Nagoya, creating single-source vulnerability for European and North American mastering facilities.
- Cloud Cold Storage Substitution:Magnetic tape and object-storage tiers from hyperscale providers are capturing mid-tier enterprise archiving budgets previously allocated to optical media.
Strategic Opportunities
- Underpenetrated African Markets:Nigeria's Nollywood production sector lacks localized disc replication infrastructure, presenting first-mover potential for regional mastering joint ventures.
- Healthcare Imaging Archiving:PACS compliance requirements for diagnostic image retention are converging with optical media longevity specifications, opening hospital system procurement channels.
- India's PLI Scheme:Production-linked incentives for electronics manufacturing are drawing substrate and disc-fabrication investment toward Gujarat and Tamil Nadu semiconductor corridors.
Industry Challenges
- Specialized Coating Chemistry Talent:Formulation expertise for scratch-resistant hard-coat layers resides with aging cohorts in Japanese and German materials labs, constraining process scaling.
- BDXL Certification Timelines:IEC 60068 environmental stress testing for quad-layer archival discs extends product validation cycles to 18-24 months, delaying revenue recognition for new format introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blu-Ray Optical Disk Market |
| Market Size in 2026 | $2.80 Billion |
| Market Size in 2035 | $3.06 Billion |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: BD-R, BD-RE, BD-ROM, BDXL Technology: Single Layer, Dual Layer, Triple Layer, Quad Layer Application: Home Entertainment, Data Storage, Professional Use, Video Gaming End User: Consumers, Enterprises, Educational Institutions, Media Production |
| Companies Covered | Sony Corporation, Panasonic Corporation, Samsung Electronics, LG Electronics, Verbatim Corporation, Ritek Corporation, CMC Magnetics Corporation, Pioneer Corporation, Taiyo Yuden, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blu-Ray Optical Disk Market Trends and Innovations
Disc mastering technology is bifurcating between consumer-grade replication and professional archival certification, with material science advances determining competitive positioning in longevity-rated segments.
Glass-based substrate research from Corning and Asahi Glass is rendering obsolete traditional polycarbonate limitations on thermal stability and scratch resistance. Broadcast archive operators in London and Sydney are piloting these prototypes for climate-uncontrolled storage environments. The structural consequence is a compression of acceptable archival media lifecycles from 50-year to 100-year certified specifications.
China's NMPA durability standards for imported optical media are tightening material traceability requirements through 2024 implementation timelines. SAMR enforcement actions against non-compliant substrate imports have disrupted supply flows to Guangdong assembly plants. Professional BDXL importers are responding by establishing in-country testing laboratories to pre-validate shipment batches against GB/T 16969 specifications.
Hospital procurement departments are consolidating optical media purchasing through group purchasing organizations rather than direct manufacturer relationships. The channel disruption concentrates volume with distributors holding IEC 62321 hazardous substance testing certifications. This consolidation is most visible in German and Austrian healthcare networks where centralized medical device procurement mandates have eliminated spot-buying flexibility for radiology departments.
Blu-Ray Optical Disk Market Segmentation
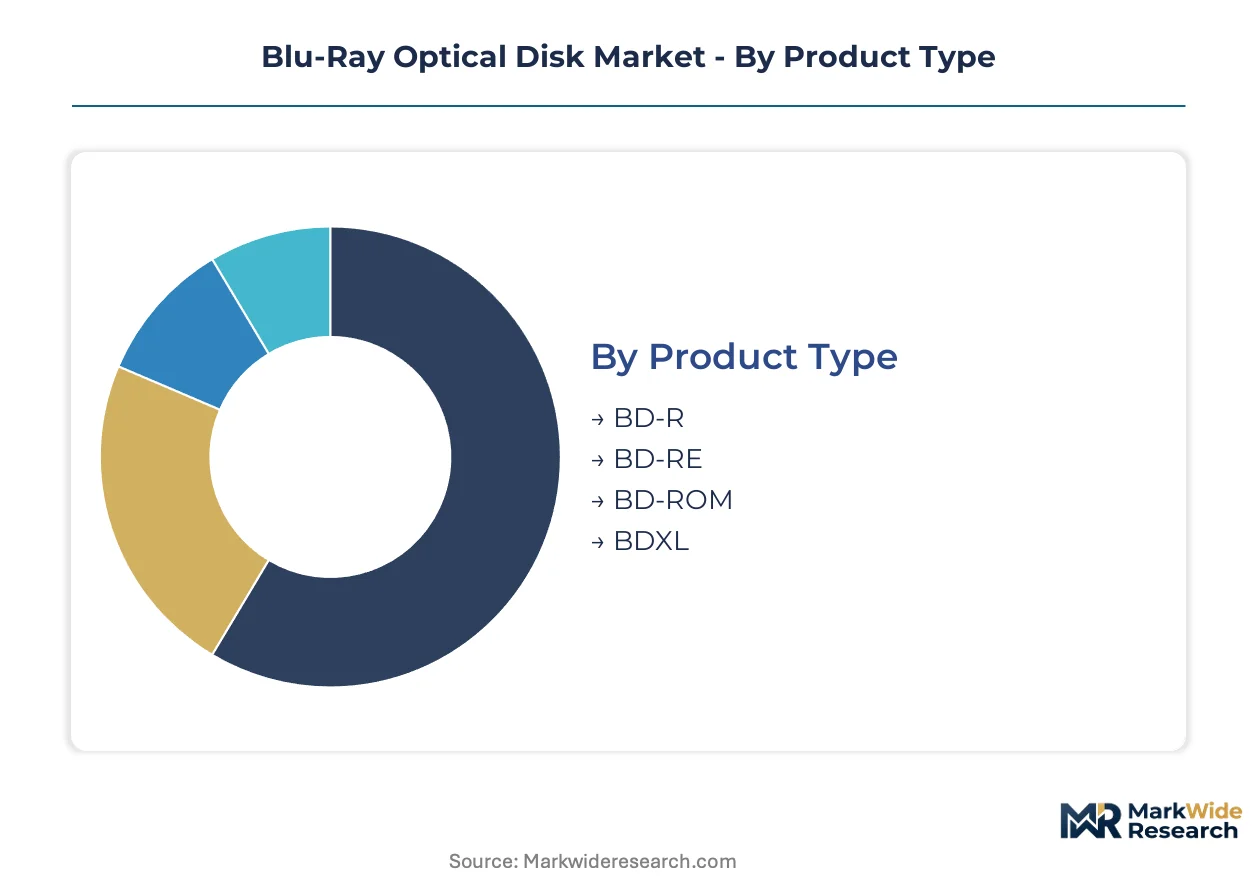
Segmentation in the Blu-Ray Optical Disk Market reveals divergent procurement rhythms across archival, consumer, and institutional channels. Cycle-time disparities between write-once formats and rewritable media create distinct inventory and pricing dynamics for manufacturers.
Product Type:
BD-R discs rotate through consumer retail channels fastest, while BDXL formats sit in enterprise procurement pipelines for quarters due to certification requirements.
- BD-R:Write-once polycarbonate discs with 25-50 GB capacity dominate home entertainment distribution. Swiss banking regulators specify BD-R for immutable transaction archives, compressing spot-buying flexibility.
- BDXL:Quad-layer 100-128 GB discs employ modified organic dye formulations for century-scale retention. Los Angeles film heritage institutions digitize analog masters to BDXL under studio preservation mandates, sustaining professional mastering demand.
- BD-RE:Rewritable formats serve iterative data backup workflows in small enterprises.
- BD-ROM:Pre-recorded discs anchor physical media retail in Japan's consumer electronics strongholds.
BD-R anchors the volume base while BDXL gains share at the steepest rate.
Technology:
Layer count stratifies manufacturing complexity and end-use certification requirements across the technology stack.
- Quad Layer:Four stacked recording layers achieve 128 GB through refined spin-coating precision. Sydney broadcast archives pilot quad-layer prototypes for climate-uncontrolled storage, validating 100-year specifications against IEC 60068 stress protocols.
- Single Layer:25 GB capacity represents the baseline polycarbonate substrate format. Nigerian Nollywood distributors rely on single-layer replication for cost-sensitive regional distribution.
- Dual Layer:50 GB capacity serves standard-definition cinema mastering.
- Triple Layer:100 GB formats occupy a narrowing mid-tier between consumer and archival segments.
Single Layer retains the highest shipment volumes while Quad Layer expands most quickly in enterprise procurement.
Application:
Application segments separate entertainment consumption from compliance-driven institutional retention mandates.
- Professional Use:Certified archival mastering for broadcast and cinema requires BDXL formats with verified environmental stress documentation. German hospital PACS compliance mandates are converging with optical longevity specifications, opening radiology procurement channels.
- Data Storage:Enterprise cold storage applications compete directly with magnetic tape from hyperscale cloud providers. Singaporean banking regulators require immutable optical archives for transaction records, insulating this segment from cloud substitution.
- Home Entertainment:Consumer video distribution faces streaming displacement.
- Video Gaming:Physical game distribution concentrates in Japanese and South Korean retail.
Home Entertainment commands the widest shipment base while Professional Use captures the most concentrated margin pools.
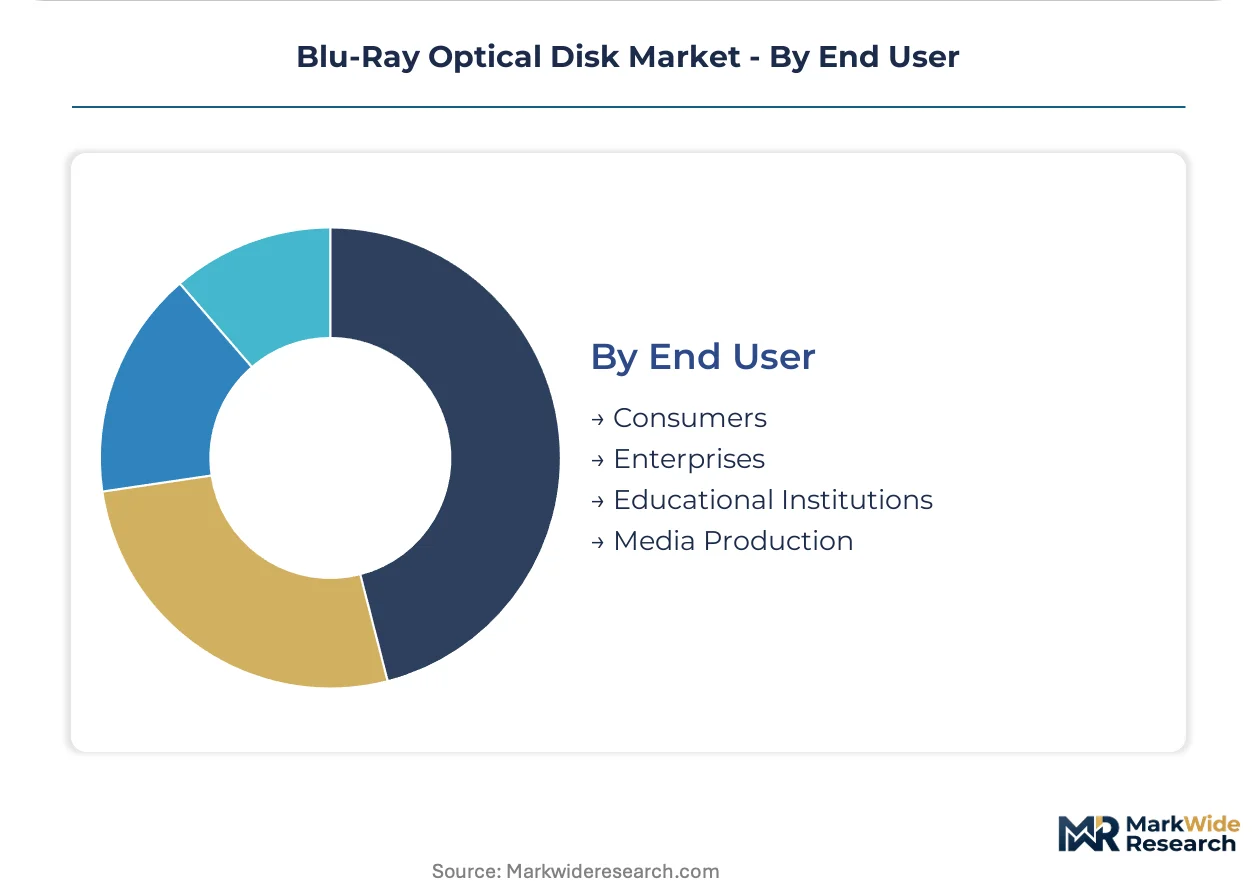
End User:
End-user categories reflect divergent technical specifications, procurement centralization, and replacement cycle patterns.
- Enterprises:Institutional buyers consolidate optical media purchasing through group purchasing organizations with IEC 62321 hazardous substance certifications. German and Austrian healthcare networks have eliminated spot-buying flexibility for radiology departments through centralized medical device procurement mandates.
- Media Production:Film and broadcast mastering facilities require certified archival-grade substrates with full material traceability. China's SAMR enforcement actions against non-compliant imports have disrupted supply flows, prompting pre-validation laboratories in Guangdong.
- Consumers:Individual purchasers drive retail turnover in physical media channels.
- Educational Institutions:University archives represent a fragmented, price-sensitive segment with extended replacement cycles.
Enterprises anchor procurement volume stability while Media Production demands the most stringent certification tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Nagoya anchors East Asian substrate flows, while Rotterdam's intermodal terminals handle European polycarbonate resin distribution for disc replication clusters.
Japan
Osaka and Nagoya host premium archival-grade substrate production for broadcast mastering facilities. METI enforces recycling directives under home appliance legislation that shape end-of-life collection obligations for optical media. Tokyo-based mastering houses supply century-scale BDXL discs to Los Angeles film heritage institutions under studio preservation contracts.
China
Guangdong assembly plants consume imported polycarbonate substrates for consumer-grade disc replication. SAMR oversees national standard compliance for optical media durability through tightened GB/T 16969 specifications. Shenzhen-based testing laboratories pre-validate shipment batches against NMPA material traceability requirements before customs clearance.
Germany
Bavarian healthcare networks consolidate optical media purchasing through group purchasing organizations with IEC 62321 certifications. REACH and RoHS directives phase out hazardous substrates in consumer electronics, accelerating certified green-polycarbonate adoption. Frankfurt-area radiology departments face centralized procurement mandates that eliminate spot-buying flexibility for PACS-compliant archiving.
Switzerland
Zurich-based banking regulators mandate immutable cold storage for transaction records, driving institutional procurement of BDXL formats. Swissmedic oversees medical device traceability requirements that intersect with diagnostic image retention standards. Basel-area pharmaceutical archives specify optical media for batch record retention under GMP compliance frameworks.
Singapore
Financial regulators require immutable optical archives for transaction records, insulating enterprise procurement from cloud substitution pressures. The country's port infrastructure handles polycarbonate resin transshipment to Southeast Asian replication facilities. Local broadcast archives serve as regional mastering hubs for Nollywood distributors lacking Nigerian replication infrastructure.
Blu-Ray Optical Disk Market Competitive Landscape
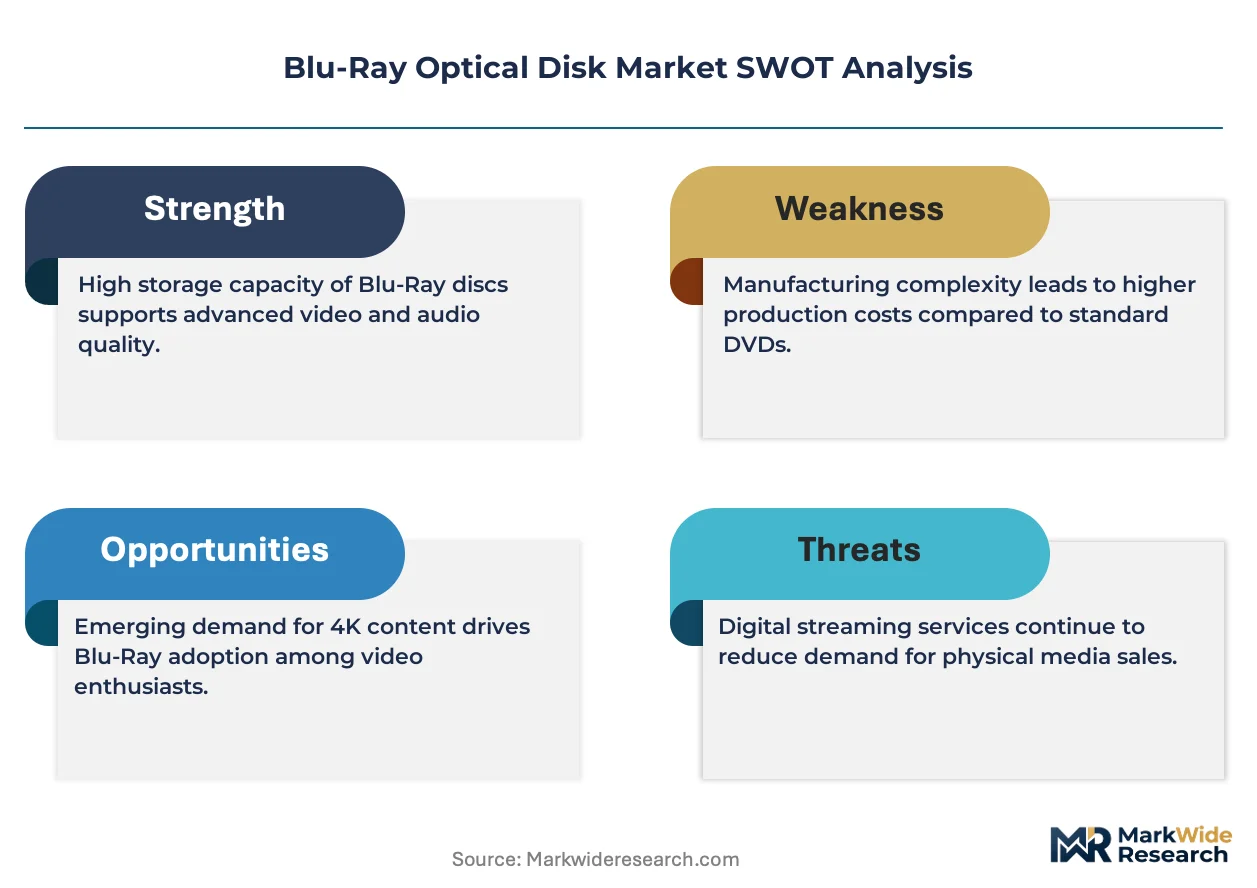
Platform integrators command the system tier; component specialists sit upstream in substrate and coating chemistry. The vendor base stratifies across three tiers: multinational electronics conglomerates with captive disc mastering operations, independent replication specialists serving regional distribution channels, and materials suppliers controlling polycarbonate and organic dye formulations. Two strategic archetypes dominate: backward-integrated substrate producers and certification-heavy archival-grade specialists. Competitive moves concentrate on capacity consolidation in East Asian manufacturing clusters and technology licensing agreements for quad-layer spin-coating precision.
Among Japanese electronics conglomerates, Sony Corporation and Panasonic Corporation occupy positions at the premium archival tier, while Samsung Electronics exemplifies the Korean integrated-systems archetype with upstream control over polycarbonate supply. These three anchors represent divergent strategic postures: proprietary disc mastering technology, professional-grade BDXL certification dominance, and backward integration into substrate manufacturing respectively.
| Leading Market Players |
|---|
| Sony Corporation |
| Panasonic Corporation |
| Samsung Electronics |
| LG Electronics |
| Verbatim Corporation |
| Ritek Corporation |
| CMC Magnetics Corporation |
| Pioneer Corporation |
| Taiyo Yuden |
| Others |
Pricing and Supply Chain Analysis
Polycarbonate substrate production clusters in Osaka and Nagoya concentrate margin capture with Japanese electronics conglomerates, while European and North American mastering facilities absorb cost pass-throughs for archival-grade certification tiers.
Pricing Analysis
REACH and RoHS directives dictate the pricing tier structure across European distribution channels, separating certified green-polycarbonate formats from standard consumer grades. Three-tier pricing structure across premium archival, professional mastering, and economy replication levels reflects certification depth and material traceability. Cost compression in economy tiers is intensifying because bisphenol-A feedstock costs fluctuate with crude oil indices. Home entertainment consumers exhibit the highest price sensitivity, while Swiss banking regulators and German hospital networks demonstrate minimal elasticity for century-scale retention specifications.
Supply Chain Analysis
Tariff exposure between China and key polycarbonate source markets dominates supply chain risk calculus for Guangdong assembly plants. Raw material flows draw from Japan, South Korea, and Taiwan for premium substrate grades, while bisphenol-A resin and organic dye formulations anchor cost structures. Single-source vulnerability concentrates in Nagoya-area coating chemistry specialists with aging formulation expertise. Distribution runs through Rotterdam's intermodal terminals for European replication clusters and Singapore's port infrastructure for Southeast Asian transshipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise archiving mandates from financial regulators and broadcast heritage institutions signal early-cycle expansion, with BDXL format penetration in institutional procurement channels accelerating beyond consumer displacement trends.
For Market Incumbents: Harden substrate supply security through captive polycarbonate production or long-term offtake agreements with Nagoya and Osaka suppliers. Deepen certification moats by accelerating IEC 60068 environmental stress testing capabilities ahead of BDXL format proliferation. Cloud cold storage substitution from hyperscale providers threatens mid-tier enterprise archiving budgets.
For New Entrants and Emerging Players: Nigerian Nollywood production infrastructure gaps present first-mover potential for regional mastering joint ventures with Lagos-based distributors. India's PLI scheme for electronics manufacturing draws substrate investment toward Gujarat corridors with favorable tariff positioning. Target hospital PACS compliance requirements in German and Austrian healthcare networks through group purchasing organization certification pathways.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across quad-layer spin-coating precision equipment as BDXL certification timelines extend validation cycles. Acquisition targets should emphasize materials suppliers controlling organic dye formulations and scratch-resistant hard-coat chemistry expertise. Watch for SAMR enforcement actions against non-compliant substrate imports as early signals of supply consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polycarbonate Supply | Samsung Electronics exemplifies margin control through captive substrate production in South Korean petrochemical corridors. |
| Quad-Layer Certification Investment | Panasonic Corporation anchors professional-grade BDXL dominance through IEC 60068 validation infrastructure in Osaka facilities. |
| Regional Mastering Joint Venture | Nigerian Nollywood distributors lack localized replication infrastructure, creating partnership openings for East Asian equipment suppliers. |
| Healthcare Procurement Channel Development | German hospital group purchasing organizations consolidate optical media purchasing through IEC 62321 certified distributors. |
| Glass Substrate Technology Licensing | Corning and Asahi Glass research renders polycarbonate limitations obsolete for climate-uncontrolled broadcast archives in Sydney and London. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with disc replication facility managers, polycarbonate procurement leads at electronics conglomerates, broadcast archive operators, hospital PACS administrators, and regulatory compliance officers at SAMR and METI. Secondary validation drew from customs trade data for optical media shipments, SEC filings of listed electronics manufacturers, IEC certification registries, and REACH substance restriction updates. Bottom-up volume modeling triangulated against top-down market sizing across product type, layer technology, application segment, and end-user category dimensions.
Calibration against historical shipment data and operating cost disclosures from Japanese and Korean substrate producers anchored the analytical framework across the projection horizon. Segmentation modeling captured write-once versus rewritable format splits, single through quad-layer technology tiers, and professional versus consumer application channels. CAGRs derived from regression analysis of procurement cycle compression in enterprise archiving and streaming displacement rates in home entertainment.
Practitioners should monitor polycarbonate price volatility, SAMR enforcement intensity, and cloud storage pricing trajectories for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
SSD Controller Market
Data Storage
Transparent Cache Market
Data Storage
Asia-Pacific Data Center Storage Market
Data Storage
All Flash Storage Market
Data Storage
Europe Next Generation Storage Market
Data Storage
APAC Next Generation Storage Market
Data Storage
Middle East and Africa SSD Caching Market
Data Storage
Multiprotocol Storage Market
Data Storage
Object-Based Storage Market
Data Storage
Ethernet Storage Market
Data Storage
Next-Generation Storage Market
Data Storage
Recordable Optical Disc Market
Data Storage
Storage Class Memory Market
Data Storage
Nearline Hard Disk Drive Market
Data Storage
Heat-Assisted Magnetic Recording (HAMR) Device Market
Data Storage
Middle East and Africa AMH and Storage Systems Market