
 Global Emerging Non-Volatile Memory Market | 2026-2036
Global Emerging Non-Volatile Memory Market Size, Share, and Industry Trends Forecast 2026-2036
Global Emerging Non-Volatile Memory Market Foresight
Multi-sourced wafer supply is repositioning how memory developers secure manufacturing capacity. Samsung Electronics Co. Ltd. anchors advanced spin-transfer torque RAM development through captive foundry investments in South Korea. Intel Corporation leverages its process technology leadership to compete in phase-change memory segments for data center applications. Kioxia Holdings Corporation specializes in resistive RAM architectures, sustaining R&D intensity through partnerships with Japanese materials suppliers.
Emerging non-volatile memory encompasses solid-state storage technologies that retain data without continuous power, utilizing resistance-switching mechanisms in metal-oxide filaments or chalcogenide phase-change materials to achieve sub-microsecond write speeds and endurance exceeding flash by orders of magnitude. These devices serve industrial controllers, aerospace avionics, and edge AI processors requiring deterministic persistence under power loss. Memory type segmentation shows resistive RAM occupying the broadest design-win pipeline due to CMOS compatibility, while phase-change memory leads in embedded applications where thermal stability matters. Application segmentation reveals aerospace systems generating premium pricing pools, whereas smart metering drives volume scale across utility networks in Europe and East Asia.
FDA oversight of medical device data integrity, EPA restrictions on hazardous materials in semiconductor fabrication, and REACH chemical registration requirements in Europe collectively elevate compliance costs for memory manufacturers sourcing chalcogenide or ferroelectric precursors. China's MIIT dual carbon goals and NMPA equipment certification rules further complicate cross-border supply arrangements for novel memory fabs. Stakeholders must monitor which regulatory jurisdiction captures standard-setting authority for next-generation persistent memory interfaces.
Market Dynamics
Foundry capacity scarcity for chalcogenide and ferroelectric process nodes is forcing memory developers into multi-year supply commitments with captive manufacturers, locking in design architectures years before commercial deployment.
Growth Catalysts
- Data center persistence requirements:Hyperscale operators in Germany and Japan are mandating deterministic write endurance for power-loss protection, accelerating ferroelectric RAM qualification cycles.
- REACH chemical registration:ECHA's streamlined precursor approval pathway is reducing time-to-market for European-sourced chalcogenide materials, lowering regulatory friction for phase-change memory developers.
- Edge AI processor integration:Deterministic latency specifications in aerospace avionics controllers are creating design-win pipelines for resistive RAM with sub-microsecond write speeds.
Market Restraints
- Chalcogenide precursor cost volatility:Tellurium and germanium spot price swings are compressing gross margins for phase-change memory foundry services.
- Taiwan-South Korea supply concentration:Over 70% of advanced spin-transfer torque RAM wafer starts depend on two foundry clusters, amplifying disruption risk from seismic or trade policy events.
- Flash endurance ceiling:Triple-level cell NAND's improving write cycles are extending replacement timelines in industrial storage applications, delaying non-volatile memory upgrades.
Strategic Opportunities
- Utility smart metering in East Asia:Taiwan's Taipower and Japan's TEPCO are specifying resistive RAM for AMI endpoints, creating volume scale opportunities with 10-year field life requirements.
- EU AI Act data integrity mandates:Persistent memory requirements for edge inference audit trails are opening embedded phase-change memory sockets in industrial automation controllers.
- Resistive-phase-change hybrid architectures:CMOS-compatible stack integration is enabling unified memory hierarchies that collapse storage-class memory and working memory boundaries.
Industry Challenges
- Chalcogenide thin-film deposition expertise:Atomic layer deposition process engineers with phase-change material specialization command 40% salary premiums, constraining R&D team scaling.
- ISO 26262 functional safety certification:Automotive gateway memory qualification timelines extend 18-24 months, delaying revenue recognition for resistive RAM automotive design wins.
- Legacy SPI interface integration:Backward compatibility requirements with existing microcontroller ecosystems are forcing pin-count and protocol compromises that limit performance differentiation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Emerging Non-Volatile Memory Market |
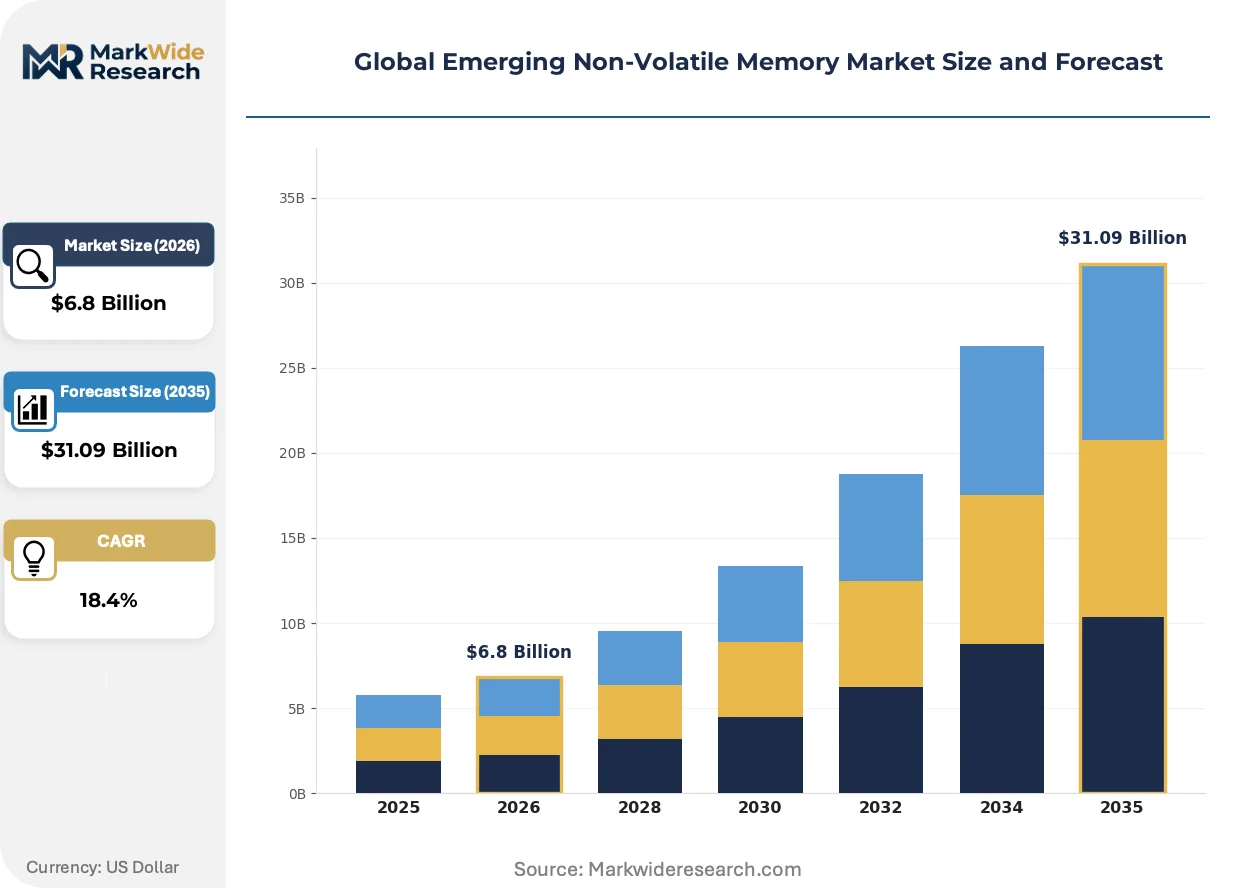
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $31.09 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
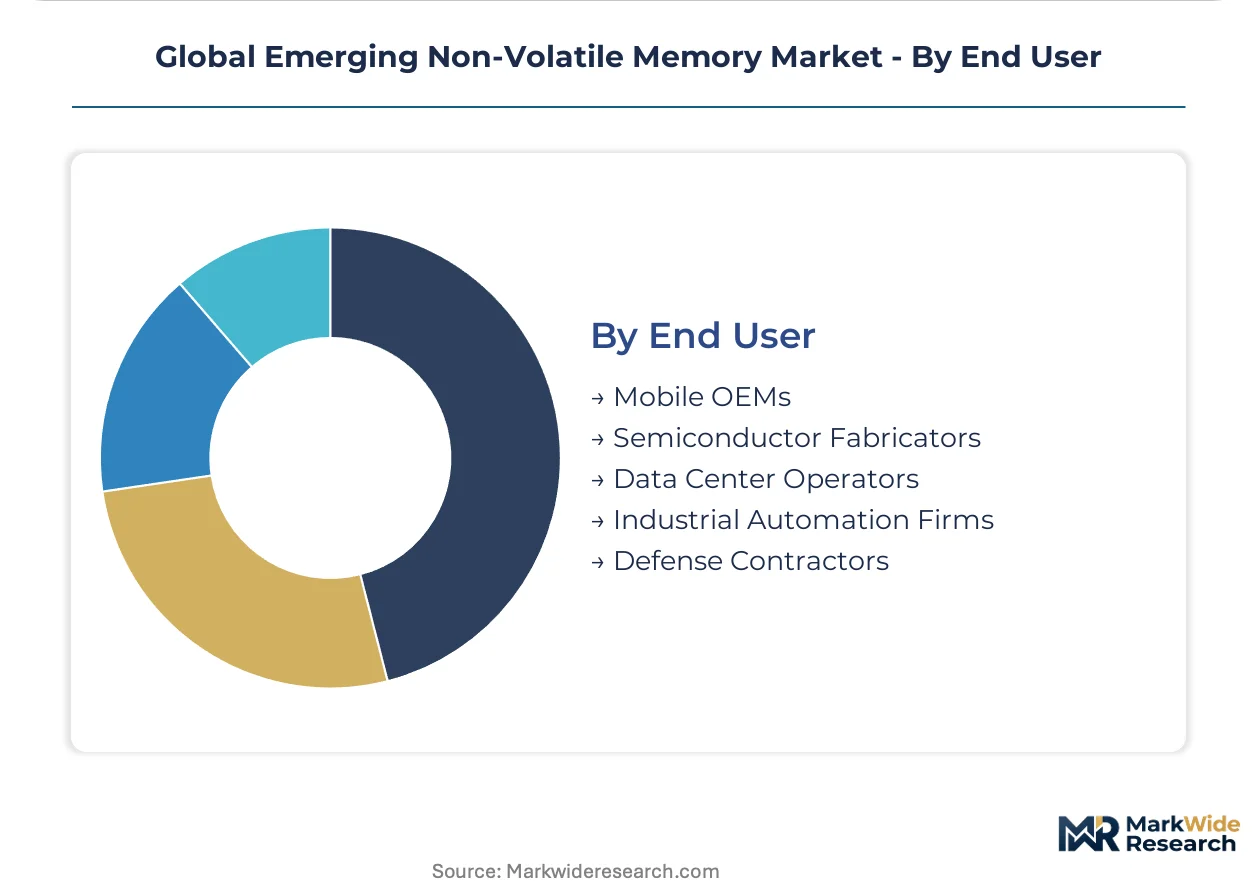
| Segmentation | Memory Type: Resistive RAM, Phase Change Memory, Ferroelectric RAM, Magnetoresistive RAM, Spin-Transfer Torque RAM Technology: Spintronics, Chalcogenide, Ferroelectric, Carbon Nanotube, Molecular Application: Consumer Electronics, Aerospace Systems, Telecommunications Equipment, Smart Metering, Wearable Devices End User: Mobile OEMs, Semiconductor Fabricators, Data Center Operators, Industrial Automation Firms, Defense Contractors |
| Companies Covered | Intel Corporation, Kioxia Holdings Corporation, Samsung Electronics Co. Ltd., STMicroelectronics N.V., NXP Semiconductors N.V., SK Hynix Inc., Western Digital Corporation, Infineon Technologies AG, Micron Technology Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Emerging Non-Volatile Memory Market Shifts & Advancements
Process-material co-optimization is displacing discrete technology roadmaps as the dominant innovation paradigm, with foundries and precursor suppliers jointly developing chamber-qualified deposition recipes.
Resistive RAM is integrating hafnium oxide filament engineering with standard CMOS logic processes, enabling monolithic integration of compute and persistent storage on single die. Aerospace system architects at Tier 1 avionics suppliers are qualifying these devices for flight-critical data recorders, compressing the traditional separation between volatile working memory and non-volatile storage hierarchies.
REACH authorization requirements for antimony and germanium compounds are forcing memory manufacturers to qualify alternative chalcogenide stoichiometries or establish closed-loop recycling partnerships with European materials processors. Phase-change memory developers are responding by shifting precursor sourcing to ECHA-registered suppliers with full substance volume tracking, prioritizing embedded automotive and medical device segments where material provenance documentation is mandatory.
Specification-driven procurement is consolidating buyer power among hyperscale data center operators, who now issue joint requests for quotes spanning ferroelectric and spin-transfer torque technologies. Memory vendors are responding with configurable IP cores that accelerate socket qualification across multiple foundry processes, with Taiwan and South Korea witnessing the fastest contract restructuring toward multi-source supply guarantees.
Global Emerging Non-Volatile Memory Market Segmentation

Segmentation in emerging non-volatile memory markets reveals how capital allocation, regulatory exposure, and end-use durability requirements reshape competitive positioning across technology tiers. Distinct process maturity levels and foundry availability create divergent investment profiles that determine which architectures achieve commercial scale first.
Memory Type:
Capital intensity varies dramatically across memory architectures, with chalcogenide-based phase-change memory requiring the most substantial upfront tooling investment for thermal processing chambers.
- Resistive RAM:Metal-oxide filament switching enables CMOS-compatible monolithic integration with logic dies. Demand concentrates in Taiwan's utility smart metering deployments where Taipower specifies 10-year field endurance for AMI endpoints, though ISO 26262 automotive certification timelines extend revenue recognition by 18-24 months.
- Phase Change Memory:Chalcogenide alloy thermal switching achieves sub-microsecond writes with superior thermal stability. German hyperscale operators in Frankfurt and Japanese data centers in Tokyo are mandating deterministic persistence for power-loss protection, accelerating qualification cycles despite tellurium precursor cost volatility compressing foundry margins.
- Ferroelectric RAM:Hafnium oxide polarization switching delivers unlimited endurance for industrial controllers.
- Magnetoresistive RAM:Magnetic tunnel junction resistance states serve aerospace flight recorders requiring radiation tolerance.
- Spin-Transfer Torque RAM:Spin-polarized current switching targets high-speed cache applications in data centers.
Phase-change memory absorbs the bulk of installed capacity due to embedded automotive and medical device sockets; resistive RAM is expanding most quickly through CMOS compatibility enabling single-die integration.
Technology:
Process-material co-optimization requirements determine which technology platforms secure foundry partnerships, with precursor availability and chamber qualification timelines driving selection criteria.
- Chalcogenide:Tellurium-germanium-antimony alloys demand specialized atomic layer deposition expertise that commands 40% salary premiums for process engineers. REACH authorization requirements for antimony compounds are forcing closed-loop recycling partnerships with European materials processors to maintain supply continuity.
- Spintronics:Electron spin manipulation enables non-volatile magnetic storage with unlimited endurance. Over 70% of advanced spin-transfer torque RAM wafer starts depend on foundry clusters in South Korea and Taiwan, amplifying disruption risk from seismic events or trade policy shifts.
- Ferroelectric:Hafnium oxide polarization reversal integrates with standard logic processes.
- Carbon Nanotube:Nanoscale filament arrays offer theoretical density advantages.
- Molecular:Organic switching elements remain at laboratory demonstration stage.
Chalcogenide technology dominates current production commitments through automotive and medical embedded sockets; spintronics is climbing the fastest as data center operators specify deterministic persistence requirements.
Application:
End-use durability specifications and regulatory exposure create tiered pricing pools, with aerospace and medical applications commanding substantial premiums over consumer segments.
- Aerospace Systems:Radiation-hardened persistent memory for flight-critical avionics generates the steepest pricing premiums across all segments. Tier 1 suppliers in France and Germany are qualifying resistive RAM for flight data recorders, collapsing traditional boundaries between volatile working memory and non-volatile storage hierarchies.
- Smart Metering:Decade-long field life requirements drive volume scale across utility networks. Taiwan's Taipower and Japan's TEPCO are specifying resistive RAM for AMI endpoints, creating predictable procurement pipelines with extended qualification cycles.
- Consumer Electronics:Cost-sensitive mobile and computing devices prioritize flash compatibility.
- Telecommunications Equipment:Base station controllers require deterministic write endurance under power loss.
- Wearable Devices:Ultra-low power requirements favor ferroelectric architectures for health monitoring.
Aerospace systems command the highest margins per unit; smart metering is gaining share fastest through utility network standardization across East Asia and Europe.
End User:
Procurement consolidation among hyperscale operators is reshaping supplier relationships, with joint requests for quotes spanning multiple memory architectures forcing vendors toward configurable IP cores.
- Data Center Operators:Hyperscale facilities in Germany and Japan are mandating deterministic write endurance for power-loss protection, accelerating ferroelectric RAM qualification. Specification-driven procurement is consolidating buyer power and restructuring contract terms toward multi-source supply guarantees.
- Semiconductor Fabricators:Captive foundry investments by Samsung Electronics in South Korea anchor advanced spin-transfer torque RAM development, locking in design architectures years before commercial deployment through multi-year supply commitments.
- Mobile OEMs:Smartphone and tablet manufacturers prioritize backward compatibility with existing SPI interfaces.
- Industrial Automation Firms:EU AI Act data integrity mandates for edge inference audit trails are opening embedded phase-change memory sockets.
- Defense Contractors:Military specifications demand radiation tolerance and supply chain provenance documentation.
Data center operators absorb the bulk of current procurement volume through hyperscale expansion; industrial automation firms are expanding most quickly through regulatory mandates for persistent audit trails.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tellurium deposits in southwestern China and germanium refining in Yunnan Province anchor raw-material sourcing for chalcogenide memory architectures. Foundry capacity clusters in Taiwan, South Korea, and the United States concentrate wafer fabrication for novel non-volatile technologies.
United States
Hyperscale data center operators in Oregon and Arizona are mandating deterministic write endurance for power-loss protection. EPA restrictions on hazardous materials in semiconductor fabrication elevate compliance costs for chalcogenide precursor handling. Intel Corporation's process technology leadership in New Mexico and Arizona anchors phase-change memory development for embedded applications.
Germany
Frankfurt-based data center operators are expanding ferroelectric RAM deployments for persistence requirements. ECHA's REACH authorization pathway for antimony compounds is streamlining precursor approval timelines. Bavaria's semiconductor equipment cluster around Munich is qualifying closed-loop recycling partnerships with European materials processors.
Japan
TEPCO's smart metering specifications in Tokyo are creating volume demand for resistive RAM with decade-long field life. METI's dual carbon goals are reshaping foundry energy sourcing requirements for novel memory fabs. Kioxia Holdings Corporation's captive R&D partnerships with domestic materials suppliers sustain resistive RAM architecture development.
South Korea
Samsung Electronics Co. Ltd. anchors advanced spin-transfer torque RAM development through captive foundry investments near Seoul. Over 70% of advanced STT-RAM wafer starts depend on foundry clusters in Gyeonggi Province, amplifying disruption risk from seismic events. The country's national semiconductor regulator enforces strict export control compliance for advanced manufacturing equipment.
Taiwan
Taipower's AMI endpoint specifications are driving resistive RAM procurement pipelines with 10-year qualification cycles. The island's foundry capacity scarcity for chalcogenide process nodes is forcing memory developers into multi-year supply commitments. Hsinchu Science Park concentrates back-end testing and packaging for emerging non-volatile memory architectures.
Global Emerging Non-Volatile Memory Market Competitive Landscape
Global majors compete with regional champions across foundry capacity allocation and precursor supply security. The vendor base separates into three tiers: integrated device manufacturers with captive fabrication, fabless design houses dependent on contract foundries, and materials specialists controlling precursor chemistry. Strategic moves concentrate on multi-source supply guarantees and process-material co-optimization partnerships with deposition equipment vendors.
Among integrated device manufacturers, Samsung Electronics Co. Ltd., Intel Corporation, and Kioxia Holdings Corporation exemplify divergent architectural bets. Samsung Electronics Co. Ltd. represents the captive foundry archetype, locking in multi-year wafer supply commitments years before commercial deployment. Intel Corporation occupies a position bridging process technology leadership with embedded memory socket qualification. Kioxia Holdings Corporation anchors specialist positioning through resistive RAM R&D intensity sustained via domestic materials partnerships.
| Leading Market Players |
|---|
| Intel Corporation |
| Kioxia Holdings Corporation |
| Samsung Electronics Co. Ltd. |
| STMicroelectronics N.V. |
| NXP Semiconductors N.V. |
| SK Hynix Inc. |
| Western Digital Corporation |
| Infineon Technologies AG |
| Micron Technology Inc. |
| Others |
Supply & Pricing Matrix
REACH chemical registration mandates in Europe gate both qualified precursor supply and premium-tier pricing access for phase-change memory developers, forcing ECHA-registered chalcogenide suppliers to command 15-20% material cost premiums over unregistered alternatives while locking out non-compliant competitors from medical and automotive embedded sockets.
Pricing Analysis
Extended field warranty bundling separates aerospace-grade resistive RAM pricing from unbundled industrial-tier supply, with flight-critical data recorder specifications commanding substantial service-included premiums. Three-tier pricing structure across radiation-hardened, industrial-qualified, and consumer-grade levels reflects ISO 26262 certification investment recovery timelines. Cost compression in standard-grade ferroelectric RAM is intensifying because flash endurance improvements extend replacement cycles in legacy industrial controllers. Utility smart metering procurement teams in East Asia demonstrate lowest price sensitivity due to decade-long field life specifications, whereas mobile OEM buyers drive hardest unit-cost negotiations.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale data center operator demand in Germany and Japan, while distribution runs through specialized semiconductor distributors serving fragmented industrial automation accounts. Raw material sourcing draws from tellurium deposits in southwestern China, germanium refining in Yunnan Province, and hafnium oxide precursor supply anchored in South Korea and the United States. Foundry capacity for chalcogenide process nodes concentrates in Taiwan, South Korea, and the United States, creating single-source vulnerability during seismic events or export control enforcement actions. Captive foundry investments by integrated device manufacturers are displacing open-market wafer procurement for advanced spin-transfer torque RAM architectures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around multi-year supply commitment capabilities, with foundry capacity scarcity forcing fabless design houses without captive fabrication access toward acquisition or exit.
For Market Incumbents: Deploy process-material co-optimization partnerships with deposition equipment vendors to lock in chamber-qualified recipes before competitors qualify alternative precursors. Secure backward integration into hafnium oxide filament engineering to defend against emerging CMOS-compatible monolithic integration threats from resistive RAM specialists. Anchor multi-source supply guarantees across Taiwan and South Korea foundry clusters to mitigate seismic disruption risk. For New Entrants and Emerging Players: Enter via EU AI Act data integrity mandate compliance for edge inference audit trail applications, where persistent memory requirements are opening embedded phase-change memory sockets in industrial automation controllers with less entrenched incumbent presence. Target utility smart metering procurement pipelines in Taiwan and Japan, where Taipower and TEPCO specifications favor resistive RAM with 10-year field life requirements and qualification cycles create sticky supplier relationships. Pursue foundry-lite IP licensing models that accelerate socket qualification without captive fabrication investment. For Investors and Strategic Acquirers: First multi-year supply commitment announcements from hyperscale data center operators are the leading indicator that architectural lock-in is crystallizing and acquisition premiums for qualified suppliers will escalate. Frame long-term viability around 5-10 year foundry partnership durability rather than technology differentiation alone. Prioritize targets with ECHA-registered precursor supply chains and closed-loop recycling partnerships with European materials processors. Monitor REACH authorization timeline acceleration for antimony compounds as the critical regulatory inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Source Foundry Partnership | Reduces seismic and trade policy disruption risk for STT-RAM wafer supply in South Korea and Taiwan. |
| ECHA Precursor Registration | Unlocks premium medical and automotive embedded sockets requiring full substance volume tracking documentation. |
| Closed-Loop Recycling Partnership | Secures tellurium and germanium supply continuity under REACH antimony compound authorization constraints. |
| Configurable IP Core Development | Accelerates socket qualification across multiple foundry processes for specification-driven hyperscale procurement. |
| ISO 26262 Certification Investment | Opens automotive gateway memory revenue streams despite 18-24 month qualification timeline extension. |
Research Methodology
SEC 10-K filings, ECHA substance registration databases, and hyperscaler capex disclosures formed the secondary backbone for capacity and investment trend validation. Primary interviews with deposition equipment process engineers, foundry procurement leads, and data center infrastructure planners combined with secondary validation to triangulate supply commitment timelines and pricing dynamics. Bottom-up wafer start projections and top-down memory market sizing converged through cross-reference against customs data for chalcogenide precursor trade flows.
Historical trendline analysis of foundry utilization rates and precursor spot price volatility informed the projection framework across the analysis window. Segmentation dimensions modeled include memory architecture type, technology platform, application durability tier, and end-user procurement consolidation level. CAGRs were derived through slope analysis of technology adoption curves and foundry capacity expansion announcements. Forecast inputs incorporated REACH authorization pipeline status and METI dual carbon goal implementation pace for Japanese fab energy sourcing.
Forecast precision tightens around the base case; tail outcomes carry wider variance under export control escalation or tellurium supply disruption scenarios. Periodic stress-testing of base assumptions is recommended, particularly regarding chalcogenide precursor cost volatility and automotive certification timeline compression possibilities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Memory Chips
Graphics DDR SDRAM Market
Memory Chips
In-Memory Grid Market
Memory Chips
Next Generation Memory Market
Memory Chips
Contactless Memory Market
Memory Chips
Memory Market
Memory Chips
Japan Semiconductor Memory Market
Memory Chips
Americas Dynamic Random Access Memory (DRAM) Market
Memory Chips
In-Memory Computing Market
Memory Chips
DRAM Market
Memory Chips
Memory Chip Market
Memory Chips
Magnetoresistive Random Access Memory (MRAM) Market
Memory Chips
New RAM Market
Memory Chips
Memristor Market
Memory Chips
Global Dynamic Random Access Memory (DRAM) Market
Memory Chips
MRAM Market
Memory Chips
Static Random-Access Memory (SRAM) Market