
 External Storage Market | 2026-2036
External Storage Market Size, Share, and Industry Trends Forecast 2026-2036
External Storage Market Analysis
GDPR Article 17 data portability and erasure requirements is realigning enterprise procurement toward certified external storage with native encryption and audit logging. Dell Technologies leverages its integrated supply chain to sustain dominance in enterprise SAN deployments across European data centers. Pure Storage differentiates through all-flash architectures that occupy the high-performance tier for AI training workloads. Kingston Technology anchors the aftermarket with memory-module expertise that extends into portable SSD channels.
External storage comprises electromechanical and solid-state devices engineered for data persistence outside host systems, typically featuring rotational speeds of 5400-15000 RPM for HDDs or NAND flash cell architectures with 3D stacking beyond 200 layers for SSDs, designed to provide redundant, transportable, or network-accessible capacity expansion. USB and Thunderbolt connectivity technologies lead the consumer and creative professional segments due to plug-and-play interoperability and bandwidth scaling to 40 Gbps. Enterprise and government end users concentrate demand for NAS and high-capacity HDD configurations where total cost of ownership and sequential read performance govern procurement criteria.
The U.S. SEC cybersecurity disclosure rules and HIPAA technical safeguards mandate encrypted external media for financial and healthcare records, elevating compliance-grade product specifications. Japan's METI energy-efficiency labeling and the EU F-Gas Regulation constrain cooling-intensive data center expansions, indirectly channeling investment toward denser, lower-wattage external storage form factors. Stakeholders must weigh regional certification divergence against platform standardization bets as sovereign data residency requirements proliferate.
Market Dynamics
Enterprise data sovereignty mandates and hyperscale cloud procurement cycles are compressing external storage refresh timelines, forcing vendors to align product roadmaps with regional certification requirements rather than pure performance metrics.
Growth Catalysts
- EU AI Act retention mandates:Archive compliance deadlines are accelerating replacement of legacy tape systems with encrypted, auditable storage arrays across German and French data centers.
- Financial services latency requirements:Real-time trading platforms in Singapore and New York are pulling all-flash configurations into standard procurement specifications.
- NAND flash layer stacking:200+ layer 3D architectures are collapsing cost-per-gigabyte differentials between SSD and high-RPM HDD tiers.
Market Restraints
- Rare earth supply concentration:Neodymium and dysprosium processing bottlenecks in Chinese refining operations are constraining HDD actuator motor output.
- F-Gas cooling constraints:EU regulations on fluorinated greenhouse gases are limiting data center expansion in Amsterdam and Frankfurt, capping attached storage deployment.
- QLC endurance ceilings:Quad-level cell NAND write amplification limits are blocking adoption for write-heavy analytics workloads.
Strategic Opportunities
- India data localization:RBI and CERT-In mandates are creating captive demand for domestic assembly of NAS and SAN systems.
- Edge AI inference nodes:Distributed training architectures are pulling high-capacity portable SSDs into manufacturing floor deployments.
- Japan METI efficiency labeling:Tier-1 ratings are becoming procurement gatekeepers for hyperscale operators, rewarding denser form factors.
Industry Challenges
- Firmware security certification:Common Criteria EAL4+ timelines are extending 8-14 months, delaying product launches for government segments.
- Legacy SAN protocol integration:Fibre Channel over Ethernet migration is forcing parallel qualification tracks that fragment engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | External Storage Market |
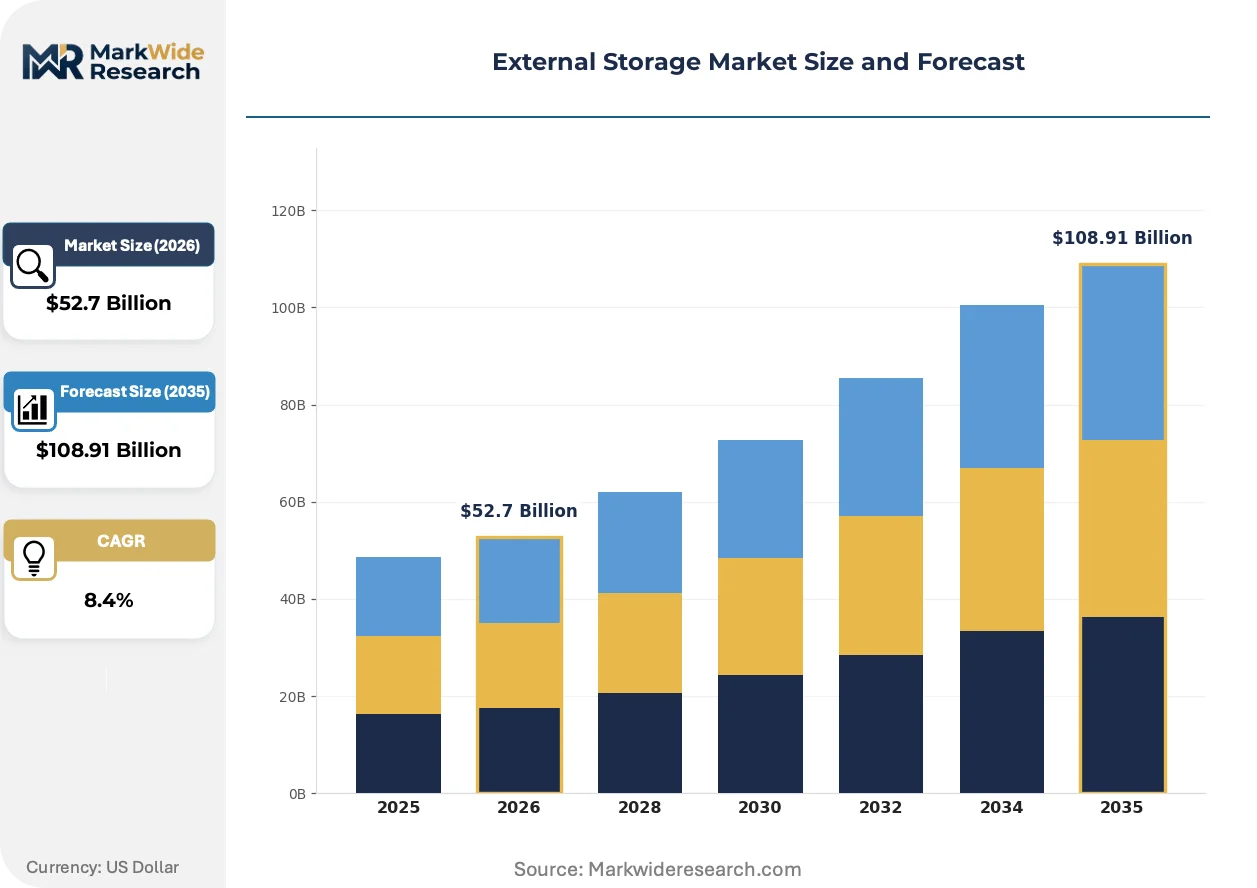
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $108.91 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HDD, SSD, Flash Drive, NAS Technology: USB, Thunderbolt, eSATA, Wi-Fi End User: Consumer, SMB, Enterprise, Government Capacity: 1TB, 2TB, 4TB, 8TB |
| Companies Covered | Dell Technologies Inc., NetApp Inc., Samsung Electronics Co. Ltd., Kingston Technology Company Inc., Pure Storage Inc., Western Digital Corporation, Hewlett Packard Enterprise Development LP, Synology Inc., Seagate Technology LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
External Storage Market Emerging Trajectories
Storage intelligence is migrating from host controllers into drive-native processing, compressing the traditional hierarchy between raw media and system-level management software.
Computational storage drives with embedded ARM processing cores are automating data reduction, encryption, and indexing tasks that previously consumed host CPU cycles. Hyperscale operators in Oregon and Virginia are qualifying these devices for video analytics pipelines. The shift is automating tiering decisions that once required separate software licenses and dedicated hardware appliances.
CSRD sustainability disclosure requirements are forcing storage vendors to publish full lifecycle carbon footprints, from wafer fabrication through end-of-life recycling. Enterprise procurement teams in Denmark and Sweden are embedding these metrics into RFP scoring rubrics. High-density SSD configurations are capturing preference over HDD arrays in Copenhagen and Stockholm due to watt-per-terabyte advantages.
Consumption-based financing is displacing capital purchase models for mid-market enterprises, with channel partners in Texas and Illinois offering storage-as-a-service bundles that wrap hardware, maintenance, and cloud egress into single contracts. Healthcare systems in Florida are accelerating adoption of these structures to align storage spending with patient volume fluctuations. The model is compressing traditional three-year depreciation cycles into monthly operational expenditures.
External Storage Market Segmentation
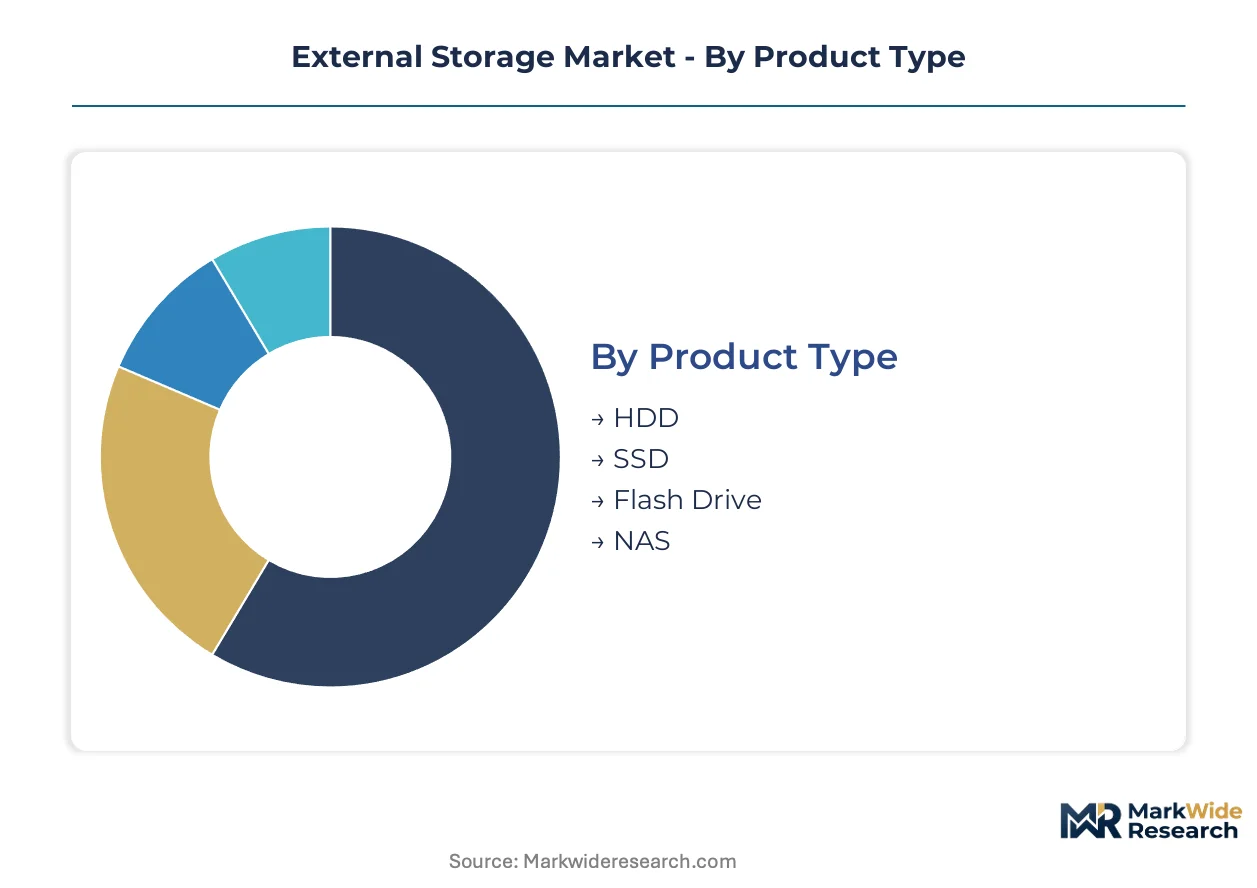
External storage procurement diverges sharply across technical specifications, connectivity standards, and organizational scale. Each segmentation axis reveals distinct compliance burdens, performance thresholds, and total cost of ownership calculations that reshape vendor positioning.
Product Type:
Rotational and solid-state architectures occupy fundamentally different positions on the performance-durability-cost matrix.
- HDD:Electromechanical platters spinning at 5400-15000 RPM deliver cost-efficient sequential read performance. Hyperscale operators in Virginia and Oregon anchor procurement for cold archive tiers where petabyte-scale economics dominate.
- SSD:NAND flash cells with 200+ layer 3D stacking achieve sub-millisecond latency. Financial services clusters in Singapore and New York mandate all-flash configurations for real-time risk analytics.
- Flash Drive:Compact USB form factors serve field technicians and mobile creative professionals. Healthcare systems in Florida deploy encrypted units for patient record transport.
- NAS:Network-attached enclosures consolidate multi-user access with RAID redundancy. SMB clusters in Texas standardize on these for distributed office synchronization.
Mature deployment sits with HDD. Newer deployment is concentrated in SSD.
Technology:
Interface selection governs bandwidth ceilings, cable complexity, and cross-platform interoperability.
- USB:Universal Serial Bus dominates consumer channels with plug-and-play simplicity. Retail procurement across Germany and Japan prioritizes backward compatibility with legacy host systems.
- Thunderbolt:Intel's 40 Gbps interconnect captures creative professional workflows. Video production houses in California and New York require daisy-chain topologies for multi-device editing suites.
- eSATA:External Serial ATA bridges internal drive performance with enclosure flexibility. Industrial automation deployments in Michigan retain this for legacy controller compatibility.
- Wi-Fi:Wireless access enables untethered media streaming and backup. Smart home installations in South Korea integrate these for residential content distribution.
Volume procurement clusters on USB. Premium positioning is expanding fastest through Thunderbolt.
End User:
Organizational scale dictates encryption mandates, support contracts, and refresh cadences.
- Consumer:Individual purchasers prioritize price-per-terabyte and retail availability. Back-to-school cycles in the United States drive seasonal demand spikes for portable units.
- SMB:Small and medium businesses balance limited IT staff against growth requirements. Professional services firms in Illinois adopt NAS for client file collaboration.
- Enterprise:Fortune 500 procurement teams enforce Common Criteria EAL4+ certification. EU AI Act retention mandates are accelerating German data center refreshes.
- Government:Federal and state agencies require FIPS 140-2 validated encryption. Defense contractors in Maryland face 8-14 month firmware approval timelines.
Standardized procurement dominates consumer channels. Complex compliance requirements concentrate in government.
Capacity:
Density tiers map directly to use-case endurance, physical form factor, and price positioning.
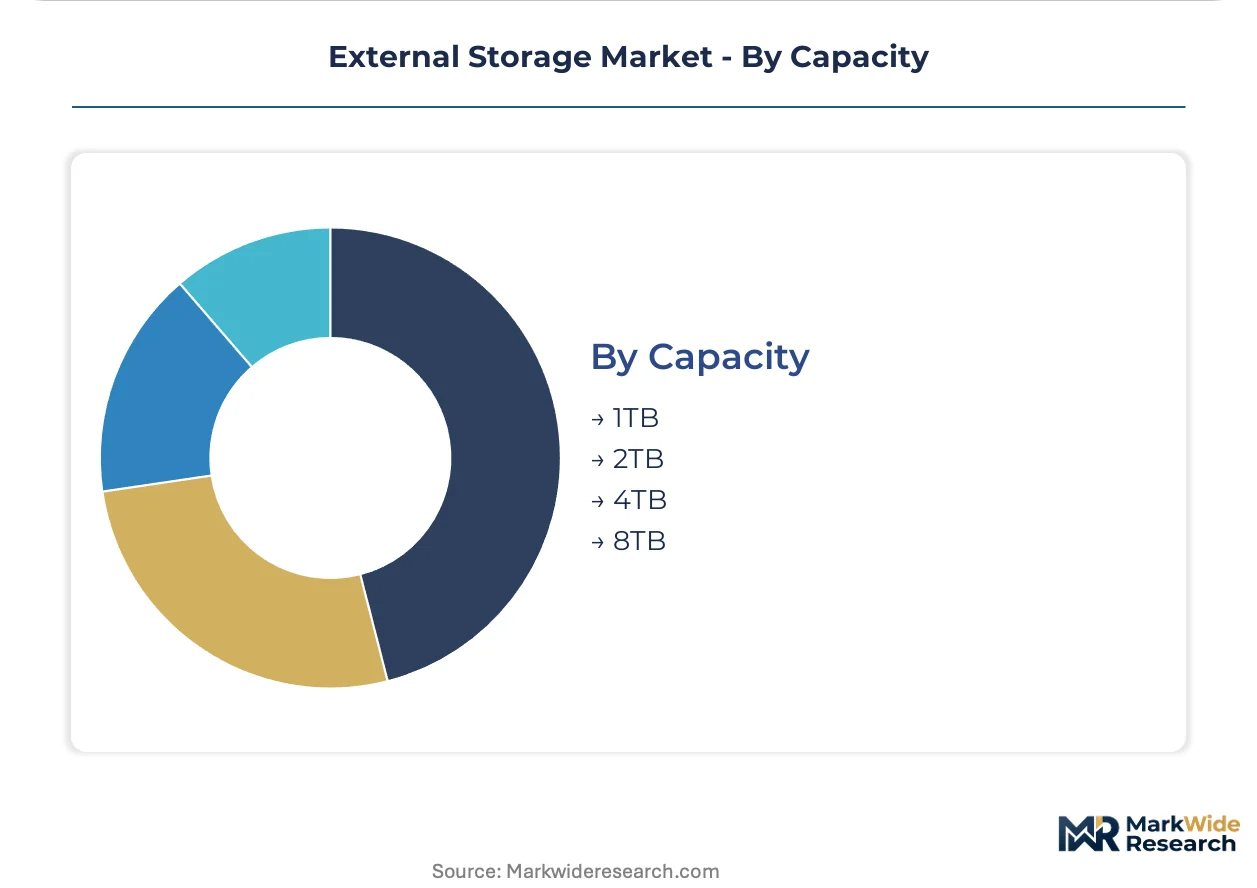
- 1TB:Entry-level density serves document archives and light media collections. Student and remote worker segments in India drive replacement cycles.
- 2TB:Mid-range capacity balances portability with photo and video libraries. Freelance photographers in France standardize on this tier.
- 4TB:Professional-grade density accommodates 4K video projects and database snapshots. Post-production studios in the United Kingdom deploy these for dailies storage.
- 8TB:Maximum portable density targets surveillance footage and raw sensor data. Autonomous vehicle testing programs in Arizona ingest terabytes daily.
Mainstream adoption clusters at 2TB. Steepest expansion trajectory is appearing at 8TB.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data center tax incentives in Singapore and Virginia are concentrating hyperscale procurement decisions. Sovereign data residency requirements are fragmenting regional deployment patterns. Energy-efficiency regulations are reshaping facility location calculus across major markets.
United States
Hyperscale operators in Virginia and Oregon anchor volume demand for high-capacity HDD arrays. SEC cybersecurity disclosure rules mandate encrypted external media for financial records. Defense contractors in Maryland face extended firmware certification timelines for government segments.
Germany
EU AI Act retention mandates are accelerating replacement of legacy tape systems in Frankfurt and Munich data centers. F-Gas Regulation constraints are limiting cooling-intensive facility expansions. Industrial automation clusters in Baden-Württemberg sustain demand for legacy-compatible storage protocols.
Japan
METI energy-efficiency labeling is becoming a procurement gatekeeper for hyperscale operators. Tier-1 ratings reward denser SSD form factors in Tokyo and Osaka facilities. NAND flash layer stacking advances are collapsing cost differentials with high-RPM HDD tiers.
India
RBI and CERT-In data localization mandates are creating captive demand for domestic NAS and SAN assembly. Professional services firms in Maharashtra and Karnataka are standardizing on network-attached enclosures for distributed office synchronization. Student and remote worker segments are driving replacement cycles at entry-level capacity tiers.
Singapore
Real-time trading platforms are pulling all-flash configurations into standard procurement specifications. Data center tax incentives are concentrating financial services infrastructure investment. Video production houses require Thunderbolt daisy-chain topologies for multi-device editing suites.
External Storage Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across product tiers. The vendor base spans electromechanical manufacturers, NAND flash fabricators, and network-attached system integrators. Three archetypes dominate: integrated IT infrastructure suppliers, dedicated storage technology developers, and memory-module specialists extending into portable channels. Competitive moves center on supply chain integration for rare earth components and firmware security certification acceleration.
Within the integrated infrastructure tier, Dell Technologies Inc. and Hewlett Packard Enterprise Development LP occupy positions spanning enterprise SAN through hyperconverged platforms. Pure Storage Inc. exemplifies the all-flash specialist archetype. Kingston Technology Company Inc. anchors the aftermarket memory-to-portable extension strategy. Samsung Electronics Co. Ltd. represents the vertical NAND fabrication-to-branded device pipeline.
| Leading Market Players |
|---|
| Dell Technologies Inc. |
| NetApp Inc. |
| Samsung Electronics Co. Ltd. |
| Kingston Technology Company Inc. |
| Pure Storage Inc. |
| Western Digital Corporation |
| Hewlett Packard Enterprise Development LP |
| Synology Inc. |
| Seagate Technology LLC |
| Others |
Supply Flow & Price Mechanics
Captive NAND fabrication anchors pricing power for integrated flash manufacturers while constraining margin flexibility for assembly-dependent vendors. Backward integration into controller silicon and firmware development separates premium-tier suppliers from commodity enclosure assemblers in Germany and Japan procurement channels.
Pricing Analysis
Short lead-time premiums command pricing advantages for FIPS 140-2 validated inventory held in Virginia and Maryland defense corridors. Three-tier pricing structure across certified government, enterprise SLA, and economy consumer levels stratifies by encryption grade and audit-log capability. Cost compression in high-capacity HDD tiers intensifies as hyperscale operators consolidate procurement volumes across Oregon and Virginia facilities. Government segments exhibit least price sensitivity due to Common Criteria certification requirements, while student and remote worker segments in India drive entry-tier discounting.
Supply Chain Analysis
Neodymium and dysprosium refining rests on Chinese processing operations that constrain HDD actuator motor output globally. NAND wafer fabrication concentrates in South Korea, Japan, and Taiwan, with controller silicon sourcing from Taiwanese and American semiconductor houses. Single-source vulnerability in rare earth magnet supply threatens production continuity for electromechanical storage architectures. Distribution runs through direct hyperscale contracts for enterprise volumes and retail channel partners for consumer portable segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into NAND fabrication and controller silicon anchors competitive positioning as raw material concentration intensifies. Players securing captive wafer supply gain procurement leverage against spot-market-dependent assemblers.
For Market Incumbents: To counter QLC endurance limitations blocking write-heavy analytics adoption, accelerate 200+ layer 3D NAND roadmaps and deepen backward integration into rare earth magnet recycling. Certification investment in Common Criteria EAL4+ acceleration compresses government segment approval timelines against emerging all-flash specialists. For New Entrants and Emerging Players: Enter via India data localization mandates requiring domestic NAS and SAN assembly for RBI and CERT-In compliance. Target captive demand from professional services firms in Maharashtra and Karnataka seeking distributed office synchronization. Go-to-market leverage rests on local assembly partnerships with established channel networks. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated infrastructure conglomerates seeking all-flash capability augmentation. Long-term viability favors vendors with captive NAND supply and firmware security certification pipelines. Watch for EU AI Act retention mandate acceleration as inflection indicator for archive system replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Controller Silicon Integration | Captive ARM core development reduces host CPU dependency for computational storage in Oregon hyperscale pipelines. |
| Firmware Security Certification | Common Criteria EAL4+ acceleration opens German and French government procurement channels closed to uncertified competitors. |
| Rare Earth Magnet Recycling | Closed-loop neodymium recovery hedges Chinese refining concentration for HDD actuator motor supply continuity. |
| Consumption-Based Financing | Storage-as-a-service bundles align Florida healthcare system spending with patient volume fluctuations. |
| Domestic Assembly Partnerships | India local content requirements create captive manufacturing footprint for RBI-mandated data localization compliance. |
Methodological Framework
Document review covered SEC 10-K filings, hyperscaler capex disclosures, and EU regulatory filings, complemented by interviews with enterprise storage procurement directors, channel sales managers, and firmware security certification consultants. Secondary validation drew from customs trade data, data center development databases, and NAND flash supply chain reports. Bottom-up demand modeling across product tiers and top-down macroeconomic triangulation anchored volume estimates.
Cross-referencing historical shipment patterns against panel input from procurement officers at Fortune 500 financial services and healthcare systems calibrated trajectory assumptions across the analysis window. Segmentation dimensions modeled include product architecture, interface technology, organizational scale, capacity tier, and regional regulatory cluster. CAGRs derived from fitted growth curves incorporating EU AI Act compliance deadlines and METI efficiency labeling adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under rare earth export restriction scenarios and F-Gas Regulation enforcement intensity variations. Forecasts reflect documented assumptions regarding hyperscale refresh cadences and sovereign data residency proliferation. A small set of triggers—NAND layer stacking cost crossover points, firmware certification timeline compression, and India domestic assembly incentive structures—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
Flash-Based Array Market
Data Storage
Transparent Caching Market
Data Storage
South Korea Data Center Storage Market
Data Storage
All Flash Storage Market
Data Storage
Enterprise Flash Storage Market
Data Storage
Asia Pacific Transparent Caching Market
Data Storage
Serial (SPI) NOR Flash Market
Data Storage
HDD Head Assembly Market
Data Storage
Data Storage Market
Data Storage
Taiwan Data Center Storage Market
Data Storage
AI Powered Storage Market
Data Storage
China Solid-State Drive Market
Data Storage
Americas Flash Memory Market
Data Storage
Object-Based Storage Market
Data Storage
OTG Pen Drive Market
Data Storage
Middle East and Africa AMH and Storage Systems Market