
 Serial (SPI) NOR Flash Market | 2026-2036
Serial (SPI) NOR Flash Market Size, Share, and Industry Trends Forecast 2026-2036
Serial (SPI) NOR Flash Market Analytics
East Asian foundry capacity is rebalancing toward automotive-grade SPI NOR Flash as consumer electronics demand plateaus. Winbond Electronics Corporation anchors its position through captive 300mm wafer supply and deep specialization in low-pin-count packages. Infineon Technologies AG leverages its automotive certification heritage to dominate safety-critical ECU sockets. GigaDevice Semiconductor competes aggressively on cost in the industrial automation segment while expanding its Quad-IO portfolio.
Serial Peripheral Interface NOR Flash comprises non-volatile memory devices communicating through a synchronous serial bus with clock speeds reaching 200 MHz in Octal-IO configurations, storing boot code and firmware in embedded systems requiring fast random access and execute-in-place capability. Quad-IO NOR commands premium positioning due to throughput demands from automotive instrument clusters and telematics units. Standard NOR persists in cost-sensitive consumer electronics where read latency tolerance allows simpler controller architectures. The above 16 MB capacity tier captures disproportionate margin pools as industrial IoT gateways and 5G base stations require larger firmware footprints.
FCC equipment authorization rules govern wireless-enabled SPI NOR deployments in US consumer electronics, while EU REACH and RoHS restrictions constrain substrate and packaging material selections for European automotive suppliers. China's GB/T standards for automotive semiconductor reliability, enforced by MIIT, create compliance barriers for non-domestic suppliers. Stakeholders must monitor evolving automotive functional safety requirements and regional content mandates to align capacity investments with qualified demand pools.
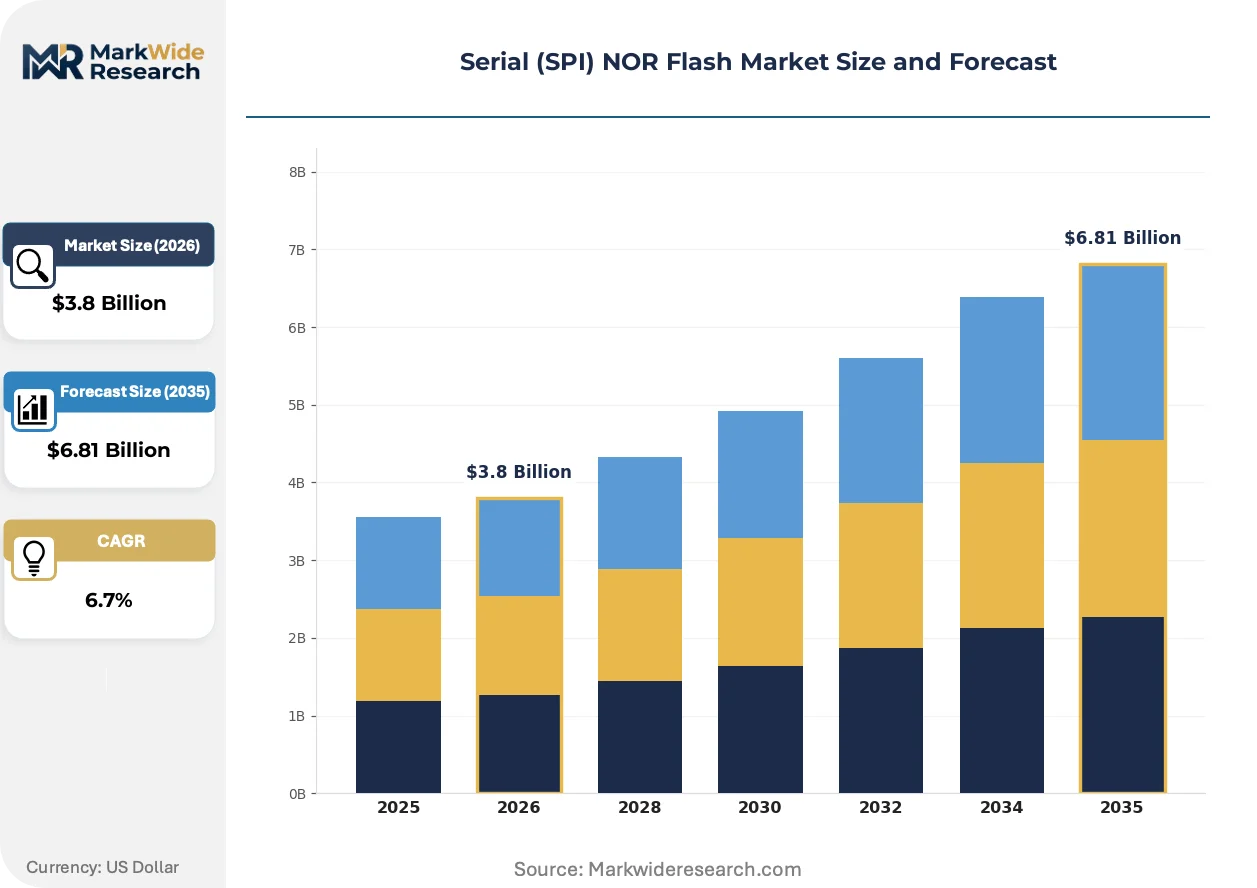
Market Dynamics
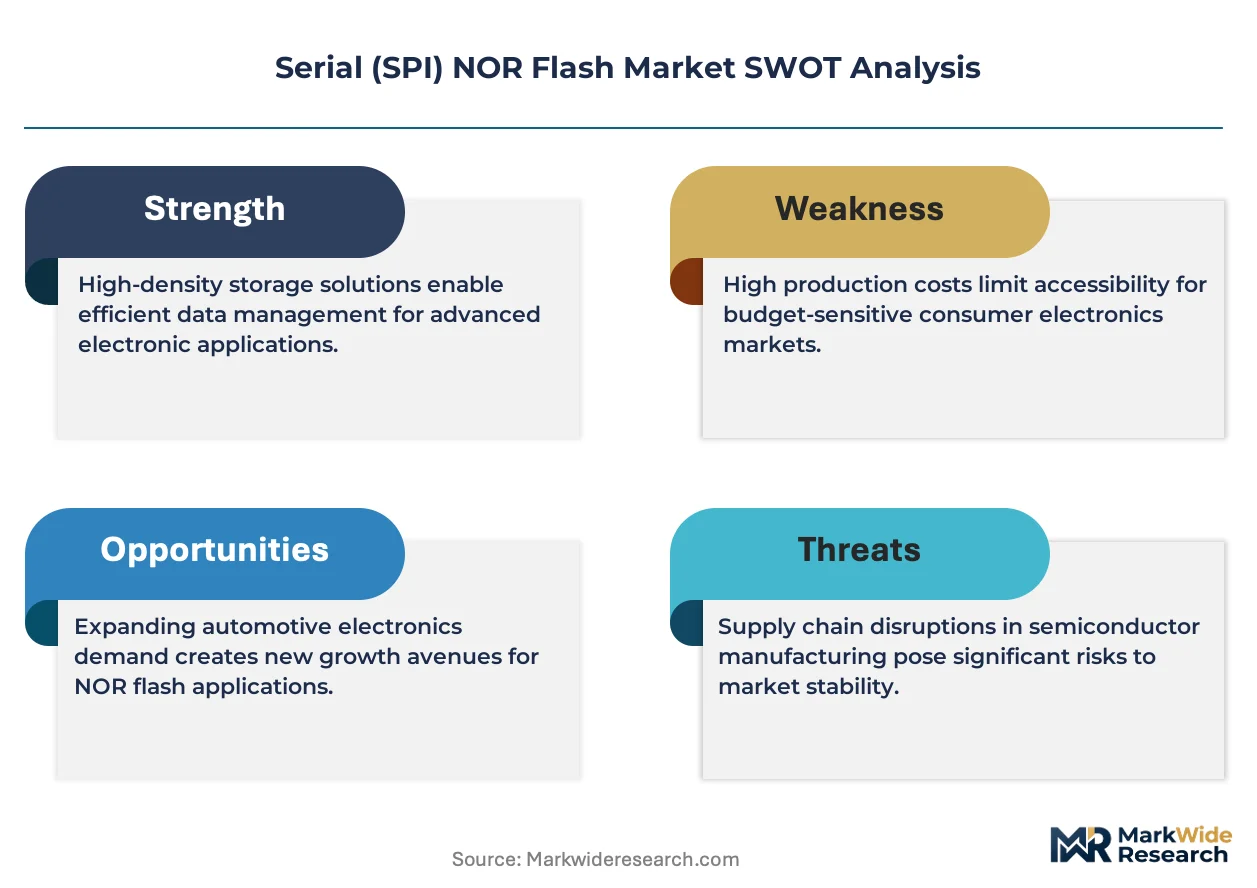
Automotive functional safety mandates and MIIT localization requirements are forcing memory suppliers to requalify production lines for AEC-Q100 Grade 1 compliance while shifting wafer procurement toward China-qualified sources.
Growth Catalysts
- ADAS Module Deployment:Camera fusion and radar processing units in passenger vehicles require execute-in-place firmware storage with deterministic read latency, pulling high-reliability SPI NOR into safety-critical ECU sockets.
- MIIT Localization Mandates:China's Ministry of Industry and Information Technology procurement rules for state-connected automotive OEMs prioritize domestic-qualified memory suppliers, redirecting foundry capacity toward GB/T-compliant production.
- Octal-IO Interface Adoption:200 MHz clock speeds with eight parallel data lines enable direct code execution from external flash without SRAM shadowing, collapsing system cost for industrial IoT gateways.
Market Restraints
- 300mm Wafer Supply Concentration:Captive fab strategies at Winbond and Macronix limit merchant market availability, constraining second-source options for automotive Tier 1s.
- NAND Flash Price Compression:SLC NAND at comparable densities threatens SPI NOR socket share in consumer electronics where execute-in-place requirements are relaxed.
- EU REACH Substrate Restrictions:Halogen-free molding compound mandates constrain package material sourcing for European automotive suppliers, extending qualification timelines.
Strategic Opportunities
- India Industrial Automation:PLI scheme incentives for electronics manufacturing are attracting control board assembly, creating demand for wide-temperature-grade SPI NOR in factory automation.
- 5G Base Station Firmware:Massive MIMO radio units require 32 MB+ boot storage with field upgrade capability, opening premium density tiers previously dominated by parallel NOR.
- Edge AI Inference Modules:Convergence of SPI NOR with deterministic memory access patterns enables weight storage in microcontroller-based neural accelerators without DRAM.
Industry Challenges
- AEC-Q100 Grade 1 Qualification:150°C ambient operation testing requires 6-12 month validation cycles, freezing product roadmaps during automotive design wins.
- Legacy SPI Controller Integration:Industrial control systems running decade-old MCU architectures lack Quad-IO command support, forcing suppliers to maintain dual-interface product variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Serial (SPI) NOR Flash Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard NOR, Dual-IO NOR, Quad-IO NOR, Octal-IO NOR End User: Consumer Electronics, Automotive Systems, Industrial Automation, Telecommunications Capacity: Below 1 MB, 1-4 MB, 4-16 MB, Above 16 MB Form Factor: WLCSP, TSOP, BGA, DIP |
| Companies Covered | Infineon Technologies AG, Microchip Technology Incorporated, Winbond Electronics Corporation, Renesas Electronics Corporation, Integrated Silicon Solution Inc., GigaDevice Semiconductor, Micron Technology Inc., Adesto Technologies LLC, Macronix International Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Serial (SPI) NOR Flash Market Evolving Landscape
Memory architectures are fragmenting across performance tiers as automotive safety requirements diverge from consumer cost optimization, while interface standards consolidate around serial protocols.
Octal-IO SPI NOR is rewriting execution performance expectations in automotive instrument clusters. The 8-bit parallel data path eliminates instruction fetch bottlenecks for graphics-rich HMI firmware. European OEMs at BMW and Volkswagen Group are specifying Octal configurations for their next-generation domain controllers, compressing the performance gap with parallel NOR at one-third the pin count.
China's GB/T 28046 automotive semiconductor reliability standards, enforced through MIIT certification, are reshaping supplier qualification workflows. The thermal cycling and humidity bias requirements exceed traditional JEDEC specifications, forcing foreign memory vendors to establish China-based test facilities. Korean and Taiwanese suppliers are responding by partnering with domestic packaging houses to secure GB/T compliance marks.
Long-term service agreements are displacing spot purchasing in automotive memory procurement. Tier 1 suppliers at Bosch and Continental are locking 5-7 year supply contracts with fixed pricing escalators, replacing quarterly price negotiations. This shift is most pronounced in Germany and Japan, where just-in-sequence manufacturing demands inventory liability transfer to memory vendors.
Serial (SPI) NOR Flash Market Segmentation
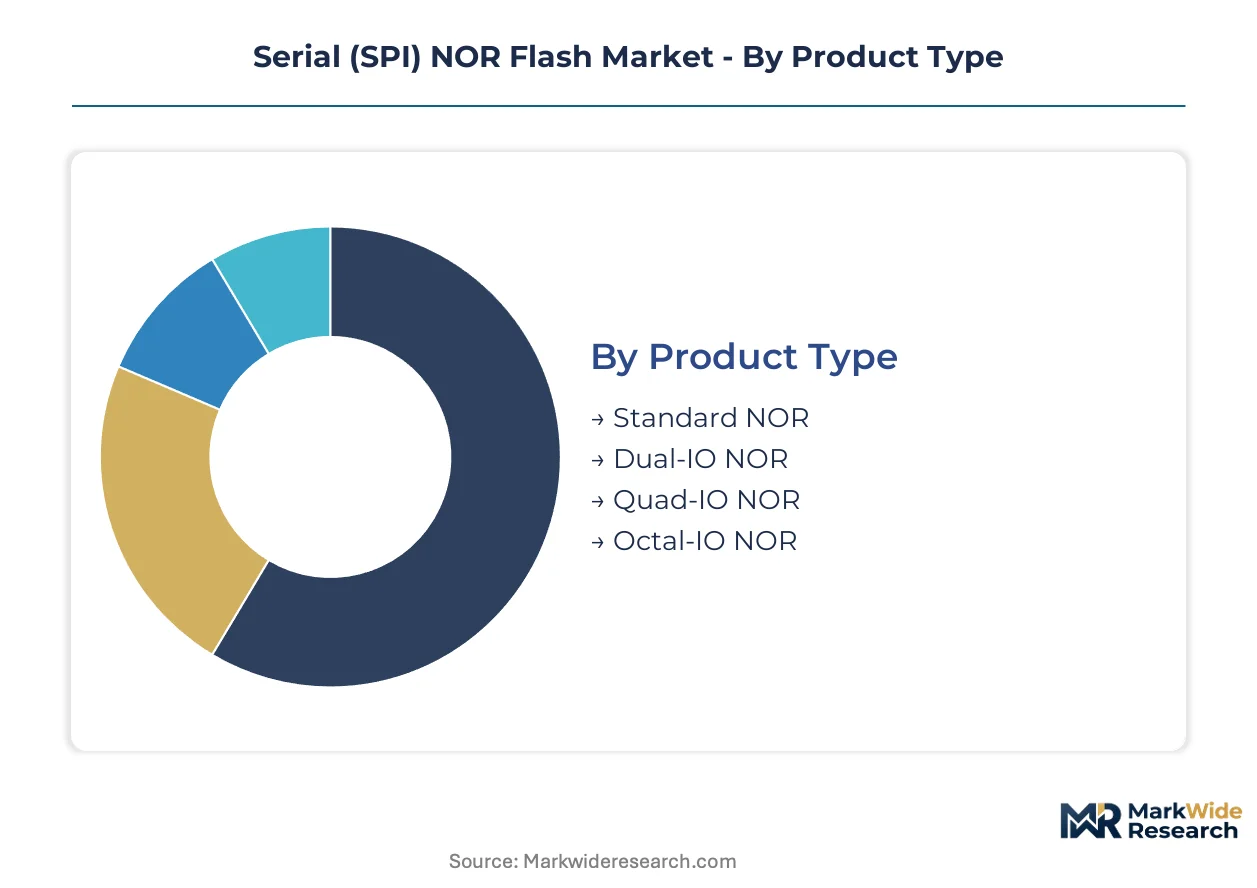
SPI NOR Flash vendors architect product portfolios around interface performance tiers and reliability grades rather than raw density. Procurement patterns diverge sharply between cost-optimized consumer sockets and safety-certified automotive modules, forcing parallel qualification tracks.
Product Type:
Interface architectures differentiate execution throughput and pin efficiency across embedded system designs.
- Octal-IO NOR:Eight parallel data lines deliver 200 MHz transfer rates for direct code execution without SRAM shadowing. BMW and Volkswagen Group domain controllers specify Octal configurations for graphics-intensive HMI firmware, collapsing the performance gap with parallel NOR at reduced pin count.
- Quad-IO NOR:Four-bit data paths command premium positioning in automotive instrument clusters and telematics units where throughput demands justify controller complexity. Camera fusion and radar processing units in passenger vehicles pull Quad-IO into safety-critical ECU sockets.
- Dual-IO NOR:Two-bit interfaces serve mid-tier industrial control boards requiring balanced cost-performance tradeoffs. Factory automation PLCs in India leverage Dual-IO for firmware storage under PLI scheme incentives.
- Standard NOR:Single-bit serial interfaces persist in cost-sensitive consumer electronics where read latency tolerance permits simpler controller architectures. Legacy MCU architectures in decade-old industrial systems lack Quad-IO command support, maintaining Standard NOR demand.
Mature deployment sits with Standard NOR. Newer deployment is concentrated in Octal-IO configurations.
End User:
Application requirements fragment across reliability grades, temperature ranges, and functional safety mandates.
- Automotive Systems:AEC-Q100 Grade 1 compliance mandates 150°C ambient operation testing with 6-12 month validation cycles. Bosch and Continental lock 5-7 year supply contracts with fixed pricing escalators for safety-critical memory sockets.
- Industrial Automation:Wide-temperature-grade requirements dominate factory control board specifications. India's PLI scheme incentives attract control board assembly, creating demand for -40°C to +105°C qualified SPI NOR.
- Telecommunications:Massive MIMO radio units require 32 MB+ boot storage with field upgrade capability. 5G base station firmware opens premium density tiers previously dominated by parallel NOR.
- Consumer Electronics:Cost optimization drives SLC NAND substitution threats where execute-in-place requirements relax. FCC equipment authorization rules govern wireless-enabled deployments in US consumer devices.
Procurement concentration sits with Automotive Systems. Volume expansion is climbing fastest in Industrial Automation.
Capacity:
Firmware footprint growth in connected infrastructure reshapes density mix toward higher tiers.
- Above 16 MB:Industrial IoT gateways and 5G base stations require larger firmware footprints with over-the-air update reserves. Edge AI inference modules store neural network weights in microcontroller-based accelerators without external DRAM.
- 4-16 MB:Automotive instrument clusters and domain controllers accommodate graphics-rich HMI code bases. GB/T 28046 thermal cycling requirements exceed traditional JEDEC specifications for this density tier.
- 1-4 MB:Mid-range industrial PLCs and telecommunications equipment balance code size against cost constraints. MIIT localization mandates redirect foundry capacity toward China-qualified sources in this segment.
- Below 1 MB:Legacy boot code storage in consumer electronics and simple sensor nodes maintains baseline demand. EU REACH halogen-free molding compound mandates constrain package material sourcing for European suppliers.
Volume concentration sits with 4-16 MB. Margin expansion is sharpest in Above 16 MB.
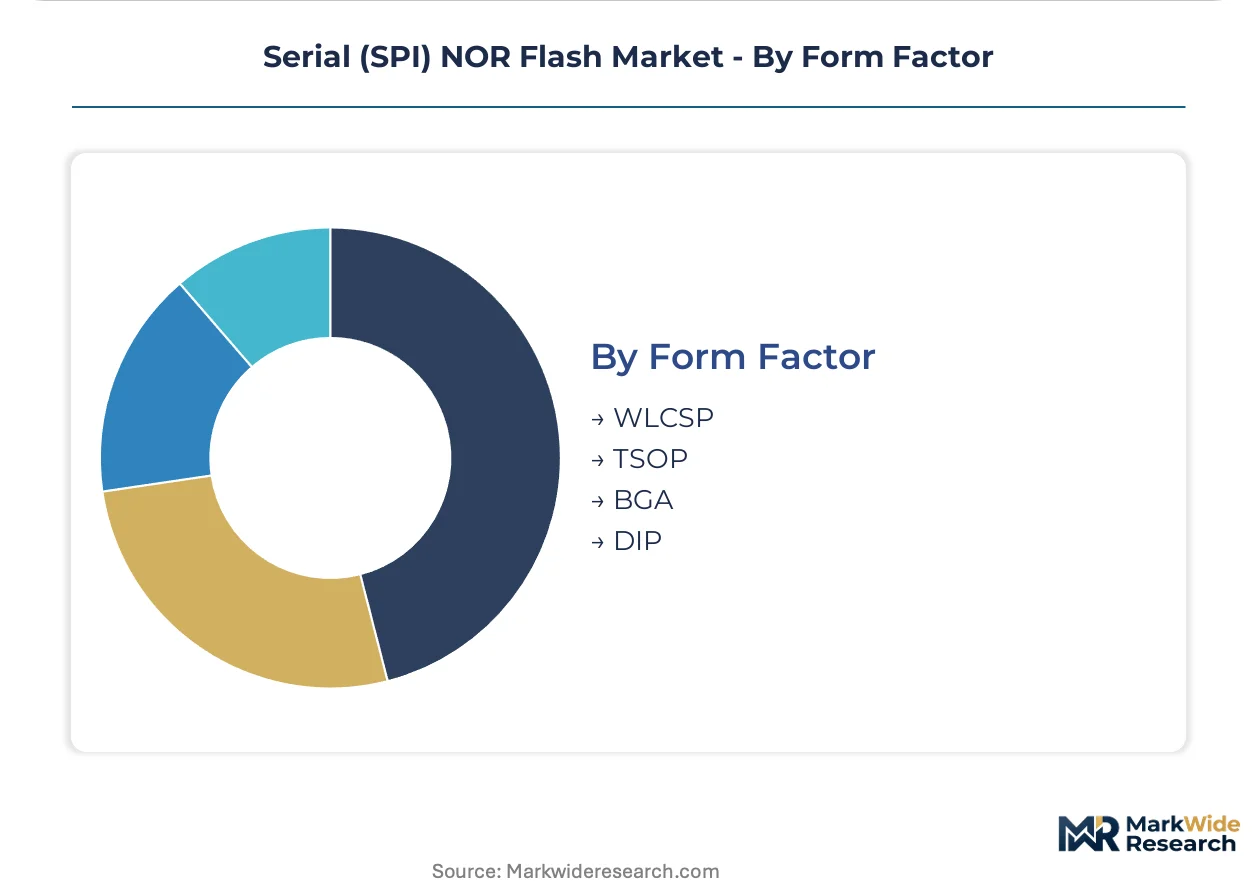
Form Factor:
Package selection trades board space, thermal performance, and second-source availability.
- WLCSP:Wafer-level chip-scale packages minimize footprint for space-constrained wearable and mobile devices. Smartphone manufacturers drive WLCSP adoption where PCB area commands premium pricing.
- BGA:Ball grid arrays deliver thermal and electrical performance for high-reliability automotive modules. AEC-Q100 qualification workflows favor BGA for safety-critical ECU deployment.
- TSOP:Thin small-outline packages maintain broad compatibility with legacy industrial equipment. Decade-old MCU architectures in factory automation rely on TSOP-mounted SPI NOR with established socket availability.
- DIP:Dual in-line packages serve prototyping, repair, and low-volume industrial applications. Hobbyist and educational markets sustain minimal DIP demand outside high-volume production.
Established volume sits with TSOP. Transition momentum is strongest toward BGA.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon wafer supply from East Asian foundry clusters anchors production geography for SPI NOR Flash, with automotive-grade capacity concentrating in Taiwan and South Korea while Chinese domestic qualification mandates reshape procurement flows.
China
MIIT localization rules prioritize GB/T 28046-certified memory for state-connected automotive OEMs, redirecting foundry output toward domestic test facilities. Wafer procurement shifts to China-qualified sources under semiconductor self-sufficiency programs. Yangtze River Delta packaging houses partner with Korean and Taiwanese suppliers to secure compliance marks for automotive socket entry.
Taiwan
Captive 300mm wafer strategies at major suppliers constrain merchant market availability for automotive Tier 1s. AEC-Q100 Grade 1 qualification workflows dominate capacity allocation toward safety-critical ECU production. Hsinchu Science Park anchors the region's concentration of high-reliability SPI NOR manufacturing for instrument cluster deployment.
South Korea
Octal-IO interface adoption accelerates through partnerships with European domain controller programs at BMW and Volkswagen Group. REACH-compliant substrate sourcing extends qualification timelines for EU-bound automotive shipments. Seoul metropolitan area foundries balance consumer electronics output with automotive certification investments.
Germany
Just-in-sequence manufacturing demands 5-7 year supply contracts with fixed pricing escalators from Bosch and Continental. Halogen-free molding compound mandates under EU REACH constrain package material sourcing for domestic automotive suppliers. Bavaria's automotive electronics corridor concentrates design-in activity for next-generation ADAS modules.
United States
FCC equipment authorization rules govern wireless-enabled SPI NOR deployments in consumer electronics, while NHTSA functional safety guidance shapes automotive memory specifications. Industrial automation demand concentrates in Midwest manufacturing zones seeking wide-temperature-grade firmware storage for control board assembly.
Serial (SPI) NOR Flash Market Competitive Landscape
Global majors compete with regional champions across automotive certification tiers, with consolidated supply-side concentration around captive fab operators and fragmented competition in merchant memory channels. Three archetypes dominate: vertically integrated wafer-to-package specialists, fabless design houses with foundry partnerships, and diversified semiconductor conglomerates with memory divisions. Capacity expansion and strategic partnerships constitute the primary competitive vectors as suppliers secure long-term automotive design wins.
Within the captive-integration tier, Winbond Electronics Corporation and Macronix International Co., Ltd. exemplify wafer-supply-controlled positioning. Among diversified technology conglomerates, Infineon Technologies AG and Renesas Electronics Corporation occupy positions shaped by automotive heritage and safety-critical system integration. GigaDevice Semiconductor represents the aggressive cost-competition archetype in industrial automation segments.
| Leading Market Players |
|---|
| Infineon Technologies AG |
| Microchip Technology Incorporated |
| Winbond Electronics Corporation |
| Renesas Electronics Corporation |
| Integrated Silicon Solution Inc. |
| GigaDevice Semiconductor |
| Micron Technology Inc. |
| Adesto Technologies LLC |
| Macronix International Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Long-term service agreements from Bosch and Continental are compressing spot-market liquidity and forcing memory vendors to absorb inventory liability through fixed-price escalators, reshaping how suppliers allocate wafer capacity between automotive and consumer tiers.
Pricing Analysis
Warranty and field-failure coverage bundling separates automotive-grade SPI NOR from merchant market transactions, with AEC-Q100 Grade 1 qualification commanding premium positioning against unqualified industrial alternatives. Three-tier pricing structure across automotive-certified, industrial-temperature, and consumer-grade levels reflects validation cycle investments and temperature range guarantees. Cost compression in the consumer tier intensifies because SLC NAND substitution threats relax execute-in-place requirements. Industrial automation buyers exhibit highest price sensitivity due to PLI scheme margin constraints, while German automotive Tier 1s lock supply contracts with minimal elasticity.
Supply Chain Analysis
GB/T 28046 certification gating redirects wafer procurement toward China-qualified test facilities, fragmenting previously consolidated qualification workflows. Taiwan, South Korea, and China anchor foundry output, with Yangtze River Delta packaging houses partnering with foreign suppliers for domestic compliance marks. Silicon wafer supply, specialty molding compounds for halogen-free mandates, and AEC-Q100 testing capacity constitute critical input dependencies. Single-source vulnerability concentrates in captive 300mm strategies at Winbond and Macronix. Distribution runs through direct long-term agreements with automotive Tier 1s rather than merchant spot channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where China's MIIT localization mandates and GB/T 28046 thermal cycling requirements erect qualification barriers that favor incumbent suppliers with established China-based test infrastructure.
For Market Incumbents: Anticipate NAND Flash price compression in consumer sockets by accelerating Octal-IO portfolio transitions toward automotive instrument cluster deployments. Secure captive wafer supply through backward integration into 300mm capacity or binding long-term foundry offtakes. Defensive consolidation around AEC-Q100 Grade 1 qualification workflows preserves socket access against emerging fabless competitors lacking automotive heritage. For New Entrants and Emerging Players: Capture India's industrial automation white space under PLI scheme incentives before established suppliers requalify wide-temperature-grade portfolios. Target 5G base station firmware storage as the most penetrable density tier above 32 MB, where parallel NOR displacement creates supplier openness. Pursue foundry partnership models with Yangtze River Delta packaging houses to secure GB/T compliance marks without captive fab investment. For Investors and Strategic Acquirers: The window for entry favors vertically integrated specialists with captive 300mm wafer supply and existing automotive certification heritage. Long-term viability hinges on 5-10 year supply contract backlogs with German and Japanese OEMs that transfer inventory liability downstream. Monitor MIIT procurement rule enforcement intensity as the inflection signal for China-qualified supplier valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| GB/T 28046 Certification Investment | China-based test facility establishment unlocks MIIT-mandated automotive procurement access. |
| Octal-IO Product Line Expansion | BMW and Volkswagen Group domain controller specifications pull 200 MHz interface adoption. |
| India Manufacturing Footprint | PLI scheme incentives attract control board assembly requiring wide-temperature-grade supply. |
| Long-term Supply Agreement Lock-in | Bosch and Continental contracts transfer inventory liability with fixed pricing escalators. |
| SLC NAND Substitution Defense | Execute-in-place performance differentiation preserves socket share in cost-sensitive tiers. |
Research Methodology
Independent corroboration across primary interviews with automotive Tier 1 procurement officers, memory vendor product marketing directors, and China packaging house operations managers underwrites the qualitative findings. Secondary validation draws from MIIT certification registry disclosures, AEC-Q100 test facility audit records, and customs wafer import data. Bottom-up triangulation across foundry capacity announcements and top-down reconciliation against OEM bill-of-materials estimates anchors volume assessments.
Comparable-period anchoring to historical automotive production cycles and consumer electronics inventory corrections shapes the projection horizon. Segmentation modeling spans interface performance tier, reliability grade, end-use application, and regional qualification status. CAGRs derive from installed base growth in ADAS modules, 5G base station deployment trajectories, and industrial automation capital expenditure patterns. Wafer supply constraints and certification timeline assumptions feed directly into capacity-constrained growth ceilings.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to MIIT enforcement intensity, REACH substrate mandate evolution, and NAND Flash cost-performance convergence. Model refresh is warranted upon material change in automotive functional safety standard revisions or China semiconductor self-sufficiency program acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
Wi-Fi SD Cards Market
Data Storage
NOR Flash Market
Data Storage
Middle East Data Center Storage Market
Data Storage
Germany Data Center Storage Market
Data Storage
North America Next Generation Storage Market
Data Storage
North America AMH and Storage Systems Market
Data Storage
Optical Disk Market
Data Storage
South Korea Data Center Storage Market
Data Storage
Next Generation Data Storage Market
Data Storage
HDD Head Assembly Market
Data Storage
Hybrid Flash Storage Market
Data Storage
Ethernet Storage Market
Data Storage
Storage and Management Market
Data Storage
NAND Flash Market
Data Storage
Europe Next Generation Storage Market
Data Storage
Universal Flash Storage Market