
 Data Storage Devices Market | 2026-2036
Data Storage Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Data Storage Devices Market Outlook
The gap between enterprise-grade NVMe arrays and consumer USB flash drives is repositioning how vendors allocate engineering resources and channel investment. Dell Technologies Inc. leverages its server-storage integration to dominate enterprise data center deployments. Seagate Technology Holdings Public Limited Company anchors the HDD segment through high-capacity nearline drives for cloud archival. Western Digital Corporation competes across both flash and disk, sustaining manufacturing scale that few rivals match.
Data storage devices are electromechanical or solid-state systems that retain digital information through magnetic recording, charge trapping in NAND cells, or phase-change memory, with capacities spanning from 1TB to 8TB and interfaces including SATA, PCIe, and Thunderbolt. Their primary commercial purpose is to enable persistent data retention for computing, analytics, and content distribution across enterprise and consumer environments. SSD and NVMe product types command the fastest expansion as latency-sensitive workloads multiply in data centers. HDD remains the margin pool for bulk archival and backup solutions where cost-per-gigabyte still dominates purchasing criteria.
FCC equipment authorization rules shape electromagnetic compatibility standards for devices sold in the United States, while the EU's RoHS and REACH frameworks restrict hazardous substances in storage hardware sold across Europe. China's GB standards and MIIT certification requirements govern product access in that market, adding compliance layers for multinational suppliers. Stakeholders must monitor how divergent data sovereignty laws across jurisdictions affect where storage infrastructure gets physically deployed.
Market Dynamics
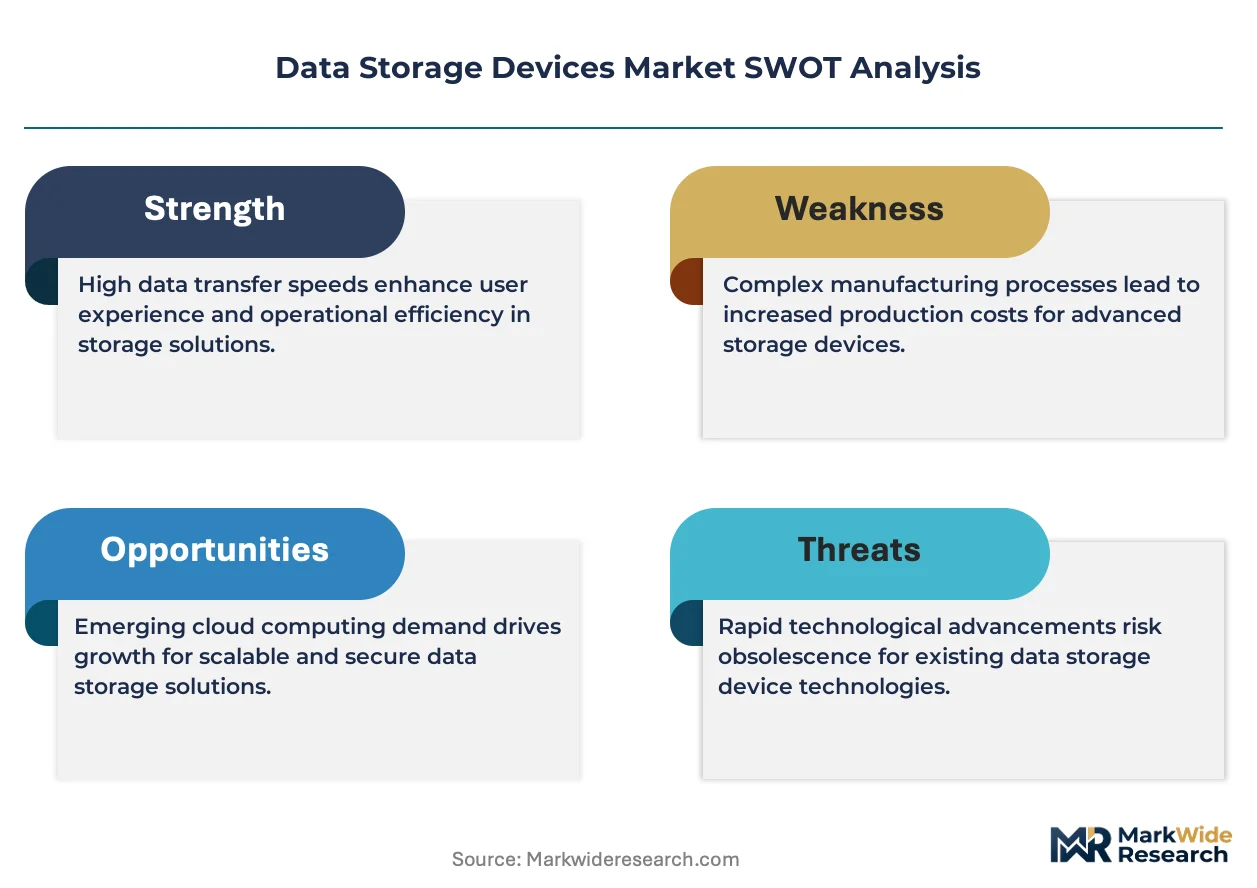
Hyperscale cloud operators are consolidating procurement power and dictating form-factor standards, compressing margins for component suppliers while accelerating the transition from SAS/SATA to NVMe interfaces across enterprise storage.
Growth Catalysts
- EU CSRD Mandate:Sustainability disclosure requirements are forcing enterprises to refresh storage infrastructure with energy-efficient solid-state systems, creating replacement demand across European data centers.
- AI Training Clusters:Machine learning workloads require low-latency petabyte-scale storage, pulling NVMe-oF deployments into financial services and autonomous vehicle development pipelines.
- Flash Foundry Scale:NAND fabrication concentration in South Korea and Taiwan has achieved cost parity with nearline HDDs for read-intensive applications below 16TB.
Market Restraints
- NAND Supply Concentration:Three manufacturers control 95% of flash wafer output, exposing buyers to allocation risk during technology node transitions.
- Chokepoint Components:Specialty controllers and enterprise DRAM caches face 26-week lead times, constraining array assembly regardless of drive availability.
- REACH Compliance Burden:ECHA substance restrictions on flame retardants and rare earth elements are disqualifying legacy HDD substrates from European public-sector tenders.
Strategic Opportunities
- India Data Center Buildout:MeitY data localization requirements are mandating in-country storage infrastructure, opening greenfield deployment opportunities for modular all-flash arrays.
- Computational Storage Convergence:Processing-in-memory architectures are merging storage and compute functions, enabling new product categories at the edge for video analytics and IoT aggregation.
- US IRA Clean Energy Credits:Domestic manufacturing incentives are subsidizing SSD assembly reshoring, reducing tariff exposure for federal procurement channels.
Industry Challenges
- Firmware Security Certification:Common Criteria and FIPS 140-3 validation timelines stretch 18-24 months, delaying product launches for government and financial verticals.
- Legacy Array Integration:Enterprise IT organizations struggle to bridge NVMe fabrics with existing Fibre Channel SAN investments without forklift upgrades.
- Specialized Talent Scarcity:Shortages of NAND flash controllers, error-correction algorithms, and thermal management engineers are constraining R&D throughput at mid-tier suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Storage Devices Market |
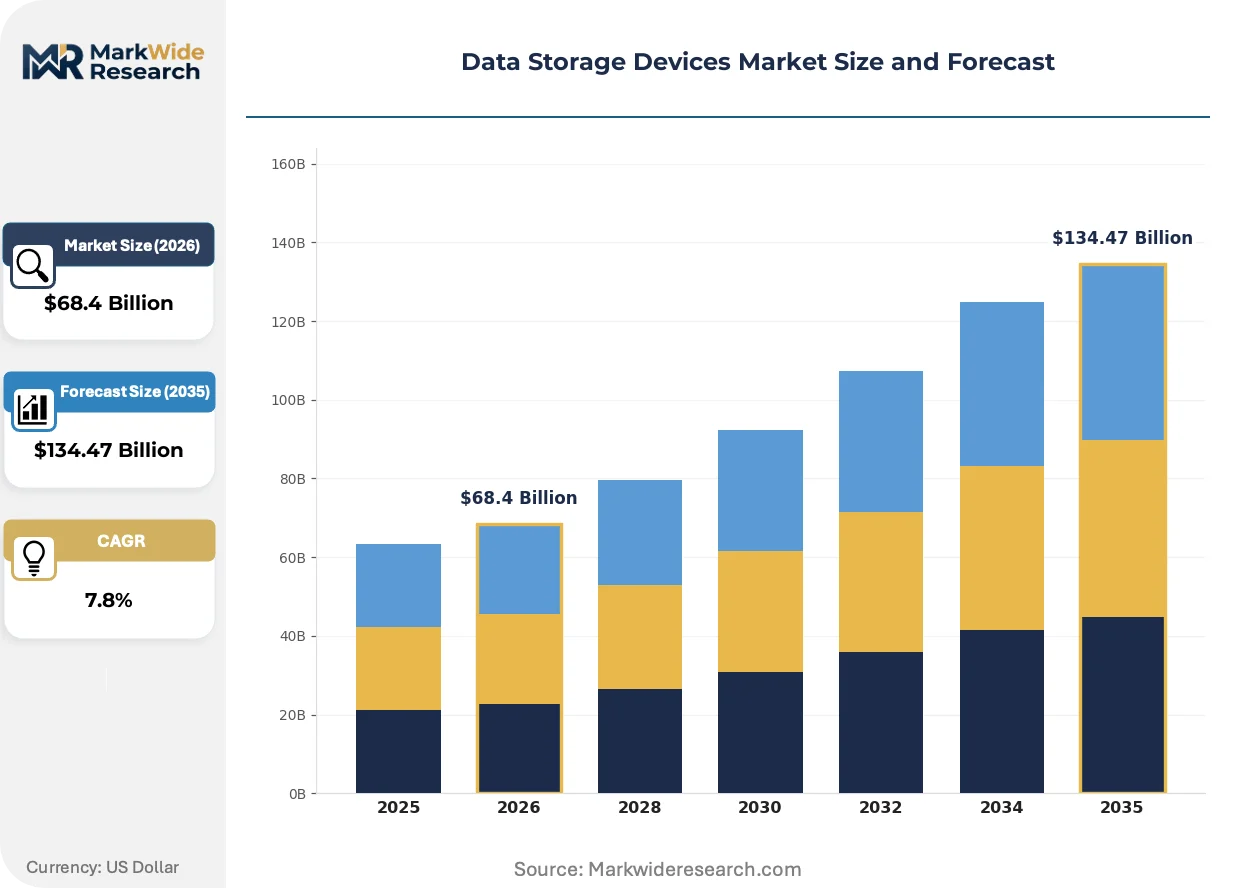
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $134.47 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HDD, SSD, NVMe, USB Flash Drive Storage Capacity: 1TB, 2TB, 4TB, 8TB Interface Type: SATA, SCSI, PCIe, Thunderbolt Usage Scenario: Data Centers, Personal Computing, Gaming, Backup Solutions |
| Companies Covered | Dell Technologies Inc., Seagate Technology Holdings Public Limited Company, NetApp, Inc., Hewlett Packard Enterprise Company, Western Digital Corporation, Pure Storage, Inc., IBM Corporation, Hitachi Vantara LLC, Huawei Investment & Holding Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Storage Devices Market Strategic Shifts
Storage architecture is fragmenting between performance-optimized flash tiers and capacity-optimized disk tiers, with software-defined disaggregation erasing traditional hardware boundaries. This divergence is spawning new vendor specializations and procurement methodologies.
QLC NAND is overtaking TLC in read-heavy cloud storage nodes where endurance requirements have relaxed. Hyperscale operators are deploying QLC-based NVMe drives for warm data tiers, accepting lower write cycles in exchange for 30% cost reduction per terabyte. This density gain is overtaking the historical preference for higher-endurance flash in secondary storage roles.
China's GB standards and MIIT certification requirements are tightening electromagnetic compatibility testing for storage devices sold domestically. Foreign suppliers must establish in-country testing partnerships, adding 4-6 months to product registration timelines. Enterprise array vendors are responding by pre-certifying controller firmware specifically for the Chinese market, segmenting their global SKU strategies.
Consumption-based financing models are displacing capital purchase agreements for mid-market enterprise storage. Dell Technologies, HPE, and Pure Storage have all launched subscription programs where customers pay per terabyte-month rather than acquiring hardware. This transition is most advanced in the United States, where CFOs prefer operating expenditure treatment for IT infrastructure amid interest rate volatility.
Data Storage Devices Market Segmentation
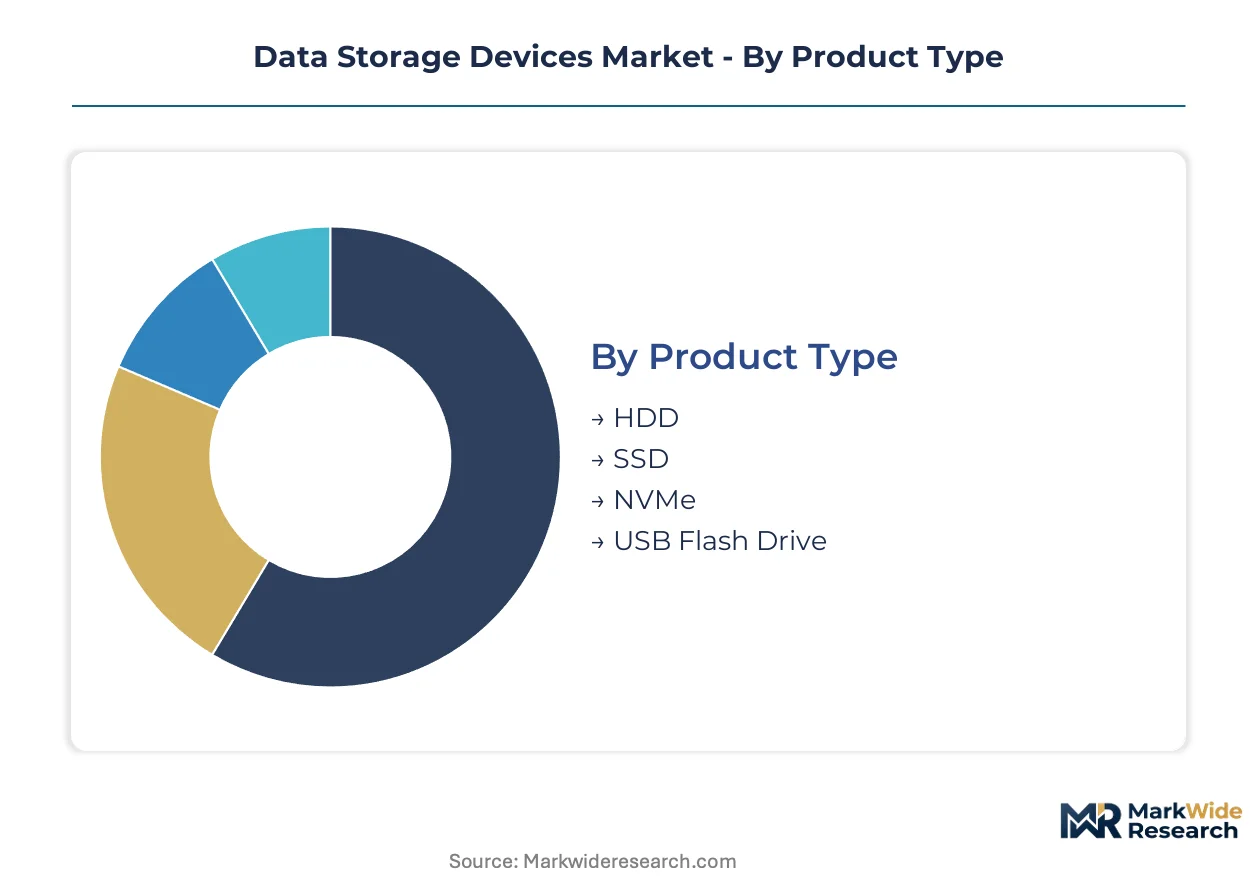
Segmentation in data storage reveals how procurement criteria diverge between latency-sensitive workloads and archival cost optimization. Understanding these fault lines helps vendors allocate engineering resources and channel investment across incompatible buyer priorities.
Product Type:
Buyers in this category separate by workload performance requirements versus cost-per-gigabyte tolerance.
- HDD:Magnetic platter technology with spinning disks delivers bulk capacity at the lowest acquisition cost per terabyte. Cloud hyperscalers in the United States deploy nearline HDDs for cold archival tiers where access frequency remains minimal. Seagate and Western Digital anchor manufacturing scale that competitors cannot replicate.
- SSD:NAND flash arrays without mechanical components provide sub-millisecond latency for transactional databases and virtualization layers. Financial services firms in Frankfurt and Singapore prioritize SSD deployments for real-time risk analytics where milliseconds translate to trading advantage.
- NVMe:PCIe-attached flash protocol eliminates SAS/SATA controller overhead, saturating host bus bandwidth for AI training clusters.
- USB Flash Drive:Portable solid-state storage in compact form factors serves content distribution and offline backup for mobile workforces.
Volume sits with HDD; growth tilts toward NVMe.
Storage Capacity:
Capacity selection tracks data generation velocity and retention policy enforcement across enterprise verticals.
- 1TB:Entry-level solid-state units address endpoint refresh cycles and branch office server deployments. Healthcare clinics in Texas and Bavaria standardize on 1TB SSDs for imaging workstation upgrades where budget constraints limit per-seat infrastructure spend.
- 2TB:Mid-range density hits the sweet spot for professional creative workstations and small business server arrays. Post-production studios in Mumbai and Seoul specify 2TB NVMe drives for 4K video editing timelines where scratch disk performance constrains render throughput.
- 4TB:High-capacity enterprise-grade units support database consolidation and virtual machine density targets.
- 8TB:Maximum-density nearline drives enable multi-petabyte rack-scale deployments without proportional footprint expansion.
Procurement concentrates at 2TB for general enterprise; 8TB climbs the fastest in hyperscale facilities.
Interface Type:
Interface selection determines protocol compatibility with existing infrastructure and thermal design power constraints.
- SATA:Legacy 6Gb/s protocol maintains backward compatibility with aging server fleets and consumer motherboards. Educational institutions across Poland and Spain extend hardware lifecycles through SATA SSD replacements that avoid full platform refreshes.
- SCSI:Parallel and serial SCSI variants persist in specialized industrial automation and legacy medical imaging equipment where certification costs block interface migration.
- PCIe:Direct CPU attachment via NVMe over PCIe Gen4/Gen5 delivers maximum bandwidth for GPU-accelerated workloads.
- Thunderbolt:External connectivity standard with DisplayPort integration serves creative professionals requiring portable high-speed storage.
Deployment share belongs to SATA; PCIe gains share fastest as data center architects retire legacy SAS fabrics.
Usage Scenario:
End-use context dictates endurance specifications, form factor constraints, and software integration requirements.
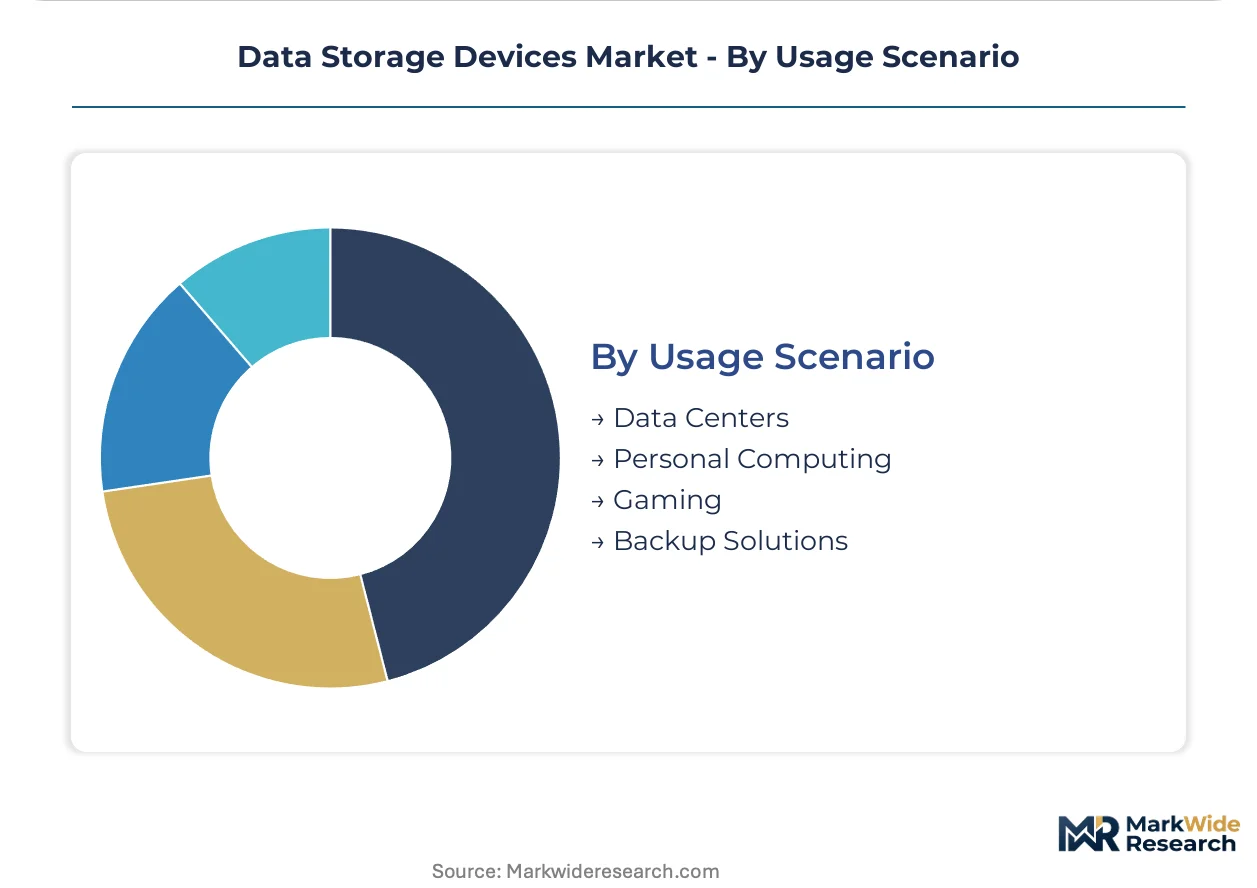
- Data Centers:Hyperscale and colocation facilities demand 24/7 availability with hot-swappable drive carriers and predictive failure analytics. Operators in Virginia, Iowa, and Dublin specify drives with power-loss protection capacitors and signed firmware for supply chain integrity verification.
- Personal Computing:Consumer laptops and desktops prioritize boot time reduction and silent operation over sustained write endurance. Retail channels in Japan and Germany bundle 1TB SSDs with premium ultrabook configurations where thin chassis preclude 2.5-inch drive accommodation.
- Gaming:Load time reduction drives enthusiast procurement of high-IOPS NVMe storage for open-world titles.
- Backup Solutions:Air-gapped and immutable storage architectures satisfy ransomware recovery requirements for regulated enterprises.
Revenue pools in data centers; gaming exhibits the steepest expansion trajectory as AAA title install sizes balloon.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Northern Virginia's Data Center Alley hosts the densest concentration of hyperscale storage infrastructure worldwide, with over 35% of global cloud capacity residing within Loudoun and Prince William counties. This concentration shapes procurement patterns across the entire sector.
United States
Hyperscale operators in Iowa, Texas, and Ohio are commissioning multi-gigawatt facilities with NVMe-native architectures. The IRA's clean energy credits subsidize domestic SSD assembly reshoring. Phoenix and Dallas-Fort Worth emerge as secondary clusters where tax abatements attract modular all-flash array deployments.
China
MIIT certification requirements and GB electromagnetic compatibility standards are tightening market access for foreign storage vendors. Yangtze Memory Technologies and domestic NAND foundries supply hyperscalers in Beijing and Hangzhou with locally certified drives. Shanghai's Pudong district anchors controller firmware development for sovereign cloud infrastructure.
Germany
Frankfurt's banking sector drives demand for FIPS-validated encrypted storage arrays under BaFin operational resilience mandates. The EU CSRD forces enterprises in Bavaria and North Rhine-Westphalia to refresh infrastructure with energy-efficient solid-state systems. Dresden's semiconductor cluster supports regional controller manufacturing.
India
MeitY data localization rules mandate in-country storage for financial and government data, opening greenfield opportunities in Mumbai and Hyderabad. BIS certification requirements for IT hardware create compliance barriers that domestic assemblers navigate more efficiently than multinationals. Bangalore's technology corridor hosts emerging local storage system integrators.
Japan
Kanto region enterprises prioritize disaster-resilient storage architectures following revised METI business continuity guidelines. Yokohama and Osaka data centers specify drives with extended temperature tolerance for seismic resilience. Domestic NAND supply from Kioxia supports preferential procurement in critical infrastructure sectors.
Data Storage Devices Market Competitive Environment
Premium-margin players sit above commodity-margin players across the enterprise-to-consumer spectrum, with integration depth separating sustainable profitability from cyclical exposure. Consolidation concentrates among five vertically integrated platform vendors controlling array-level software and hardware. Three archetypes dominate: full-stack enterprise systems houses, component-specialist volume manufacturers, and cloud-native software-defined challengers. Strategic moves center on NVMe fabric acquisition and computational storage IP licensing rather than capacity expansion.
Within the integrated systems tier, Dell Technologies Inc. and Hewlett Packard Enterprise Company occupy positions exemplifying server-storage convergence strategies, while Western Digital Corporation represents the dual-technology manufacturer archetype spanning flash and magnetic media. Pure Storage, Inc. anchors the all-flash native category that bypasses legacy HDD transition costs entirely.
| Leading Market Players |
|---|
| Dell Technologies Inc. |
| Seagate Technology Holdings Public Limited Company |
| NetApp, Inc. |
| Hewlett Packard Enterprise Company |
| Western Digital Corporation |
| Pure Storage, Inc. |
| IBM Corporation |
| Hitachi Vantara LLC |
| Huawei Investment & Holding Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
QLC NAND die shrinks and controller ASIC integration are compressing cost-per-terabyte curves while simultaneously concentrating wafer supply among three foundry operators. This dual transformation tightens margin pools for mid-tier array vendors and amplifies procurement leverage for hyperscale cloud operators who dictate form-factor roadmaps.
Pricing Analysis
Throughput-based pricing anchors enterprise NVMe contracts where customers pay for guaranteed IOPS rather than raw capacity. Three-tier pricing structure across premium, standard, and economy levels separates FIPS-validated encrypted arrays from general-purpose SSDs and bulk archival HDDs. Cost compression in nearline HDD tiers is intensifying because hyperscalers are consolidating procurement volumes under long-term offtake agreements. Cloud hyperscalers exhibit the lowest price sensitivity while mid-market enterprises with Fibre Channel legacy infrastructure face the highest.
Supply Chain Analysis
Dual-sourcing requirements from hyperscale operators mandate multi-supplier qualification for NAND flash controllers and power-loss protection capacitors. Geographic supply concentration centers on South Korea, Taiwan, and China for wafer fabrication, with Malaysia and Thailand anchoring drive assembly and test operations. Raw material dependencies include silicon wafers, rare earth elements for spindle motors, and cobalt for DRAM cache modules. Single-source vulnerability runs through specialty controller firmware houses. Distribution runs through direct procurement channels for hyperscale operators and tier-one distributors for enterprise VARs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where controller IP and captive NAND supply determine who captures margin expansion. Players are pursuing backward integration into flash foundry partnerships or forward integration into software-defined storage platforms.
For Market Incumbents: Anticipate margin compression from computational storage convergence by acquiring FPGA-based processing-in-memory startups before they scale. Secure supply chain integrity through signed firmware verification and power-loss protection capacitor dual-sourcing. Defend against white-label NVMe challengers by embedding predictive analytics into array management software.
For New Entrants and Emerging Players: Regional system integrators in India and Southeast Asia represent the most penetrable channel for modular all-flash arrays under data localization mandates. Target sovereign cloud infrastructure projects where domestic certification requirements disadvantage multinational incumbents. Lead with consumption-based financing models that convert capital expenditure to operating expenditure for CFOs facing interest rate volatility.
For Investors and Strategic Acquirers: Re-rating potential sits with computational storage IP holders given AI training cluster demand for near-memory processing. Long-term viability over a multi-year horizon hinges on defensible controller architecture and thermal management patents. The signal to watch is hyperscaler qualification timelines for QLC-based NVMe drives as a proxy for flash cost-parity acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| NVMe Fabric Acquisition | PCIe Gen5 switch integration enables rack-scale disaggregation for AI training clusters. |
| Controller ASIC Development | In-house error-correction algorithms reduce dependency on Marvell and Phison silicon. |
| Computational Storage Partnership | FPGA acceleration for video analytics merges storage and compute at the edge. |
| Domestic Assembly Reshoring | US IRA clean energy credits subsidize SSD manufacturing for federal procurement channels. |
| Software-Defined Platform Launch | Subscription pricing converts hardware revenue to recurring terabyte-month streams. |
Study Parameters
SEC 10-K filings, hyperscaler capex disclosures, and customs trade records formed the secondary backbone for volume and pricing calibration. Primary interviews with data center procurement officers, NAND flash controller engineers, and enterprise storage VARs validated demand assumptions across workload segments. Bottom-up and top-down triangulation reconciled foundry wafer output estimates with array-level shipment data.
Bottom-up modeling aggregated individual product SKUs across interface types, capacity tiers, and usage scenarios. Segmentation dimensions included storage protocol, endurance classification, deployment scale, and regional regulatory cluster. CAGRs were derived from regression analysis of historical hyperscaler infrastructure spend against projected AI training cluster buildouts. Forecast inputs incorporated EU CSRD compliance timelines and India MeitY localization mandates.
Caveats apply where NAND technology node transitions or REACH substance restrictions could materially shift the outlook. Deviation in hyperscaler capital expenditure cycles would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
Flash Memory Market
Data Storage
Solid State Drive (SSD) Market
Data Storage
Global 3D Nand Flash Memory Market
Data Storage
NAND Flash Memory Market
Data Storage
Tape Storage Market
Data Storage
Optical Disk Market
Data Storage
AI Powered Storage Market
Data Storage
Powered Storage Devices Market
Data Storage
Solid State Array Market
Data Storage
Middle East Data Center Storage Market
Data Storage
Japan Data Center Storage Market
Data Storage
Storage Class Memory Market
Data Storage
Enterprise Flash Storage Market
Data Storage
Middle East and Africa SSD Caching Market
Data Storage
Middle East and Africa AMH and Storage Systems Market
Data Storage
Data Center Ssds Market