
 Recordable Optical Disc Market | 2026-2036
Recordable Optical Disc Market Size, Share, and Industry Trends Forecast 2026-2036
Recordable Optical Disc Market Analysis
Subscription-based archival verification services is decoupling hardware ownership from long-term data retention contracts. Taiyo Yuden Co., Ltd. leverages its dye-formulation expertise to dominate professional-grade BD-R supply. Sony Corporation anchors broadcast-archiving workflows through proprietary error-correction protocols. RITEK Corporation competes on polycarbonate sourcing scale across Southeast Asian manufacturing nodes.
A recordable optical disc comprises a polycarbonate substrate, reflective metal layer, organic dye or phase-change recording layer, and protective lacquer, manufactured through injection molding, sputtering, and spin-coating processes to enable one-time or rewritable digital data inscription. DVD-R and BD-R command the residual margin pool as broadcasters and national archives require write-once verification for legal compliance. CD-R persists in audio mastering niches where uncompressed PCM fidelity outweighs convenience. Data storage applications retain structural priority as enterprises confront ransomware recovery mandates.
Japan's METI enforces JIS standards on recording-layer stability, while China's MEE regulates polycarbonate resin emissions through GB standards; REACH compliance in Europe constrains heavy-metal reflective-layer formulations. Stakeholders must monitor whether archival-certification requirements expand beyond current broadcast and government verticals into pharmaceutical chain-of-custody documentation.
Market Dynamics
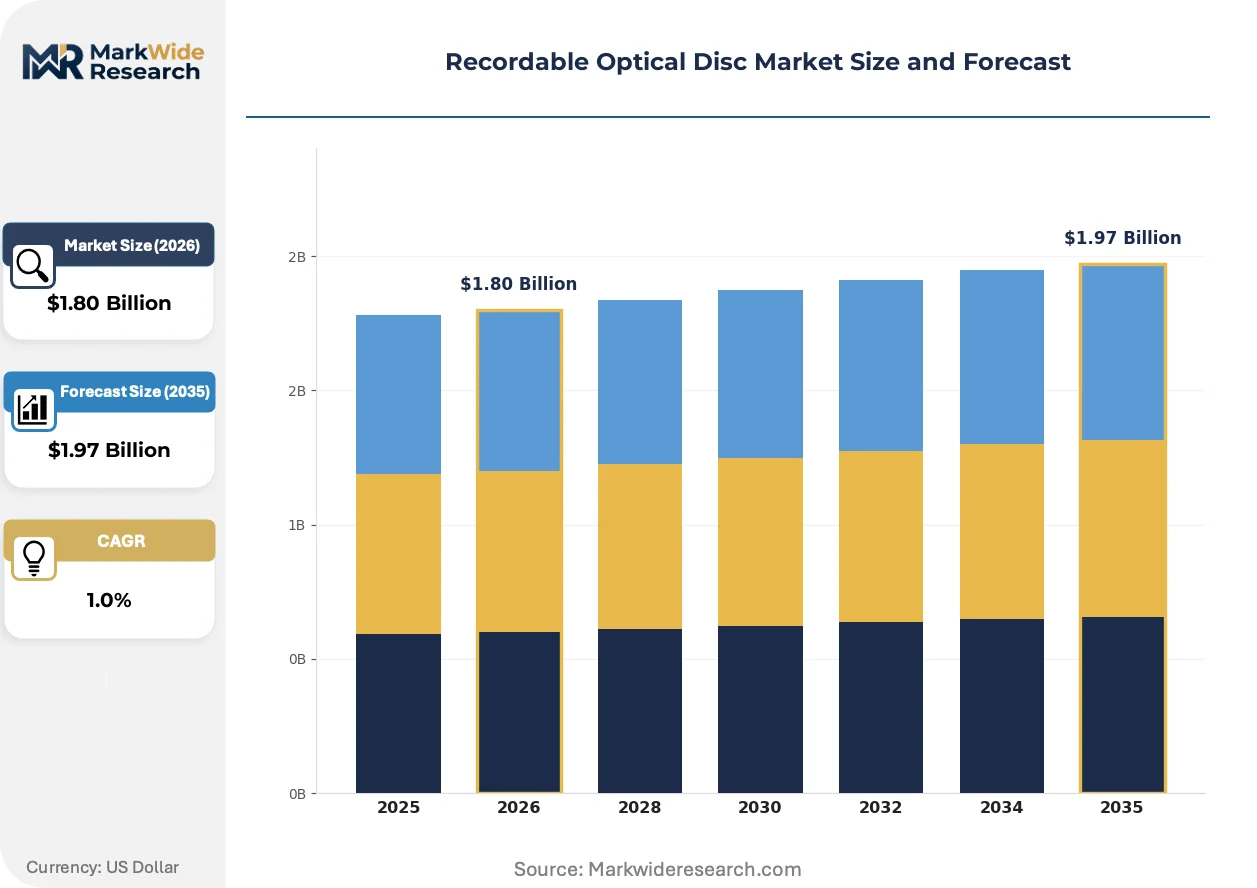
Archival-certification mandates from broadcast regulators and national archives are preserving demand for write-once optical media despite streaming displacement, while polycarbonate supply constraints under China's MEE dual-carbon framework are compressing margin structures for substrate-dependent manufacturers.
Growth Catalysts
- Ransomware Recovery Mandates:Enterprise disaster-recovery protocols are codifying offline write-once media as the immutable backup tier for critical datasets, creating structural pull from financial and healthcare data centers.
- Japan's JIS Stability Standards:METI-enforced recording-layer longevity certifications are differentiating professional-grade discs from consumer-tier alternatives, enabling premium pricing for broadcast-archiving applications.
- Carbon-Intensive Resin Sourcing:China's polycarbonate production concentration under MEE emissions caps is forcing substrate manufacturers toward captive chemical partnerships, locking in supply security for compliant producers.
Market Restraints
- Cloud Storage Substitution:Hyperscale cold-storage tiers from AWS Glacier and Azure Archive are undercutting optical media on total cost of ownership for non-regulated enterprise archives.
- Polycarbonate Monopoly Geography:Substrate resin production clusters in Shandong and Zhejiang provinces create single-country dependency risk for disc manufacturers lacking backward chemical integration.
- REACH Heavy-Metal Limits:ECHA restrictions on silver and gold reflective-layer formulations are forcing alloy substitutions that degrade signal-to-noise ratios in high-density BD-R formats.
Strategic Opportunities
- Pharmaceutical Chain-of-Custody:FDA 21 CFR Part 11 compliance gaps in electronic batch records are creating openings for tamper-evident optical documentation in generic drug manufacturing.
- Subscription Verification Services:Hardware-ownership decoupling through archival-retention contracts is transforming one-time disc sales into recurring revenue streams for certified service providers.
- EU CSRD Data Retention:Corporate sustainability reporting directives are mandating decade-long audit trails that favor immutable optical storage over rewritable magnetic alternatives.
Industry Challenges
- Dye-Formulation Talent Scarcity:Organic chemistry expertise for recording-layer stability engineering is concentrating among retiring specialists at Japanese and Taiwanese compounders, constraining new product development pipelines.
- Multi-Standard Certification Overhead:Simultaneous compliance with JIS, IEC, and GB testing protocols is extending product launch timelines by 8-14 months for cross-border disc suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recordable Optical Disc Market |
| Market Size in 2026 | $1.80 Billion |
| Market Size in 2035 | $1.97 Billion |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DVD-R, DVD+R, CD-R, BD-R Material: Polycarbonate, Reflection Layer, Recording Layer, Protective Coating Application: Data Storage, Video Recording, Audio Recording, Software Distribution End User: Home Users, Educational Institutions, Corporate, Retailers |
| Companies Covered | Taiyo Yuden Co., Ltd., Hitachi Maxell Ltd., CMC Magnetics Corporation, Falcon Technologies International LLC, Singulus Technologies, RITEK Corporation, Fujifilm Holdings Corporation, Princo Corp., Sony Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recordable Optical Disc Market Emerging Trajectories
Manufacturers are embedding authentication features and service-layer contracts into physical media to escape commodity pricing traps, while regulatory data-retention mandates are expanding addressable markets beyond traditional broadcast verticals.
Archival-grade BD-R media is integrating inorganic phase-change recording layers that replace organic dyes, extending rated shelf life from fifty to one hundred years. National archives in Germany and Australia are mandating these formulations for born-digital cultural heritage preservation. This specification tightening is integrating professional-grade supply chains with substrate purity requirements that exclude second-tier polycarbonate sources.
REACH Annex XVII amendments are restricting cadmium and lead content in reflective metal sputtering targets, forcing European disc manufacturers to qualify alternative aluminum-silver alloys. The reformulation cycle is compressing production yields during qualification periods. Medical-device documentation archives in Switzerland and the Netherlands are absorbing these cost premiums to maintain CE-marked compliance.
Broadcasters are unbundling hardware procurement from managed archival services, contracting verification and migration responsibilities to specialized operators. This service-layer pivot is displacing direct disc sales in Western European public television networks. Sveriges Television and Denmark's DR are piloting subscription-based retention contracts that transfer obsolescence risk to service providers.
Recordable Optical Disc Market Segmentation
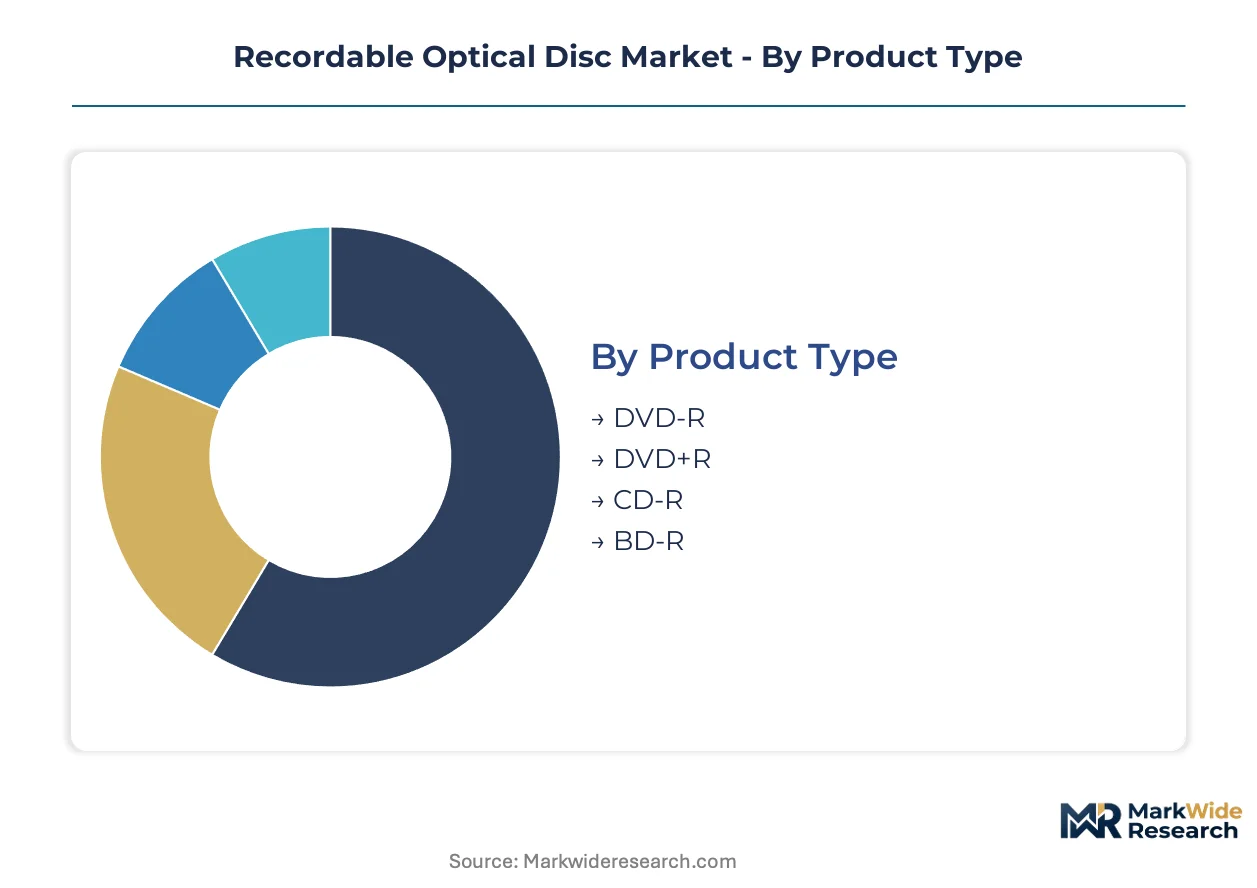
Segmentation in recordable optical media reveals how certification requirements fragment demand across professional and consumer tiers. Disc specifications determine compliance eligibility for broadcast archiving, pharmaceutical documentation, and government retention mandates.
Product Type:
Certification burdens concentrate on BD-R and DVD-R formats where JIS longevity standards and archival mandates apply, while CD-R operates under lighter consumer-audio regulations without broadcast-tier verification requirements.
- BD-R:Inorganic phase-change recording layers replace organic dyes in professional-grade formulations. National archives in Germany and Australia mandate these discs for born-digital cultural heritage, locking out uncertified suppliers.
- DVD-R:Write-once verification protocols satisfy legal compliance for broadcasters and national archives. Sveriges Television and Denmark's DR specify DVD-R for subscription-based archival retention contracts.
- DVD+R:Competing format with comparable capacity but distinct recording-layer chemistry requiring separate certification pathways.
- CD-R:Persists in audio mastering niches where uncompressed PCM fidelity outweighs streaming convenience.
Leading the category by volume: DVD-R. Growing fastest: BD-R.
Material:
Cost tiers separate captive polycarbonate producers from substrate-dependent competitors, with MEE emissions caps in China concentrating supply security among backward-integrated manufacturers.
- Polycarbonate:Substrate resin production clusters in Shandong and Zhejiang provinces create single-country dependency risk for manufacturers lacking chemical integration. China's dual carbon goals under MEE pressure sourcing strategies.
- Recording Layer:Organic dye formulations concentrate among Japanese and Taiwanese compounders facing talent scarcity as specialists retire. Taiyo Yuden leverages this expertise for professional-grade BD-R supply.
- Reflection Layer:REACH Annex XVII restricts cadmium and lead sputtering targets, forcing European manufacturers to qualify aluminum-silver alloys.
- Protective Coating:Lacquer formulations shield recording layers from environmental degradation across all format tiers.
Polycarbonate commands the steepest cost pressure. Recording layers carry the highest technical premium.
Application:
Customer type determines whether immutable write-once verification outweighs rewritable convenience, with regulated enterprises accepting optical media despite cloud substitution in unregulated segments.
- Data Storage:Enterprise disaster-recovery protocols codify offline write-once media as the immutable backup tier. Financial and healthcare data centers absorb ransomware recovery mandates.
- Video Recording:Broadcast-archiving workflows anchor demand through proprietary error-correction protocols. Sony supplies this vertical with certified professional-grade media.
- Audio Recording:Uncompressed PCM mastering in professional studios sustains residual CD-R demand against streaming displacement.
- Software Distribution:Physical media persists for offline installation scenarios in secure or bandwidth-constrained environments.
Data storage generates the highest compliance premiums. Video recording maintains the most stable contract base.
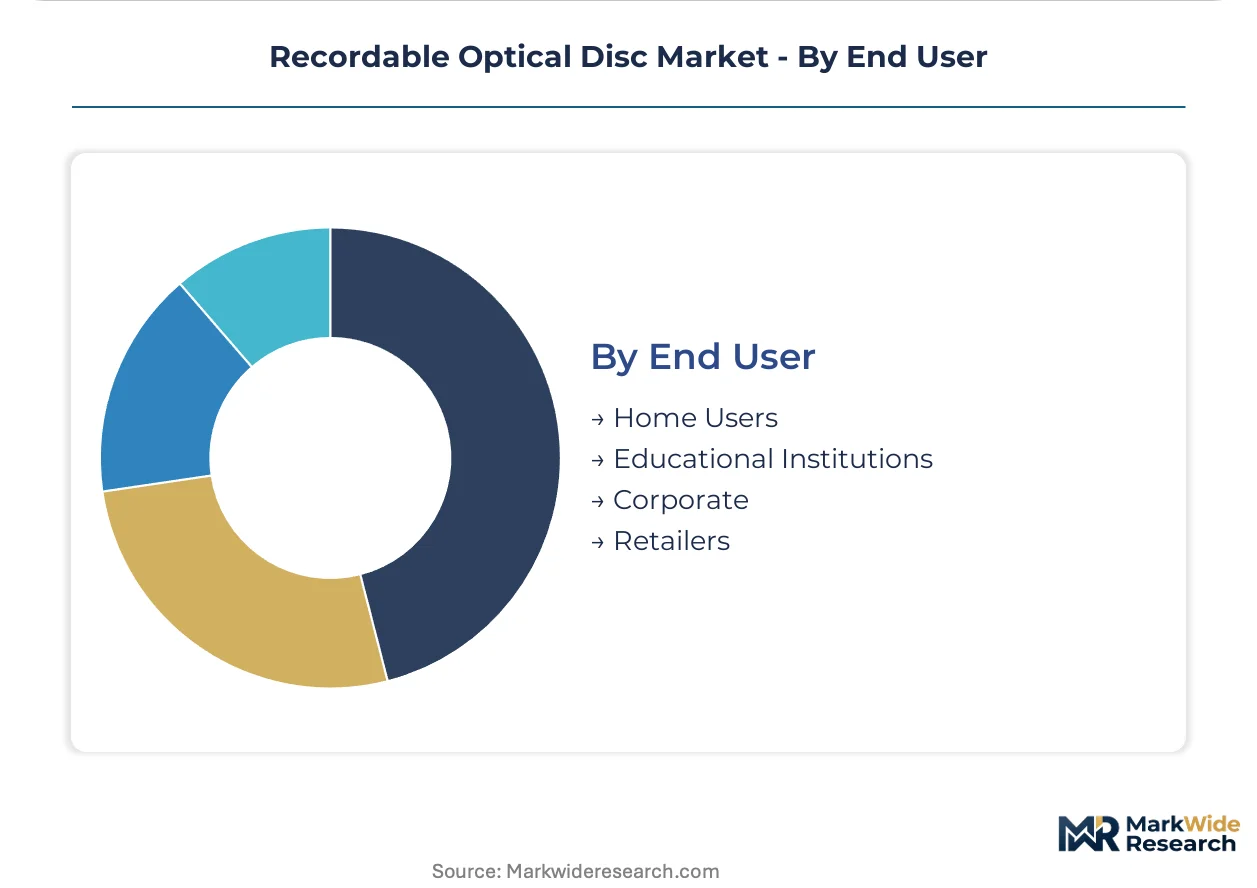
End User:
Procurement scale separates enterprise archival contracts from transactional retail purchases, with service-layer bundling transforming hardware ownership into recurring revenue for certified operators.
- Corporate:Enterprises confront ransomware recovery mandates and FDA 21 CFR Part 11 compliance gaps in electronic batch records. Pharmaceutical manufacturers absorb cost premiums for tamper-evident optical documentation.
- Educational Institutions:Research libraries and university archives specify JIS-certified media for thesis preservation and dataset retention.
- Home Users:Consumer tier faces complete streaming and cloud substitution, with residual demand concentrated in audio enthusiast niches.
- Retailers:Distribution channel for unbranded and private-label media serving price-sensitive residual demand.
Corporate buyers concentrate the highest value per terabyte. Educational institutions represent the most price-insensitive public-sector demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polycarbonate substrate production concentrates in China's Shandong and Zhejiang provinces, while precision recording-layer manufacturing clusters in Japan and Taiwan. This geographic split creates supply-chain dependencies that reshape procurement strategies for disc manufacturers worldwide.
China
Shandong and Zhejiang resin producers supply the majority of optical-grade polycarbonate globally. MEE dual-carbon emissions caps are constraining substrate output and forcing manufacturers toward captive chemical partnerships. Taiyuan and Shanghai house the principal disc fabrication facilities serving domestic archival demand.
Japan
METI-enforced JIS longevity standards differentiate professional-grade media for broadcast archiving and national heritage preservation. Tokyo and Osaka metropolitan areas concentrate dye-formulation expertise among legacy compounders. Kanto region facilities supply certified BD-R media to NHK and regional broadcasters under subscription retention contracts.
Germany
REACH Annex XVII restrictions on heavy-metal reflective layers are forcing aluminum-silver alloy qualifications among European manufacturers. Bavaria and Baden-Württemberg host medical-device documentation archives absorbing these compliance premiums. Frankfurt broadcasters specify inorganic phase-change media for born-digital cultural heritage mandates.
United States
FDA 21 CFR Part 11 compliance gaps in pharmaceutical electronic batch records sustain demand for tamper-evident optical documentation. Financial services data centers in New York and Chicago deploy offline write-once media for ransomware recovery protocols. Healthcare enterprises absorb cost premiums for immutable backup tiers.
Australia
National archives in Canberra mandate inorganic phase-change BD-R formulations for born-digital preservation exceeding fifty-year retention horizons. Sydney and Melbourne broadcasters pilot subscription-based archival verification services displacing direct hardware procurement. TGA-aligned medical documentation standards reinforce optical media specifications for device manufacturers.
Recordable Optical Disc Market Vendor Landscape
Capital-heavy substrate producers compete with asset-light recording-layer specialists across tiered supply positions. The vendor base separates into polycarbonate-integrated manufacturers, dye-formulation compounders, and assembly-scale fabricators. Three archetypes dominate: backward-integrated resin producers, certified archival-grade specialists, and volume-driven commodity assemblers. Competitive moves center on captive chemical partnerships and service-layer bundling that transfers hardware obsolescence risk to contracted operators.
Among Japanese precision manufacturers, Taiyo Yuden Co., Ltd. and Sony Corporation occupy positions defined by formulation expertise and broadcast workflow integration respectively. RITEK Corporation represents the scale-driven fabrication archetype with Southeast Asian manufacturing nodes. These three entities anchor the supply structure: Taiyo Yuden exemplifies the recording-layer specialization tier, Sony anchors premium-tier archival certification, and RITEK occupies volume-scale assembly positioning.
| Leading Market Players |
|---|
| Taiyo Yuden Co., Ltd. |
| Hitachi Maxell Ltd. |
| CMC Magnetics Corporation |
| Falcon Technologies International LLC |
| Singulus Technologies |
| RITEK Corporation |
| Fujifilm Holdings Corporation |
| Princo Corp. |
| Sony Corporation |
| Others |
Supply Flow & Price Mechanics
Inorganic phase-change recording-layer adoption across archival-grade BD-R manufacturing simultaneously elevates substrate purity requirements and concentrates supply security among polycarbonate-integrated producers, compressing margin structures for second-tier compounders while locking in premium pricing for certified suppliers.
Pricing Analysis
Margin tightening in professional-grade tiers reflects JIS longevity certification overhead and REACH-compliant reflective-layer alloy substitutions. Three-tier pricing structure across archival-certified, broadcast-standard, and economy consumer levels separates compliant producers from commodity assemblers. Cost compression accelerates in substrate-dependent manufacturing as China's MEE emissions caps constrain polycarbonate resin availability. Corporate archival buyers exhibit lowest price sensitivity due to ransomware recovery mandates, while home users face complete streaming substitution.
Supply Chain Analysis
Single-source vulnerability sits with Shandong and Zhejiang province resin clusters supplying optical-grade polycarbonate substrate. Disc manufacturing draws from Chinese polycarbonate, Japanese and Taiwanese dye formulations, and European aluminum-silver reflective-layer alloys. Regulatory restriction risk intensifies under REACH Annex XVII heavy-metal limits and MEE dual-carbon enforcement. Distribution runs through broadcast equipment OEMs, pharmaceutical documentation integrators, and direct archival service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance arena where Japan's METI-enforced JIS recording-layer stability standards erect technical barriers that sustain premium pricing for certified incumbents while excluding undercapitalized entrants.
For Market Incumbents: Anticipate dye-formulation talent scarcity as Japanese and Taiwanese organic chemistry specialists retire, accelerating defensive consolidation around captive chemical partnerships and backward integration into polycarbonate substrate production. Lock in broadcast-archiving subscription contracts with Sveriges Television and Denmark's DR to transfer hardware obsolescence risk before cloud cold-storage tiers erode enterprise demand. For New Entrants and Emerging Players: Direct-to-archival-service channels bypass capital-intensive disc fabrication entirely, enabling SaaS-tiered verification contracts without substrate exposure. Pharmaceutical chain-of-custody documentation under FDA 21 CFR Part 11 compliance gaps represents the most penetrable white-space, with generic drug manufacturers absorbing cost premiums for tamper-evident optical batch records. For Investors and Strategic Acquirers: Exit pathways concentrate in service-layer bundling acquisitions and backward-integrated substrate producers with MEE-compliant chemical partnerships. Long-term viability hinges on whether archival-certification mandates expand beyond broadcast and government verticals into EU CSRD-mandated sustainability audit trails. Watch for JIS standard adoption by pharmaceutical regulators as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polycarbonate | MEE-compliant resin partnerships lock in substrate security against Shandong supply caps. |
| Archival Subscription Service Launch | Sveriges Television contracts demonstrate hardware-ownership decoupling viability. |
| JIS Certification Investment | METI-enforced longevity standards differentiate professional-grade from consumer-tier alternatives. |
| Pharmaceutical Documentation Partnership | FDA 21 CFR Part 11 gaps create tamper-evident optical batch record demand. |
| Inorganic Phase-Change Layer Transition | German and Australian national archives mandate hundred-year shelf life specifications. |
Methodological Framework
Document review covered customs/trade data, SEC filings from disc manufacturers, and JIS certification registries, complemented by interviews with broadcast archiving engineers, pharmaceutical documentation compliance officers, polycarbonate procurement leads, and national archive preservation specialists. Primary fieldwork across Tokyo, Shanghai, and Frankfurt validated secondary sources including METI regulatory bulletins, ECHA REACH amendments, and MEE emissions disclosure filings. Bottom-up demand modeling triangulated against top-down supply capacity assessments.
Cross-referencing historical pricing trajectories with expert panel input on MEE enforcement timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product format tier, recording-layer chemistry type, end-use application vertical, and geographic regulatory cluster. CAGRs derived from substrate supply elasticity and certification mandate diffusion curves incorporated polycarbonate resin cost indices and archival service contract growth rates.
The model holds under sustained JIS and REACH enforcement; deviation in MEE emissions cap relaxation or cloud cold-storage regulatory equivalency would shift volume trajectories. Forecasts reflect assumptions on dye-formulation talent pipeline continuity and broadcast subscription contract renewal rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
Storage Virtualization Market
Data Storage
Global Digital Storage Devices Market
Data Storage
Middle East and Africa AMH and Storage Systems Market
Data Storage
Optical Disk Market
Data Storage
Global Personal and Entry Level Storage (PELS) Market
Data Storage
Flash-Based Array Market
Data Storage
APAC SSD Caching Market
Data Storage
Transparent Cache Market
Data Storage
Europe Next Generation Storage Market
Data Storage
Data Storage Market
Data Storage
Australia Data Center Storage Market
Data Storage
Powered Storage Devices Market
Data Storage
Serial EEPROM Market
Data Storage
North America AMH and Storage Systems Market
Data Storage
AI Powered Storage Market
Data Storage
Enterprise Flash Storage Market