
 Next-Generation Storage Market | 2026-2036
Next-Generation Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Next-Generation Storage Market Outlook
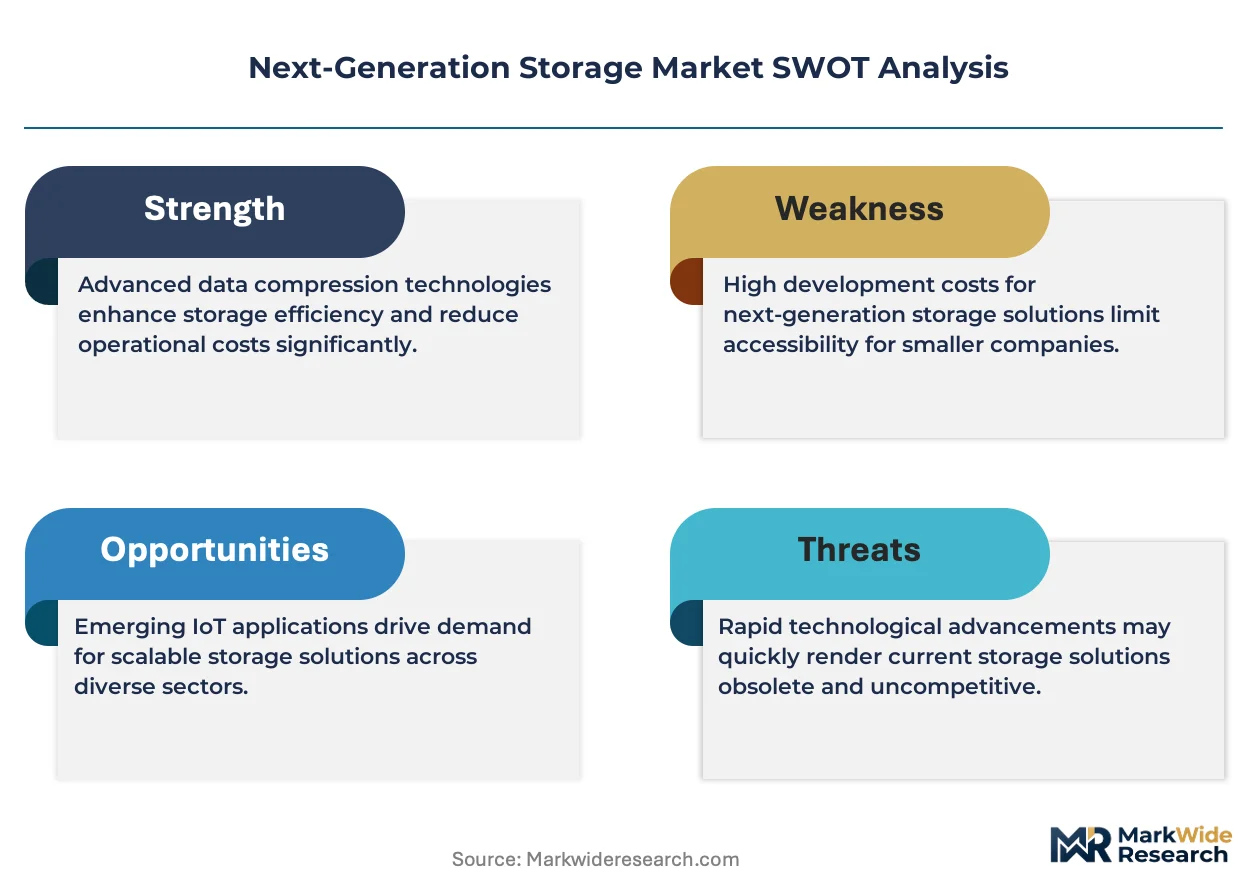
Enterprise procurement of next-generation storage is fragmenting as cloud providers, hyperscalers, and sovereign data center operators pursue diverging technical specifications and contracting models. Dell Technologies leverages its integrated supply chain to sustain margin control across hybrid storage deployments. Pure Storage differentiates through software-defined architectures that reduce hardware refresh cycles. Huawei Technologies dominates domestic procurement pipelines while navigating export control complexity in select Western markets.
Next-generation storage encompasses solid-state, software-defined, and cloud-native architectures engineered for sub-millisecond latency, petabyte-scale capacity, and autonomous data management across distributed environments. These systems employ NVMe over Fabrics, computational storage processors, and AI-driven tiering algorithms to serve real-time analytics, machine learning training pipelines, and resilient backup workloads. SSD and NVMe segments are capturing the fastest expansion as enterprise flash displacement of mechanical hard drives accelerates; object storage anchors archival and unstructured data lakes with mature margin profiles; hybrid arrays retain relevance in regulated verticals requiring on-premises control with burst-to-cloud flexibility.
FERC grid interconnection standards, EPA e-waste directives, and EU CSRD sustainability disclosure requirements are reshaping procurement criteria for data center storage infrastructure across North America and Europe. These frameworks mandate embodied carbon reporting, circular design protocols, and energy efficiency thresholds that filter vendor qualification and extend contract evaluation timelines. Stakeholders must monitor how evolving efficiency benchmarks and supply chain provenance rules reshape total cost-of-ownership calculations and vendor shortlisting criteria.
Market Dynamics
Hyperscale data center operators are fragmenting procurement specifications as NVMe over Fabrics and computational storage processors create divergent performance tiers across cloud-native, hybrid, and sovereign deployment models.
Growth Catalysts
- EU CSRD mandates:Sustainability disclosure rules are accelerating refresh cycles toward energy-efficient flash arrays as enterprises pre-empt audit requirements.
- Machine learning training pipelines:Sub-millisecond latency requirements from AI infrastructure operators are displacing mechanical hard drives in primary storage tiers.
- Northern Virginia cluster expansion:Concentrated data center construction is absorbing petabyte-scale NVMe deployments from cloud service providers.
Market Restraints
- NAND flash supply concentration:Korean and Japanese memory foundries create input cost volatility during fab conversion cycles.
- Export control complexity:Western trade restrictions on advanced storage controllers limit vendor qualification pools for certain hyperscale tenders.
- Mechanical hard drive residual value:Cold archival workloads retain tape and HDD economics that compress all-flash pricing power at the bottom tier.
Strategic Opportunities
- Germany battery supply chain rules:Due diligence mandates for embodied carbon reporting favor vendors with circular design certification.
- Computational storage convergence:In-situ processing integration with AI inference chips creates new performance tiers at the edge.
- Sovereign data center procurement:National cloud operators in France and Italy are specifying on-premises NVMe arrays with burst-to-cloud failover.
Industry Challenges
- FERC interconnection timelines:Grid connection delays for hyperscale facilities in Texas and Virginia compress deployment windows and strain working capital.
- NVMe over Fabrics skill scarcity:Network-storage convergence expertise remains concentrated among specialized systems integrators, limiting enterprise self-deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Next-Generation Storage Market |
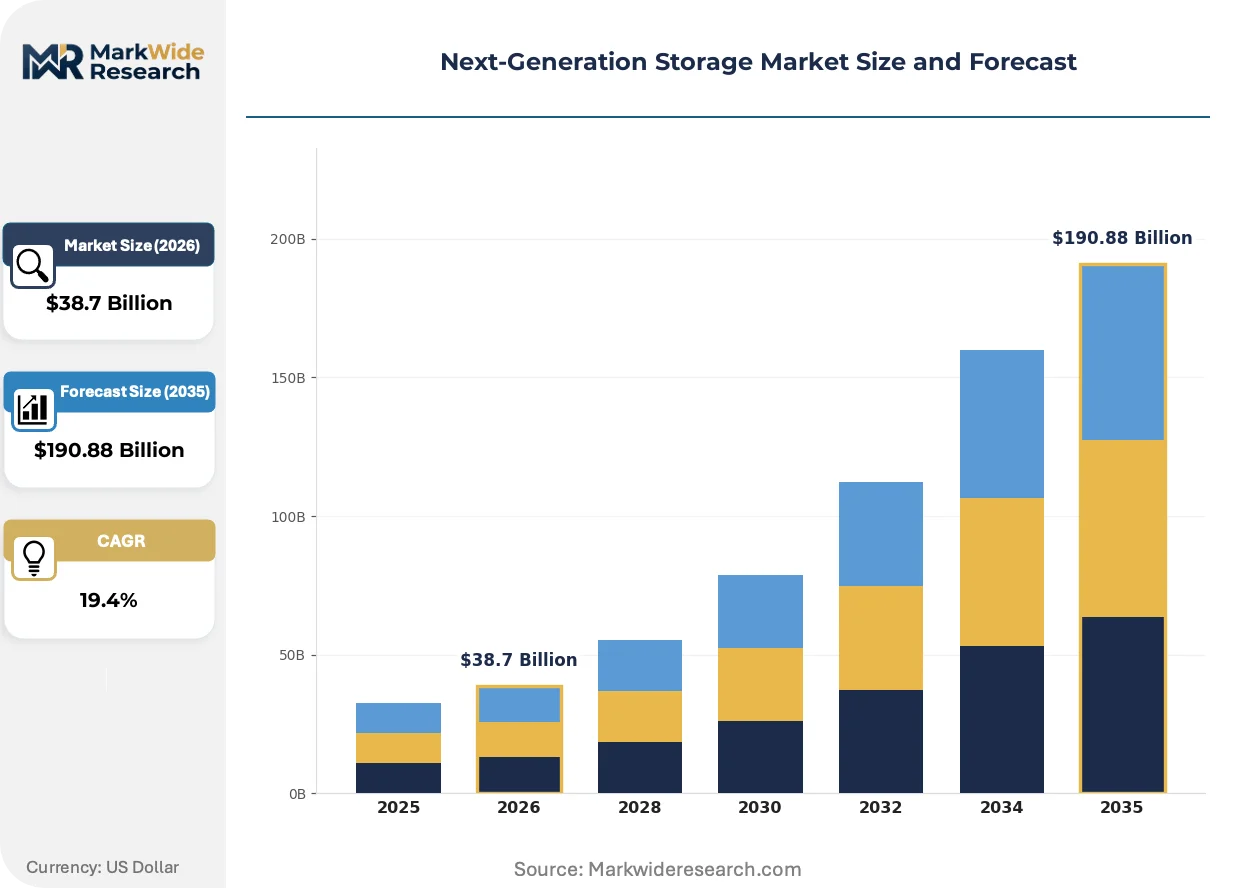
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $190.88 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hybrid Storage, SSD, Object Storage, Cloud Storage Technology: NAND Flash, 3D XPoint, NVMe, SATA End User: Enterprises, Data Centers, SMBs, Cloud Providers Application: Data Backup, Analytics, Virtualization, Machine Learning |
| Companies Covered | Dell Technologies, Hewlett Packard Enterprise, NetApp, IBM Corporation, Pure Storage, Hitachi Vantara, Huawei Technologies, DataDirect Networks, Micron Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Next-Generation Storage Market Strategic Shifts
Computational storage architectures are compressing the boundary between memory and processing, forcing vendors to reposition around data gravity rather than capacity metrics alone.
Computational storage processors with in-situ analytics engines are digitizing how raw NAND capacity transforms into queryable data structures without host CPU intervention. Financial services and autonomous vehicle developers are deploying these arrays for real-time fraud detection and sensor fusion workloads. This capability is digitizing the traditional storage tiering model by collapsing latency hierarchies into single-layer architectures.
EPA e-waste directives and EU CSRD circular design protocols are mandating hardware modularity and end-of-life material recovery across North American and European procurement. Vendors must now document embodied carbon per terabyte and provide disassembly instructions to qualify for enterprise tenders. Regulated verticals including healthcare and government are extending contract evaluation timelines to verify compliance documentation.
Consumption-based financing models are displacing capital purchase agreements as hyperscalers prefer operating expense treatment for storage infrastructure. Equipment lessors and cloud-adjacent financiers are capturing margin previously held by direct sales organizations. This shift is most visible in United States enterprise procurement, where CFO preference for balance sheet flexibility overrides traditional total-cost-of-ownership calculations.
Next-Generation Storage Market Segmentation
Storage procurement patterns diverge sharply across product architectures, interface technologies, and workload requirements. Each segmentation dimension reveals distinct margin structures and vendor qualification criteria that reshape competitive positioning.
Product Type:
Cost tier determines refresh cadence and total cost-of-ownership calculations across enterprise procurement committees.
- SSD:Solid-state drives built on NAND flash deliver sub-millisecond latency for primary storage tiers. Hyperscale operators in Northern Virginia and Dallas-Fort Worth are absorbing petabyte-scale NVMe-based SSD deployments to serve real-time analytics pipelines.
- Object Storage:Distributed architectures anchor archival and unstructured data lakes with erasure-coded durability. Mature margin profiles attract cloud providers managing exabyte-scale cold tiers for compliance and media archives.
- Hybrid Storage:Tiered arrays combine flash and mechanical media for regulated verticals requiring on-premises control with burst-to-cloud flexibility. Healthcare and financial services procurement favors these configurations.
- Cloud Storage:Consumption-based capacity with API-driven management abstracts underlying hardware from enterprise operators. CFO preference for operating expense treatment accelerates displacement of capital purchase agreements.
SSD commands the established base. The steepest expansion runs through Object Storage.
Technology:
Interface bandwidth and cell stacking density separate performance tiers across enterprise and hyperscale deployment models.
- NVMe:PCIe-based protocol eliminates SCSI translation overhead to unlock flash parallelism. Machine learning training pipelines demand NVMe over Fabrics for distributed GPU storage access.
- NAND Flash:3D TLC and QLC cell architectures balance endurance against cost-per-gigabyte for read-intensive workloads. Korean and Japanese foundry concentration creates input cost volatility during fab conversion cycles.
- 3D XPoint:Phase-change memory bridges DRAM and NAND latency hierarchies for persistent memory applications. Intel's discontinuation of Optane contracts the addressable market to specialized database acceleration.
- SATA:Legacy interface retains relevance in cost-sensitive SMB segments and secondary tier migrations where bandwidth requirements remain modest.
NAND Flash anchors volume shipments. NVMe is climbing the fastest as interface migration accelerates.
End User:
Customer scale dictates contracting models, support expectations, and customization requirements across the vendor base.
- Data Centers:Hyperscale and colocation operators specify commodity hardware with software-defined management. Procurement concentrates in United States corridors where FERC interconnection standards shape facility economics.
- Enterprises:Mid-to-large organizations balance performance SLAs against legacy integration requirements. EU CSRD disclosure mandates filter vendor shortlists toward circular design certification.
- Cloud Providers:Vertical integration into controller firmware and flash translation layers compresses supplier margins. These operators drive interface standardization through the NVM Express consortium.
- SMBs:Price-sensitive segments favor SATA-based appliances with bundled support contracts. Channel partners and managed service providers intermediate procurement decisions.
Enterprises retain the broadest installed base. Cloud Providers are expanding capacity fastest as AI infrastructure investment accelerates.
Application:
Latency tolerance and access patterns determine hardware specifications across primary, secondary, and archival tiers.
- Machine Learning:Training pipelines require randomized read throughput at petabyte scale. Computational storage processors with in-situ analytics collapse data movement overhead for sensor fusion and fraud detection workloads.
- Analytics:Columnar query engines drive sequential scan patterns favoring high-density QLC flash. Financial services and autonomous vehicle developers deploy these arrays for real-time decision support.
- Virtualization:Consolidated server environments demand consistent sub-millisecond response for VDI and container orchestration. VMware and Hyper-V certification requirements extend vendor qualification timelines.
- Data Backup:Immutable snapshots and air-gapped replication satisfy ransomware recovery mandates. Object storage with S3-compatible APIs dominates modern backup architecture.
Data Backup represents the most mature revenue stream. Machine Learning is gaining share fastest as AI infrastructure investment reshapes primary storage specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in United States hyperscale corridors where NVMe procurement volumes command vendor discounts, while European markets absorb compliance premiums from circular design mandates and carbon disclosure requirements.
United States
FERC grid interconnection standards and EPA e-waste directives filter vendor qualification pools across Northern Virginia and Dallas-Fort Worth data center clusters. Machine learning training pipelines from cloud providers absorb petabyte-scale NVMe deployments. The Northern Virginia corridor sustains the densest concentration of flash array procurement globally.
Germany
Battery supply chain due diligence rules and EU CSRD sustainability disclosure requirements extend contract evaluation timelines for storage hardware tenders. Industrial automation and automotive data lakes drive demand for hybrid arrays with burst-to-cloud failover. Bavaria hosts sovereign data center operators specifying circular design certification.
China
Domestic hyperscale operators and national cloud procurement pipelines favor indigenous controller architectures amid export control complexity. MIIT efficiency benchmarks and dual carbon goals accelerate displacement of mechanical hard drives in primary tiers. Yangtze River Delta data center construction absorbs QLC flash at scale.
Japan
METI energy efficiency standards and JIS circular economy protocols mandate hardware modularity for enterprise tenders. Financial services and precision manufacturing sectors deploy computational storage processors for real-time analytics. Tokyo-Osaka corridor concentration supports specialized systems integrator ecosystems for NVMe over Fabrics deployment.
South Korea
NAND flash foundry concentration creates input cost volatility that ripples through global procurement contracts during fab conversion cycles. MFDS data localization requirements and national cloud initiatives specify on-premises NVMe arrays with sovereign failover. Seoul Capital Area hyperscale facilities anchor regional demand for high-density flash.
Next-Generation Storage Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream with captive supply advantages. The vendor base separates into three strategic tiers: integrated hardware-software platforms, flash memory foundries with downstream controller capabilities, and pure-play software-defined architectures. Consolidation pressure runs through M&A activity targeting NVMe over Fabrics expertise and strategic partnerships securing NAND supply commitments.
Within the integrated platform tier, Dell Technologies and Hewlett Packard Enterprise occupy positions spanning hybrid cloud deployments, while Pure Storage exemplifies the software-defined specialist archetype. Huawei Technologies anchors domestic procurement pipelines in China amid Western trade restrictions. These three represent divergent competitive vectors: supply chain integration versus architectural abstraction versus geographic market capture.
| Leading Market Players |
|---|
| Dell Technologies |
| Hewlett Packard Enterprise |
| NetApp |
| IBM Corporation |
| Pure Storage |
| Hitachi Vantara |
| Huawei Technologies |
| DataDirect Networks |
| Micron Technology |
| Others |
Value Chain & Pricing Dynamics
Korean and Japanese NAND flash foundry concentration concentrates margin capture upstream, forcing array vendors to compete on controller firmware differentiation and software-defined management layers to defend downstream pricing power. Contract structures bifurcate between long-term offtake agreements locking in hyperscale volumes and spot-adjacent purchasing for enterprise refresh cycles, with FERC interconnection delays in Texas and Virginia compressing deployment windows and straining working capital for facility operators.
Pricing Analysis
Configured-to-order NVMe array pricing commands substantial premiums over standard catalog configurations, with customization depth around computational storage processor integration and AI-driven tiering algorithms separating premium tiers from commodity flash deployments. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with EU CSRD circular design certification and FERC efficiency compliance extending evaluation timelines and inflating procurement costs for qualified vendors. Cost compression in QLC-based cold tiers is intensifying because mechanical hard drive residual economics retain tape and HDD advantages for archival workloads, compressing all-flash pricing power at the bottom tier. SMB segments demonstrate highest price sensitivity, favoring SATA-based appliances with bundled support contracts, while cloud providers exhibit lowest sensitivity given operating expense preference and consumption-based financing models.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk matrices for advanced storage controllers, filtering vendor qualification pools and forcing architectural pivots toward indigenous controller designs in certain procurement pipelines. Manufacturing gravity centers on South Korea, Japan, and Taiwan for NAND flash fabrication, with 3D TLC and QLC cell architectures drawing from Korean and Japanese foundry capacity that experiences input cost volatility during fab conversion cycles. Raw material dependencies span silicon wafers, rare earth elements for controller chip packaging, and specialized substrates for PCIe interface cards. Single-source vulnerability concentrates in advanced controller ASICs subject to Western trade restrictions. Distribution runs through direct vendor sales organizations for hyperscale accounts, specialized systems integrators for NVMe over Fabrics deployments, and channel partners for SMB segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across cloud-native, hybrid, and sovereign deployment models creates niche opportunities for specialized architectures, with diverging technical specifications from hyperscalers versus regulated verticals opening competitive whitespace beyond integrated platform dominance.
For Market Incumbents: Pre-empt computational storage convergence by securing strategic partnerships with AI inference chip vendors, collapsing latency hierarchies before specialized edge processors capture queryable data structure margins. Defend against Pure Storage's software-defined abstraction by deepening controller firmware integration and accelerating circular design certification to meet EU CSRD and Germany battery supply chain due diligence mandates. Capacity addition in Northern Virginia and Dallas-Fort Worth corridors sustains hyperscale relationship density. For New Entrants and Emerging Players: Pursue sovereign data center procurement in France and Italy, where national cloud operators specify on-premises NVMe arrays with burst-to-cloud failover and lack incumbent relationship lock-in. Target healthcare and financial services hybrid storage configurations, where regulated verticals require on-premises control and incumbent refresh cycles create replacement windows. Go-to-market through specialized systems integrators with NVMe over Fabrics expertise, bridging skill scarcity that limits enterprise self-deployment. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed software-defined storage specialists possessing NVMe over Fabrics expertise but lacking captive NAND supply commitments. Long-term viability favors vendors with architectural abstraction capabilities decoupled from hardware refresh economics, positioned for consumption-based financing model expansion. Watch hyperscaler vertical integration into controller firmware and flash translation layers as inflection signal compressing supplier margins and triggering consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Computational Storage Processor Integration | Collapses data movement overhead for sensor fusion and fraud detection workloads in financial services. |
| Circular Design Certification Investment | Qualifies vendors for EU CSRD and Germany battery supply chain due diligence procurement mandates. |
| NVMe over Fabrics Partnership | Addresses skill scarcity limiting enterprise self-deployment through specialized systems integrator channels. |
| Consumption-Based Financing Model | Captures CFO preference for operating expense treatment displacing capital purchase agreements. |
| Indigenous Controller Architecture Development | Navigates export control complexity limiting Western vendor qualification in China domestic procurement. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, with data center infrastructure executives, storage procurement officers at hyperscale operators, NVMe over Fabrics systems integrators, and circular design certification auditors contributing qualitative intelligence. Secondary validation drew from SEC filings of publicly traded storage vendors, hyperscaler capex disclosures, FERC interconnection queue data, and EU CSRD regulatory documentation. Bottom-up unit economics triangulated against top-down market sizing across product type, technology, end user, and application segmentation dimensions.
Calibration against historical refresh cycle patterns and observed hyperscale deployment timelines anchored growth trajectory assumptions across the analysis window. Segmentation modeling incorporated interface technology migration rates, workload-specific latency requirements, and regional regulatory framework variations. CAGRs derived from slope analysis of technology adoption curves and substitution dynamics between flash and mechanical storage tiers. Industry-specific forecast inputs included NAND fab conversion schedules and GPU cluster storage attachment ratios from machine learning training pipeline operators.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cloud providers into vertical controller integration or specialized edge processor vendors into computational storage convergence would shift outcomes beyond modeled parameters. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
Holographic Versatile Disc (HVD) Market
Data Storage
External Storage Market
Data Storage
Global Personal and Entry Level Storage (PELS) Market
Data Storage
Middle East and Africa SSD Caching Market
Data Storage
All Flash Storage Market
Data Storage
Solid State Drive (SSD) Market
Data Storage
China Solid-State Drive Market
Data Storage
Ireland Data Center Storage Market
Data Storage
Enterprise Flash Storage Market
Data Storage
Asia-Pacific Data Center Storage Market
Data Storage
Enterprise-Class Hybrid Storage Market
Data Storage
Archival Grade Blu-Ray Discs Market
Data Storage
Hybrid Flash Storage Market
Data Storage
Global Portable Data Storage Market
Data Storage
SSD Controller Market
Data Storage
North America Next Generation Storage Market