
 Intelligent Electronic Devices Market | 2026-2036
Intelligent Electronic Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Intelligent Electronic Devices Market Intelligence
Asian semiconductor foundry capacity is shifting toward automotive-grade and industrial microcontrollers that power intelligent electronic devices. Schneider Electric leverages its European manufacturing base to sustain leadership in substation automation controllers. ABB Ltd. anchors its competitive position through deep specialization in protective relay systems for high-voltage networks. Siemens Corporation dominates the digital twin integration layer, where software-defined control merges with hardware-level circuit protection.
Intelligent electronic devices are microprocessor-enabled apparatus designed to monitor, control, and protect electrical infrastructure with response times measured in milliseconds and communication latency below four milliseconds. These devices execute fault detection, load balancing, and remote telemetry for power distribution and smart grid operations. Protective relays command the highest margin pools within the product type dimension due to their safety-critical certification requirements and long replacement cycles. Microprocessor-based technology leads the technology dimension, displacing analog architectures as utilities mandate IEC 61850 protocol compliance and edge-computing capability. Smart grid application segments are expanding fastest, driven by bidirectional power flows from distributed solar and battery storage assets.
The Federal Energy Regulatory Commission enforces grid reliability standards that mandate intelligent electronic device deployment for bulk power system protection across the United States. In Europe, the EU Green Deal and F-Gas Regulation are accelerating replacement of legacy switchgear with intelligent, low-emission protection systems that integrate real-time emissions monitoring. China's MIIT and GB standards bodies enforce domestic cybersecurity certification for grid-connected intelligent devices, creating market access conditions distinct from IEC frameworks. Stakeholders must decide whether to pursue multi-certification strategies or accept geographic segmentation of their product portfolios as regulatory divergence deepens.
Market Dynamics
IEC 61850 protocol adoption is forcing a wholesale replacement cycle across utility protection networks, as legacy analog architectures lose certification eligibility under modern grid reliability mandates.
Growth Catalysts
- China's dual carbon policy framework:National decarbonization targets mandate smart grid infrastructure deployment, accelerating intelligent electronic device procurement across state-owned transmission networks.
- Protective relay certification requirements:Safety-critical SIL ratings create durable demand for specialized microprocessor-based units with decade-long replacement cycles.
- Distributed energy resource integration:Bidirectional power flows from solar and battery assets require real-time monitoring capabilities that only intelligent electronic devices provide.
Market Restraints
- Automotive-grade semiconductor allocation:Foundry capacity prioritization toward vehicle electrification creates input scarcity for industrial microcontroller production.
- Asian foundry concentration:Taiwan and South Korea control advanced node production, exposing supply chains to geographic concentration risk.
- Cybersecurity certification fragmentation:China's GB standards diverge from IEC frameworks, forcing redundant testing and compliance costs.
Strategic Opportunities
- Edge-computing convergence with 5G private networks:Ultra-low latency communication enables predictive maintenance applications previously requiring centralized SCADA infrastructure.
- EU Green Deal switchgear replacement incentives:F-Gas Regulation penalties accelerate migration from sulfur hexafluoride-dependent protection systems to intelligent low-emission alternatives.
- Rural electrification programs in India:Central Electricity Authority mandates for smart distribution transformers create untapped demand for cost-optimized intelligent electronic devices.
Industry Challenges
- IEC 61850 engineering talent scarcity:Protocol specialization requirements exceed available utility workforce training pipelines, extending deployment timelines.
- Legacy substation integration complexity:Brownfield retrofit projects face interoperability failures between new intelligent devices and decades-old electromechanical protection schemes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intelligent Electronic Devices Market |
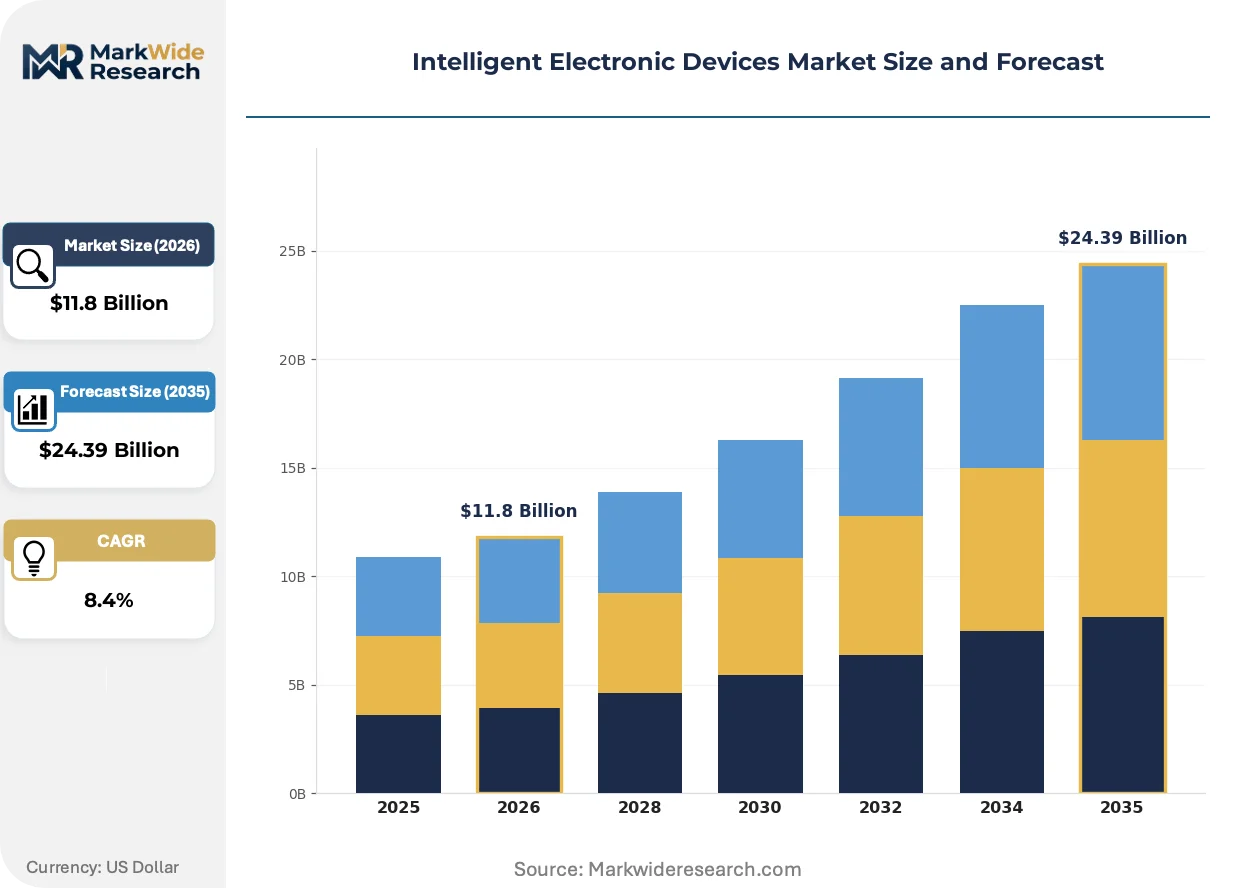
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $24.39 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Relays, Circuit Breakers, Sensors, Meters, Controllers Technology: Microprocessor-Based, Digital, Analog, Hybrid, Wireless Application: Power Distribution, Smart Grid, Automation, Substation Protection, Load Management End User: Utilities, Renewable Operators, Mining Firms, Manufacturing Plants, Data Centers |
| Companies Covered | Siemens Corporation, Schneider Electric, ABB Ltd., Eaton Corporation, Honeywell International, Cisco Systems, Rockwell Automation, Black & Veatch, SUBNET Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intelligent Electronic Devices Market Strategic Shifts & Innovations
Digital twin architectures are merging software-defined control with hardware-level circuit protection, collapsing the traditional separation between operational technology and information technology layers.
Time-sensitive networking extensions to IEC 61850-9-3 are rewriting synchronization requirements for sampled value transmission, enabling merged unit architectures that combine multiple protection functions on single hardware platforms. Transmission utilities in Germany and Japan are piloting these consolidated designs to reduce substation footprint and maintenance burden. The technology is compressing vendor margins by eliminating redundant device categories previously sold as separate product lines.
The EU AI Act's risk classification framework is reshaping procurement specifications for autonomous fault-detection algorithms embedded in protective relays. High-risk system designations now mandate human-in-the-loop validation for certain grid protection decisions, forcing firmware architecture revisions. European transmission system operators are responding by demanding explainable AI documentation from suppliers before contract award.
Performance-based service contracts are displacing traditional hardware-plus-maintenance agreements in Nordic utility procurement. Vendors now guarantee availability metrics and response-time thresholds rather than selling discrete devices, transferring operational risk to manufacturers. Finland and Norway lead this shift, with their national grid operators unbundling capital expenditure from operational technology lifecycle management.
Intelligent Electronic Devices Market Segmentation
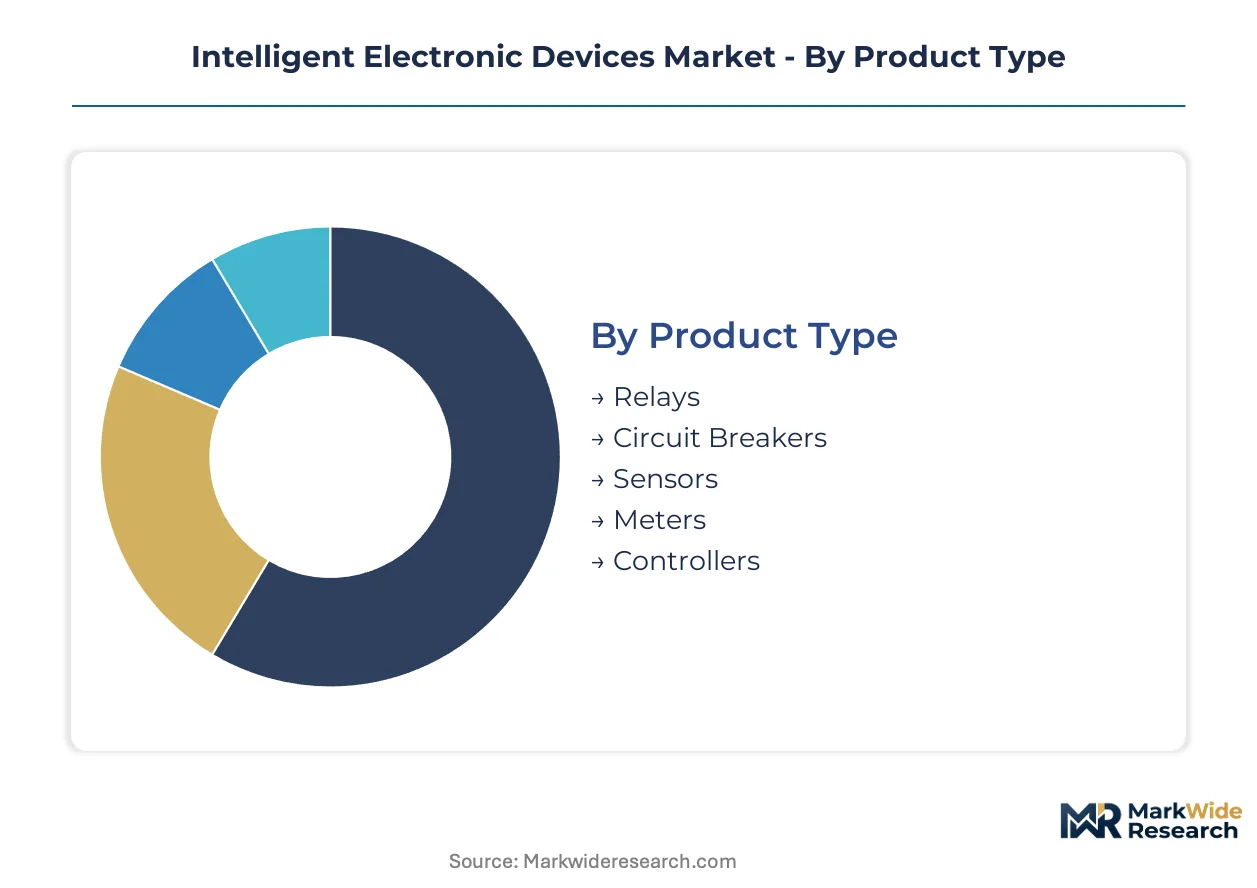
Intelligent electronic devices serve distinct protection and control functions across electrical infrastructure, with certification requirements varying sharply by deployment environment. Segmentation reveals how IEC 61850 compliance, SIL safety ratings, and cybersecurity mandates reshape procurement patterns across product categories.
Product Type:
Certification burden concentrates heaviest in protective functions where SIL ratings and fault-response validation determine market access. Relays and circuit breakers carry the most stringent third-party testing requirements, while meters and sensors face lighter conformity assessment pathways.
- Relays:Microprocessor-enabled units execute fault detection and isolation commands within four-millisecond windows. Demand clusters in high-voltage transmission networks across Germany and Japan where merged-unit architectures reduce substation footprint. IEC 61850-9-3 time-sensitive networking compliance now mandatory for new procurement.
- Circuit Breakers:Intelligent trip units integrate real-time current monitoring with programmable protection curves. China's state-owned grid operators drive volume procurement under dual carbon infrastructure mandates, though GB cybersecurity certification adds six-month approval delays versus IEC-only pathways.
- Sensors:Merged unit designs combine multiple measurement functions on single hardware platforms.
- Meters:Revenue-grade accuracy certification required for utility billing applications.
- Controllers:Substation automation units coordinate multiple protection devices through station bus architectures.
Leading the category by volume: Relays. Growing fastest: Circuit Breakers.
Technology:
Cost tier separation runs deepest between legacy analog architectures and microprocessor-based platforms, with hybrid designs occupying a narrowing middle band as utilities mandate full digital protocol compliance.
- Microprocessor-Based:Edge-computing capability enables local analytics without SCADA dependency. Nordic utilities in Finland and Norway prioritize these units for performance-based service contracts where vendors guarantee availability metrics.
- Digital:Fixed-function DSP architectures deliver deterministic response times at lower unit cost than full microprocessor platforms.
- Analog:Electromechanical designs face certification ineligibility under modern grid reliability mandates.
- Hybrid:Mixed-signal approaches bridge legacy substation retrofit requirements.
- Wireless:5G private network integration enables predictive maintenance applications without fiber deployment.
Highest margin tier: Microprocessor-Based. Steepest decline trajectory: Analog.
Application:
Customer type differentiation separates capital-intensive transmission utilities from distributed asset operators with divergent procurement cycles and technical specifications.
- Smart Grid:Bidirectional power flow monitoring for solar and battery storage integration. India's Central Electricity Authority mandates drive cost-optimized device procurement for rural distribution transformer deployments.
- Substation Protection:Safety-critical fault clearing with decade-long replacement cycles.
- Power Distribution:Feeder automation and sectionalizing for outage management.
- Automation:Process control integration for industrial electrical systems.
- Load Management:Demand response coordination for grid stability services.
Fastest application expansion: Smart Grid. Most mature procurement segment: Substation Protection.
End User:
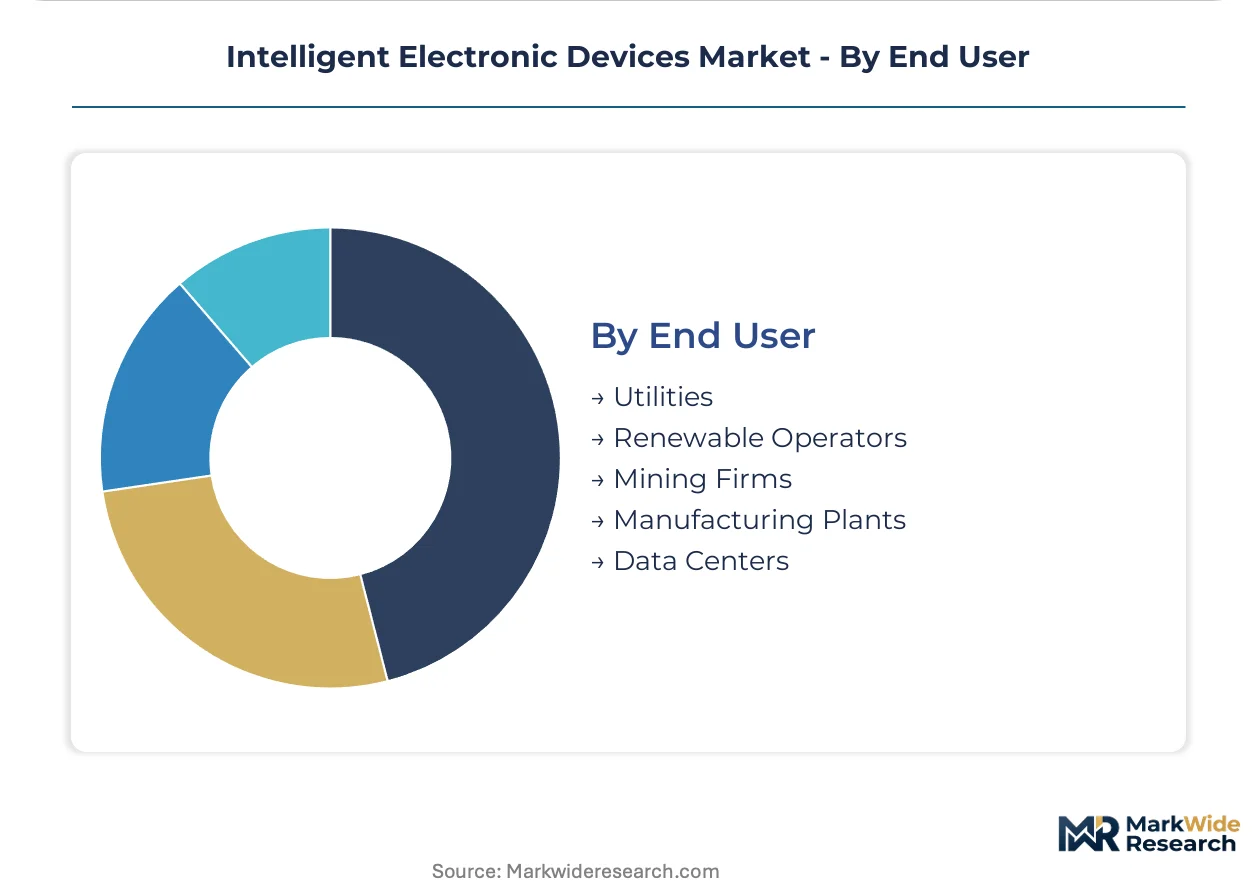
Geographic concentration of demand varies by end user category, with utilities anchoring procurement in established markets while renewable operators drive growth in emerging installations.
- Utilities:Transmission and distribution operators with standardized IEC 61850 procurement specifications. European TSOs now demand explainable AI documentation for autonomous fault-detection algorithms under EU AI Act risk classifications.
- Renewable Operators:Solar and wind farm developers requiring grid-code compliance certification.
- Mining Firms:Harsh-environment durability requirements for remote extraction operations.
- Manufacturing Plants:Power quality monitoring for sensitive industrial processes.
- Data Centers:Uptime Institute tier certification drives redundant protection system investment.
Volume anchor: Utilities. Fastest-growing customer type: Renewable Operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon foundry capacity in Taiwan and South Korea anchors the semiconductor substrate supply for intelligent electronic devices. Grid modernization mandates across Germany, China, Japan, India, and the United States are redistributing procurement volume toward these manufacturing centers.
China
State Grid Corporation procurement under dual carbon infrastructure targets drives volume demand for protective relays and circuit breakers. MIIT and GB standards bodies enforce domestic cybersecurity certification, creating six-month approval delays versus IEC-only pathways. Yangtze River Delta manufacturing clusters around Shanghai produce merged-unit architectures for transmission substation deployment.
Germany
Transmission system operators pilot time-sensitive networking extensions under IEC 61850-9-3 for consolidated protection functions. EU AI Act risk classifications mandate explainable AI documentation for autonomous fault-detection algorithms in protective relays. Industrial automation corridors in Bavaria and Baden-Württemberg host substation automation controller development facilities.
United States
FERC grid reliability standards mandate intelligent electronic device deployment for bulk power system protection across transmission networks. Infrastructure Investment and Jobs Act funding accelerates rural cooperative procurement for distribution automation. Texas ERCOT grid operators drive demand for real-time monitoring amid renewable integration challenges.
Japan
METI strategic energy plan targets smart grid infrastructure investment to accommodate distributed solar and battery storage assets. JIS standards alignment with IEC 61850 facilitates technology transfer from domestic automation specialists. Kansai region utilities around Osaka deploy merged-unit architectures to reduce urban substation footprint.
India
Central Electricity Authority mandates for smart distribution transformers create procurement opportunities for cost-optimized intelligent electronic devices. PLI scheme incentives for domestic manufacturing attract component assembly investments. Gujarat and Maharashtra industrial corridors concentrate renewable project development requiring grid-code compliant protection systems.
Intelligent Electronic Devices Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue edge-computing integration and AI-enabled predictive maintenance. The market structure consolidates around electrical equipment conglomerates with captive semiconductor sourcing relationships. Three archetypes dominate: integrated automation platforms, specialized protective relay manufacturers, and communications infrastructure specialists. Competitive moves center on digital twin software acquisitions and 5G private network partnership formations.
Within the integrated platform tier, Siemens Corporation and Schneider Electric represent archetypal positions spanning hardware control systems through software-defined automation layers. ABB Ltd. exemplifies the protective relay specialization archetype with deep anchoring in high-voltage network applications. These three entities collectively illustrate how vendor strategies diverge between full-stack integration and vertical depth in safety-critical protection functions.
| Leading Market Players |
|---|
| Siemens Corporation |
| Schneider Electric |
| ABB Ltd. |
| Eaton Corporation |
| Honeywell International |
| Cisco Systems |
| Rockwell Automation |
| Black & Veatch |
| SUBNET Solutions |
| Others |
Cost & Logistics Intelligence
China's MIIT cybersecurity certification mandates force six-month approval delays for IEC-only devices, compelling suppliers to absorb redundant testing costs or surrender price competitiveness in state-owned grid procurement. This demand-side regulatory fragmentation compresses margins on merged-unit architectures while rewarding vendors with captive GB-compliant engineering capacity.
Pricing Analysis
Warranty and predictive maintenance service bundling now separates premium relay vendors from transactional hardware suppliers. Three-tier pricing structure across premium, standard, and economy levels reflects SIL certification grade and edge-computing capability. Cost compression in economy-tier microprocessor units intensifies because automotive-grade semiconductor allocation diverts foundry capacity. Distribution utilities exhibit highest price sensitivity; transmission system operators prioritize availability guarantees over unit cost.
Supply Chain Analysis
Freight cost volatility from Asian manufacturing clusters to European substation sites amplifies landed cost differentials for protective relay systems. Supply concentrates in Taiwan and South Korea for advanced microcontroller fabrication, with Yangtze River Delta assembly for merged-unit integration. Raw material dependencies span automotive-grade silicon wafers, rare-earth magnetics for current sensors, and epoxy resins for harsh-environment encapsulation. Single-source vulnerability in 300mm wafer supply exposes lead times to geographic concentration risk. Distribution runs through authorized electrical distributor networks with factory-trained engineering support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around vendors with captive semiconductor sourcing and multi-certification engineering capacity, as IEC 61850 protocol complexity and cybersecurity fragmentation eliminate pure-play hardware assemblers.
For Market Incumbents: Cement leadership in protective relay systems through backward integration into automotive-grade microcontroller supply chains, insulating against foundry allocation shifts. Acquire edge-computing software specialists to collapse OT-IT separation before digital twin architectures commoditize hardware margins. Defend against communications infrastructure specialists encroaching on station bus architectures by embedding 5G private network modules in next-generation controller designs. For New Entrants and Emerging Players: Regional system integrators in India's Gujarat and Maharashtra industrial corridors offer the most penetrable channel for cost-optimized circuit breaker controllers under Central Electricity Authority smart transformer mandates. Target rural electrification procurement where incumbent engineering support networks remain thin. Pursue white-label manufacturing partnerships with Yangtze River Delta assembly facilities to bypass GB certification timeline disadvantages. For Investors and Strategic Acquirers: Re-rating potential sits with protective relay specialists possessing SIL-4 validation archives and explainable AI firmware architectures given EU AI Act risk classification enforcement. Long-term viability favors vendors with demonstrated multi-protocol engineering capacity spanning IEC 61850-9-3 time-sensitive networking and China's GB/T standards. Watch Nordic utility adoption of performance-based service contracts as the inflection signal for outcome-based revenue model validation.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Software Acquisition | Siemens Corporation's software-defined control layer merges predictive analytics with hardware protection. |
| 5G Private Network Partnership | Ultra-low latency communication enables predictive maintenance without centralized SCADA infrastructure. |
| Multi-Certification Engineering Investment | Dual IEC 61850 and GB pathway capacity unlocks State Grid procurement under dual carbon mandates. |
| Edge-Computing Capability Integration | Local analytics without SCADA dependency differentiates microprocessor-based units for Nordic utilities. |
| Protective Relay SIL Validation Archive | Decade-long replacement cycles and safety-critical certification create durable margin pools. |
Research Approach
SEC 10-K filings, FERC grid reliability compliance databases, and IEC standards documentation formed the secondary backbone for market sizing validation. Primary interviews with utility protection engineers, substation automation procurement officers, and semiconductor distribution channel managers triangulated against customs records and transmission operator capital expenditure disclosures. Bottom-up unit shipment estimates across relay, circuit breaker, and controller categories reconciled with top-down grid modernization budget allocations.
Historical trendline analysis of protective relay replacement cycles and smart grid infrastructure deployment rates anchored the projection framework. Segmentation modeling spanned product type, technology architecture, application environment, and end-user procurement authority across the analysis window. CAGR derivation incorporated foundry capacity allocation forecasts, regulatory certification timeline assumptions, and distributed energy resource integration penetration curves. Microcontroller supply constraints and cybersecurity compliance cost trajectories served as industry-specific forecast inputs.
Caveats apply where automotive-grade semiconductor allocation priorities or GB-IEC regulatory divergence could materially shift the outlook. Forecasts reflect assumptions about dual carbon policy continuity, time-sensitive networking adoption velocity, and edge-computing capability maturation. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Devices & Electrical Systems
Printed Electronics Devices Market
Electronic Devices & Electrical Systems
Global Hybrid Devices Market
Electronic Devices & Electrical Systems
High Current Springs Market
Electronic Devices & Electrical Systems
Portable Charger Market
Electronic Devices & Electrical Systems
Rugged Handheld Electronic Devices Market
Electronic Devices & Electrical Systems
Digital Instrument Clusters Market
Electronic Devices & Electrical Systems
Electronic Weighing Machines Market
Electronic Devices & Electrical Systems
Digital Devices Technologies Market
Electronic Devices & Electrical Systems
Electronic Skin Market
Electronic Devices & Electrical Systems
Global Sequence of Events Recorder Market
Electronic Devices & Electrical Systems
Electrical and Electronic Computer-Aided Design (ECAD) Market
Electronic Devices & Electrical Systems
Workstation Market
Electronic Devices & Electrical Systems
Global Automotive Electronic Devices Market
Electronic Devices & Electrical Systems
Blu-Ray Media and Devices Market
Electronic Devices & Electrical Systems
Electronic Load Market
Electronic Devices & Electrical Systems
Global Volt/VAR Management Market