
 Object-Based Storage Market | 2026-2036
Object-Based Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Object-Based Storage Market Analytics
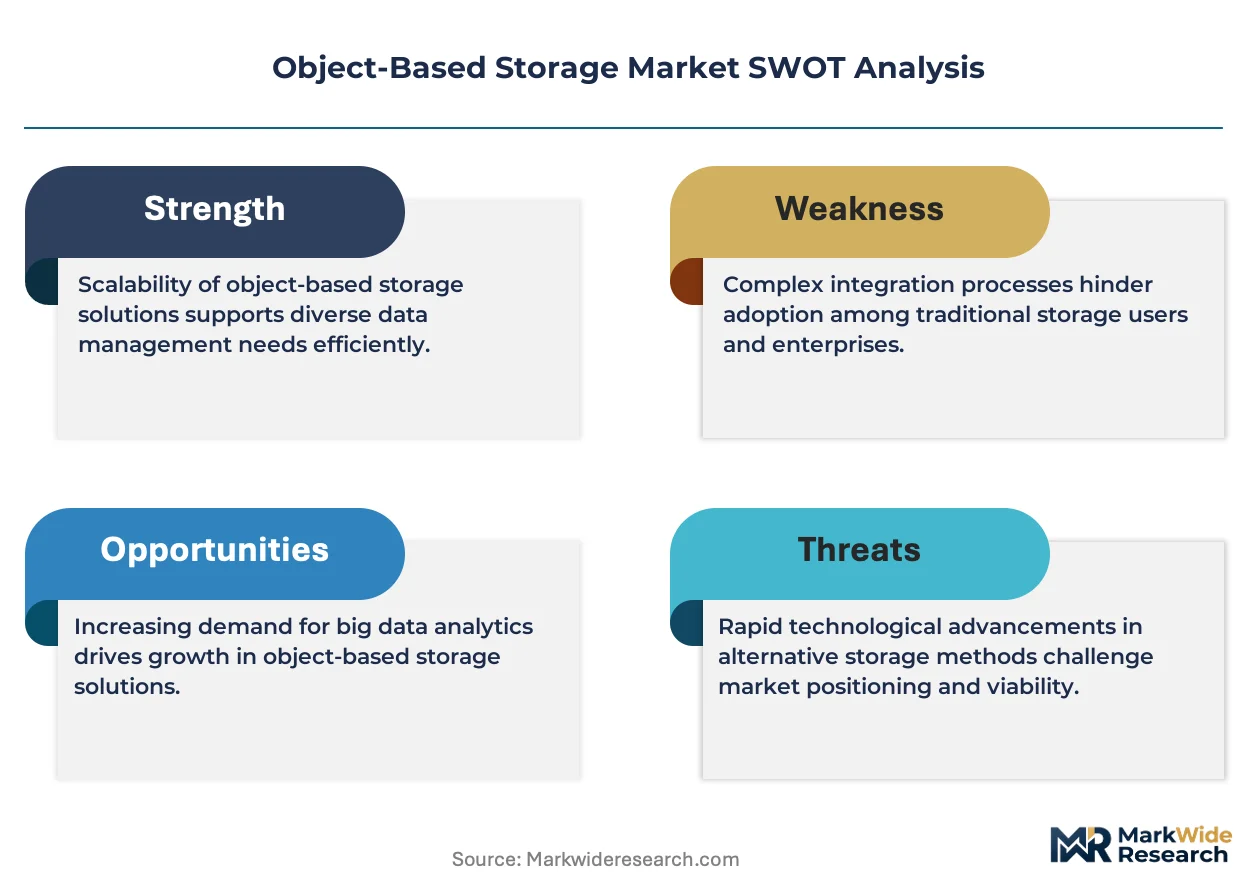
The object-based storage landscape is pivoting on a widening gap between premium erasure-coded enterprise tiers and commodity archival nodes optimized for cold data economics. Dell Technologies leverages its integrated hardware-software stack to anchor high-performance deployments in regulated verticals. Scality specializes in software-defined architectures that compete on deployment flexibility across hybrid cloud footprints. IBM Corporation sustains mainframe-adjacent object protocols that dominate legacy financial infrastructure migrations.
Object-based storage organizes data as discrete units with metadata-rich addressing rather than hierarchical file paths, typically distributing objects across nodes with redundancy schemes such as Reed-Solomon erasure coding at 10+4 or 16+4 configurations for durability exceeding eleven nines. This architecture serves primary commercial purposes in unstructured data lakes, video content repositories, and machine learning feature stores where linear scalability outweighs latency sensitivity. Hybrid cloud deployment models lead adoption as enterprises retain sensitive payloads on-premises while bursting analytics workloads to public infrastructure. Big data analytics applications capture the fastest expansion trajectory as vector databases and real-time inference pipelines consume object-native formats. Content distribution remains a mature margin pool where established delivery networks optimize existing footprints rather than greenfield buildouts.
GDPR data-localization provisions enforced by European national regulators, HIPAA security rule oversight from HHS in the United States, and China's MEE cybersecurity review protocols for critical information infrastructure collectively reshape product roadmaps toward geo-fenced replication and encryption-at-rest certifications. ISO 27001 and SOC 2 Type II attestations function as baseline market-access credentials for vendor procurement shortlists across enterprise and government segments. Stakeholders must weigh jurisdictional compliance overhead against latency economics when selecting primary object storage regions for AI and analytics workloads.
Market Dynamics
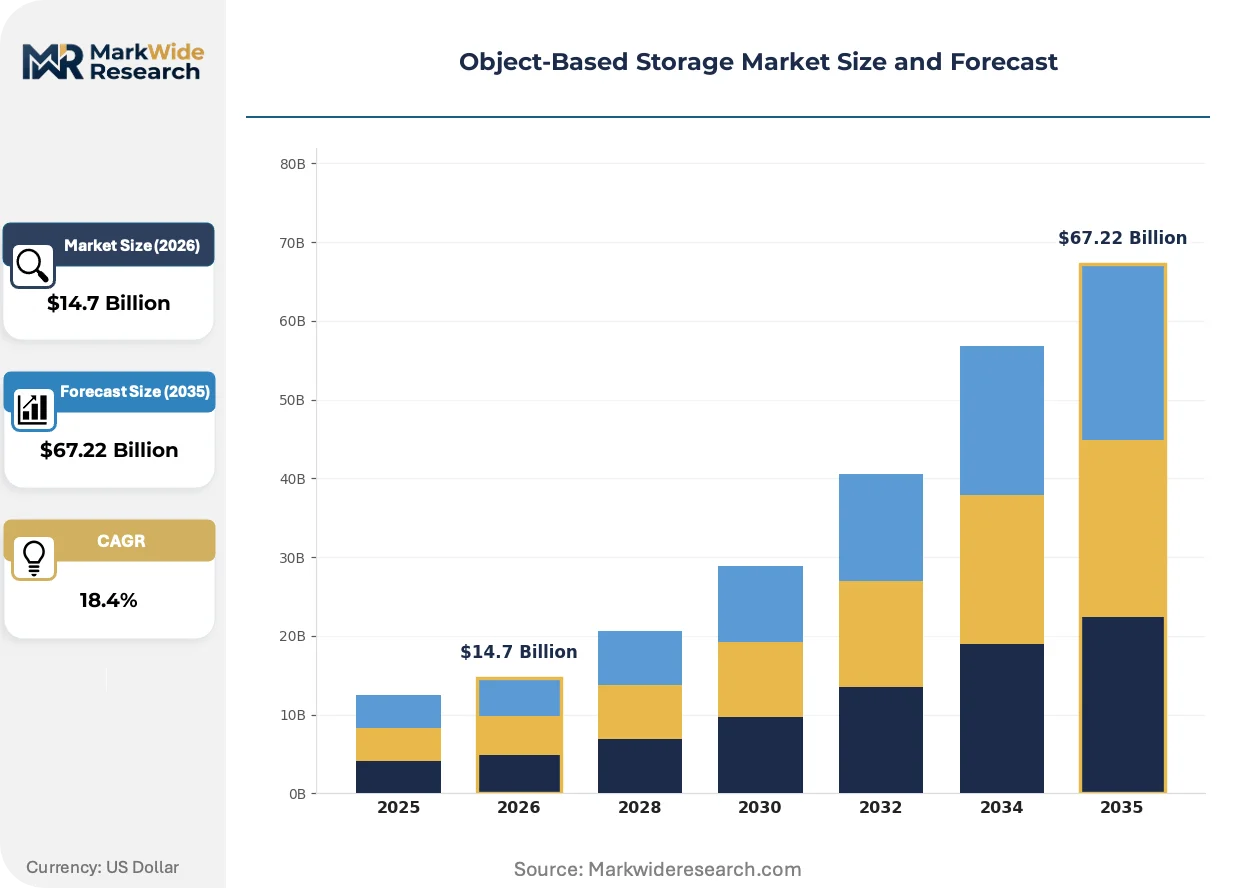
Petabyte-scale AI training pipelines and media streaming architectures are compressing deployment cycles for object storage infrastructure, forcing vendors to reconcile latency economics with jurisdictional data sovereignty mandates.
Growth Catalysts
- GDPR localization mandates:European national regulators enforce data-residency requirements that compel enterprises to deploy geo-fenced object repositories, expanding hardware footprints across Germany, France, and the Netherlands.
- Vector database proliferation:Machine learning feature stores and real-time inference pipelines consume object-native formats, pulling storage demand from financial services and autonomous vehicle development clusters.
- Hyperscaler region expansion:Cloud providers accelerate buildouts in the United States, China, and Germany, anchoring demand for high-durability erasure-coded tiers in regulated verticals.
Market Restraints
- Silicon supply concentration:Advanced storage controllers and high-bandwidth memory modules depend on Taiwanese and South Korean fabrication capacity, exposing procurement timelines to geopolitical friction.
- Energy cost volatility:Petabyte-scale deployments face power-density constraints in European and North American data center markets where electricity tariffs fluctuate with grid decarbonization mandates.
- Erasure coding overhead:Reed-Solomon 16+4 configurations impose computational penalties that limit adoption in latency-sensitive transactional workloads, preserving block storage dominance in OLTP environments.
Strategic Opportunities
- India's data localization framework:The country's central bank and telecom regulator impose strict cross-border data restrictions, creating greenfield demand for domestic object storage infrastructure serving fintech and e-commerce platforms.
- Healthcare AI pipelines:HIPAA-compliant imaging archives and genomic sequencing repositories represent underpenetrated workloads where object-native formats displace legacy PACS architectures.
- Edge-to-core convergence:5G MEC deployments and industrial IoT sensor networks require tiered storage hierarchies that synchronize cold archival nodes with warm edge caches.
Industry Challenges
- Distributed systems engineering scarcity:Vendor hiring pipelines strain to source talent capable of optimizing consistency models across eventually consistent object namespaces.
- ISO 27001 certification timelines:Enterprise procurement shortlists demand current attestations, compressing vendor sales cycles and inflating compliance overhead for mid-tier competitors.
- Mainframe protocol integration:Legacy financial infrastructure migrations stall on API translation complexity between IBM COS protocols and modern S3-compatible interfaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Object-Based Storage Market |
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $67.22 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises End User: Enterprises, SMBs, Government, Educational Institutions Application: Backup & Recovery, Data Archiving, Content Distribution, Big Data Analytics Service Type: Storage as a Service, Managed Services, Consulting Services, Integration Services |
| Companies Covered | Dell Technologies, IBM Corporation, NetApp, Hewlett Packard Enterprise, Hitachi Vantara, Amazon Web Services, Scality, Oracle Corporation, Microsoft Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Object-Based Storage Market Evolving Landscape
Storage architectures are bifurcating between performance-optimized tiers for active analytics and deep archival nodes for compliance-driven retention, with automation threading through both paths.
Policy-driven lifecycle management is automating data placement across hot, warm, and cold storage tiers based on access-pattern predictions and regulatory retention schedules. Financial services firms in Frankfurt and Singapore deploy these engines to preempt GDPR and MEE audit triggers. The compression of manual tiering decisions is reallocating storage administrator capacity toward security posture management.
REACH chemical restrictions and EU AI Act documentation requirements are mandating granular provenance tracking for training datasets stored in object repositories. German automotive manufacturers and French pharmaceutical firms must now maintain immutable audit trails linking model inputs to specific storage objects. This regulatory layering is accelerating adoption of WORM-compliant object classes with cryptographic verification.
Consumption-based billing models are displacing capacity-purchase contracts across enterprise procurement desks. Buyers in the United States and China increasingly demand metered egress pricing aligned with actual query volumes rather than provisioned petabytes. This behavioral shift pressures vendor margin structures while favoring software-defined architectures with granular usage telemetry.
Object-Based Storage Market Segmentation
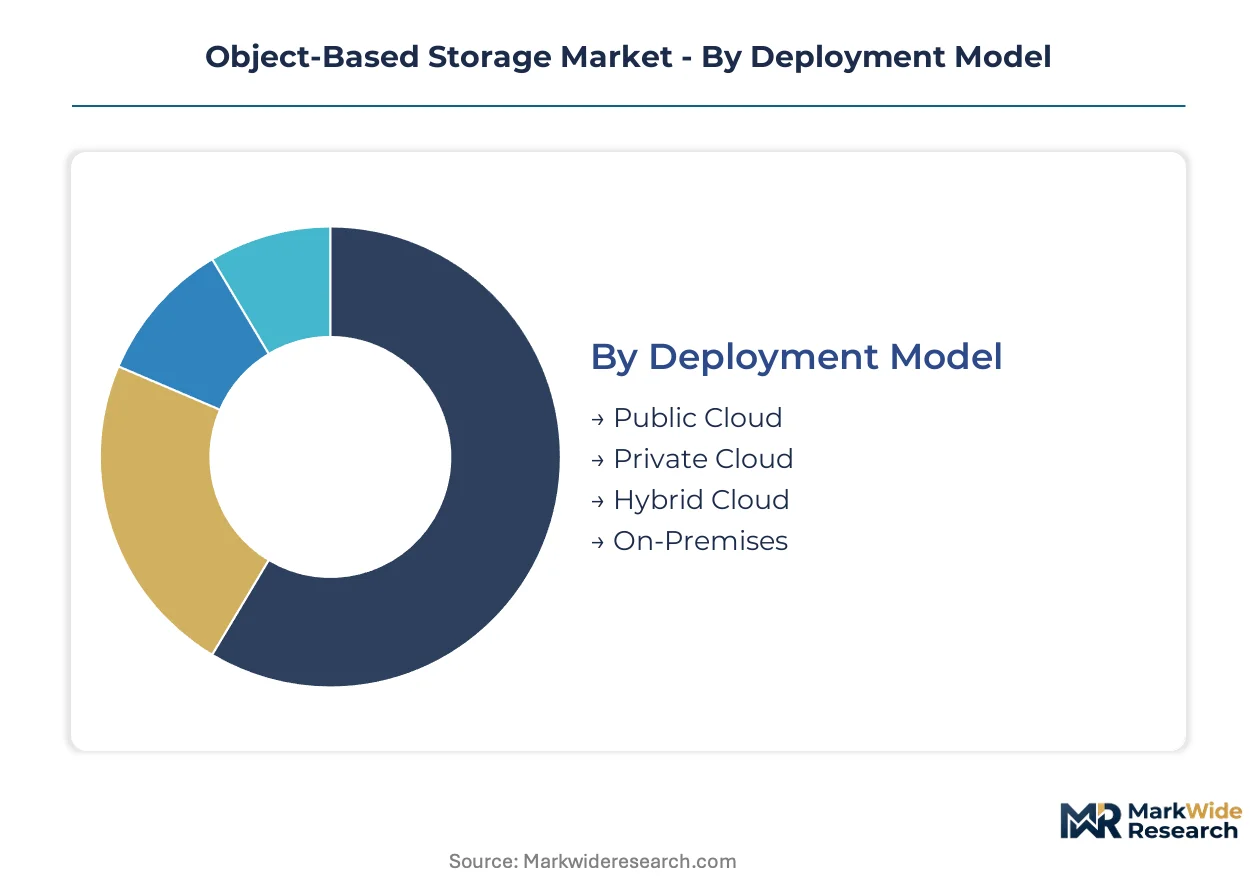
Object-based storage architectures diverge sharply across deployment topologies, customer scale, workload patterns, and service delivery models. Each segmentation axis reveals distinct margin structures, procurement cycles, and vendor competitive advantages that reshape go-to-market positioning.
Deployment Model:
Latency tolerance, data sovereignty exposure, and capital efficiency trade-offs define how enterprises distribute object storage across infrastructure layers.
- Public Cloud:Hyperscaler object services deliver elastic petabyte scaling without hardware procurement cycles. Media streaming platforms and AI training pipelines in the United States and China anchor demand for S3-compatible APIs with cross-region replication. Cloud providers absorb infrastructure risk while metering egress fees compress margins for high-throughput workloads.
- Hybrid Cloud:Enterprises retain sensitive payloads on-premises while bursting analytics to public infrastructure, reconciling GDPR localization mandates with compute elasticity. Financial services clusters in Frankfurt and Singapore deploy tiered policies that automate data placement across jurisdictional boundaries. Procurement desks favor this model for regulatory flexibility despite API translation complexity.
- Private Cloud:Dedicated object clusters serve classified government workloads and proprietary AI model training where multi-tenancy risks are unacceptable. Defense contractors and pharmaceutical manufacturers in Germany and France absorb premium hardware costs for air-gapped environments.
- On-Premises:Legacy data center footprints persist in regulated verticals with decade-old depreciation schedules and mainframe protocol dependencies. IBM COS installations in banking infrastructure exemplify migration friction toward modern S3 interfaces.
Hybrid Cloud leads on scale; Public Cloud leads on momentum.
End User:
Procurement sophistication and compliance burden intensity segment buyer behavior across organizational scale.
- Enterprises:Global 2000 firms negotiate multi-year enterprise license agreements with stringent ISO 27001 and SOC 2 Type II attestation requirements. Vector database deployments for machine learning feature stores drive petabyte-scale expansion in autonomous vehicle development and quantitative trading clusters.
- SMBs:Mid-market buyers consume object storage through bundled SaaS offerings with limited direct infrastructure visibility. Backup and archival use cases dominate as IT teams lack specialized storage engineering capacity.
- Government:Federal and state agencies mandate FIPS 140-2 encryption and domestic data residency, creating captive demand for certified vendors. India's data localization framework and China's MEE cybersecurity review protocols reshape product roadmaps toward geo-fenced replication.
- Educational Institutions:Research universities deploy object repositories for genomic sequencing archives and telescope imagery datasets with grant-funded procurement cycles. NIH and NSF compliance requirements overlay academic open-access mandates.
Enterprises dominate revenue concentration; Government segments climb the fastest on regulatory tailwinds.
Application:
Workload characteristics determine durability requirements, access latency tolerances, and lifecycle automation intensity.
- Backup & Recovery:Immutable object classes with WORM compliance replace tape libraries for ransomware-resistant retention. Healthcare systems under HIPAA security rule oversight deploy air-gapped copies with cryptographic verification.
- Data Archiving:Deep cold tiers optimized for eleven-nines durability with Reed-Solomon 16+4 erasure coding displace legacy optical media. Financial services firms automate retention schedules to preempt GDPR audit triggers.
- Content Distribution:CDN-integrated object storage delivers video streaming and software update payloads with edge-cached performance. Established delivery networks optimize existing footprints rather than greenfield buildouts.
- Big Data Analytics:Vector databases and real-time inference pipelines consume object-native formats, pulling demand from feature stores and model training pipelines. This application expands most quickly as AI workloads compress deployment cycles.
Big Data Analytics gains share fastest; Content Distribution anchors mature margin pools.
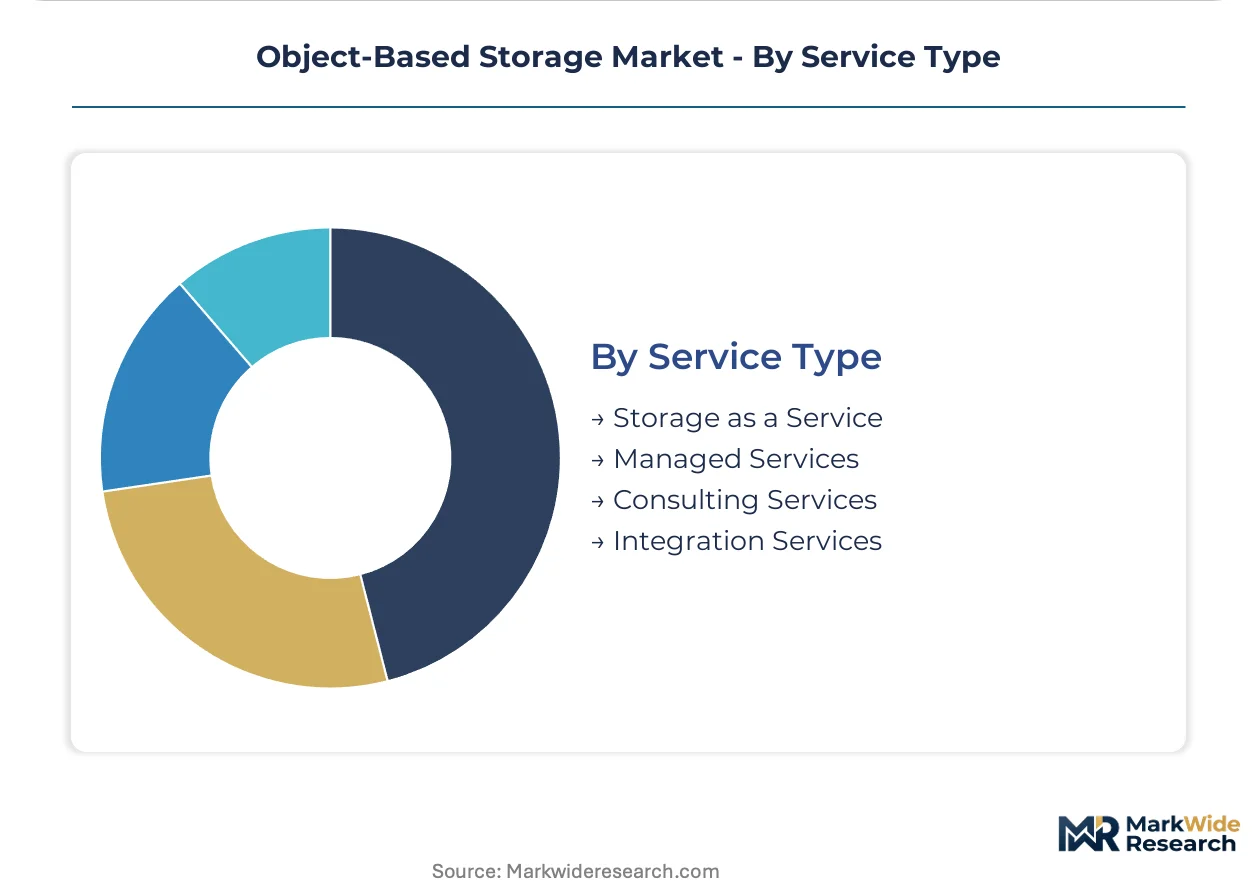
Service Type:
Delivery model selection reflects internal engineering capacity, risk tolerance, and preference for operational versus capital expenditure treatment.
- Storage as a Service:Metered consumption models displace capacity-purchase contracts as buyers demand egress pricing aligned with actual query volumes. Software-defined architectures with granular telemetry capture procurement preference in the United States and China.
- Managed Services:Third-party operators assume lifecycle management, security patching, and capacity planning for enterprises with constrained storage engineering pipelines. MSPs in Germany and India build practices around GDPR and RBI data localization compliance.
- Consulting Services:Migration architecture and tiering policy design engagements support mainframe protocol translation and hybrid cloud orchestration. IBM and legacy vendor ecosystems dominate this attach revenue.
- Integration Services:API development and data pipeline engineering connect object repositories to analytics platforms, MLOps workflows, and enterprise applications. Systems integrators capture value from cloud-native transformation mandates.
Storage as a Service leads on commercial momentum; Managed Services deepens penetration in compliance-intensive verticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Storage engineering talent concentrates in San Francisco Bay Area hyperscaler headquarters, Frankfurt financial technology clusters, and Beijing cloud infrastructure campuses. These workforce pools anchor petabyte-scale deployment velocity and compliance architecture innovation across three continents.
United States
Hyperscaler region expansion in Northern Virginia, Oregon, and Texas drives demand for erasure-coded enterprise tiers. HIPAA security rule oversight from HHS compels healthcare AI pipelines toward compliant imaging archives. Autonomous vehicle development clusters in the San Francisco Bay Area consume object-native formats for vector database training.
Germany
Frankfurt financial services firms deploy tiered storage policies to preempt GDPR audit triggers from national regulators. REACH chemical restrictions and EU AI Act documentation requirements mandate immutable audit trails for automotive training datasets. Bavarian automotive manufacturers maintain WORM-compliant object classes with cryptographic verification.
China
Cloud providers accelerate buildouts in Beijing-Tianjin-Hebei and Yangtze River Delta corridors. MEE cybersecurity review protocols for critical information infrastructure reshape product roadmaps toward geo-fenced replication. Domestic fintech platforms in Shenzhen and Hangzhou drive greenfield demand under data localization frameworks.
India
RBI and TRAI impose strict cross-border data restrictions, creating captive demand for domestic object storage infrastructure. Mumbai and Bengaluru fintech clusters deploy petabyte-scale repositories for real-time payment analytics. E-commerce platforms in Delhi-NCR absorb software-defined architectures with granular usage telemetry.
United Kingdom
London financial compliance hubs expand object storage footprints for quantitative trading feature stores. CNIL-equivalent national regulators enforce GDPR localization mandates across England and Scotland. Edinburgh and Cambridge research universities deploy genomic sequencing archives with grant-funded procurement cycles.
Object-Based Storage Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the object storage landscape. Integrated hardware-software vendors anchor high-performance deployments in regulated verticals, while software-defined specialists compete on deployment flexibility across hybrid cloud footprints. Three archetypes dominate: integrated infrastructure incumbents, cloud-native hyperscalers, and software-defined storage specialists. Competitive moves concentrate on strategic partnerships for hybrid orchestration and portfolio diversification into edge-to-core tiering.
Within the integrated infrastructure tier, Dell Technologies and Hewlett Packard Enterprise exemplify hardware-anchored positioning. IBM Corporation occupies a distinct archetype bridging mainframe-adjacent protocols with modern S3-compatible interfaces. Among software-defined specialists, Scality represents deployment flexibility across jurisdictional boundaries. These three anchors illustrate how vendor selection stratifies between capital intensity, legacy protocol support, and cloud-native elasticity.
| Leading Market Players |
|---|
| Dell Technologies |
| IBM Corporation |
| NetApp |
| Hewlett Packard Enterprise |
| Hitachi Vantara |
| Amazon Web Services |
| Scality |
| Oracle Corporation |
| Microsoft Corporation |
| Others |
Value Network & Pricing Analysis
Hyperscaler procurement desks in Northern Virginia and Frankfurt financial services clusters anchor demand for consumption-based billing models that displace capacity-purchase contracts. This buyer concentration compresses margin structures for high-throughput workloads while rewarding software-defined architectures with granular usage telemetry.
Pricing Analysis
Bundled managed services and unbundled raw storage capacity split procurement preferences across enterprise segments. Three-tier pricing structure across premium erasure-coded tiers, standard hybrid deployments, and economy archival nodes reflects durability guarantees and jurisdictional compliance certification levels. Cost compression in commodity cold storage tiers intensifies as Taiwanese and South Korean memory module supply constraints ease. SMB buyers exhibit highest price sensitivity, while government agencies absorbing FIPS 140-2 certified deployments show lowest elasticity.
Supply Chain Analysis
High-bandwidth memory module supply rests on Taiwanese and South Korean fabrication capacity. Advanced storage controllers, NAND flash substrates, and specialized cooling systems feed from concentrated East Asian manufacturing corridors. Single-source vulnerability in controller ASIC design exposes procurement timelines to geopolitical friction. Distribution runs through hyperscaler direct procurement channels, systems integrator partnerships, and certified MSP networks serving regulated verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds on regulatory layering, with GDPR localization mandates and HIPAA security rule oversight from HHS forcing architectural redesigns toward geo-fenced replication.
For Market Incumbents: Lock in hybrid cloud orchestration capabilities through API translation investments that bridge IBM COS protocols and modern S3-compatible interfaces. Anchor high-performance deployments in regulated verticals with integrated hardware-software stacks that preempt ISO 27001 certification timeline compression threatening mid-tier competitors. Defensive consolidation around mainframe-adjacent object protocols preserves legacy financial infrastructure migration revenue. For New Entrants and Emerging Players: Managed service providers in Germany and India represent the most accessible channel partners for GDPR and RBI data localization compliance practices. Healthcare AI pipelines and genomic sequencing archives offer underpenetrated white-space where object-native formats displace legacy PACS architectures. Position through software-defined architectures with granular usage telemetry that captures procurement preference in metered consumption models. For Investors and Strategic Acquirers: Cloud providers expanding hyperscaler regions are the most active acquirers in this space, seeking edge-to-core tiering capabilities and jurisdictional compliance expertise. Target acquisition archetypes include software-defined storage specialists with deployment flexibility across hybrid cloud footprints. Watch India's data localization framework enforcement intensity as inflection indicator for greenfield infrastructure demand.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API translation investments bridge IBM COS protocols with S3-compatible interfaces for financial migrations. |
| Geographic Expansion | Hyperscaler buildouts in Germany and India capture GDPR and RBI data localization compliance demand. |
| Strategic Partnership | Managed service provider alliances in Frankfurt and Singapore deepen penetration in compliance-intensive verticals. |
| Acquisition of Specialist Firm | Software-defined storage specialists add deployment flexibility across hybrid cloud footprints. |
| Product Launch | WORM-compliant object classes with cryptographic verification address EU AI Act documentation requirements. |
Research Methodology
Direct dialogue with storage engineering directors, IT procurement officers at Global 2000 firms, hyperscaler infrastructure planners, and managed service provider principals grounded qualitative findings. Secondary validation drew from SEC 10-K filings, hyperscaler capex disclosures, ISO 27001 certification registries, and GDPR enforcement actions from European national regulators. Bottom-up deployment sizing and top-down market aggregation triangulated volume estimates across deployment models and end-user segments.
Market sizing outputs incorporate installed base expansion, replacement cycles, and greenfield capacity additions across the projection horizon. Segmentation dimensions modeled include deployment topology, organizational scale tier, workload application type, and regional regulatory cluster. CAGRs derive from elasticity-adjusted demand curves and vendor revenue trajectory analysis. Vector database proliferation rates and data sovereignty mandate enforcement intensity serve as key forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to silicon supply concentration disruptions and energy cost volatility in European data center markets. Forecasts reflect assumptions around hyperscaler region expansion schedules and regulatory compliance timeline compression. A small set of triggers—including MEE cybersecurity review protocol expansion and REACH chemical restriction layering—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
Global 3D Nand Flash Memory Market
Data Storage
Distributed Storage System Market
Data Storage
Middle East and Africa AMH and Storage Systems Market
Data Storage
NOR Flash Market
Data Storage
Enterprise Storage System Market
Data Storage
Global Hard Disk Drive (HDD) Market
Data Storage
Blu-Ray Drive Market
Data Storage
Wi-Fi SD Cards Market
Data Storage
Nearline Hard Disk Drive Market
Data Storage
Global Purpose-Built Backup Appliance (PBBA) Market
Data Storage
Middle East Data Center Storage Market
Data Storage
Substrates for Magnetic Disks Market
Data Storage
OTG Pen Drive Market
Data Storage
Middle East and Africa Data Storage Market
Data Storage
Channel Storage Systems Market
Data Storage
HDD Head Assembly Market